
 France Mammography Market | 2026-2036
France Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
France Mammography Market Foresight
France is tilting its diagnostic imaging capacity toward digital breast tomosynthesis as public hospitals modernize screening infrastructure. GE Healthcare leverages its long-standing installed base of full-field digital systems to sustain renewal cycles across regional hospital networks. Hologic Inc anchors the premium segment with 3D mammography platforms that dominate France's organized screening programs. Siemens Healthineers competes through integrated workflow solutions that connect acquisition with AI-assisted reading protocols.
Mammography encompasses X-ray imaging of breast tissue using low-dose ionizing radiation, typically operating at 25–35 kVp with molybdenum or rhodium target-filter combinations to optimize soft-tissue contrast for detecting microcalcifications and masses. Digital mammography captures images via flat-panel detectors, replacing analog film with immediate electronic storage and transmission to PACS networks. Tomosynthesis technology is displacing conventional two-view screening in France's high-volume centers, where reconstructed slice images reduce tissue overlap artifacts and callback rates. Full-field digital systems occupy the mature replacement market, while contrast-enhanced mammography represents the emerging functional imaging frontier for dense breast evaluation. Diagnostic applications command margin premiums over screening volumes due to complex case protocols and multidisciplinary team coordination requirements.
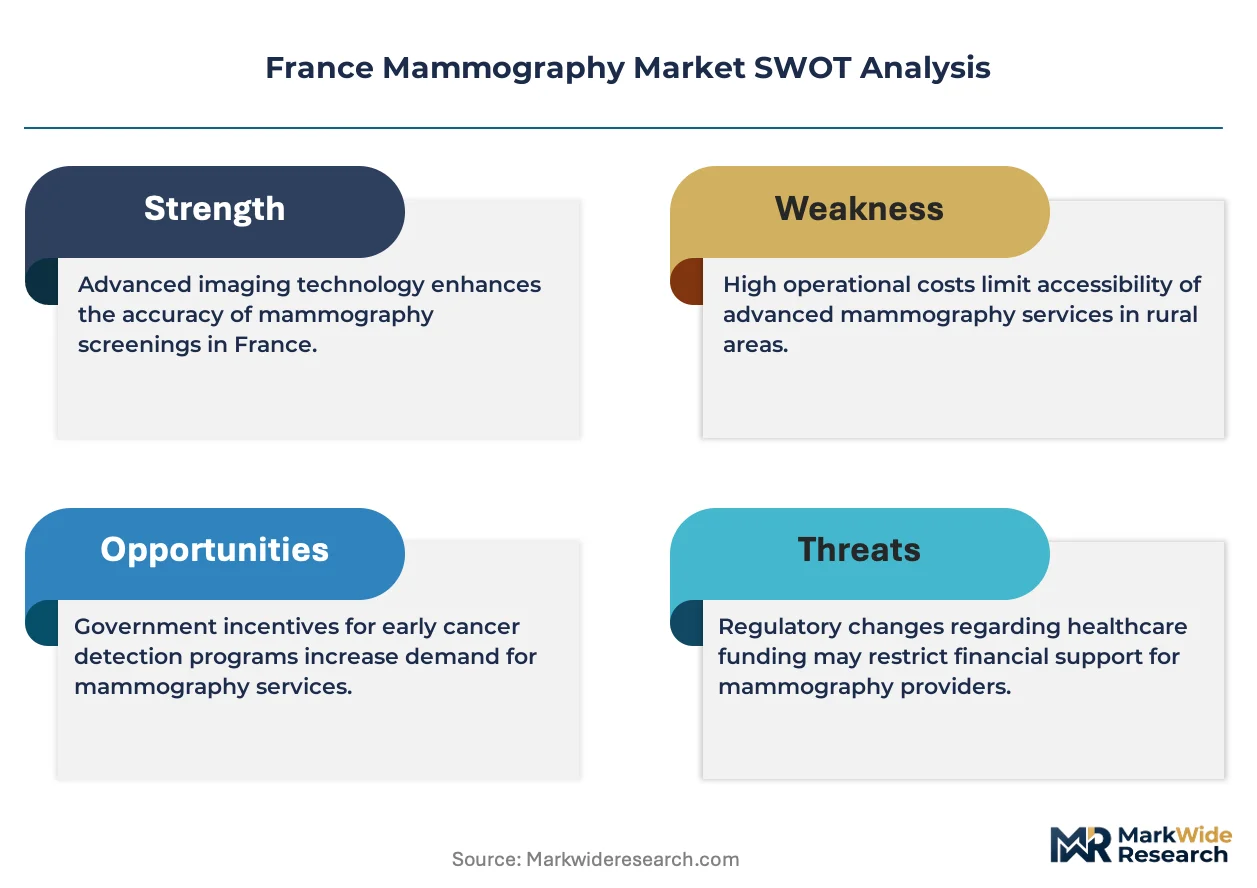
ANSM oversees medical device market access and post-market surveillance for mammography systems in France, enforcing MDR conformity and clinical evidence standards that extend approval timelines for novel imaging modalities. HAS evaluates screening program cost-effectiveness, directly influencing regional health authority reimbursement decisions and equipment procurement specifications. CNIL data protection rules constrain cloud-based image archiving architectures, compelling vendors to architect on-premise or sovereign-hosted storage solutions. Stakeholders must monitor how France's incorporation of AI-based lesion detection into national screening guidelines reshapes capital allocation between hardware upgrades and software licensing.
Market Dynamics
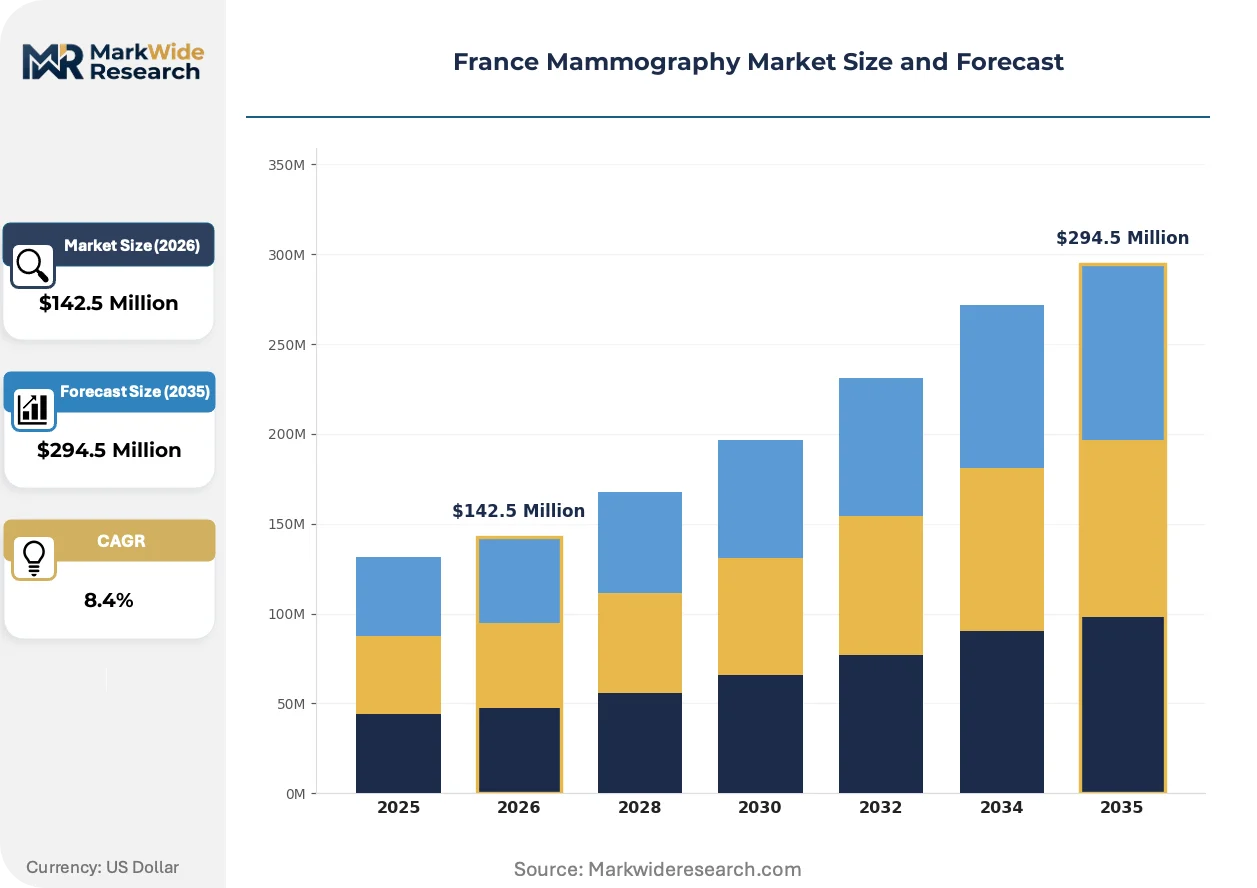
France's mammography market is undergoing structural compression as digital breast tomosynthesis supplants conventional two-dimensional screening, forcing equipment refresh cycles and retraining investments across regional hospital networks.
Growth Catalysts
- HAS protocol modernization:France's national health authority has elevated tomosynthesis to preferred screening status, compelling regional health agencies to fund system replacements.
- Île-de-France hospital consolidation:Centralized procurement by merged hospital groups is driving volume purchases of integrated imaging platforms with AI-assisted reading.
- Dense breast evaluation protocols:Rising clinical recognition of contrast-enhanced mammography for dense tissue assessment is expanding diagnostic application volumes.
Market Restraints
- MDR conformity timelines:ANSM enforcement of EU Medical Device Regulation extends approval durations for novel imaging modalities, delaying market entry.
- Rhodium target supply concentration:Molybdenum-rhodium anode materials for soft-tissue optimization depend on concentrated upstream refining capacity.
- Cloud archiving restrictions:CNIL data sovereignty rules block standard cloud PACS architectures, forcing costly on-premise infrastructure.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur screening gaps:Underpenetrated coastal regions outside Parisian clusters present equipment deployment whitespace.
- AI lesion detection integration:HAS evaluation of computer-aided detection for national screening guidelines creates software licensing expansion potential.
- Workflow convergence:Integration of tomosynthesis acquisition with automated breast density assessment streamlines radiologist throughput.
Industry Challenges
- Radiologist workforce constraints:Specialized breast imaging expertise shortages in regional centers limit screening program expansion.
- Legacy system interoperability:PACS integration between analog-era archives and new DICOM tomosynthesis datasets requires costly middleware.
- Capital intensity of 3D upgrades:Full-field digital system replacements demand substantial upfront investment from budget-constrained public hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Mammography Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, Analog Mammography, 3D Mammography, Portable Mammography Technology: Full-Field Digital, Computed Radiography, Tomosynthesis, Contrast-Enhanced Mammography Application: Breast Cancer Screening, Diagnostic Mammography, Preoperative Planning, Monitoring Post-Treatment End User: Diagnostic Centers, Specialty Clinics, Academic Research Institutions, Mobile Screening Units |
| Companies Covered | GE Healthcare, Hologic Inc, Siemens Healthineers, Fujifilm Holdings Corporation, Planmed Oy, Canon Medical Systems Corporation, Koninklijke Philips NV, Carestream Health Inc, IMS Giotto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Mammography Market Shifts & Advancements
Three convergent forces are compressing France's mammography value chain: hardware digitization, regulatory AI integration, and procurement centralization. These shifts favor integrated platform vendors over point-solution specialists.
Digital breast tomosynthesis is digitizing screening workflows by reconstructing slice-based images that eliminate tissue overlap artifacts. Public hospital networks in Île-de-France and Rhône-Alpes are adopting these systems at accelerated replacement cycles. This technology is digitizing radiologist reading protocols, compressing interpretation time while reducing callback rates.
France's HAS is evaluating AI-based lesion detection algorithms for incorporation into organized screening guidelines. This regulatory trajectory is forcing vendors to bundle software licenses with hardware procurement. Diagnostic centers in urban clusters are responding by prioritizing platforms with native AI integration over standalone imaging systems.
Regional health authorities are consolidating equipment purchasing through centralized hospital group procurement offices. This buyer concentration is displacing fragmented departmental-level acquisition. The shift is most visible in Grand Est and Occitanie, where merged public hospital networks negotiate multi-site imaging platform contracts.
France Mammography Market Segmentation
France's mammography market segments reflect competing pressures between legacy infrastructure replacement and next-generation diagnostic capability. Procurement patterns diverge sharply across product types and end-use settings, with public hospital networks driving volume while private diagnostic centers prioritize workflow efficiency.
Product Type:
Equipment selection spans the full use-case spectrum from high-throughput organized screening to point-of-care diagnostic access in underserved territories.
- Digital Mammography:Flat-panel detector systems operating at 25–35 kVp with molybdenum-rhodium filtration dominate France's replacement cycles. Regional hospital groups in Île-de-France and Auvergne-Rhône-Alpes concentrate procurement for organized screening program compliance.
- 3D Mammography:Tomosynthesis platforms reconstruct slice-based images eliminating tissue overlap artifacts. HAS protocol revisions elevating 3D to preferred screening status are accelerating deployment in high-volume centers facing callback rate reduction mandates.
- Analog Mammography:Film-screen systems persist in budget-constrained rural facilities awaiting capital allocation. ANSM MDR compliance timelines are forcing accelerated phase-out where maintenance parts availability constricts.
- Portable Mammography:Mobile units mounted on dedicated screening vehicles extend organized program reach to Provence-Alpes-Côte d'Azur coastal gaps and overseas territories lacking fixed infrastructure.
Established volume favors digital mammography; emerging adoption favors 3D mammography.
Technology:
Technical differentiation clusters around detector architecture and image reconstruction algorithms that determine diagnostic yield per examination.
- Tomosynthesis:Multi-angle X-ray acquisition with iterative reconstruction generates 1mm slice separation through compressed breast thickness. Grand Est hospital networks are prioritizing this technology for dense breast evaluation protocols.
- Full-Field Digital:Amorphous selenium or cesium iodide direct-conversion detectors capture 50-micron spatial resolution images. Mature installed base across French public hospitals sustains renewal demand as systems reach end-of-design-life.
- Computed Radiography:Photostimulable phosphor plate systems bridge analog-to-digital transition for smaller facilities. Plate consumption economics and slower workflow are displacing this technology from organized screening programs.
- Contrast-Enhanced Mammography:Dual-energy subtraction imaging with iodinated contrast agents enables functional vascular assessment. Emerging adoption in Occitanie academic centers targets dense breast diagnostic specificity gaps.
Full-field digital systems command current procurement volume; tomosynthesis platforms are climbing the fastest.
Application:
Clinical utility varies across the care continuum from asymptomatic population screening to active disease management.
- Breast Cancer Screening:Organized biennial examination of women aged 50–74 constitutes France's highest-volume application. HAS quality metrics and callback rate targets shape equipment specification requirements.
- Diagnostic Mammography:Symptomatic evaluation and callback resolution demand higher resolution and specialized views. Complex case protocols command margin premiums due to extended examination time and multidisciplinary coordination.
- Preoperative Planning:Localization wire placement and lesion extent mapping guide surgical approach. Academic medical centers in Paris cluster concentrate this specialized application volume.
- Monitoring Post-Treatment:Surveillance imaging following surgery, radiation, or systemic therapy tracks recurrence. Longitudinal comparison requirements favor facilities with stable equipment platforms and PACS archive depth.
Screening applications sustain equipment utilization rates; diagnostic applications generate margin concentration.
End User:
Facility type determines capital intensity tolerance and workflow integration requirements.
- Diagnostic Centers:Dedicated breast imaging facilities combine high patient throughput with specialized radiologist staffing. CNIL data sovereignty rules compel on-premise PACS architecture investments.
- Specialty Clinics:Gynecology and oncology practices integrate mammography with complementary diagnostic services. Smaller footprint systems with automated positioning dominate this segment.
- Academic Research Institutions:Teaching hospitals and university centers drive protocol innovation and AI validation studies. HAS guideline development ties directly to evidence generation from these sites.
- Mobile Screening Units:Vehicle-deployed systems extend organized program geographic coverage. Rhône-Alpes and Bretagne health authorities are expanding fleet deployment to address access inequities.
Diagnostic centers anchor current procurement volume; mobile screening units represent the steepest expansion trajectory for installed base growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM regulates medical device market access across France's mammography sector, with HAS protocol revisions directly shaping equipment procurement specifications in high-volume screening regions.
Île-de-France
Hospital consolidation drives centralized imaging investments across Parisian metropolitan clusters. HAS quality metrics mandate callback rate reductions, compelling merged hospital groups to fund tomosynthesis system replacements. The Paris-Saclay academic corridor concentrates AI validation studies for national screening guideline development.
Auvergne-Rhône-Alpes
Dense breast evaluation protocols expand diagnostic application volumes in Lyon and Grenoble medical centers. CNIL data sovereignty rules constrain cloud-based PACS architectures, forcing on-premise infrastructure investments. The Lyon biotech cluster anchors contrast-enhanced mammography adoption for functional vascular assessment.
Provence-Alpes-Côte d'Azur
Underpenetrated coastal regions present equipment deployment whitespace outside established urban screening networks. Mobile screening units extend organized program reach to Nice and Marseille peripheries. Regional health authorities fund fleet expansion to address geographic access inequities in breast cancer detection.
Grand Est
Centralized procurement by merged public hospital networks negotiates multi-site imaging platform contracts across Strasbourg and Nancy. Tomosynthesis technology displaces conventional two-view screening in high-volume centers. The region prioritizes integrated workflow solutions connecting acquisition with AI-assisted reading protocols.
Occitanie
Academic medical centers in Toulouse and Montpellier drive contrast-enhanced mammography adoption for dense tissue diagnostic specificity. MDR conformity timelines extend approval durations for novel imaging modalities, delaying market entry for emerging vendors. Research institutions validate AI-based lesion detection algorithms for HAS guideline incorporation.
France Mammography Market Competitive Landscape
Integrated platform vendors and point-solution specialists split the market along workflow convergence lines. Concentration favors vendors bundling hardware procurement with software licensing for AI-assisted reading. Three archetypes dominate: full-field digital incumbents leveraging installed base renewal cycles, tomosynthesis premium-positioned challengers, and AI-native software entrants seeking guideline validation. Competitive moves center on strategic partnerships for regulatory pathway acceleration and portfolio diversification into automated breast density assessment.
Among diversified medical technology conglomerates, GE Healthcare anchors the replacement market through its longstanding installed base across French regional hospital networks. Hologic Inc occupies the premium tomosynthesis tier, with Siemens Healthineers representing the integrated workflow archetype connecting acquisition systems with reading protocols. These three exemplify how vendor positioning aligns with HAS procurement criteria emphasizing callback rate reduction and radiologist throughput optimization.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic Inc |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Planmed Oy |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Carestream Health Inc |
| IMS Giotto |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility feeds directly into mammography equipment landed costs, amplifying price spreads between premium tomosynthesis platforms and standard digital systems while regional hospital group consolidation intensifies volume-based negotiation leverage.
Pricing Analysis
Geographic price spreads between Île-de-France procurement hubs and peripheral regions like Provence-Alpes-Côte d'Azur reflect differential logistics burdens and local installation capacity constraints. Three-tier pricing structure across premium tomosynthesis, standard full-field digital, and economy analog replacement levels dominates equipment transactions, with HAS certification tier and bundled AI software licensing as primary differentiation drivers. Cost compression in the standard digital tier is intensifying because merged hospital groups negotiate multi-site framework agreements. Public hospital networks exhibit highest price sensitivity due to fixed capital budgets, while private diagnostic centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard practice among French regional health authorities, straining manufacturer working capital and favoring diversified conglomerates with captive financing facilities. X-ray tube production concentrates in Germany, Japan, and the United States, while flat-panel detector manufacturing centers on South Korea, Taiwan, and Japan. Rhodium target materials for molybdenum-rhodium anode systems draw from concentrated South African and Russian refining capacity. Single-source vulnerability in rhodium supply creates exposure to commodity price spikes and export restriction scenarios. Distribution runs through authorized dealer networks with direct service engineering support, bypassing traditional medical device distributors for complex installation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital group mergers across France's regional health authorities, fragmenting vendor pricing leverage as centralized procurement offices displace departmental-level acquisition autonomy.
For Market Incumbents: Insulate installed base renewal cycles by embedding AI-assisted reading software into hardware service contracts, locking out standalone software competitors seeking HAS guideline validation. Deepen backward integration into detector refurbishment capabilities to capture margin from extended equipment lifecycles in budget-constrained public hospitals. The threat of AI-native entrants with cloud-architected solutions demands preemptive bundling of on-premise PACS compliance. For New Entrants and Emerging Players: Build out mobile screening unit deployment capabilities targeting Provence-Alpes-Côte d'Azur coastal access gaps and overseas territories lacking fixed infrastructure. The most penetrable segment lies in contrast-enhanced mammography for dense breast evaluation protocols, where established vendors have slower regulatory approval timelines. A go-to-market angle anchored to academic medical center validation studies accelerates HAS guideline incorporation and subsequent regional health authority procurement eligibility. For Investors and Strategic Acquirers: HAS evaluation of AI-based lesion detection for national screening guideline incorporation reshapes the acquisition landscape toward software-hardware convergence plays. Long-term viability favors platforms with regulatory pathway momentum and installed base density for recurring service revenue. Acquisition targets should display native AI integration and established ANSM MDR conformity. The signal to watch is HAS publication of formal screening protocol revisions mandating tomosynthesis or AI-assisted reading.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | ANSM MDR compliance timelines compress competitive windows for novel imaging modalities entering France. |
| Hospital System Partnership | Multi-site framework agreements with merged Île-de-France hospital groups secure predictable replacement cycle revenue. |
| Software Companion Development | Native AI lesion detection integration addresses HAS screening guideline evaluation criteria directly. |
| Reimbursement Strategy | HAS cost-effectiveness assessments determine regional health authority funding allocation for equipment procurement. |
| Backward Integration into Detector Refurbishment | In-house remanufacturing capability captures margin from extended public hospital equipment lifecycles. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, radiology department heads, and regional health authority procurement officers and refined through secondary validation against ANSM device registration databases, HAS screening program reports, CNIL data protection guidance documents, and European hospital procurement transparency records. Bottom-up equipment shipment tracking was triangulated with top-down health authority budget allocation analysis.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, technology architecture, clinical application, and end-user facility category, with additional dimensioning by regional health authority procurement cluster. CAGRs were derived from installed base replacement cycle analysis and screening program volume elasticity estimates. Key forecast inputs included HAS protocol revision timelines and MDR conformity approval trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native software entrants or diversified imaging conglomerates would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Global Cardiac Imaging Software Market