
 Spain Hospital Supplies Market | 2026-2036
Spain Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Hospital Supplies Market Analytics
Multi-source procurement frameworks is recalibrating how Spanish hospital networks secure critical inventory. Cardinal Health leverages its European distribution infrastructure to serve Iberian health systems with consolidated logistics. B. Braun anchors its position through in-house production of infusion therapy and surgical instruments manufactured at its Rubí facility near Barcelona. Grifols competes in plasma-derived hospital supplies, drawing on its Catalan manufacturing heritage to sustain regional contract strength.
Spain hospital supplies encompass sterile and non-sterile products used in diagnosis, surgery, patient care, and facility maintenance, including items ranging from latex examination gloves meeting EN 455 standards to electrosurgical generators operating at 400-500 kHz for tissue cutting and coagulation. These products serve to prevent cross-contamination, enable minimally invasive procedures, and maintain continuous clinical operations across acute and chronic care settings. Medical consumables generate recurring revenue through high-turnover disposables, while patient monitoring systems embed longer replacement cycles and software upgrade paths. Surgical instruments retain margin concentration in specialized laparoscopic and robotic-assisted tool sets, with diagnostic equipment representing capital-intensive procurement subject to hospital budget allocation cycles.
Spain's national health system operates under EU Medical Device Regulation oversight administered through the Spanish Agency for Medicines and Health Products, with BIS-equivalent standards coordination through the Ministry of Health for domestic procurement compliance. The EU Green Deal and national waste reduction targets pressure hospitals to transition toward reusable instrument sterilization workflows and reduced packaging protocols. Stakeholders must weigh EU AI Act implications for diagnostic equipment algorithms against the capital requirements of Spain's regional health authority budget cycles.
Market Dynamics
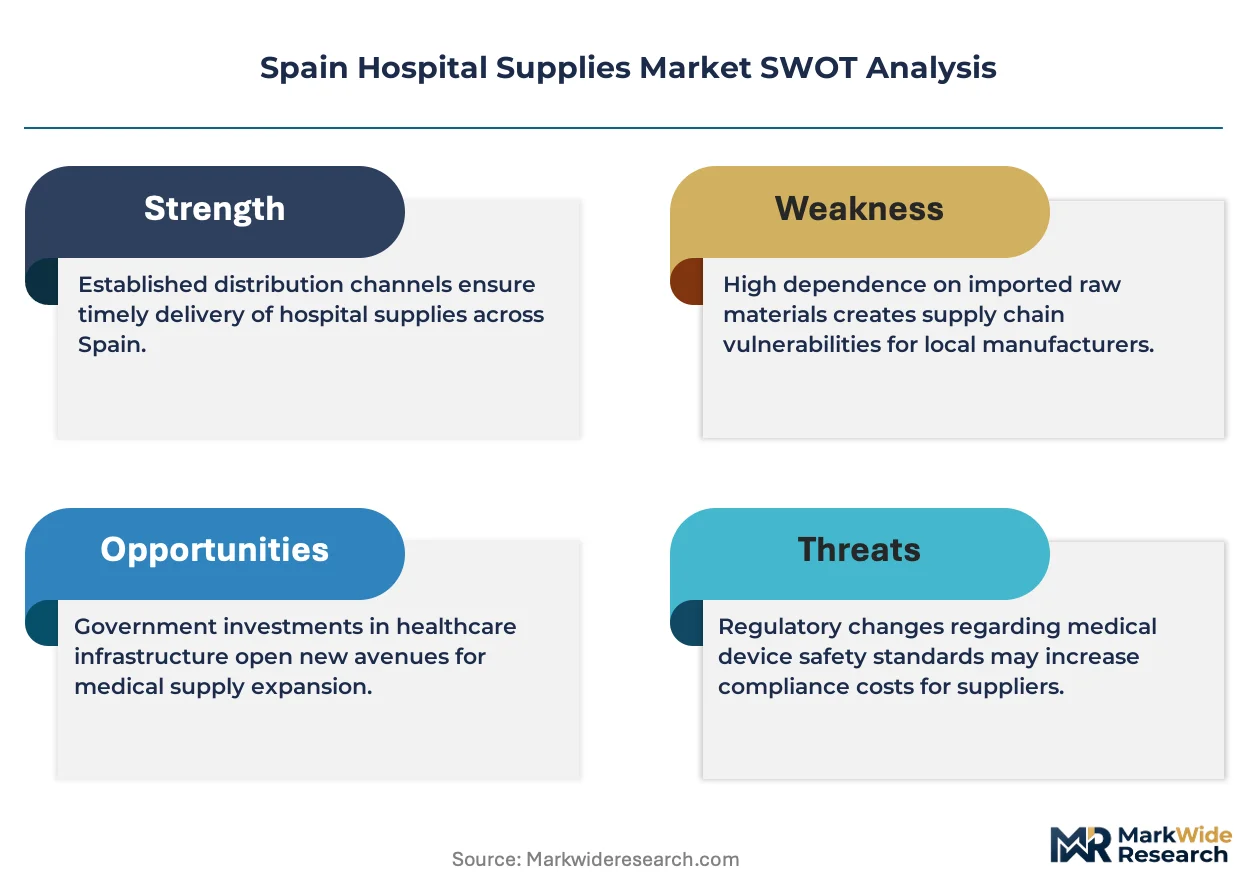
Spain's hospital supplies sector faces structural recalibration as EU Medical Device Regulation enforcement tightens supply chain documentation requirements and regional health authorities consolidate procurement volumes.
Growth Catalysts
- EU MDR compliance deadlines:Spanish hospitals accelerate inventory turnover to meet post-2024 device certification requirements, generating replacement demand for re-registered surgical consumables.
- Andalusia public hospital expansion:The Junta de Andalucía's infrastructure investment program drives bulk purchasing of single-use surgical kits and sterilization supplies across 46 public hospitals.
- Plasma-derived therapeutics:Catalonia's concentration of fractionation facilities sustains captive demand for specialized collection and processing disposables.
Market Restraints
- Polymer input cost volatility:Polypropylene and PVC price fluctuations squeeze margins on disposable syringes and infusion sets manufactured for Spanish health systems.
- Single-source sterilization services:Centralized ethylene oxide processing in the Barcelona-Tarragona corridor creates supply vulnerability for surgical instrument reprocessing.
- Reusable instrument substitution:EU Green Deal waste reduction targets pressure hospitals to extend sterilization cycles, compressing volume demand for certain disposable categories.
Strategic Opportunities
- Galicia underpenetration:The northwest region's dispersed hospital network lacks consolidated logistics infrastructure, opening channel entry for specialized distributors.
- AI-integrated diagnostic equipment:EU AI Act implementation creates compliance-service bundling opportunities for patient monitoring system vendors.
- Direct-to-hospital e-procurement:Madrid's regional health authority pilots digital purchasing platforms that bypass traditional medical supply wholesalers.
Industry Challenges
- MDR technical documentation backlog:Spanish notified body capacity constraints delay product re-certification timelines for mid-tier manufacturers.
- Legacy HIS integration friction:Hospital information system fragmentation across 17 autonomous communities complicates inventory management software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Hospital Supplies Market |
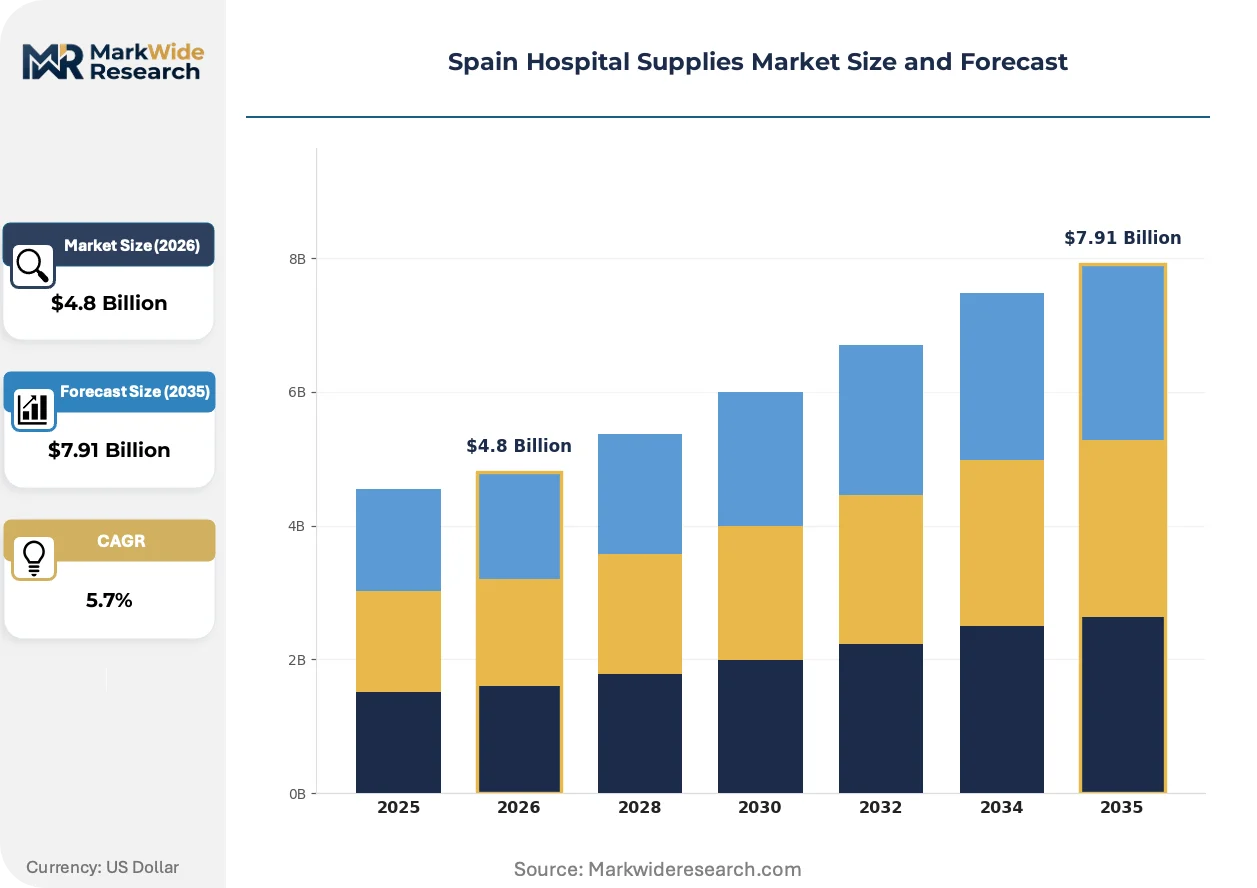
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Medical Consumables, Surgical Consumables End User: Public Hospitals, Private Hospitals, Clinics, Emergency Services Service Type: Maintenance Services, Supply Chain Services, Installation Services, Consultancy Services Technology: Telemedicine Solutions, Wearable Devices, Electronic Health Records, Patient Monitoring Systems |
| Companies Covered | Cardinal Health, Medtronic, B. Braun, GE HealthCare, Baxter, Becton Dickinson, Thermo Fisher Scientific, Johnson & Johnson, Grifols, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Hospital Supplies Market Evolving Landscape
Digital traceability systems and sustainable material transitions are restructuring how Spanish hospitals source, track, and dispose of medical consumables.
Radio-frequency identification tagging is overtaking barcode-based inventory tracking in Madrid's tertiary hospitals. RFID-enabled surgical sponge and instrument tracking systems reduce retained foreign object incidents while enabling real-time supply chain visibility. This technology is compressing working capital requirements for high-turnover consumable categories.
EU Green Deal packaging reduction mandates force suppliers to eliminate secondary cardboard and plastic wrapping on sterile procedure kits. Spanish regional health authorities now specify reduced-packaging requirements in tender documents. Surgical tray manufacturers respond with consolidated instrument sets that minimize individual sterile barriers.
Hospital buying committees increasingly specify EN 455-certified nitrile gloves over latex alternatives to address staff allergy protocols. Valencia's hospital network completed this transition in 2023, establishing procurement templates that other autonomous communities replicate. This preference shift concentrates demand with nitrile compounders holding EU MDR device certification.
Spain Hospital Supplies Market Segmentation
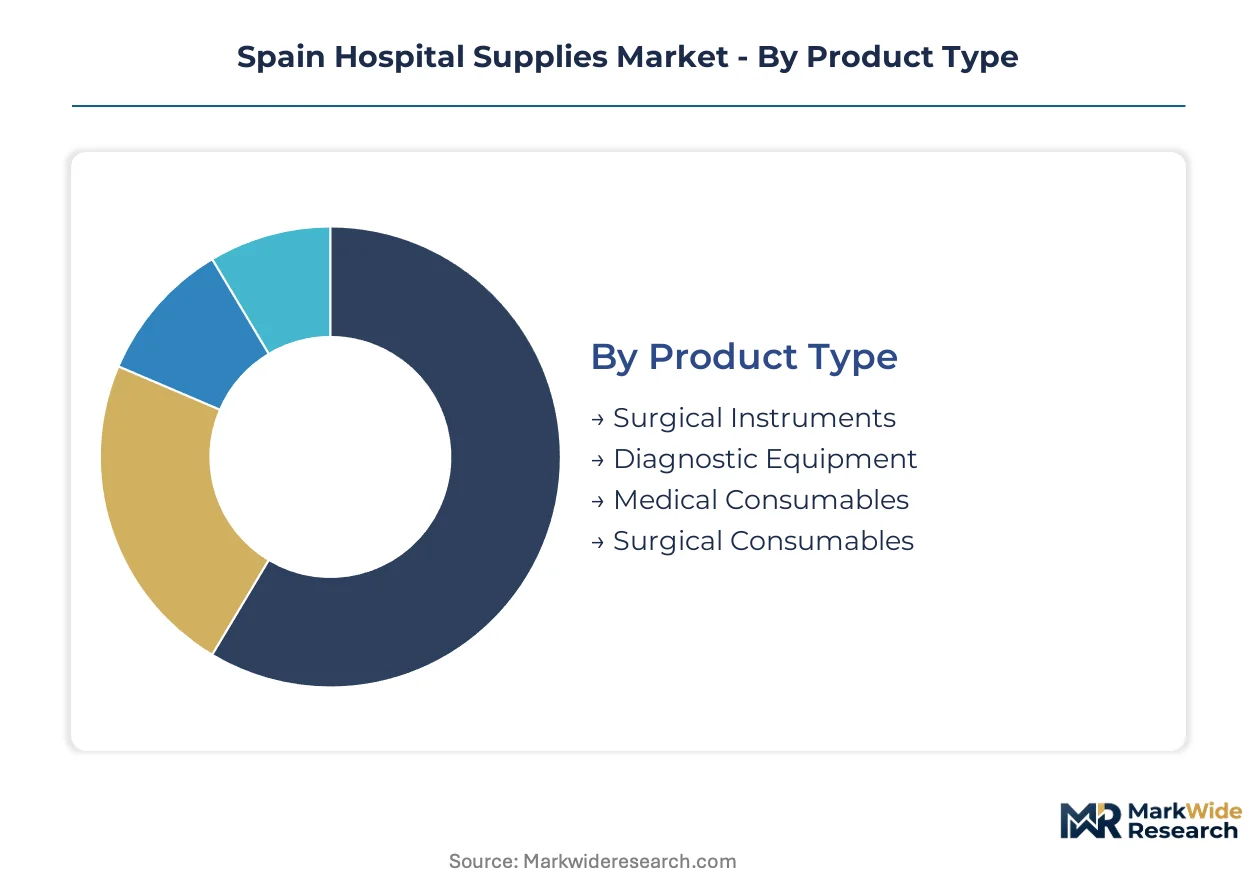
Supply concentration across Catalonia and Madrid determines how procurement patterns fragment across product categories. Segmentation reveals where regional health authority budgets concentrate purchasing power versus where specialized distributors capture dispersed demand.
Product Type:
Supply concentration tilts toward manufacturers with EU MDR-certified production facilities located within Iberian logistics corridors.
- Medical Consumables:Single-use disposables including syringes, catheters, and wound dressings manufactured to EN ISO 13485 standards. Madrid's hospital cluster drives bulk purchasing through centralized regional tenders, with polymer input costs squeezing margin structures on high-volume lines.
- Surgical Consumables:Sterile procedure kits, drapes, and suction devices requiring ethylene oxide sterilization certification. Demand concentrates in Andalusia's expanding public hospital network, where the Junta de Andalucía consolidates procurement across 46 facilities.
- Surgical Instruments:Reusable and disposable tools for open and minimally invasive procedures.
- Diagnostic Equipment:Imaging and laboratory systems subject to capital budget allocation cycles.
Today's leader: Medical Consumables. Tomorrow's challenger: Surgical Consumables.
End User:
Procurement scale separates institutions by budget autonomy and tender participation thresholds.
- Public Hospitals:Regional health authority-controlled facilities operating under national health system procurement frameworks. Catalonia and Andalusia channel the largest volumes through consolidated purchasing platforms, with MDR compliance deadlines accelerating replacement cycles for aging device inventories.
- Private Hospitals:Investor-owned and non-profit facilities with direct supplier negotiation leverage. Barcelona's medical technology corridor hosts the densest concentration, where faster decision cycles enable rapid adoption of RFID-enabled inventory tracking systems.
- Clinics:Outpatient and ambulatory surgical centers with limited sterilization infrastructure.
- Emergency Services:Mobile and fixed emergency care units requiring rapid-deployment supply configurations.
Public Hospitals command procurement volume. Private Hospitals gain share fastest on technology refresh rates.
Service Type:
Margin structures diverge between recurring maintenance contracts and one-time installation revenue.
- Supply Chain Services:Inventory management, logistics, and consignment stocking arrangements. Cardinal Health's European distribution infrastructure anchors this segment through consolidated delivery networks serving Iberian health systems with reduced working capital requirements.
- Maintenance Services:Preventive and corrective servicing of capital equipment under multi-year contracts. Diagnostic equipment vendors bundle these agreements to secure replacement part revenue streams and software upgrade paths.
- Installation Services:Physical deployment and commissioning of hospital infrastructure.
- Consultancy Services:Workflow optimization and regulatory compliance advisory.
Supply Chain Services generate recurring revenue. Maintenance Services deepen vendor lock-in.
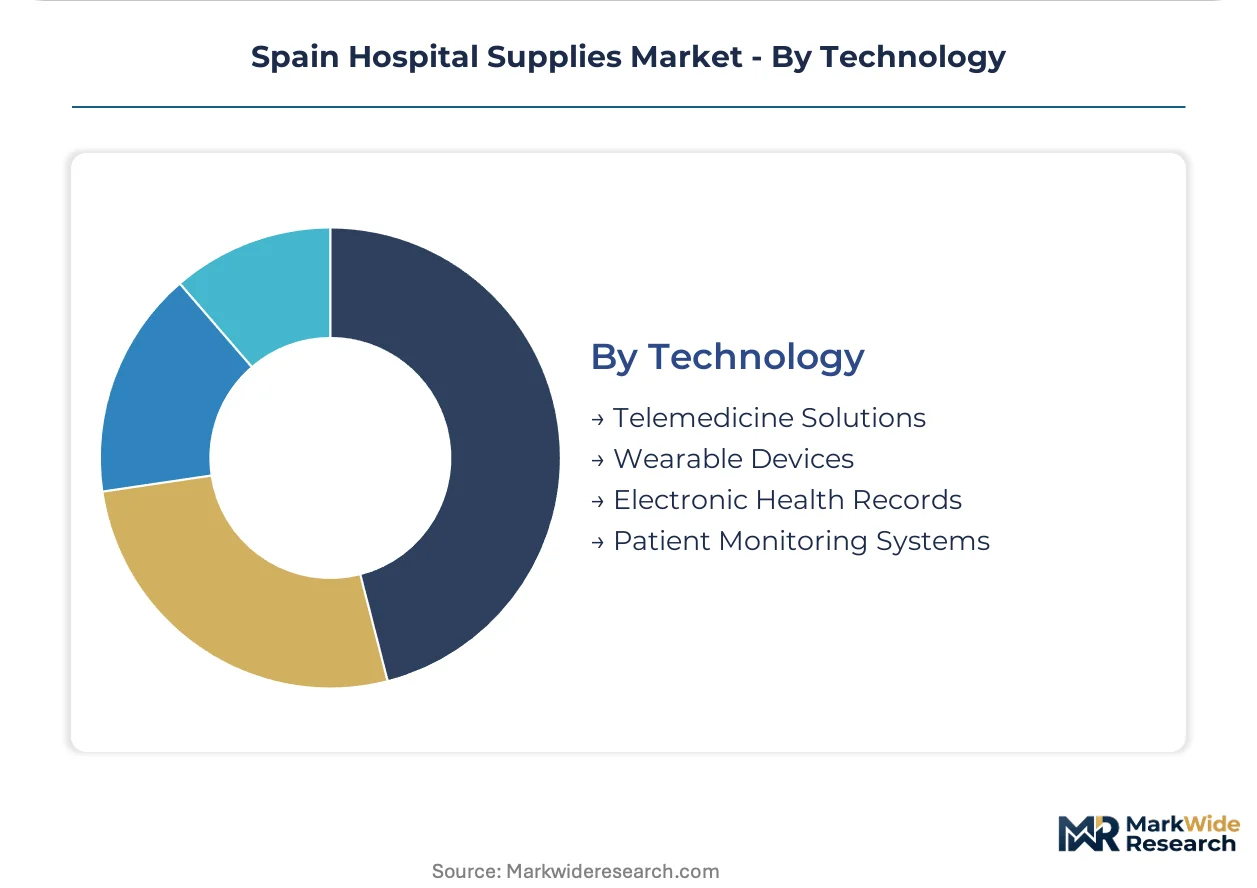
Technology:
Regulatory complexity separates segments by EU AI Act applicability and data governance requirements.
- Patient Monitoring Systems:Continuous vital sign tracking devices integrating with hospital information systems. Madrid's tertiary hospitals lead RFID-enabled real-time location system deployment, compressing inventory carrying costs for high-turnover consumables.
- Electronic Health Records:Digital patient data platforms requiring interoperability across Spain's 17 autonomous communities. Legacy system fragmentation complicates vendor software deployment and inventory management integration.
- Telemedicine Solutions:Remote consultation and diagnostic platforms expanding post-acute care reach.
- Wearable Devices:Ambulatory monitoring tools for chronic disease management.
Patient Monitoring Systems capture capital budgets. Electronic Health Records face integration headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid's hospital cluster anchors procurement volume for surgical consumables and diagnostic equipment, with regional health authority budgets channeling investment toward EU MDR-compliant inventory modernization.
Madrid
Public hospital networks in the capital region drive centralized tendering for single-use surgical kits and patient monitoring systems. The regional health authority's digital procurement platform pilots direct-to-hospital e-procurement, bypassing traditional medical supply wholesalers. Madrid's tertiary hospitals lead RFID-enabled inventory tracking deployment across Spain's national health system.
Catalonia
Barcelona's medical technology corridor concentrates private hospital procurement and plasma-derived therapeutic manufacturing. The Catalan health service consolidates sterilization services in the Barcelona-Tarragona corridor, creating supply concentration for surgical instrument reprocessing. Grifols maintains regional contract strength through its Rubí facility's captive production of infusion therapy disposables.
Andalusia
The Junta de Andalucía's infrastructure investment program drives bulk purchasing across 46 public hospitals for single-use surgical consumables. Regional procurement frameworks prioritize EN ISO 13485-certified manufacturers with Iberian logistics capabilities. Seville and Málaga hospital clusters generate concentrated demand for sterilization supplies and procedure kits.
Basque Country
Advanced manufacturing heritage in Bilbao and San Sebastián supports specialized surgical instrument production and medical device component supply. Regional health authorities emphasize local supplier preference in public tenders for maintenance services and capital equipment. The Basque health system's integrated delivery networks compress procurement decision cycles for diagnostic equipment refresh programs.
Valencia
Hospital networks in the Valencian Community completed sector-wide transitions to nitrile examination gloves, establishing procurement templates replicated by other autonomous communities. Regional health authority budgets prioritize EU Green Deal packaging reduction mandates in tender specifications. Valencia's dispersed hospital geography sustains demand for specialized distributor logistics services.
Spain Hospital Supplies Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital procurement platform integration and AI-enabled diagnostic equipment compliance services. The vendor base stratifies across multinational distributors with European logistics infrastructure, regional manufacturers with captive sterilization capabilities, and specialized plasma-derived therapeutic suppliers. Three archetypes dominate: consolidated logistics providers, vertically integrated instrument manufacturers, and fractionation-focused disposable specialists. Competitive intensity centers on M&A activity to secure notified body certification capacity and strategic partnerships to embed inventory management software within hospital information systems.
Within the multinational distributor tier, Cardinal Health leverages its European distribution infrastructure to serve Iberian health systems with consolidated logistics networks. B. Braun anchors the vertically integrated manufacturer position through in-house production of infusion therapy and surgical instruments manufactured at its Rubí facility near Barcelona. Grifols occupies the plasma-derived therapeutic specialist archetype, drawing on its Catalan manufacturing heritage to sustain regional contract strength across hospital supply categories.
| Leading Market Players |
|---|
| Cardinal Health |
| Medtronic |
| B. Braun |
| GE HealthCare |
| Baxter |
| Becton Dickinson |
| Thermo Fisher Scientific |
| Johnson & Johnson |
| Grifols |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap sterilization specialists anchor supply-side discipline across Spain's hospital supplies sector, compressing margin leakage through captive ethylene oxide processing while regional health authority tender consolidation amplifies buyer pricing power.
Pricing Analysis
Polypropylene and PVC input cost pass-through dominates pricing dynamics for disposable syringes and infusion sets manufactured for Spanish health systems. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified producers from uncertified competitors and generic imports. Cost compression in standard-tier consumables is intensifying because polymer feedstock volatility outpaces contract renegotiation cycles. Public hospital procurement committees exhibit highest price sensitivity, while private hospitals in Barcelona's medical technology corridor absorb premiums for RFID-enabled inventory integration.
Supply Chain Analysis
Single-source vulnerability sits with centralized ethylene oxide sterilization capacity concentrated in the Barcelona-Tarragona corridor. Manufacturing draws from Germany for precision surgical instruments, China for polymer-based disposables, and domestic Catalan facilities for plasma-derived therapeutics. Raw material dependencies span medical-grade polypropylene, nitrile rubber compounds, and sterilization-grade ethylene oxide. Logistics chokepoint risk concentrates at the Port of Barcelona for Iberian distribution. Distribution runs through Cardinal Health's European hub-and-spoke network serving regional health authority consignment stocking arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's hospital supplies market offers margin expansion through nitrile glove substitution protocols and EU MDR compliance-driven premium tier shifts, with polymer cost volatility creating procurement arbitrage opportunities for consolidated buyers.
For Market Incumbents: To counter Grifols' captive plasma-derived supply position, B. Braun and Cardinal Health should deepen backward integration into nitrile compounding and secure notified body certification capacity for MDR transition backlogs. Channel control through direct-to-hospital e-procurement platform embedding represents the critical defensive lever against Madrid's regional health authority digital tender pilots.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in RFID-enabled surgical consumables creates entry space for specialized distributors targeting Galicia's dispersed hospital network. White-space concentration sits with AI-integrated patient monitoring systems bundling EU AI Act compliance services. Seville and Málaga hospital clusters offer the most penetrable geography for sterilization supply alternatives. Go-to-market execution should anchor on GPO contract participation rather than direct regional health authority tender competition.
For Investors and Strategic Acquirers: Private equity-backed European healthcare distributors is the most active acquirer in this space, rolling up mid-tier sterilization service providers to capture MDR certification scarcity premiums. Long-term viability across the analysis window hinges on EU Green Deal packaging mandate compliance and AI diagnostic equipment regulatory service bundling. Acquisition target archetype: notified body-certified manufacturers with Iberian logistics infrastructure and existing regional health authority framework agreements. The signal to watch is Andalusia's infrastructure investment program procurement award timing as volume inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body capacity scarcity creates first-mover advantage for re-registered device portfolios. |
| Hospital System Partnership | Consignment stocking arrangements with Catalonia's regional health service compress competitor access. |
| Backward Integration into Polymer Compounding | In-house nitrile production at Rubí facility shields B. Braun from raw material volatility. |
| Software Companion Development | RFID-enabled inventory tracking integration with Madrid's tertiary hospital information systems deepens vendor lock-in. |
| Reimbursement Strategy | Plasma-derived therapeutic coding alignment with Spain's national health system payment frameworks sustains Grifols contract renewals. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through hospital procurement databases, AEMPS device registration filings, and regional health authority tender documents; plus customs trade data for polymer import flows — were reconciled through bottom-up and top-down triangulation.
Historical spending patterns from procurement databases were cross-referenced against panel input from supply chain directors to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, end-user institution category, service arrangement structure, and technology integration level. CAGRs were derived from regression analysis against hospital bed expansion plans and MDR compliance-driven replacement cycle acceleration.
Caveats apply where polymer feedstock volatility, notified body certification delays, or EU AI Act implementation timelines could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Skin Tac Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Blood Bags Market
Medical Supplies
Global Syringe Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Filter Needles Market
Medical Supplies
Latex Medical Disposables Market