
 China Group Health Insurance Market | 2026-2036
China Group Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Group Health Insurance Market Insights
Digital health platforms are decoupling traditional group insurance from paper-based underwriting and manual claims processing. Ping An Insurance leverages its Ping An Good Doctor ecosystem to integrate telemedicine with corporate benefit plans. China Life Insurance anchors its group health portfolio through exclusive bancassurance partnerships with state-owned banks. Taikang Life Insurance differentiates via elderly-care-linked group policies that bundle nursing home access with medical coverage.
China group health insurance constitutes employer-sponsored medical coverage pooling risk across employee cohorts, with policies typically specifying inpatient reimbursement ceilings, outpatient copayment ratios, and critical illness lump-sum triggers. The primary commercial purpose centers on talent retention and regulatory compliance with municipal social insurance contribution mandates. Large corporations dominate premium volume due to mandatory participation rules and bargaining scale, while small enterprises represent the fastest-expanding segment as micro-business clustering platforms reduce administrative barriers. Inpatient coverage commands the deepest premium pool given hospital cost inflation, though preventive care is gaining policy weight under Healthy China 2030 implementation.
China's National Healthcare Security Administration coordinates supplementary insurance frameworks, while the National Financial Regulatory Administration supervises product filing and solvency requirements under the Insurance Law. The Banking and Insurance Regulatory Information System mandates standardized data reporting that shapes product design granularity and cross-province portability. Stakeholders must monitor municipal integration pilots that merge basic medical insurance with commercial group supplements in tier-one cities.
Market Dynamics
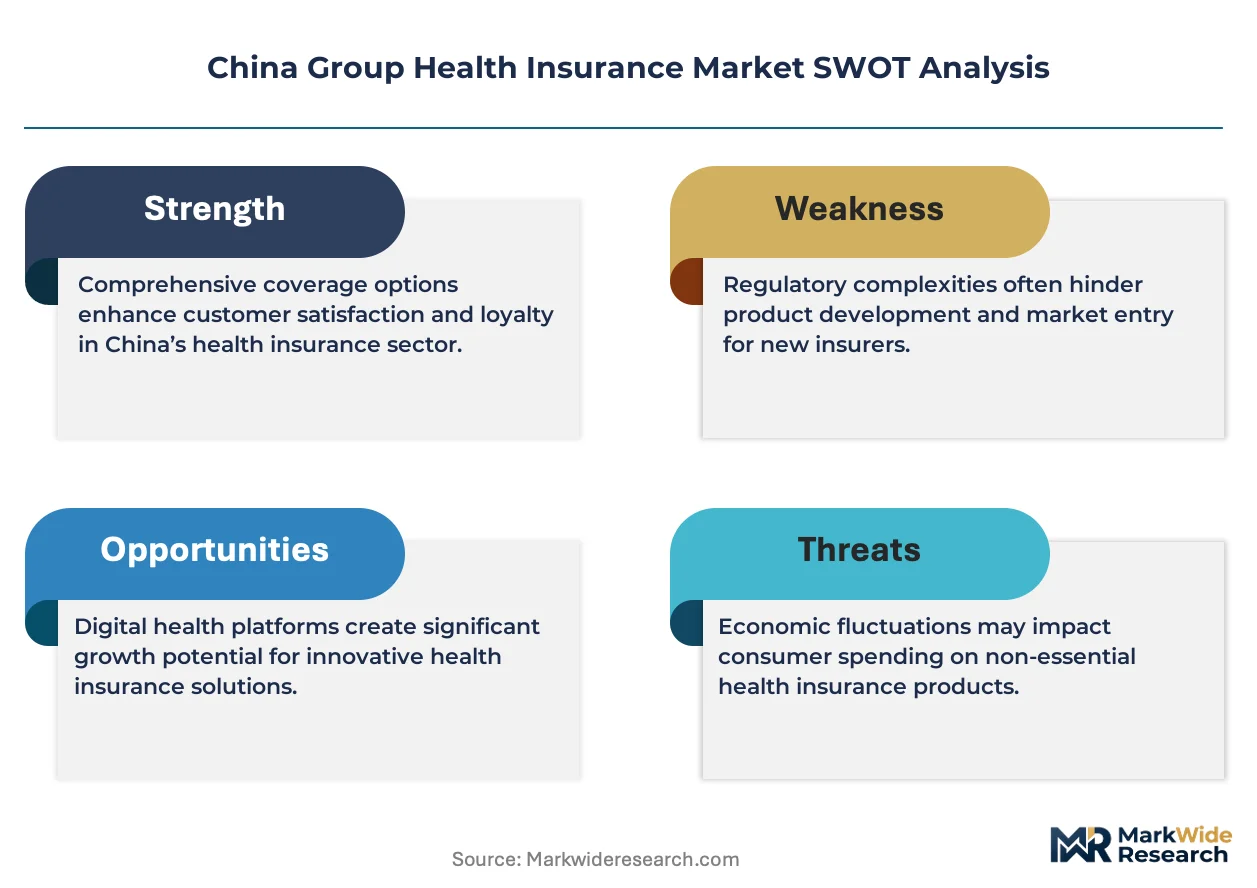
China's National Healthcare Security Administration reforms are forcing commercial insurers to reposition group products as supplementary layers atop basic medical schemes rather than standalone coverage.
Growth Catalysts
- Healthy China 2030 implementation:Municipal governments in Shanghai and Beijing mandate expanded corporate wellness benefits, creating mandatory enrollment pipelines for commercial group riders.
- State-owned enterprise benefit expansion:Central SASAC directives require SOEs to enhance employee retention packages, channeling premium volume toward inpatient reimbursement and critical illness lump-sum products.
- Telemedicine platform integration:Digital health ecosystems are embedding insurance distribution into remote consultation workflows, collapsing traditional agent acquisition costs.
Market Restraints
- Hospital cost inflation:Inpatient reimbursement ceilings face pressure from tertiary hospital pricing power, compressing insurer margins on core group products.
- Social insurance substitution:Basic medical insurance expansion in tier-two cities reduces perceived necessity for commercial supplementary coverage among price-sensitive employers.
- Data portability friction:The Banking and Insurance Regulatory Information System mandates localized reporting standards that fragment cross-province policy administration.
Strategic Opportunities
- Elderly-care convergence:Nursing home access bundling with medical coverage targets aging employee populations in Shenzhen and Guangzhou corporate pools.
- Micro-enterprise platform aggregation:Digital clustering services for small businesses reduce underwriting acquisition costs below traditional group policy economics.
- Preventive care weighting:Municipal pilots in Beijing integrate annual health screening mandates into group policy pricing, shifting premium pools toward wellness outcomes.
Industry Challenges
- Legacy system integration:Provincial social insurance databases lack API standardization, forcing insurers to maintain parallel claims adjudication infrastructure.
- Actuarial talent scarcity:Shortage of professionals versed in both Chinese mortality tables and international group pricing methodologies constrains product innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Group Health Insurance Market |
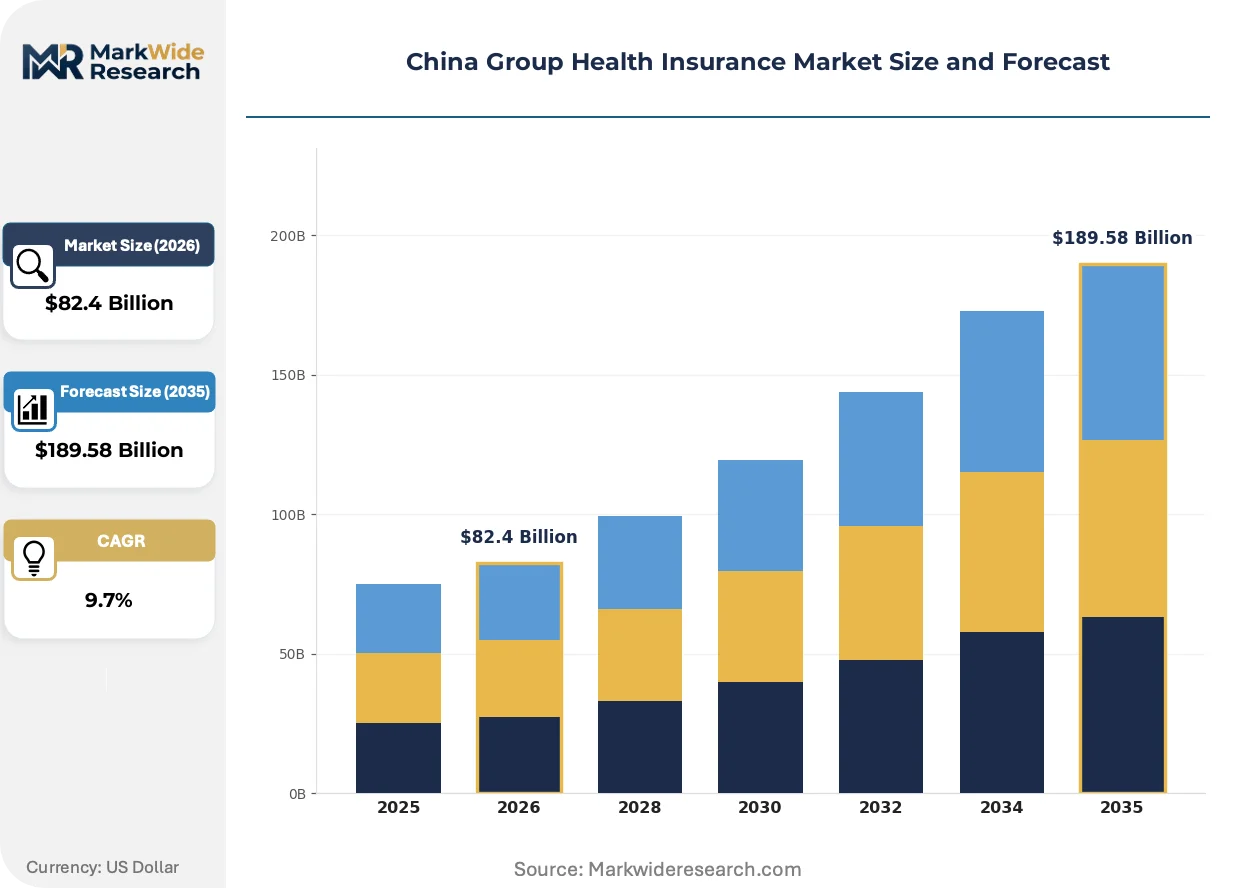
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $189.58 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Non-Profits Coverage Type: Inpatient Coverage, Outpatient Coverage, Preventive Care, Critical Illness Policy Duration: Annual, Biennial, Monthly, Flexible Term Payment Model: Premium-Based, Co-Payment, Reimbursement, Fixed Coverage |
| Companies Covered | Ping An Insurance, China Life Insurance, People's Insurance Company of China, China Pacific Insurance, China Taiping Insurance Holdings, New China Life Insurance, Taikang Life Insurance, Minsheng Life Insurance, Huaxia Life Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Group Health Insurance Market Trends and Innovations
Digital infrastructure is compressing the traditional separation between risk assessment, policy issuance, and claims settlement into continuous data loops.
Blockchain-enabled smart contracts are unifying premium collection, eligibility verification, and automated claims payment into single distributed ledgers. Large manufacturing employers in Jiangsu province are piloting real-time payroll-deduction integration. This architecture is unifying previously siloed HR, finance, and insurance operations into unified employee benefit platforms.
China's National Financial Regulatory Administration has tightened solvency reporting requirements for group health riders under revised Insurance Law implementation rules. Product filing timelines have extended from 30 to 60 days for supplementary inpatient coverage. Foreign-invested joint ventures are responding by localizing actuarial teams to accelerate regulatory response cycles.
Employer procurement of group health coverage is fragmenting from centralized HR decisions toward employee-choice architectures. Technology sector firms in Hangzhou and Chengdu are adopting flexible benefit allowances that permit staff to allocate budgets across medical, dental, and wellness modules. This shift is most visible among unicorn-stage companies competing for engineering talent against state-backed competitors.
China Group Health Insurance Market Segmentation
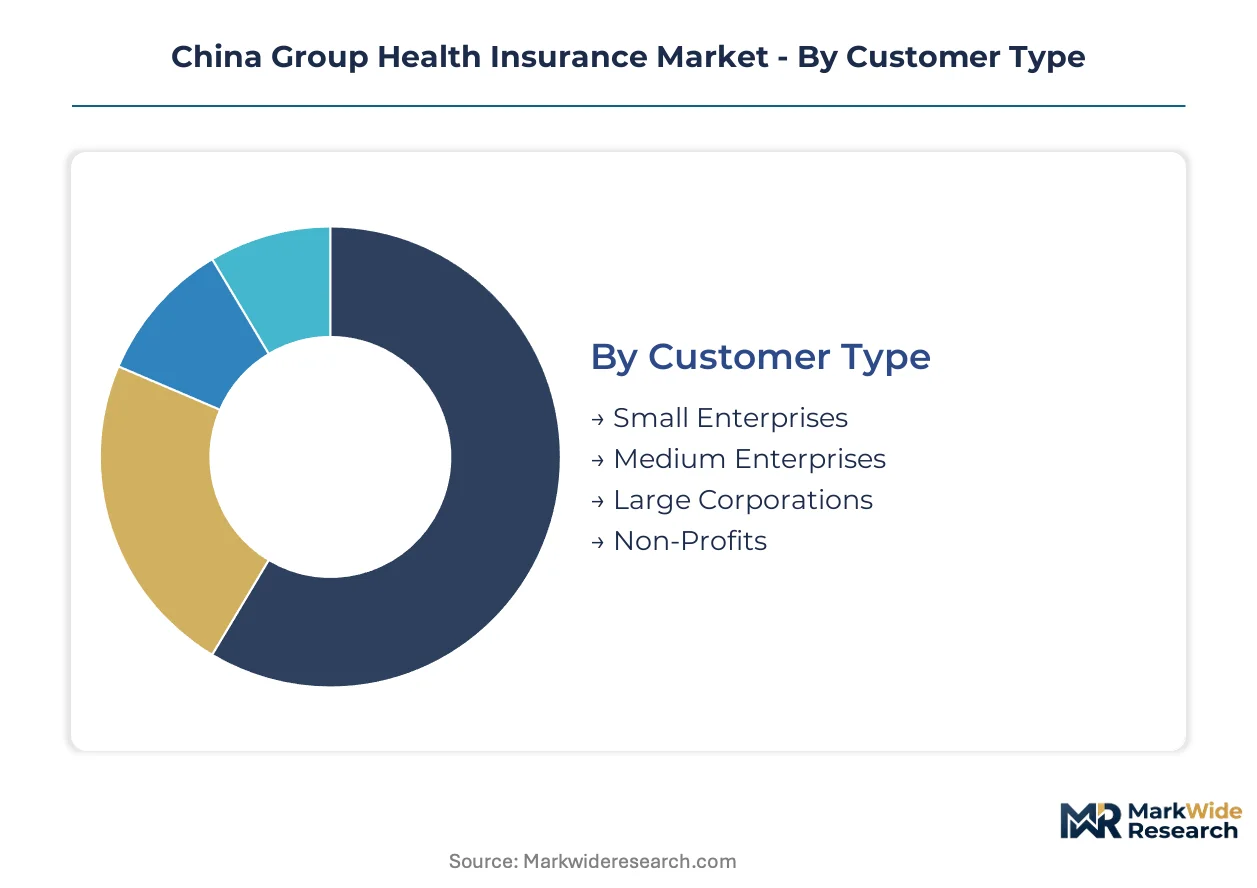
China's group health insurance market fragments across employer size, benefit design, and administrative architecture. Each segmentation dimension reflects distinct risk pooling economics and regulatory compliance requirements. Insurers must align product portfolios with the specific cost structures and employee demographics of each segment category.
Customer Type:
Standardization dominates at the large-employer end of this spectrum, while small enterprises demand configurable benefit modules and streamlined enrollment platforms.
- Small Enterprises:Micro-business clustering platforms aggregate underwriting risk across dispersed employer pools, reducing administrative costs below traditional group policy thresholds. Demand concentrates in Hangzhou and Chengdu where digital-native startups lack dedicated HR infrastructure but face intense talent competition from state-backed employers.
- Large Corporations:Mandatory participation rules and SASAC directives lock in comprehensive coverage frameworks with negotiated inpatient reimbursement ceilings and critical illness lump-sum triggers. Central state-owned enterprises in Beijing and Shanghai channel the deepest premium volumes through exclusive bancassurance distribution.
- Medium Enterprises:Hybrid procurement approaches blend standardized core benefits with elective wellness riders.
- Non-Profits:Budget-constrained coverage prioritizes catastrophic protection over routine care access.
Most installed capacity flows through Large Corporations. Expansion is steepest in Small Enterprises.
Coverage Type:
Cost tier stratification separates hospitalization reimbursement from preventive services, with premium allocation reflecting severity-weighted actuarial risk.
- Inpatient Coverage:Tertiary hospital reimbursement ceilings anchor the premium pool, though margin compression intensifies as medical cost inflation outpaces pricing adjustments. Municipal social insurance integration pilots in tier-one cities are reshaping supplementary layer positioning.
- Critical Illness:Lump-sum triggers upon diagnosis of specified conditions provide liquidity for treatment access and income replacement. Technology sector employers in Shenzhen bundle this coverage with stock option vesting schedules to engineer retention hooks.
- Outpatient Coverage:Copayment ratios vary by facility tier under municipal social insurance coordination.
- Preventive Care:Annual health screening mandates in Beijing pilots are shifting premium weight toward wellness outcomes.
Most installed capacity flows through Inpatient Coverage. Expansion is steepest in Preventive Care.
Policy Duration:
Customer type dictates duration preferences, with large employers favoring multi-year stability and small businesses requiring enrollment flexibility.
- Annual:Standard renewal cycles align with corporate fiscal planning and regulatory filing calendars. State-owned enterprises in Shanghai and Beijing lock in twelve-month terms to synchronize with social insurance contribution schedules.
- Flexible Term:Project-based and seasonal workforces demand pro-rated coverage windows. Gig-economy platforms in Guangzhou pilot month-to-month structures for delivery and ride-hail driver pools.
- Biennial:Multi-year commitments reduce administrative overhead for stable corporate workforces.
- Monthly:High-turnover sectors use short-duration policies to minimize premium leakage from employee churn.
Most installed capacity flows through Annual. Expansion is steepest in Flexible Term.
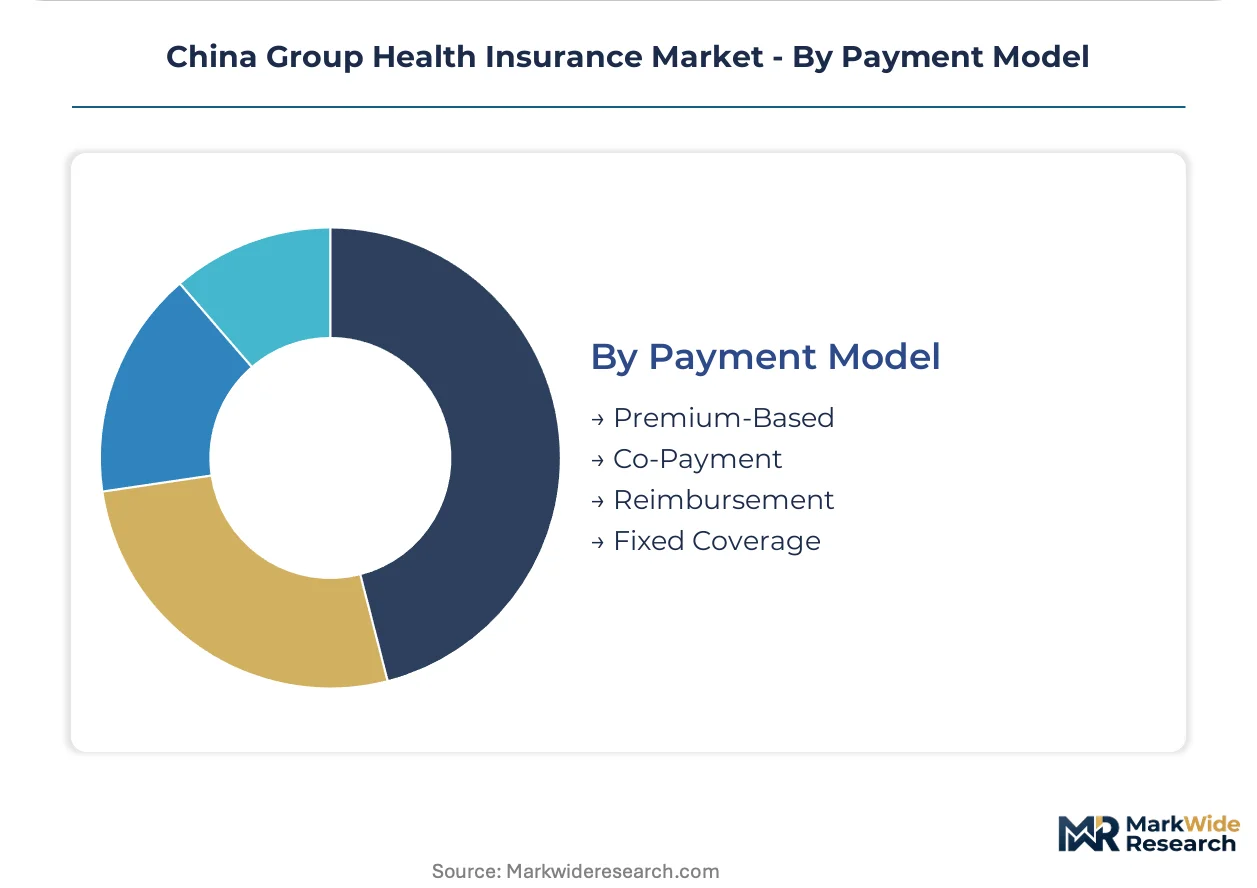
Payment Model:
Margin structure varies sharply across payment architectures, with reimbursement models bearing administrative complexity and fixed coverage models transferring utilization risk to policyholders.
- Premium-Based:Upfront payment locks in coverage ceilings with predictable insurer cash flow. Large manufacturing employers in Jiangsu province integrate real-time payroll deduction via blockchain-enabled smart contract infrastructure.
- Reimbursement:Post-service claim settlement dominates inpatient coverage where treatment costs exceed prepayment feasibility. Provincial social insurance database fragmentation forces parallel claims adjudication systems.
- Co-Payment:Cost-sharing ratios reduce moral hazard in outpatient utilization.
- Fixed Coverage:Predetermined benefit amounts simplify administration but limit protection depth.
Most installed capacity flows through Premium-Based. Expansion is steepest in Reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta corporate benefit budgets anchor national premium concentration, with Shanghai municipal wellness mandates driving supplementary insurance enrollment pipelines. State-owned enterprise clusters in Beijing-Tianjin-Hebei and technology employer pools in Pearl River Delta generate complementary demand waves. Provincial social insurance integration pilots reshape competitive positioning across tier-one urban corridors.
Yangtze River Delta
Shanghai municipal governments mandate expanded corporate wellness benefits under Healthy China 2030 implementation, creating compulsory enrollment channels for commercial group riders. The National Healthcare Security Administration coordinates supplementary insurance frameworks that merge basic medical coverage with commercial layers. Manufacturing employers in Jiangsu province pilot blockchain-enabled payroll deduction integration for real-time premium collection.
Beijing-Tianjin-Hebei
Central SASAC directives require state-owned enterprises to enhance employee retention packages, channeling premium volume toward inpatient reimbursement products. The National Financial Regulatory Administration supervises product filing and solvency requirements under revised Insurance Law implementation rules. Beijing municipal pilots integrate annual health screening mandates into group policy pricing, shifting premium pools toward wellness outcomes.
Pearl River Delta
Technology sector employers in Shenzhen bundle critical illness coverage with stock option vesting schedules to engineer retention hooks for engineering talent. The Banking and Insurance Regulatory Information System mandates standardized data reporting that shapes product design granularity. Guangzhou gig-economy platforms pilot month-to-month policy structures for delivery and ride-hail driver pools.
Sichuan-Chongqing
Digital-native startups in Chengdu lack dedicated HR infrastructure but face intense talent competition from state-backed employers, accelerating micro-business clustering platform adoption. Provincial social insurance databases lack API standardization, forcing insurers to maintain parallel claims adjudication infrastructure. Chongqing's expanding automotive and electronics manufacturing base drives medium-enterprise hybrid procurement approaches.
Shandong Peninsula
Heavy industry employers in Qingdao and Yantai lock in comprehensive coverage frameworks with negotiated inpatient reimbursement ceilings under mandatory participation rules. Municipal social insurance contribution mandates in Jinan enforce baseline coverage that commercial products supplement. Aging employee populations in coastal manufacturing cities generate demand for nursing home access bundling with medical coverage.
China Group Health Insurance Market Competitive Landscape
Portfolio diversification dominates the current landscape as insurers reposition group products as supplementary layers atop basic medical schemes. State-backed incumbents leverage exclusive bancassurance distribution channels while private carriers build digital health ecosystems. Three archetypes define competitive positioning: state-owned integrated financial conglomerates, private digital-first insurers, and foreign-invested joint ventures with localized actuarial teams. M&A activity and telemedicine platform integration represent the dominant competitive vectors reshaping market share distribution.
Within the state-backed tier, Ping An Insurance and China Life Insurance anchor competitive dynamics through divergent strategic architectures. Ping An leverages its Ping An Good Doctor ecosystem to integrate telemedicine with corporate benefit plans, collapsing traditional agent acquisition costs. China Life anchors its group health portfolio through exclusive bancassurance partnerships with state-owned banks, locking in premium volume from central SOEs in Beijing and Shanghai. Taikang Life Insurance occupies a differentiated position via elderly-care-linked group policies that bundle nursing home access with medical coverage, targeting aging employee populations in Shenzhen and Guangzhou corporate pools.
| Leading Market Players |
|---|
| Ping An Insurance |
| China Life Insurance |
| People's Insurance Company of China |
| China Pacific Insurance |
| China Taiping Insurance Holdings |
| New China Life Insurance |
| Taikang Life Insurance |
| Minsheng Life Insurance |
| Huaxia Life Insurance |
| Others |
Pricing and Supply Chain Analysis
State-owned enterprise procurement clusters in Beijing and Shanghai anchor premium-tier pricing power, locking in multi-year contracts with negotiated inpatient reimbursement ceilings that compress margin flexibility for commercial carriers. This buyer concentration forces private insurers toward micro-enterprise segments where digital clustering platforms enable dynamic premium adjustment based on real-time enrollment volatility.
Pricing Analysis
Hospital cost inflation passes through to premium adjustments faster than social insurance reimbursement benchmarks can absorb, compressing insurer margins on core inpatient products. Premium-mid-economy pricing differentiation separates central SOE comprehensive packages from configurable small-business modules. Cost compression in standard-tier coverage is intensifying because tertiary hospital pricing power outpaces municipal supplementary insurance integration pilots. Small enterprises exhibit highest price sensitivity due to thin benefit budgets, while technology sector employers in Shenzhen show lowest sensitivity when bundling critical illness coverage with equity compensation.
Supply Chain Analysis
Claims adjudication infrastructure rests on provincial social insurance databases across China, with API fragmentation forcing parallel system maintenance by commercial carriers. Medical service delivery concentrates in tier-one city hospital networks, while actuarial talent pools center on Beijing and Shanghai. Single-source vulnerability runs through the Banking and Insurance Regulatory Information System's localized reporting standards that impede cross-province policy administration. Distribution runs through exclusive bancassurance partnerships for state-backed incumbents and telemedicine-embedded digital channels for private competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's group health insurance market offers margin expansion through preventive care premium weighting under Healthy China 2030 municipal pilots, as wellness outcome pricing shifts value capture from inpatient reimbursement toward longitudinal risk management.
For Market Incumbents: Acquire telemedicine platform capabilities to collapse agent acquisition costs and defend against digital-native entrants embedding insurance into remote consultation workflows. Central SASAC benefit expansion directives lock in SOE premium volume but require accelerated regulatory response cycles as National Financial Regulatory Administration filing timelines extend. Backward integration into elderly-care facility networks captures aging employee population demand in Shenzhen and Guangzhou corporate pools. For New Entrants and Emerging Players: National Healthcare Security Administration supplementary insurance framework reforms in tier-one cities open a window for positioning group products as mandatory-merge layers atop basic medical schemes. Micro-enterprise clustering platforms in Hangzhou and Chengdu represent the most penetrable segment, where digital-native startups lack HR infrastructure but face acute talent competition. Go-to-market execution should anchor on real-time payroll-deduction integration via blockchain-enabled smart contract infrastructure piloted in Jiangsu province manufacturing employers. For Investors and Strategic Acquirers: Foreign-invested joint ventures with localized actuarial teams are the most active acquirer in this space, responding to tightened solvency reporting requirements under revised Insurance Law implementation. Long-term viability centers on capturing the shift from inpatient reimbursement toward preventive care and elderly-care convergence products. Watch municipal integration pilots that merge basic medical insurance with commercial group supplements as the signal for supplementary layer positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Ping An Good Doctor collapses traditional agent acquisition costs into remote consultation workflows. |
| Elderly-Care Facility Network Expansion | Taikang Life bundles nursing home access with medical coverage for aging Shenzhen employee pools. |
| Blockchain-Enabled Payroll Deduction | Jiangsu province manufacturing employers pilot real-time premium collection via distributed ledger infrastructure. |
| Localized Actuarial Team Buildout | Foreign-invested joint ventures accelerate regulatory response cycles as product filing timelines extend. |
| Preventive Care Premium Weighting | Beijing municipal pilots integrate annual health screening mandates into group policy pricing structures. |
Research Methodology
Coverage spans Yangtze River Delta, Beijing-Tianjin-Hebei, Pearl River Delta, and Sichuan-Chongqing, with primary inputs from each region's corporate benefits managers, insurance product development executives, National Healthcare Security Administration policy officers, and hospital procurement administrators. Secondary validation draws from National Financial Regulatory Administration solvency filings, Banking and Insurance Regulatory Information System data reporting standards, and municipal social insurance integration pilot documentation. Bottom-up enrollment data triangulates against top-down premium volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across employer size tiers, coverage type categories, and policy duration segments. The analytical framework models customer type, coverage design, payment architecture, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from enrollment trajectory analysis and premium per covered life trends, with inputs from SASAC directive implementation timelines and Healthy China 2030 municipal mandate rollout patterns.
Revisions become necessary when National Healthcare Security Administration framework reforms accelerate, tertiary hospital pricing power triggers reimbursement ceiling adjustments, or provincial social insurance database API standardization advances beyond current fragmentation. Forecasts reflect documented assumptions regarding regulatory filing timeline stability and municipal pilot expansion velocity. A small set of named triggers warrants ongoing watch: SASAC benefit expansion directive scope, telemedicine platform regulatory classification, and cross-province policy portability mechanism development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United States Commercial Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
IoT Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Car Insurance Market
Insurance
Embedded Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Canada Home Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
US Long-Term Care Private Insurance Market