
 Property and Casualty Insurance Market | 2026-2036
Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Property and Casualty Insurance Market Analytics
Telematics data is broadening risk-modeling precision across auto underwriting. State Farm Group leverages its captive agency network to sustain regional pricing power in homeowners lines. Progressive Ins Group anchors its competitive stance through direct-to-consumer digital distribution. Berkshire Hathaway Ins differentiates via reinsurance-backed capital capacity that absorbs catastrophic property exposures.
Property and casualty insurance is a risk-transfer mechanism where insurers pool premiums to indemnify policyholders against specified perils including fire, liability, and natural catastrophe, with reserves regulated under statutory accounting principles. Its primary commercial purpose is to restore capital and operational continuity after fortuitous losses. Auto coverage leads premium volume among policy type segments, while commercial lines command wider margins due to complex risk engineering. Online platforms represent the fastest-growing distribution channel, though independent brokers still dominate middle-market placements where coverage customization matters.
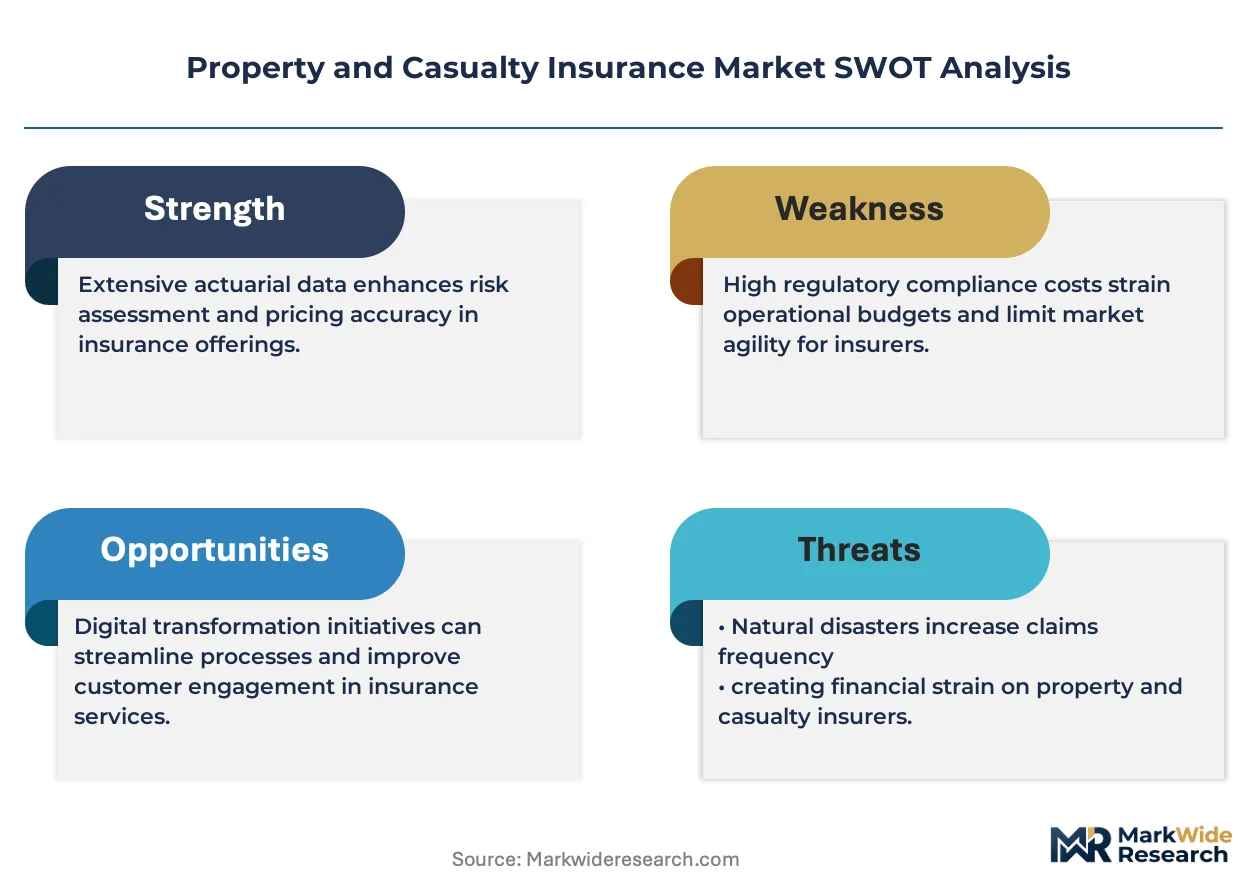
The National Association of Insurance Commissioners coordinates state-level reserve standards and rate-filing oversight across the United States. The EU's Solvency II framework and the UK's Prudential Regulation Authority impose risk-based capital requirements that shape product design and market entry. Climate stress testing by the Federal Reserve and EIOPA is forcing carriers to reprice catastrophe-exposed portfolios. Stakeholders must decide whether to build in-house climate analytics capabilities or license third-party catastrophe models as underwriting volatility intensifies.
Market Dynamics
Climate stress testing by the Federal Reserve and EIOPA is forcing carriers to reprice catastrophe-exposed portfolios, compressing margins in high-risk geographies while capital migrates toward climate-resilient underwriting models.
Growth Catalysts
- Telematics penetration:Connected vehicle data streams are enabling usage-based pricing models that align premiums with actual driving behavior, expanding addressable markets among price-sensitive auto policyholders.
- EU Digital Operational Resilience Act:DORA mandates operational resilience frameworks that compel financial institutions to purchase enhanced cyber coverage, creating mandatory demand pools.
- Litigation financing expansion:Third-party litigation funding in the United States sustains elevated liability claim frequency, driving commercial general liability premium growth.
Market Restraints
- Reinsurance capacity tightening:Catastrophe bond spreads and collateralized reinsurance pricing have hardened, raising cost-of-capital for primary carriers writing property risks.
- Long-tail asbestos and environmental reserves:Legacy liability lines continue generating adverse development, trapping capital in runoff portfolios that constrain strategic redeployment.
- Social inflation in US tort costs:Nuclear verdicts in state jurisdictions with elected judges amplify severity trends beyond actuarial pricing assumptions.
Strategic Opportunities
- Embedded insurance distribution:Point-of-sale integration with auto lenders and property technology platforms enables frictionless policy origination at transaction moments.
- Parametric crop coverage:Satellite-indexed triggers eliminate claims adjustment costs while expanding penetration among agricultural producers in climate-vulnerable regions.
- India's regulatory sandbox:IRDAI's innovation framework permits controlled testing of microinsurance products for informal sector workers previously excluded from formal coverage.
Industry Challenges
- Catastrophe model recalibration:Vendor model updates reflecting non-stationary climate assumptions create reserve volatility and rating agency scrutiny.
- Core system modernization:Policy administration platforms built on COBOL architectures impede real-time data integration with IoT sensors and third-party data providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Property and Casualty Insurance Market |
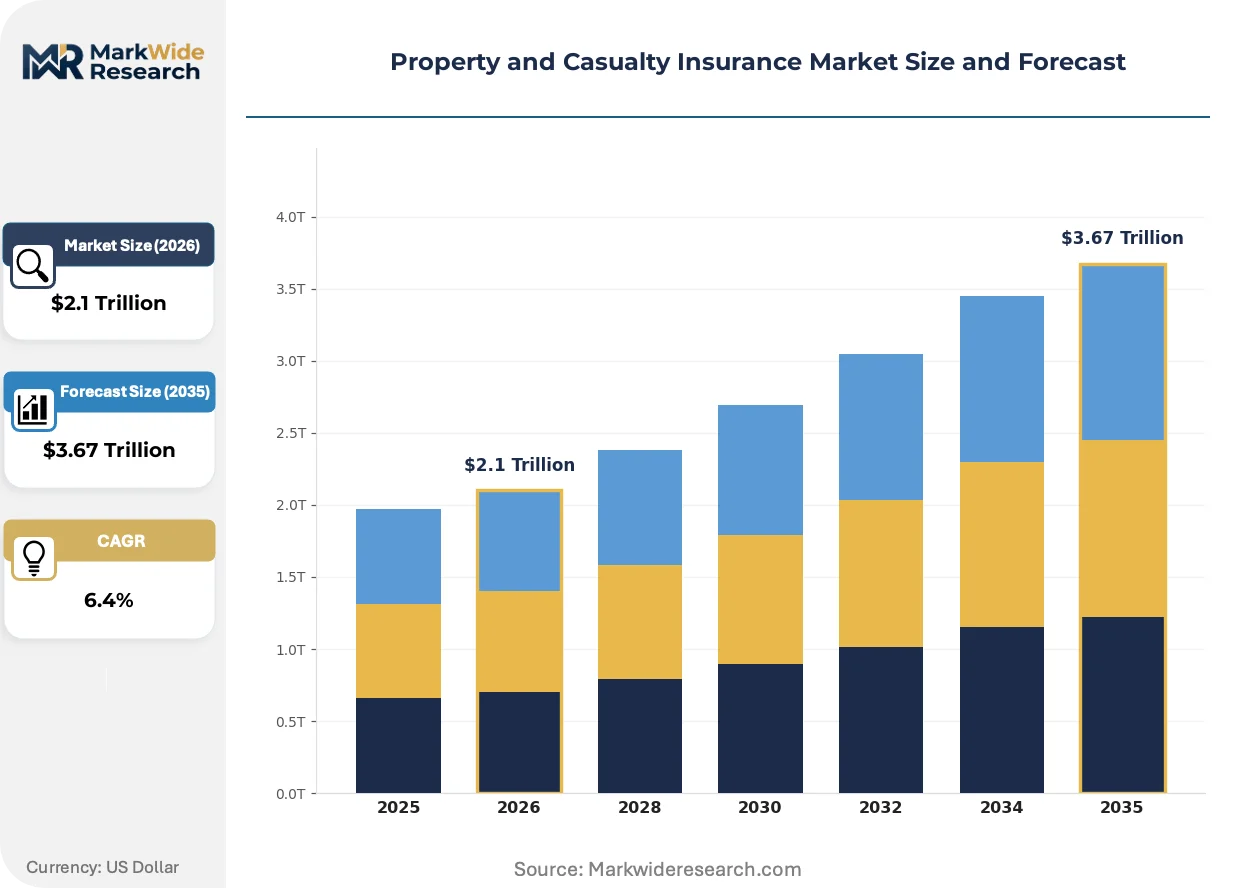
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.67 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Homeowners, Renters, Auto, Commercial Coverage Type: Liability, Comprehensive, Collision, Personal Injury Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Customer Type: Individuals, Small Businesses, Corporations, Nonprofits |
| Companies Covered | State Farm Group, Berkshire Hathaway Ins, Progressive Ins Group, Allstate Ins Group, Liberty Mutual Ins Cos, Travelers Group, USAA Group, Chubb INA Group, Nationwide Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Property and Casualty Insurance Market Evolving Landscape
Data ingestion pipelines and algorithmic decisioning are compressing underwriting cycles from weeks to minutes, redefining carrier-policyholder interaction models across personal and commercial lines.
Computer vision damage assessment is electrifying claims processing workflows. Auto carriers deploy smartphone-based image analysis to estimate collision repair costs within hours of first notice of loss. Commercial property underwriters apply satellite imagery to validate roof condition and occupancy data at bind. This compression of indemnification timelines is electrifying customer retention metrics and reducing loss adjustment expense ratios.
The EU's Digital Operational Resilience Act imposes mandatory ICT risk management standards on financial entities including insurers. Carriers must map critical dependencies, test recovery capabilities, and report major incidents to national competent authorities. Cross-border groups face overlapping compliance obligations where home and host regulators assert concurrent supervisory rights.
Small commercial buyers increasingly bypass traditional agent channels for direct digital platforms that quote and bind in single sessions. InsurTech aggregators capture this demand by unbundling coverage components and enabling self-service policy customization. This channel migration is most pronounced among micro-enterprises with straightforward risk profiles and limited advisory service requirements.
Property and Casualty Insurance Market Segmentation
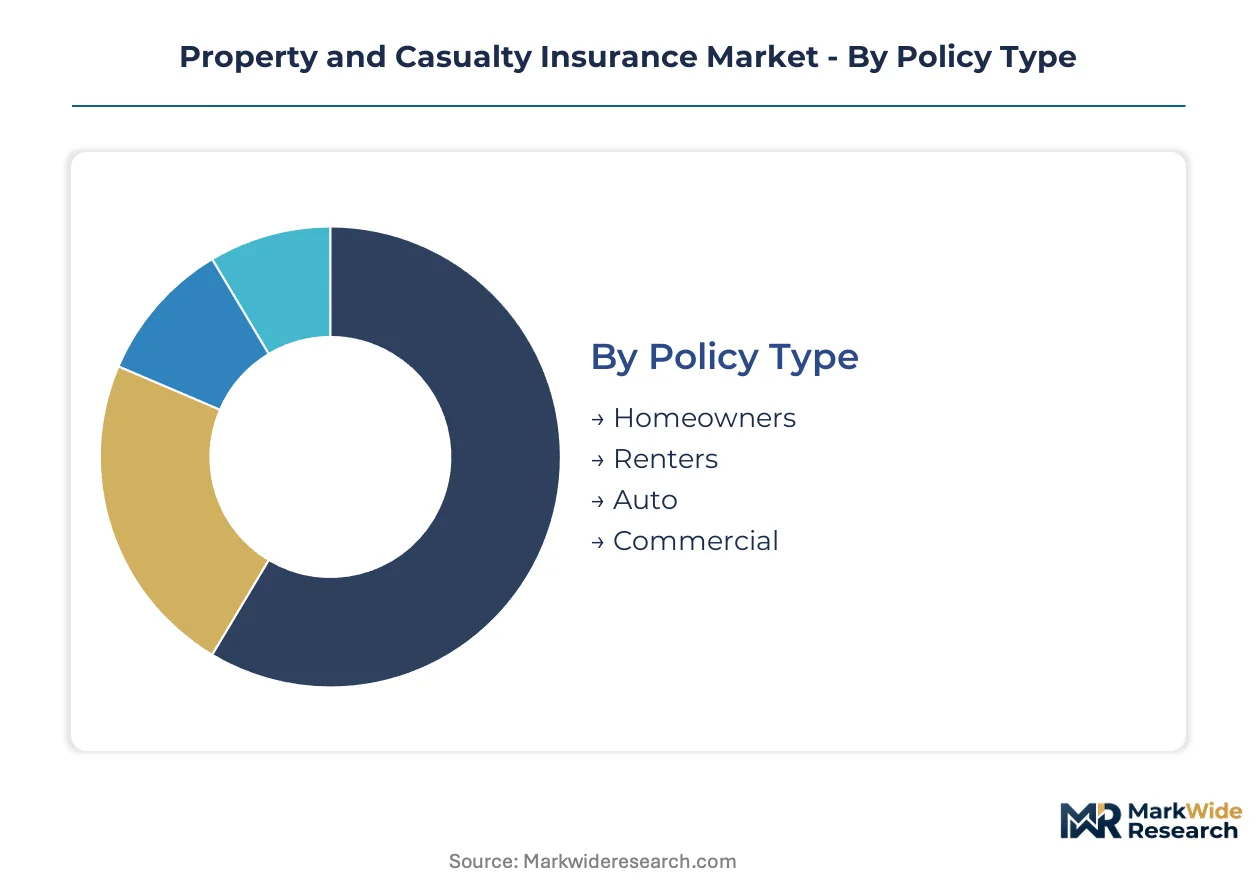
Segmentation in property and casualty insurance determines capital allocation, pricing precision, and distribution investment. Distinct risk profiles across policy types and customer categories demand specialized underwriting infrastructure and separate reserving methodologies.
Policy Type:
Auto and homeowners policies function as standalone consumer purchases with standardized forms, while commercial lines embed within broader risk management programs requiring bespoke engineering.
- Homeowners:Multi-peril contracts covering dwelling, contents, and liability exposure under unified policy forms. Demand clusters in coastal United States counties where mortgage lenders mandate coverage; catastrophe model recalibration is compressing margins in high-wind zones. Volume placements concentrate in Homeowners; the faster expansion belongs to Commercial.
- Auto:Personal and commercial vehicle coverage split between personal auto (private passenger) and commercial auto (fleet and specialty vehicles). Telematics integration is accelerating in this segment as Progressive and State Farm deploy usage-based pricing algorithms.
- Renters:Contents and liability coverage for non-owner occupants with lower premium per policy but minimal loss adjustment expense. Urban multifamily construction in Texas and Florida metros sustains placement growth.
- Commercial:General liability, property, and specialty lines for enterprise risk transfer. Complex underwriting requirements sustain broker channel dominance and wider expense ratios.
Homeowners captures the highest policy count; Commercial lines command the steepest expansion trajectory.
Coverage Type:
Cost tier differentiation separates mandatory liability minimums from optional comprehensive protection, with collision and personal injury occupying intermediate price points.
- Liability:Third-party injury and property damage indemnity triggered by legal negligence findings. Social inflation in US state courts is amplifying severity beyond historical pricing bands.
- Comprehensive:Named-peril coverage for theft, vandalism, and weather damage excluding collision. This segment gains share fastest as lenders require full physical damage protection for financed vehicles.
- Collision:First-party vehicle damage coverage irrespective of fault. Repair cost inflation and parts scarcity are elevating loss costs in this mature segment.
- Personal Injury:Medical payments and no-fault coverage for occupant injuries. Regulatory fragmentation across US states creates pricing complexity.
Mandatory Liability placements dominate policy volume; Comprehensive coverage is climbing the fastest among optional protections.
Distribution Channel:
Customer type dictates channel preference, with individuals gravitating toward digital self-service while corporations demand advisory-intensive placement.
- Direct Sales:Carrier-owned channels including call centers and proprietary websites. GEICO and Progressive anchor this model with advertising-intensive customer acquisition.
- Brokers:Independent intermediaries accessing multiple carrier markets for commercial and complex personal risks. Middle-market commercial buyers rely on broker expertise for coverage customization.
- Online Platforms:InsurTech aggregators and embedded insurance APIs enabling quote comparison and instant bind. This channel is expanding most quickly among micro-enterprises and price-sensitive auto shoppers.
- Agents:Captive and independent producers building local relationships for homeowners and small commercial accounts. State Farm's captive network sustains regional pricing power through this channel.
Agent-driven placements retain the largest volume share; Online Platforms are gaining share fastest among emerging customer cohorts.
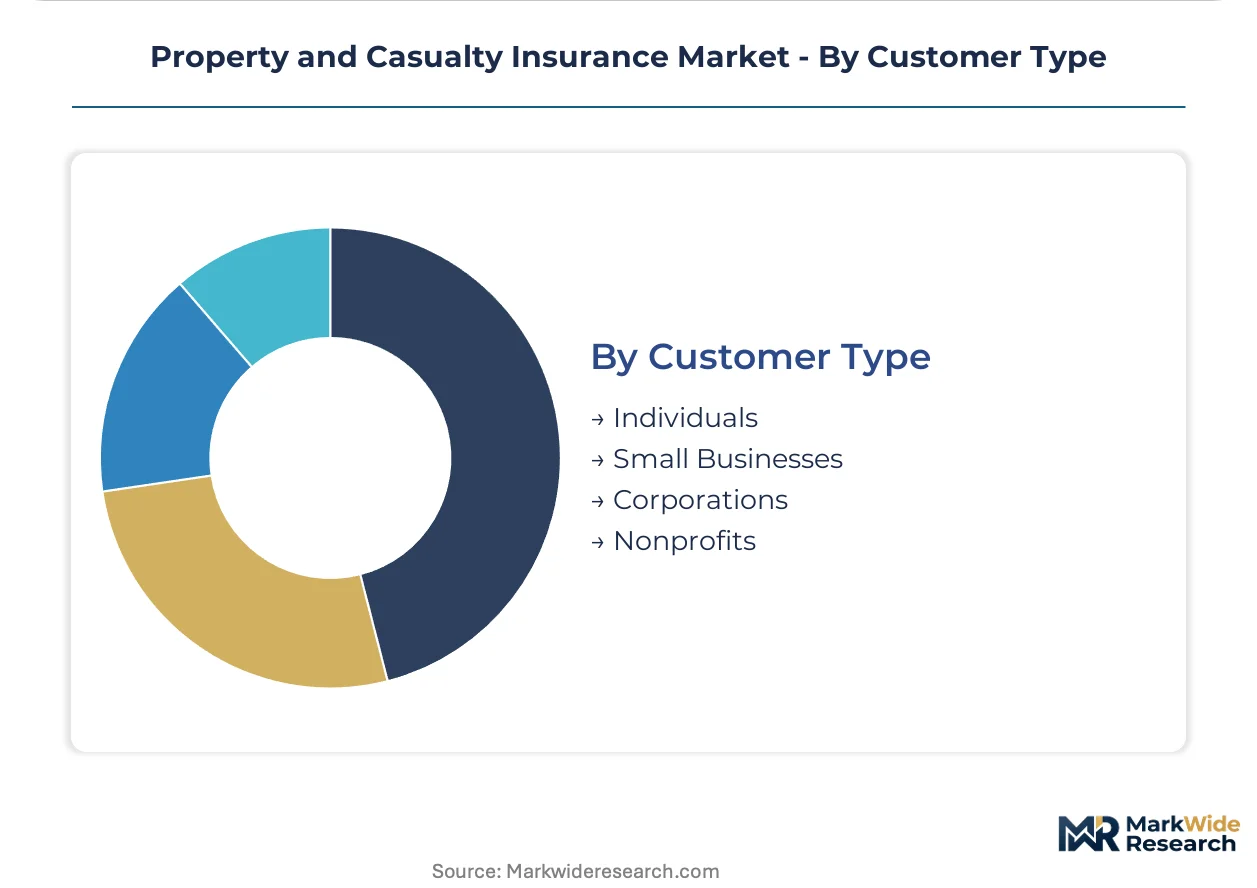
Customer Type:
Application complexity scales from standardized individual policies to multinational corporate programs requiring captive structures and fronting arrangements.
- Individuals:Personal lines buyers with homogeneous risk profiles and price-elastic demand. Digital distribution penetration is highest in this segment.
- Small Businesses:Commercial package policy buyers with straightforward operations and limited risk engineering requirements. Business Owners Policy (BOP) forms dominate this tier.
- Corporations:Large commercial buyers with complex global exposures requiring specialty lines and alternative risk transfer. D&O, cyber, and international property programs concentrate here; this segment shows the steepest premium growth.
- Nonprofits:Mission-driven organizations with unique liability exposures including directors and officers, employment practices, and abuse coverage. Underwriting expertise scarcity limits carrier participation.
Individual policyholders generate the highest transaction count; Corporate accounts deliver the fastest premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bermuda and Singapore concentrate captive insurance formations, attracting capital through favorable regulatory treatment and tax-efficient domicile structures that reduce operational costs for multinational risk retention.
United States
Catastrophic weather exposure and litigation financing sustain premium expansion across Florida, Texas, and California coastal counties. The National Association of Insurance Commissioners coordinates state-level reserve standards that shape carrier solvency requirements. Miami-Dade and Houston metropolitan clusters concentrate homeowners policy volume where mortgage lenders mandate wind and flood coverage.
United Kingdom
London's Lloyd's market anchors specialty and excess lines placement for global commercial risks. The Prudential Regulation Authority imposes risk-based capital requirements under Solvency II equivalence arrangements. The City of London insurance cluster processes complex international property and marine exposures through broker-mediated subscription markets.
Germany
Industrial manufacturing concentration in Bavaria and North Rhine-Westphalia drives commercial property and liability demand. BaFin enforces stringent solvency supervision that influences product design across the European Economic Area. Munich and Frankfurt host major carrier headquarters where engineering-driven underwriting serves automotive and chemical sector clients.
China
Rapid urbanization and vehicle fleet expansion accelerate auto and property coverage penetration in tier-one cities. The National Financial Regulatory Administration implements consumer protection rules that standardize policy terms and disclosure requirements. Shanghai and Shenzhen insurance clusters develop digital distribution platforms targeting mass-market personal lines buyers.
India
Motor third-party liability mandates and rising vehicle ownership expand policy volumes across Maharashtra and Karnataka. IRDAI's regulatory sandbox permits controlled testing of microinsurance products for informal sector workers. Mumbai and Bengaluru fintech clusters embed insurance distribution within ride-hailing and e-commerce transaction flows.
Property and Casualty Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with personal lines consolidating around direct-to-consumer platforms while commercial placement fragments across broker-mediated markets. The United States dominates carrier headquarters concentration, though Bermuda and London maintain captive and specialty line dominance. Three archetypes define positioning: capital-heavy mutuals with agency networks, direct writers with advertising-intensive acquisition, and global commercial specialists with treaty reinsurance backing. Competitive moves center on telematics data integration and embedded distribution partnerships with auto lenders and property technology platforms.
Among US-based mutual carriers, State Farm Group exemplifies the captive agency archetype sustaining regional pricing power through localized producer relationships. Progressive Ins Group anchors the direct-to-consumer vector with digital-first quoting infrastructure and usage-based pricing algorithms. Berkshire Hathaway Ins occupies the capital-capacity tier, absorbing catastrophic property exposures through reinsurance-backed balance sheet strength.
| Leading Market Players |
|---|
| State Farm Group |
| Berkshire Hathaway Ins |
| Progressive Ins Group |
| Allstate Ins Group |
| Liberty Mutual Ins Cos |
| Travelers Group |
| USAA Group |
| Chubb INA Group |
| Nationwide Group |
| Others |
Value Network & Pricing Analysis
Corporate risk managers at Fortune 500 manufacturers anchor the commercial property and casualty insurance market's pricing model, their concentrated purchasing power driving contract-based long-term placements that reward multi-year commitments with rate stability and bundled coverage discounts. This buyer archetype's procurement sophistication compresses margins for primary carriers while elevating pricing power for reinsurance-backed specialists with demonstrated catastrophe response capabilities.
Pricing Analysis
Expedited policy issuance commands premium pricing in commercial lines, where brokers and risk managers pay surcharges for same-day bind authority on complex multi-peril programs. The market structures around three-tier pricing separating admitted carriers from surplus lines specialists and captive alternatives, with differentiation resting on AM Best rating tiers and claims-paying track records. Pricing pressure stems from reinsurance cost-of-capital increases that primary carriers cannot fully pass through to rate-regulated personal lines. Small commercial buyers exhibit highest price elasticity, while multinational corporations prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Regional distribution centers in London, Bermuda, and Singapore anchor the insurance supply chain's hub-and-spoke pattern, concentrating underwriting capacity, regulatory expertise, and capital formation in specialized financial zones. Carrier operations draw from actuarial talent pools in the United States and United Kingdom, technology infrastructure from Ireland and India, and catastrophe modeling services from specialized vendors in the United States and United Kingdom. Single-source vulnerability concentrates in third-party catastrophe model dependencies, where vendor recalibrations cascade through reserving and pricing decisions. Distribution runs through broker-mediated subscription markets for commercial risks and direct digital platforms for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinsurance capacity constraints prop pricing discipline across catastrophe-exposed portfolios, sustaining carrier profitability despite elevated loss costs in coastal United States markets.
For Market Incumbents: Acquire telematics data assets and climate analytics capabilities to fortify underwriting precision against InsurTech challengers deploying algorithmic pricing. State Farm's captive agency network demonstrates how localized distribution control defends regional pricing power; replicate this through exclusive producer arrangements in high-retention geographies. Backward integration into catastrophe modeling reduces vendor dependency and accelerates rate adequacy responses. For New Entrants and Emerging Players: Embedded insurance APIs at point-of-sale transaction moments offer the lowest-friction entry vector for digital-native carriers without legacy distribution infrastructure. India's regulatory sandbox permits controlled microinsurance testing for informal sector workers excluded from formal coverage, representing the most penetrable white-space geography. Partner with auto lenders and property technology platforms to capture policy origination at financing and lease execution moments. For Investors and Strategic Acquirers: The window for entry favors specialty commercial carriers with demonstrated catastrophe response capabilities and established broker relationships. Mid-tier mutual insurers with excess capital and aging membership bases present consolidation targets for acquirers seeking in-force policy blocks and state regulatory licenses. Watch reinsurance renewal pricing as the inflection signal; hardening collateralized capacity markets indicate sustained primary carrier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Progressive's usage-based pricing algorithms demonstrate how driving behavior data compresses loss ratios and expands addressable markets. |
| Embedded Distribution Integration | Point-of-sale policy origination with auto lenders captures customers at peak coverage intent with minimal acquisition cost. |
| Catastrophe Model Backward Integration | In-house climate analytics capabilities reduce vendor dependency and accelerate rate adequacy responses to non-stationary risk assumptions. |
| Regulatory Sandbox Market Entry | IRDAI's innovation framework permits controlled microinsurance testing for informal sector workers previously excluded from coverage. |
| Reinsurance Treaty Restructuring | Berkshire Hathaway's capital capacity demonstrates how reinsurance-backed balance sheets absorb peak catastrophe exposures that constrain competitors. |
Research Methodology
NAIC rate filings, SEC 10-K insurance segment disclosures, and Lloyd's market performance reports formed the secondary backbone, supplemented by Lloyd's subscription market data and EIOPA stress testing disclosures. Primary interviews with chief underwriting officers, reinsurance brokers, catastrophe model vendors, and state insurance commissioners validated quantitative assumptions and refined segmentation boundaries. Bottom-up policy count and premium volume estimates triangulated against top-down carrier revenue disclosures across the analysis window.
Historical premium trendline analysis informed baseline growth assumptions, with segmentation dimensions spanning policy type, coverage tier, distribution channel, and customer complexity category. Modeled outputs incorporate catastrophe loss simulation outputs, telematics penetration trajectories, and regulatory capital requirement changes throughout the forecast period. CAGRs derive from fitted trend extrapolation moderated by structural shift assumptions including channel migration and climate risk repricing.
Inputs from NAIC statistical compilations and Lloyd's market data were available through the study window; gaps in non-public reinsurance pricing introduce uncertainty bands around catastrophe-exposed portfolio forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Car Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Global SME Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Global Home Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
Jewelry Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Crop Insurance Market
Insurance
Saudi Arabia Health Insurance Market