
 US Homeowner's Insurance Market | 2026-2036
US Homeowner's Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Homeowner's Insurance Market Analytics
Florida's residential property market is hardening after consecutive hurricane seasons strained regional carrier solvency. State Farm leverages its captive agency network to sustain underwriting discipline in catastrophe-prone counties. Allstate competes through granular pricing models that segment risk at the ZIP-code level. Progressive anchors its homeowner portfolio with auto-policy bundling that reduces customer acquisition costs.
US homeowner's insurance is a property and casualty contract indemnifying residential structures, personal contents, and third-party liability against named perils, typically written on an HO-3 or HO-5 form with replacement-cost valuation and sublimits for jewelry, water backup, and ordinance coverage. Dwelling coverage dominates premium volume as reconstruction costs outpace inflation in lumber and labor markets. Liability coverage represents the fastest-expanding margin pool as social inflation drives nuclear verdicts in premises cases. Single-family home policies constitute the mature core, while condominium and townhouse products face structural growth from urban infill development and aging millennial household formation.
NAIC rate filing standards, state-specific windstorm pool mandates, and FEMA flood insurance requirements collectively shape product design and distribution eligibility across jurisdictions. The National Flood Insurance Program's risk rating overhaul is forcing carriers to clarify private flood endorsements or exclude water damage entirely. Stakeholders must monitor whether state regulators in Texas, California, and Florida approve sufficient rate adequacy to prevent further carrier withdrawals from high-risk markets.
Market Dynamics
NAIC rate filing scrutiny is compressing carrier timelines for premium adequacy adjustments as reconstruction costs surge and catastrophe models demand recalibration. State regulators balance consumer affordability mandates against solvency requirements, forcing product redesign and selective market participation.
Growth Catalysts
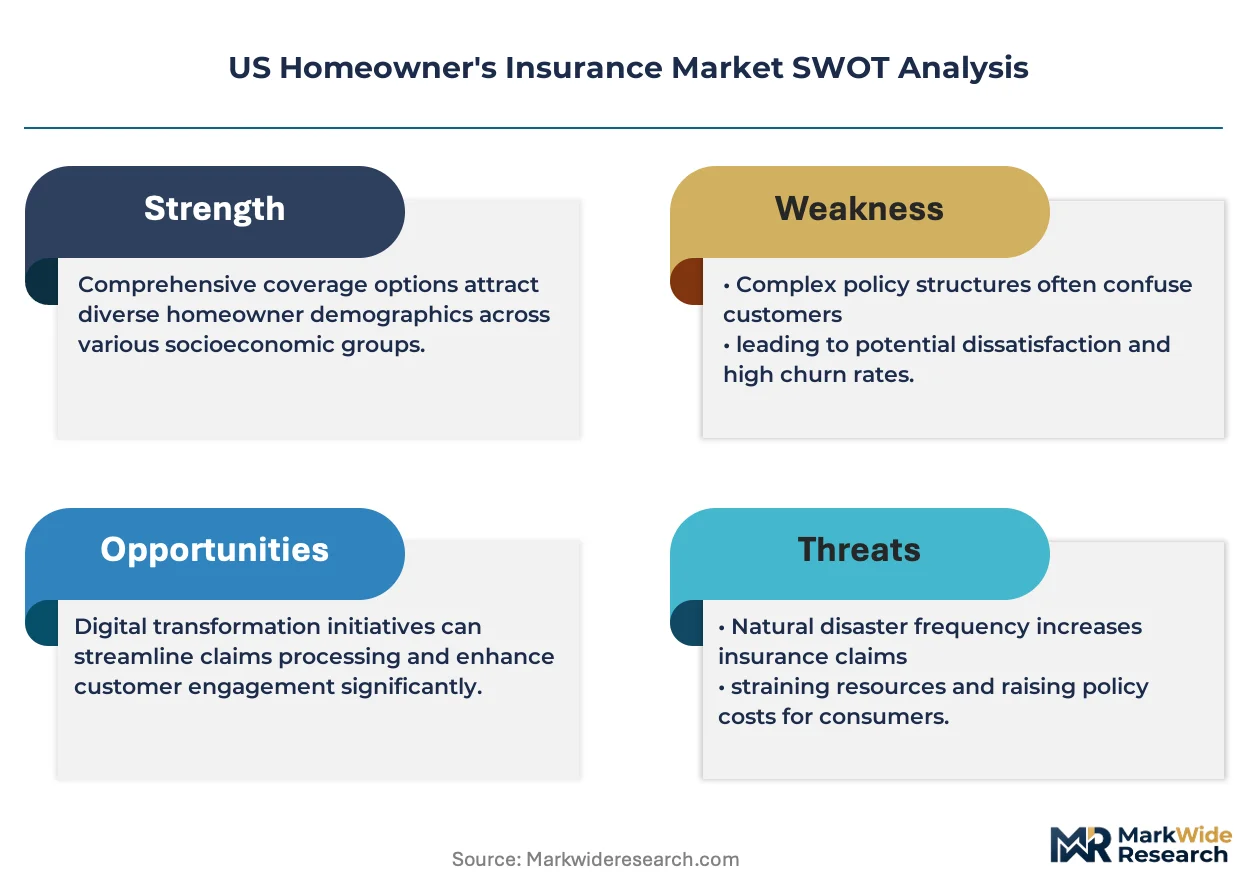
- Millennial household formation:Aging cohorts are entering prime first-time homebuying years in Sun Belt metros, creating policy volume expansion in Texas, Florida, and Arizona corridors.
- FEMA Risk Rating 2.0:The National Flood Insurance Program's actuarial overhaul is pushing private carriers to develop supplemental flood endorsements, unlocking new premium pools beyond NFIP caps.
- Smart home sensor adoption:IoT-enabled leak detection and security systems are reducing claims frequency, allowing carriers to deploy usage-based pricing discounts and retention incentives.
Market Restraints
- Reinsurance cost escalation:Property catastrophe treaty renewals in Florida and Gulf Coast states have tightened capacity, forcing primary carriers to reduce exposure or exit wind-prone counties entirely.
- Social inflation in liability:Nuclear verdicts in premises liability litigation are compressing underwriting margins and triggering sublimit reductions in HO-3 and HO-5 policy forms.
- Construction input volatility:Lumber and skilled labor shortages are inflating replacement cost estimates, creating premium adequacy gaps between policy inception and claim settlement.
Strategic Opportunities
- Embedded insurance distribution:Mortgage origination platforms and proptech closing services are creating direct policy placement channels that bypass traditional agency commissions.
- Parametric wind products:Index-triggered hurricane coverage is emerging as a complement to traditional indemnity policies, offering faster liquidity in catastrophe recovery scenarios.
- California FAIR Plan backfill:Wildfire risk concentration in the state-mandated pool is creating openings for admitted carriers with granular wildfire scoring capabilities to recapture preferred risks.
Industry Challenges
- Catastrophe model talent scarcity:Actuarial and geospatial analytics roles with climate risk expertise command premium compensation, constraining mid-market carrier hiring pipelines.
- Legacy policy administration migration:Core systems modernization projects face integration friction with decades-old rating engines, delaying product speed-to-market in competitive states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Homeowner's Insurance Market |
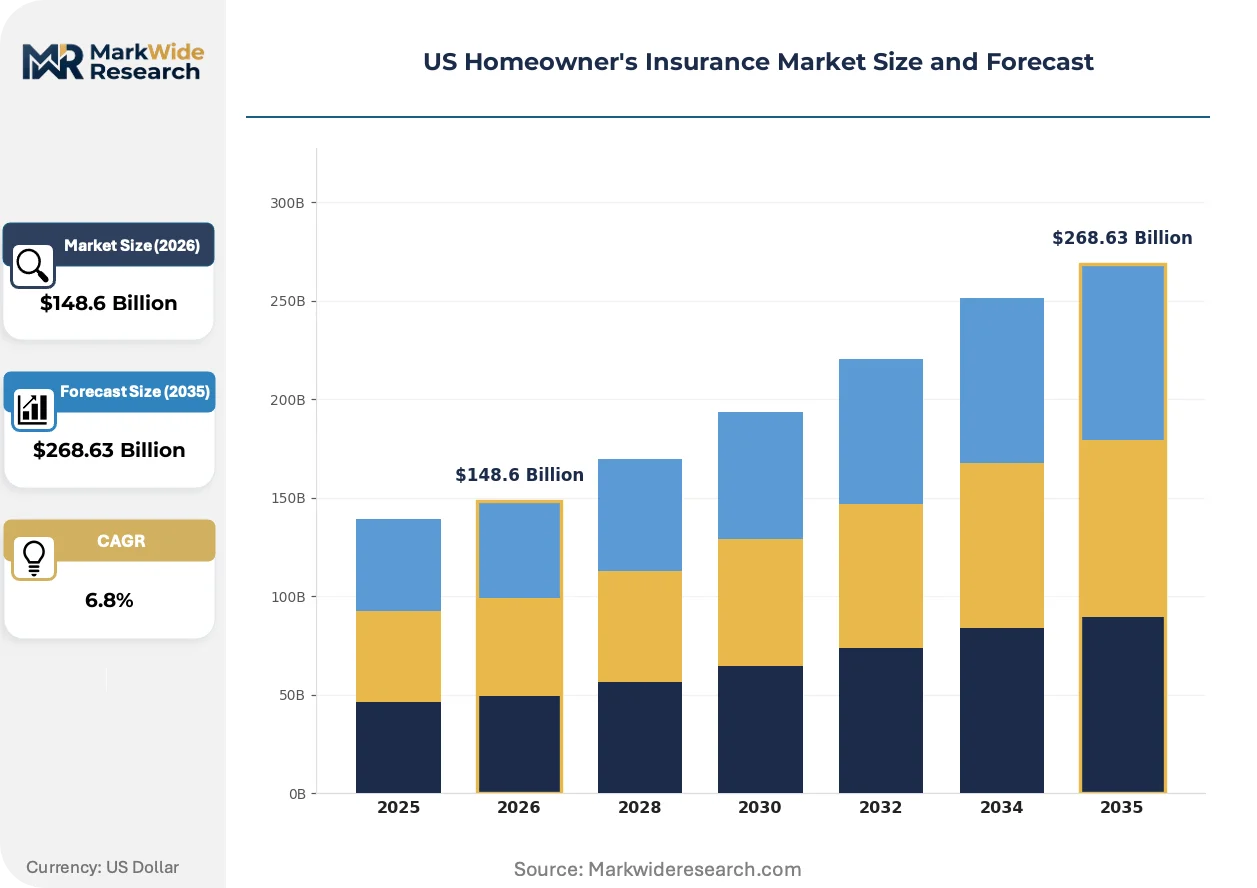
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Dwelling Coverage, Personal Property Coverage, Liability Coverage, Additional Living Expenses Coverage Policy Term: Annual, Multi-Year, Monthly, Short-Term Deductible Level: High Deductible, Low Deductible, Split Deductible, No Deductible Home Type: Single-Family Home, Condominium, Townhouse, Multi-Family Home |
| Companies Covered | State Farm, Allstate, Liberty Mutual Insurance, Farmers, USAA, Nationwide, Travelers, Progressive, Chubb, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Homeowner's Insurance Market Evolving Landscape
Telematics-derived property data is compressing traditional underwriting workflows as carriers shift from retrospective rating to real-time risk monitoring. This technological pivot is redrawing competitive boundaries between incumbent insurers and insurtech platforms.
Computer vision roof assessment is consolidating property inspection protocols across the industry. Drone and satellite imagery vendors are supplying carriers with automated condition scoring that replaces manual adjuster site visits. National carriers are embedding this capability into new business quoting, compressing cycle times from days to hours and reducing acquisition expense ratios.
FEMA's Risk Rating 2.0 methodology is redistributing flood premiums toward actuarially sound individual risk pricing. The overhaul is eliminating subsidized legacy rates and exposing true water exposure costs to homeowners. Gulf Coast and Northeast riverine communities face the steepest adjustments, prompting demand for private flood endorsements that cap NFIP premium escalations.
Digital-first distribution is fragmenting traditional agency channel dominance. Direct-to-consumer platforms and embedded mortgage-closing integrations are capturing younger policyholders who prioritize transactional convenience over agent relationships. Texas and Arizona markets exhibit the highest digital conversion rates, while Florida and Louisiana retain stronger agency dependencies due to catastrophe complexity.
US Homeowner's Insurance Market Segmentation
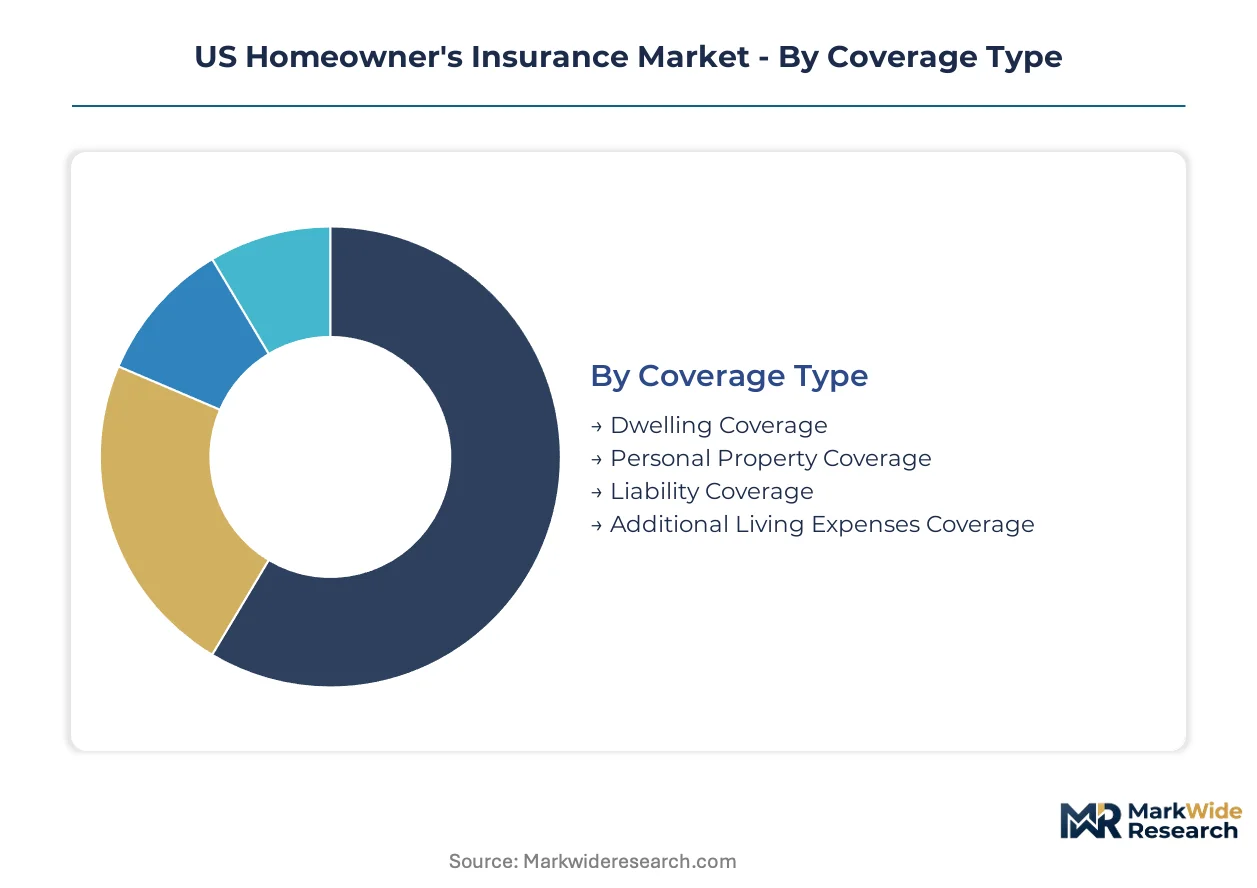
Homeowner's insurance segmentation reveals how capital deployment, risk concentration, and regulatory capital requirements vary across policy structures. Carriers optimize product mix by matching coverage granularity to reconstruction cost volatility and liability exposure curves.
Coverage Type:
Dwelling coverage commands the heaviest capital reserves due to catastrophe-exposed replacement cost exposure, while liability coverage demands pricing sophistication against social inflation.
- Dwelling Coverage:Indemnifies physical structure against named perils with replacement-cost valuation tied to lumber and labor indices. Demand concentrates in Florida and Gulf Coast counties where windstorm deductibles and NFIP coordination create complex underwriting workflows.
- Liability Coverage:Protects against third-party bodily injury and property damage claims with per-occurrence and aggregate limits. Growth is accelerating fastest in California and New York metros where premises litigation and nuclear verdicts drive limit escalation.
- Personal Property Coverage:Covers contents against theft, fire, and water damage with scheduled sublimits for jewelry, art, and collectibles.
- Additional Living Expenses Coverage:Reimburses temporary housing costs during repair periods, increasingly triggered by extended construction delays.
Most installed capacity flows through Dwelling Coverage. Expansion is steepest in Liability Coverage.
Policy Term:
Term structure shapes premium recognition patterns and customer lifetime value calculations, with annual contracts dominating regulatory filings and capital adequacy testing.
- Annual:Standard 12-month term with guaranteed renewal rights and state-mandated cancellation notice periods. Texas and Arizona regulators scrutinize non-renewal patterns in catastrophe-exposed counties.
- Multi-Year:Two-to-five year terms with rate lock provisions that transfer inflation risk to carriers. Adoption is climbing fastest among new construction buyers seeking payment stability.
- Monthly:Installment billing with finance charges, common in non-standard and force-placed markets.
- Short-Term:30-to-90 day coverage for vacant properties, renovations, or real estate transactions.
Annual terms carry the largest premium volume. Multi-Year policies are gaining share fastest among rate-sensitive buyers.
Deductible Level:
Deductible selection functions as a risk retention mechanism, with catastrophe-specific wind and hail deductibles operating on percentage-of-dwelling bases rather than flat dollar amounts.
- High Deductible:Typically 2-5% of dwelling limit for wind and hail exposure, reducing premium outlays by 15-30% in coastal Florida and Louisiana parishes. Selection correlates with mortgage-free ownership and liquidity buffers.
- Low Deductible:Flat dollar amounts ($500-$1,000) standard for fire and theft perils, preferred by first-time buyers with limited savings.
- Split Deductible:Separate triggers for named storms versus all other perils, common in Texas windstorm territories.
- No Deductible:Rare endorsements for scheduled valuables or equipment breakdown coverage.
High Deductible structures dominate catastrophe-prone coastal markets. Low Deductible retention is strongest in inland Midwest and Northeast states.
Home Type:
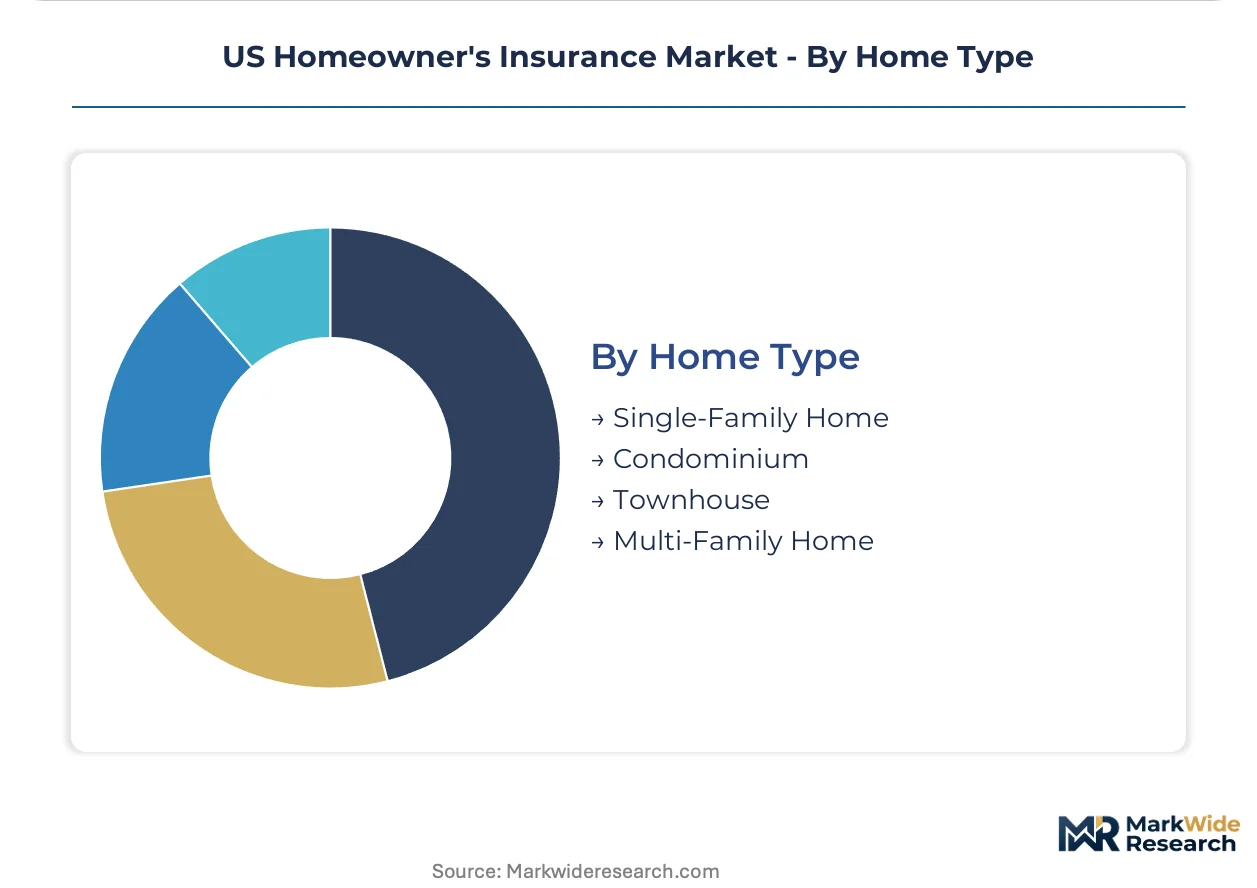
Structural classification determines replacement cost estimation methodology, with single-family homes requiring full dwelling valuation and condominiums relying on master policy coordination.
- Single-Family Home:Detached structures with individual roof, foundation, and utility systems requiring comprehensive HO-3 or HO-5 forms. Texas and Florida metros generate the highest new policy volume from millennial household formation.
- Condominium:Unit-owner policies covering interior improvements and personal property while master policies handle common elements. Urban infill in Seattle, Denver, and Austin is expanding this segment.
- Townhouse:Attached dwellings with hybrid coverage needs between single-family and condominium forms.
- Multi-Family Home:Duplex-to-fourplex owner-occupied properties requiring dwelling fire or commercial package policies.
Single-Family Home policies represent the largest premium pool. Condominium coverage is expanding most quickly in Sun Belt urban cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between state insurance departments creates uneven carrier participation, with capital migrating toward jurisdictions permitting adequate rate adequacy. Florida and California regulators impose stricter filing scrutiny than Texas or Arizona, reshuffling market capacity across state lines.
Florida
Hurricane exposure and litigation costs have driven eight regional carriers into insolvency since 2022. The Florida Office of Insurance Regulation enforces stricter capital adequacy requirements under Senate Bill 2-A. Miami-Dade and Broward counties concentrate the state's residual market burden, with Citizens Property Insurance absorbing risks that admitted carriers decline.
Texas
Hail and windstorm frequency generates the nation's highest property claims severity outside Florida. The Texas Department of Insurance oversees the Texas Windstorm Insurance Association for coastal counties. Dallas-Fort Worth and Houston metros attract new carrier entrants with granular catastrophe modeling and reinsurance treaty access.
California
Wildfire risk concentration has pushed seven admitted carriers into non-renewal moratoriums since 2019. The California Department of Insurance enforces Proposition 103 rate filing restrictions. Los Angeles County and the Sierra Nevada foothills exhibit the steepest FAIR Plan enrollment growth, creating backfill opportunities for wildfire-scoring specialists.
New York
Premises liability litigation and aging housing stock elevate loss costs in downstate markets. The New York State Department of Financial Services mandates hurricane deductibles and flood disclosure requirements. Long Island and the Hudson Valley corridor concentrate coastal wind exposure, with carriers demanding percentage-based deductibles for named storms.
Arizona
Water scarcity and extreme heat damage claims are emerging as novel underwriting variables. The Arizona Department of Insurance maintains lighter rate filing scrutiny than coastal states. Phoenix and Tucson metros attract millennial household formation, with digital-first carriers capturing share through embedded mortgage platform distribution.
US Homeowner's Insurance Market Competitive Landscape
Established carriers occupy the standard tier; emerging insurtech entrants pursue embedded distribution and parametric product niches. The market exhibits moderate consolidation among national writers, with the top five carriers commanding disproportionate premium volume in catastrophe-exposed states. Three archetypes dominate: mutual insurers with captive agency networks, stock carriers with direct-to-consumer platforms, and specialty writers with high-net-worth segmentation. Competitive intensity centers on reinsurance treaty access and catastrophe model sophistication rather than price alone.
Within the mutual insurer archetype, State Farm and USAA exemplify policyholder-owned structures that prioritize retention over growth velocity. Allstate represents the stock carrier model with hybrid agency and direct distribution. Chubb occupies the specialty tier, anchoring high-value dwelling coverage with differentiated risk selection. These three carriers collectively illustrate how capital structure and distribution mode determine competitive positioning across state regulatory environments.
| Leading Market Players |
|---|
| State Farm |
| Allstate |
| Liberty Mutual Insurance |
| Farmers |
| USAA |
| Nationwide |
| Travelers |
| Progressive |
| Chubb |
| Others |
Value Network & Pricing Analysis
Carrier-captive agency networks versus independent broker distribution splits the market into divergent cost structures, with the former commanding pricing discipline through exclusive appointment rights while the latter faces margin compression from commission competition and reinsurance pass-through costs. This bifurcation shapes both premium adequacy outcomes and supply chain sourcing decisions, as carriers with direct distribution control invest in proprietary catastrophe modeling while broker-dependent writers outsource risk selection to third-party vendors.
Pricing Analysis
Agency commission layers add 8-15% to premium acquisition costs before reinsurance ceding. Three-tier pricing structure across premium, standard, and non-standard levels differentiates carriers by NAIC complaint ratios and A.M. Best ratings. Pricing pressure stems from Florida and California rate filing moratoriums that trap inadequate premiums against surging reconstruction costs. First-time buyers in Texas and Arizona exhibit highest price sensitivity, while mortgage-free coastal owners in Florida accept percentage-based wind deductibles to reduce outlays.
Supply Chain Analysis
Domestic-content requirements in state residual markets like Citizens Property Insurance and California FAIR Plan restrict facultative reinsurance placement to U.S.-licensed carriers. Reinsurance capacity concentrates in Bermuda, London, and Zurich treaty markets. Primary carriers depend on property catastrophe bonds, industry loss warranties, and collateralized reinsurance vehicles for peak wind and wildfire exposure. Single-source vulnerability runs through the Florida Hurricane Catastrophe Fund's limited payout capacity. Distribution runs through captive agency networks, independent brokers, and embedded mortgage platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Texas and Florida, where lighter rate filing scrutiny in the former permits faster premium adequacy adjustments against reconstruction cost inflation that regulators in the latter suppress.
For Market Incumbents: Anticipate further state-level rate filing restrictions by pre-positioning granular catastrophe scoring capabilities that justify premium differentiation under regulatory challenge. Defensive consolidation into excess and surplus lines licensing expands underwriting flexibility where admitted market constraints tighten. Reinsurance treaty restructuring represents the priority lever for managing peak exposure concentration without exiting high-volume states. For New Entrants and Emerging Players: Embedded mortgage origination platforms offer the most penetrable entry vector, bypassing agency commission structures that inflate customer acquisition costs for traditional distribution. White-space targets include parametric wind endorsements for high-net-worth coastal properties and private flood gap coverage in Gulf Coast counties where NFIP premium escalations create displacement. Go-to-market execution should anchor with digital-first user experience and real-time quoting integration. For Investors and Strategic Acquirers: Consolidation pressure builds where midsize regional carriers face simultaneous reinsurance cost escalation and trapped capital from rate filing delays. Long-term viability favors carriers with diversified state footprints, proprietary catastrophe model licensing, and embedded distribution partnerships rather than pure agency-dependent writers. Acquisition target archetype: admitted carriers with 3-5 state licenses and granular wildfire or wind scoring IP. Signal to watch: state regulator approval velocity for rate adequacy filings in Florida and California as inflection indicator for carrier solvency stress.| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Treaty Restructuring | Reduces peak exposure concentration through collateralized coverage and catastrophe bond placement. |
| Embedded Distribution Partnership | Captures millennial homebuyers through mortgage closing platform integration, slashing acquisition costs. |
| Parametric Product Development | Accelerates liquidity for policyholders via index-triggered hurricane and wildfire coverage payouts. |
| Legacy Core System Modernization | Enables real-time rating engine updates that compress product speed-to-market in competitive states. |
| Excess and Surplus Lines Licensing | Expands underwriting flexibility beyond admitted market rate filing constraints in restricted jurisdictions. |
Research Methodology
Coverage spans Florida, Texas, California, New York, and Arizona, with primary inputs from each state's regulatory environment and competitive dynamics. Primary interviews with state insurance department rate filing officers, catastrophe model vendor actuaries, reinsurance broker placement specialists, and captive agency network directors combined with secondary validation. Secondary sources included NAIC rate filing databases, A.M. Best financial strength reports, state residual market enrollment data, and FEMA flood policy transaction records. Bottom-up policy volume estimates triangulated against top-down premium pool calculations from state insurance department annual statements.
Granularity-level modeling operated at state-county-ZIP code hierarchy for catastrophe exposure, by coverage type for capital reserve requirements, and by distribution channel for acquisition cost segmentation. Analytical framework projected premium volume and policy count across the analysis window using cohort-based household formation models and replacement cost inflation indices. CAGRs derived from exponential smoothing of historical premium growth adjusted for regulatory filing lag effects. Industry-specific forecast inputs included lumber and labor cost indices from Bureau of Labor Statistics construction series and RMS/Moody's catastrophe loss simulation outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state regulatory approval patterns for rate adequacy and reinsurance market capacity contraction in Florida and Gulf Coast territories. Projections reflect assumptions regarding continued NAIC oversight consistency and no fundamental restructuring of the National Flood Insurance Program. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Aggregators Market
Insurance
India Liability Insurance Market
Insurance
Agricultural Insurance Market
Insurance
China Parametric Insurance Market
Insurance
US Travel Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Disability Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Gap Insurance Market