
 Business Income Insurance Market | 2026-2036
Business Income Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Business Income Insurance Market Outlook
Actuarial talent scarcity is bifurcating the competitive landscape between carriers with in-house catastrophe modeling teams and those dependent on third-party vendors. Hartford Financial Services leverages proprietary risk-engineering platforms to sustain pricing precision on complex manufacturing accounts. Chubb dominates the high-net-worth commercial segment with tailored contingent business interruption products. American International Group competes through its integrated multinational capabilities, offering seamless cross-border coverage for US-based firms with offshore supply chains.
Business income insurance indemnifies policyholders for net income loss and continuing operating expenses when covered perils interrupt normal commercial operations, typically requiring proof of direct physical damage to insured property and specified waiting periods before coverage triggers. The policy duration segment shows structural momentum toward annual contracts as carriers push multi-year commitments to lock in rate adequacy, while short-term policies attract gig-economy and event-driven enterprises seeking flexible protection. Among end users, hospitality sector accounts command elevated premiums due to pandemic-era loss history and evolving virus exclusion language, whereas manufacturing firms anchor volume through packaged property and business interruption programs.
US state insurance commissioners and the National Association of Insurance Commissioners shape market conduct through statutory accounting principles and risk-based capital requirements that constrain carrier leverage. The Federal Insurance Office monitors systemic exposure accumulation, while state-level business interruption coverage mandates following recent hurricane seasons are expanding minimum policy attachment obligations. Stakeholders must monitor evolving court interpretations of physical loss requirements and parametric trigger innovations that could redefine coverage boundaries without traditional damage prerequisites.
Market Dynamics
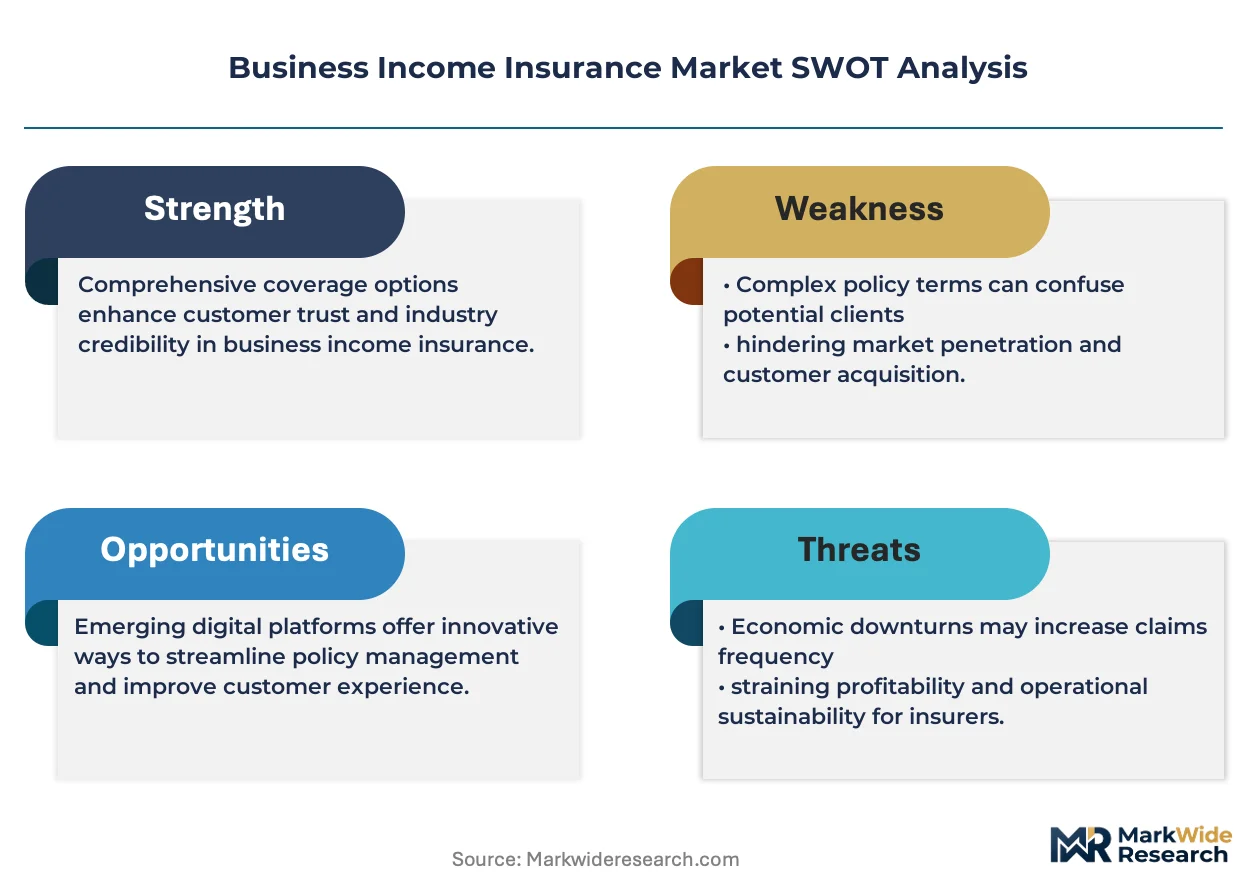
Climate volatility and regulatory fragmentation are compressing underwriting cycles while forcing carriers to rebuild risk models around parametric triggers and non-damage business interruption language.
Growth Catalysts
- NFIP Reauthorization:Congressional reforms to the National Flood Insurance Program are expanding commercial policy attachment mandates in coastal zones, pushing uninsured enterprises into private surplus lines markets.
- Contingent Business Interruption:Manufacturing supply chain vulnerability is accelerating demand for coverage protecting against supplier facility disruptions without direct physical damage to the insured.
- State-Level Mandates:Florida and Louisiana commissioners now require minimum business interruption riders on standard commercial property policies in designated catastrophe corridors.
Market Restraints
- Reinsurance Capacity Squeeze:Bermuda and London market retrocession shortages are compressing primary carrier capacity for multi-location manufacturing risks.
- Actuarial Talent Scarcity:Catastrophe modeler shortages constrain in-house pricing precision, forcing reliance on third-party vendor platforms with standardized assumptions.
- Virus Exclusion Litigation:Ambiguous pandemic-era policy language is generating coverage disputes that elevate legal defense reserves and slow claim settlement velocity.
Strategic Opportunities
- Parametric Triggers:Index-based coverage using wind speed or flood depth thresholds eliminates physical damage proof requirements, opening underserved service-sector segments.
- Midwest Manufacturing Corridors:Ohio and Illinois riverine flood zones show penetration gaps below 35 percent despite elevated business interruption exposure.
- Gig-Economy Short-Term Policies:Event-driven and seasonal operators are migrating from annual contracts to flexible duration products with modular coverage attachments.
Industry Challenges
- Catastrophe Model Integration:Legacy policy administration systems require costly API overhauls to ingest real-time exposure data from RMS and AIR Worldwide platforms.
- Claims Adjuster Specialization:Complex business income calculations demand forensic accounting expertise that carrier workforces and independent adjuster networks struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Income Insurance Market |
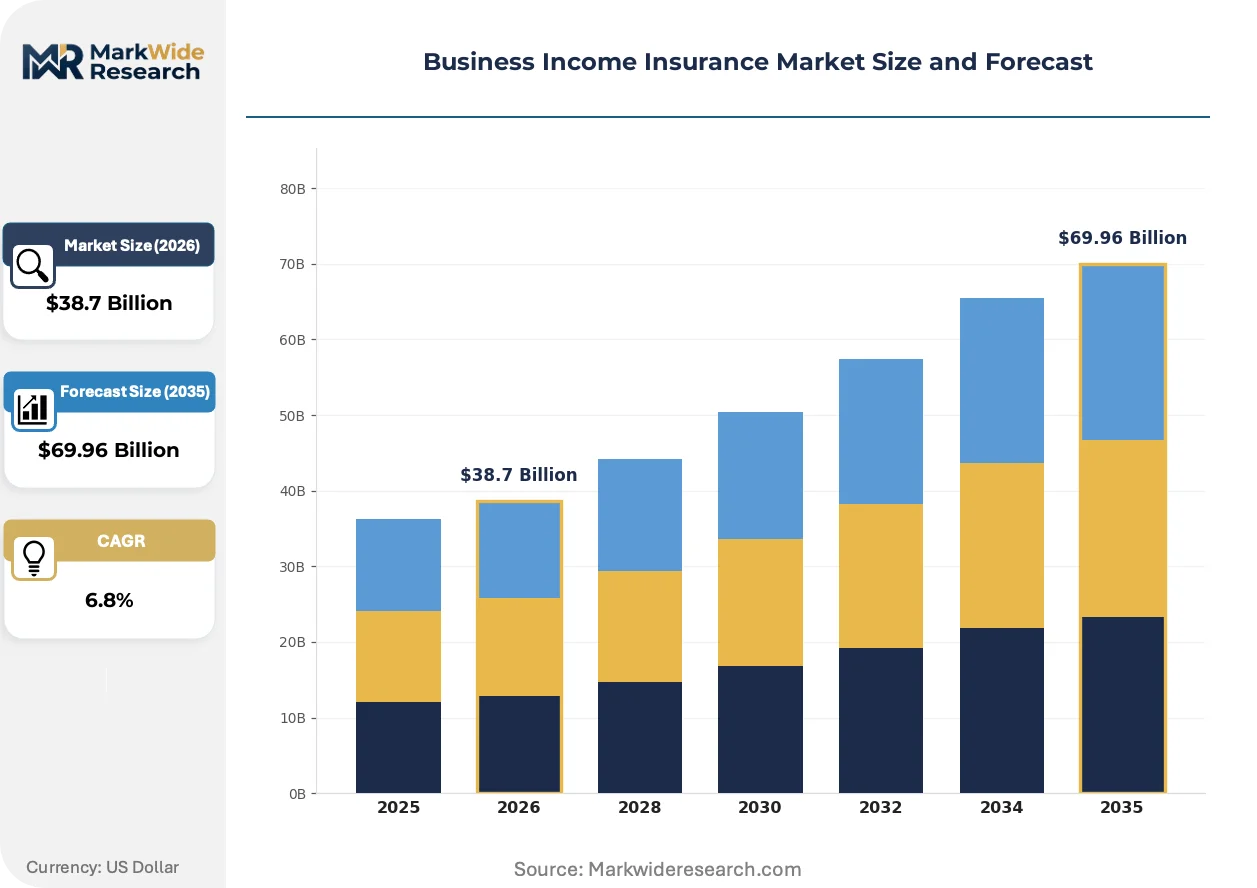
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Business Interruption, Extra Expense, Rental Income, Contingent Business Interruption Policy Duration: Short-Term, Long-Term, Quarterly, Annual End User: Retail Enterprises, Manufacturing Firms, Hospitality Sector, Service Providers Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | Hartford Financial Services, American International Group, Travelers Companies, Nationwide, Allstate, Chubb, CNA Financial, Progressive, Liberty Mutual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Income Insurance Market Strategic Shifts
Digital underwriting infrastructure and alternative risk transfer mechanisms are displacing traditional indemnity structures, compressing policy issuance timelines from weeks to hours while fragmenting distribution across embedded and direct channels.
Telematics-enabled property monitoring is bifurcating the risk assessment landscape. Sensor networks measuring structural integrity, temperature, and occupancy patterns now feed real-time data streams to carrier pricing engines. Large commercial accounts with capital-intensive facilities are adopting these systems fastest. The technology is bifurcating premium pools into precision-priced monitored risks and residual unmonitored portfolios bearing cross-subsidized rates.
The US National Association of Insurance Commissioners is finalizing model laws for business interruption data call standardization. This framework will force carriers to submit granular exposure and loss information for regulatory aggregation. Small and mid-sized carriers with fragmented policy administration systems face the steepest compliance costs. Texas and California departments are already piloting the reporting infrastructure ahead of national adoption.
Buyer procurement patterns are fragmenting across channel types. Mid-market enterprises are bypassing traditional wholesale brokers for direct carrier portals and managing general agent platforms that quote business income extensions instantaneously. This disintermediation concentrates in technology and professional services verticals with standardized property footprints. The shift is most visible in Austin and Raleigh-Durham metro areas where venture-backed firms prioritize coverage speed over advisory relationships.
Business Income Insurance Market Segmentation
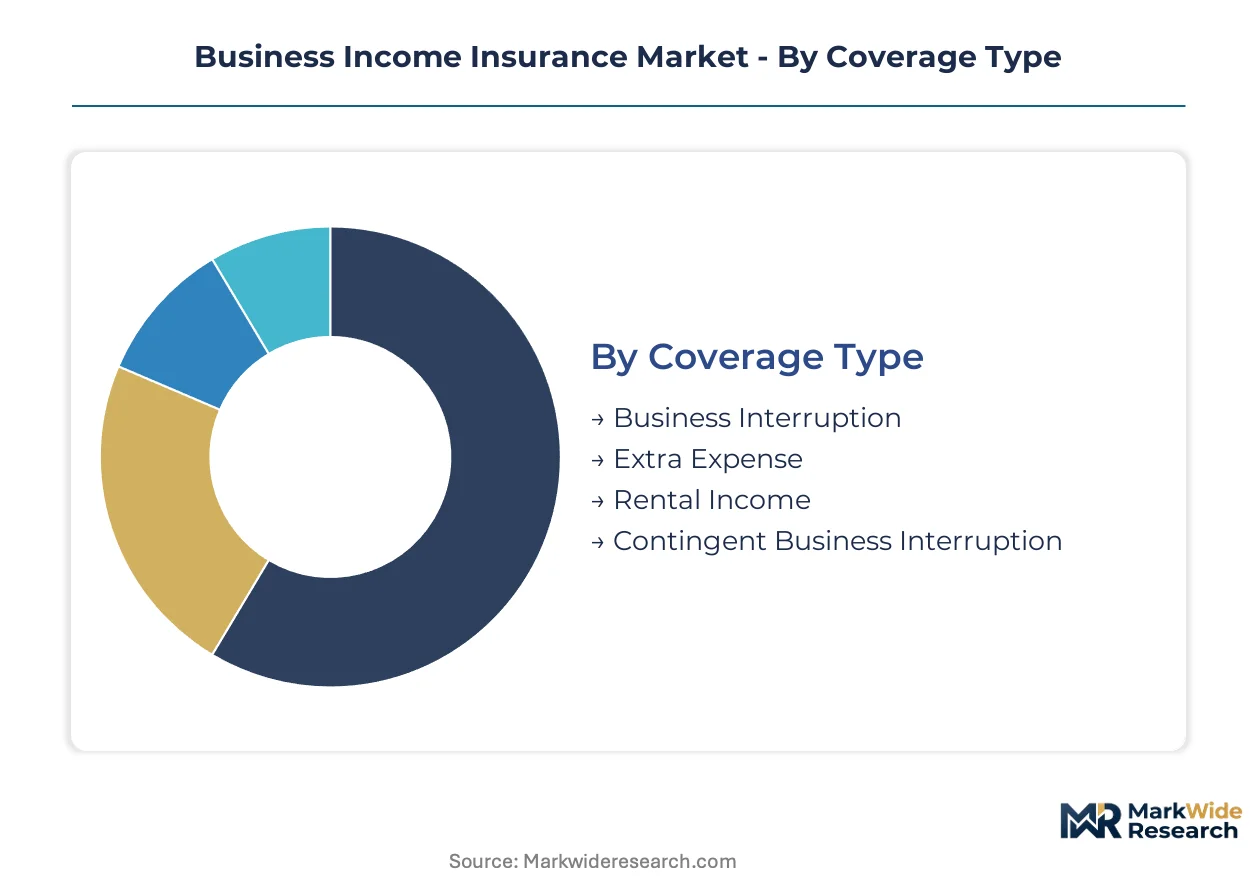
Segmentation in business income insurance determines pricing precision, distribution strategy, and regulatory capital allocation. Carriers calibrate underwriting appetite and commission structures around coverage complexity, policy duration flexibility, and buyer sophistication tiers.
Coverage Type:
Brokers dominate placement for complex coverage combinations, while direct channels and online platforms capture standardized single-peril policies. Manufacturing accounts with contingent supplier exposure flow through specialized wholesale brokers, whereas retail enterprises purchase business interruption riders via agent networks.
- Business Interruption:Core indemnity coverage for net income loss and continuing operating expenses following direct physical damage to insured premises. Demand concentrates in coastal Florida and Louisiana manufacturing corridors where hurricane exposure drives mandatory attachment requirements.
- Extra Expense:Reimbursement for costs incurred to mitigate loss severity, including temporary relocation and expedited shipping. Hospitality sector accounts in pandemic-affected markets command elevated premiums due to virus exclusion litigation and forensic accounting complexity.
- Rental Income:Protection for landlords against lost tenant revenue streams during property restoration periods. Commercial real estate investment trusts in Midwest riverine flood zones purchase through managing general agents.
- Contingent Business Interruption:Coverage for income loss stemming from supplier or customer facility disruptions without direct damage to insured property. Automotive and electronics manufacturers with offshore supply chains drive placement through multinational broker networks.
Business Interruption dominates installed base. Contingent Business Interruption is where expansion concentrates.
Policy Duration:
Cost tier stratification separates annual contracts with rate-adequacy locks from flexible short-term products carrying premium surcharges. Gig-economy operators and event-driven enterprises cluster in higher-cost-per-day short-duration tiers.
- Annual:Standard contract term with multi-year commitment options for rate stability. Large manufacturing firms with capital-intensive facilities anchor volume through packaged property and business interruption programs.
- Short-Term:Flexible duration products spanning weeks to months for seasonal and project-based operations. Austin and Raleigh-Durham venture-backed technology firms purchase through direct carrier portals prioritizing coverage speed.
- Long-Term:Extended commitments beyond three years with inflation-adjusted coverage limits. Public infrastructure contractors in federally designated catastrophe corridors utilize for project continuity guarantees.
- Quarterly:Medium-term alignment with fiscal reporting cycles and seasonal revenue fluctuations. Agricultural processing cooperatives in Illinois and Ohio riverine zones match coverage to harvest and processing windows.
Annual contracts dominate installed base. Short-Term is climbing the fastest as gig-economy penetration deepens.
End User:
Application-specific risk profiles determine underwriting methodology and claims adjuster specialization requirements. Manufacturing accounts demand forensic accounting expertise, while retail enterprises standardize around templated loss calculations.
- Manufacturing Firms:Capital-intensive operations with complex supply chain interdependencies and extended business interruption horizons. Ohio and Illinois manufacturing corridors show penetration gaps below 35 percent despite elevated flood exposure.
- Retail Enterprises:Inventory-heavy operations with shorter restoration periods and standardized revenue documentation. Small and mid-sized retailers in coastal states expand coverage purchases as climate-related disruptions intensify.
- Hospitality Sector:Service-intensive operations with pandemic-era loss history and evolving virus exclusion language. Florida and Louisiana commissioners now require minimum business interruption riders in designated catastrophe corridors.
- Service Providers:Human-capital-dependent operations with minimal physical asset bases and parametric trigger suitability. Professional services firms in Austin and Raleigh-Durham metro areas adopt index-based coverage using wind speed thresholds.
Manufacturing Firms dominate installed base. Service Providers is where expansion concentrates.
Distribution Channel:
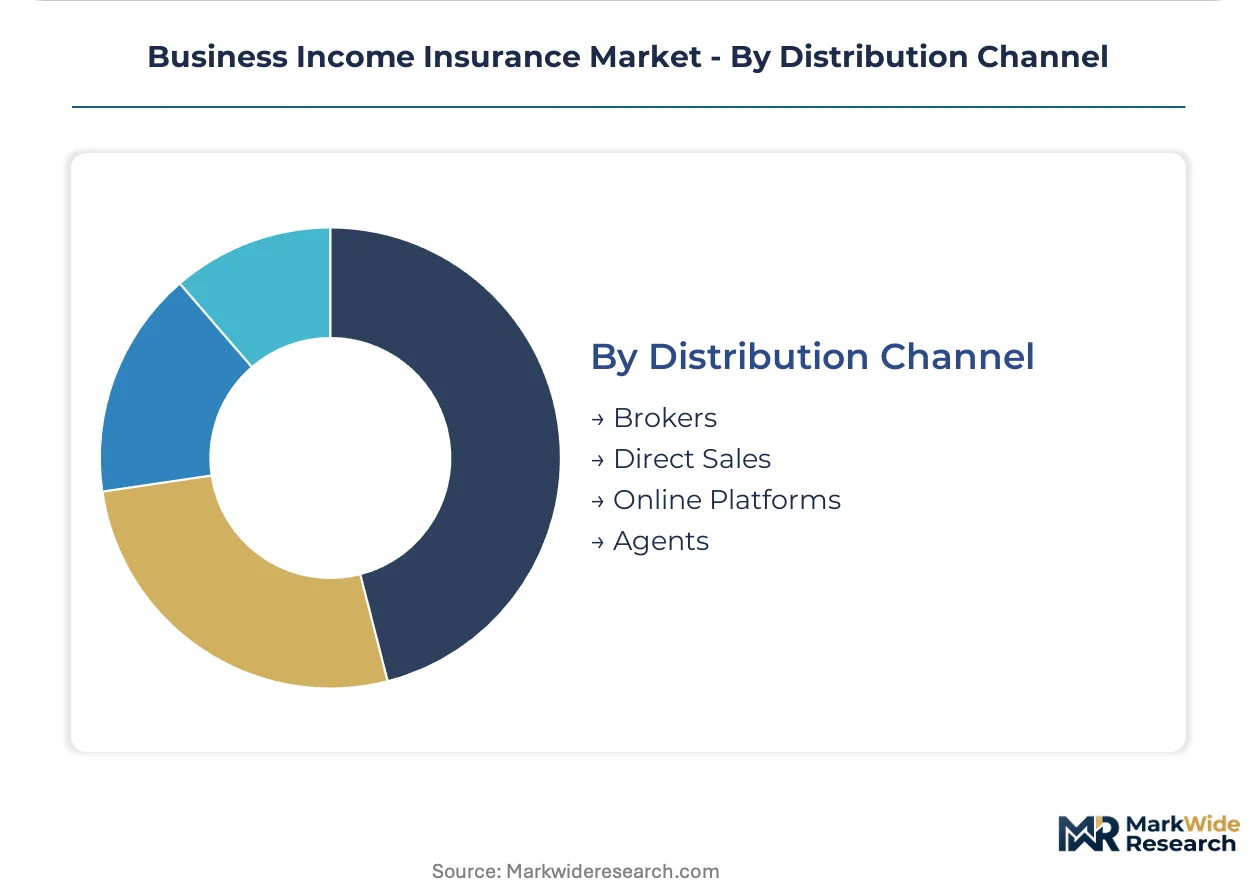
Geographic concentration of buyer sophistication determines channel viability. Technology clusters with standardized property footprints disintermediate traditional brokers, while complex manufacturing risks retain advisory relationships.
- Brokers:Intermediary placement for complex multi-location risks requiring coverage customization and claims advocacy. Contingent business interruption for multinational supply chains flows through wholesale and retail broker networks.
- Agents:Localized placement for small commercial accounts with standardized coverage needs and relationship-driven renewal patterns. Louisiana and Florida state-mandated riders distribute through captive and independent agency forces.
- Direct Sales:Carrier-controlled placement for large national accounts with in-house risk management capabilities. Hartford Financial Services and Chubb deploy proprietary risk-engineering platforms for direct manufacturing account acquisition.
- Online Platforms:Automated quoting for standardized coverage with instantaneous policy issuance. Mid-market technology and professional services verticals in Austin and Raleigh-Durham bypass traditional wholesale brokers for managing general agent platforms.
Brokers dominate installed base. Online Platforms is gaining share fastest as mid-market procurement patterns fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between coastal catastrophe corridors and inland manufacturing belts. Coastal enterprises prioritize contingent business interruption for supply chain resilience, while Midwestern firms emphasize flood-specific coverage extensions.
United States
Coastal Florida and Louisiana manufacturing corridors drive mandatory business interruption attachment requirements following state-level hurricane mandates. The National Association of Insurance Commissioners shapes carrier conduct through statutory accounting principles and risk-based capital requirements. Austin and Raleigh-Durham technology clusters disintermediate traditional brokers for direct carrier portals prioritizing coverage speed.
Canada
Ontario and Quebec manufacturing belts concentrate demand for packaged property and business interruption programs with cross-border supply chain protection. Federal and provincial insurance regulators coordinate solvency standards through the Office of the Superintendent of Financial Institutions. Toronto financial services firms anchor placement volume through managing general agent platforms.
Germany
Industrial machinery and automotive manufacturers in Bavaria and Baden-Württemberg demand sophisticated contingent business interruption for supplier facility disruptions. BaFin enforces risk-based capital requirements that constrain carrier leverage for complex manufacturing accounts. Stuttgart and Munich industrial clusters sustain advisory broker relationships for multinational coverage.
United Kingdom
London commercial insurance market anchors global placement for multinational contingent business interruption with seamless cross-border capabilities. The Prudential Regulation Authority and Financial Conduct Authority monitor systemic exposure accumulation through stress testing frameworks. Lloyd's syndicates and specialty carriers concentrate in the City for complex risk engineering.
Japan
Tokyo and Osaka manufacturing corridors prioritize extended business interruption horizons for capital-intensive operations with complex supply chain interdependencies. METI coordinates catastrophe risk modeling standards while the Financial Services Agency enforces solvency margins. Kanto region electronics and automotive manufacturers drive demand for parametric trigger innovations.
Business Income Insurance Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with tiering driven by proprietary risk-engineering capabilities versus third-party vendor dependence. The upper tier commands pricing precision on complex manufacturing accounts through in-house catastrophe modeling teams. Specialist carriers compete through tailored contingent business interruption products and flexible duration offerings. Dominant competitive moves include API infrastructure overhauls for real-time exposure data integration and forensic accounting workforce scaling for claims specialization.
Within the integrated leader tier, Hartford Financial Services and Chubb occupy positions defined by proprietary platforms and high-net-worth commercial specialization respectively. American International Group anchors the multinational vector with cross-border coverage architecture. These three exemplify how vertical integration into risk engineering and direct distribution capabilities separates premium-tier carriers from vendor-dependent competitors.
| Leading Market Players |
|---|
| Hartford Financial Services |
| American International Group |
| Travelers Companies |
| Nationwide |
| Allstate |
| Chubb |
| CNA Financial |
| Progressive |
| Liberty Mutual |
| Others |
Value Chain & Pricing Dynamics
Annual policy commitments with multi-year rate locks anchor carrier-client relationships, binding premium stability to captive capacity allocation and shielding underwriters from retrocession volatility in Bermuda and London markets. This contract-structure pattern concentrates pricing power among integrated carriers with proprietary catastrophe modeling capabilities while squeezing vendor-dependent competitors into spot-market reinsurance dependency.
Pricing Analysis
Long-term offtake structures dominate the Business Income Insurance Market, with annual contracts carrying multi-year commitment options that lock rate adequacy against retrocession squeezes. Price differentiation rests on actuarial sophistication tier and proprietary risk-engineering platform access, separating Hartford Financial Services and Chubb from third-party-dependent underwriters. Pricing pressure stems from reinsurance capacity compression in catastrophe corridors, forcing primary carriers to cede larger risk shares. Small and mid-sized retail enterprises show highest price sensitivity, whereas multinational manufacturing accounts with contingent business interruption exposure accept premium elevation for supply chain certainty.
Supply Chain Analysis
Bermuda retrocession capacity chokepoints constrain primary carrier appetite for multi-location manufacturing risks, forcing reliance on London market alternatives. Supply concentration centers on the United States, United Kingdom, and Bermuda for risk capital, with catastrophe modeling software dependencies drawing from RMS and AIR Worldwide platforms. Single-source vulnerability runs through legacy policy administration systems requiring costly API overhauls for real-time exposure integration. Distribution runs through wholesale broker networks for complex contingent coverage, while direct carrier portals capture standardized business interruption riders in technology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Business Income Insurance Market rewards carriers with captive actuarial talent and proprietary modeling infrastructure, while punishing dependence on standardized vendor platforms. Forensic accounting specialization gaps slow claims velocity and elevate legal defense reserves, creating separation between precision-priced monitored risks and residual unmonitored portfolios.
For Market Incumbents: Compound proprietary risk-engineering capabilities through in-house catastrophe modeler recruitment and API infrastructure overhauls integrating real-time telematics feeds. Defend against parametric trigger disrupters by embedding sensor-network monitoring into large commercial accounts. Expand forensic accounting workforce scaling to accelerate claim settlement velocity and reduce virus-exclusion litigation exposure. For New Entrants and Emerging Players: Anchor in gig-economy short-term policy white space, where flexible duration products with modular coverage attachments attract event-driven and seasonal operators underserved by annual contract incumbents. Target service providers in Austin and Raleigh-Durham technology clusters with index-based parametric coverage using wind speed thresholds. Deploy managing general agent platforms for instantaneous quoting that bypasses traditional wholesale broker relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized carriers with fragmented policy administration systems facing steep NAIC data call standardization compliance costs, where acquisition creates operational consolidation value. Long-term viability hinges on backward integration into catastrophe modeling capabilities and direct distribution architecture. Watch court interpretations of physical loss requirements as the inflection signal for parametric trigger market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Infrastructure Overhaul | Legacy policy administration systems ingest real-time exposure data from RMS and AIR Worldwide platforms. |
| Forensic Accounting Workforce Scaling | Complex business income calculations demand expertise that carrier networks struggle to deploy. |
| Parametric Trigger Product Launch | Index-based coverage using wind speed thresholds eliminates physical damage proof requirements. |
| Telematics-Enabled Property Monitoring | Sensor networks measuring structural integrity feed real-time data streams to carrier pricing engines. |
| Managing General Agent Platform Expansion | Mid-market technology firms in Austin and Raleigh-Durham bypass traditional wholesale brokers for speed. |
Study Parameters
The analysis maps business interruption coverage types, policy duration tiers, and end-user verticals, each validated through underwriters, actuarial directors, claims adjusters, and risk engineering specialists. Primary interviews with carrier executives and broker placement professionals combined with secondary validation from NAIC data call filings, state insurance commissioner reports, SEC 10-K insurance disclosures, and catastrophe model vendor documentation. Bottom-up policy volume aggregation and top-down premium pool estimation triangulate market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework modeled coverage type complexity, policy duration flexibility, end-user risk profiles, and distribution channel fragmentation dimensions. CAGRs derived from regression analysis of historical premium growth and exposure accumulation trajectories. Industry-specific forecast inputs incorporated NFIP reauthorization impacts, state-level mandate expansion, and parametric trigger adoption curves.
Material uncertainties — climate volatility intensification, court reinterpretation of physical loss requirements, and retrocession capacity shocks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and catastrophe model vendor platform continuity. Practitioners should keep alternative scenarios live as NAIC data call standardization and parametric trigger legal recognition evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Property Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Horse Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Europe Bancassurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
EV Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Spain Group Health Insurance Market
Insurance
Agriculture Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Middle East and Africa Travel Insurance Market