
 Art Insurance Market | 2026-2036
Art Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Art Insurance Market Analysis
Specialized art lending and premium finance structures is fragmenting competitive dynamics across the sector. AIG leverages its global underwriting footprint to serve museum networks across multiple continents. Hiscox anchors its position through bespoke coverage for emerging contemporary artists and private dealers. Lloyd's of London competes via syndicate specialization in war, terrorism, and political risk extensions for transit exposures.
Art insurance constitutes specialized property and casualty coverage designed to indemnify financial loss from physical damage, theft, mysterious disappearance, or total destruction of fine art, decorative objects, and collectible assets, with policies typically incorporating agreed-value clauses, pairs-and-sets provisions, and restoration-cost sublimits. Coverage type segments reveal All Risks policies commanding premium positioning due to comprehensive peril breadth, while Named Perils structures retain relevance for lower-value collections seeking cost containment. Insured asset segmentation shows Paintings generating the largest premium pool by absolute value, though Sculptures present elevated technical complexity due to fabrication material heterogeneity and installation vulnerability.
US state insurance regulators, the UK's Financial Conduct Authority, and EU Solvency II frameworks collectively shape capital adequacy requirements, policy form standardization, and claims-handling timelines across jurisdictions. GDPR and emerging US state privacy laws constrain how insurers collect, share, and retain provenance documentation and collector personal data. Stakeholders must monitor evolving climate peril modeling and its integration into transit and storage risk assessments.
Market Dynamics
Blockchain provenance verification is compressing claims investigation timelines and forcing traditional underwriters to rebuild policy administration systems around immutable record architectures.
Growth Catalysts
- EU Solvency II capital frameworks:Harmonized reserve requirements across EU member states enable cross-border art lending structures and premium finance products.
- Freeport storage facilities:Luxembourg, Singapore, and Geneva freeports create tax-advantaged concentration points demanding specialized transit-to-storage coverage.
- Digital condition monitoring:IoT sensors tracking temperature, humidity, and vibration during shipment reduce loss ratios and enable usage-based premium adjustments.
Market Restraints
- Specialized appraiser scarcity:Certified fine art valuators concentrate in London, New York, and Paris, creating bottlenecks for mid-market collection underwriting.
- GDPR documentation constraints:European privacy law limits cross-border sharing of provenance records containing previous owner personal data.
- Forgery detection lag:Technical analysis of synthetic pigments and AI-generated provenance documents outpaces laboratory authentication capacity.
Strategic Opportunities
- Middle Eastern sovereign collections:Abu Dhabi and Doha museum construction programs generate demand for long-term exhibition coverage and conservation risk transfer.
- NFT and digital art custody:Cold storage solutions for cryptographic keys and on-chain ownership records require novel first-party cyber-physical policies.
- Climate peril modeling integration:Parametric flood and wildfire triggers for transit routes through vulnerable corridors enable rapid claims settlement.
Industry Challenges
- Restoration specialist recruitment:Conservation science programs produce insufficient graduates trained in contemporary synthetic materials and digital media preservation.
- Legacy policy administration migration:Decades-old agreed-value clauses require manual reinterpretation to accommodate blockchain-verified ownership transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Art Insurance Market |
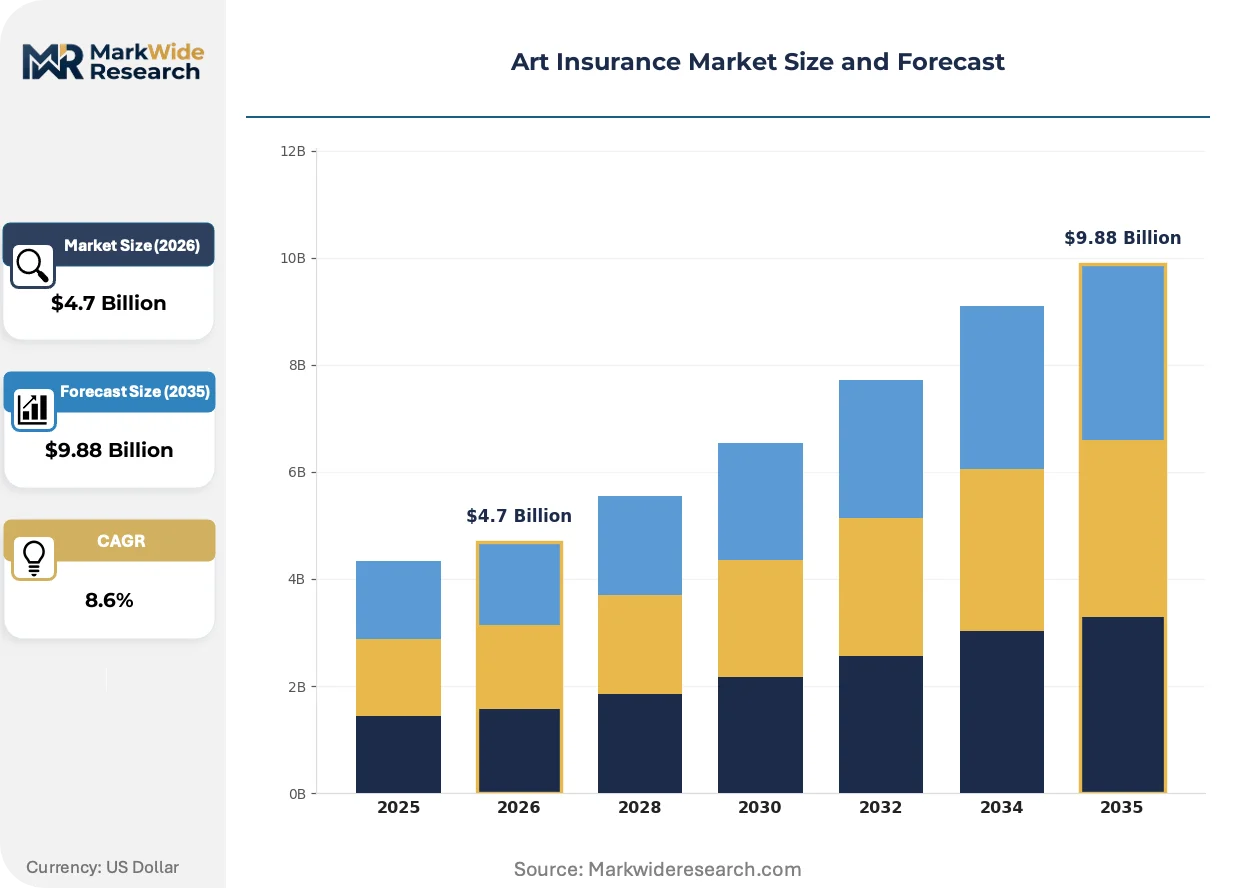
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: All Risks, Specified Perils, Named Perils, Valuation Coverage Insured Asset: Paintings, Sculptures, Antiques, Collectibles Policy Type: Individual Policy, Group Policy, Blanket Policy, Transit Policy Client Type: Artists, Galleries, Collectors, Museums |
| Companies Covered | AIG, Hiscox, AXA, Huntington T. Block, Zurich Insurance Group, Chubb, Lloyd's of London, Markel, Allianz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Art Insurance Market Emerging Trajectories
Distributed ledger architectures and parametric risk instruments are fragmenting traditional indemnity models while compressing the role of intermediary loss adjusters.
Blockchain-based title registries are hybridizing ownership verification with automated smart contract payouts. Private collectors in Switzerland and Singapore now require insurers to interface with distributed ledger systems for real-time provenance updates. This technology is hybridizing the claims settlement process from months-long investigations to near-instantaneous verification-triggered disbursements.
GDPR's right-to-erasure provisions create friction with immutable provenance records. Insurers operating across EU jurisdictions must architect data retention policies that satisfy supervisory authority audits while preserving chain-of-title integrity. German and French regulators now scrutinize how carriers reconcile deletion requests with century-old auction house archives.
Collector risk retention is shifting toward self-insurance vehicles and captive structures for ultra-high-value holdings. Family offices in the United States and United Kingdom increasingly retain first-dollar losses below thresholds, purchasing only catastrophic layer coverage. This pattern concentrates premium flow toward syndicates specializing in tail-risk pricing rather than primary market underwriters.
Art Insurance Market Segmentation
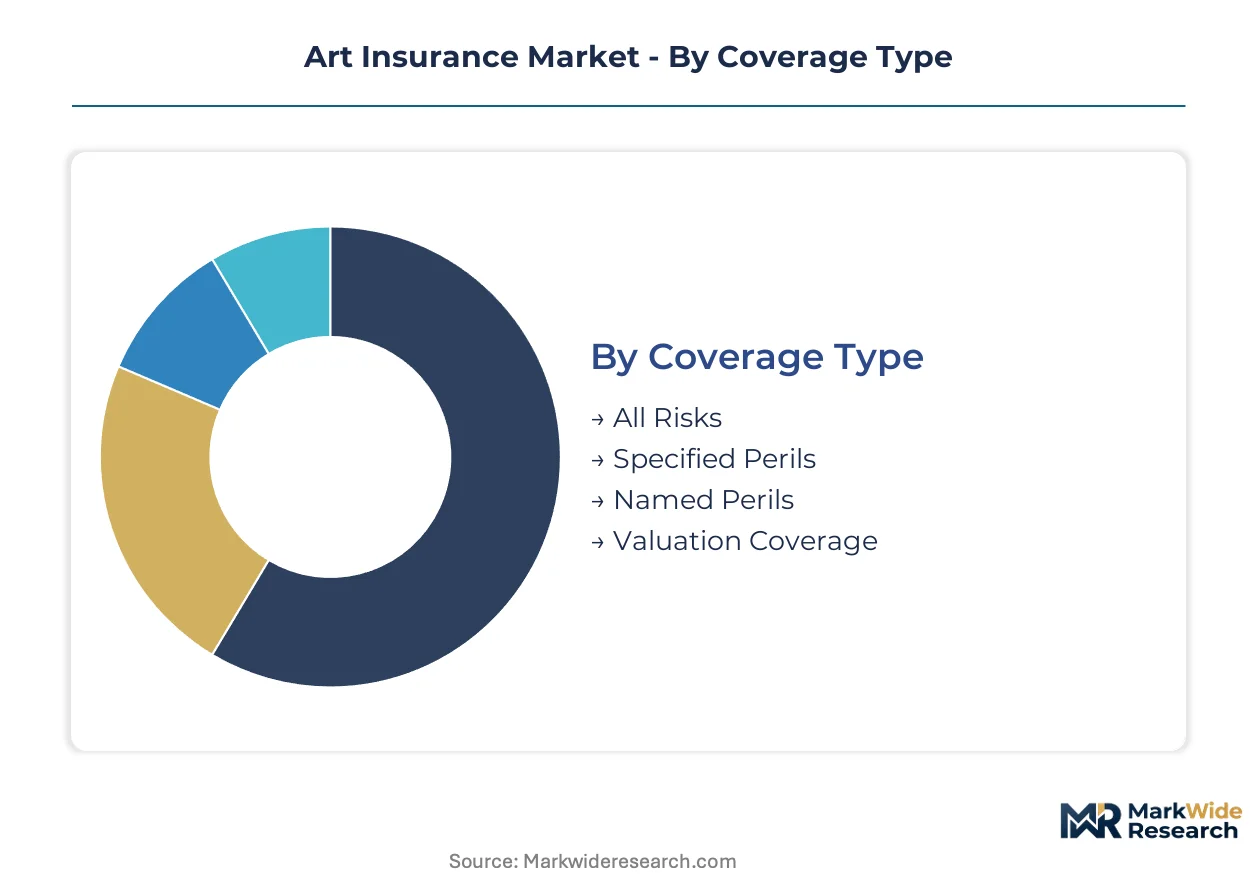
Art insurance segmentation reflects divergent risk profiles across asset classes and ownership structures. Underwriters calibrate premium loadings, sublimit structures, and claims protocols to match the specific loss characteristics of each category.
Coverage Type:
Collector risk appetites span from comprehensive protection to targeted peril isolation based on collection value and storage conditions.
- All Risks:Comprehensive policies indemnify against physical damage, theft, and mysterious disappearance without enumerated exclusions. Private collectors in the United States and United Kingdom prioritize this structure for high-value contemporary works where provenance verification reduces moral hazard.
- Specified Perils:Coverage activates only against listed events such as fire, flood, or transit collision. German institutional collections favor this tier for mid-value decorative objects held in climate-controlled freeport facilities where environmental controls mitigate unlisted risks.
- Named Perils:Narrowest coverage scope enumerating specific causes of loss, typically excluding gradual deterioration and inherent vice. Cost-conscious collectors in regional markets select this structure for lower-value holdings.
- Valuation Coverage:Policies incorporating agreed-value clauses eliminate post-loss appraisal disputes. This segment serves estates and inheritance transfers where beneficiary alignment requires predetermined indemnity amounts.
Established volume favors All Risks; emerging adoption favors Valuation Coverage.
Insured Asset:
Material composition and installation complexity drive differentiated underwriting expertise across asset categories.
- Paintings:Canvas and panel works generate the largest absolute premium pool due to market liquidity and auction price transparency. Demand concentrates among United States private collectors and United Kingdom family offices where contemporary blue-chip acquisition rates sustain coverage renewals.
- Sculptures:Fabrication material heterogeneity—bronze, marble, steel, synthetic composites—creates elevated technical complexity. Installation vulnerability and outdoor exposure in Middle Eastern sovereign collections necessitate specialized engineering reviews.
- Antiques:Pre-twentieth-century decorative objects including furniture, ceramics, and textiles. Provenance documentation requirements under GDPR constrain cross-border underwriting for European collections containing personal data in ownership histories.
- Collectibles:Numismatic, philatelic, and memorabilia assets with volatile secondary markets. Singapore and Luxembourg freeport storage facilities drive demand for transit-to-vault coverage with parametric triggers.
Paintings anchor premium volume; Sculptures present the steepest expansion trajectory for specialized underwriting capacity.
Policy Type:
Ownership scale and mobility patterns determine whether individualized or aggregated coverage structures optimize cost efficiency.
- Individual Policy:Single-asset coverage with bespoke terms for museum-quality works. United States state insurance regulators scrutinize agreed-value adequacy for policies exceeding threshold limits.
- Group Policy:Multi-asset aggregation for corporate collections and foundation holdings. EU Solvency II capital frameworks enable cross-border group structures spanning Luxembourg, Germany, and France.
- Blanket Policy:Agreed-value coverage for entire collections without itemized schedules. Galleries in London and New York utilize this structure for inventory rotation flexibility.
- Transit Policy:Time-bound coverage for shipment exposures including war, terrorism, and political risk extensions. Lloyd's of London syndicates dominate this segment via specialized marine and aviation cargo expertise.
Individual Policy retains margin leadership; Transit Policy gains share fastest from exhibition lending growth.
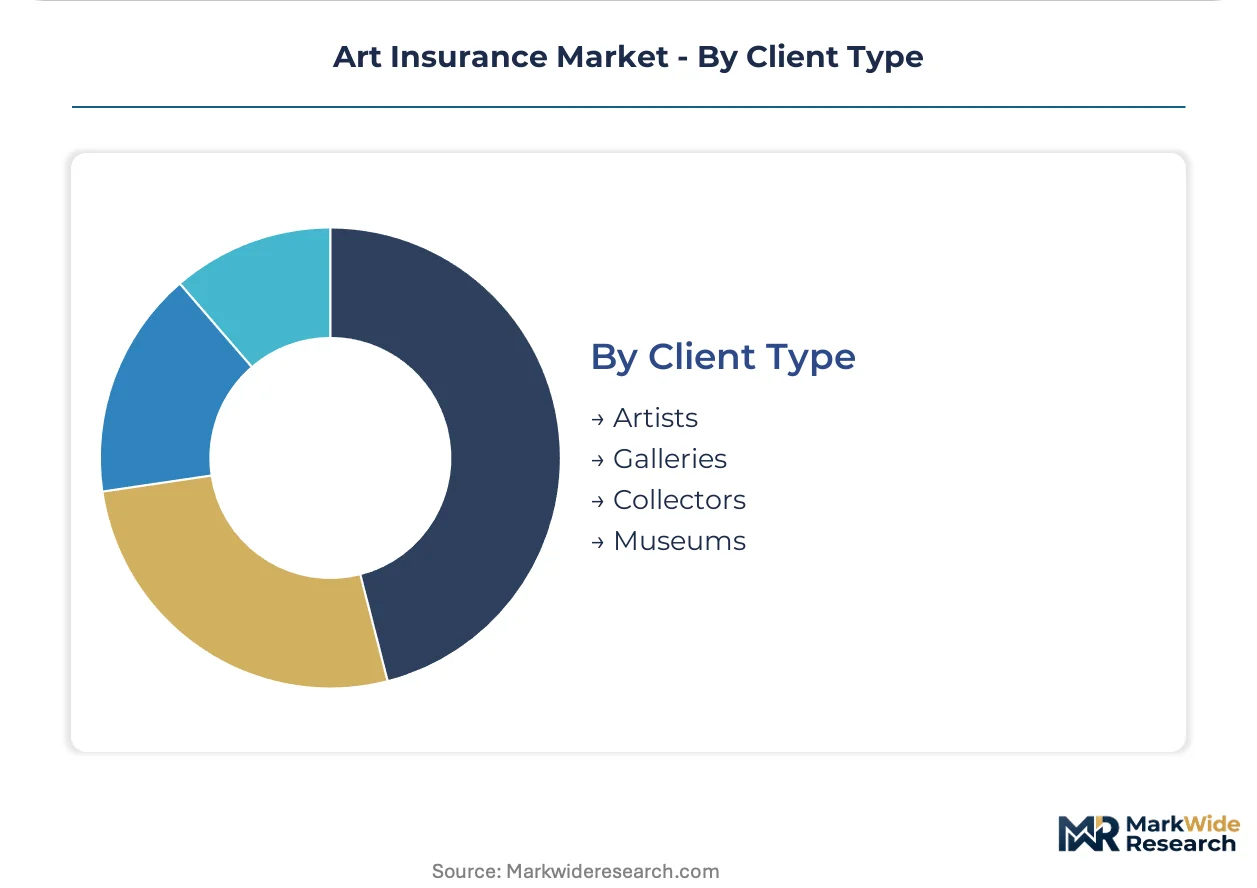
Client Type:
Professional versus amateur status shapes loss prevention investment and claims frequency patterns.
- Artists:Studio and inventory coverage protecting unsold works and materials. Studios in Berlin and Los Angeles drive demand for equipment and finished piece bundling.
- Galleries:Consignment inventory and exhibition liability protection. Primary market dealers in New York and London require coverage for works on loan to client premises.
- Collectors:Private individual coverage spanning residential display, storage, and transit. Family offices increasingly retain first-dollar losses below thresholds, purchasing catastrophic layer coverage only.
- Museums:Permanent collection, loan exhibition, and conservation risk transfer. Abu Dhabi and Doha construction programs generate demand for long-term exhibition coverage.
Collectors represent the deepest premium pool; Museums command the highest per-asset valuations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The art insurance market exhibits a pronounced import-export imbalance in premium flow, with underwriting capacity concentrated in mature financial centers while collector demand spreads across emerging wealth hubs. Cross-border art lending structures generate substantial transit coverage requirements between these poles.
United States
New York and Los Angeles collectors drive demand for high-value contemporary coverage, with family offices increasingly adopting captive structures for first-dollar retention. State insurance regulators in New York and California scrutinize agreed-value adequacy for policies exceeding threshold limits. Miami's emergence as a Latin American art hub generates specialized transit-to-storage coverage for works moving between freeport facilities.
United Kingdom
London's auction houses and gallery districts sustain the deepest premium pool outside North America, with Lloyd's syndicates dominating war and terrorism risk extensions. The Financial Conduct Authority shapes capital adequacy requirements and policy form standardization across underwriting entities. Mayfair and St. James's clusters concentrate both broker expertise and collector residential exposure.
Germany
Berlin's contemporary artist studios and Munich's museum networks generate divergent coverage needs, from equipment bundling to long-term exhibition policies. EU Solvency II frameworks enable cross-border group structures spanning Luxembourg and France. Cologne's art fair circuit creates seasonal spikes in transit policy demand.
Switzerland
Geneva and Zurich freeport storage facilities concentrate tax-advantaged collections requiring specialized vault-to-vault coverage. Swissmedic and FINMA oversight intersects with art market regulation through anti-money laundering protocols for high-value transactions. Basel's position as a tri-national hub generates complex multi-jurisdictional underwriting requirements.
Singapore
The city-state's freeport expansion and Southeast Asian collector base growth drive demand for parametric transit triggers and climate-controlled storage coverage. The Monetary Authority of Singapore's risk-based capital framework shapes insurer entry strategies. Marina Bay's cultural district development generates long-term exhibition coverage requirements for institutional lenders.
Art Insurance Market Vendor Landscape
On the supply side, the industry is tiered between global multi-line carriers with dedicated fine art divisions and specialized syndicates concentrating on niche peril extensions. Premium flow concentrates among underwriters with proven claims-handling relationships in major art market centers. Three archetypes dominate: integrated property-casualty giants with museum network relationships, boutique Lloyd's syndicates with transit specialization, and regional carriers with freeport storage expertise. Competitive dynamics center on geographic expansion into Middle Eastern sovereign collections and technology partnerships for blockchain-verified underwriting.
Within the integrated carrier tier, AIG leverages its global underwriting footprint across multiple continents while Chubb anchors positions through bespoke high-net-worth collector relationships. Among specialized syndicate structures, Lloyd's of London competes via peril-specific expertise in war, terrorism, and political risk extensions. Hiscox exemplifies the boutique vector with focused coverage for emerging contemporary artists and private dealers. These three represent distinct strategic postures without implying specific market share or relative scale.
| Leading Market Players |
|---|
| AIG |
| Hiscox |
| AXA |
| Huntington T. Block |
| Zurich Insurance Group |
| Chubb |
| Lloyd's of London |
| Markel |
| Allianz |
| Others |
Supply Flow & Price Mechanics
Geneva-London air freight corridors carry the highest per-kilogram insurance loadings in fine art logistics, with their cost volatility feeding directly into premium stratification across collector tiers and underwriting capacity concentration in Swiss and UK domiciles.
Pricing Analysis
Ultra-high-net-worth collectors anchor art insurance pricing through bespoke agreed-value structures. Three-tier pricing separates white-glove concierge service from standard collector policies and economy-tier transit riders. Price differentiation rests on valuation methodology—appraiser certification tier and blockchain provenance verification status—and geographic delivery cost for freeport-to-residence transit. Cost compression in mid-market coverage is intensifying because Lloyd's syndicates are ceding primary layers to captives. Family offices demonstrate the lowest price sensitivity; emerging collectors in Southeast Asia show the highest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates art insurance supply chain risk through disrupted exhibition lending flows and stranded transit coverage. Underwriting capacity concentrates in the United Kingdom, Switzerland, and the United States. Raw material dependencies include specialized crating composites, climate-controlled container fleets, and conservation-grade packing materials. Single-source vulnerability sits with certified fine art valuators concentrated in London, New York, and Paris. Distribution runs through broker networks anchored in Mayfair, Manhattan, and Geneva.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Art insurance functions as a platform economy in transition, with blockchain title registries and parametric payout oracles creating interoperability layers that reward carriers with API-first policy administration architectures.
For Market Incumbents: Pre-empt disintermediation by distributed ledger consortia through captive investment in smart contract infrastructure and conservation science talent pipelines. Threat vectors include insurtech entrants with automated valuation models and parametric triggers that compress claims cycles from months to hours. Priority levers include backward integration into digital condition monitoring hardware and exclusive partnerships with freeport operators in Singapore and Luxembourg.
For New Entrants and Emerging Players: Southeast Asian private banking channels offer the most penetrable white-space for art insurance distribution, with Singapore's family office density outpacing local underwriting capacity. Target Middle Eastern sovereign collection construction programs in Abu Dhabi and Doha for long-term exhibition coverage mandates. Go-to-market angle centers on parametric climate peril products for transit through flood-prone corridors.
For Investors and Strategic Acquirers: Carve-out targets emerge from multi-line carriers with dormant fine art divisions lacking blockchain integration or conservation risk transfer expertise. Long-term viability over the coming decade hinges on data network effects from provenance verification partnerships. Signal to monitor: Lloyd's syndicate consolidation rates and specialist underwriter migration to technology-enabled platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Smart contract payouts via Ethereum-compatible oracles compress claims settlement from quarters to minutes. |
| Parametric Climate Product Launch | Flood and wildfire triggers for Geneva-Singapore transit routes enable rapid indemnity without loss adjustment. |
| Conservation Science Partnership | Exclusive alliances with Courtauld Institute and NYU conservation programs secure restoration capacity. |
| Freeport Operator Joint Venture | Luxembourg and Singapore vault-to-vault coverage integration locks in tax-advantaged storage premium flow. |
| Family Office Captive Structuring | Bermuda and Cayman domiciliation services for first-dollar retention concentrate tail-risk pricing power. |
Methodological Framework
A standing panel of fine art underwriters, museum risk managers, freeport operators, and conservation scientists provided ongoing calibration against operating reality. Primary interviews with Lloyd's syndicate leads, AIG and Chubb division heads, and Geneva-based brokers were cross-referenced with secondary validation from EU Solvency II regulatory filings, Financial Conduct Authority policy form registrations, and customs data from USITC art import records. Bottom-up premium flow modeling triangulated against top-down market size estimates from auction house transaction databases.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include coverage type tier, insured asset material category, policy structure, and client professional status. CAGRs were derived from exponential smoothing of historical premium growth adjusted for blockchain adoption curves and freeport storage capacity expansion. Industry-specific forecast inputs incorporated IoT sensor penetration rates in high-value transit and GDPR enforcement patterns affecting cross-border provenance documentation.
Practitioners should monitor regulatory technology mandates from EU supervisory authorities and US state insurance commissioners for early signals of forecast revision. Assumptions regarding parametric trigger adoption and collector captive formation rates carry the greatest uncertainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Japan Property and Casualty Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Online Insurance Market
Insurance
Family Floater Health Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Cargo Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
General Insurance Market
Insurance
Bancassurance in ASEAN Market