
 Pelvic Reconstruction Market | 2026-2036
Pelvic Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Reconstruction Market Analytics
ISO 13485 certification is bifurcating the competitive landscape into qualified manufacturers and excluded aspirants. Johnson & Johnson Services leverages its broad surgical portfolio to sustain institutional purchasing contracts across major health systems. Boston Scientific differentiates through urogynecology specialization and deep clinical training infrastructure. Medtronic anchors its position via integrated operating room ecosystems that bundle navigation with implant delivery.
Pelvic reconstruction encompasses surgical restoration of pelvic floor integrity, organ suspension, and skeletal stabilization using biocompatible mesh matrices, collagen-derived grafts, and titanium or resorbable fixation hardware engineered for load-bearing anatomical zones. Mesh implants command the largest revenue pool despite regulatory scrutiny, while biological grafts capture expanding share among safety-conscious surgeons and institutional review boards. Robot-assisted surgery as a delivery mode is growing fastest as capital equipment depreciation models and training curricula mature across teaching hospitals.
FDA premarket notification requirements and ongoing mesh safety orders shape product development timelines and liability exposure for manufacturers. EMA's Medical Device Regulation and CE marking protocols govern European market access with escalating clinical evidence standards. Stakeholders must monitor how regulator risk-benefit reassessments redirect procurement criteria and surgeon training investments without explicit timeline anchors.
Market Dynamics
FDA mesh safety orders and EMA MDR enforcement are compressing product qualification timelines while hospitals consolidate purchasing around ISO 13485-certified suppliers. This regulatory bifurcation is restructuring competitive access and capital allocation across the implant ecosystem.
Growth Catalysts
- Robot-assisted delivery infrastructure:Teaching hospitals in the United States are depreciating da Vinci and Hugo RAS platforms across pelvic floor service lines, expanding addressable case volumes for precision implant placement.
- Biological graft procurement mandates:Institutional review boards at tertiary referral centers are rewriting procurement criteria to prioritize collagen-derived matrices over synthetic alternatives amid liability exposure concerns.
- Hospital service line expansion:Health systems are designating pelvic reconstruction as core revenue pillars, dedicating capital budgets to dedicated urogynecology suites and specialized nursing staff.
Market Restraints
- Polypropylene input cost volatility:Petrochemical feedstock fluctuations and supply chain disruptions are compressing margins on synthetic mesh manufacturing, particularly for mid-tier suppliers without backward integration into polymer production.
- European regulatory friction:EMA MDR clinical evidence requirements and notified body capacity constraints are extending CE marking timelines, freezing market access for non-legacy manufacturers.
- Biological graft substitution pressure:Porcine and human cadaveric allografts are capturing preference share among safety-conscious surgeons, displacing synthetic mesh in anterior compartment repair protocols.
Strategic Opportunities
- Underpenetrated ambulatory surgical center channel:Freestanding ASCs in Texas and Florida are installing dedicated pelvic floor robotics, creating new case volume outside hospital purchasing agreements.
- Navigation-implant convergence:Optical tracking systems from spinal surgery are migrating into pelvic reconstruction, enabling real-time fixation hardware placement with reduced fluoroscopy exposure.
- Resorbable polymer tailwinds:PLA-PLGA copolymer fixation screws are qualifying for preferential reimbursement under device innovation pathways at CMS, accelerating material transition away from permanent titanium.
Industry Challenges
- Specialized surgical talent scarcity:Fellowship-trained urogynecologists and female pelvic medicine specialists remain concentrated at academic medical centers, constraining case volume expansion into community hospital settings.
- ISO 13485 certification timeline compression:Quality management system audits and technical documentation requirements are extending product launch cycles, particularly for biological graft manufacturers navigating animal tissue sourcing compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Reconstruction Market |
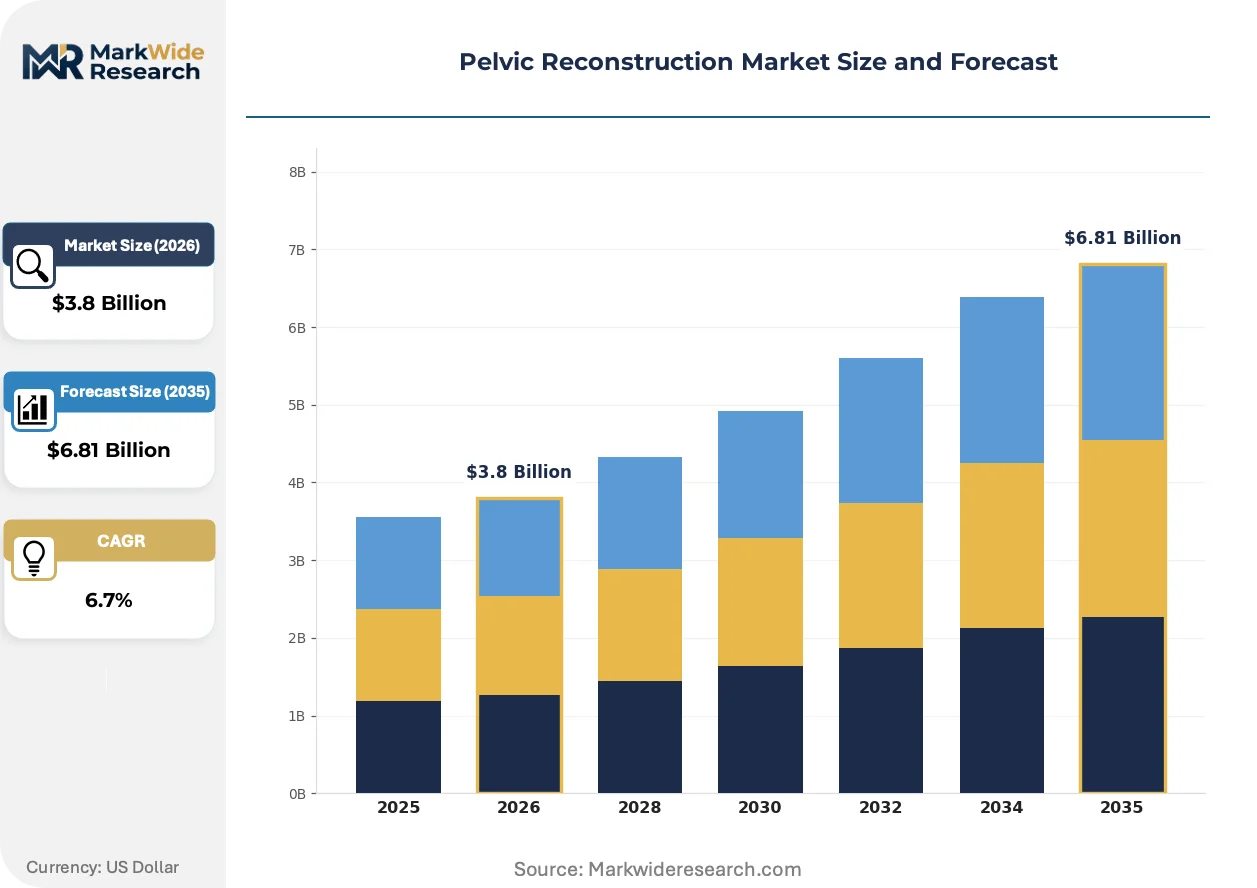
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Implants, Biological Grafts, Surgical Tools, Fixation Devices Application: Hernia Repair, Prolapse Treatment, Bone Stabilization, Surgery Assistance End User: Surgery Centers, Hospitals, Rehabilitation Facilities, Outpatient Clinics Delivery Mode: Traditional Surgery, Minimally Invasive Surgery, Robot-Assisted Surgery, Outpatient Procedures |
| Companies Covered | Johnson & Johnson Services, Coloplast, Boston Scientific, Cook Medical, CooperSurgical, Promedon, Medtronic, Integra LifeSciences, Dr. Arabin GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Reconstruction Market Evolving Landscape
Three intersecting forces are restructuring how pelvic reconstruction technologies reach surgeons and patients. Material science advances, regulatory evidence requirements, and purchasing centralization are each reshaping competitive positioning.
Resorbable polymer fixation hardware is decomposing the permanent implant paradigm in pelvic floor reconstruction. Academic medical centers in the United States are transitioning anterior and posterior compartment repair protocols toward PLA-PLGA screws and tacks that eliminate long-term foreign body exposure. This material shift is decomposing the service revenue model for revision surgery, compressing aftermarket potential while opening primary procedure volume.
EMA MDR Article 117 and enhanced clinical evidence requirements are forcing biological graft manufacturers to generate prospective data packages. European notified bodies are rejecting legacy predicate comparisons for animal-derived matrices, mandating de novo clinical investigations. Synthetic mesh suppliers with pre-MDR certificates are exploiting this transition friction to defend installed base positions while biological competitors absorb trial costs.
Hospital value analysis committees are consolidating implant purchasing around single-source agreements with comprehensive vendor inventory management. Tertiary referral centers are replacing surgeon-specific preference cards with system-wide contracted SKUs, standardizing mesh and graft selection across service lines. This concentration is most visible in the United States, where IDN consolidation has reduced independent hospital purchasing autonomy.
Pelvic Reconstruction Market Segmentation
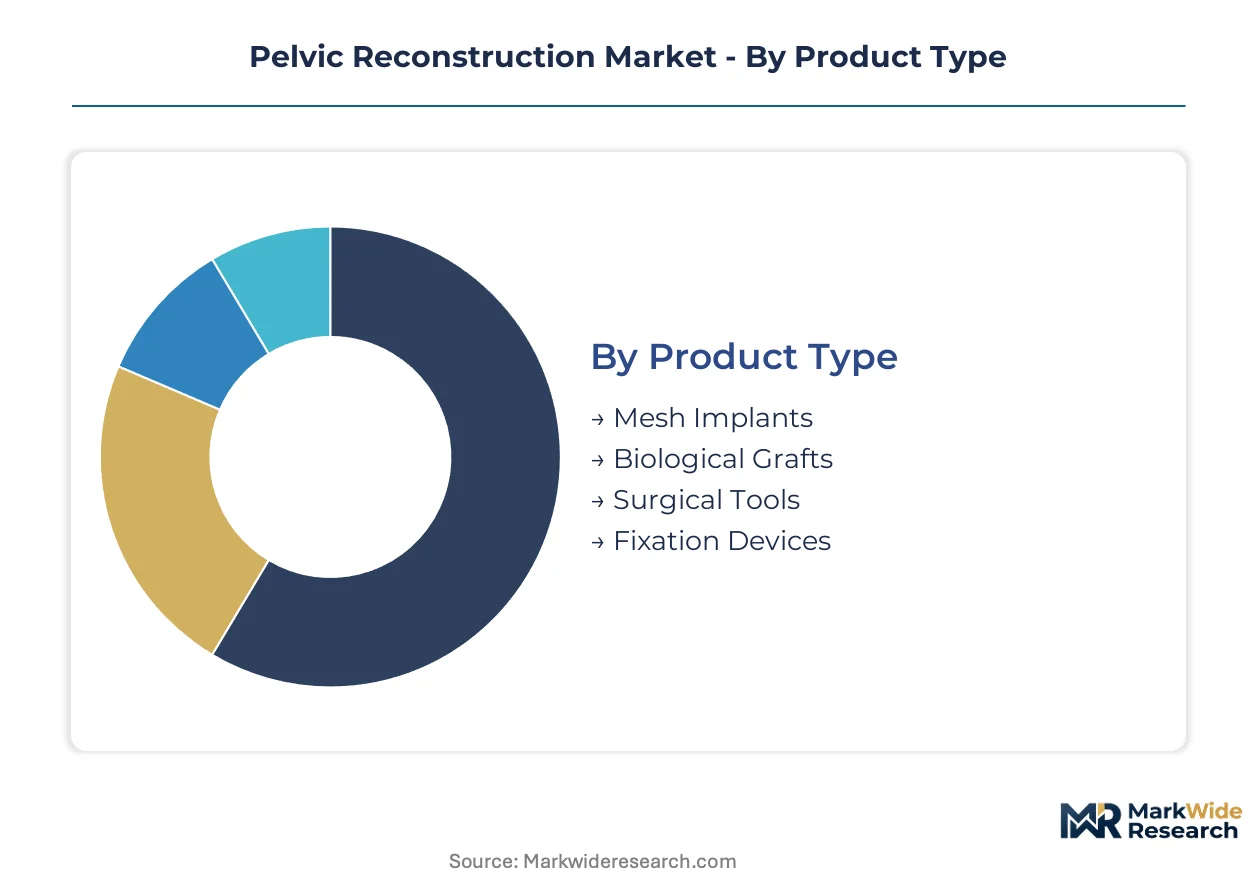
Pelvic reconstruction markets fragment across four dimensions that determine procurement pathways and margin capture. Product composition, surgical application, care setting, and delivery technology each create distinct competitive battlegrounds with divergent regulatory exposure and pricing power.
Product Type:
Margin pools concentrate in implantable matrices where material science differentiation commands premium positioning against commodity hardware.
- Mesh Implants:Polypropylene and composite polymer matrices engineered for tensile strength in load-bearing pelvic zones. Demand clusters at tertiary referral centers in the United States where complex prolapse cases require synthetic reinforcement, though FDA safety orders have tightened qualification pathways and liability exposure.
- Biological Grafts:Collagen-derived matrices sourced from porcine dermis or human cadaveric allograft tissue. Academic medical centers in California and Massachusetts are rewriting procurement protocols to prioritize these alternatives amid institutional review board pressure to reduce synthetic foreign body exposure.
- Surgical Tools:Dissectors, retractors, and specialized instrumentation for pelvic floor access.
- Fixation Devices:Titanium screws, tacks, and anchoring hardware for graft suspension.
The dominant share belongs to Mesh Implants, while Biological Grafts is closing the gap fastest.
Application:
Volume concentration tracks the epidemiology of pelvic floor disorders, with prolapse and hernia repair generating recurring procedure demand.
- Prolapse Treatment:Anterior, posterior, and apical compartment suspension procedures using mesh or graft reinforcement. Tertiary urogynecology centers in Texas and Florida are expanding dedicated service lines for complex multicompartment cases, driving preference for robot-assisted delivery platforms.
- Hernia Repair:Inguinal and ventral hernia mesh placement where pelvic reconstruction techniques overlap with general surgery. Community hospitals in the Midwest United States maintain high throughput for these procedures, prioritizing cost-efficient synthetic mesh over biological alternatives.
- Bone Stabilization:Pelvic fracture fixation and acetabular reconstruction using plate and screw systems.
- Surgery Assistance:Adjunctive products for exposure and hemostasis during pelvic procedures.
Prolapse Treatment holds the largest addressable base, with Hernia Repair expanding most quickly through ambulatory migration.
End User:
Purchasing autonomy determines contract structure, with consolidated health systems extracting volume discounts unavailable to independent facilities.
- Hospitals:Integrated delivery networks with centralized value analysis committees and single-source vendor agreements. Major systems in the Northeast United States are standardizing mesh and graft selection across urogynecology, colorectal, and general surgery service lines.
- Surgery Centers:Freestanding ambulatory facilities investing in dedicated pelvic floor robotics. Texas and Florida ASCs are capturing migration of uncomplicated prolapse cases from hospital outpatient departments through specialized nursing staff and depreciated capital equipment.
- Rehabilitation Facilities:Postoperative care settings with limited direct implant procurement.
- Outpatient Clinics:Diagnostic and minor procedural sites without surgical implant demand.
Hospitals retain the dominant procurement volume, though Surgery Centers are gaining share fastest through case migration.
Delivery Mode:
Technology intensity separates reimbursement tiers and capital investment requirements across surgical approaches.
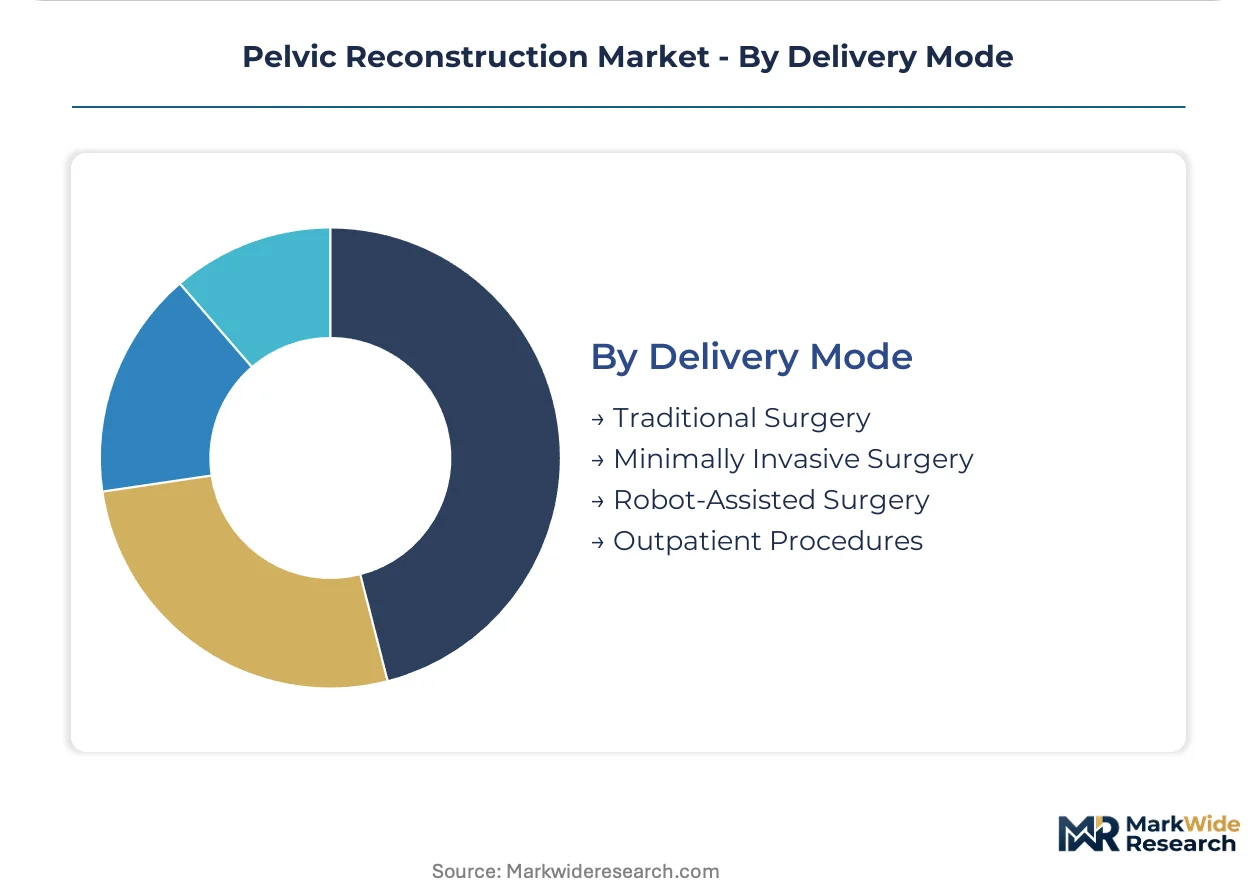
- Robot-Assisted Surgery:Da Vinci and Hugo RAS platforms enabling precision mesh placement and suturing through magnified 3D visualization. Teaching hospitals in Illinois and Pennsylvania are depreciating these systems across pelvic floor service lines, expanding fellowship training curricula and case volume.
- Minimally Invasive Surgery:Laparoscopic and vaginal approaches reducing recovery time versus open procedures. Community hospitals in the Southeastern United States are prioritizing laparoscopic prolapse repair to meet patient preference for shorter stays without full robotic capital commitment.
- Traditional Surgery:Open abdominal or vaginal approaches for complex revision cases.
- Outpatient Procedures:Office-based minor interventions without implant placement.
Robot-Assisted Surgery commands the steepest expansion trajectory, while Minimally Invasive Surgery maintains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and tertiary referral hospitals concentrate procurement authority across major economies, with regulatory divergence creating distinct qualification pathways for implant manufacturers seeking market access.
United States
Tertiary urogynecology centers in Texas, Florida, and Illinois drive complex prolapse case volumes through dedicated service lines. FDA mesh safety orders and evolving premarket notification requirements reshape product liability exposure and surgeon training investments. The Greater Boston and California clusters prioritize biological graft procurement mandates amid institutional review board pressure to reduce synthetic foreign body exposure.
Germany
Baden-Württemberg and Bavaria host concentrated manufacturing capabilities for precision fixation hardware and resorbable polymer systems. EMA Medical Device Regulation enforcement and notified body capacity constraints extend CE marking timelines for biological graft entrants. The North Rhine-Westphalia hospital network consolidates purchasing around ISO 13485-certified suppliers with comprehensive inventory management agreements.
United Kingdom
NHS integrated care systems in London and the Southeast standardize mesh and graft selection through centralized value analysis committees. MHRA alignment with EMA MDR clinical evidence standards elevates barriers for animal-derived matrix manufacturers. The Midlands surgical hub network expands robot-assisted pelvic floor service lines through depreciated da Vinci platform deployment.
Japan
PMDA marketing authorization requirements and reimbursement pricing negotiations govern market entry for foreign implant manufacturers. The Kanto/Tokyo academic medical center cluster drives adoption of navigation-integrated fixation systems migrated from spinal surgery applications. Kansai region hospitals prioritize minimally invasive delivery modes to meet patient preference for reduced recovery periods.
Australia
TGA conformity assessment procedures and prostheses list inclusion determine reimbursement eligibility for mesh and biological graft products. New South Wales and Victoria teaching hospitals expand fellowship-trained urogynecology capacity to address specialized surgical talent scarcity. Queensland ambulatory surgical centers capture uncomplicated prolapse case migration from hospital outpatient departments.
Pelvic Reconstruction Market Competitive Landscape
Player mix skews toward diversified surgical portfolio conglomerates with broad institutional purchasing contracts, ISO 13485-certified specialists with regulatory qualification moats, and regional biological graft manufacturers navigating animal tissue sourcing compliance. Strategic archetypes include integrated operating room ecosystem bundlers, urogynecology-focused clinical training infrastructure builders, and resorbable polymer material science innovators. Dominant competitive moves center on single-source vendor agreement consolidation and navigation-implant technology convergence partnerships.
Among diversified surgical conglomerates, Johnson & Johnson Services and Boston Scientific occupy positions anchoring institutional purchasing networks across major health systems, while Medtronic exemplifies the integrated ecosystem archetype bundling navigation with implant delivery platforms. Coloplast and Cook Medical represent specialized urogynecology and biological graft qualification pathways respectively, with CooperSurgical sitting within the female pelvic medicine training infrastructure tier. Promedon, Integra LifeSciences, and Dr. Arabin GmbH & Co. KG exemplify regional specialists navigating EMA MDR and FDA parallel qualification demands.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| Coloplast |
| Boston Scientific |
| Cook Medical |
| CooperSurgical |
| Promedon |
| Medtronic |
| Integra LifeSciences |
| Dr. Arabin GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with polypropylene suppliers lock in both raw material access and production cost visibility for mesh manufacturers navigating petrochemical feedstock volatility. These contracts anchor pricing stability for tier-one suppliers while mid-tier competitors absorb spot market exposure.
Pricing Analysis
Cost-plus contracts with ethylene price indexation dominate synthetic mesh procurement between manufacturers and integrated health systems. Three-tier pricing structure across premium biological grafts, standard polypropylene mesh, and economy fixation hardware reflects ISO 13485 certification grade and surgeon training bundling. Cost compression in economy synthetic tiers intensifies because Asian polymer suppliers are expanding polypropylene capacity. Community hospitals in the Midwest United States exhibit highest price sensitivity, while tertiary academic centers prioritize graft biocompatibility over unit cost.
Supply Chain Analysis
Inventory buffers for biological grafts extend lead times to ninety days amid porcine tissue sourcing compliance audits. Manufacturing concentrates in Germany, Switzerland, and the United States for precision fixation hardware, while China and India supply titanium raw stock. Polypropylene resin and collagen tissue matrix feed from petrochemical and abattoir networks respectively. Single-source vulnerability concentrates in European notified body capacity for CE marking. Distribution runs through hospital value analysis committees and GPO contracts rather than direct surgeon purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated IDNs with single-source vendor mandates, fragmenting surgeon autonomy over implant selection. Hospital system consolidation across the United States accelerates this procurement centralization.
For Market Incumbents: Secure exclusive multi-year contracts with top-ten IDNs before biological graft competitors complete EMA MDR clinical trials. Lock in da Vinci platform bundling agreements with teaching hospitals in Texas and Florida. Biological graft substitution and resorbable polymer startups threaten synthetic mesh installed bases. Backward integration into collagen tissue sourcing insulates margin pressure from allograft suppliers. For New Entrants and Emerging Players: Differentiate on resorbable PLA-PLGA fixation hardware with CMS innovation pathway reimbursement codes. Target ambulatory surgical centers in Texas and Florida where robot-assisted case volumes outpace hospital purchasing committee oversight. White-space exists in navigation-integrated pelvic floor systems migrated from spinal surgery applications. Go-to-market through specialized urogynecology distributor networks bypasses entrenched GPO lockouts. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 13485-certified biological graft manufacturers with de novo clinical data packages nearing EMA MDR submission. Long-term viability hinges on regulatory qualification moats rather than commodity manufacturing scale. Watch FDA mesh safety order expansion as inflection signal for accelerated biological graft procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | 510(k) clearance anchors liability exposure and surgeon training investments for mesh manufacturers. |
| CE Marking Under EMA MDR Article 117 | Enhanced clinical evidence requirements freeze market access for non-legacy biological graft entrants. |
| Hospital System Partnership | Single-source agreements with IDNs consolidate procurement around ISO 13485-certified supplier rosters. |
| Software Companion Development | Navigation-implant convergence enables real-time fixation placement with reduced fluoroscopy exposure. |
| Reimbursement Strategy | CMS device innovation pathways accelerate preferential coding for resorbable polymer fixation screws. |
Research Methodology
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings on purchasing centralization trends. Primary fieldwork encompassed urogynecologists, biomedical engineers, GPO contracts managers, and value analysis committee chairs across the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) filings, EMA MDR notified body registers, CMS reimbursement coding updates, and hospital capital expenditure disclosures. Bottom-up implant volume modeling triangulates against top-down health system service line revenue estimates.
Sensitivity analysis around regulatory timeline scenarios and raw material cost assumptions tests forecast robustness across the projection horizon. Segmentation dimensions include product composition, surgical application, care setting, and delivery technology, with additional modeling of reimbursement pathway tier. CAGRs derive from logistic adoption curves for robot-assisted surgery penetration and biological graft substitution elasticities. Forecast inputs incorporate fellowship-trained surgeon supply constraints and IDN consolidation trajectories.
The analysis sits within stated boundaries; outcomes outside EMA MDR enforcement continuity or FDA mesh safety order stability would require recalibration. Forecasts reflect documented assumptions on case volume migration to ambulatory settings and resorbable polymer qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Surgical AR Systems Market
Medical Devices
TMJ Implants Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Europe Otoscope Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Sphincterotomes Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Vaginal Applicators Market