
 Line Clamp Market | 2026-2036
Line Clamp Market Size, Share, and Industry Trends Forecast 2026-2036
Line Clamp Market Analytics
Market Overview
AS9100-grade specification tiers is collapsing the gap between commercial and aerospace line clamp offerings as procurement teams consolidate supplier bases. TransDigm Group leverages its captive aerospace distribution network to sustain premium positioning across OEM qualification lists. Voss Industries anchors European aftermarket demand through DIN-standard catalog breadth and regional stocking points. Caillau competes in the French automotive tier with localized stamping capacity and just-in-sequence delivery contracts.
Technical Profile and Segment Structure
A line clamp is a mechanical fastening device that secures tubes, hoses, or cables to structural surfaces, typically manufactured from stamped metal or injection-molded polymer with specified clamping force ratings and vibration resistance parameters. Its primary industrial purpose is to prevent chafing, fatigue, and dislocation in fluid power, pneumatic, and electrical routing systems across mobile and fixed equipment. Aluminum material grades capture disproportionate margin pools in aerospace applications where weight reduction commands specification premiums, while quick-release clamp configurations represent the fastest-growing product type as maintenance-interval reduction drives tool-free serviceability demands in automotive and wind energy installations. Steel variants still dominate construction and heavy manufacturing end uses where cost sensitivity outweighs mass considerations and corrosion exposure remains moderate.
Regulatory Environment and Outlook
FAA airworthiness directives and EASA certification specifications govern aerospace line clamp fatigue life, galvanic compatibility, and traceability documentation, while REACH substance restrictions and RoHS hazardous material limits constrain plating chemistries and polymer additives in European-sourced products. The EU Green Deal embodied carbon reporting requirements are beginning to flow through tier-one supplier scorecards, reshaping sourcing geography for extruded and stamped clamp components. Stakeholders must monitor evolving CSRD supply chain disclosure rules and their cascading qualification burdens on mid-tier fastener manufacturers.
Market Dynamics
Aerospace OEM fastener standardization programs are compressing supplier qualification timelines while collapsing the historical divide between commercial and aerospace-grade line clamp specifications. This structural force is redrawing competitive boundaries across material grades and certification tiers.
Growth Catalysts
- EU Green Deal embodied carbon reporting:Tier-one supplier scorecards now mandate carbon disclosure, creating specification premiums for low-carbon aluminum extrusions and stamped components in German automotive and industrial machinery clusters.
- Quick-release clamp configurations:Tool-free serviceability demands from wind energy maintenance protocols and automotive service-interval reduction are accelerating adoption of polymer-spring hybrid designs.
- REACH substance restrictions:Plating chemistry constraints on cadmium and hexavalent chromium are forcing material transitions that favor qualified European suppliers with compliant surface treatment capabilities.
Market Restraints
- Aluminum alloy supply concentration:Aerospace-grade 7075 and 2024 series dependence on limited North American and European mill capacity creates input cost volatility and elongates lead times.
- AS9100 certification barriers:Small and mid-tier stampers face structural exclusion from OEM qualification lists due to audit cost burdens and documentation infrastructure requirements.
- Polymer substitution ceiling:Galvanic compatibility mandates and fire-smoke-toxicity specifications in aerospace applications constrain polymer clamp penetration regardless of weight advantages.
Strategic Opportunities
- Indian defense aerospace localization:Offset obligations and indigenization mandates under the country's defense procurement procedures create qualification pathways for AS9100-certified suppliers establishing joint ventures with domestic metalwork clusters.
- CSRD supply chain disclosure rules:Extended reporting obligations on European corporates are forcing tier-two fastener manufacturers to implement traceability systems, creating first-mover advantage for compliant suppliers.
- Additive manufacturing convergence:Topology-optimized titanium clamp geometries from powder-bed fusion processes are opening performance tiers unachievable through conventional stamping or extrusion.
Industry Challenges
- AS9100D transition fatigue:Mid-tier manufacturers struggle with auditor availability and interpretation variance across certification bodies, delaying qualification renewals and freezing new business development.
- Legacy ERP integration:Aerospace traceability requirements for heat lot and test report digitization clash with decades-old shop floor data architectures, demanding capital-intensive MES overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Line Clamp Market |
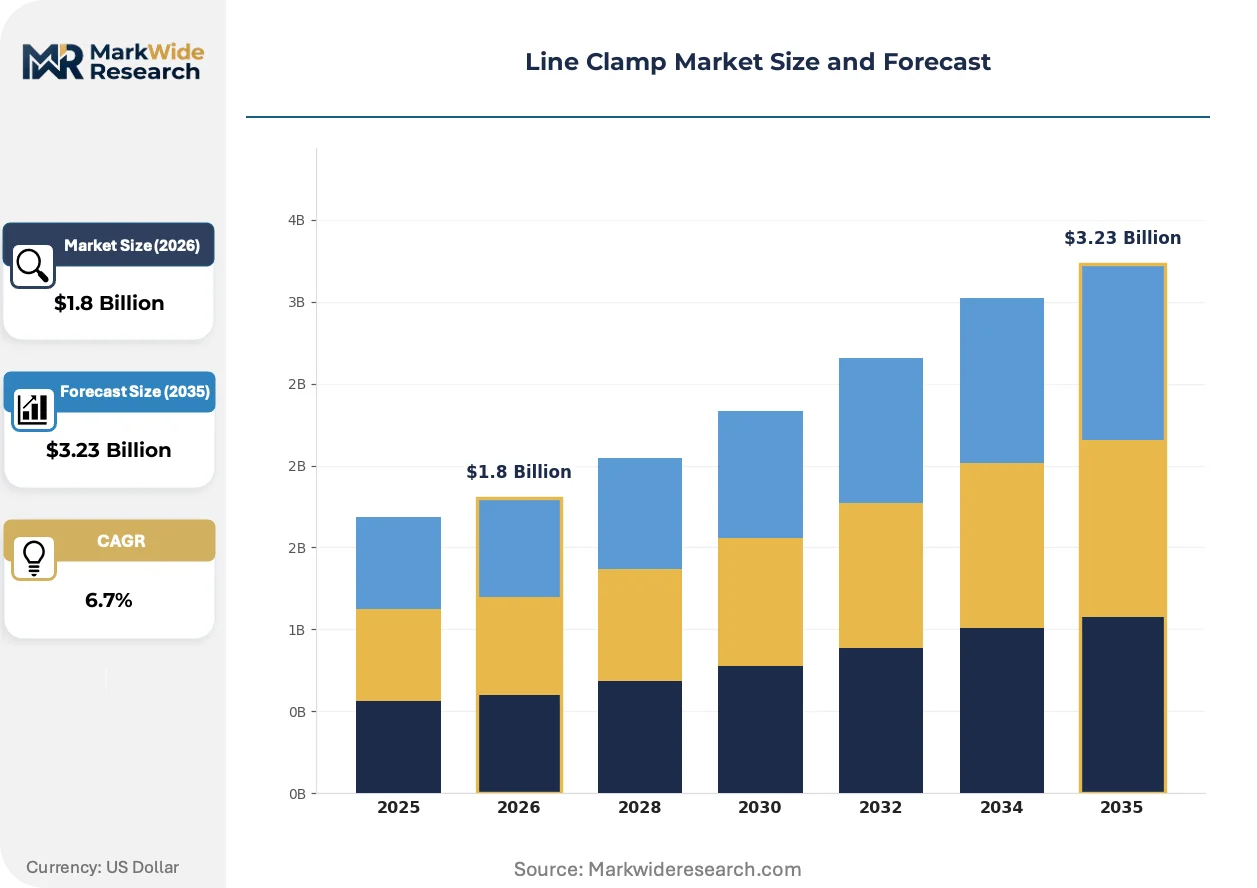
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Clamps, Adjustable Clamps, Quick-Release Clamps, Specialty Clamps Material: Aluminum, Steel, Plastic, Composite End User: Construction, Manufacturing, Automotive, Aerospace Distribution Channel: Online Retailers, Direct Sales, Distributors, Wholesalers |
| Companies Covered | TransDigm Group, Voss Industries, Caillau, Umpco Inc., J&M Products, TeConnex, Pacmet Aerospace, Ho-Ho Kus Inc., Eaton Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Line Clamp Market Evolving Landscape
Active reshaping in line clamp markets stems from material science advances colliding with regulatory chemistry constraints and procurement consolidation. These forces are compressing product lifecycles while elevating specification complexity.
Topology-optimized polymer-overmolded clamps with integrated vibration damping are fragmenting the traditional metal-stamping value pool. Wind turbine OEMs in Denmark and Spain are specifying these configurations for nacelle cable management, displacing stainless steel band-and-trunnion designs. The technology is fragmenting supplier capabilities into discrete competencies—polymer formulation, metal insert precision, and overmold process control—that rarely coexist in legacy stamping houses.
ECHA's REACH candidate list expansion to include PFAS and bisphenol derivatives is forcing reformulation of nylon 6/6 and PBT compounds used in automotive underhood clamps. Compounders in Germany and Belgium are accelerating bio-based polyamide development programs to maintain specification compliance. European-sourced products face the most immediate reformulation pressure, with plating houses simultaneously pivoting from hexavalent chromium to trivalent and zinc-nickel alternatives.
Consolidated procurement functions at tier-one aerospace suppliers are unbundling after-sales inventory management from component supply contracts. Airlines and MRO facilities in the United Arab Emirates and Singapore are demanding vendor-managed inventory programs with consignment stocking at hub locations. This behavioral shift compresses distributor margins while elevating logistics capabilities to competitive parity with metallurgical qualifications.
Line Clamp Market Segmentation
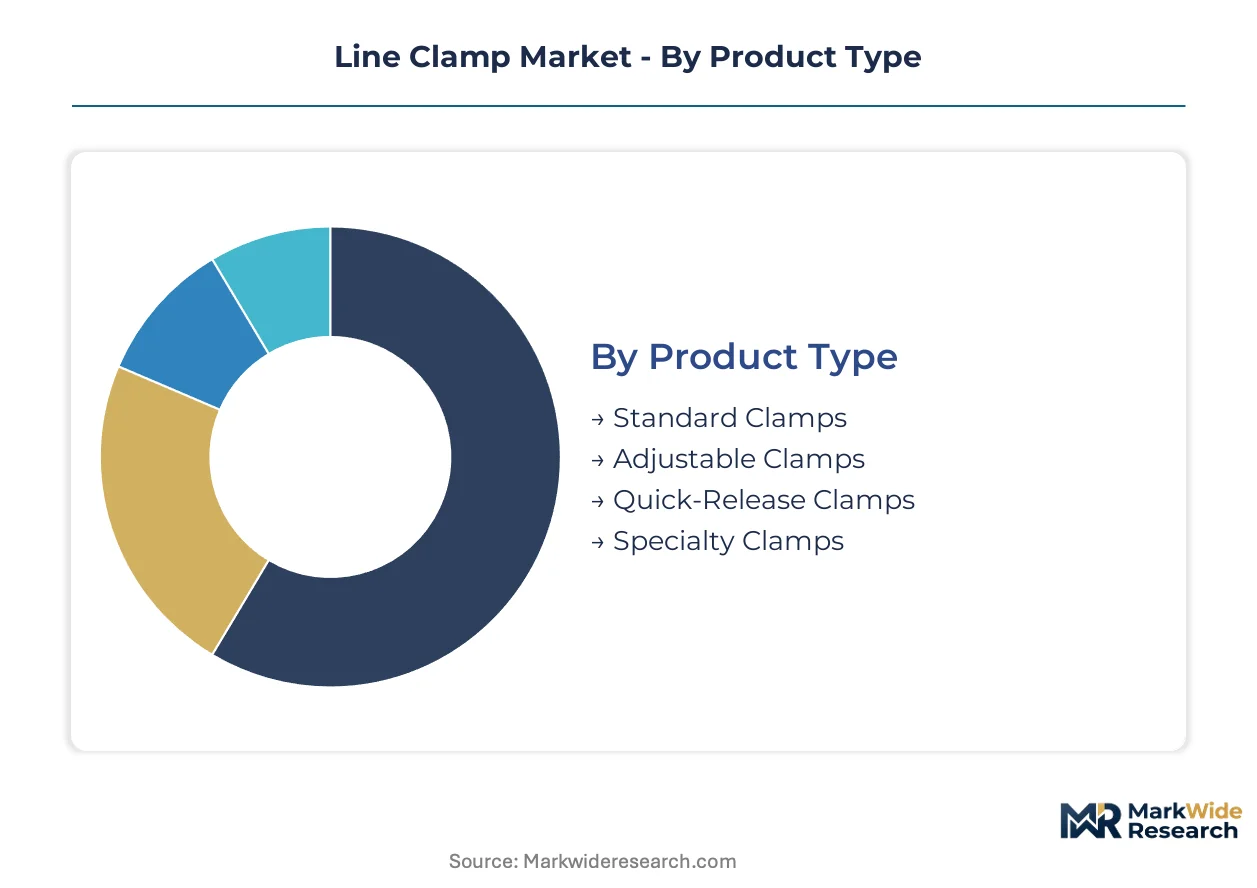
Line clamp procurement patterns fragment sharply across specification grades and material certifications. Aerospace OEMs, automotive tier suppliers, and construction distributors operate on incompatible qualification timelines and margin expectations.
Product Type:
Margin pools concentrate in quick-release configurations where tool-free serviceability commands specification premiums across wind energy and automotive maintenance protocols.
- Quick-Release Clamps:Polymer-spring hybrid designs enable single-hand operation without tooling. Wind turbine OEMs in Denmark and Spain specify these for nacelle cable management, displacing stainless steel band-and-trunnion alternatives as maintenance-interval reduction drives specification shifts.
- Specialty Clamps:Custom-engineered geometries address galvanic compatibility mandates and fire-smoke-toxicity specifications in aerospace applications. AS9100-certified suppliers capture disproportionate margin pools where traceability documentation and fatigue life testing create qualification barriers.
- Standard Clamps:Stamped steel or aluminum band-and-trunnion configurations dominate high-volume construction and industrial machinery procurement.
- Adjustable Clamps:Threaded or slotted designs accommodate diameter tolerance stacks in fluid power and pneumatic routing systems.
Specialty clamps hold installed capacity in aerospace qualification lists. Quick-release configurations are rotating up the share rankings in renewable energy and automotive service applications.
Material:
Cost tier stratification separates specification-grade aluminum extrusions from commodity steel stampings and polymer substitution ceilings.
- Aluminum:7075 and 2024 series alloys capture premium positioning in aerospace applications where weight reduction commands specification premiums. REACH and RoHS compliance constraints on plating chemistries favor qualified European suppliers with trivalent chromium and zinc-nickel surface treatment capabilities.
- Steel:Mild and stainless grades dominate construction and heavy manufacturing where cost sensitivity outweighs mass considerations. DIN-standard catalog breadth anchors European aftermarket demand through regional stocking points.
- Plastic:Nylon 6/6 and PBT compounds face ECHA reformulation pressure as PFAS and bisphenol derivatives enter REACH candidate list restrictions.
- Composite:Polymer-overmolded metal inserts with integrated vibration damping fragment traditional value pools in wind turbine nacelle applications.
Steel maintains volume leadership in construction procurement. Aluminum is climbing fastest in aerospace and automotive lightweighting programs.
End User:
Customer type determines certification burden intensity and procurement consolidation patterns across specification tiers.
- Aerospace:FAA airworthiness directives and EASA certification specifications govern fatigue life, galvanic compatibility, and heat lot traceability. AS9100D qualification barriers structurally exclude small and mid-tier stampers from OEM supplier lists.
- Automotive:Just-in-sequence delivery contracts and vendor-managed inventory programs compress distributor margins while elevating logistics capabilities to competitive parity with metallurgical qualifications.
- Construction:Price-sensitive procurement through wholesale and distributor channels favors standardized steel clamp configurations.
- Manufacturing:Industrial machinery clusters in Germany drive specification-grade procurement with embodied carbon reporting requirements flowing through tier-one supplier scorecards.
Construction holds volume concentration in legacy distribution channels. Aerospace is gaining share fastest in value terms through qualification-driven consolidation.
Distribution Channel:
Supply concentration patterns diverge between captive aerospace networks and fragmented construction wholesale.
- Distributors:Regional stocking points in Germany and France anchor European aftermarket demand through DIN-standard catalog breadth. Consignment programs at UAE and Singapore hub locations compress margins while locking in logistics relationships.
- Direct Sales:Aerospace OEM fastener standardization programs consolidate supplier bases through long-term qualification contracts with integrated traceability documentation.
- Online Retailers:Construction and light industrial procurement migrates toward digital channels with limited specification complexity.
- Wholesalers:Bulk volume aggregation serves price-sensitive construction segments with minimal certification requirements.
Distributors hold relationship density in European industrial clusters. Direct sales is rotating up the share rankings in aerospace consolidation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in aerospace-qualified metalwork corridors and automotive stamping clusters where specification-grade procurement commands premium positioning. German industrial machinery demand and US aerospace OEM consolidation programs anchor volume concentration. REACH compliance mandates and carbon disclosure requirements reshape sourcing geography across extruded and stamped component networks.
United States
Aerospace OEM fastener standardization programs compress supplier qualification timelines across Boeing and Lockheed Martin supply chains. FAA airworthiness directives govern fatigue life documentation and heat lot traceability for AS9100-certified clamp manufacturers. Wichita's aviation cluster and Seattle's Boeing supplier ecosystem concentrate specification-grade aluminum extrusion capacity.
Germany
Automotive and industrial machinery clusters in Stuttgart and Munich drive DIN-standard procurement with embodied carbon reporting flowing through tier-one supplier scorecards. REACH substance restrictions on cadmium and hexavalent chromium plating favor qualified surface treatment houses in Baden-Württemberg. Voss Industries anchors European aftermarket demand through regional stocking points and catalog breadth.
France
Caillau competes in automotive tier supply with localized stamping capacity and just-in-sequence delivery contracts to Renault and Stellantis assembly plants. ECHA's PFAS candidate list expansion forces reformulation of nylon compounds used in underhood clamps. The Auvergne-Rhône-Alpes region hosts precision metalwork clusters serving aerospace qualification lists.
China
Wind turbine OEMs in Jiangsu and Guangdong provinces specify quick-release polymer-spring hybrid clamps for nacelle cable management. MIIT industrial standards and GB certification requirements constrain plating chemistry transitions for export-bound hardware. The Yangtze River Delta concentrates stamped metal capacity serving construction and heavy machinery procurement.
India
Defense procurement procedures create qualification pathways for AS9100-certified suppliers establishing joint ventures with domestic metalwork clusters in Bangalore and Hyderabad. Offset obligations under the country's defense indigenization mandates accelerate aerospace fastener localization. BIS standards govern construction-grade steel clamp specifications for infrastructure projects.
Line Clamp Market Competitive Landscape
Concentration sits with aerospace-qualified specialists and automotive-tier stampers operating on incompatible certification timelines. AS9100D barriers structurally exclude mid-tier fabricators from OEM supplier lists while REACH-compliant European houses capture specification premiums. Two archetypes dominate: captive aerospace distribution networks sustaining premium positioning, and DIN-standard catalog suppliers anchoring aftermarket demand. Competitive moves center on M&A consolidation of qualification lists and geographic expansion through joint venture localization.
Within the aerospace-qualified tier, TransDigm Group and Eaton Aerospace exemplify captive distribution strategies leveraging OEM qualification density. Voss Industries occupies a position among European aftermarket specialists with regional stocking infrastructure. Caillau represents the automotive-tier archetype with localized stamping and just-in-sequence delivery capabilities. These three anchors illustrate the market's structural segmentation across certification burdens and procurement consolidation patterns.
| Leading Market Players |
|---|
| TransDigm Group |
| Voss Industries |
| Caillau |
| Umpco Inc. |
| J&M Products |
| TeConnex |
| Pacmet Aerospace |
| Ho-Ho Kus Inc. |
| Eaton Aerospace |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for aerospace-grade aluminum extrusions concentrate pricing power among North American and European mill-qualified suppliers, compressing margin capture for mid-tier stampers locked out of OEM qualification lists. This inventory friction cascades through tier-one supplier scorecards where embodied carbon reporting mandates now overlay traditional metallurgical premiums.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European-sourced line clamps, separating qualified surface treatment houses with trivalent chromium capabilities from commodity plating operations facing compliance exclusion. Three-tier pricing structure across premium, standard, and economy levels reflects AS9100 certification grade, volume scale, and after-sales inventory bundling. Cost compression in standard steel configurations is intensifying because construction procurement migrates toward digital channels with minimal specification complexity. Automotive tier suppliers exhibit lowest price sensitivity where just-in-sequence delivery contracts lock in logistics premiums, while construction wholesalers face acute margin pressure from spot-market aluminum volatility.
Supply Chain Analysis
Strait of Hormuz transit underwrites Gulf-based logistics hubs serving UAE and Singapore consignment programs, elevating inventory carrying costs for distributor networks. Supply concentrates in Germany, the United States, and China where automotive stamping clusters, aerospace-qualified metalwork corridors, and wind turbine component manufacturing anchor regional capacity. Raw material dependencies draw from 7075 and 2024 series aluminum, nylon 6/6 compounds, and zinc-nickel plating chemistries. Single-source vulnerability sits with limited North American and European mill capacity for aerospace-grade alloys. Distribution runs through captive aerospace networks and DIN-standard catalog suppliers with regional stocking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with mid-tier manufacturers as procurement consolidation unbundles after-sales inventory management from component supply contracts, creating niche entry points for logistics-capable specialists.
For Market Incumbents: Shield qualification list density by accelerating AS9100D certification renewals before auditor availability constraints freeze new business development. Deepen backward integration into aluminum extrusion capacity near Wichita and Seattle aviation clusters to capture margin pools from supply-constrained 7075 series inputs. Channel control through vendor-managed inventory programs at UAE and Singapore hub locations locks in airline and MRO relationships against emerging logistics specialists. For New Entrants and Emerging Players: AS9100 certification fast-track through joint ventures with Bangalore and Hyderabad metalwork clusters opens Indian defense aerospace localization pathways under offset obligation mandates. Target wind turbine nacelle cable management specifications in Denmark and Spain where quick-release polymer-spring hybrid designs displace legacy stainless steel configurations. Go-to-market angle centers on topology-optimized titanium geometries from powder-bed fusion processes unachievable through conventional stamping. For Investors and Strategic Acquirers: Long-term, this sits as a qualification-arbitrage play because AS9100D barriers structurally exclude mid-tier fabricators while consolidating procurement functions elevate traceability documentation to competitive parity with metallurgical performance. Acquisition target archetype: European aftermarket specialists with REACH-compliant surface treatment capabilities and regional stocking infrastructure. Signal to watch is CSRD supply chain disclosure rule implementation forcing tier-two fastener manufacturers into capital-intensive MES overhauls.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Qualification renewal density locks out mid-tier competitors from Boeing and Airbus supplier lists. |
| Joint Venture Localization | Indian defense offset mandates create pathways for certified suppliers partnering with domestic metalwork clusters. |
| Additive Manufacturing Adoption | Topology-optimized titanium clamps from powder-bed fusion open performance tiers beyond conventional stamping limits. |
| Consignment Inventory Programs | UAE and Singapore hub stocking compresses distributor margins while cementing logistics relationships with MRO facilities. |
| REACH-Compliant Surface Treatment | Trivalent chromium and zinc-nickel capabilities capture specification premiums as ECHA restrictions eliminate hexavalent alternatives. |
Research Methodology
Operator-level perspectives from aerospace procurement directors, automotive tier supplier quality managers, wind turbine OEM cable management engineers, and European surface treatment house technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directive filings, EASA certification specification databases, REACH candidate list updates, and tier-one supplier sustainability scorecards. Customs data for aluminum extrusion trade flows, DIN-standard catalog breadth analysis, and AS9100 registrar audit statistics provided quantitative anchors. Bottom-up build from product-type and material-grade demand curves triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around aluminum alloy price volatility, auditor availability for AS9100D transitions, and CSRD disclosure timeline acceleration informed scenario boundaries. The modeling framework segmented volume and value across product type, material certification grade, end-use industry, and regional regulatory cluster throughout the forecast period. CAGRs derived from weighted-average replacement rates in aerospace aftermarket cycles, automotive production content-per-vehicle trends, and wind turbine installation growth curves. Industry-specific inputs included heat lot traceability digitization adoption curves and plating chemistry transition timelines under ECHA restrictions.
Decision-makers should treat outputs as directional under base assumptions of sustained aerospace OEM standardization programs and REACH substance list expansion; material deviation in defense procurement localization timelines or aluminum mill capacity additions would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal embodied carbon reporting thresholds and PFAS candidate list expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
SATA Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Global Fiber Optic Connectors Market
Connectors
5G Connector Market
Connectors
PCI-E Connectors Market
Connectors
Power Connector Market
Connectors
Underwater Connectors Market
Connectors
Mexico Connector Market
Connectors
Wire-To-Board Connector Market
Connectors
AS-Interface Market
Connectors
Japan Connector Market
Connectors
DIN Connectors Market
Connectors
Latin America Connector Market
Connectors
Space Grade Connectors Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Canada Connector Market