
 Telecom Mounting Hardware Market | 2026-2036
Telecom Mounting Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Mounting Hardware Market Analytics
The gap between premium-grade telecom mounting hardware and commodity-grade alternatives is broadening as 5G deployments impose stricter load-bearing and wind-resistance specifications on tower infrastructure. Sabre Industries dominates heavy-duty steel pole manufacturing for macro-cell towers across North American utility corridors. Infinite Electronics International leverages its RF component integration expertise to anchor demand for antenna-optimized mounting systems. Kendall Howard specializes in compact cabinet and rack solutions that compete aggressively in enterprise and data center edge deployments.
Telecom mounting hardware comprises structural support equipment designed to secure antennas, transceivers, cable assemblies, and power systems to towers, rooftops, poles, and indoor infrastructure, typically fabricated from hot-dip galvanized steel, marine-grade aluminum, or fiber-reinforced polymer composites with load ratings spanning 50 kg to over 2,000 kg and wind-speed certifications up to 200 km/h. Its primary purpose is ensuring mechanical stability, electromagnetic interference mitigation, and technician safety across outdoor and indoor telecommunication installations. Steel brackets and poles retain the largest volume share due to entrenched tower standards and lower material costs, though aluminum mounts represent the fastest-expanding material segment as operators prioritize weight reduction for rooftop and small-cell sites. Cabinet demand concentrates in data center and enterprise applications where thermal management integration commands margin premiums over standard outdoor enclosures.
The Federal Communications Commission shapes tower siting and structural loading requirements in the United States, while the European Telecommunications Standards Institute and national regulators such as Germany's Federal Network Agency enforce wind-load and climactic resilience benchmarks across EU member states. India's Department of Telecommunications mandates specific steel grades and anti-corrosion treatments for tower hardware through its unified license framework, directly influencing procurement specifications for network providers. Stakeholders must monitor evolving national broadband targets and tower-sharing mandates that will determine whether capital flows toward new-build infrastructure or retrofit mounting upgrades.
Market Dynamics
5G network densification is compressing tower upgrade cycles and forcing hardware specifications upward, creating a structural split between legacy infrastructure and next-generation mounting requirements that operators must bridge through phased retrofit programs or complete replacement strategies.
Growth Catalysts
- India's Department of Telecommunications unified license framework:Mandates specific steel grades and anti-corrosion treatments, creating standardized procurement pipelines that accelerate replacement demand across tower portfolios.
- Composite material innovation:Fiber-reinforced polymer mounting solutions reduce rooftop structural loads while meeting wind-speed certifications, enabling small-cell deployments previously blocked by weight constraints.
- Germany's Federal Network Agency wind-load benchmarks:Drive tower reinforcement cycles across utility corridors, forcing operators to upgrade bracket and pole specifications ahead of climactic resilience deadlines.
Market Restraints
- Hot-dip galvanized steel input volatility:Zinc price fluctuations compress margin stability for bracket manufacturers serving price-sensitive tower upgrade markets in Brazil and India.
- European supply concentration:Heavy-duty pole fabrication clusters in German and Polish industrial corridors create geographic vulnerability to energy cost shocks and logistics bottlenecks.
- Aluminum alloy substitution ceiling:Load-bearing limitations above 1,500 kg prevent displacement of steel in macro-cell tower applications, constraining material mix evolution.
Strategic Opportunities
- Brazilian tower-sharing mandates:Regulatory pressure on co-location is expanding addressable hardware volume per site as multiple operators install equipment on single structures.
- Data center edge thermal integration:Cabinet mounting systems that incorporate active cooling represent unbundled margin potential beyond standard enclosure specifications.
- RF component convergence:Antenna-optimized mounting hardware that pre-integrates cable management and grounding is expanding into enterprise private network deployments.
Industry Challenges
- Structural engineering talent scarcity:Specialized load-analysis capabilities for 200 km/h wind certification are concentrated among aging technical workforces in North American and European fabrication facilities.
- Multi-standard compliance timelines:Simultaneous FCC, ETSI, and national regulator approval processes extend product launch cycles by 8-14 months for modular mounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Mounting Hardware Market |
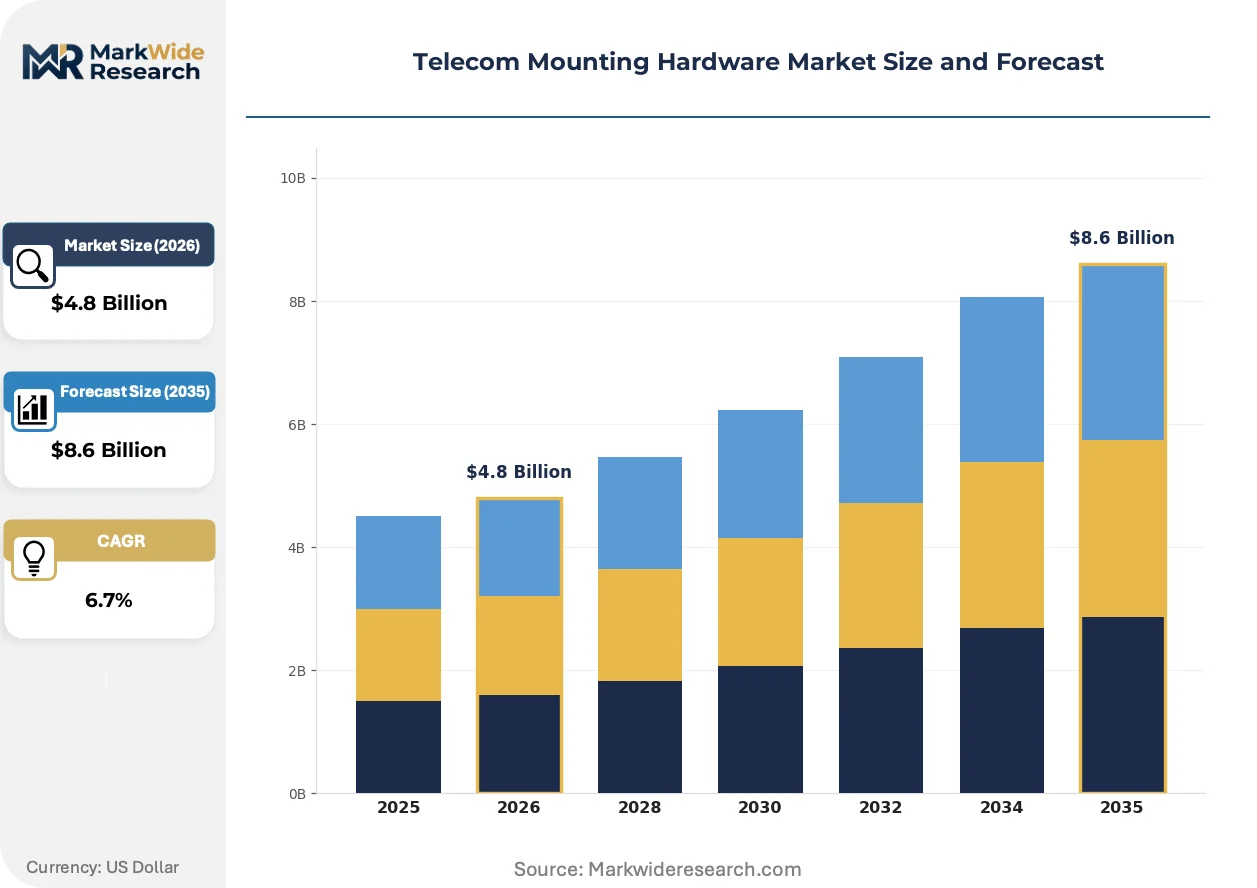
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Poles, Cabinets, Mounts Material: Steel, Aluminum, Plastic, Composite Application: Telecommunication Towers, Antenna Installations, Data Centers, Wireless Networks End User: Telecom Operators, Network Providers, Enterprises, Government Agencies |
| Companies Covered | Malico, Infinite Electronics International, Sabre Industries, Kendall Howard, LEAX Arkivator Telecom AB, Trylon, Talley, Legrand North America, Kenwood Telecom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Mounting Hardware Market Evolving Landscape
Hardware specification convergence with RF performance requirements is blurring traditional boundaries between structural support and electromagnetic optimization, forcing fabrication competencies to expand beyond mechanical engineering into signal integrity domains.
Marine-grade aluminum mounting systems are expanding into rooftop and small-cell installations where weight reduction enables deployment on structures with limited load capacity. Telecom operators in dense urban corridors are specifying these alloys for 5G densification projects where steel would require costly structural reinforcement. The shift is compressing total installation cost while expanding the addressable building stock for outdoor small-cell placement.
ETSI wind-load and climactic resilience benchmarks are tightening certification requirements across EU member states, forcing manufacturers to retest legacy bracket designs against updated stress parameters. German tower operators are responding by consolidating procurement around pre-certified hardware families that reduce site-specific engineering overhead. The regulatory momentum is marginalizing uncertified commodity suppliers from premium infrastructure contracts.
Buyer consolidation among tower companies is compressing vendor negotiation cycles and unbundling after-sales service from hardware procurement. Major operators in the United States are shifting toward multi-year framework agreements that lock in volume pricing while internalizing installation and maintenance capabilities. The model shift is squeezing margin contribution from service attach rates that historically subsidized equipment pricing.
Telecom Mounting Hardware Market Segmentation
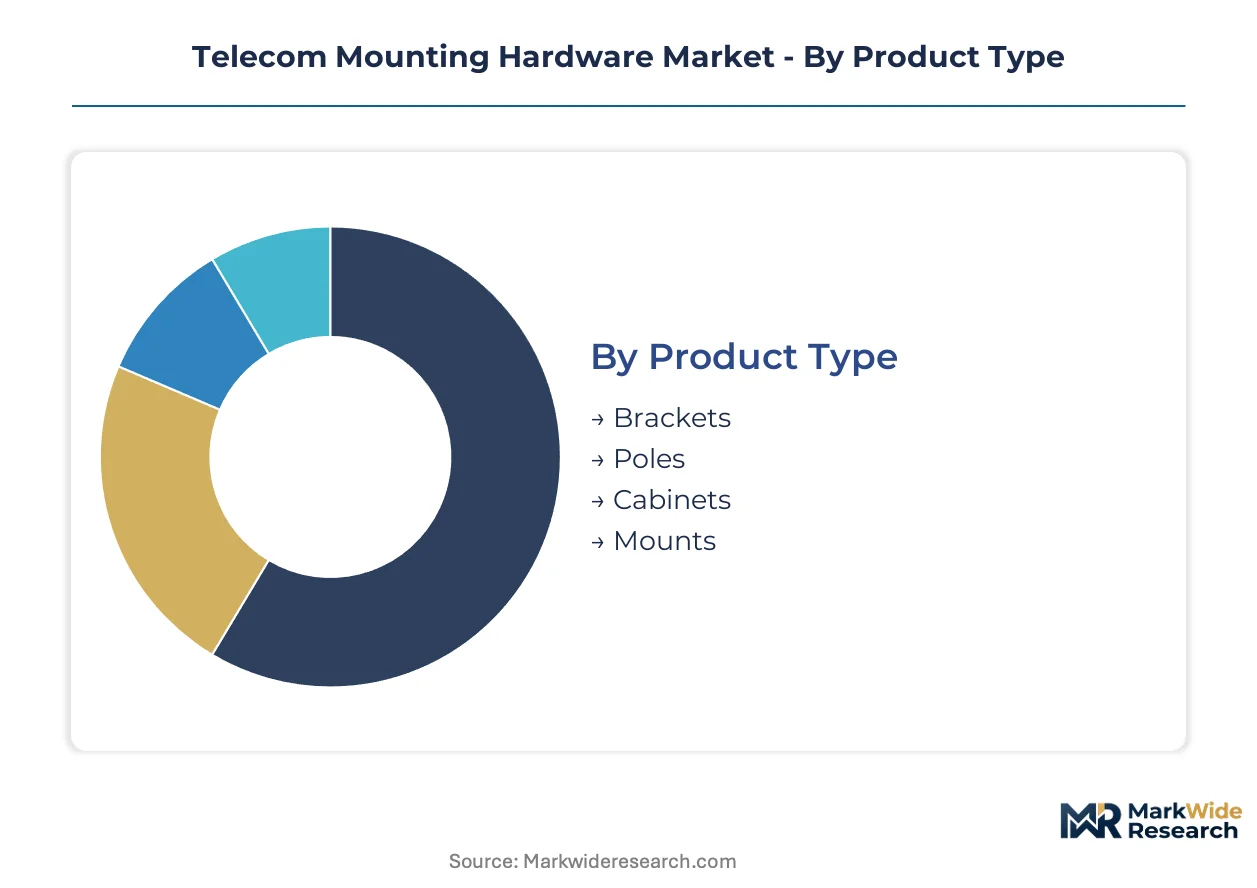
Telecom mounting hardware procurement splits sharply between macro-cell tower reinforcement and small-cell densification, with material selection and load-bearing specifications diverging across deployment contexts. Buyers prioritize wind-speed certification tiers and corrosion resistance ratings that align with site-specific climactic exposure and structural constraints.
Product Type:
Cost tier determines specification depth, with premium-grade hardware commanding extended warranty terms and site-specific engineering support.
- Brackets:Hot-dip galvanized or marine-grade aluminum brackets secure antennas and cable assemblies to tower faces and rooftop structures. Demand clusters in Germany and India where tower upgrade cycles intensify, driven by regulatory mandates for enhanced wind-load resistance.
- Poles:Heavy-duty steel poles support macro-cell towers across utility corridors with load ratings exceeding 2,000 kg. Sabre Industries dominates fabrication for North American deployments where 200 km/h wind certification is standard.
- Cabinets:Compact enclosures integrate thermal management for data center edge applications. Kendall Howard competes aggressively on rack density and cable organization features.
- Mounts:Antenna-optimized mounting systems pre-integrate RF component alignment and grounding pathways. Infinite Electronics International anchors demand through signal integrity expertise.
Volume sits with brackets and poles; growth tilts toward cabinets and mounts as 5G densification accelerates.
Material:
Application environment dictates material selection, with weight constraints and corrosion exposure driving substitution patterns.
- Steel:Hot-dip galvanized steel retains entrenched tower standards and lower material costs for heavy-load macro-cell applications. Procurement specifications in Brazil and India concentrate demand for specific grades mandated by national regulators.
- Aluminum:Marine-grade aluminum alloys reduce structural loads for rooftop and small-cell sites where steel would require costly reinforcement. Telecom operators in dense urban corridors specify these for 5G densification projects.
- Plastic:Limited to lightweight indoor applications and temporary installations where load-bearing requirements remain minimal.
- Composite:Fiber-reinforced polymer solutions enable small-cell deployments previously blocked by weight constraints, meeting wind-speed certifications while reducing rooftop structural loads.
Steel dominates volume; aluminum and composite materials are expanding most quickly as operators prioritize weight reduction.
Application:
Customer type shapes deployment scale, with enterprise and government buyers emphasizing discrete site solutions over portfolio-wide standardization.
- Telecommunication Towers:Macro-cell structures require heavy-duty steel poles and reinforced brackets with 200 km/h wind certification. Germany's Federal Network Agency benchmarks drive reinforcement cycles across utility corridors.
- Antenna Installations:Rooftop and small-cell deployments specify aluminum mounts to minimize structural load and avoid reinforcement costs. FCC siting requirements shape installation protocols in the United States.
- Data Centers:Cabinet and rack solutions compete on thermal management integration and cable density, commanding margin premiums over standard outdoor enclosures.
- Wireless Networks:Enterprise private network deployments drive demand for antenna-optimized mounting hardware with pre-integrated cable management.
Telecommunication towers anchor volume; antenna installations are gaining share fastest as 5G densification penetrates urban corridors.
End User:
Procurement consolidation patterns differentiate buyer segments, with framework agreements and volume pricing reshaping vendor relationships.
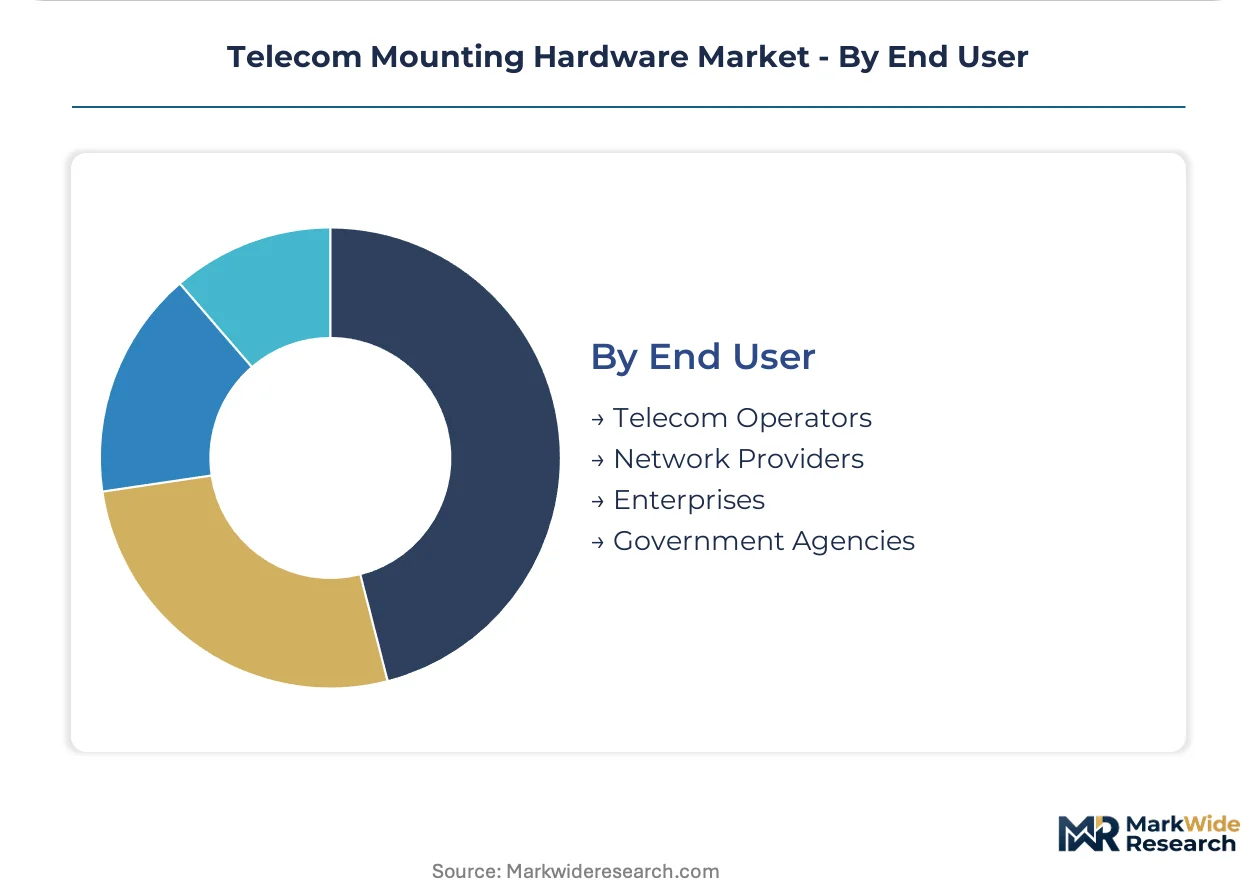
- Telecom Operators:Major tower companies in the United States shift toward multi-year framework agreements that internalize installation capabilities and squeeze service attach margins.
- Network Providers:India's Department of Telecommunications unified license framework mandates specific steel grades, creating standardized procurement pipelines that accelerate replacement demand.
- Enterprises:Data center and edge computing deployments prioritize cabinet systems with active cooling integration, representing unbundled margin potential.
- Government Agencies:Public infrastructure projects emphasize climactic resilience certification and extended warranty terms, often requiring ETSI or national regulator pre-approval.
Telecom operators hold volume concentration; enterprises show the steepest expansion trajectory as private network deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor in Germany anchors heavy-duty pole fabrication for European macro-cell tower deployments, with Dortmund-based steel mills supplying hot-dip galvanized brackets certified to Federal Network Agency wind-load benchmarks.
United States
FCC tower siting requirements compress upgrade timelines across utility corridors, with Sabre Industries dominating heavy-duty steel pole manufacturing for macro-cell infrastructure. The Federal Communications Commission mandates 200 km/h wind certification standards that force bracket specification upgrades. Dallas-Fort Worth metroplex clusters fabrication capacity for North American telecom mounting hardware procurement.
Germany
Federal Network Agency climactic resilience deadlines accelerate tower reinforcement cycles across utility corridors, with operators consolidating procurement around pre-certified hardware families. ETSI wind-load benchmarks tighten certification requirements that marginalize uncertified commodity suppliers. Dortmund and Duisburg industrial zones concentrate heavy-duty pole fabrication capacity serving EU member state deployments.
India
Department of Telecommunications unified license framework mandates specific steel grades and anti-corrosion treatments, creating standardized procurement pipelines that accelerate replacement demand. TRAI tower-sharing directives expand addressable hardware volume per site as multiple operators co-locate equipment. Gujarat and Maharashtra industrial corridors concentrate bracket manufacturing capacity serving domestic tower upgrade cycles.
Brazil
ANVISA-equivalent national telecom regulator frameworks intersect with tower-sharing mandates that expand hardware volume per structure as co-location intensifies. Hot-dip galvanized steel input volatility from zinc price fluctuations compresses margin stability for bracket manufacturers serving price-sensitive upgrade markets. São Paulo state anchors fabrication clusters for Latin American telecom mounting hardware distribution.
China
MIIT 5G network densification targets drive small-cell deployment acceleration across dense urban corridors, with marine-grade aluminum mounting systems penetrating rooftop installations previously blocked by weight constraints. GB standards for structural loading shape procurement specifications for domestic tower operators. Yangtze River Delta manufacturing zones concentrate composite material innovation capacity for fiber-reinforced polymer solutions.
Telecom Mounting Hardware Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and load-bearing specification tiers, with three structural archetypes defining competitive positioning. Heavy-duty steel pole specialists command entrenched relationships with North American utility corridors and European tower operators. RF-integrated mounting system providers leverage signal integrity expertise to capture antenna-optimized hardware premiums. Compact cabinet and rack fabricators compete on thermal management integration for data center edge deployments. Dominant competitive moves include multi-year framework agreement consolidation by major tower companies and backward integration into captive steel and aluminum supply by volume-scale fabricators.
Within the heavy-duty infrastructure tier, Sabre Industries exemplifies scale-driven fabrication archetypes serving macro-cell tower deployments across utility corridors. Kendall Howard occupies a position among compact enclosure specialists competing aggressively on rack density and cable organization features for enterprise and data center applications. Infinite Electronics International represents RF convergence archetypes anchoring demand for antenna-optimized mounting systems through pre-integrated cable management and grounding pathway expertise.
| Leading Market Players |
|---|
| Malico |
| Infinite Electronics International |
| Sabre Industries |
| Kendall Howard |
| LEAX Arkivator Telecom AB |
| Trylon |
| Talley |
| Legrand North America |
| Kenwood Telecom |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up fabrication specialists have consolidated bracket and pole manufacturing across North American utility corridors, tightening pricing discipline through volume-scale procurement leverage while squeezing margin contribution from smaller regional suppliers serving price-sensitive tower upgrade markets.
Pricing Analysis
Value-based pricing anchored to wind-speed certification tiers separates premium-grade hardware with 200 km/h ratings from commodity alternatives lacking ETSI or FCC pre-approval. Three-tier pricing structure across premium, standard, and economy levels stratifies by load-bearing specification and after-sales service bundling. Cost compression in the economy tier intensifies because hot-dip galvanized steel input volatility from zinc price swings compresses manufacturer margins. Tower companies in Brazil and India exhibit the highest price sensitivity, while German operators under Federal Network Agency mandates demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Polish industrial corridors for heavy-duty pole fabrication, where energy cost shocks and logistics bottlenecks threaten delivery continuity for EU macro-cell tower deployments. Raw material dependencies center on hot-dip galvanized steel from Ruhr Valley mills, marine-grade aluminum from Yangtze River Delta smelters, and fiber-reinforced polymer composites from Chinese manufacturing zones. Supply chain risk manifests as tariff exposure on aluminum alloy imports into North American markets. Distribution runs through multi-year framework agreements that major tower companies negotiate directly with volume-scale fabricators, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine-grade aluminum mounting systems are displacing hot-dip galvanized steel in rooftop and small-cell applications, compressing installation costs while expanding addressable building stock for 5G densification projects.
For Market Incumbents: Deepen backward integration into captive aluminum and steel supply to insulate margin stability from zinc price volatility and alloy input cost swings. Sabre Industries and comparable heavy-duty pole specialists should accelerate certification investment for 200 km/h wind-load ratings ahead of ETSI benchmark tightening, while consolidating procurement relationships with tower companies shifting toward internalized installation capabilities. For New Entrants and Emerging Players: Enter via composite material innovation for fiber-reinforced polymer mounting solutions that reduce rooftop structural loads below 1,500 kg thresholds where steel retains dominance. The most penetrable white space sits with enterprise private network deployments requiring antenna-optimized hardware with pre-integrated cable management. A direct-to-tower-company sales model bypassing established distributor relationships offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: TRAI tower-sharing directive implementation in India is the leading indicator that hardware volume per site will expand materially as co-location intensifies across multiple operators. Acquisition targets should concentrate on mid-cap fabricators with pre-certified hardware families and established relationships with India's Department of Telecommunications. Watch for Brazilian ANVISA-equivalent regulatory frameworks intersecting with tower-sharing mandates as the next regional inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive hot-dip galvanized steel production insulates Sabre Industries from zinc price volatility. |
| Certification Investment for Wind-Load Ratings | 200 km/h ETSI pre-approval marginalizes uncertified commodity suppliers from German Federal Network Agency contracts. |
| Composite Material R&D Partnership | Fiber-reinforced polymer innovation unlocks rooftop deployments previously blocked by weight constraints. |
| Multi-Year Framework Agreement Consolidation | Direct procurement relationships with major tower companies reduce distributor margin extraction. |
| RF Component Convergence Development | Antenna-optimized mounting with pre-integrated grounding captures Infinite Electronics International's signal integrity premiums. |
Research Methodology
Regulatory filings from the FCC, ETSI documentation, and India's Department of Telecommunications unified license framework formed the secondary backbone, cross-referenced against tower company procurement disclosures and steel mill production data. Primary interviews with tower engineering directors, bracket fabrication plant managers, and telecom operator infrastructure procurement leads validated specification trends and pricing dynamics. Bottom-up unit economics for bracket, pole, cabinet, and mount categories were triangulated against top-down market sizing from customs trade records and industry association aggregates.
Historical trendline analysis across steel input costs, aluminum alloy pricing, and composite material adoption rates informed the projection framework. Segmentation dimensions modeled include product type, material grade, application environment, and end-user procurement consolidation pattern. CAGRs were derived from slope analysis of replacement cycle compression and 5G densification penetration curves. Forecast inputs incorporated Federal Network Agency climactic resilience deadlines and TRAI tower-sharing directive implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under zinc price volatility extremes and energy cost shock scenarios in German industrial corridors. Forecasts reflect assumptions regarding 5G deployment cadence, regulatory certification timeline stability, and tower-sharing mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
SATA Connector Market
Connectors
AS-Interface Market
Connectors
Connector Adapter Kits Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Connector Kits Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Pin Retainer Market
Connectors
Press Fit Connector Market
Connectors
Small Bore Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Filtered Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
Australia Connector Market