
 Automotive Data Connectors Market | 2026-2036
Automotive Data Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Data Connectors Market Insights
Domain-centralized electrical architectures is tilting connector specifications toward multi-gigabit throughput and miniaturized form factors. TE Connectivity leverages its integrated sensor-to-connector portfolio to anchor high-speed Ethernet deployment across EV platforms. Amphenol sustains manufacturing scale advantages in ruggedized circular connectors for battery management systems. Yazaki Corporation dominates traditional wire-to-board supply chains while navigating the transition to fiber-optic backbone networks.
Automotive data connectors are electromechanical interfaces engineered to transmit power, signals, and data between vehicle subsystems, typically rated for temperatures from -40°C to 150°C and vibration resistance per ISO 16750-3. Their primary purpose is ensuring reliable communication across increasingly complex vehicle networks where signal integrity directly impacts safety-critical functions. PCB connectors lead unit volume in infotainment module assembly, while coaxial connectors command premium positioning in ADAS radar and camera links. Ethernet technology segments are expanding fastest as 100BASE-T1 and 1000BASE-T1 standards displace legacy CAN bus for zonal architecture backbones.
NHTSA's FMVSS requirements for automatic emergency braking and the EU's Cyber Resilience Act are mandating hardened connector designs with tamper-evident sealing and encrypted data pathways. ISO 26262 functional safety standards further constrain supplier qualification timelines, raising barriers for unproven entrants. Stakeholders must weigh backward integration into connector manufacturing against long-term technology bets on optical versus copper interfaces for autonomous driving data loads.
Market Dynamics
Zonal electrical architectures are collapsing distributed ECU networks into domain controllers, forcing connector suppliers to consolidate multi-protocol interfaces into single miniaturized housings. This structural compression is redrawing qualification timelines and procurement specifications across OEM supply chains.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory hardware security modules in connected vehicle components are accelerating demand for encrypted connector platforms with tamper-evident sealing architectures.
- Battery management systems:High-voltage EV platforms require ruggedized circular connectors rated above 800V, pulling specialized interconnect demand through German and Chinese assembly lines.
- Fiber-optic backbone migration:Autonomous driving data loads are pushing OEMs toward optical interfaces for camera and lidar links, opening specification windows beyond traditional copper dominance.
Market Restraints
- Raw material concentration:High-performance copper alloys and engineered thermoplastics face supply bottlenecks from Southeast Asian smelters, compressing margin structures for mid-tier connector manufacturers.
- ISO 26262 functional safety:ASIL-D qualification requirements extend development cycles by 18-24 months, freezing out unproven entrants from safety-critical ADAS connector sockets.
- Legacy CAN bus entrenchment:Established vehicle networks resist wholesale Ethernet replacement due to backward compatibility requirements with 15-20 year vehicle lifecycles.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air update capabilities are creating demand for field-serviceable connector designs with modular pin configurations and tool-free mating cycles.
- Indian EV manufacturing:PLI scheme subsidies for domestic automotive electronics are attracting connector localization investments around Chennai and Pune industrial corridors.
- 1000BASE-T1 standardization:IEEE's multi-gigabit automotive Ethernet specification is opening specification windows for shielded twisted-pair connectors in zonal gateway modules.
Industry Challenges
- Signal integrity engineering talent:Scarce expertise in high-speed PCB connector design for 10Gbps+ channels is constraining product development bandwidth at tier-two suppliers.
- Cleanroom assembly capex:Fiber-optic connector termination requires Class 1000 manufacturing environments, demanding capital commitments that fragment competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Data Connectors Market |
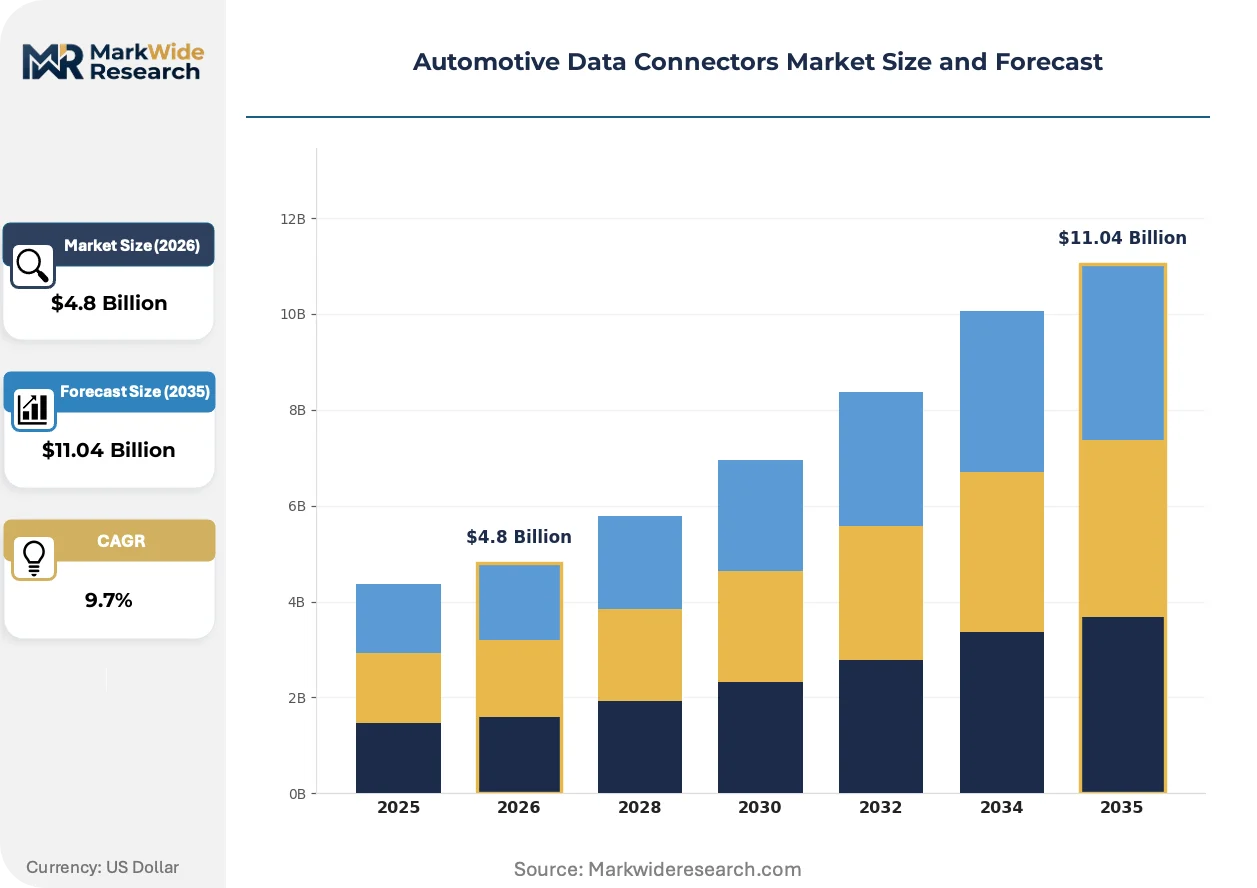
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCB Connectors, Wire-to-Board Connectors, Coaxial Connectors, Circular Connectors, Cable Assemblies Technology: Fiber Optic, USB, Ethernet, CAN Bus, LVDS, HDMI Application: Infotainment Systems, Advanced Driver Assistance Systems, Powertrain Control, Chassis Systems, Body Electronics End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | TE Connectivity, Aptiv, Amphenol, Yazaki Corporation, Molex, Sumitomo Electric Industries, Hirose Electric, Japan Aviation Electronics Industry, Rosenberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Data Connectors Market Trends and Innovations
Physical layer consolidation is collapsing multiple interconnect generations into unified platforms. Suppliers are racing to bridge copper-to-optical transitions while hardening designs against electromagnetic interference and cyber intrusion vectors.
Automotive Ethernet is virtualizing the in-vehicle network stack by collapsing discrete CAN, LIN, and FlexRay domains into unified IP-based backbones. Tier-one suppliers are adopting 100BASE-T1 and 1000BASE-T1 specifications for zonal controller links, compressing wiring harness complexity by eliminating protocol translation gateways. This convergence is forcing connector manufacturers to integrate active signal conditioning directly into housing assemblies.
NHTSA's automatic emergency braking mandate is hardening connector specifications for radar and camera modules with sealed, vibration-resistant designs per FMVSS testing protocols. OEMs are specifying IP6K9K-rated interfaces with redundant locking mechanisms for safety-critical sensor chains. The compliance burden is concentrating procurement authority among suppliers with pre-qualified ASIL-B through ASIL-D component portfolios.
Fleet operators are compressing supplier qualification cycles by demanding modular connector families with common housing platforms across vehicle programs. Tier-one integrators are responding with configurable pin-count variants that share tooled components across economy and premium trim specifications. This standardization push is most visible in North American commercial vehicle manufacturing, where uptime requirements favor field-replaceable connector modules over hard-wired harness repairs.
Automotive Data Connectors Market Segmentation
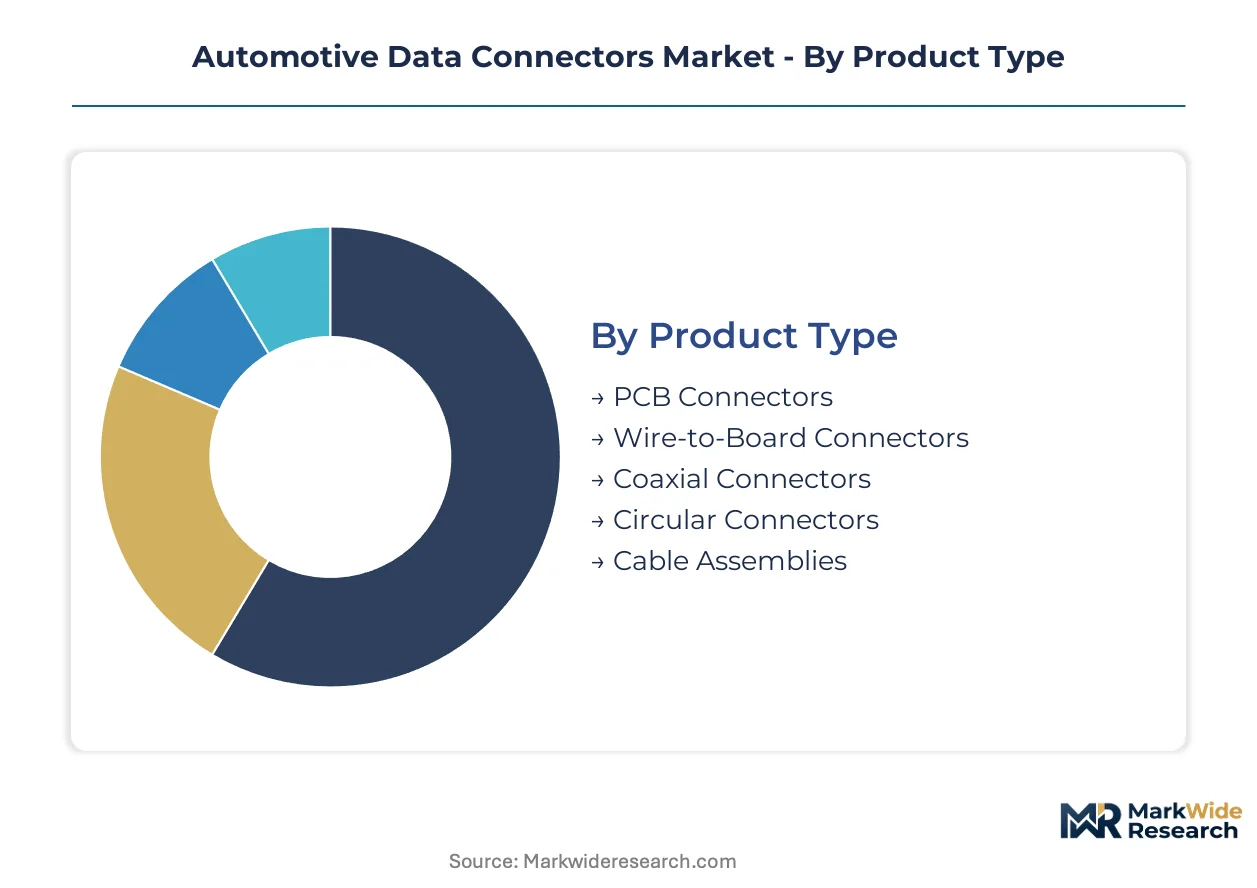
Automotive data connector specifications diverge sharply across vehicle subsystems, with replacement cycles spanning months for infotainment upgrades versus decades for chassis harnesses. Procurement teams calibrate inventory strategies around these velocity differentials, balancing obsolescence risk against qualification lead times.
Product Type:
PCB connectors turn over fastest with each infotainment module refresh, while circular connectors in battery systems endure full vehicle lifecycles without replacement.
- PCB Connectors:Surface-mount and through-hole configurations dominate infotainment module assembly with pitch densities down to 0.35mm. Demand clusters around Stuttgart and Wolfsburg manufacturing corridors where domain-centralized architectures are compressing connector counts per vehicle. NHTSA FMVSS requirements for automatic emergency braking are hardening specifications for vibration resistance per ISO 16750-3.
- Circular Connectors:Ruggedized metal-shell designs rated above 800V anchor battery management system interconnects across German and Chinese EV platforms. ASIL-D qualification per ISO 26262 extends development cycles by 18-24 months, freezing out unproven entrants from safety-critical sockets.
- Wire-to-Board Connectors:Traditional crimp-and-poke configurations persist in body electronics where cost minimization overrides performance density.
- Coaxial Connectors:Precision impedance-controlled interfaces command premium positioning in ADAS radar and camera links requiring shielding effectiveness above 60dB.
- Cable Assemblies:Pre-terminated harness segments reduce field installation labor for zonal architecture deployments.
Wire-to-board connectors dominate installed base volume. Circular connectors are where expansion concentrates.
Technology:
Cost tiers separate legacy protocol maintenance from next-generation backbone investments, with Ethernet commanding 3-5x premium over CAN bus equivalents.
- Ethernet:100BASE-T1 and 1000BASE-T1 standards displace legacy CAN bus for zonal architecture backbones, collapsing wiring harness complexity by eliminating protocol translation gateways. IEEE multi-gigabit specifications are opening procurement windows for shielded twisted-pair connectors in gateway modules serving German OEM assembly lines.
- Fiber Optic:Optical physical layers handle autonomous driving data loads for camera and lidar links where copper signal integrity degrades beyond 10 meters. Cleanroom assembly capex for Class 1000 termination environments fragments competitive positioning among mid-tier suppliers.
- CAN Bus:Established vehicle networks resist wholesale replacement due to backward compatibility requirements across 15-20 year vehicle lifecycles.
- USB:Consumer-electronics-derived protocols bridge passenger-facing charging and data ports with standardized connector footprints.
- LVDS:Low-voltage differential signaling persists in display link applications where transition to Ethernet is incomplete.
- HDMI:High-definition multimedia interfaces serve rear-seat entertainment systems with direct consumer electronics adaptation.
CAN Bus anchors legacy installed base. Ethernet is climbing the fastest as zonal architectures proliferate.
Application:
Customer type splits between safety-critical systems with ASIL-D mandates and convenience features with consumer-electronics refresh cycles.
- Advanced Driver Assistance Systems:Radar and camera modules require IP6K9K-rated interfaces with redundant locking mechanisms per NHTSA FMVSS testing protocols. Compliance burdens concentrate procurement authority among suppliers with pre-qualified ASIL-B through ASIL-D component portfolios.
- Infotainment Systems:Passenger-facing modules drive highest unit volume with shortest replacement cycles, pulling PCB connector demand through module assembly lines. Over-the-air update capabilities are creating demand for field-serviceable designs with modular pin configurations.
- Powertrain Control:Engine management and transmission control units demand temperature ratings from -40°C to 150°C with vibration resistance.
- Chassis Systems:Brake-by-wire and steer-by-wire architectures impose functional safety requirements matching ADAS stringency.
- Body Electronics:Door modules, lighting controls, and climate systems tolerate lower performance tiers with cost-optimized connector selections.
Body electronics dominates unit volume. Advanced Driver Assistance Systems represent the steepest expansion trajectory.
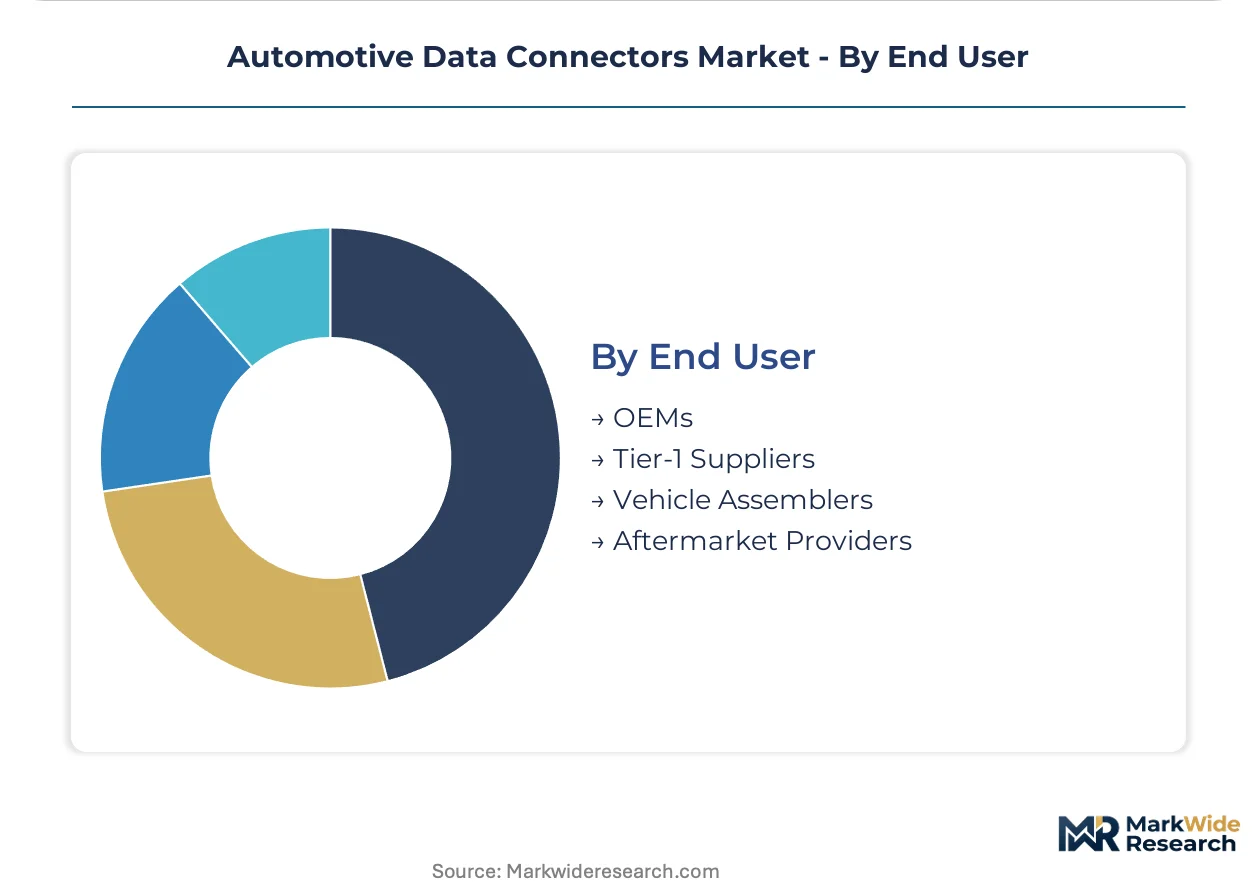
End User:
Supply concentration varies by tier, with OEMs direct-sourcing strategic interconnects while delegating commodity harnesses to vehicle assemblers.
- OEMs:Volkswagen, BMW, and Mercedes-Benz anchor procurement authority for high-speed data interfaces, specifying multi-gigabit Ethernet backbones across EV platforms. EU Cyber Resilience Act mandates are accelerating demand for encrypted connector platforms with tamper-evident sealing architectures.
- Tier-1 Suppliers:Continental, Bosch, and ZF Friedrichshafen consolidate multi-protocol interfaces into single miniaturized housings for domain controller integration.
- Vehicle Assemblers:Contract manufacturers execute harness installation with limited specification influence beyond labor cost optimization.
- Aftermarket Providers:Fleet operators favor field-replaceable connector modules over hard-wired repairs, compressing supplier qualification cycles for modular families with common housing platforms.
Vehicle assemblers dominate unit volume throughput. Tier-1 suppliers are where specification authority concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German connector exports flow disproportionately toward Chinese EV assembly lines, while Japanese manufacturers supply radar and camera link hardware to North American OEMs. This bilateral trade pattern concentrates specification authority in Stuttgart-Wolfsburg and Nagoya-Toyota City corridors.
United States
NHTSA's automatic emergency braking mandate is hardening connector specifications for radar and camera modules with IP6K9K-rated interfaces. The FMVSS testing protocols now require redundant locking mechanisms for safety-critical sensor chains. Detroit-Warren manufacturing clusters anchor procurement for zonal architecture deployments across domestic EV platforms.
Germany
EU Cyber Resilience Act mandates are accelerating demand for encrypted connector platforms with tamper-evident sealing architectures. KBA type-approval requirements extend qualification timelines for ASIL-D safety-critical sockets. Stuttgart and Wolfsburg corridors concentrate specification authority for multi-gigabit Ethernet backbones across Volkswagen, BMW, and Mercedes-Benz assembly lines.
China
Domestic EV platforms are pulling specialized interconnect demand through MIIT-mandated intelligent connected vehicle standards. GB/T protocol specifications for battery management systems require ruggedized circular connectors rated above 800V. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou anchor localization investments for high-speed data interfaces.
Japan
METI's automotive semiconductor strategy is channeling R&D subsidies toward fiber-optic backbone migration for autonomous driving data loads. JIS standards for vibration resistance per ISO 16750-3 constrain supplier qualification timelines. Nagoya-Toyota City and Kanto-Tokyo corridors concentrate tier-one integrator procurement for domain controller integration.
India
PLI scheme subsidies for domestic automotive electronics are attracting connector localization investments around Chennai and Pune industrial corridors. BIS certification requirements for high-voltage EV platforms are compressing supplier qualification cycles for modular connector families. Tamil Nadu and Maharashtra manufacturing clusters anchor field-serviceable designs with tool-free mating cycles.
Automotive Data Connectors Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated sensor-to-connector platforms, ruggedized high-voltage specialists, and fiber-optic backbone enablers. Strategic archetypes include full-spectrum electromechanical integrators, regional harness-scale manufacturers, and cleanroom-dependent optical termination specialists. Dominant competitive moves span backward integration into copper alloy smelting and strategic partnerships for IEEE 1000BASE-T1 standardization.
Within the integrated platform tier, TE Connectivity and Amphenol occupy positions as anchors for high-speed Ethernet deployment and ruggedized circular connector supply respectively. Yazaki Corporation exemplifies the traditional wire-to-board specialist archetype navigating optical transition requirements. These three entities collectively represent the spectrum from sensor-integrated platforms through legacy harness dominance toward fiber-optic backbone migration.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv |
| Amphenol |
| Yazaki Corporation |
| Molex |
| Sumitomo Electric Industries |
| Hirose Electric |
| Japan Aviation Electronics Industry |
| Rosenberger |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-Wolfsburg manufacturing corridors anchor European connector capacity, and their dominance in high-speed Ethernet qualification timelines translates directly into premium pricing power for ASIL-certified suppliers serving German OEM assembly lines. Raw material bottlenecks from Southeast Asian copper alloy smelters are compressing margin structures for mid-tier manufacturers unable to pass through input cost volatility.
Pricing Analysis
Next-generation 1000BASE-T1 Ethernet connectors command 3-5x premiums over legacy CAN bus equivalents, while fiber-optic interfaces for autonomous driving applications sit at the apex of the technology curve with cleanroom-assembly cost structures. Three-tier pricing stratification separates ASIL-D safety-certified premium sockets from standard industrial-grade connectors and economy wire-to-board configurations. Cost compression in mid-tier PCB connectors is intensifying because unproven entrants face 18-24 month ISO 26262 qualification barriers. Tier-1 integrators exhibit lowest price sensitivity for safety-critical ADAS modules, while vehicle assemblers drive hardest bargains on body electronics harnesses.
Supply Chain Analysis
High-performance copper alloys feed from Southeast Asian smelters, engineered thermoplastics hinge on German and Japanese specialty chemical producers, and precision stamping equipment centers on Swiss and Italian machine tool builders. Geographic supply concentration clusters in Germany for automotive-grade connector development, China for high-volume circular connector stamping, and Japan for fiber-optic termination equipment. Single-source vulnerability runs through Southeast Asian copper alloy supply given limited alternative qualified smelters for automotive conductivity specifications. Distribution runs through Tier-1 integrator consolidation points with OEM direct-sourcing for strategic high-speed data interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connector specification fragmentation creates multiple white-space entry points as zonal architectures splinter procurement authority across domain controllers, battery systems, and sensor chains. The shift toward software-defined vehicles with over-the-air update capabilities is fragmenting demand into field-serviceable modular designs distinct from traditional hard-wired harnesses.
For Market Incumbents: Harden ASIL-D certification portfolios against emerging fiber-optic specialists by deepening backward integration into copper alloy smelting and captive supply of engineered thermoplastics. Lock in long-term offtake agreements with Yangtze River Delta battery manufacturers before Chinese domestic suppliers achieve equivalent qualification timelines. Priority defensive moves center on pre-qualifying next-generation 1000BASE-T1 shielded twisted-pair platforms across Volkswagen, BMW, and Mercedes-Benz gateway module specifications. For New Entrants and Emerging Players: Pursue modular pin-configuration designs for Indian EV manufacturing corridors around Chennai and Pune where PLI scheme subsidies are compressing localization investment requirements. Target aftermarket fleet operator segments with tool-free mating cycle connectors that reduce field-service labor costs versus hard-wired harness repairs. Go-to-market angle should emphasize IEEE 1000BASE-T1 standardization partnerships with domestic Tier-1 integrators lacking high-speed signal integrity engineering talent. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cleanroom-dependent optical termination specialists with captive Class 1000 manufacturing infrastructure as autonomous driving data loads accelerate fiber-optic backbone migration. Long-term viability across the projection horizon rests on acquisition targets with pre-qualified IP6K9K-rated sealed designs for NHTSA FMVSS automatic emergency braking compliance. Signal to monitor: German KBA type-approval timeline compression for encrypted connector platforms with tamper-evident sealing architectures under EU Cyber Resilience Act implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Modular connector families sharing tooled components across economy and premium trim specifications reduce qualification burden for Tier-1 integrators. |
| Battery Supply Agreement | Long-term offtake contracts for 800V+ ruggedized circular connectors anchor capacity planning through German and Chinese EV assembly lines. |
| Software-Defined Vehicle Investment | Field-serviceable designs with over-the-air update compatibility capture procurement shifts in North American commercial vehicle manufacturing. |
| Geographic Manufacturing Footprint | Localization investments around Chennai and Pune industrial corridors access PLI scheme subsidies for domestic automotive electronics production. |
| Charging Infrastructure Partnership | High-voltage interconnect specifications for DC fast-charging networks extend connector portfolios beyond vehicle-integrated applications. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations heads, and fiber-optic termination equipment manufacturers and refined through secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, IEEE standardization committee disclosures, and customs trade data for copper alloy imports. Bottom-up connector unit demand modeling triangulated against top-down automotive electronics spend projections.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from S-curve technology adoption patterns for Ethernet displacement of CAN bus, overlaid with regulatory mandate timing for NHTSA automatic emergency braking and EU Cyber Resilience Act implementation.
Macroeconomic conditions sit as an overlay; deviation in copper alloy spot pricing, semiconductor capital expenditure cycles, or Chinese EV subsidy trajectories would shift the trajectory. Cross-checking against IHS Markit vehicle production forecasts and IEEE 802.3 standardization committee timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Mexico Connector Market
Connectors
Connector for PV System Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Japan Connector Market
Connectors
Filtered Connectors Market
Connectors
Telecom Mounting Hardware Market
Connectors
PCI-E Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
Latin America Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Canada Connector Market
Connectors
Circular Waterproof Connector Market
Connectors
Wire-To-Board Connector Market
Connectors
China Connector Market
Connectors
Circular Connectors Market
Connectors
SATA Connector Market