
 Cloud Gateway Module Market | 2026-2036
Cloud Gateway Module Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Gateway Module Market Analysis
Healthcare Institutions is reorganizing procurement priorities for cloud gateway modules, shifting investment toward encrypted, compliant data exchange infrastructure. Microsoft Corporation leverages its Azure Stack hybrid portfolio to anchor enterprise gateway deployments across regulated industries. Cisco Systems specializes in network-layer security integration, sustaining competitive position through hardware-software convergence at the edge. Huawei Technologies dominates in Asia-Pacific carrier markets, extending its integrated gateway footprint through telecom provider partnerships.
A cloud gateway module functions as an interconnection appliance or software layer that translates protocols, manages API traffic, and enforces security policies between on-premises systems and cloud environments, typically supporting throughput rates from 1 Gbps to 100 Gbps depending on deployment scale. Its primary purpose is to enable seamless, secure data flow across heterogeneous infrastructure while maintaining governance and latency control. Hardware Gateway configurations currently lead in telecom and large enterprise settings where dedicated appliances meet strict performance thresholds. Software Gateway deployments are expanding fastest among Cloud Service Providers seeking elastic, containerized edge connectivity. Integrated Gateway solutions concentrate margin pools where vendors bundle management, encryption, and virtualization into unified platforms.
The EU AI Act and GDPR impose strict data handling and auditability requirements that directly shape gateway module specifications for European deployments. In the United States, NIST cybersecurity frameworks and HIPAA compliance mandates drive healthcare and federal sector procurement toward modules with embedded encryption and access logging. China's GB standards and data localization rules under MIIT oversight require domestic gateway architectures with certified cryptographic modules. Stakeholders must evaluate regulatory divergence across jurisdictions when selecting gateway architectures, as compliance compatibility will determine market access and upgrade pathways.
Market Dynamics
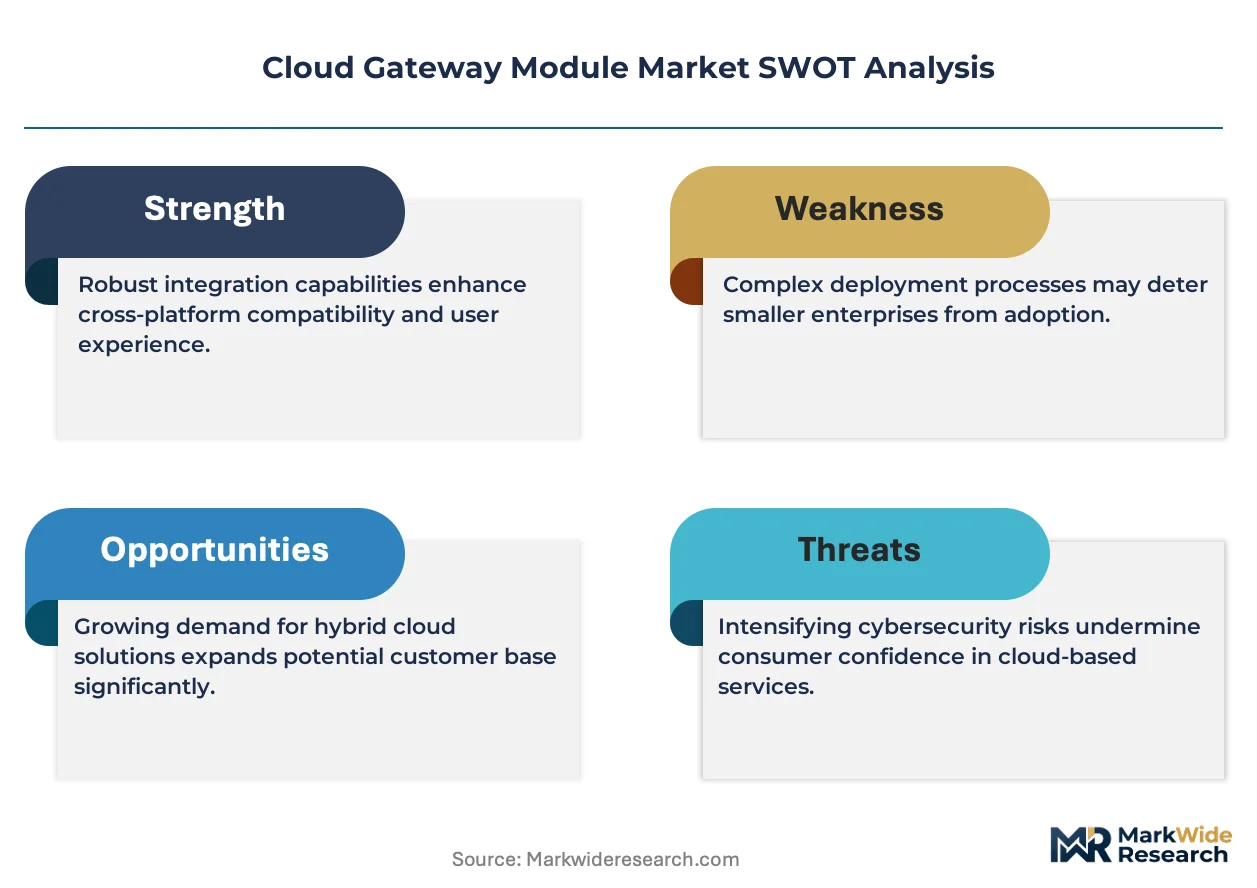
Encrypted data sovereignty mandates across Germany, France, and the United States are forcing healthcare and industrial buyers to re-architect gateway deployments around certified cryptographic modules rather than commodity connectivity.
Growth Catalysts
- GDPR and EU AI Act compliance:European healthcare institutions must deploy encrypted gateway architectures with full audit trails, accelerating replacement cycles for legacy appliances.
- Industrial cloud adoption in Germany:Manufacturing verticals require local data processing under strict sovereignty rules, driving module deployment at plant-floor edge locations.
- Containerized edge connectivity:Cloud service providers are standardizing software gateway stacks for elastic throughput scaling, displacing fixed-capacity hardware procurement.
Market Restraints
- Semiconductor supply concentration:Advanced encryption processors depend on Taiwan and South Korea foundry capacity, creating 12-18 month lead time volatility for high-throughput modules.
- Certification cost structure:Common Criteria and FIPS 140-3 validation cycles add 18-24 months to product launch timelines, compressing vendor R&D returns.
- Legacy protocol fragmentation:Industrial Modbus and proprietary SCADA systems resist standard API translation, limiting gateway deployment scope in brownfield manufacturing sites.
Strategic Opportunities
- Underpenetrated healthcare in India:Hospital digitization under the Ayushman Bharat Digital Mission creates demand for HIPAA-equivalent gateway infrastructure with localized data residency.
- 5G network slicing convergence:Telecom operators are bundling guaranteed-latency gateway modules with private cellular deployments for autonomous manufacturing.
- CSRD disclosure mandates:European enterprises must track data center energy and carbon metrics, creating attach revenue for gateway vendors with embedded telemetry.
Industry Challenges
- Embedded systems security engineering:Vendors face acute scarcity of firmware developers with side-channel attack mitigation expertise for cryptographic module design.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of FIPS 140-3, Common Criteria EAL4+, and China's OSCCA approvals fragments engineering resources and extends validation timelines.
- Brownfield integration complexity:Manufacturing customers demand seamless coexistence with 15-20 year-old control systems, forcing costly custom protocol adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Gateway Module Market |
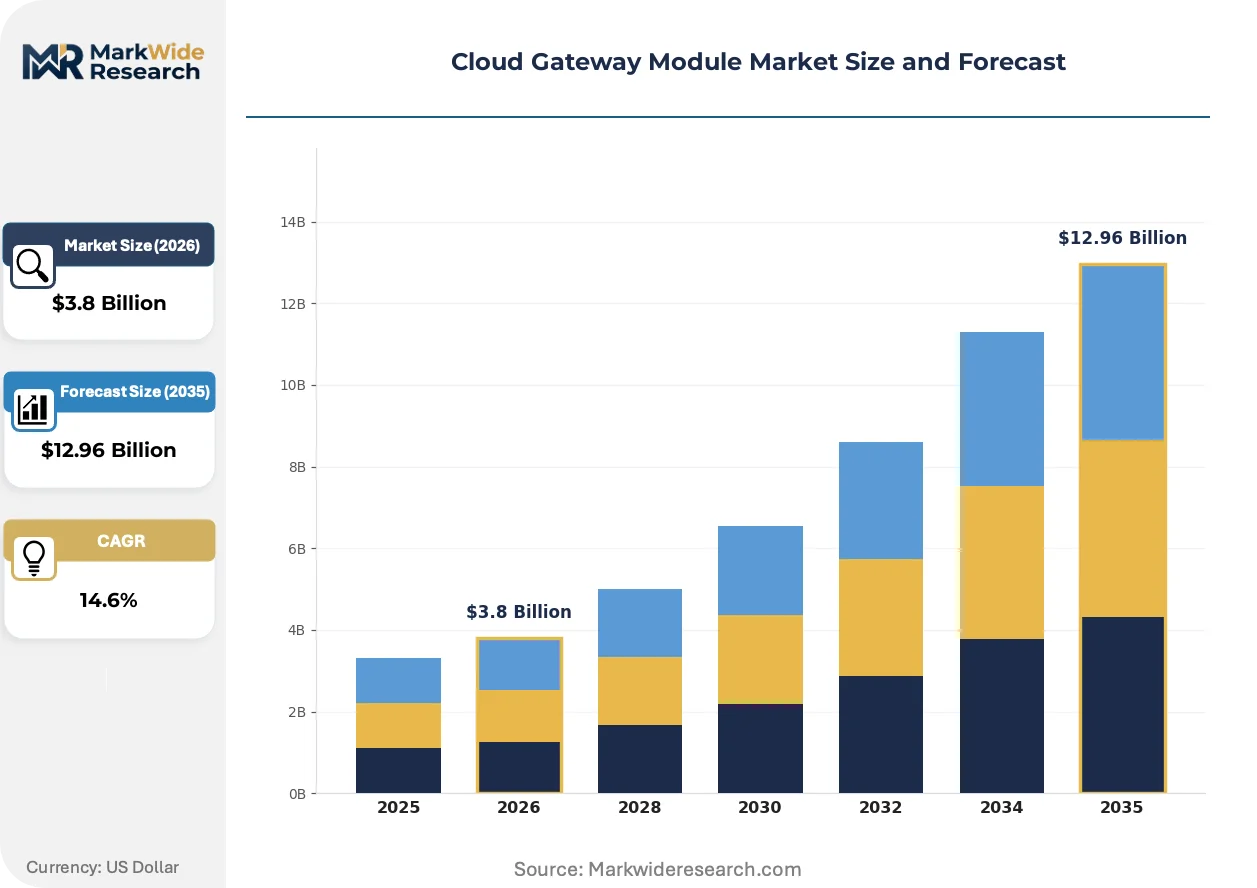
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Gateway, Hardware Gateway, Integrated Gateway, Network Gateway End User: IT Enterprises, Telecom Providers, Cloud Service Providers, Healthcare Institutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: API Management, Security Protocols, Data Encryption, Virtualization |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Oracle Corporation, NetApp, Dell EMC, Cisco Systems, Intel Corporation, Huawei Technologies, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Gateway Module Market Emerging Trajectories
Gateway architectures are fragmenting into specialized layers as buyers reject monolithic appliances in favor of composable, policy-driven connectivity stacks.
Software-defined perimeter technology is decomposing traditional hardware gateway functions into discrete microservices for authentication, encryption, and traffic management. Healthcare IT departments in the United States are piloting these disaggregated stacks to isolate patient data flows without forklift appliance upgrades. This decomposition compresses vendor lock-in and enables best-of-breed procurement for each security layer.
China's GB standards and MIIT data localization rules are mandating domestic cryptographic modules for all cross-border data transfers. Industrial manufacturers operating in Shanghai and Shenzhen must deploy certified gateway architectures with SM4 encryption, disqualifying standard international product SKUs. Local vendors with OSCCA certification are capturing deployment slots previously held by global suppliers.
Subscription-based gateway management is displacing perpetual license purchases among mid-market enterprises. Managed security service providers in Germany and France are bundling hardware, monitoring, and compliance reporting into fixed monthly fees, transferring capex risk from healthcare and manufacturing buyers. This shift concentrates purchasing authority with procurement departments rather than IT engineering teams.
Cloud Gateway Module Market Segmentation
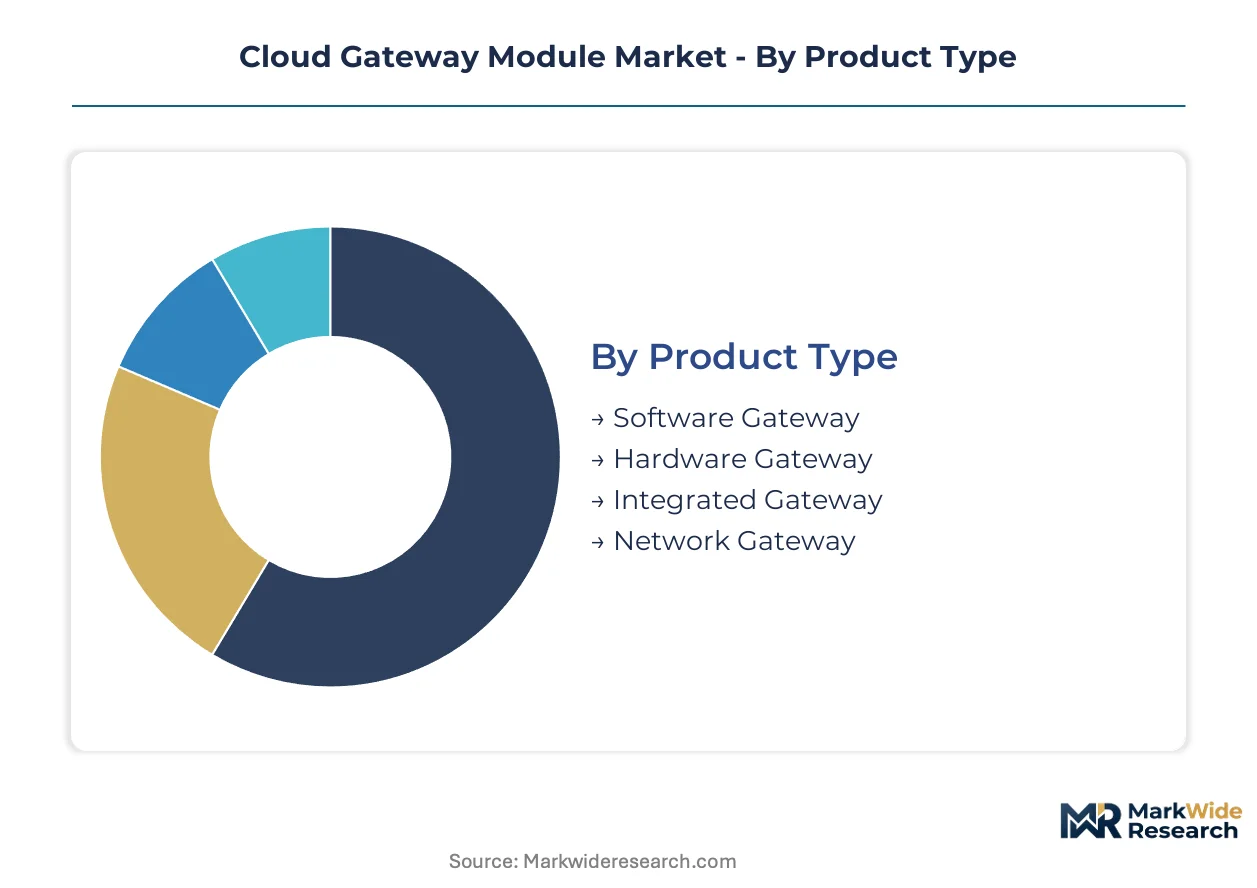
Cloud gateway module procurement splits sharply between regulated domestic deployments and export-oriented elastic infrastructure. Buyers in Germany and France prioritize certified hardware appliances for data sovereignty compliance. Cloud service providers across Asia-Pacific and North America favor software stacks for containerized scale-out.
Product Type:
Hardware Gateway shipments concentrate in European industrial corridors where GDPR and EU AI Act mandates require certified encryption appliances with documented supply chains. Software Gateway volumes flow primarily to North American and Asian cloud providers building multi-tenant edge platforms.
- Software Gateway:Containerized code stacks deploy on standard servers, enabling elastic throughput scaling from 1 Gbps to 100 Gbps without hardware swaps. Cloud service providers in the United States and India are standardizing these architectures for DevOps pipelines, displacing fixed-capacity procurement cycles.
- Hardware Gateway:Dedicated appliances with embedded cryptographic processors enforce strict latency and security thresholds for regulated workloads. Manufacturing plants in Germany and healthcare networks in France specify these units for air-gapped edge locations under BSI and ANSSI certification requirements.
- Integrated Gateway:Unified platforms bundling management, encryption, and virtualization layers for simplified procurement.
- Network Gateway:Protocol translation appliances optimized for carrier-grade telecom interconnects.
Hardware Gateway commands the established base. The steepest expansion runs through Software Gateway.
End User:
Telecom Providers and Cloud Service Providers drive export-facing volume with multi-tenant gateway deployments. Healthcare Institutions and IT Enterprises anchor domestic procurement around compliance-heavy single-tenant architectures.
- Healthcare Institutions:Hospital systems deploy patient-data gateways with HIPAA audit trails in the United States and GDPR-compliant encryption in Europe. Procurement in Germany is accelerating under the Digital Healthcare Act, which mandates interoperable health data exchange infrastructure.
- Cloud Service Providers:Hyperscalers and regional operators consume software-defined gateway stacks for elastic customer onboarding. Indian providers under the MeitY data localization framework are building domestic gateway capacity to retain sovereign data flows.
- IT Enterprises:Corporate IT departments managing hybrid workforce connectivity and legacy system integration.
- Telecom Providers:Carriers bundling gateway modules with private 5G network slices for manufacturing clients.
Cloud Service Providers capture volume leadership. Healthcare Institutions are climbing the fastest as regulatory deadlines force replacement cycles.
Deployment:
Private Cloud and Hybrid Cloud configurations dominate European procurement where data residency rules prohibit public cloud alternatives. Multi-Cloud adoption spreads fastest among North American enterprises avoiding vendor lock-in.
- Hybrid Cloud:Architectures split workloads between on-premises appliances and public cloud extensions, enabling gradual migration without forklift upgrades. German automotive suppliers favor this model for plant-floor data processing under strict BSI IT-Grundschutz requirements.
- Multi-Cloud:Gateway fabrics abstracting AWS, Azure, and Google Cloud APIs into unified control planes. Financial services firms in Singapore and the United States deploy these stacks to arbitrage cloud pricing and mitigate concentration risk.
- Public Cloud:Fully managed gateway services where cloud providers operate the underlying infrastructure.
- Private Cloud:Single-tenant deployments on customer-owned hardware for maximum isolation.
Hybrid Cloud retains the installed base. Multi-Cloud is gaining share fastest as enterprise procurement prioritizes portability.
Technology:
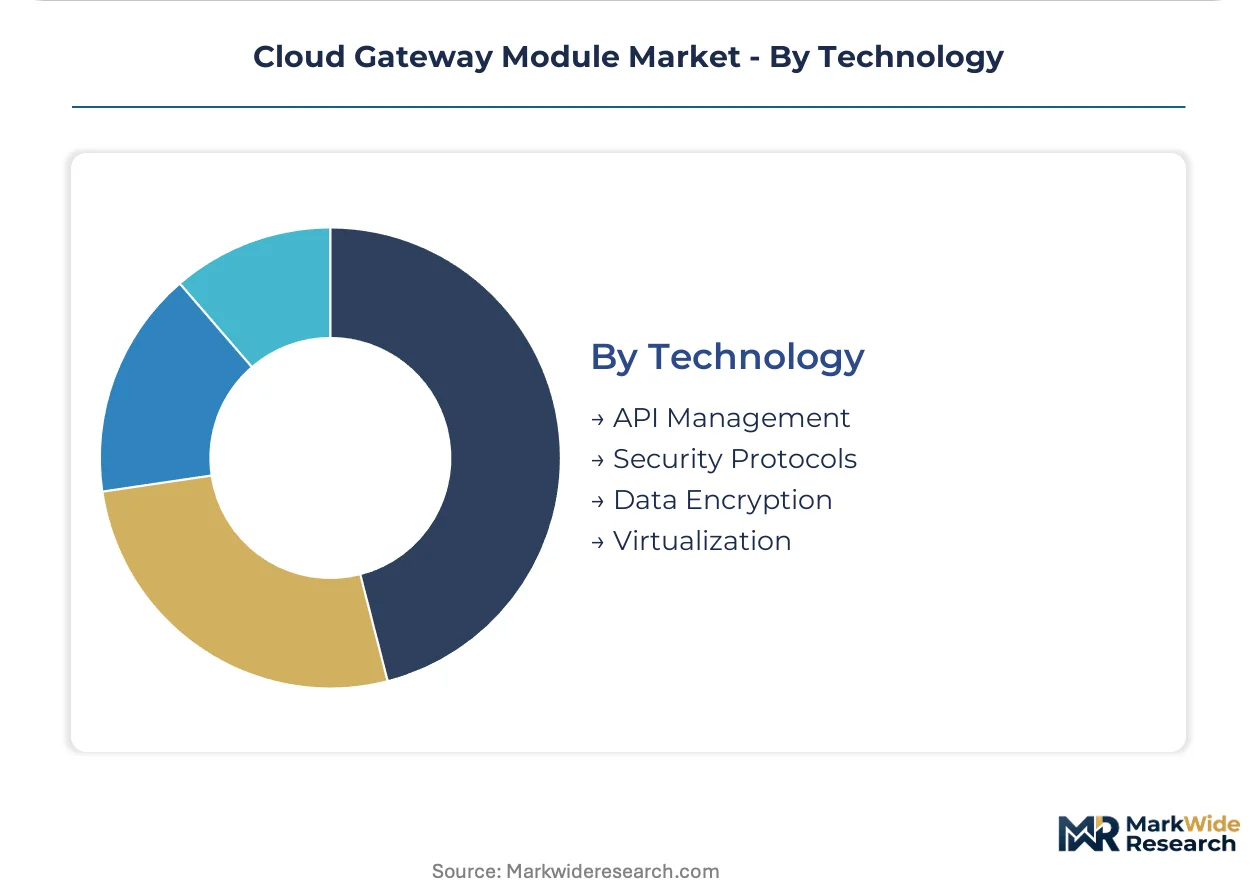
Security Protocols and Data Encryption concentrate margin in European and Chinese markets with mandatory certification regimes. API Management and Virtualization scale more broadly across price-sensitive global deployments.
- Data Encryption:Hardware security modules and software cryptographic layers protecting data in transit and at rest. China's MIIT requires SM4-certified modules for all cross-border transfers, creating captive demand for OSCCA-approved gateway architectures in Shanghai and Shenzhen.
- API Management:Traffic routing, rate limiting, and protocol translation services for microservices interconnect. Indian IT enterprises under the Digital India initiative are deploying these layers to modernize legacy government system integrations.
- Security Protocols:TLS, IPsec, and zero-trust policy enforcement engines.
- Virtualization:Hypervisor-based gateway isolation for multi-tenant resource sharing.
Data Encryption commands premium positioning. API Management is expanding most quickly as application modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports encrypted gateway hardware to healthcare networks across France and the Netherlands, while Chinese manufacturers supply OSCCA-certified modules to domestic industrial clusters under MIIT localization mandates.
United States
Hospital systems and federal agencies drive procurement of FIPS 140-3 validated gateway appliances with embedded audit logging. HIPAA compliance deadlines force replacement of legacy connectivity infrastructure in Texas medical centers. Cloud service providers in Northern Virginia data center corridors consume software-defined gateway stacks for elastic multi-tenant deployments.
Germany
Automotive suppliers and pharmaceutical manufacturers require BSI IT-Grundschutz certified hardware for plant-floor edge processing. The EU AI Act and GDPR impose strict data sovereignty rules on cross-border patient data flows. Industrial gateway deployment concentrates in Baden-Württemberg manufacturing corridors around Stuttgart.
China
MIIT data localization rules mandate SM4 cryptographic modules for all cross-border industrial data transfers. GB standards certification creates captive demand for domestic gateway architectures in Shanghai and Shenzhen electronics manufacturing zones. State-owned telecom operators bundle certified gateway modules with private 5G network slices.
India
Hospital digitization under the Ayushman Bharat Digital Mission creates demand for HIPAA-equivalent gateway infrastructure with localized data residency. MeitY data localization frameworks require domestic cloud providers to build sovereign gateway capacity. IT enterprises in Bangalore deploy API management layers to modernize legacy government system integrations.
France
Healthcare networks procure ANSSI-certified encrypted gateways for patient data exchange under strict GDPR enforcement. The CSRD disclosure mandate creates attach revenue for vendors with embedded carbon telemetry in data center gateway deployments. Pharmaceutical manufacturing clusters around Lyon specify certified appliances for air-gapped production environments.
Cloud Gateway Module Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with hybrid cloud portfolios, creating a tiered structure where network specialists and cloud-native platforms occupy distinct competitive layers. Strategic archetypes include hyperscale cloud providers bundling gateway services with infrastructure platforms, telecom-integrated hardware vendors leveraging carrier relationships, and cybersecurity-focused specialists emphasizing encryption certification stacks. Dominant competitive moves center on strategic partnerships with regulated industry verticals and portfolio diversification into subscription-based managed gateway services.
Among diversified technology conglomerates, Microsoft Corporation and Cisco Systems occupy positions anchoring enterprise gateway deployments across regulated industries. Microsoft exemplifies the hybrid cloud archetype through Azure Stack portfolio integration, while Cisco represents network-layer security convergence at the edge. Amazon Web Services sits within the hyperscale cloud provider tier, standardizing software-defined gateway stacks for elastic customer onboarding.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Oracle Corporation |
| NetApp |
| Dell EMC |
| Cisco Systems |
| Intel Corporation |
| Huawei Technologies |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-month lead times for FIPS 140-3 encryption processors concentrate pricing power with Taiwanese and South Korean foundry operators, forcing healthcare and industrial buyers to absorb premium surcharges for certified hardware while software gateway vendors exploit containerized elasticity to compress margins at the mid-market tier.
Pricing Analysis
Next-generation 100 Gbps hardware appliances command 40-60% premiums over prior-generation 10 Gbps units, while current-generation 40 Gbps configurations anchor the volume tier. Three-tier pricing structure across premium certified hardware, standard enterprise appliances, and economy software subscriptions stratifies procurement across regulated and price-sensitive segments. Pricing pressure stems from hyperscaler software stacks displacing fixed-capacity hardware procurement among cloud service providers. Healthcare institutions in Germany and France exhibit lowest price sensitivity due to BSI and ANSSI compliance mandates, while Indian hospital systems under Ayushman Bharat demonstrate acute price responsiveness.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for cryptographic processor shipments from Taiwan and South Korea. Hardware gateway production draws from concentrated semiconductor fabrication in Taiwan, advanced packaging in South Korea, and final assembly in China and Mexico. Single-source vulnerability around TSMC's 7nm encryption chip capacity creates disruption exposure for FIPS-validated module supply. Distribution runs through direct enterprise sales for regulated verticals and managed security service provider channels for subscription-based deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive suppliers and French hospital networks through multi-year framework agreements, fragmenting procurement authority away from decentralized IT departments toward centralized compliance and sourcing functions.
For Market Incumbents: Fortify certification moats by accelerating Common Criteria EAL4+ and China's OSCCA approval timelines before emerging Asian chip vendors achieve cryptographic module parity. Prioritize backward integration into encryption processor design to reduce Taiwan foundry dependency and capture margin pools currently flowing to semiconductor subcontractors.
For New Entrants and Emerging Players: Anchor in India's underpenetrated hospital digitization wave under Ayushman Bharat, where HIPAA-equivalent gateway infrastructure demand outpaces certified vendor supply. Target software-defined perimeter stacks for mid-market IT enterprises in Bangalore and Hyderabad seeking containerized alternatives to legacy appliance upgrades.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates seeking to divest non-core gateway hardware units amid portfolio rationalization toward cloud-native software. Monitor 5G network slicing deployment velocity among European telecom operators as inflection signal for private cellular gateway module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Program | Compresses FIPS 140-3 validation cycles to capture GDPR-driven replacement demand in German healthcare networks. |
| Backward Integration into Encryption Silicon | Reduces Taiwan foundry dependency and captures margin pools from cryptographic processor supply. |
| Managed Security Service Bundling | Transfers capex risk from French hospital procurement departments to vendor balance sheets via subscription models. |
| OSCCA Certification Pursuit | Unlocks captive demand in Shanghai and Shenzhen manufacturing zones under MIIT data localization mandates. |
| 5G Network Slicing Partnership | Positions gateway modules within private cellular deployments for autonomous manufacturing in Baden-Württemberg corridors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cloud gateway procurement officers, hospital IT directors, telecom infrastructure planners, and manufacturing automation engineers; and secondary validation against SEC filings from hyperscaler cloud providers, EU medical device regulatory databases, and customs records for encryption hardware trade flows. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across deployment models and certification tiers.
Across the analysis window, the forecasting framework modeled volume and value trajectories through product type segmentation (hardware, software, integrated), end-user verticals (healthcare, cloud service providers, telecom, manufacturing), deployment architecture (hybrid, multi-cloud, private), and regional regulatory clusters (EU AI Act/GDPR, HIPAA, MIIT localization). CAGRs derived from elasticity-adjusted adoption curves incorporating compliance deadline impacts and technology substitution dynamics. Industry-specific inputs included semiconductor foundry capacity utilization, Common Criteria certification pipeline backlogs, and 5G private network deployment schedules.
Material uncertainties — foundry capacity disruptions, regulatory timeline accelerations or delays, and protocol standardization outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification completion rates and enterprise cloud migration velocities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Network Switches Market
Network Technology
US Private 5G Network Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Small Cell Networks Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Global Routing Market
Network Technology
Protocol Analyzer Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Unified Network Management Market
Network Technology
Europe SD-WAN Market
Network Technology
Asia Pacific Structured Cabling Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Router and Switch Market