
 Microencapsulated Oil Market | 2026-2036
Microencapsulated Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Oil Market Analytics
Direct-to-nutraceutical-manufacturer channels is reconfiguring how microencapsulated oils reach end-formulators, bypassing traditional ingredient traders. BASF SE leverages its pharmaceutical-grade encapsulation infrastructure to anchor European supply. Koninklijke DSM N.V. sustains global reach through its prebiotic-lipid hybrid platforms. Stepan Specialty Products LLC specializes in surfactant-stabilized delivery systems for North American beverage applications.
Microencapsulated oil comprises lipid cores—typically polyunsaturated fatty acids from marine or botanical sources—sheathed within wall materials such as modified starches, gums, or proteins through spray-drying or coacervation, yielding particles between 1 and 1000 micrometers that shield oxidation-prone actives from oxygen, heat, and gastric degradation. The dietary supplements application dominates current volume as consumers prioritize cardiovascular and cognitive health positioning, while the beverages segment accelerates fastest where cold-chain-stable omega-3 fortification resolves long-standing taste and shelf-life barriers. Fish oil retains the largest product-type share due to established EPA/DHA clinical validation, though flaxseed oil gains traction among plant-forward formulation pipelines.
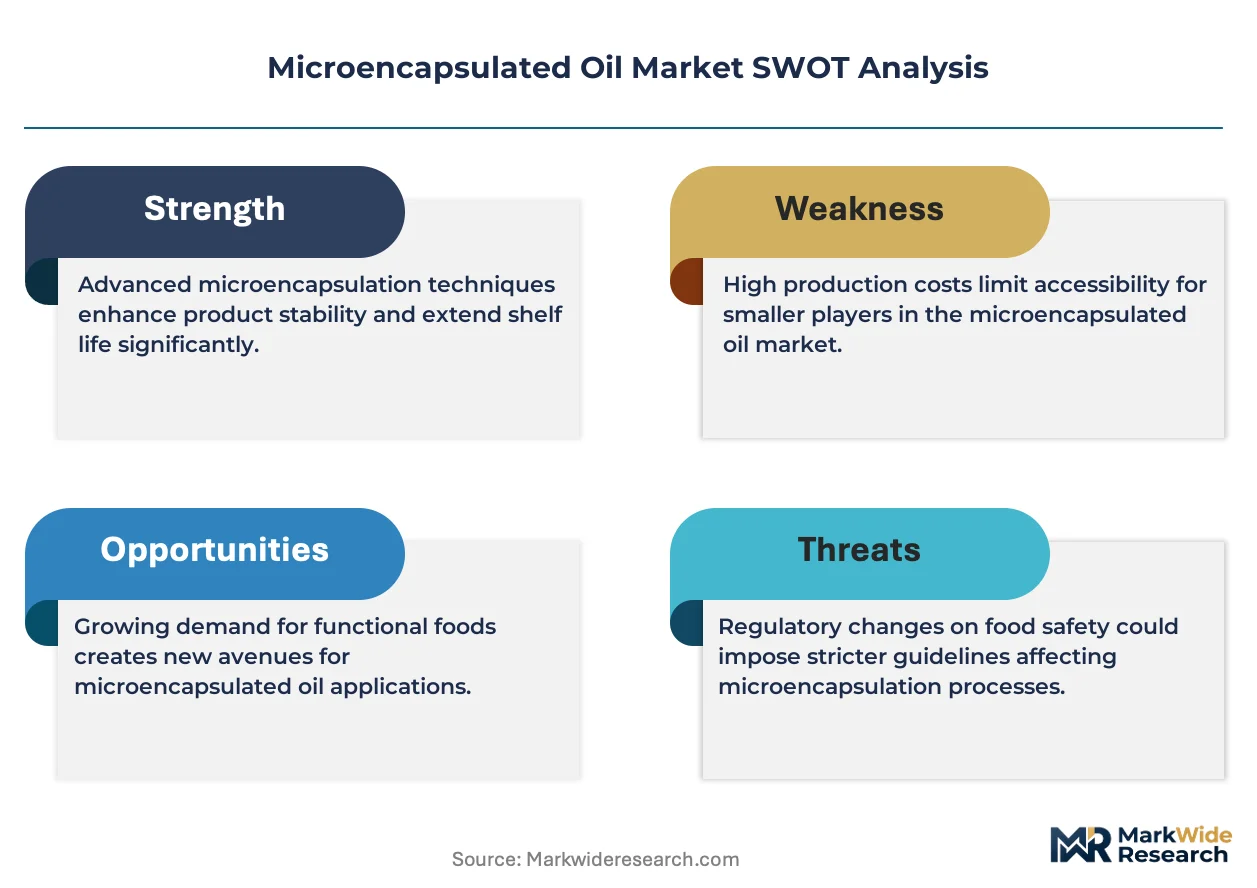
EFSA novel food assessments and Japan's Consumer Affairs Agency Foods with Function Claims notification system shape product entry pathways and substantiation requirements across two major demand poles. REACH compliance for wall-material chemistries and FDA GRAS self-affirmation protocols further constrain formulation flexibility for suppliers targeting European and United States markets. Stakeholders must monitor evolving nanomaterial classification debates, as particle-size thresholds in emerging regulatory frameworks could reclassify certain microencapsulation formats and trigger additional safety-data obligations.
Market Dynamics
Regulatory substantiation requirements from EFSA and Japan's Consumer Affairs Agency are compressing product development timelines while simultaneously validating premium positioning for bioactive oil formats, forcing suppliers to front-load clinical investment before market entry.
Growth Catalysts
- EFSA Article 13 Health Claims:Validated cardiovascular and cognitive benefit statements enable premium pricing for omega-3 fortified finished goods in European retail channels.
- Cold-chain-stable beverage fortification:Microencapsulation resolves taste masking and oxidation barriers that previously blocked omega-3 inclusion in ambient-distributed functional drinks.
- Japan Foods with Function Claims:The notification system accelerates time-to-market for encapsulated EPA/DHA products versus full FOSHU approval, stimulating domestic nutraceutical innovation.
Market Restraints
- Marine oil input volatility:Fish oil supply concentrates in Peruvian and Chilean anchovy fisheries, exposing processors to El Niño-driven catch fluctuations and price spikes.
- REACH wall-material compliance:Modified starches and gum acacia derivatives face evolving registration requirements that extend qualification timelines for European supply.
- Plant oil oxidation kinetics:Flaxseed and algae lipid cores exhibit inferior shelf-life stability versus refined fish oil, limiting substitution in long-dated retail SKUs.
Strategic Opportunities
- Sports nutrition expansion:Recovery-positioned protein powders and RTD shakes in North America represent underpenetrated vectors for branched-chain fatty acid microencapsulation.
- Infant formula fortification:DHA encapsulation for powdered and liquid formats addresses formulation heat-stability requirements in Chinese and Southeast Asian markets.
- Prebiotic-lipid hybrid platforms:Convergence of resistant starch wall materials with omega-3 cores enables dual-function positioning for gut-brain axis marketing claims.
Industry Challenges
- Encapsulation chemist scarcity:Formulation expertise spanning emulsion science, spray-drying optimization, and regulatory dossier preparation concentrates in fewer than twenty specialist firms globally.
- Scale-up validation timelines:Pilot-to-commercial transitions for coacervation processes require 18-24 month stability studies that delay revenue recognition and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Oil Market |
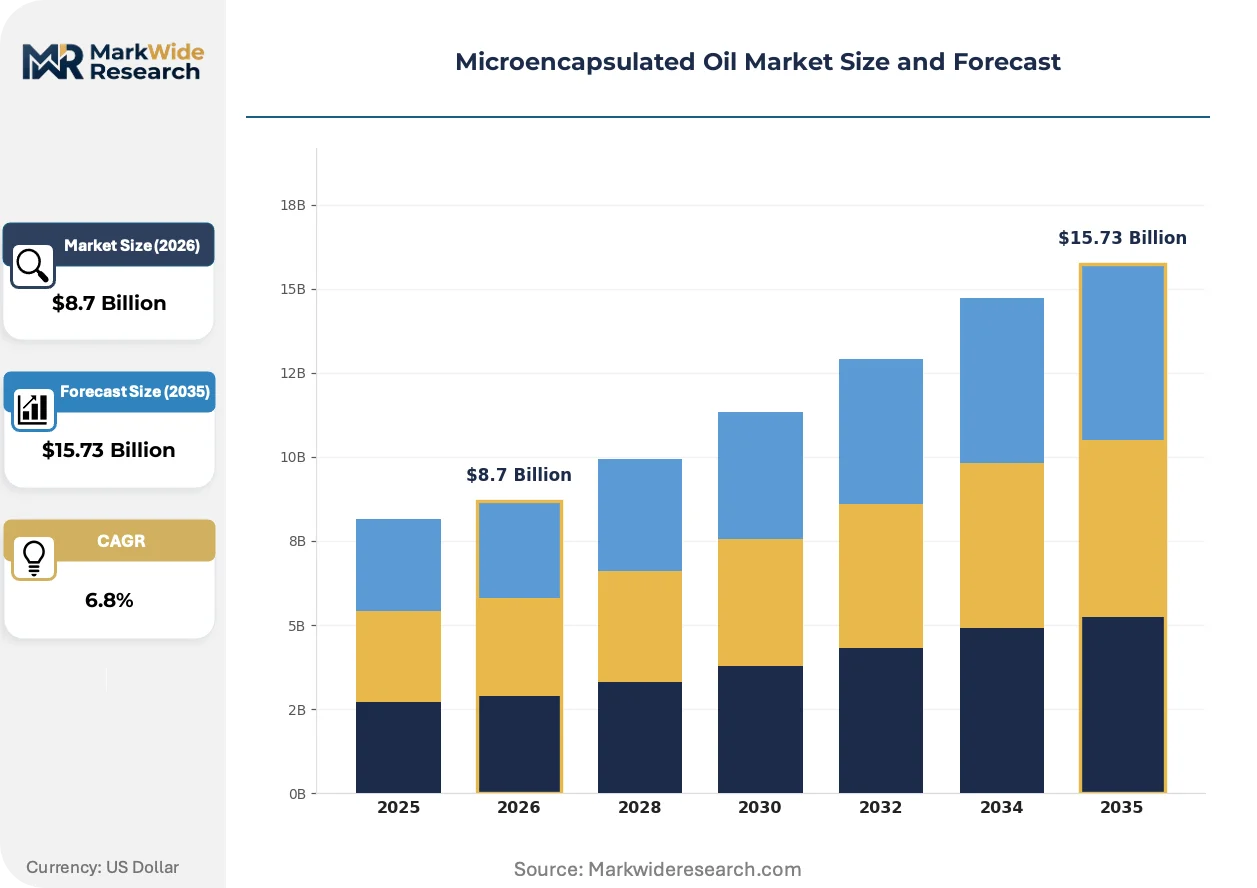
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Coconut Oil, Flaxseed Oil, Olive Oil End User: Food Industry, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Beverages, Bakery Products, Dietary Supplements, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Clover Corporation Limited, Stepan Specialty Products LLC, The Wright Group, Koninklijke DSM N.V., BASF SE, Microbelcaps, PR LABS, Nordic Naturals, Inc., Arjuna Natural Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Oil Market Evolving Landscape
Encapsulation technology is converging with precision fermentation and advanced drying methods to expand bioactive oil applications beyond traditional supplement formats into mainstream food matrices.
Complex coacervation using gelatin-gum arabic or pea protein-polysaccharide complexes is hybridizing with electrospinning and electrospraying techniques to produce sub-50-micrometer particles with tunable release profiles. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these hybrid systems to serve pharmaceutical clients seeking enteric-targeted delivery. The technology is compressing the performance gap between food-grade and pharmaceutical-grade encapsulation, enabling dual-use production lines.
REACH nanomaterial classification debates are forcing suppliers to document particle-size distributions with greater granularity, particularly for sub-100-nanometer fractions that may trigger novel substance obligations. ECHA guidance on cross-linked starch derivatives is creating compliance uncertainty for spray-dried formulations using modified maize starches. European suppliers are responding by qualifying alternative wall materials and investing in laser diffraction characterization capabilities to preempt regulatory reclassification.
Direct technical engagement between encapsulation houses and finished-product formulators is displacing traditional ingredient distribution intermediaries in North American and European supply chains. BASF SE and Koninklijke DSM N.V. now field application scientists at customer R&D facilities to co-develop bespoke particle specifications. This channel compression is most visible in the beverages segment, where taste and stability requirements demand iterative formulation collaboration rather than off-the-shelf ingredient procurement.
Microencapsulated Oil Market Segmentation
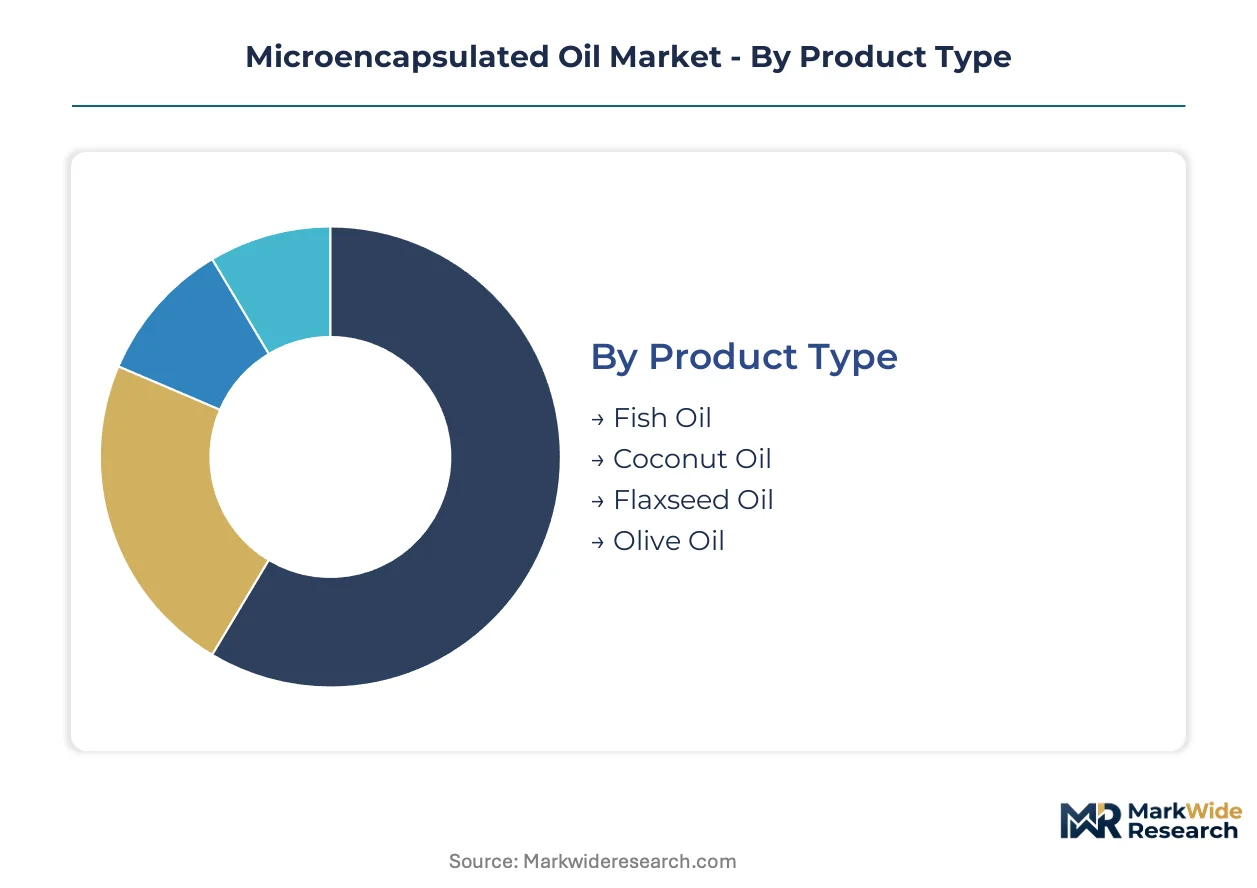
Segmentation in microencapsulated oils separates supply structures by lipid chemistry, end-use technical requirements, and channel economics. Each dimension carries distinct formulation specifications, regulatory pathways, and margin profiles that determine supplier positioning.
Product Type:
Cost tier differentiation across lipid feedstocks drives raw material procurement strategies and encapsulation complexity.
- Fish Oil:Marine-derived EPA/DHA concentrates remain the reference standard for clinical substantiation. Demand concentrates in German and Japanese nutraceutical manufacturing where EFSA Article 13 claims and Foods with Function Claims notifications validate premium positioning. El Niño-driven Peruvian anchovy catch volatility compresses margin predictability for processors.
- Flaxseed Oil:Botanical ALA sources serve plant-forward formulation pipelines with modified starch wall systems. European beverage fortification in France and Netherlands accelerates uptake as clean-label positioning overrides oxidation-stability concerns in short-dated SKUs.
- Coconut Oil:Medium-chain triglyceride cores target sports nutrition applications with rapid gastric release profiles.
- Olive Oil:Polyphenol-retentive encapsulation serves Mediterranean diet-positioned supplements in Italian and Spanish retail channels.
Fish oil holds installed capacity. Flaxseed oil is rotating up the share rankings.
End User:
Application maturity determines technical service intensity and regulatory dossier requirements.
- Nutraceuticals:Dietary supplement manufacturers specify enteric-release particles with validated bioaccessibility data. German contract manufacturers and Japanese functional food houses drive specification intensity through direct technical collaboration with encapsulation suppliers.
- Food Industry:Beverage and bakery formulators prioritize cold-chain stability and taste masking over gastric targeting. North American RTD protein platforms and European ambient juice fortification represent the steepest expansion trajectory for omega-3 inclusion.
- Pharmaceuticals:Prescription-grade EPA/DHA requires pharmaceutical excipient compliance and batch-level documentation.
- Cosmetics:Topical delivery systems emphasize oxidative stability in emulsion matrices over oral bioavailability.
Nutraceuticals holds installed capacity. Food Industry is rotating up the share rankings.
Application:
Volume concentration and margin structure diverge sharply between established supplement formats and emerging food matrices.
- Dietary Supplements:Softgel and powder formats dominate current revenue with established specification templates and validated stability protocols. Japanese and German manufacturers anchor demand through health claims substantiation requirements.
- Beverages:Ambient-distributed functional drinks represent the most technically demanding application, requiring sub-50-micrometer particles with complete taste occlusion. French and US beverage houses are expanding fastest as cold-chain-stable encapsulation resolves long-standing formulation barriers.
- Bakery Products:Heat-stable wall materials enable omega-3 inclusion in baked goods with extended shelf-life requirements.
- Personal Care:Cosmetic emulsions utilize microencapsulated oils for controlled release and oxidation protection in topical formulations.
Dietary Supplements holds installed capacity. Beverages is rotating up the share rankings.
Distribution Channel:
Channel configuration determines customer intimacy requirements and working capital intensity.
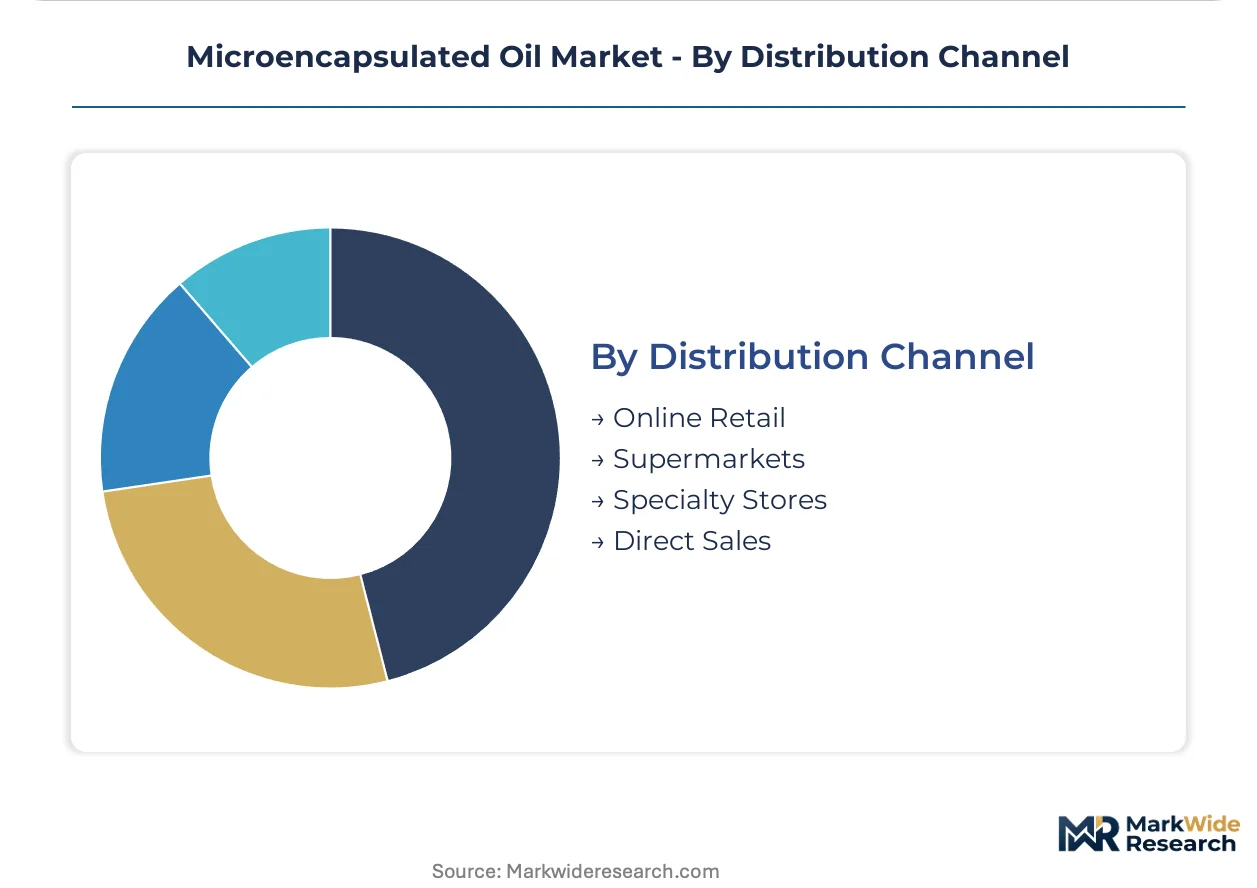
- Direct Sales:Technical engagement between encapsulation houses and finished-product formulators is displacing traditional ingredient traders. BASF SE and DSM field application scientists at customer R&D facilities to co-develop bespoke particle specifications, compressing iteration cycles for beverage and supplement clients.
- Online Retail:E-commerce platforms serve small-batch nutraceutical startups with standardized particle specifications and reduced minimum order quantities. German and US direct-to-consumer supplement brands accelerate procurement velocity through digital channels.
- Supermarkets:Mass retail distribution concentrates in private-label supplement lines with simplified specification requirements.
- Specialty Stores:Premium health food retailers stock practitioner-grade encapsulated oils with enhanced bioavailability claims.
Direct Sales holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European omega-3 distribution, while Japan's Kobe pharmaceutical corridor anchors Asia-Pacific encapsulation capacity. These logistics assets determine regional sourcing patterns for marine lipid processors.
Germany
EFSA Article 13 health claims validation drives demand from Frankfurt and Munich nutraceutical contract manufacturers. REACH compliance for modified starch wall materials extends qualification timelines for encapsulation houses serving the European market. The Baden-Württemberg cluster hosts application scientists co-developing bespoke particle specifications with beverage formulators.
United States
FDA GRAS self-affirmation protocols govern EPA/DHA ingredient entry for Chicago and New York functional food houses. Cold-chain-stable omega-3 fortification accelerates in RTD protein platforms distributed through ambient retail channels. California's sports nutrition manufacturers in Orange County drive specification intensity for branched-chain fatty acid encapsulation.
Japan
The Consumer Affairs Agency Foods with Function Claims notification system compresses time-to-market versus full FOSHU approval for Tokyo and Osaka functional food developers. METI standards guide encapsulation quality benchmarks for infant formula DHA fortification. The Kansai pharmaceutical corridor concentrates spray-drying capacity for enteric-targeted delivery systems.
France
ANSM oversight intersects with EFSA novel food assessments for Paris and Lyon beverage fortification projects. Clean-label positioning in ambient juice applications accelerates flaxseed oil uptake with modified starch wall systems. The Provence-Alpes-Côte d'Azur cluster houses prebiotic-lipid hybrid platform development for gut-brain axis claims.
Netherlands
Amsterdam's ingredient trading infrastructure supports direct technical engagement between encapsulation suppliers and finished-product formulators. ECHA guidance on cross-linked starch derivatives creates compliance uncertainty for modified maize starch formulations. The Randstad region concentrates laser diffraction characterization capabilities to document sub-100-nanometer particle fractions.
Microencapsulated Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation science and regulatory dossier capabilities. The supplier base concentrates among fewer than twenty specialist firms globally, with pharmaceutical-grade encapsulation infrastructure separating premium-positioned players from commodity processors. Two strategic archetypes dominate: diversified chemical conglomerates leveraging existing excipient manufacturing networks, and pure-play nutraceutical houses built around spray-drying and coacervation expertise. Competitive moves center on direct technical engagement displacing traditional ingredient traders, and pilot-to-commercial scale-up investments compressing 18-24 month stability validation timelines.
Within the diversified chemical tier, BASF SE and Koninklijke DSM N.V. represent platform integrators with pharmaceutical-grade encapsulation infrastructure spanning European and Asian supply corridors. Stepan Specialty Products LLC exemplifies the North American specialist archetype, with surfactant-stabilized delivery system expertise concentrated in beverage applications. Clover Corporation Limited occupies a position among Asia-Pacific encapsulation houses serving infant formula fortification requirements in Chinese and Southeast Asian markets.
| Leading Market Players |
|---|
| Clover Corporation Limited |
| Stepan Specialty Products LLC |
| The Wright Group |
| Koninklijke DSM N.V. |
| BASF SE |
| Microbelcaps |
| PR LABS |
| Nordic Naturals, Inc. |
| Arjuna Natural Ltd. |
| Others |
Value Network & Pricing Analysis
Undercapacity in European spray-drying infrastructure is compressing lead times for modified starch wall systems and tilting negotiation power toward encapsulation houses serving EFSA-compliant nutraceutical manufacturers. This utilization squeeze propagates through contract pricing for German and Japanese functional food developers, who now face minimum order quantity escalations and reduced spot-market flexibility.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical-grade, food-grade, and feed-grade encapsulation tiers, with EPA/DHA concentration levels and enteric-release certification driving spreads between adjacent brackets. Pricing pressure intensifies in the standard food-grade band as Peruvian anchovy supply volatility feeds raw material cost uncertainty into processor quotations. Small-batch nutraceutical startups exhibit highest price sensitivity due to working capital constraints, while infant formula manufacturers absorb premiums for heat-stability validated particles.
Supply Chain Analysis
Export-control regime scrutiny on spray-drying equipment with sub-50-micrometer capability constrains technology transfer to emerging encapsulation houses in Southeast Asia. Marine lipid supply concentrates in Peru, Chile, and Norway, while modified starch wall materials draw from maize processing clusters in the United States and Thailand. Single-source vulnerability in Peruvian anchovy fisheries exposes processors to El Niño-driven catch disruptions. Distribution runs through direct technical engagement channels displacing traditional ingredient traders in North American and European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as beverage fortification demand splinters specification requirements beyond the capacity of commoditized encapsulation processors, creating niches for specialists with coacervation expertise and regulatory dossier capabilities.
For Market Incumbents: Build regulatory dossier moats by pre-qualifying alternative wall materials ahead of ECHA nanomaterial reclassification debates. BASF SE and Koninklijke DSM N.V. should accelerate pilot-to-commercial scale-up investments to compress 18-24 month stability validation timelines that strain working capital for smaller competitors. Channel control through embedded application scientists at customer R&D facilities defends against ingredient trader displacement. For New Entrants and Emerging Players: Southeast Asian infant formula fortification represents the most penetrable geography, with Chinese and Vietnamese powder manufacturers seeking DHA encapsulation partners outside established Japanese supply corridors. Sports nutrition applications in North American RTD protein platforms offer a second white-space target with lower regulatory entry barriers than pharmaceutical-grade segments. A co-development go-to-market angle with regional contract manufacturers accelerates specification validation without captive infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across spray-drying capacity expansions as REACH compliance documentation and laser diffraction characterization capabilities become mandatory cost layers. Acquisition targets should screen for prebiotic-lipid hybrid platform pipelines and existing Foods with Function Claims notification experience in Japan. The signal to watch is EFSA novel food assessment backlog length, which indicates regulatory capacity constraints that could throttle premium-tier supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marine Lipid Supply | Captive anchovy procurement from Peruvian fisheries insulates processors from El Niño price spikes. |
| Prebiotic-Lipid Hybrid Platform Development | Resistant starch wall systems with omega-3 cores enable dual-function gut-brain axis positioning. |
| Direct Technical Engagement Channel Buildout | Embedded application scientists at beverage formulator R&D facilities compress iteration cycles. |
| Alternative Wall Material Qualification | Pea protein-polysaccharide complexes preempt ECHA reclassification risk for modified maize starches. |
| Infant Formula Heat-Stability Certification | METI-validated DHA encapsulation opens Chinese and Southeast Asian powdered format markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food registers, Japanese Consumer Affairs Agency Foods with Function Claims notifications, and REACH registration dossiers. Encapsulation technology directors, regulatory affairs leads at nutraceutical contract manufacturers, and procurement officers at German beverage houses provided operational validation. Trade data from European and Asian customs authorities, SEC filings from diversified chemical conglomerates, and spray-drying equipment import records supplied quantitative anchors. Bottom-up volume estimates triangulated against top-down value projections.
Forecast inputs incorporate lipid feedstock cost trajectories, wall material qualification timelines, and health claims substantiation success rates across the projection horizon. Segmentation modeling spans lipid chemistry, end-use technical requirements, application formats, and distribution channel economics. CAGRs derive from regression analysis against historical price-volume relationships and capacity utilization signals. Industry-specific inputs include El Niño cycle projections for anchovy catch forecasting and ECHA guidance evolution timelines for nanomaterial classification risk.
Practitioners should monitor EFSA assessment queue lengths, Peruvian anchovy biomass surveys, and ECHA sub-100-nanometer guidance updates for early signals of forecast deviation. Material shifts in regulatory classification thresholds or marine ecosystem productivity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Europe Soy Protein Market
Ingredients
China Corn Glucose Market
Ingredients
Mineral Premix Market
Ingredients
Global Distillers Grains Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Chlorella Ingredients Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Dill Seed Oil Market
Ingredients
All Purpose Flour Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Cocoa Beans Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Europe Protein Market
Ingredients
North America Corn Starch Market