
 Global Gelatin Market | 2026-2036
Global Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gelatin Market Analysis
Clean-label extraction technologies is reconfiguring gelatin manufacturing, replacing traditional acid-lime processing with enzymatic methods that reduce batch variability and water intensity. GELITA AG leverages its vertical integration from raw material to pharmaceutical-grade output to sustain margin control across European and North American supply chains. Rousselot anchors its position through deep specialization in hydrolyzed collagen peptides for nutraceutical applications, while Darling Ingredients competes via its dominance in rendering-derived feedstock security across multiple protein streams.
Gelatin is a thermally reversible hydrocolloid derived from partial hydrolysis of collagen, with bloom strength typically ranging from 50 to 300 grams and isoelectric points varying by raw material source between pH 4.7 and 5.4; it functions primarily as a gelling agent, stabilizer, and encapsulation matrix across food and pharmaceutical systems. Pig skin gelatin occupies the largest volume share due to established rendering infrastructure and consistent gel strength profiles, though fish gelatin represents the fastest-growing product type as kosher and halal certification requirements expand across Middle Eastern and Southeast Asian markets. Pharmaceutical applications command premium pricing tiers due to stringent endotoxin and microbial limits, while nutraceuticals deepen demand for hydrolyzed variants with enhanced bioavailability.
EMA pharmacopeial standards and FDA Current Good Manufacturing Practice regulations govern endotoxin limits and traceability for pharmaceutical-grade gelatin, with EU REACH frameworks additionally restricting hexavalent chromium thresholds in bovine hide processing. Halal certification bodies including Indonesia's MUI and Malaysia's JAKIM now mandate species-segregated supply chains, reshaping sourcing patterns for multinational food and cosmetic manufacturers. Stakeholders must monitor evolving religious certification requirements alongside enzymatic processing scale-up economics to secure preferred supplier status in premium pharmaceutical and nutraceutical segments.
Market Dynamics
Halal-certification mandates from Indonesia's MUI and Malaysia's JAKIM are forcing species-segregated supply chain reconfigurations, compressing procurement timelines for pharmaceutical and cosmetic manufacturers sourcing across Southeast Asia.
Growth Catalysts
- Enzymatic Processing Scale-Up:Enzymatic hydrolysis methods reduce batch variability and water intensity compared to traditional acid-lime processing, attracting sustainability-focused nutraceutical buyers.
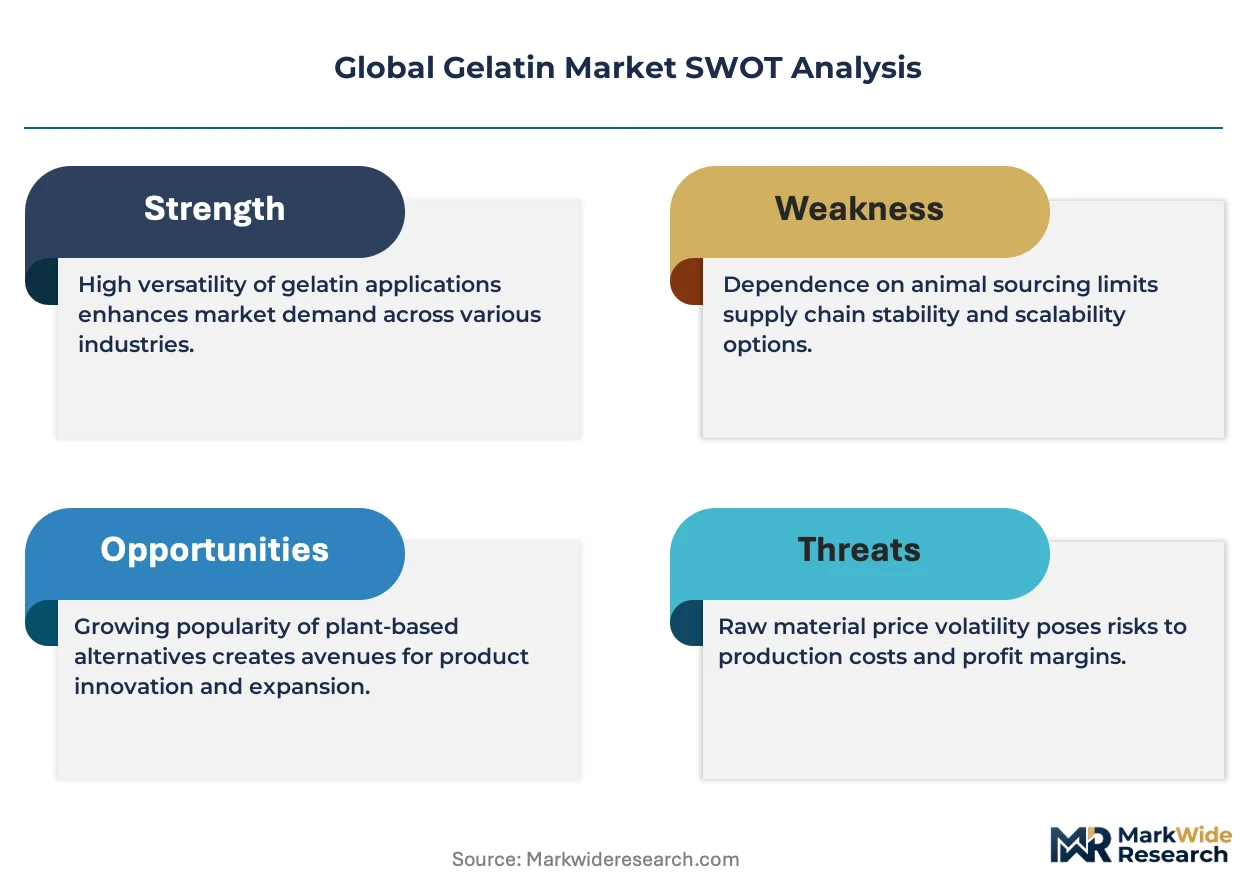
- EMA Pharmacopeial Alignment:Stringent endotoxin and microbial limits for pharmaceutical-grade gelatin create premium pricing tiers that reward certified suppliers with traceable supply chains.
- Fish-Derived Substitution:Kosher and halal certification requirements across Middle Eastern markets accelerate fish gelatin adoption as a non-bovine, non-porcine alternative for capsule and cosmetic applications.
Market Restraints
- Raw Material Volatility:Pig skin and bovine hide prices fluctuate with livestock cycles and rendering capacity constraints in Brazil and Argentina.
- Supply Concentration Risk:European rendering infrastructure dominates pharmaceutical-grade feedstock, creating geographic single-point vulnerability for multinational formulators.
- Collagen Peptide Substitution:Hydrolyzed collagen peptides from Rousselot and competing suppliers displace traditional gelatin in functional food and beverage applications.
Strategic Opportunities
- Indonesia Halal Infrastructure:MUI-certified species-segregated facilities capture premium positioning as domestic pharmaceutical manufacturing expands.
- Clean-Label Cosmetic Formulation:Non-bovine gelatin aligns with EU REACH hexavalent chromium restrictions and consumer preference for transparent sourcing in skincare.
- Pharmaceutical-Grade Bioreactor Cultivation:Recombinant collagen expression technologies converge with enzymatic processing to enable endotoxin-free, animal-origin-free encapsulation matrices.
Industry Challenges
- Certification Timeline Compression:JAKIM and MUI audit cycles extend 12-18 months, delaying market entry for new suppliers in high-growth Southeast Asian markets.
- Rendering-to-Pharma Skill Migration:Technical expertise in endotoxin control and pyrogen testing concentrates in European facilities, limiting capacity expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gelatin Market |
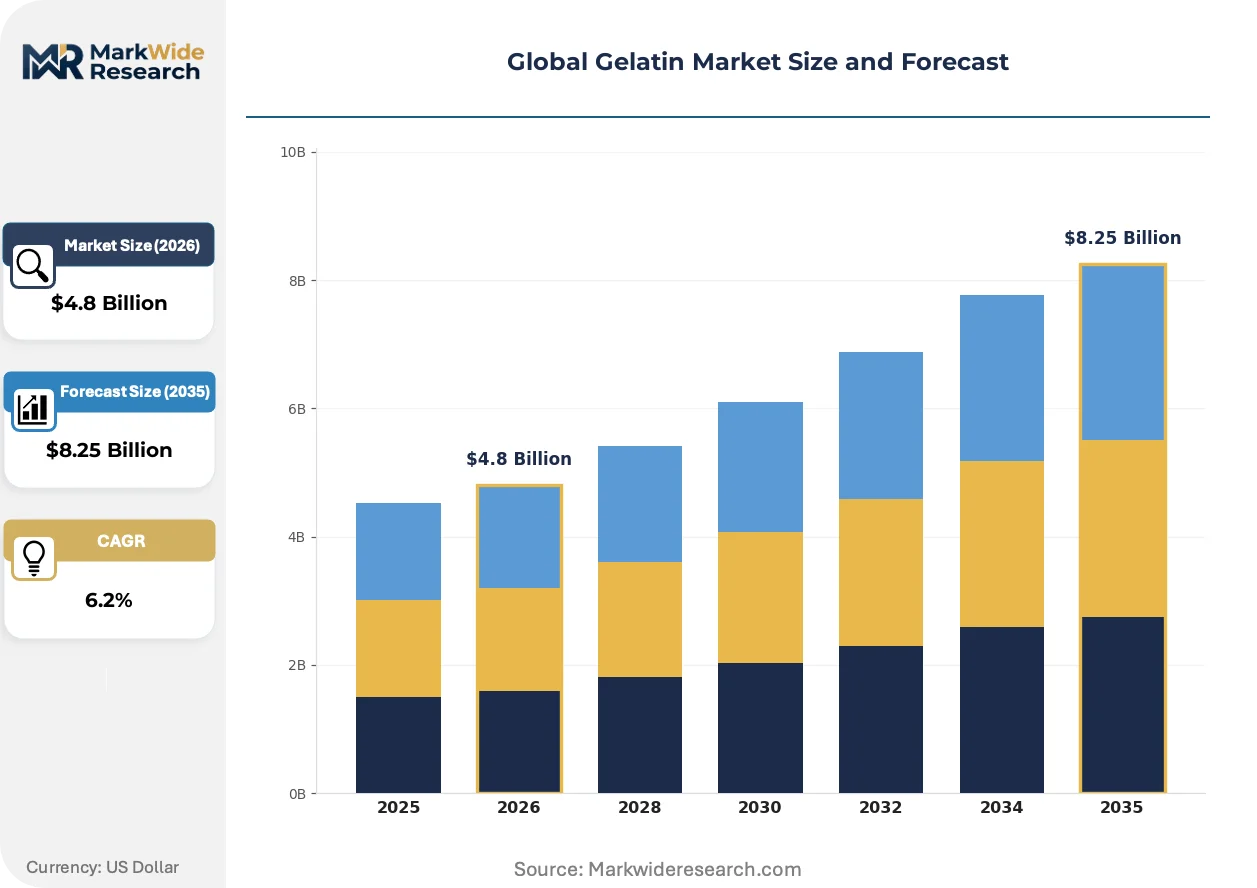
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Gelatin, Pig Skin Gelatin, Bovine Hide Gelatin, Fish Gelatin Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics Form: Powder, Sheet, Granules, Capsules End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Research Institutions |
| Companies Covered | GELITA AG, Rousselot, Darling Ingredients, Nitta Gelatin Inc., Weishardt, Tessenderlo Group, PB Leiner, Lapi Gelatine S.p.a., Trobas Gelatine B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gelatin Market Emerging Trajectories
Clean-label extraction technologies and religious certification requirements are simultaneously elevating process transparency and fragmenting sourcing strategies across food, pharmaceutical, and cosmetic applications.
Enzymatic hydrolysis is collapsing the traditional acid-lime processing paradigm by eliminating lime-curing stages that introduce batch-to-batch variability. Pharmaceutical manufacturers in Germany and Switzerland adopt these methods to meet EMA pharmacopeial consistency requirements. The technology compresses water usage and processing time, enabling smaller-batch pharmaceutical production with tighter endotoxin control.
EU REACH frameworks restricting hexavalent chromium thresholds in bovine hide processing are elevating fish-derived and porcine alternatives in cosmetic and food-grade segments. Manufacturers reformulate encapsulation matrices and gelling systems to preempt compliance costs. French and Italian cosmetic brands lead this pivot, substituting certified fish gelatin for bovine sources in premium skincare lines.
Buyer concentration among contract development and manufacturing organizations is compressing supplier qualification timelines and unbundling technical service from material supply. Large pharmaceutical formulators in the United States and Japan now demand dedicated audit trails and captive inventory buffers. This pattern concentrates procurement leverage with vertically integrated suppliers capable of species-segregated production.
Global Gelatin Market Segmentation
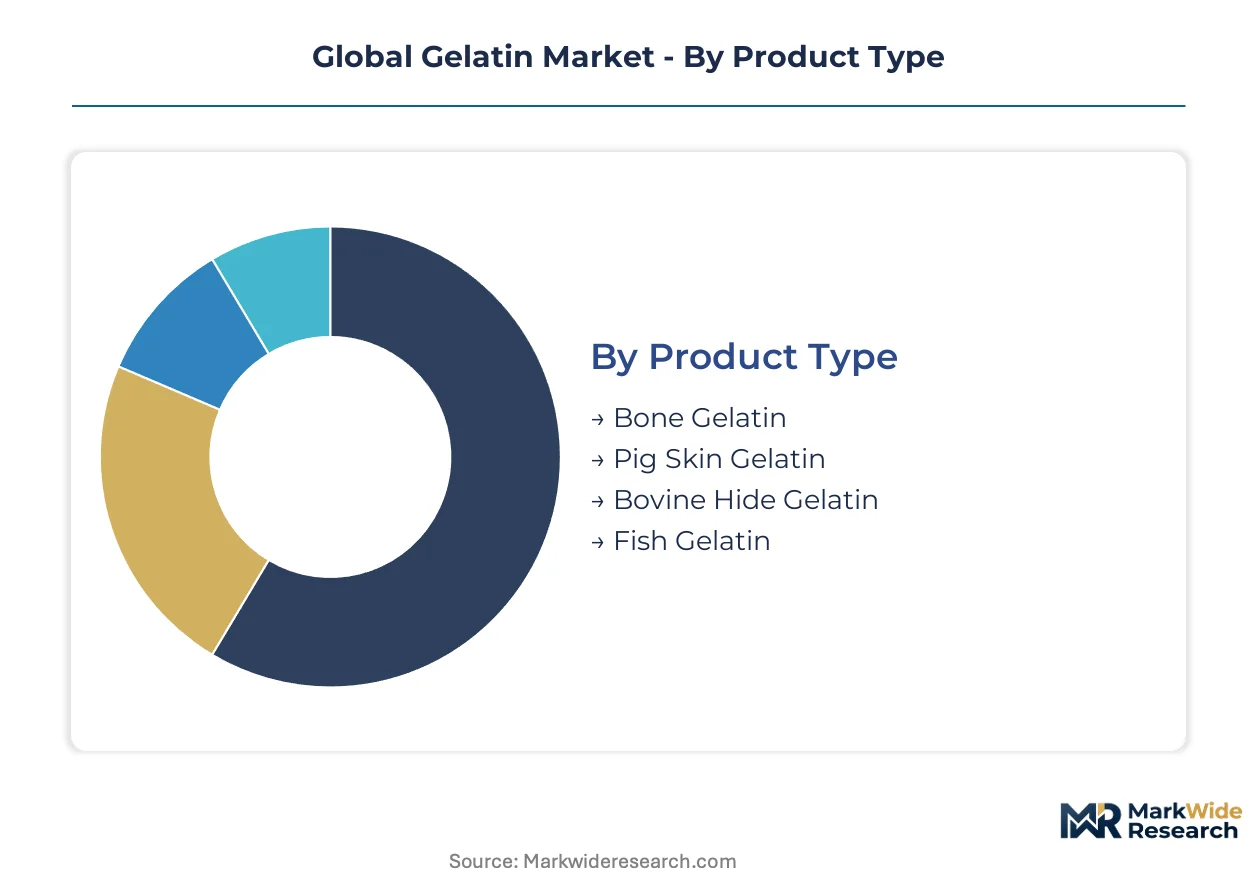
Segmentation in gelatin markets reflects divergent technical specifications across religious certification requirements, pharmaceutical purity thresholds, and cosmetic formulation needs. Each dimension carries distinct margin structures and supply chain rigor.
Product Type:
Cost tier stratification separates commodity-grade rendering outputs from pharmaceutical-grade species-segregated production.
- Pig Skin Gelatin:Derived from porcine dermal collagen with bloom strength typically between 150-250g. Food manufacturers in Germany and the United States dominate procurement volumes, though JAKIM and MUI certification exclusions constrain access across Southeast Asian pharmaceutical markets.
- Fish Gelatin:Extracted from cold-water fish species with lower melting points and distinctive amino acid profiles. Cosmetic brands in France and Italy accelerate adoption to satisfy EU REACH hexavalent chromium restrictions and kosher/halal labeling requirements in Middle Eastern markets.
- Bone Gelatin:Sourced from demineralized bovine or porcine skeletal tissue for high-bloom industrial applications.
- Bovine Hide Gelatin:Processed from cattle hide splits with variable isoelectric points dependent on liming duration.
Pig skin gelatin commands the established base. The steepest expansion runs through fish gelatin.
Application:
Application scope spans gelling functionality through encapsulation matrices to bioactive peptide delivery.
- Pharmaceuticals:Hard and soft capsule shells demand endotoxin limits below 10 EU/g and full batch traceability. EMA pharmacopeial alignment and FDA Current Good Manufacturing Practice regulations govern pyrogen testing protocols, with Swissmedic and Health Canada applying parallel stringency for imported excipients.
- Food & Beverage:Confectionery gelling, dairy stabilization, and meat binding utilize Type A and Type B gelatin with variable bloom strengths. Manufacturers in Belgium and the Netherlands concentrate procurement for premium confectionery exports.
- Nutraceuticals:Hydrolyzed collagen peptides for joint and skin health formulations compete with intact gelatin gelling systems.
- Cosmetics:Film-forming and moisture-retention properties drive skincare and haircare incorporation.
Pharmaceuticals anchor margin capture. Nutraceuticals climb the fastest as functional positioning displaces commodity gelling.
Form:
Volume concentration favors powder for industrial scale, while precision dosing elevates alternative formats.
- Powder:Standardized particle size distributions enable bulk dissolution in food and pharmaceutical processing. Brazilian and Argentine rendering outputs predominantly flow into powder form for international distribution.
- Capsules:Pre-formed two-piece shells eliminate on-site gelatin handling for pharmaceutical formulators. Japanese and South Korean contract manufacturers specify pre-locked capsule specifications to compress qualification timelines.
- Sheet:Traditional culinary applications and artisanal confectionery production in France and Italy.
- Granules:Intermediate dissolution kinetics for specialized food processing equipment.
Powder retains volume dominance. Capsules gain share fastest through pharmaceutical outsourcing concentration.
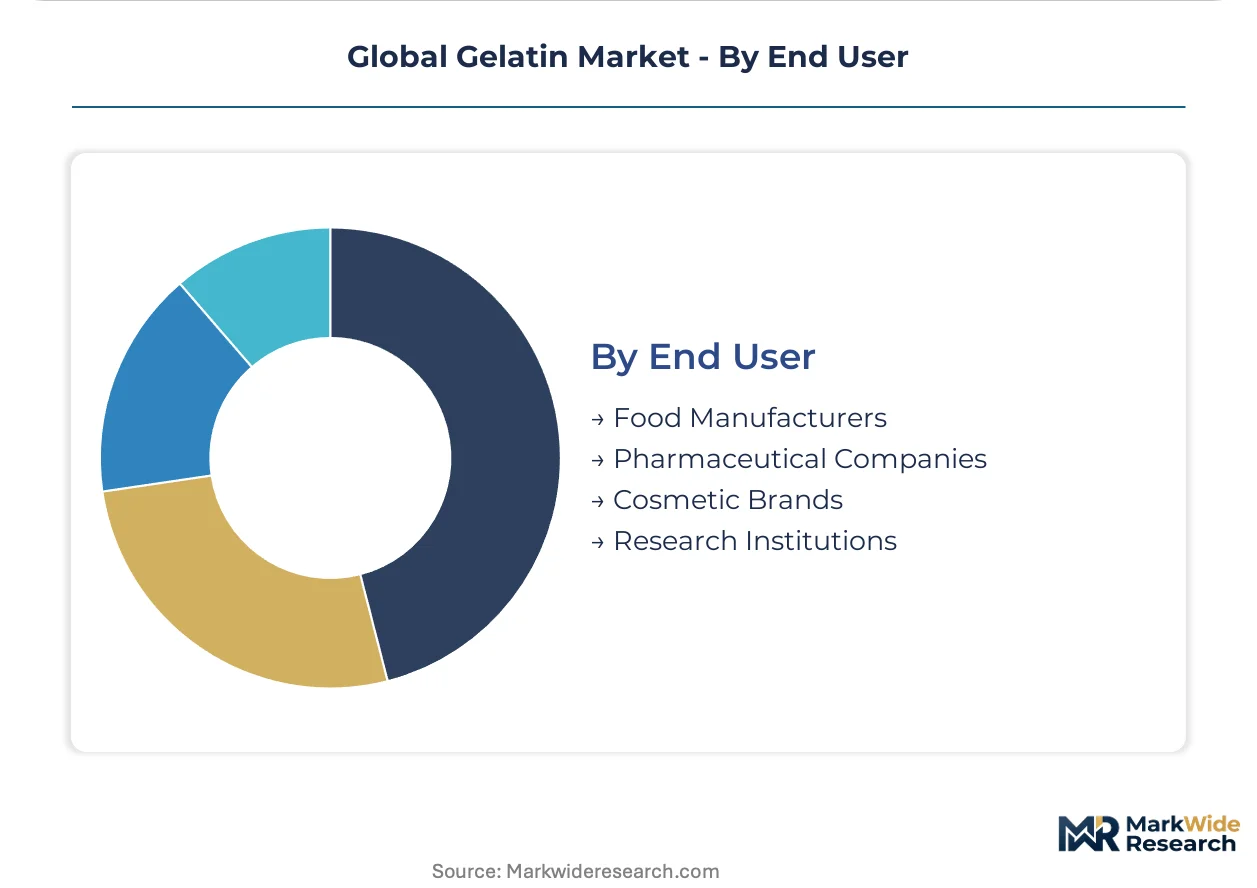
End User:
Customer type determines specification stringency, with pharmaceutical and cosmetic buyers imposing segregated supply chain audits.
- Pharmaceutical Companies:Multinational formulators in Switzerland, Germany, and Japan demand captive inventory buffers and dedicated audit trails. EMA and PMDA inspections enforce species-segregated production lines with documented chain-of-custody from rendering through final hydrolysis.
- Cosmetic Brands:Clean-label positioning in French and Italian premium skincare drives non-bovine sourcing and enzymatic processing verification. EU REACH compliance documentation supersedes traditional food-grade certification.
- Food Manufacturers:Confectionery and dairy processors prioritize bloom consistency and cost optimization over traceability depth.
- Research Institutions:Cell culture and laboratory applications require low-endotoxin research-grade material with documented origin.
Food manufacturers represent the volume foundation. Pharmaceutical companies concentrate value capture as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian rendering facilities export pharmaceutical-grade feedstock to German capsule manufacturers, while Indonesian halal-certified processors supply Malaysia's expanding domestic pharmaceutical sector.
United States
FDA Current Good Manufacturing Practice regulations enforce endotoxin limits below 10 EU/g for pharmaceutical-grade imports. Chicago-area formulators demand captive inventory buffers from species-segregated suppliers. Darling Ingredients anchors rendering-derived feedstock security across multiple protein streams for domestic capsule producers.
Germany
EMA pharmacopeial alignment drives enzymatic processing adoption among Baden-Württemberg pharmaceutical manufacturers. EU REACH frameworks restrict hexavalent chromium thresholds in bovine hide processing. GELITA AG leverages vertical integration from raw material to pharmaceutical-grade output to sustain margin control across European supply chains.
Indonesia
MUI halal-certification mandates force species-segregated supply chain reconfigurations for pharmaceutical and cosmetic manufacturers. Domestic pharmaceutical manufacturing expansion accelerates demand for certified gelatin procurement. JAKIM audit cycles extending 12-18 months delay market entry for new suppliers in high-growth Southeast Asian markets.
Japan
PMDA inspections enforce species-segregated production lines with documented chain-of-custody from rendering through final hydrolysis. Tokyo and Osaka contract manufacturers specify pre-locked capsule specifications to compress qualification timelines. Technical expertise in endotoxin control and pyrogen testing concentrates in Japanese facilities.
France
ANSM documentation requirements elevate fish-derived and porcine alternatives in cosmetic and food-grade segments. French cosmetic brands lead substitution of certified fish gelatin for bovine sources in premium skincare lines. Lyon and Paris formulation clusters reformulate encapsulation matrices to preempt EU REACH compliance costs.
Global Gelatin Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor base anchored by rendering-to-pharma integrators. European facilities dominate pharmaceutical-grade feedstock supply, creating geographic concentration risk for multinational formulators. Three archetypes prevail: vertically integrated rendering specialists, hydrolyzed collagen peptide specialists, and regional halal-certified processors. Capacity expansion and enzymatic processing licensing represent the dominant competitive moves.
Within the vertically integrated tier, GELITA AG exemplifies backward integration from raw material through pharmaceutical-grade output. Rousselot occupies a position among hydrolyzed collagen peptide specialists for nutraceutical applications. Darling Ingredients anchors the rendering-derived feedstock security archetype across multiple protein streams.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot |
| Darling Ingredients |
| Nitta Gelatin Inc. |
| Weishardt |
| Tessenderlo Group |
| PB Leiner |
| Lapi Gelatine S.p.a. |
| Trobas Gelatine B.V. |
| Others |
Supply Flow & Price Mechanics
Raw material volatility in Brazilian and Argentine livestock cycles compresses margin structures across pharmaceutical-grade tiers while simultaneously forcing buyers toward species-segregated supply commitments that carry premium pricing. This dual pressure widens spreads between commodity rendering outputs and certified pharmaceutical grades as enzymatic processing investments accumulate.
Pricing Analysis
Traditional acid-lime processing and emerging enzymatic hydrolysis methods anchor a widening technology-generation pricing gap that separates established commodity producers from premium pharmaceutical suppliers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects certification depth and endotoxin control stringency. Pricing pressure stems from hydrolyzed collagen peptide substitution in functional food applications as Rousselot and competing suppliers displace intact gelatin. Food manufacturers exhibit highest price sensitivity due to commoditized gelling requirements, while pharmaceutical companies absorb premiums for traceable, species-segregated supply.
Supply Chain Analysis
Extended payment terms from multinational pharmaceutical formulators in Germany, Japan, and Switzerland strain working capital for rendering-to-gelatin processors. Supply concentrates in Brazil, Argentina, and Germany for raw material rendering, with pharmaceutical-grade hydrolysis capacity clustering in Baden-Württemberg and Osaka prefecture. Feedstock dependencies center on pig skin, bovine hide splits, and cold-water fish species. Single-source vulnerability runs through European pharmaceutical-grade hydrolysis infrastructure. Distribution runs through vertically integrated suppliers with captive inventory buffers for species-segregated production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gelatin market tracks a cyclical recovery pattern as livestock herd rebuilding in South America restores rendering feedstock availability following drought-constrained supply. Pharmaceutical capsule demand expansion across Southeast Asian manufacturing clusters provides the demand-side cyclical anchor.
For Market Incumbents: Pre-empt certification timeline compression by securing MUI and JAKIM audit slots before Indonesian pharmaceutical manufacturing expansion accelerates. Invest in enzymatic processing scale-up to defend margin position against hydrolyzed collagen peptide substitution in nutraceutical applications. Lock species-segregated rendering agreements in Brazil to secure feedstock priority ahead of competitor capacity additions.
For New Entrants and Emerging Players: Build out halal-certified fish gelatin processing in Indonesia to capture MUI-compliant supply gaps before European incumbents complete Southeast Asian facility qualification. Target cosmetic brand procurement in France and Italy where EU REACH hexavalent chromium restrictions elevate non-bovine sourcing premiums. Lead with clean-label extraction technology verification as the primary go-to-market differentiator.
For Investors and Strategic Acquirers: EMA pharmacopeial alignment with FDA Current Good Manufacturing Practice regulations reshapes the acquisition landscape toward traceable, endotoxin-capable processing assets. Five-to-ten-year viability favors processors with backward integration into rendering and forward integration into pharmaceutical-grade hydrolysis. Monitor JAKIM and MUI certification backlog clearance rates as the inflection signal for Southeast Asian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Reduces water intensity and batch variability for EMA pharmacopeial compliance. |
| Species-Segregated Facility Certification | Captures MUI and JAKIM premiums in Indonesian pharmaceutical procurement. |
| Backward Integration into Rendering | Secures pig skin and fish feedstock priority amid Brazilian livestock cycle volatility. |
| Fish Gelatin Capacity Addition | Aligns with EU REACH hexavalent chromium restrictions in French cosmetic formulation. |
| Pharmaceutical-Grade Bioreactor Cultivation | Enables endotoxin-free, animal-origin-free encapsulation for premium capsule markets. |
Methodological Framework
A standing panel of pharmaceutical procurement managers, cosmetic formulation chemists, rendering facility operations directors, and regulatory affairs specialists provided ongoing calibration across primary interview rounds and secondary validation. Primary fieldwork encompassed gelatin processors in Germany, Brazil, Indonesia, and Japan alongside downstream capsule manufacturers and skincare formulators. Secondary sources included FDA Current Good Manufacturing Practice guidance documents, EMA pharmacopeial monographs, JAKIM and MUI certification registries, and customs trade data for gelatin and collagen peptide flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, food, nutraceutical, and cosmetic applications.
Scenario-bracketing framed projections across enzymatic processing adoption rates, halal-certification timeline variations, and collagen peptide substitution intensity. Segmentation dimensions encompassed product type, application, form, and end-user category with geographic production cluster overlays. CAGRs derived from elasticity-adjusted demand curves and capacity expansion schedules across the projection horizon. Forecast inputs incorporated livestock cycle recovery trajectories in South America and pharmaceutical manufacturing buildout rates in Southeast Asia.
Practitioners should monitor MUI and JAKIM certification backlog clearance, EU REACH enforcement intensity on hexavalent chromium, and recombinant collagen expression technology maturation for early signals of structural shift. Forecasts reflect documented assumptions on regulatory trajectory and processing technology diffusion. Macroeconomic disruption in livestock markets, regulatory acceleration in religious certification requirements, or breakthroughs in animal-origin-free encapsulation matrices would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cooking Oils and Fats Market
Ingredients
Starch Market
Ingredients
Chickpea Fiber Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Virginiamycin Market
Ingredients
Jasmine Extract Market
Ingredients
Spelt Flour Market
Ingredients
Oak Extract Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Corn Starch Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Canola Meal Market