
 Heating Tape Market | 2026-2036
Heating Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Heating Tape Market Analytics
Multi-source procurement of heating elements is shifting toward vertically integrated domestic suppliers as lead times for imported resistance wire fluctuate. Chromalox leverages in-house mineral insulation manufacturing to control thermal output consistency across its trace heating lines. BriskHeat anchors its competitive position through extensive distributor networks serving North American oilfield services. Tempco Electric Heater Corporation differentiates via custom watt-density configurations for semiconductor fabrication thermal management.
Heating tape is an electrically resistive flexible element, typically constructed from nickel-chromium or copper-nickel alloy wire wrapped around a fiberglass or polymer core and insulated with silicone rubber or fluoropolymer sheathing, designed to maintain pipe, vessel, or surface temperatures above ambient or process setpoints through joule heating. Self-regulating polymer matrix formulations dominate plumbing and residential freeze protection applications due to inherent energy savings from positive temperature coefficient behavior. Silicone heating tape leads industrial equipment segments where sustained temperatures exceed 200°C and chemical resistance proves critical. Flexible heating tape variants are gaining share in automotive battery thermal management as OEMs integrate cell conditioning into pack architectures.
UL 515 standards for electrical resistance heat tracing and IEC 62395 for industrial applications govern product certification and installation compliance across major demand centers. OSHA process safety management requirements for petrochemical facilities mandate documented heat trace maintenance protocols, creating recurring inspection and replacement cycles. EPA energy efficiency guidelines for commercial buildings indirectly influence specification trends toward lower standby-loss designs. Stakeholders must monitor evolving building electrification codes and industrial decarbonization timelines to align product portfolios with emerging thermal system integration requirements.
Market Dynamics
US Department of Energy efficiency mandates are compressing wattage specifications across industrial heating tape portfolios, forcing manufacturers to redesign resistive element geometries while maintaining thermal output density in subzero extraction environments.
Growth Catalysts
- Petrochemical Winterization Mandates:Post-2021 Texas grid failures triggered state-level retrofit programs requiring freeze protection on above-ground piping. Facility operators in the Permian Basin and Gulf Coast are procuring self-regulating cable systems in bulk.
- US DOE Industrial Efficiency Standards:Minimum performance requirements for process heating equipment are accelerating replacement cycles in refineries and chemical plants. Compliance deadlines are pulling forward capital expenditure timelines for trace heating upgrades.
- Silicone Sheathing Advances:Fluoropolymer-coated variants now sustain continuous operation above 250°C in semiconductor diffusion furnaces. Wafer fabrication facilities in Arizona and Oregon are specifying these for chamber thermal uniformity.
Market Restraints
- Nickel-Chromium Alloy Volatility:Resistance wire feedstock prices fluctuate with stainless steel scrap and nickel ore markets. Chinese smelter output cuts in 2024 tightened spot availability for North American cable extruders.
- Mineral Insulation Supply Concentration:Magnesium oxide powder for high-temperature heating tapes sources predominantly from Indian and Chinese refractory producers. Geopolitical friction creates lead time unpredictability for US-based manufacturers.
- Positive Temperature Coefficient Limitations:Self-regulating polymer matrices degrade above 150°C, excluding them from industrial oven and autoclave applications where silicone rubber tapes dominate despite higher energy consumption.
Strategic Opportunities
- Electric Vehicle Battery Conditioning:Automotive OEMs are integrating flexible heating tapes into lithium-ion pack architectures for cold-climate preconditioning. Cell manufacturers in Michigan and South Carolina are qualifying tape suppliers for 2026 platform launches.
- Hydrogen Infrastructure Thermal Management:Electrolyzer and fueling station operators require freeze protection for high-pressure hydrogen lines. German and Dutch hydrogen corridor projects are specifying certified trace heating for 700-bar dispensing systems.
- US Inflation Reduction Act Credits:Domestic content bonuses for clean energy manufacturing equipment are incentivizing reshoring of heating element production. Texas and Ohio facility expansions are capturing procurement preference from tax-credit-seeking developers.
Industry Challenges
- UL 515 Certification Timelines:Third-party testing for electrical resistance heat tracing approval extends 14-20 weeks. Product launch schedules compress as manufacturers parallel-track design validation and documentation submission.
- OSHA Process Safety Management Documentation:Petrochemical facilities must maintain inspection records for heat trace systems per 29 CFR 1910.119. Vendor technical service teams face capacity constraints supporting recurring audit preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heating Tape Market |
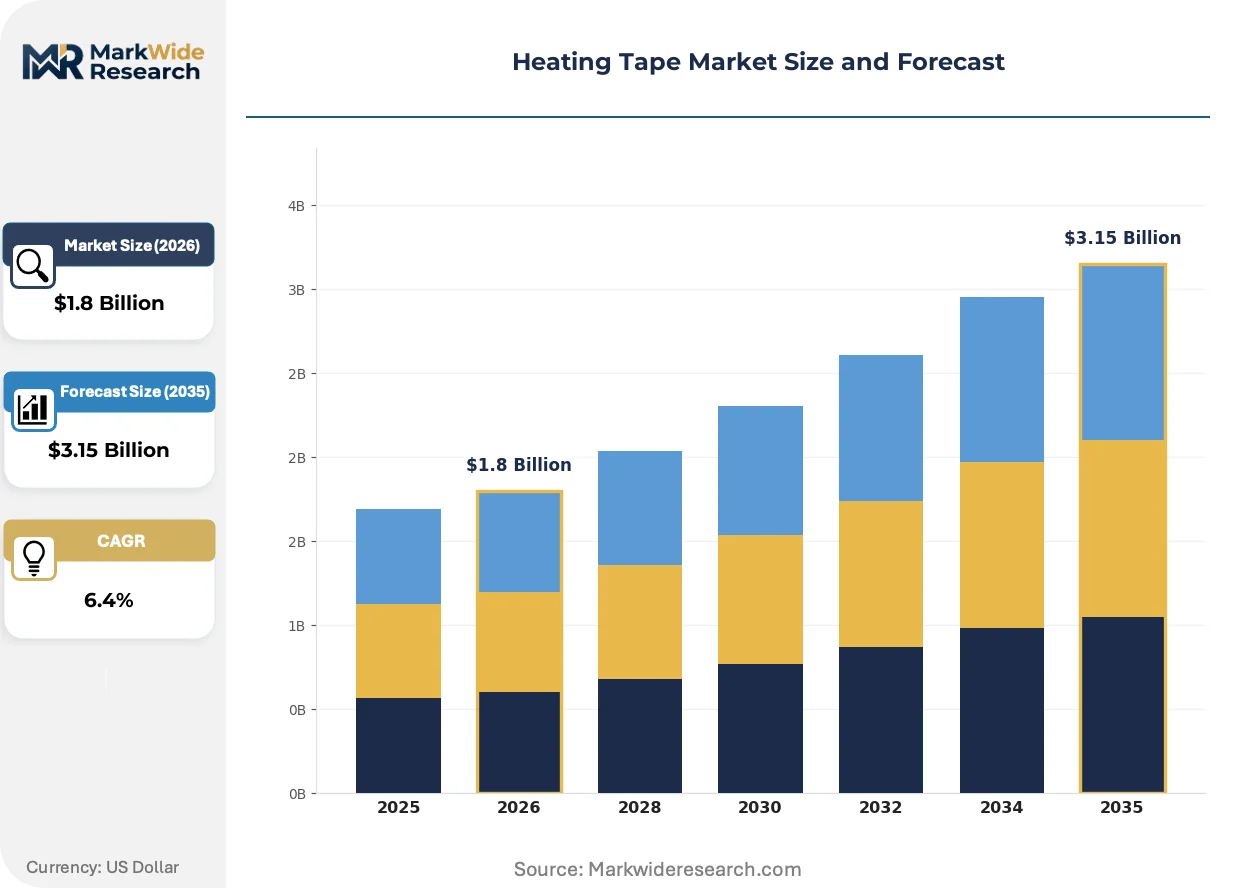
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Heating Tape, Rigid Heating Tape, Flexible Heating Tape, Self-Adhesive Heating Tape Material: Polyimide, PVC, Rubber, Fiberglass Application: Plumbing, Automotive, Industrial Equipment, Pets End User: Manufacturers, Homeowners, Contractors, Maintenance Services |
| Companies Covered | Chromalox, Heat-Line, WATTCO, Goldleaf Scientific, Astraglass Innovations, Tempco Electric Heater Corporation, HTS/Amptek, Atlantex Manufacturing Corp., BriskHeat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heating Tape Market Evolving Landscape
Material science advances in polymer matrix formulations and ceramic insulation are redrawing performance boundaries between self-regulating and constant-wattage architectures. Regulatory pressure on industrial energy intensity is accelerating specification shifts.
Polyimide-based flexible heating films are expanding into aerospace de-icing and satellite thermal control applications where weight reduction outweighs cost premiums. Boeing and Lockheed Martin suppliers in California are qualifying these for wing leading-edge and propellant line conditioning. The technology is expanding into defense contractor supply chains as ITAR-compliant domestic sourcing requirements tighten.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon blowing agents used in some heating tape insulation foams. German and Dutch chemical processors are reformulating silicone rubber compounds with water-based expansion systems. Industrial equipment OEMs in the Rhine-Ruhr cluster are demanding certified low-global-warming-potential alternatives for export-compliant machinery.
Specification authority is migrating from maintenance departments to corporate energy management offices with centralized sustainability targets. Facility operators in Texas and Louisiana are consolidating vendor relationships to capture volume discounts and standardized service protocols. Engineering-procurement-construction firms are embedding heating tape specifications into lump-sum turnkey contracts, compressing direct manufacturer engagement with end users.
Heating Tape Market Segmentation
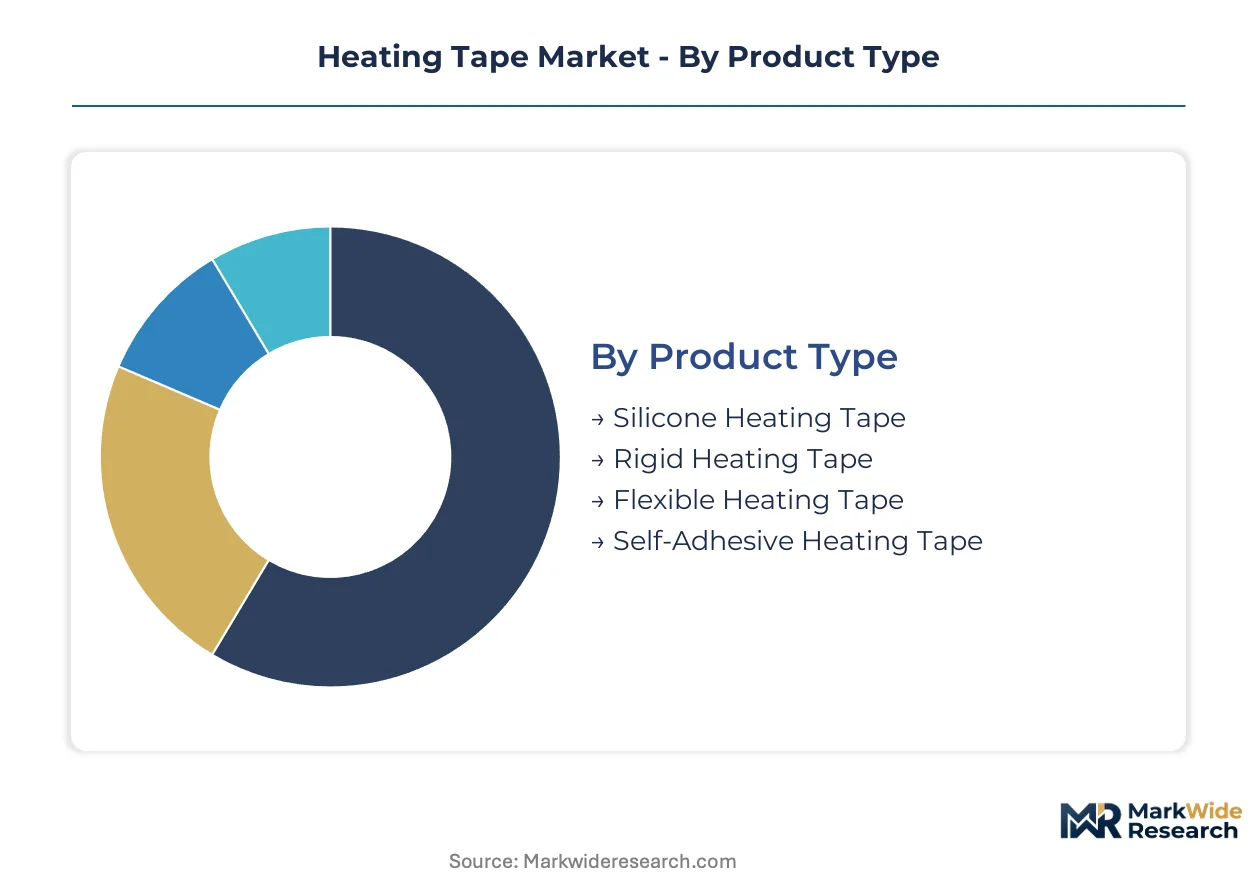
Segmentation in heating tape markets reveals how thermal output requirements, installation constraints, and end-use environments dictate procurement specifications. Buyers prioritize watt-density consistency, chemical resistance, and compliance certification over unit cost in industrial applications.
Product Type:
Application temperature range and mechanical flexibility requirements determine specification authority between constant-wattage and self-regulating architectures.
- Silicone Heating Tape:Nickel-chromium resistance wire embedded in fiberglass-reinforced silicone rubber sheathing sustains continuous operation above 200°C. Semiconductor diffusion furnaces in Arizona and Oregon specify fluoropolymer-coated variants for chamber thermal uniformity.
- Flexible Heating Tape:Thin-film polymer substrates with etched foil or wire-wound elements enable conformal wrapping around complex geometries. Automotive OEMs in Michigan integrate these into lithium-ion battery pack architectures for cold-climate preconditioning.
- Rigid Heating Tape:Mineral-insulated metal-sheathed construction delivers maximum thermal output density for fixed pipeline installations.
- Self-Adhesive Heating Tape:Pressure-sensitive backing accelerates installation on flat surfaces where mechanical fasteners are impractical.
Silicone heating tape leads on scale; flexible heating tape leads on momentum.
Material:
Dielectric strength, thermal conductivity, and chemical resistance trade-offs shape material selection across voltage ratings and exposure conditions.
- Polyimide:Amber-colored film substrates with exceptional dielectric strength and radiation resistance enable aerospace de-icing and satellite thermal control where weight reduction outweighs cost premiums. Boeing and Lockheed Martin suppliers in California qualify these for ITAR-compliant domestic sourcing.
- Rubber:Silicone and EPDM compounds provide elasticity and moisture sealing for outdoor plumbing freeze protection. German chemical processors reformulate with water-based expansion systems to meet EU F-Gas Regulation phase-down schedules.
- PVC:Cost-effective insulation for residential and commercial plumbing applications with moderate temperature requirements.
- Fiberglass:Woven glass fiber tapes serve as primary electrical insulation in high-temperature industrial environments.
Rubber dominates volume shipments; polyimide commands the steepest expansion trajectory.
Application:
Operating environment severity and energy efficiency mandates create divergent specification paths between residential, commercial, and industrial procurement.
- Industrial Equipment:Process heating, vessel trace heating, and autoclave thermal management demand mineral-insulated or silicone-sheathed tapes with documented UL 515 certification. OSHA process safety management requirements per 29 CFR 1910.119 mandate inspection record maintenance, creating recurring replacement cycles.
- Plumbing:Residential and commercial freeze protection drives specification of self-regulating polymer matrix tapes with positive temperature coefficient behavior for inherent energy savings. Post-2021 Texas grid failures triggered state-level retrofit programs requiring above-ground piping protection.
- Automotive:Battery thermal management and fluid line conditioning integrate flexible heating elements into vehicle architectures.
- Pets:Low-voltage warming applications for animal husbandry and companion animal products.
Industrial equipment commands specification authority; plumbing delivers the highest unit volumes.
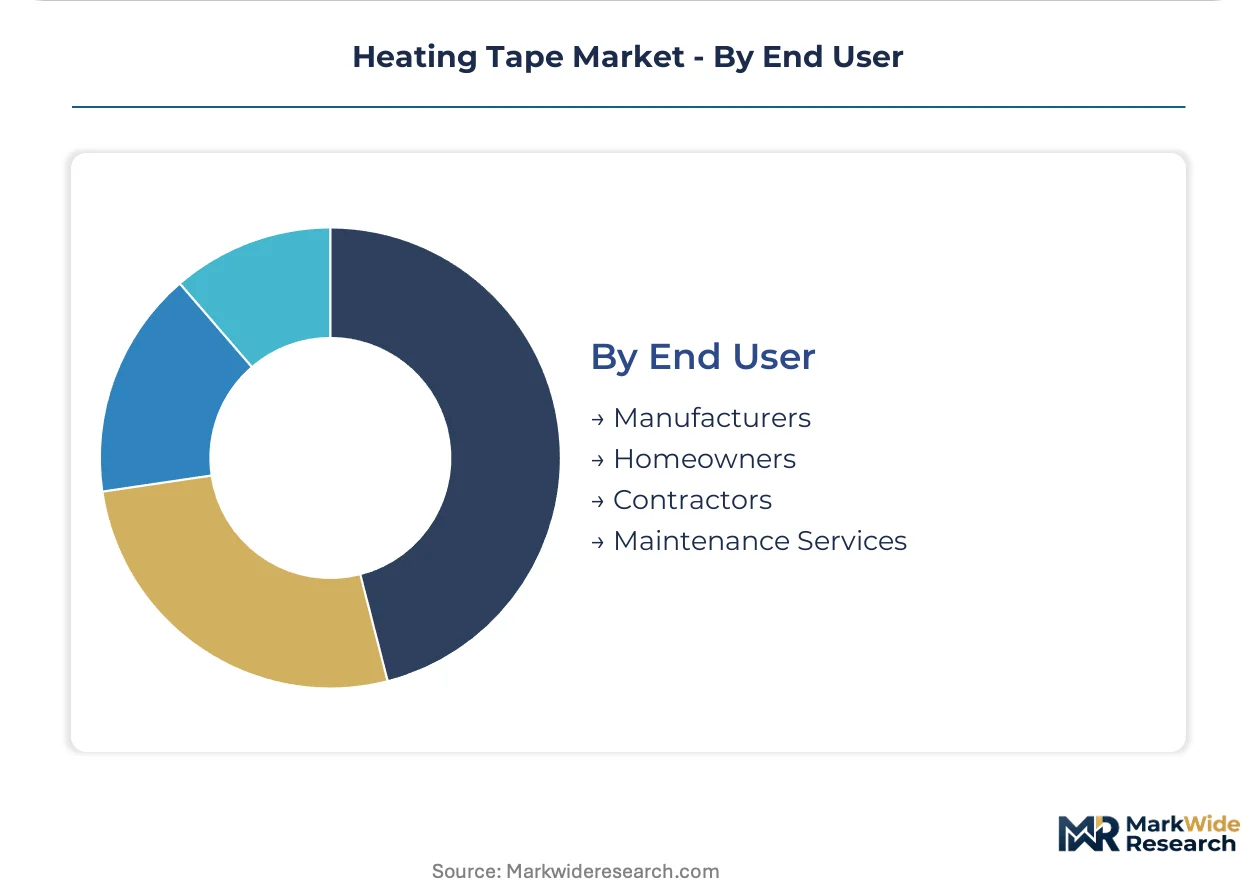
End User:
Procurement sophistication and technical specification ownership vary sharply between institutional buyers and dispersed residential purchasers.
- Contractors:Engineering-procurement-construction firms embed heating tape specifications into lump-sum turnkey contracts, consolidating vendor relationships for volume discounts and standardized service protocols. Texas and Louisiana facility operators leverage this channel for petrochemical winterization programs.
- Manufacturers:OEMs and industrial equipment builders specify custom watt-density configurations for integration into capital equipment. Semiconductor fabrication facilities demand thermal uniformity certification for chamber conditioning systems.
- Homeowners:Retail-channel purchases for residential plumbing freeze protection prioritize ease of installation and plug-and-play compatibility.
- Maintenance Services:Facility management providers manage recurring inspection and replacement cycles under OSHA documentation requirements.
Contractors concentrate procurement volume; manufacturers drive technical innovation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin and Gulf Coast petrochemical corridor concentrates North American heating tape procurement, with state-level winterization mandates pulling forward replacement cycles and bulk procurement of self-regulating cable systems.
United States
Texas petrochemical facility expansions and post-2021 grid failure retrofits drive concentrated demand for above-ground piping freeze protection. OSHA process safety management requirements per 29 CFR 1910.119 mandate documented heat trace maintenance protocols. Facility operators in the Permian Basin and along the Gulf Coast are consolidating vendor relationships for standardized service protocols.
Germany
Rhine-Ruhr industrial cluster chemical processors are reformulating silicone rubber compounds to comply with EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents. German electrolyzer operators in the hydrogen corridor projects specify certified trace heating for 700-bar dispensing systems. Engineering-procurement-construction firms in North Rhine-Westphalia embed heating tape specifications into lump-sum turnkey contracts.
China
Magnesium oxide powder supply concentration from domestic refractory producers creates lead time advantages for cable extruders serving industrial equipment segments. Chinese smelter output fluctuations in 2024 tightened spot availability of nickel-chromium alloy feedstock for resistance wire. Yangtze River Delta manufacturing clusters are expanding mineral-insulated metal-sheathed tape production for fixed pipeline installations.
Japan
Automotive OEMs in the Nagoya-Chubu region integrate flexible heating elements into lithium-ion battery pack architectures for cold-climate preconditioning. METI industrial efficiency standards accelerate replacement cycles in chemical plants and refineries. Cell manufacturers are qualifying tape suppliers for 2026 platform launches targeting North American export markets.
India
Bureau of Indian Standards certification requirements for electrical resistance heat tracing are compressing product launch timelines for domestic and imported manufacturers. Petrochemical facility expansions in Gujarat and Maharashtra drive specification of silicone-sheathed tapes for process heating applications. Engineering contractors in the Delhi-Mumbai Industrial Corridor are embedding UL 515-equivalent compliance into procurement specifications.
Heating Tape Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in battery thermal management and hydrogen infrastructure. The vendor base spans vertically integrated domestic suppliers controlling mineral insulation manufacturing and distributor-anchored service networks serving oilfield services. Three archetypes dominate: captive-feedstock specialists, distributor-network operators, and custom-configuration engineers. Capacity expansion in Texas and Ohio captures Inflation Reduction Act domestic content bonuses; backward integration into resistance wire production defends margin positions against nickel alloy volatility.
Among US-based thermal equipment fabricators, Chromalox exemplifies the captive-feedstock archetype through in-house mineral insulation manufacturing. BriskHeat anchors the distributor-network model with extensive North American oilfield services coverage. Tempco Electric Heater Corporation occupies the custom-configuration tier, serving semiconductor fabrication demand for thermal uniformity certification. These three represent distinct competitive positioning vectors within a market where specification authority migrates toward corporate energy management offices.
| Leading Market Players |
|---|
| Chromalox |
| Heat-Line |
| WATTCO |
| Goldleaf Scientific |
| Astraglass Innovations |
| Tempco Electric Heater Corporation |
| HTS/Amptek |
| Atlantex Manufacturing Corp. |
| BriskHeat |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents gate qualified silicone rubber supply and premium-tier pricing access for German and Dutch chemical processors reformulating insulation compounds. Compliance-certified manufacturers command 15-25% price premiums over uncertified competitors while spot buyers face allocation risk during reformulation transitions.
Pricing Analysis
Input-cost pass-through from nickel-chromium alloy wire and magnesium oxide powder dominates pricing dynamics for mineral-insulated heating tapes. Three-tier pricing structure across UL 515-certified premium, standard industrial, and uncertified economy levels separates procurement channels. Price differentiation hinges on certification grade and volume scale, with bulk petrochemical contracts compressing per-meter rates. Pricing pressure stems from Chinese smelter output fluctuations tightening resistance wire spot availability. Residential plumbing buyers exhibit highest price sensitivity; semiconductor fabrication facilities show lowest.
Supply Chain Analysis
UL 515 and IEC 62395 certification gating concentrates qualified supply among vertically integrated domestic manufacturers with in-house mineral insulation capabilities. Production gravity centers on the United States, China, and Germany for distinct tape architectures. Raw material dependencies include nickel-chromium alloy wire, magnesium oxide powder, and fluoropolymer sheathing compounds. Supply chain risk manifests in single-source vulnerability for Indian and Chinese refractory-grade magnesium oxide. Distribution runs through engineering-procurement-construction firms embedding specifications into lump-sum turnkey contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heating tape market functions as a stable compounder anchored by recurring OSHA-mandated inspection and replacement cycles in petrochemical facilities that institutionalize steady demand.
For Market Incumbents: Cement feedstock security through backward integration into resistance wire production or captive magnesium oxide sourcing to defend margin positions against nickel alloy volatility. Expand Texas and Ohio capacity to capture Inflation Reduction Act domestic content bonuses. Prioritize UL 515 certification maintenance as regulatory documentation requirements tighten. For New Entrants and Emerging Players: The premium-to-economy price-point gap in automotive battery thermal management offers white-space entry for flexible heating tape specialists. Target Michigan and South Carolina cell manufacturer qualification programs for 2026 platform integrations. Pursue hydrogen infrastructure certification for 700-bar dispensing systems as German and Dutch corridor projects scale. For Investors and Strategic Acquirers: Roll-up economics work for distributor-network operators because petrochemical facility operators are consolidating vendor relationships for standardized service protocols and volume discounts. Five-to-ten-year viability favors custom-configuration specialists with semiconductor thermal uniformity certification. Watch for inflection in US DOE efficiency mandate enforcement accelerating replacement cycle pull-forward.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resistance Wire | Chromalox-style captive feedstock manufacturing defends margins against nickel-chromium volatility. |
| UL 515 Certification Investment | OSHA process safety documentation mandates create recurring replacement revenue streams. |
| Texas/Ohio Capacity Expansion | Inflation Reduction Act domestic content bonuses incentivize reshoring for tax-credit-seeking developers. |
| Automotive Battery Qualification | Michigan and South Carolina cell manufacturers are qualifying tape suppliers for cold-climate preconditioning. |
| Hydrogen Infrastructure Certification | German and Dutch electrolyzer operators specify certified trace heating for 700-bar dispensing systems. |
Research Methodology
Bottom-up industrial equipment and automotive modeling reconciled against top-down resistance wire and magnesium oxide supply tracking forms the analytical core. Primary interviews with petrochemical maintenance directors, semiconductor fabrication thermal engineers, EPC contract procurement leads, and automotive battery pack designers combined with secondary validation from UL certification databases, OSHA 29 CFR 1910.119 inspection records, US DOE efficiency mandate filings, and EU F-Gas Regulation compliance registries. Cross-referencing manufacturer production disclosures with end-user procurement patterns enables triangulation.
Input-output matrices map nickel-chromium alloy consumption and magnesium oxide powder allocation against heating tape production volumes across the modeling period. Segmentation dimensions include product architecture, material substrate, application severity, and end-user procurement sophistication. CAGRs derive from regression analysis of historical replacement cycles, regulatory compliance deadlines, and platform launch timelines. Forecast inputs incorporate petrochemical facility winterization retrofit commitments and automotive OEM battery thermal management integration roadmaps.
Caveats apply where nickel ore market disruptions, Chinese refractory export restrictions, or accelerated US DOE efficiency standard enforcement could materially shift the outlook. Forecasts reflect assumptions about certification timeline stability and feedstock supply continuity. A model refresh is warranted upon material change in OSHA process safety management audit frequency or EU F-Gas Regulation phase-down acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Global Lubrication Pumps Market