
 Progressive Cavity Pump (PCP) Market | 2026-2036
Progressive Cavity Pump (PCP) Market Size, Share, and Industry Trends Forecast 2026-2036
Progressive Cavity Pump (PCP) Market Analysis
Digital twin integration is rewriting how progressive cavity pumps are specified, monitored, and maintained across distributed wellpad networks. NETZSCH Holding GmbH & Co. KG leverages its precision elastomer manufacturing to anchor premium positions in chemical and food-grade applications. Seepex GmbH sustains technology leadership through modular pump designs that simplify field retrofit. Schlumberger Limited dominates artificial lift service bundling, integrating PCP hardware with downhole diagnostics and remote monitoring platforms.
A progressive cavity pump consists of a single helical rotor turning eccentrically within a double-helical elastomer stator, creating sealed cavities that progress from suction to discharge at rates typically spanning 0.5 to 1,000 cubic meters per hour with discharge pressures reaching 48 bar. This positive displacement mechanism handles viscous, abrasive, and multiphase fluids that centrifugal designs cannot manage, making it indispensable for heavy crude extraction, polymer dosing, and sludge transfer. Heavy-duty pumps command the largest revenue share due to replacement frequency in oilfield environments, while multi-stage configurations represent the fastest-growing product category as operators push deeper into high-pressure reservoirs. Electric driven technology leads installation counts across industrial and upstream sectors, though hydraulic driven systems retain critical roles in offshore and explosion-risk zones where electrical isolation matters.
EPA underground injection control regulations and API 676 vibration standards shape material selection and sealing architectures for US-deployed units, while REACH compliance governs elastomer chemistry for European chemical processing customers. The EU F-Gas Regulation indirectly influences PCP specification in refrigeration and heat pump transfer circuits where hermetic designs replace compressor-dependent systems. Stakeholders must weigh capital intensity against total lifecycle cost as predictive maintenance platforms and stator material advances redefine competitive benchmarks.
Market Dynamics
Digital twin deployment across wellpad networks is compressing maintenance cycles and forcing stator manufacturers to integrate sensor-ready geometries into elastomer designs from the mold stage.
Growth Catalysts
- Permian Basin artificial lift density:Unconventional well spacing below 500 feet creates demand for compact, high-torque PCP configurations that fit restricted surface footprints.
- API 676 vibration compliance:Updated standards for rotary pump mechanical integrity are accelerating replacement of legacy pump trains in US downstream facilities.
- Thermoset elastomer advances:Hydrogenated nitrile formulations extending stator life by 40% in heavy crude service are penetrating Canadian oil sands and Venezuelan Orinoco operations.
Market Restraints
- Specialty elastomer supply concentration:Precision-molded stator liners depend on three German and Japanese compounders controlling hydrogenation catalyst access.
- Centrifugal pump substitution in dilbit blending:Diluted bitumen transport pipelines below 15 cP viscosity increasingly specify multistage centrifugal designs with abrasion-resistant coatings.
- REACH chemical authorization delays:ECHA substance evaluation timelines for curative agents in stator manufacturing extend qualification cycles by 18-24 months.
Strategic Opportunities
- Subsea PCP deployment:Seabed processing architectures for heavy oil tiebacks off Brazil and West Africa lack proven artificial lift solutions.
- EU F-Gas Regulation displacement:Hermetic PCP circuits in industrial heat pumps replace compressor-dependent refrigerant loops in food processing and chemical plants.
- Digital twin service bundling:Real-time rotor-stator clearance monitoring enables predictive stator replacement contracts decoupled from equipment ownership.
Industry Challenges
- Elastomer failure analysis expertise:Root-cause determination of stator delamination requires polymer chemists and tribology specialists rarely co-located with field service organizations.
- Downhole sensor integration:Temperature and pressure transmitters embedded in pump housings must survive 150°C operating environments while maintaining API 11AX electrical safety ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressive Cavity Pump (PCP) Market |
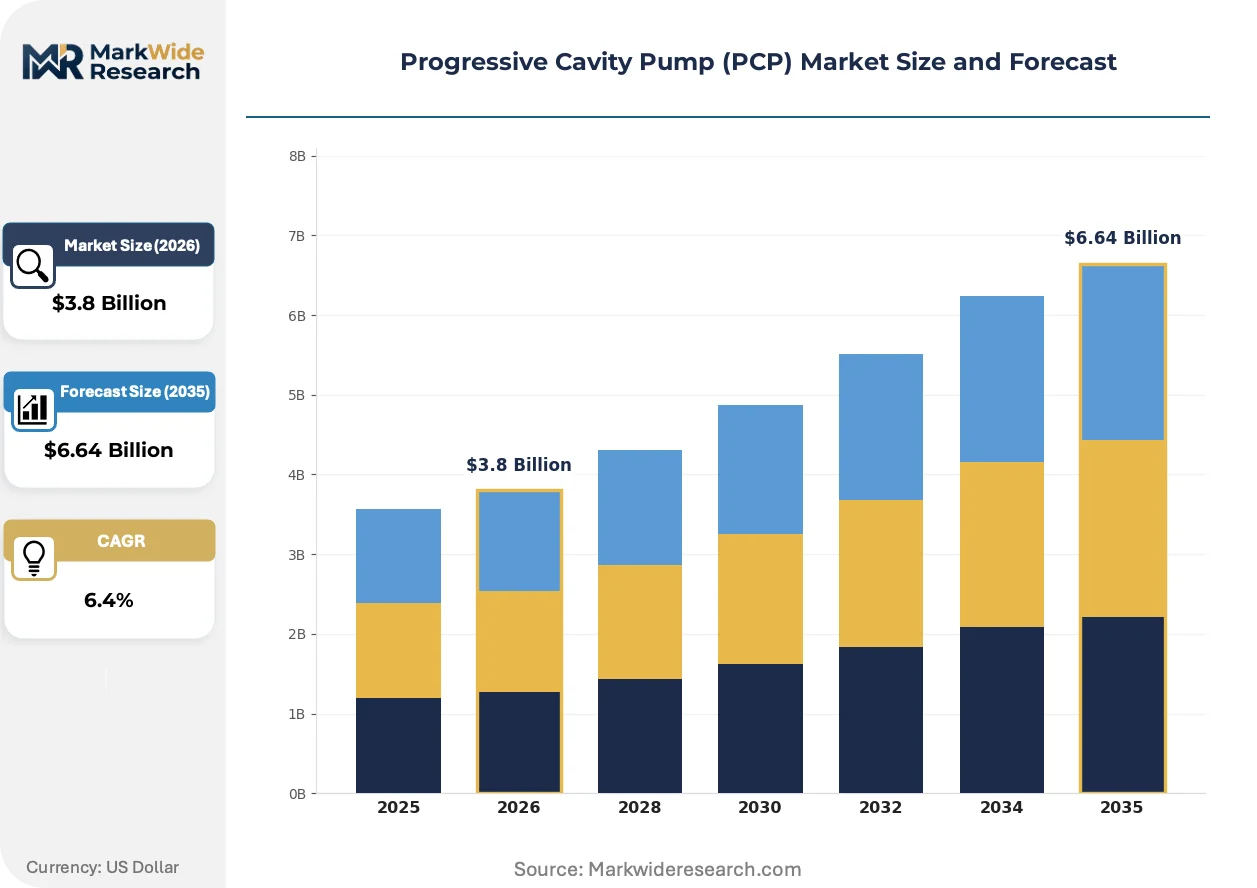
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pumps, Compact Pumps, Heavy-Duty Pumps, Multi-Stage Pumps Application: Oil & Gas, Chemical Processing, Wastewater Treatment, Food & Beverage End User: Industrial Sector, Residential Sector, Agriculture Sector, Marine Sector Technology: Electric Driven, Hydraulic Driven, Pneumatic Driven, Others |
| Companies Covered | Xylem Inc, Seepex GmbH, Schlumberger Limited, Roto Pumps Limited, Weatherford International plc, NETZSCH Holding GmbH & Co. KG, PCM S.A., Pumpenfabrik Wangen GmbH, National Oilwell Varco, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressive Cavity Pump (PCP) Market Emerging Trajectories
Materials science and connected infrastructure are converging to redefine performance benchmarks across upstream and process industries. Three developments merit particular attention.
Additive-manufactured rotor geometries with variable pitch profiles are collapsing the traditional trade-off between volumetric efficiency and solids handling capacity. SAGD operators in Alberta and thermal EOR projects in California are piloting these designs to manage produced sand without choking flow paths. The compression of conventional fixed-geometry rotor specifications is forcing incumbent manufacturers to retool grinding operations or outsource precision machining.
EPA underground injection control revisions for Class II brine disposal wells are tightening mechanical integrity demonstration requirements for surface injection pumps. PCP operators must now document real-time pressure containment verification rather than periodic hydrostatic testing. Downhole chemical injection systems in Texas and Oklahoma are retrofitting hermetic seal configurations to satisfy the new continuous monitoring mandates.
Integrated service contracts that bundle pump hardware, elastomer replacement, and remote diagnostics are displacing traditional capital purchase models in North American shale operations. Mid-size E&P companies lacking in-house artificial lift engineering prefer single-vendor accountability for run-life performance. This preference shift is most pronounced in the Permian Delaware sub-basin where private equity-backed operators prioritize capital efficiency over asset ownership.
Progressive Cavity Pump (PCP) Market Segmentation
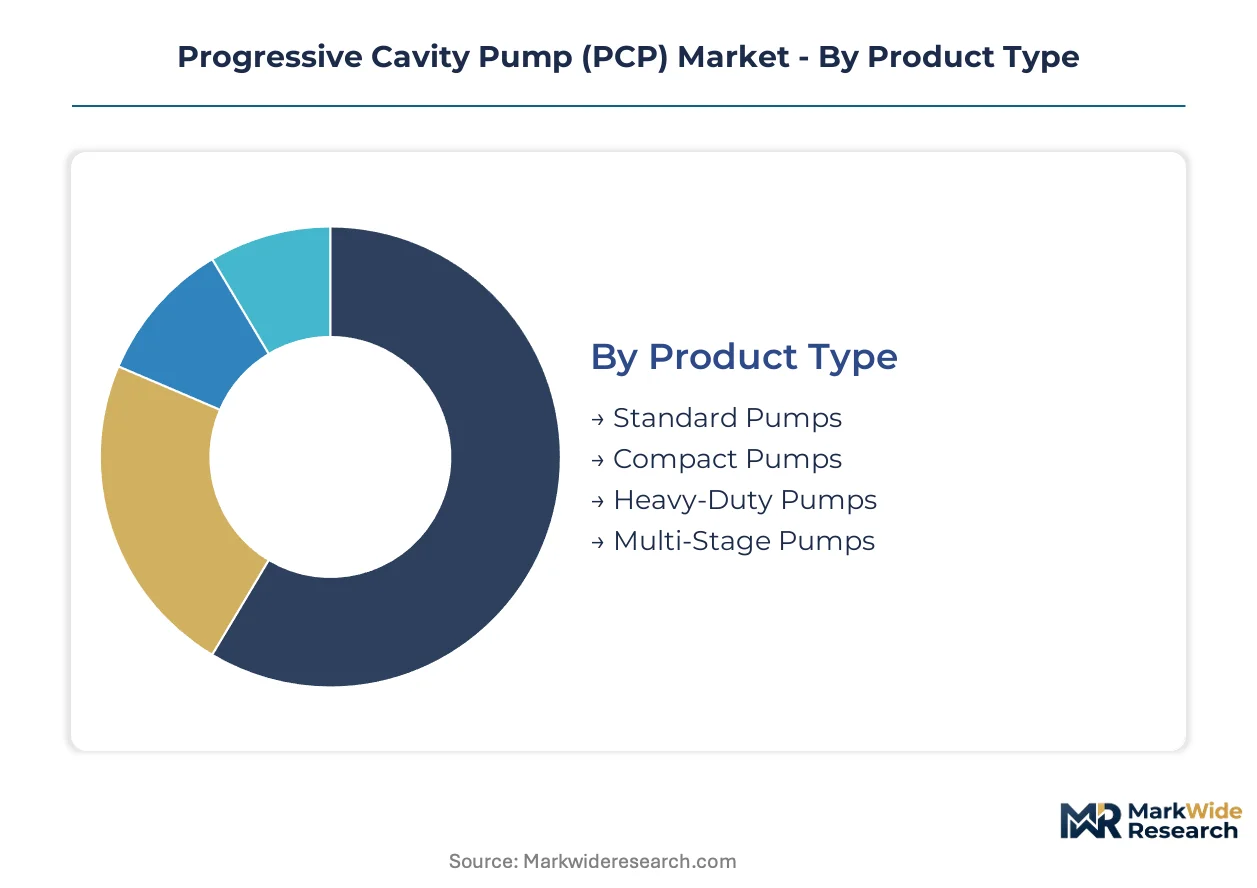
Segmentation in the Progressive Cavity Pump market reveals how rotor-stator geometry, elastomer chemistry, and drive configurations align with distinct operating environments. Each dimension carries implications for procurement strategy, lifecycle cost modeling, and vendor selection criteria across upstream oilfield and process industry deployments.
Product Type:
Mature configurations dominate installed bases while emerging geometries capture replacement cycles and greenfield specifications.
- Heavy-Duty Pumps:Reinforced bearing frames and hardened rotor coatings withstand abrasive multiphase flow in thermal EOR operations. Permian Basin operators specify these for high-sand-cut production where standard stator compounds fail within weeks. API 676 vibration compliance mandates are accelerating replacement of legacy pump trains with heavy-duty architectures in US downstream facilities.
- Multi-Stage Pumps:Stacked rotor-stator modules in series configuration achieve discharge pressures exceeding 48 bar for deep reservoir drawdown. Canadian oil sands SAGD projects and Venezuelan Orinoco heavy crude operations are the primary demand centers as operators push into high-pressure formations. Thermoset elastomer advances extending stator life by 40% are penetrating these installations fastest.
- Standard Pumps:Fixed-geometry single-stage designs serve polymer dosing and sludge transfer in municipal wastewater networks.
- Compact Pumps:Reduced footprint configurations fit restricted wellpad spacing below 500 feet in unconventional shale developments.
Heavy-duty pumps retain volume leadership; multi-stage pumps hold the steepest expansion curve.
Application:
Application segmentation tracks fluid rheology demands and regulatory exposure intensity across process environments.
- Oil & Gas:Artificial lift deployment in heavy crude extraction requires pumps handling viscosities from 100 to 10,000 cP with entrained gas fractions. Unconventional well spacing in North American shale basins and thermal EOR projects in California concentrate demand. EPA emissions standards and API specifications tighten seal and material requirements for surface and downhole installations.
- Chemical Processing:Hermetic designs for aggressive reagent transfer and polymer synthesis demand fluorocarbon or perfluoroelastomer stator compounds. REACH compliance governs elastomer chemistry qualification cycles for European chemical processing customers. EU F-Gas Regulation indirectly influences PCP specification in refrigeration circuits where hermetic designs replace compressor-dependent systems.
- Wastewater Treatment:Abrasion-resistant nitrile stators handle primary sludge and thickened waste activated sludge with high solids content.
- Food & Beverage:FDA-compliant elastomer formulations and sanitary surface finishes serve high-viscosity product transfer and CIP-compatible installations.
Oil & Gas commands the largest revenue share; Chemical Processing is expanding most quickly on process intensification trends.
End User:
End user segmentation distinguishes capital intensity tolerance and technical support requirements across operating models.
- Industrial Sector:Continuous-duty process applications in refining, petrochemicals, and manufacturing demand predictive maintenance platforms and rapid spare parts availability. Mid-size operators lacking in-house artificial lift engineering prefer single-vendor accountability for run-life performance. Integrated service contracts bundling hardware, elastomer replacement, and remote diagnostics are displacing traditional capital purchase models.
- Agriculture Sector:Manure handling and biogas feedstock transfer applications prioritize initial cost over lifecycle optimization.
- Marine Sector:Offloading pumps and bilge systems require explosion-proof certifications and compact footprints in engine room constraints.
- Residential Sector:Septic tank effluent and small-scale water pressure boosting represent minimal market presence.
Industrial Sector retains volume leadership; Marine Sector is gaining share fastest on offshore heavy oil development.
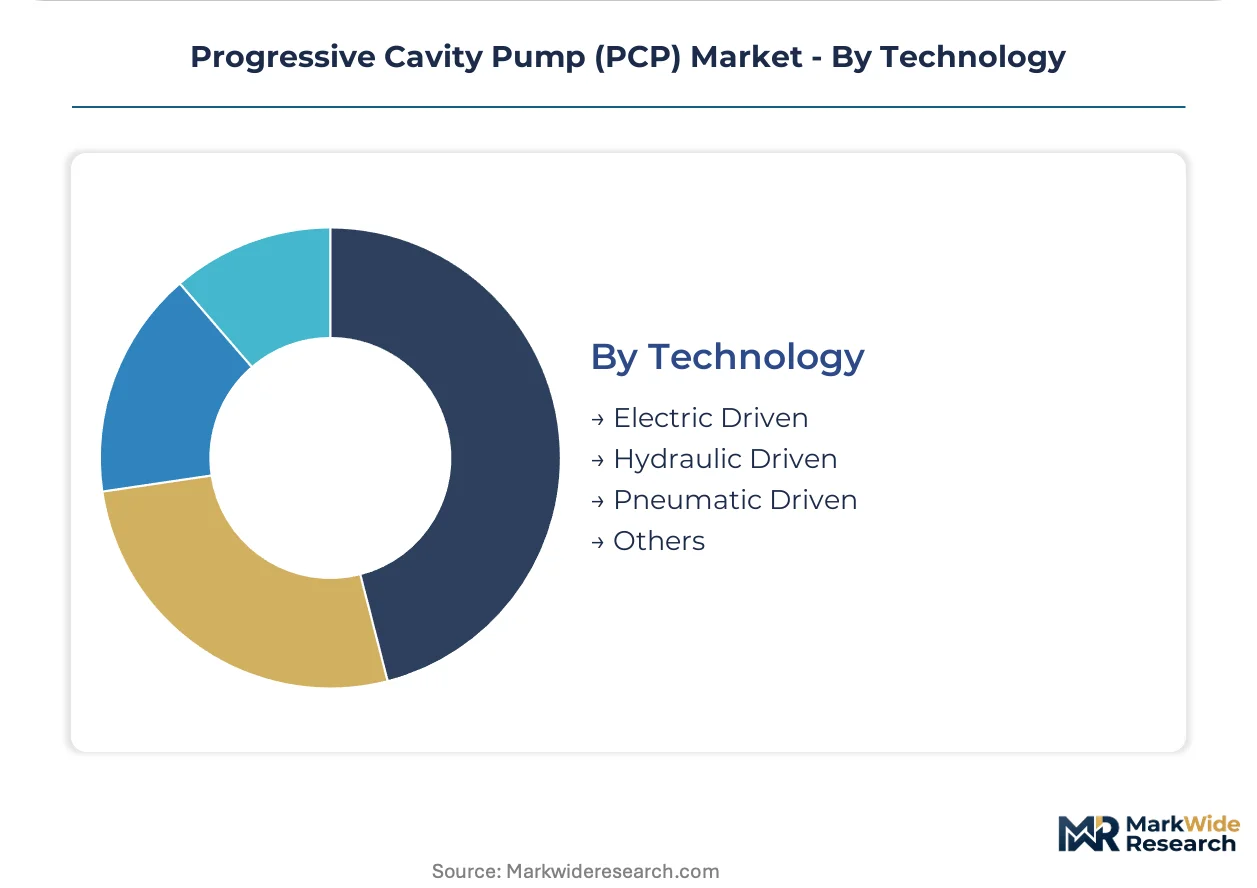
Technology:
Technology segmentation reflects power availability, safety zone classification, and torque control precision requirements.
- Electric Driven:Variable frequency drive compatibility and precise flow control dominate industrial and upstream installation counts. Downhole sensor integration for temperature and pressure transmitters must survive 150°C operating environments while maintaining API 11AX electrical safety ratings. Digital twin deployment across wellpad networks is compressing maintenance cycles and forcing sensor-ready stator geometries.
- Hydraulic Driven:Intrinsic safety in explosion-risk zones and subsea applications where electrical isolation matters retains critical roles. Hydraulic power units eliminate spark ignition hazards in offshore platforms and tank farm installations.
- Pneumatic Driven:Limited to portable utility applications and hazardous atmosphere zones without electrical infrastructure.
- Others:Emerging drive configurations including hybrid electric-hydraulic systems for torque-limited well interventions.
Electric Driven retains volume leadership; Hydraulic Driven is climbing the fastest on subsea and safety-critical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-molded stator liners and hydrogenated nitrile compounds to Canadian oil sands operators and US Permian Basin developers, anchoring the trade corridor for high-performance elastomer components.
United States
Permian Basin well spacing below 500 feet drives compact PCP configurations, while EPA underground injection control revisions mandate real-time pressure containment verification for brine disposal pumps. Houston-Gulf Coast clusters concentrate artificial lift service bundling and downhole diagnostics integration.
Canada
Alberta SAGD thermal operations and steam-assisted heavy crude extraction push multi-stage pump demand for high-pressure reservoir drawdown. Environment and Climate Change Canada emissions protocols tighten seal specifications for surface processing equipment. Calgary-Edmonton corridor hosts integrated service contracts bundling hardware with predictive maintenance platforms.
Germany
REACH chemical authorization timelines for curative agents extend stator manufacturing qualification cycles, while precision elastomer compounders control hydrogenation catalyst access for premium stator liners. NETZSCH Holding GmbH & Co. KG anchors chemical and food-grade pump manufacturing in Waldkraiburg, with Seepex GmbH modular designs serving field retrofit demand across European process industries.
Brazil
Pre-salt heavy oil tiebacks off Santos Basin lack proven subsea artificial lift solutions, creating specification gaps for seabed processing architectures. ANP regulatory frameworks for offshore equipment certification shape import requirements for downhole pump systems. Rio de Janeiro-Petrópolis industrial corridor concentrates local assembly partnerships with international service providers.
China
Shale gas development in Sichuan Basin and coalbed methane operations in Shanxi Province expand artificial lift deployment for multiphase flow handling. MIIT equipment safety standards and GB technical regulations govern pump certification for explosive atmosphere zones. Yangtze River Delta manufacturing clusters produce cost-competitive standard pumps for domestic wastewater and agricultural applications.
Progressive Cavity Pump (PCP) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct value-capture positions. The vendor base organizes around three strategic archetypes: precision elastomer compounders with captive stator manufacturing, integrated oilfield service bundlers combining hardware with remote diagnostics, and modular design specialists enabling rapid field reconfiguration. Dominant competitive moves include backward integration into hydrogenated nitrile compound production and geographic expansion through local assembly partnerships in high-growth basins.
Among Germany-based precision manufacturers, NETZSCH Holding GmbH & Co. KG and Seepex GmbH exemplify the product-specialist archetype, occupying positions anchored in elastomer chemistry expertise and modular architecture respectively. Schlumberger Limited represents the integrated service bundler model, sitting within the channel-controlling tier through artificial lift service packaging. These three entities illustrate how competitive positioning splits between compound-level technical differentiation and service-level accountability for run-life performance.
| Leading Market Players |
|---|
| Xylem Inc |
| Seepex GmbH |
| Schlumberger Limited |
| Roto Pumps Limited |
| Weatherford International plc |
| NETZSCH Holding GmbH & Co. KG |
| PCM S.A. |
| Pumpenfabrik Wangen GmbH |
| National Oilwell Varco, Inc. |
| Others |
Supply Flow & Price Mechanics
Waldkraiburg's precision elastomer manufacturing cluster dictates pricing power for hydrogenated nitrile stator liners, with German compounders capturing premium tiers while Asian manufacturers compete on standard pump configurations. This geographic concentration of specialty elastomer production creates asymmetric margin structures across the value chain.
Pricing Analysis
Next-generation additive-manufactured rotor geometries command substantial premiums over conventional ground-steel designs, while legacy fixed-pitch rotors face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates API 676-certified heavy-duty configurations from compact shale-field units and municipal wastewater pumps. Cost compression in standard pump tiers stems from Yangtze River Delta manufacturing scale. Mid-size E&P operators show highest price sensitivity, prioritizing integrated service contracts over capital purchase models.
Supply Chain Analysis
German and Japanese export controls on hydrogenation catalyst technologies constrain stator liner production capacity expansion outside established compounders. Precision-molded elastomer manufacturing draws from hydrogenated nitrile rubber, specialized curative agents, and precision grinding equipment. Single-source vulnerability concentrates in catalyst supply for premium stator compounds. Distribution runs through oilfield service bundlers in Houston-Gulf Coast clusters and direct OEM channels for process industry applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platform economics are restructuring vendor-customer relationships, with predictive maintenance interoperability becoming the decisive ecosystem battleground for artificial lift accountability.
For Market Incumbents: Build predictive maintenance data moats by embedding sensor-ready stator geometries from mold design through field deployment. Backward integration into hydrogenated nitrile compound production secures catalyst-constrained supply positions against emerging Asian compounders. Prioritize API 11AX-certified downhole sensor integration to defend against centrifugal pump substitution in dilbit blending applications. For New Entrants and Emerging Players: Subsea PCP deployment for Brazilian pre-salt heavy oil tiebacks represents the most penetrable entry point, with seabed processing architectures lacking proven artificial lift solutions. EU F-Gas Regulation-driven hermetic pump circuits in industrial heat pumps offer second-mover advantage in food processing applications. Partner with local assembly operations in Rio de Janeiro-Petrópolis corridor to satisfy ANP offshore certification requirements. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because integrated service contracts bundling hardware, elastomer replacement, and remote diagnostics displace capital purchase models. Target precision elastomer compounders with captive hydrogenation catalyst access. Watch for inflection when real-time rotor-stator clearance monitoring achieves sufficient predictive accuracy to decouple stator replacement from equipment ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive hydrogenated nitrile production insulates against German-Japanese catalyst supply concentration. |
| Digital Twin Service Bundling | Predictive stator replacement contracts shift revenue from equipment sale to performance accountability. |
| Subsea PCP Development Partnership | Seabed processing architectures for Brazilian pre-salt fields lack proven artificial lift solutions. |
| Sensor-Ready Stator Geometry Integration | Embedded temperature and pressure transmitters survive 150°C environments while maintaining API 11AX ratings. |
| Local Assembly Partnership in High-Growth Basins | Rio de Janeiro-Petrópolis corridor operations satisfy ANP regulatory frameworks for offshore equipment certification. |
Methodological Framework
Initial hypotheses were tested against primary input from artificial lift engineering directors, elastomer compounder R&D leads, E&P procurement managers, and oilfield service operations heads and refined through secondary validation. Sources included API certification databases, EPA underground injection control filings, REACH substance registration data, and customs trade records for hydrogenated nitrile compounds. Bottom-up wellpad deployment counts and top-down artificial lift service revenue estimates were triangulated.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by pressure rating and elastomer chemistry, application segmentation by fluid rheology requirements, and technology segmentation by drive configuration safety classification. CAGRs were derived from replacement cycle compression in shale basins and greenfield specification shifts toward multi-stage configurations. Forecast inputs included SAGD thermal EOR project timelines and EPA regulatory revision implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands or North American shale drilling activity would shift the trajectory. Forecasts reflect assumptions on elastomer life extension rates and digital twin adoption curves. Material shifts in REACH chemical authorization timelines or subsea PCP technical validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Seawater Pump Market