
 Bridge Bearing Pad Market | 2026-2036
Bridge Bearing Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Bearing Pad Market Insights
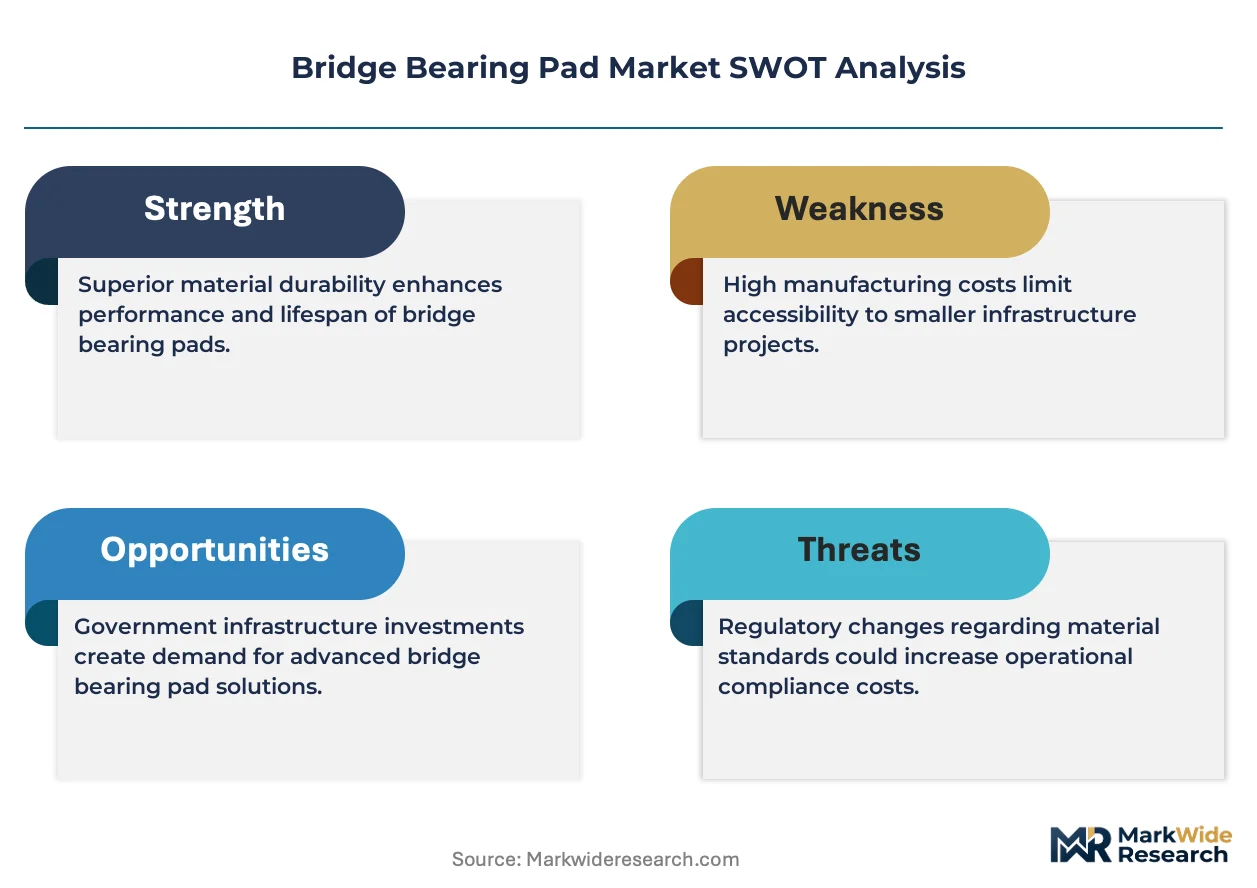
Performance-based maintenance contracts is shifting how agencies procure bridge bearing systems across extended service intervals. Trelleborg leverages polymer compounding expertise to sustain specification leadership in seismic-rated elastomeric designs. Mageba anchors European rail infrastructure with specialized guided bearing systems for high-speed track interfaces. Freyssinet competes through integrated supply of structural bearings plus installation supervision, extending contractor accountability beyond material delivery.
A bridge bearing pad is a structural interface element, typically fabricated from reinforced elastomeric compounds or steel-pot assemblies with PTFE sliding surfaces, engineered to transmit vertical loads while accommodating horizontal translation, rotation, and thermal movement in bridge superstructures. Elastomeric bearings dominate highway applications due to cost efficiency and proven fatigue resistance under cyclic loading. Steel-reinforced pot bearings capture premium rail bridge contracts where higher load capacities and controlled rotation define specifications. Composite material formulations are gaining specification share in corrosive environments where traditional rubber degradation accelerates replacement demand.
The Federal Highway Administration enforces National Bridge Inspection Standards that mandate load-path verification, directly stimulating bearing replacement cycles across state-managed inventories. AASHTO LRFD specifications govern material testing and performance certification, creating compliance barriers for uncertified suppliers. European Committee for Standardization EN 1337 series defines bearing design methods and factory production control requirements. Stakeholders must monitor evolving sustainability mandates in public procurement frameworks, as embodied carbon thresholds begin penetrating infrastructure material selection criteria.
Market Dynamics
Federal Highway Administration load-rating mandates are compressing replacement cycles for aging bridge infrastructure, forcing state agencies into accelerated procurement schedules for certified bearing systems.
Growth Catalysts
- Highway Rehabilitation Mandates:The Federal Highway Administration's National Bridge Inspection Standards require systematic load-path verification, triggering bearing replacement across state-managed inventories.
- Elastomeric Material Advancements:Reinforced elastomeric compounds with enhanced fatigue resistance under cyclic loading are capturing specification share in highway bridge applications.
- Rail Infrastructure Modernization:Germany's federal trunk road bridge inventories require systematic bearing upgrades, concentrating demand for high-capacity steel-reinforced pot bearings.
Market Restraints
- Raw Material Volatility:Natural rubber and synthetic polymer feedstock price swings compress margin stability for compound formulators serving infrastructure projects.
- Certification Barriers:AASHTO LRFD specifications create compliance hurdles for uncertified suppliers, limiting market entry for regional manufacturers.
- Steel-Pot Substitution Limits:Elastomeric bearings cannot displace steel-reinforced pot bearings in premium rail bridge contracts where controlled rotation defines specifications.
Strategic Opportunities
- Corrosion-Resistant Formulations:Composite material bearings are gaining specification share in coastal and de-icing salt environments where traditional rubber degradation accelerates replacement demand.
- Sustainability Procurement Mandates:Embodied carbon thresholds in European public procurement frameworks are rewriting material selection criteria for infrastructure projects.
- Seismic-Rated System Demand:High-speed rail expansion across Japan and Taiwan is creating specification pull for guided bearing systems with multi-directional movement capacity.
Industry Challenges
- Skilled Installation Labor Scarcity:Precision alignment of PTFE sliding surfaces and pot bearing assemblies requires certified technicians, creating bottleneck conditions during peak construction seasons.
- Factory Production Control Audits:EN 1337 series factory production control requirements impose recurring compliance costs and documentation burdens on European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Bearing Pad Market |
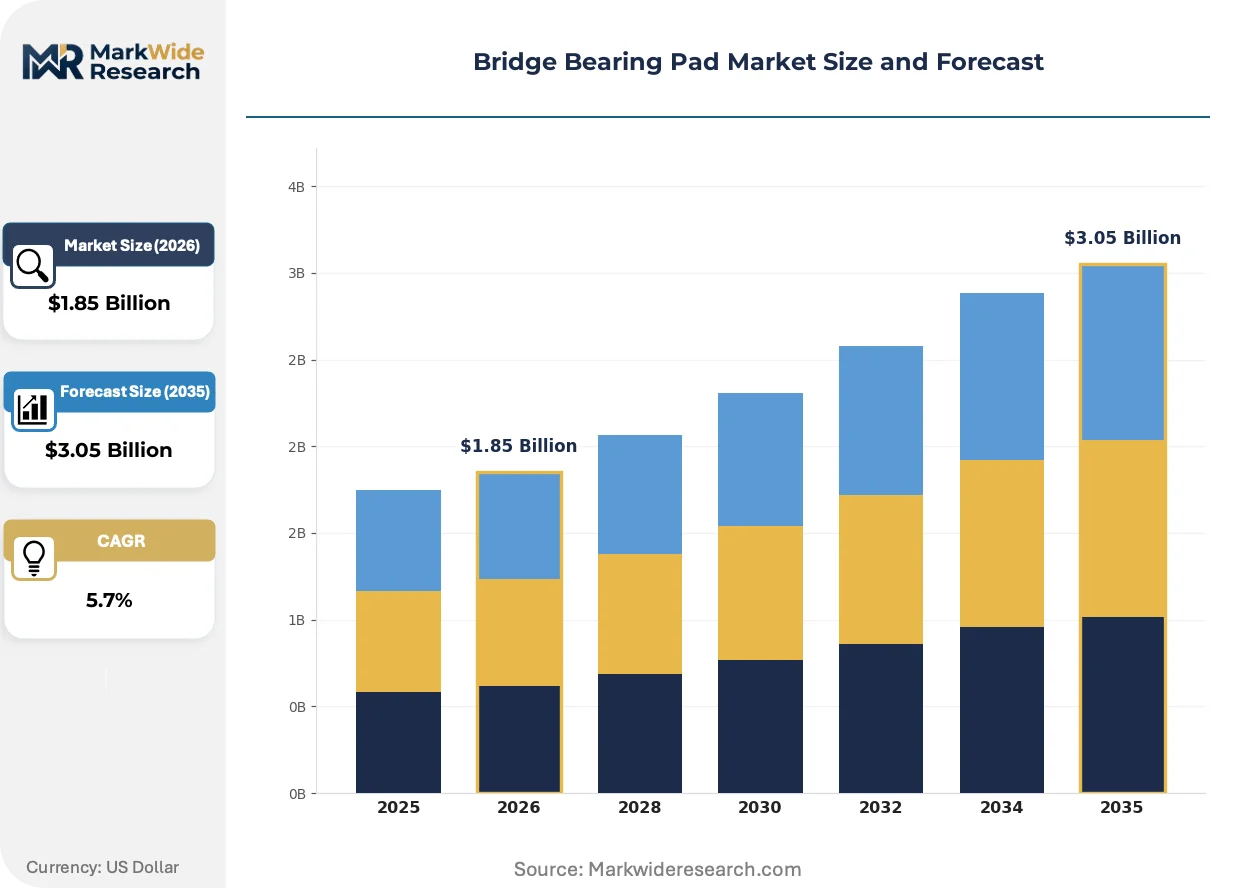
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastomeric, Sliding, Pot, Other Material: Rubber, Steel, Composite, PTFE Application: Highway Bridges, Rail Bridges, Pedestrian Bridges, Overpasses End User: Construction Companies, Government Agencies, Engineering Firms, Contractors |
| Companies Covered | Trelleborg, Freyssinet, Mageba, Vossloh, Granor, RJ Watson, Canam Group, DS Brown, Scougal Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Bearing Pad Market Trends and Innovations
Material science breakthroughs and procurement model evolution are compressing traditional specification hierarchies, enabling hybrid bearing systems to capture share from established product categories.
Shape-memory alloy dampers integrated into elastomeric bearing cores are rewriting seismic performance benchmarks for bridge infrastructure. State transportation departments in California and Japan are specifying these systems for fault-zone crossings. The technology is compressing traditional seismic isolation procurement into single-source bearing contracts.
REACH substance restrictions on polycyclic aromatic hydrocarbons in rubber compounds are forcing compound reformulation across European supply chains. Manufacturers must certify alternative plasticizers and curing agents through extended testing protocols. German and French infrastructure agencies are prioritizing suppliers with verified low-PAH compound streams.
Performance-based maintenance contracts now bundle bearing supply with multi-decade service intervals, displacing traditional unit-price procurement. State DOTs in Texas and Florida are piloting these arrangements for major corridor rehabilitations. The model concentrates vendor accountability and is compressing supplier qualification timelines.
Bridge Bearing Pad Market Segmentation
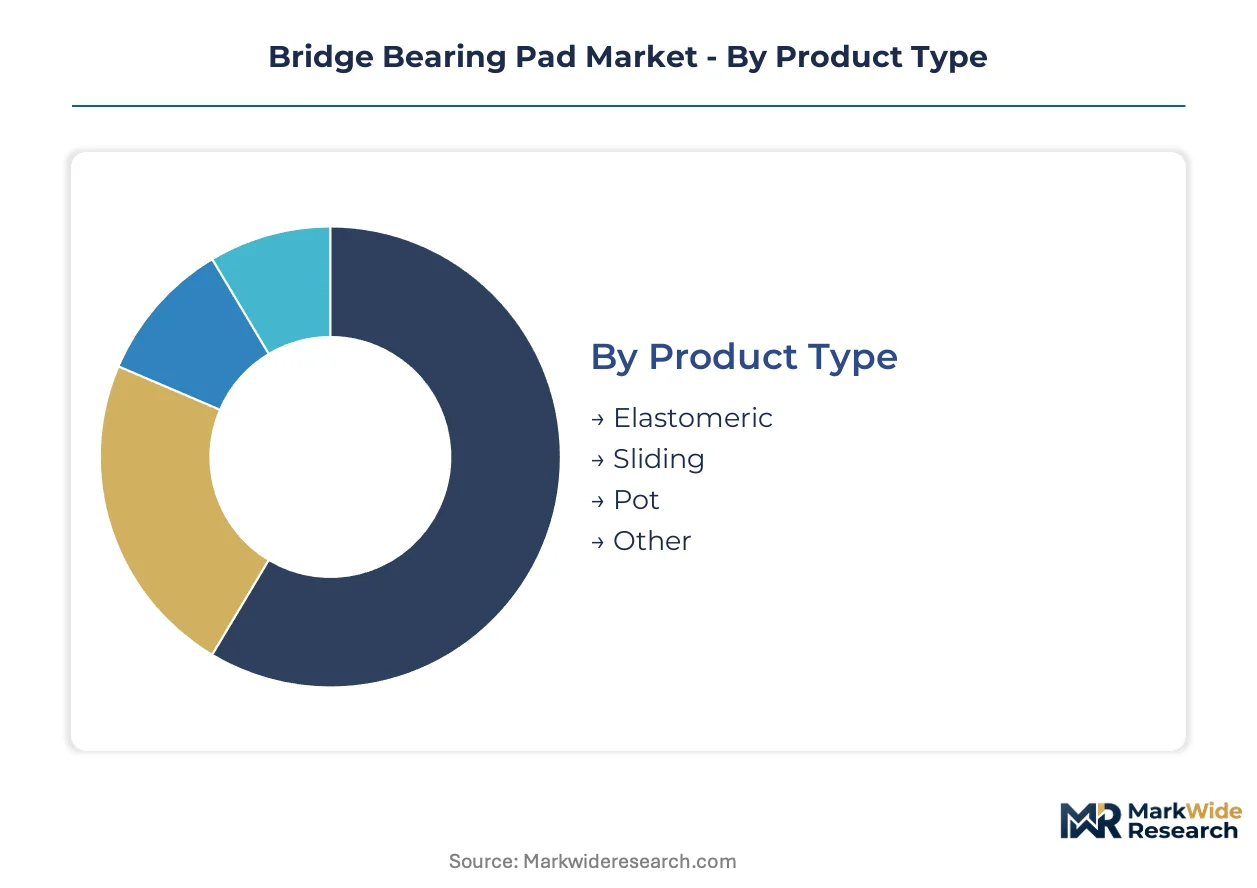
Bridge bearing pad procurement splits across specification hierarchies where load capacity, movement accommodation, and environmental exposure dictate material selection. Federal mandates and rail modernization programs concentrate demand in distinct product categories with divergent certification requirements.
Product Type:
Specification differentiation tracks load-bearing capacity and multi-directional movement requirements across infrastructure classes.
- Elastomeric:Fabricated from reinforced natural or synthetic rubber compounds with embedded steel shims, these bearings transmit vertical loads while accommodating horizontal translation and rotation through elastic deformation. Highway bridge rehabilitation programs in the United States are expanding procurement of these systems as the Federal Highway Administration mandates load-rating assessments that accelerate replacement cycles.
- Sliding:PTFE-stainless steel interfaces enable controlled horizontal movement under heavy vertical loads, with low-friction coefficients maintaining structural integrity during thermal expansion cycles. Germany's federal trunk road bridge inventories require systematic bearing upgrades, concentrating demand for guided sliding configurations in high-speed rail interfaces.
- Pot:Steel-reinforced elastomeric discs confined within precision-machined steel housings deliver controlled rotation capacity for heavy rail applications.
- Other:Spherical bearings and disc bearings serve specialized seismic isolation and curved alignment scenarios.
Mature deployment sits with Elastomeric bearings in highway rehabilitation. Newer deployment is concentrated in Sliding systems for rail corridor modernization.
Material:
Compound selection balances fatigue resistance, environmental degradation tolerance, and embodied carbon thresholds in public procurement frameworks.
- Rubber:Natural and synthetic elastomer formulations with carbon black reinforcement and anti-oxidant packages dominate cost-sensitive highway contracts. REACH substance restrictions on polycyclic aromatic hydrocarbons are forcing compound reformulation across European supply chains.
- Steel:High-yield structural steel housings and confinement rings define pot bearing assemblies for premium rail applications. Fabrication concentrates in certified foundries with EN 1337 factory production control audits.
- Composite:Fiber-reinforced polymer formulations resist de-icing salt and coastal corrosion where traditional rubber degradation accelerates replacement demand.
- PTFE:Virgin and filled polytetrafluoroethylene sliding surfaces enable low-friction movement in guided bearing systems.
Volume leadership belongs to Rubber compounds. Steepest expansion trajectory is occurring in Composite formulations for corrosion-critical environments.
Application:
Structural movement patterns and load spectra create distinct specification regimes across bridge infrastructure categories.
- Highway Bridges:Multi-span concrete and steel superstructures with thermal expansion ranges of 50-150mm drive standardized elastomeric bearing procurement. State transportation departments in California and Japan are specifying shape-memory alloy dampers integrated into bearing cores for fault-zone crossings.
- Rail Bridges:Controlled rotation and longitudinal restraint requirements under rolling stock dynamic loads mandate steel-reinforced pot bearings with guided sliding surfaces. High-speed rail expansion across Japan and Taiwan is creating specification pull for multi-directional movement capacity.
- Pedestrian Bridges:Lower load magnitudes enable simplified elastomeric pad configurations with reduced shim reinforcement.
- Overpasses:Urban corridor structures with constrained maintenance access favor sealed bearing systems with extended service intervals.
Replacement volume concentrates in Highway Bridges. Greenfield deployment is climbing the fastest in Rail Bridges for high-speed corridor expansion.
End User:
Procurement authority and risk allocation determine contracting structures and vendor qualification requirements.
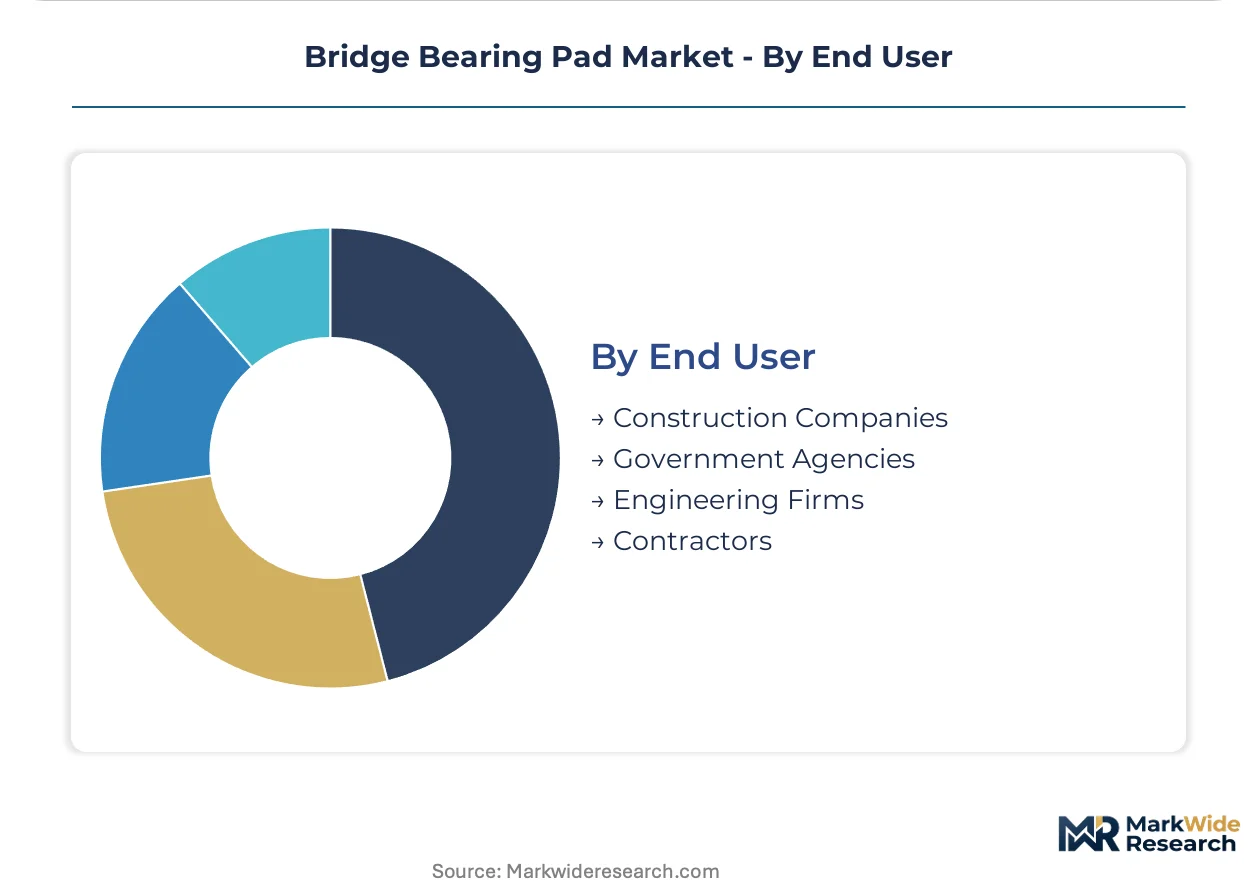
- Construction Companies:General contractors executing design-bid-build highway projects procure certified bearing systems through competitive bidding with AASHTO LRFD compliance documentation.
- Government Agencies:State departments of transportation and federal highway administrations administer performance-based maintenance contracts bundling bearing supply with multi-decade service intervals, displacing traditional unit-price procurement in Texas and Florida pilot programs.
- Engineering Firms:Design consultants specify bearing types during preliminary engineering, influencing downstream procurement through performance criteria embedded in contract documents.
- Contractors:Specialized bridge rehabilitation contractors bear installation risk for precision alignment of PTFE sliding surfaces and pot bearing assemblies.
Contracting authority sits with Government Agencies. Procurement innovation is gaining share fastest through Construction Companies adopting performance-based arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge bearing pad production concentrates in Germany and Japan, while consumption pulls strongest from United States highway rehabilitation programs and Chinese rail corridor expansion. This geographic split creates trade flows where certified manufacturers in industrialized economies supply infrastructure booms in high-growth markets.
United States
Federal Highway Administration load-rating mandates are compressing replacement cycles across state-managed bridge inventories. The National Bridge Inspection Standards require systematic load-path verification, triggering accelerated procurement schedules for AASHTO LRFD-certified bearing systems. State transportation departments in California and Texas are piloting performance-based maintenance contracts that bundle bearing supply with multi-decade service intervals.
Germany
Federal trunk road bridge inventories require systematic bearing upgrades, concentrating demand for high-capacity steel-reinforced pot bearings and guided sliding configurations. The European Committee for Standardization EN 1337 series defines factory production control requirements, creating compliance barriers for uncertified suppliers. Industrial clusters in North Rhine-Westphalia and Bavaria host precision-machined steel housing fabricators serving premium rail applications.
China
High-speed rail expansion across eastern provinces is creating specification pull for multi-directional movement capacity in guided bearing systems. The Ministry of Ecology and Environment enforces dual carbon goals that are rewriting material selection criteria for infrastructure projects. Manufacturing concentration in the Yangtze River Delta supplies domestic rail modernization while exporting elastomeric compounds to Southeast Asian markets.
Japan
Seismic isolation procurement is compressing into single-source bearing contracts as state agencies specify shape-memory alloy dampers integrated into elastomeric cores for fault-zone crossings. The Ministry of Economy, Trade and Industry governs JIS standards for structural bearings used in rail infrastructure. Industrial capacity clusters in the Chubu region around Nagoya supply precision PTFE sliding surfaces for high-speed track interfaces.
India
National highway widening programs and dedicated freight corridors are expanding procurement of reinforced elastomeric bearing systems for multi-span concrete superstructures. The Bureau of Indian Standards mandates testing protocols for bridge bearings used in public infrastructure projects. Manufacturing activity concentrates in Gujarat and Maharashtra, where compound formulators serve state bridge authorities with cost-optimized rubber formulations.
Bridge Bearing Pad Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bridge bearing pad market, with integrated foundries and polymer compounders facing specialized installation contractors. The structure tilts toward consolidation at the premium tier, where EN 1337 certification and AASHTO LRFD compliance create qualification barriers. Three archetypes dominate: integrated elastomer compounders, precision steel fabricators, and full-service installation supervisors. Competitive moves center on backward integration into polymer feedstocks and geographic expansion through local certification partnerships.
Among European-anchored specialists, Trelleborg exemplifies the integrated compounder archetype, while Mageba occupies a position within precision steel fabrication for rail applications. Freyssinet represents the installation-supervision model, extending contractor accountability beyond material delivery through integrated supply chains. These three patterns illustrate how specification leadership in seismic-rated designs, high-speed track interfaces, and performance-based contracting each demand distinct capability configurations.
| Leading Market Players |
|---|
| Trelleborg |
| Freyssinet |
| Mageba |
| Vossloh |
| Granor |
| RJ Watson |
| Canam Group |
| DS Brown |
| Scougal Rubber |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between AASHTO LRFD-certified systems and uncertified regional alternatives manifests in both pricing stratification and supply chain configuration, with premium-tier producers commanding project-based long-term contracts while commodity suppliers compete on per-unit spot pricing. This bifurcation concentrates procurement authority among certified compounders in Germany and Japan, forcing price-sensitive state DOTs into dual-sourcing arrangements that balance compliance assurance against budget constraints.
Pricing Analysis
Margin tightening in elastomeric bearing tiers reflects raw material volatility in natural rubber and synthetic polymer feedstocks, compressing compound formulators serving infrastructure projects. Three-tier pricing structure across premium EN 1337-certified, standard AASHTO-compliant, and economy non-certified levels tracks certification investment and factory production control audit burdens. Cost-down pressure on highway rehabilitation contracts accelerates because state agencies prioritize lowest responsive bids for standardized elastomeric pads. Construction companies exhibit highest price sensitivity, while rail infrastructure authorities demonstrate lowest sensitivity given controlled rotation specifications that mandate steel-reinforced pot bearings.
Supply Chain Analysis
Dual-sourcing requirements from state DOTs and federal highway administrations mandate qualified supplier redundancy across certified bearing manufacturers. Geographic supply concentration centers on Germany, Japan, and the United States, with precision-machined steel housing fabricators clustering in North Rhine-Westphalia and Bavaria. Raw material dependencies draw from natural rubber plantations in Southeast Asia, high-yield structural steel from integrated foundries, and virgin PTFE resin from fluoropolymer specialists. Single-source vulnerability persists for seismic-rated elastomeric cores with shape-memory alloy dampers. Distribution runs through specialized bridge rehabilitation contractors and direct procurement channels to government agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics dominate competitive positioning as compounders pursue captive supply of polymer feedstocks and installation contractors acquire precision fabrication capabilities to capture performance-based maintenance contract premiums.
For Market Incumbents: Anchor specification leadership through backward integration into certified polymer compound streams and EN 1337 factory production control audit maintenance. Defend against emerging composite material substitutes by deepening fatigue resistance testing protocols for reinforced elastomeric designs. Prioritize capacity positioning in high-speed rail corridor geographies to capture guided bearing system demand. For New Entrants and Emerging Players: The price-point gap between premium pot bearings and economy elastomeric pads opens white-space targeting for corrosion-resistant composite formulations in coastal infrastructure markets. Underpenetrated specification share exists for seismic isolation systems with multi-directional movement capacity in fault-zone geographies. Target state DOT pilot programs for performance-based maintenance contracts as the most penetrable procurement innovation channel, leveraging installation supervision capabilities as primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with integrated compounder-foundry hybrids given embodied carbon threshold enforcement in European public procurement frameworks. Long-term viability over the analysis window favors manufacturers with dual AASHTO LRFD and EN 1337 certification portfolios spanning highway and rail applications. Monitor REACH substance restriction enforcement on polycyclic aromatic hydrocarbons as inflection indicator for compound reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive natural rubber supply insulates margin stability from Southeast Asian commodity price swings. |
| Performance-Based Maintenance Contract Expansion | Texas and Florida DOT pilots demonstrate multi-decade service interval bundling concentrates vendor accountability. |
| Composite Material Formulation Development | Fiber-reinforced polymer bearings capture specification share in de-icing salt and coastal corrosion environments. |
| Seismic-Rated System Certification Investment | Shape-memory alloy damper integration qualifies suppliers for California and Japan fault-zone crossing contracts. |
| Geographic Certification Partnership Expansion | Local EN 1337 and AASHTO LRFD qualification partnerships enable market entry in high-growth rail corridors. |
Research Methodology
Multi-period observation of Federal Highway Administration load-rating mandate implementation, state DOT procurement schedule acceleration, and EN 1337 factory production control audit compliance anchored the trend analysis, supplemented by interviews with bridge rehabilitation contractors, state transportation department procurement officers, polymer compound R&D directors, and structural bearing installation supervisors. Secondary validation drew from FHWA National Bridge Inventory data, AASHTO LRFD specification updates, European Committee for Standardization EN 1337 series documentation, and customs trade records for elastomeric compound imports. Bottom-up project pipeline tracking and top-down infrastructure spending allocation models were triangulated to verify demand estimates.
Input-output matrix framing connected raw material feedstock availability through compound formulation capacity to finished bearing system output across product type, material grade, application category, and end-user procurement structure dimensions. Modeled segmentation captured elastomeric versus steel-reinforced pot versus sliding versus spherical bearing architectures; rubber, steel, composite, and PTFE material classes; highway bridge, rail bridge, pedestrian bridge, and overpass applications; and construction company, government agency, engineering firm, and specialized contractor end-user channels. CAGRs were derived from infrastructure spending trajectory alignment with replacement cycle compression factors. Forecast inputs incorporated seismic isolation procurement consolidation patterns and REACH substance restriction compliance timelines.
Inputs from FHWA bridge inspection databases and state DOT capital improvement programs were available through the study window; gaps in real-time project award data and proprietary compound formulation specifications introduce uncertainty bands around near-term demand timing. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and infrastructure funding authorization levels. Deviation in federal highway rehabilitation appropriation levels or REACH PAH restriction implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Europe Facade Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Concrete Slabs Market