
 Structural Lightweight Concrete Market | 2026-2036
Structural Lightweight Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Lightweight Concrete Market Insights
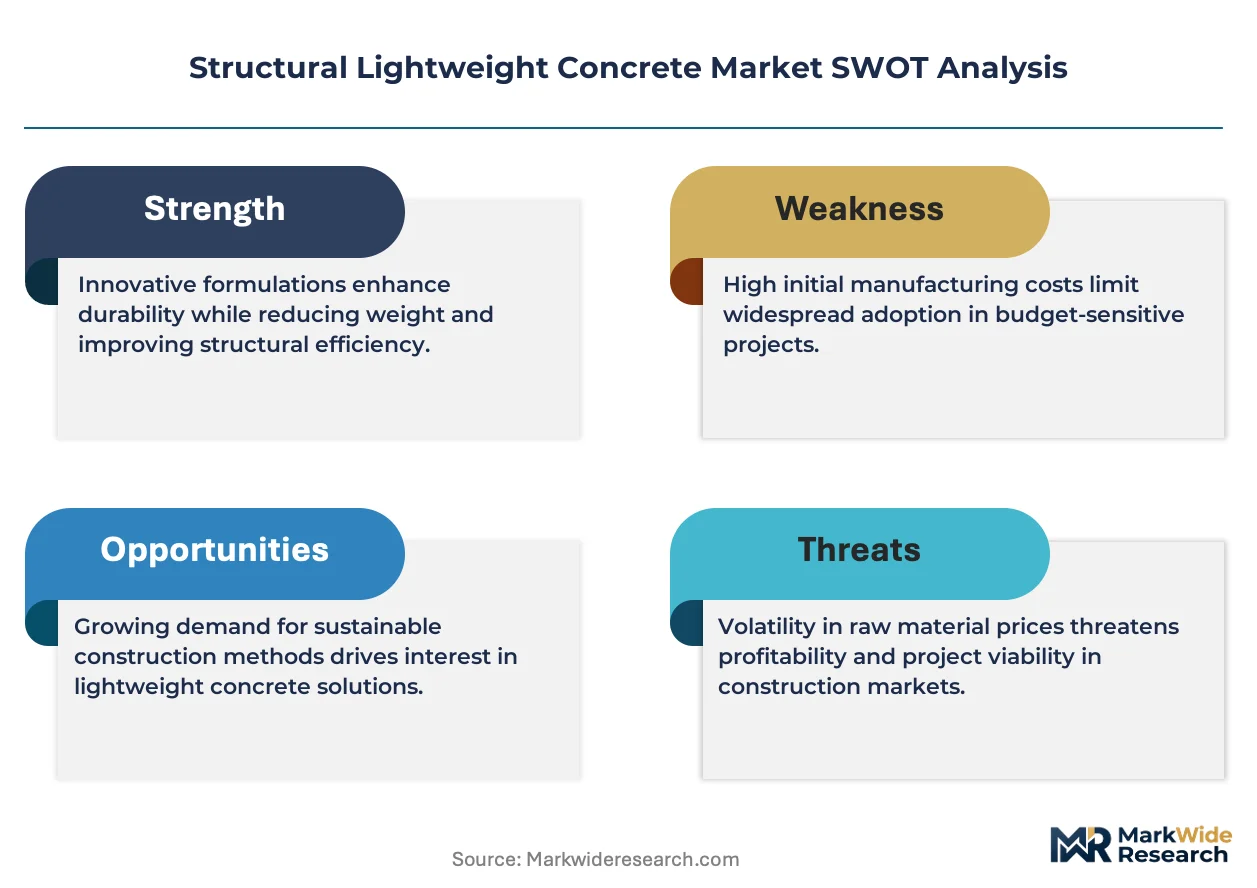
Performance-based maintenance contracts is decoupling capital expenditure from lifecycle value in structural lightweight concrete procurement. Cemex S.A.B. de C.V. leverages its vertically integrated aggregate network to secure supply continuity for expanded clay operations across Mexico and the southern United States. Heidelberg Materials AG anchors European specification through its EN 206-compliant production footprint and technical advisory services tied to large infrastructure tenders. Sika AG differentiates via admixture-curing system bundles that reduce permeability in air-dried lightweight placements.
Structural lightweight concrete incorporates low-density aggregates such as expanded clay, shale, or pumice to achieve dry densities between 300 and 1850 kg per cubic metre while maintaining specified compressive strength for load-bearing elements. The material primarily serves applications where reduced self-weight translates to smaller foundations, longer spans, or improved seismic response in framed structures. Expanded clay aggregate commands the dominant share of product type demand due to its controlled porosity and consistent thermal performance across climates. Bridge decks and high-rise buildings represent the fastest-expanding application clusters as engineers optimize for dead-load reduction in long-span and vertical construction. Precast concrete elements carry concentrated margin pools because factory-controlled curing enables tighter dimensional tolerances and lower cement factors than site-cast alternatives.
ASTM C330 governs aggregate qualification for structural lightweight concrete in the United States, while EN 206 and EN 13055 set parallel requirements across European member states; compliance with these standards determines market access for both domestic producers and importers. The EU Green Deal and national building codes in Germany and France tighten embodied carbon thresholds, pushing specification toward aggregates with lower kiln-energy intensity such as expanded slag. Stakeholders must monitor evolving carbon accounting methodologies and regional aggregate scarcity patterns to align capacity investments with where regulatory pressure and construction volume intersect most intensely.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing specification windows for structural lightweight concrete across European construction tenders, forcing aggregate selection toward lower kiln-energy alternatives and reshaping procurement criteria for superstructure applications.
Growth Catalysts
- EU Green Deal enforcement:Binding carbon thresholds in Germany and France are mandating lightweight aggregate systems for public infrastructure tenders, accelerating specification of expanded clay in bridge decks and high-rise cores.
- Seismic engineering demand:Japan's building code revisions for earthquake resilience are specifying reduced mass concrete for mid-rise frames in Tokyo and Osaka metropolitan zones.
- Urban densification patterns:China's superstructure construction in tier-one cities is concentrating demand for dead-load reduction to enable taller vertical build on constrained footprints.
Market Restraints
- Natural gas cost volatility:Expanded clay production requires sustained kiln temperatures exceeding 1100°C, exposing margins to European energy price spikes and Russian supply uncertainty.
- Aggregate deposit concentration:High-quality pumice reserves cluster in Italy and Turkey, creating import dependency for Asian precast manufacturers seeking consistent porosity grades.
- ASTM-EN divergence:Technical incompatibility between US aggregate qualification protocols and European EN 13055 testing regimes fragments cross-border specification and raises compliance costs for multinational projects.
Strategic Opportunities
- Indian infrastructure buildout:The country's National Infrastructure Pipeline is specifying lightweight concrete for metro viaducts and airport terminals where foundation constraints limit conventional dead loads.
- Carbon capture integration:Emerging mineralization technologies are converging with lightweight aggregate production to sequester CO2 within expanded clay pore structures, creating negative-emission material credentials.
- Performance-based procurement:Dutch and Danish public works agencies are piloting lifecycle-cost contracting that rewards durability guarantees over upfront material pricing, opening margin capture for certified producers.
Industry Challenges
- Mix design specialization gap:Site engineers lack training in air-dried curing protocols for lightweight placements, causing variability in permeability outcomes and warranty disputes on high-specification projects.
- EN 206 compliance timelines:Certification for new aggregate sources requires 18-24 months of testing documentation, delaying market entry for alternative materials like expanded slag.
- Legacy equipment retrofit costs:Existing precast plants require batching system upgrades to handle lower-density aggregates without segregation, demanding capital commitments that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Lightweight Concrete Market |
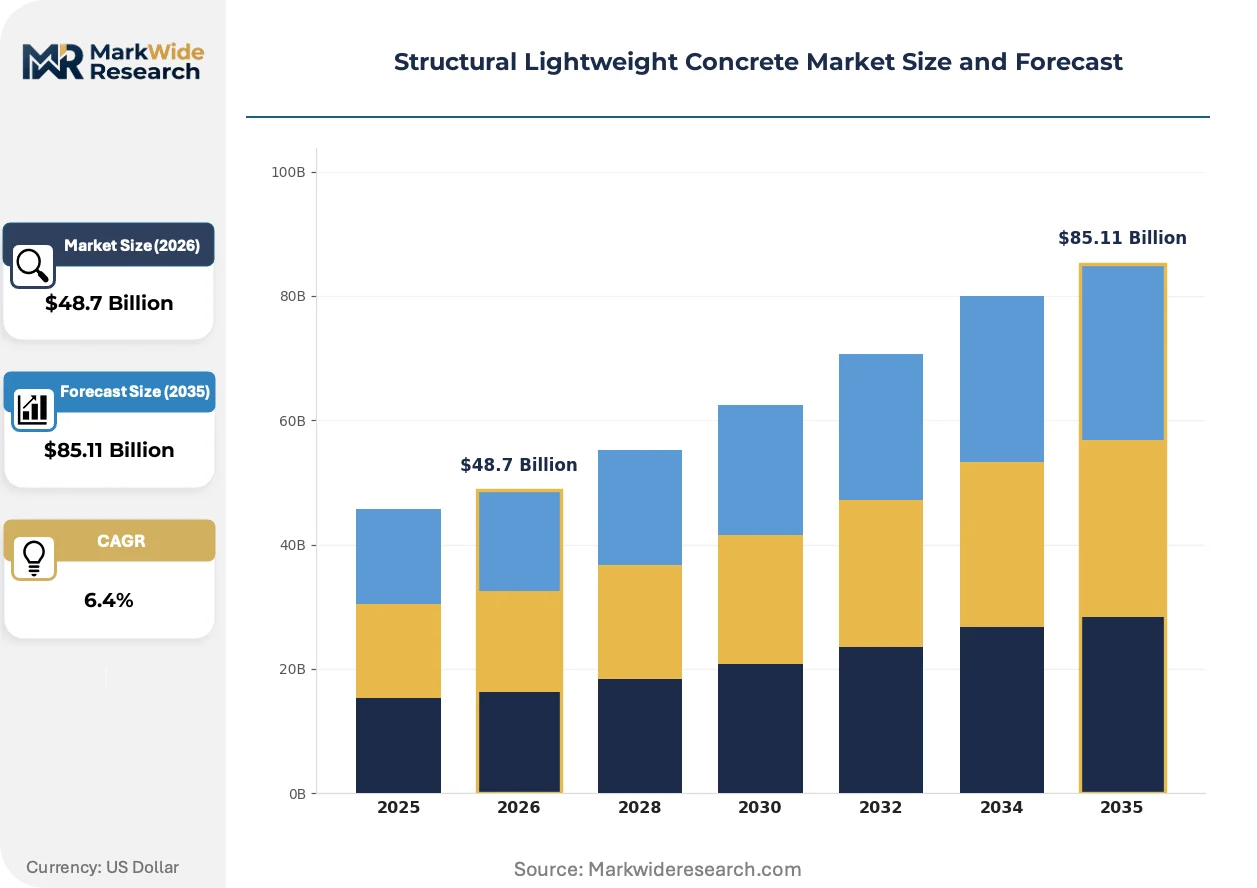
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Clay Aggregate, Expanded Shale Aggregate, Expanded Slag Aggregate, Pumice Aggregate, Perlite Aggregate Application: Precast Concrete Elements, Bridge Decks, High-Rise Buildings, Tunnel Linings, Parking Structures End User: Construction Contractors, Civil Engineering Firms, Government Agencies, Infrastructure Developers Curing Method: Steam Curing, Air Drying, Water Curing, Membrane Curing |
| Companies Covered | Cemex S.A.B. de C.V., BASF SE, Heidelberg Materials AG, Holcim Ltd, CRH plc, Buzzi Unicem S.p.A., Sika AG, Arcosa, Inc., LafargeHolcim Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Lightweight Concrete Market Trends and Innovations
Digital twin modeling of structural performance is compressing design cycles for lightweight concrete systems, while regulatory carbon accounting and shifting procurement authority are redistributing value capture across the supply chain.
Recycled glass cullet is integrating into expanded aggregate feedstocks to reduce virgin clay dependence and lower kiln energy intensity by 15-20 percent. Dutch precast specialists are specifying these hybrid aggregates for facade elements where thermal performance ratings determine tender awards. The technology is integrating quality control protocols from semiconductor manufacturing to achieve consistent density gradients across production batches.
REACH authorization requirements for crystalline silica content are restricting traditional aggregate processing methods across EU member states. Industrial consequence includes accelerated investment in closed-circuit dust suppression systems at crushing facilities. Precast concrete segments for infrastructure applications face the tightest compliance timelines, with German producers already retrofitting plants to maintain specification eligibility for federal tenders.
Buyer organizations are consolidating material procurement through engineering-procurement-construction consortia that bundle structural concrete with steel and MEP packages. The shift compresses direct supplier relationships and transfers specification authority from site contractors to design-phase engineers. This concentration is most visible in French and Spanish hospital and data center projects where single-source accountability reduces interface risk.
Structural Lightweight Concrete Market Segmentation
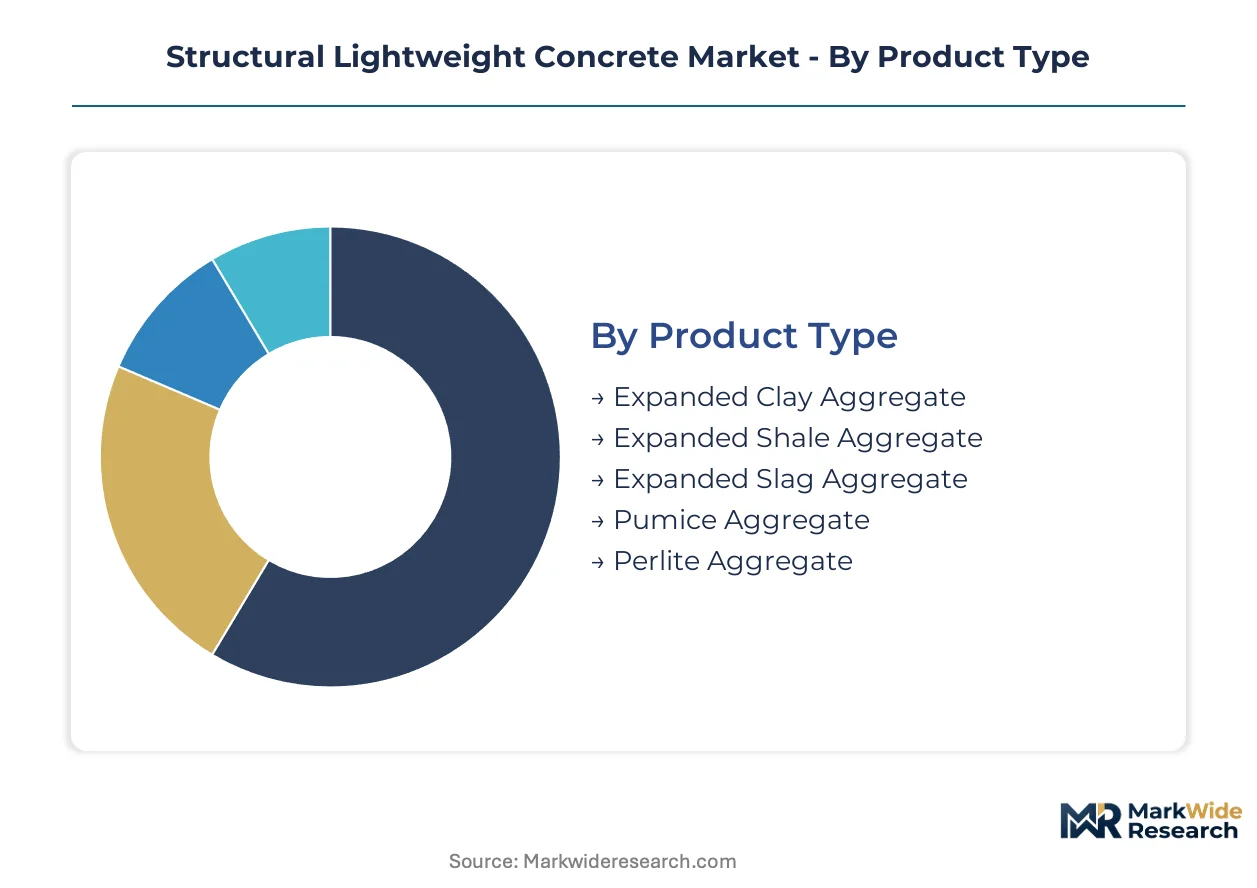
Structural lightweight concrete procurement hinges on matching aggregate characteristics to structural load requirements and curing constraints. Specification decisions cascade through product type, application geometry, end-user procurement authority, and curing protocol compatibility.
Product Type:
Supply concentration for kiln-fired aggregates determines regional availability and specification lock-in across major construction corridors.
- Expanded Clay Aggregate:Controlled porosity from rotary kiln sintering delivers consistent thermal performance and compressive strength gradations. China's superstructure construction in tier-one cities concentrates demand for this material where dead-load reduction enables taller vertical build on constrained footprints.
- Expanded Shale Aggregate:Lower kiln-energy intensity than clay alternatives attracts specification under EU Green Deal carbon thresholds. German and French public infrastructure tenders are mandating this aggregate for bridge deck applications where embodied carbon compliance determines award eligibility.
- Expanded Slag Aggregate:Industrial byproduct feedstock reduces virgin material dependence.
- Pumice Aggregate:Natural volcanic origin limits supply to Italian and Turkish deposit clusters.
- Perlite Aggregate:Lower density ceiling restricts use to non-structural insulation layers.
Expanded clay aggregate absorbs the bulk of installed capacity; expanded shale aggregate is expanding most quickly.
Application:
Project scale and repeatability shape margin structures across installation environments.
- Precast Concrete Elements:Factory-controlled curing enables tighter dimensional tolerances and lower cement factors than site-cast alternatives. Dutch and Danish hospital projects are bundling these elements into engineering-procurement-construction consortia where single-source accountability reduces interface risk.
- Bridge Decks:Long-span dead-load optimization drives specification in Japan's metropolitan zones where seismic engineering demand is accelerating. Tokyo and Osaka code revisions for earthquake resilience are mandating reduced mass concrete for mid-rise frame applications.
- High-Rise Buildings:Vertical densification in China and India concentrates procurement volume.
- Tunnel Linings:Waterproofing integration requirements favor specific aggregate porosity grades.
- Parking Structures:Exposure class durability demands dominate specification criteria.
Precast concrete elements capture concentrated margin pools; bridge decks are climbing the fastest.
End User:
Procurement authority consolidation is transferring specification control from site contractors to design-phase engineers.
- Construction Contractors:Direct site accountability for placement quality and curing protocol execution. Field-level training gaps in air-dried lightweight concrete protocols are causing permeability variability and warranty disputes on high-specification projects.
- Civil Engineering Firms:Design-phase authority over material specification in bundled EPC contracts. French and Spanish data center projects are seeing these firms consolidate concrete procurement with steel and MEP packages.
- Government Agencies:Lifecycle-cost contracting pilots in the Netherlands reward durability guarantees over upfront pricing.
- Infrastructure Developers:Long-horizon asset ownership aligns procurement with total cost of ownership metrics.
Construction contractors absorb the bulk of installed capacity; civil engineering firms are gaining share fastest.
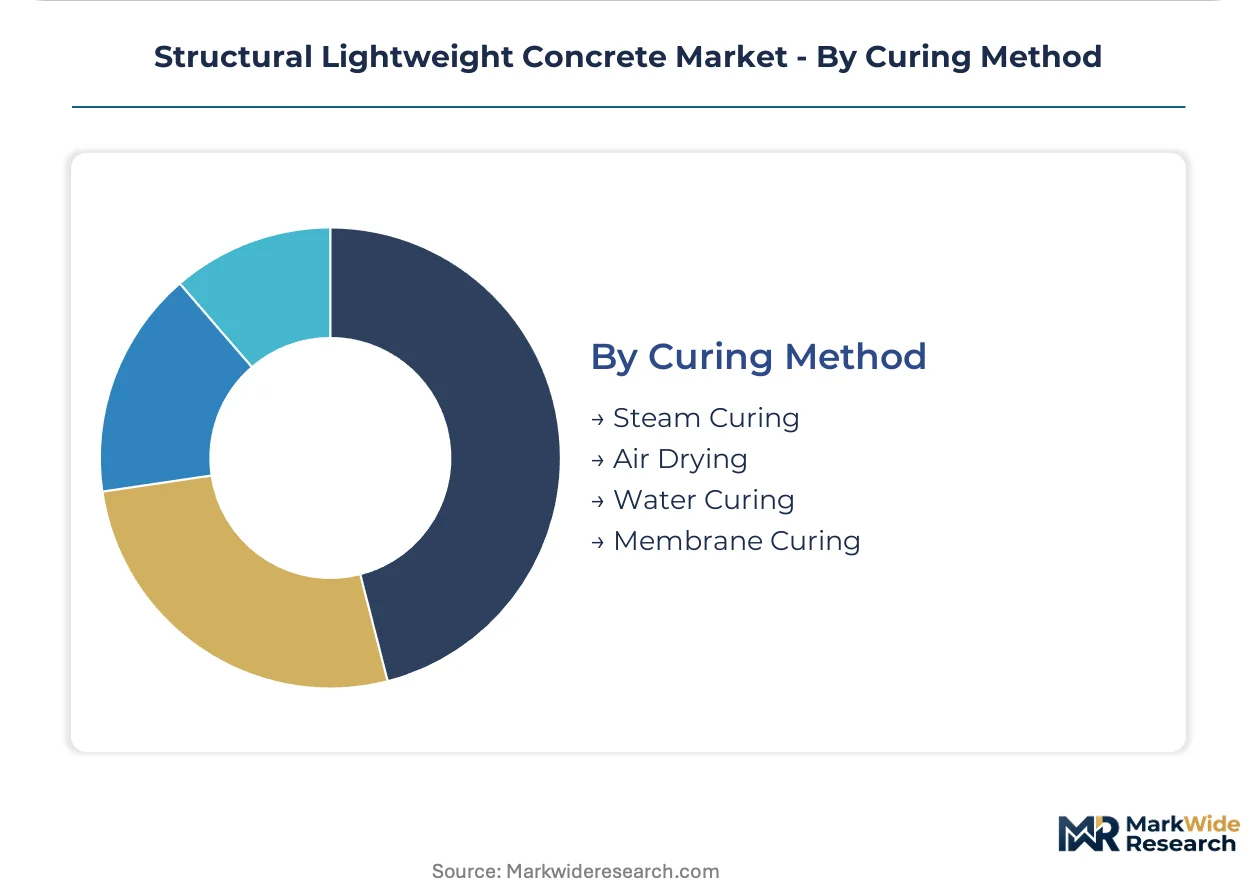
Curing Method:
Energy input requirements and quality control feasibility divide factory versus site applicability.
- Steam Curing:Accelerated strength development enables rapid formwork turnover in precast plants. German producers are retrofitting steam systems to maintain EN 206 specification eligibility for federal infrastructure tenders.
- Air Drying:Reduced energy intensity aligns with EU Green Deal carbon accounting frameworks. Sika AG bundles admixture systems with this protocol to reduce permeability in placements where moisture retention is constrained.
- Water Curing:Conventional immersion methods face labor cost pressure on large-scale sites.
- Membrane Curing:Chemical film formation suits remote locations with water scarcity constraints.
Steam curing absorbs the bulk of installed capacity; air drying is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's superstructure construction concentrates the heaviest procurement volume for structural lightweight concrete as developers optimize vertical build on constrained urban footprints.
China
Tier-one cities including Beijing, Guangzhou, and Shenzhen are mandating dead-load reduction in high-rise cores to enable taller construction on limited land parcels. The country's dual carbon goals under MEE oversight are tightening embodied carbon thresholds for public infrastructure tenders. Yangtze River Delta precast manufacturers are retrofitting batching systems to handle lower-density aggregates without segregation.
United States
Bridge deck rehabilitation across interstate corridors is accelerating specification of expanded clay systems for long-span dead-load optimization. ASTM C330 governs aggregate qualification, creating compliance friction with European EN 13055 protocols on multinational projects. Texas and California transportation departments are concentrating procurement through engineering-procurement-construction consortia that bundle concrete with steel packages.
Germany
Federal infrastructure tenders under EU Green Deal enforcement are mandating expanded shale aggregate for bridge applications where embodied carbon compliance determines award eligibility. EN 206 certification timelines of 18-24 months are delaying market entry for alternative materials like expanded slag. Rhine-Ruhr precast producers are retrofitting steam-curing systems to maintain specification eligibility for federal contracts.
India
The National Infrastructure Pipeline is specifying lightweight concrete for metro viaducts and airport terminals where foundation constraints limit conventional dead loads. BIS standards are evolving to accommodate lower-density aggregate systems in structural applications. Mumbai and Delhi construction corridors are seeing civil engineering firms consolidate procurement authority through bundled design-build contracts.
Japan
Tokyo and Osaka metropolitan zones are revising building codes to mandate reduced mass concrete for mid-rise frames in earthquake resilience zones. METI oversight is aligning material specifications with seismic engineering demand curves. Kanto region precast specialists are integrating digital twin modeling to compress design cycles for lightweight structural systems.
Structural Lightweight Concrete Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the structural lightweight concrete value chain. Kiln-fired aggregate manufacturers anchor the supply base with vertically integrated operations spanning mining, expansion, and distribution networks. Three archetypes dominate: multinational building materials conglomerates with captive aggregate reserves; regional precast specialists leveraging factory-controlled curing for dimensional precision; and admixture-chemical bundlers reducing permeability in air-dried placements. Competitive intensity centers on EN 206 certification speed and carbon-accounting credentials rather than price alone.
Among European-based building materials groups, Heidelberg Materials AG and Holcim Ltd exemplify the integrated-production archetype through EN 206-compliant footprints and technical advisory services tied to large infrastructure tenders. Sika AG occupies a distinct position as an admixture-curing system bundler serving placements where moisture retention is constrained. These three entities represent contrasting pathways to specification capture: certification anchoring, carbon compliance, and performance-guarantee contracting.
| Leading Market Players |
|---|
| Cemex S.A.B. de C.V. |
| BASF SE |
| Heidelberg Materials AG |
| Holcim Ltd |
| CRH plc |
| Buzzi Unicem S.p.A. |
| Sika AG |
| Arcosa, Inc. |
| LafargeHolcim Ltd |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers and family-owned mid-caps dominate kiln-fired aggregate supply, concentrating pricing power in German and Italian production clusters while compressing margins for independent batching operators dependent on spot purchases.
Pricing Analysis
Value-based pricing anchors on compressive strength guarantees and EN 206 certification tier rather than commodity tonnage. Pricing stratifies across premium certified, standard compliant, and economy uncertified tiers, with differentiation driven by carbon-accounting credentials and volume scale commitments. Cost compression in economy-grade expanded clay is intensifying because natural gas price spikes erode kiln economics. Government agencies exhibit lowest price sensitivity due to lifecycle-cost contracting, while mid-tier construction contractors face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for demolished concrete are emerging as secondary aggregate feedstocks, though quality variability limits structural applications. Supply concentrates in China, Germany, and Italy for expanded clay and shale, with pumice deposits tethered to Turkish and Italian volcanic zones. Raw material dependencies include natural gas for kiln firing, virgin clay and shale deposits, and industrial slag from steel production. Single-source vulnerability runs through Russian pipeline gas exposure for European kiln operators. Distribution runs through vertically integrated building materials conglomerates with captive rail and riverine networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon thresholds are forcing a consolidation play, eliminating uncertified batching operators unable to fund 18-24 month EN 206 compliance timelines.
For Market Incumbents: Acquire distressed precast manufacturing assets in China's Yangtze River Delta to secure dead-load reduction contracts from tier-one city developers. Cement factor optimization and captive expanded clay supply are critical levers against margin erosion from natural gas volatility. Retrofit steam-curing systems to maintain federal tender eligibility in Germany. For New Entrants and Emerging Players: Launch via air-dried curing protocol specialization targeting Indian metro viaduct projects where foundation constraints limit conventional concrete. The National Infrastructure Pipeline represents the most penetrable demand cluster. Partner with civil engineering firms consolidating procurement authority through bundled design-build contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap expanded shale producers in Germany and France with existing EU Green Deal compliance infrastructure. Long-term viability hinges on carbon capture integration credentials and kiln energy intensity below sector benchmarks. Monitor natural gas forward curves and MEE dual carbon enforcement intensity as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Expanded Clay Reserves | Cemex secures supply continuity across Mexico and southern US corridors against import dependency. |
| Carbon Capture Integration with Kiln Operations | Mineralization technologies sequester CO2 within expanded clay pore structures for negative-emission credentials. |
| EN 206 Certification Fast-Track Investment | Heidelberg Materials accelerates market entry timelines for alternative aggregates like expanded slag. |
| Performance-Based Procurement Contracting | Dutch public works agencies reward durability guarantees over upfront material pricing. |
| Admixture-Curing System Bundling | Sika AG reduces permeability in air-dried lightweight placements where moisture retention is constrained. |
Research Methodology
Multi-period observation of kiln capacity utilization, EN 206 certification timelines, and carbon-accounting adoption anchored the trend analysis, supplemented by interviews with aggregate plant managers, precast manufacturing directors, civil engineering specification leads, and government procurement officers. Secondary validation drew from customs trade data, SEC 10-K filings of listed building materials groups, EU ETS carbon price records, and national infrastructure pipeline disclosures. Bottom-up project pipeline assessment and top-down sector expenditure analysis were triangulated to calibrate volume estimates.
Segment-weighting across product type, application geometry, end-user procurement authority, and curing protocol compatibility structured the analytical framework. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules throughout the forecast period. Industry-specific inputs included natural gas forward price assumptions, urban densification velocity in tier-one Chinese cities, and seismic code revision timelines in Japan.
Regulatory enforcement intensity, feedstock energy price spikes, and aggregate deposit depletion rates are the dominant revision risks to modeled outputs. Practitioners should monitor EU Green Deal threshold tightening, MEE dual carbon oversight, and Rhine-Ruhr kiln retrofit completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Structural Steel Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
North America Facade Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Global Structural Health Monitoring Market