
 Japan Freight Forwarding Market | 2026-2036
Japan Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Freight Forwarding Market Insights
Carbon fiber-reinforced pallets is broadening load-bearing economics for high-value electronics shipments. Nippon Express leverages its nationwide depot network to sustain temperature-controlled pharmaceutical flows. SG Holdings anchors last-mile dominance through its parcel-delivery infrastructure. Mitsui O.S.K. Lines competes on ocean-freight scale across transpacific lanes.
Freight forwarding encompasses the coordination of cargo movement across carriers, customs, and documentation, typically managing container loads from 20-foot equivalent units to bulk charter volumes for industrial clients. Its primary purpose centers on consolidating fragmented shipper demand into optimized transport contracts while navigating tariff classifications and port protocols. Ocean freight commands the largest value pool among service types, though air freight captures premium margins from just-in-time electronics and pharmaceutical verticals. Multi-modal transport is gaining share as manufacturers seek single-accountability chains from factory floor to retail shelf.
METI enforces energy-efficiency benchmarks for logistics fleets, while Japan's Ministry of Land, Infrastructure, Transport and Tourism regulates driver hours and cross-border road permits. These frameworks elevate compliance costs for road-dedicated operators while creating procurement preference for certified multi-modal providers. Stakeholders must monitor how amendments to the Act on Rationalization of Energy Use reshape fleet-renewal timelines and intermodal investment priorities.
Market Dynamics
Japan's freight forwarding sector is recalibrating around METI's supply chain resilience mandates, which require automotive and electronics manufacturers to diversify parts procurement across multiple transit corridors rather than single-source routes.
Growth Catalysts
- Automotive parts procurement diversification:METI directives compel Toyota, Honda, and Nissan suppliers to maintain redundant ocean-air routing options, expanding forwarding contract volumes.
- Pharmaceutical cold chain expansion:PMDA temperature-validation requirements for biologics shipments are accelerating demand for qualified GDP-certified logistics infrastructure.
- Kanto industrial corridor concentration:Tokyo-Yokohama-Chiba manufacturing density creates natural consolidation points for high-frequency container services.
Market Restraints
- Diesel price volatility:Road freight operators face margin compression from fuel cost swings, with no hedging mechanisms permitted under Japan's commercial road transport licensing framework.
- Driver hour restrictions:Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces strict daily driving limits that cap fleet utilization rates below regional benchmarks.
- Port capacity bottlenecks:Yokohama and Nagoya container terminal congestion creates scheduling unreliability for time-sensitive automotive just-in-time flows.
Strategic Opportunities
- Kyushu semiconductor cluster development:Kumamoto and Fukuoka fabs under construction will require dedicated forwarding corridors for photolithography equipment imports.
- Hydrogen fuel cell truck corridors:METI subsidies for zero-emission fleet trials open dedicated lane contracts along Tokyo-Osaka expressways.
- Carbon fiber pallet standardization:JIS certification pathways for lightweight composite loading equipment enable premium pricing on high-value electronics lanes.
Industry Challenges
- Customs broker talent scarcity:Declining enrollment in Japan Customs' broker examination pipeline constrains documentation throughput during peak seasonal volumes.
- Legacy WMS integration:Forwarders' warehouse management systems require costly API redevelopment to connect with shippers' SAP and Oracle ERP platforms.
- Multi-modal liability fragmentation:Disputes over damage attribution between ocean, air, and road carriers delay claims resolution and erode shipper trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Freight Forwarding Market |
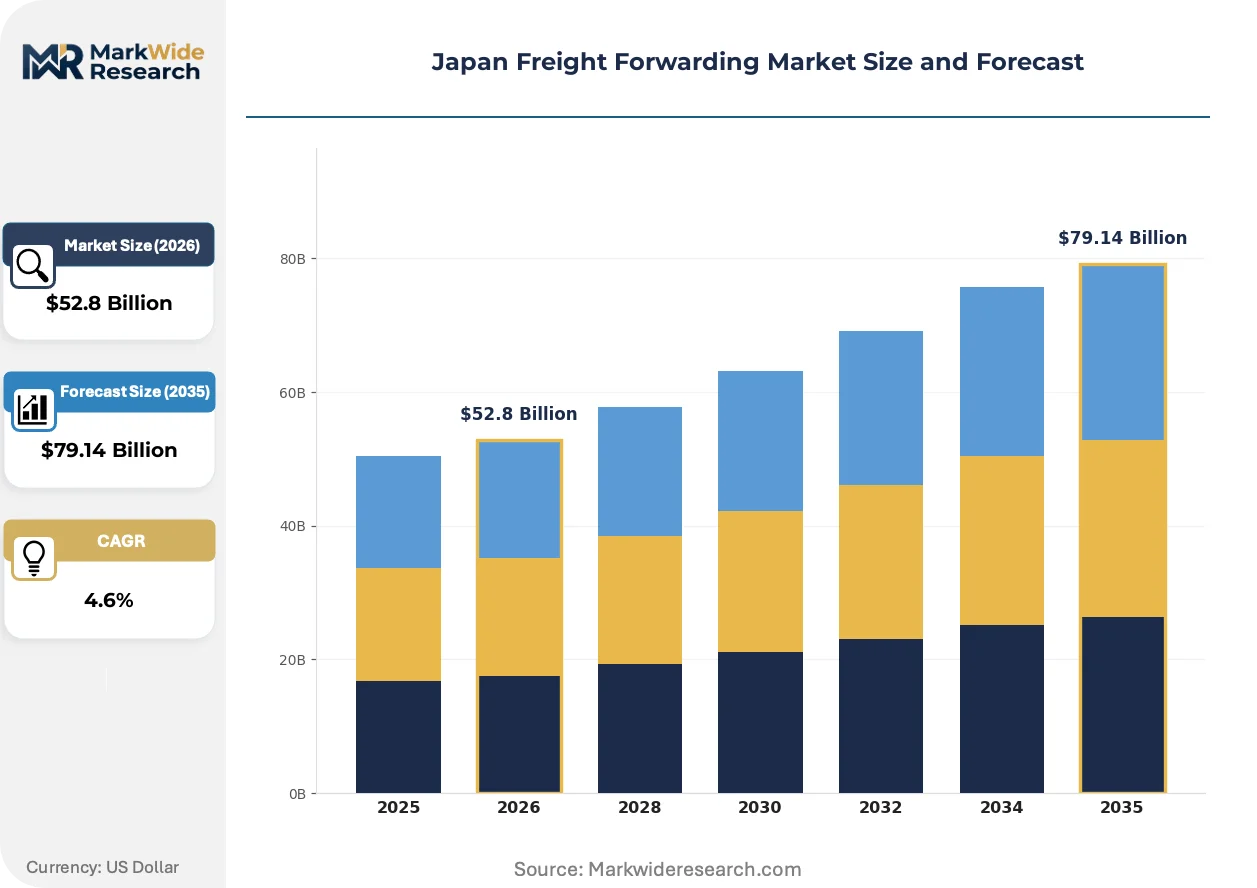
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight Customer Type: Manufacturers, Retailers, Importers, Exporters Transport Mode: Multi-modal, Dedicated Transport, Intermodal, Last Mile Industry Vertical: Automotive, Consumer Goods, Pharmaceuticals, Electronics |
| Companies Covered | SG Holdings, Mitsui O.S.K. Lines, Nippon Express, Kuehne + Nagel, Yusen Logistics, Yamato Holdings, Kintetsu World Express, JAS Forwarding, NYK Line, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Freight Forwarding Market Trends and Innovations
Digital freight platforms and sustainable transport technologies are restructuring how cargo owners contract capacity, with real-time visibility and emissions accountability becoming baseline procurement requirements rather than differentiators.
Blockchain-enabled bill-of-lading documentation is converging with IoT container sensors to create tamper-evident custody chains for pharmaceutical and semiconductor shipments. Japanese electronics manufacturers now mandate sensor-equipped reefer bookings for cross-border component flows. This convergence is compressing insurance premiums and reducing dispute resolution cycles from weeks to days.
METI's Act on Rationalization of Energy Use amendments now require logistics operators above specified fuel consumption thresholds to submit decarbonization roadmaps with verified interim targets. Fleet operators must document alternative fuel trials or face procurement exclusion from government-affiliated shippers. Road-dedicated carriers in the Kanto region are accelerating intermodal partnerships to distribute compliance burdens.
Shippers are unbundling forwarding contracts from integrated 3PL arrangements, seeking direct relationships with niche ocean and air specialists for core lanes while retaining parcel specialists for final-mile execution. Automotive tier-one suppliers in Aichi Prefecture now run separate RFP processes for transpacific ocean capacity and domestic truck brokerage. This pattern is most pronounced among precision equipment manufacturers with concentrated supplier bases in central Japan.
Japan Freight Forwarding Market Segmentation
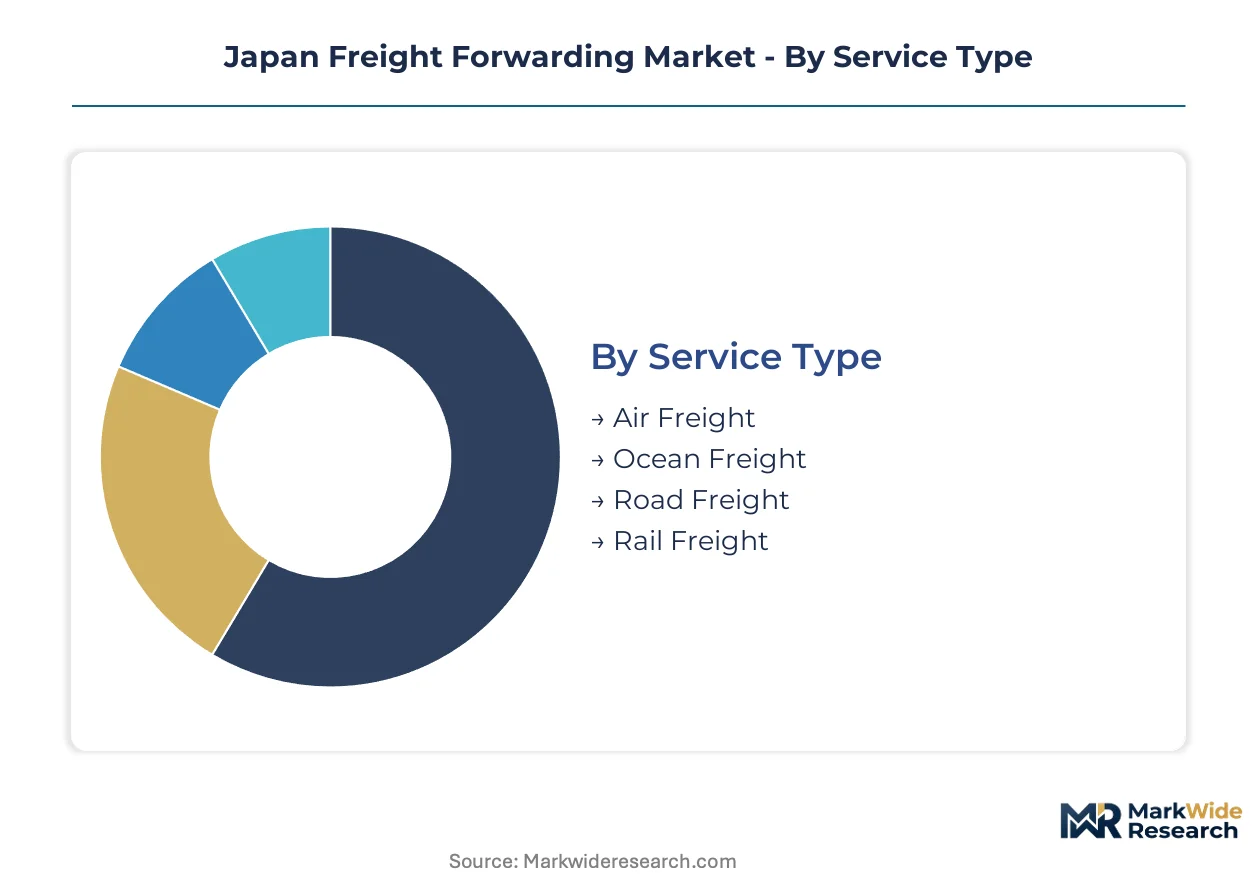
Segmentation reveals how Japanese freight forwarders allocate capital across service tiers and customer profiles. Service type and transport mode splits determine margin architecture, while vertical specialization dictates compliance investments and carrier partnerships.
Service Type:
Ocean freight commands volume dominance while air freight captures premium pricing from time-critical verticals.
- Ocean Freight:Full-container-load and less-than-container-load services handle automotive parts and consumer goods volumes across transpacific and intra-Asia lanes. Toyota and Honda suppliers in Aichi Prefecture rely on scheduled Asia-North America sailings for just-in-time assembly line replenishment, though Yokohama terminal congestion forces buffer stock accumulation.
- Air Freight:Temperature-controlled and high-value cargo movements leverage Narita and Kansai International hub capacity for semiconductor equipment and biologics. PMDA-validated cold chain protocols for pharmaceutical exports to North America and Europe sustain rate premiums above ocean alternatives.
- Road Freight:Domestic truck brokerage connects port terminals to inland distribution centers across the Kanto industrial corridor.
- Rail Freight:Containerized movements on JR Freight networks serve bulk chemical and paper product flows between regional production hubs.
Today's leader: Ocean Freight. Tomorrow's challenger: Air Freight.
Customer Type:
Manufacturer contracts anchor revenue stability while retailer relationships demand flexible capacity scaling.
- Manufacturers:Automotive and electronics producers negotiate annual contracts with volume commitments and dedicated lane allocations. METI supply chain resilience directives now require redundant routing options, expanding forwarding procurement from single-source to multi-carrier arrangements.
- Importers:Raw material and component buyers manage customs classification complexity and duty optimization across JIS standards and Harmonized System codes.
- Exporters:Finished goods shippers coordinate export documentation and certificate-of-origin processing for destination market compliance.
- Retailers:Seasonal demand surges from e-commerce platforms and department store chains require spot market capacity access and rapid customs clearance.
Manufacturers provide contract depth. Retailers drive volume volatility.
Transport Mode:
Single-accountability chains are displacing fragmented handoffs as shippers prioritize damage attribution clarity.
- Multi-modal:Door-to-door contracts combining ocean, air, and road legs under single forwarder liability. Electronics manufacturers in Tokyo-Yokohama-Chiba now mandate sensor-equipped visibility across all modal transitions.
- Intermodal:Rail-truck combinations for cost-sensitive bulk commodities moving between regional industrial zones.
- Dedicated Transport:Captive fleet or exclusive charter arrangements for high-security pharmaceutical and precision equipment flows.
- Last Mile:Parcel and light-truck final delivery from urban distribution centers to retail points or end consumers.
Multi-modal contracts are expanding most quickly. Dedicated Transport retains margin leadership.
Industry Vertical:
Vertical specialization determines certification requirements and carrier selection criteria across the forwarding portfolio.
- Automotive:Tier-one and tier-two supplier networks require synchronized inbound logistics to assembly plants in Toyota City, Yokohama, and Oppama. METI-mandated procurement diversification is multiplying forwarding contract volumes per supplier.
- Pharmaceuticals:GDP-certified cold chain infrastructure supports biologics and vaccine distribution with PMDA temperature-validation documentation. Kyowa Kirin and Takeda exports to North America sustain premium rate structures.
- Electronics:Semiconductor equipment and consumer device movements demand shock-resistant packaging and customs-bonded warehousing near Narita and Kansai airports.
- Consumer Goods:High-frequency replenishment of retail inventory across convenience store and department store channels.
Automotive delivers contract scale. Pharmaceuticals offer margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto industrial corridor freight volumes anchor Japan's forwarding demand, with Tokyo-Yokohama-Chiba manufacturing density creating natural consolidation points for container services and multi-modal handoffs.
Kanto
Automotive assembly plants and electronics manufacturing clusters in Tokyo, Yokohama, and Chiba generate continuous container flows through Yokohama port terminals. METI supply chain resilience directives require Toyota and Honda suppliers to maintain redundant ocean-air routing options. Port capacity bottlenecks at Yokohama container terminals force buffer stock accumulation for just-in-time automotive flows.
Kansai
Osaka-based precision equipment manufacturers and Kyoto semiconductor fabricators demand shock-resistant packaging and customs-bonded warehousing near Kansai International Airport. PMDA-validated cold chain protocols support biologics exports from Osaka pharmaceutical clusters. Kansai International hub capacity handles temperature-controlled movements for Takeda and Kyowa Kirin shipments to North America.
Chubu
Toyota City and Nagoya anchor tier-one and tier-two automotive supplier networks requiring synchronized inbound logistics. Aichi Prefecture manufacturers now run separate RFP processes for transpacific ocean capacity and domestic truck brokerage under METI-mandated procurement diversification. Nagoya port congestion creates scheduling unreliability for automotive assembly line replenishment.
Kyushu
Kumamoto and Fukuoka semiconductor fabs under construction will require dedicated forwarding corridors for photolithography equipment imports. Kyushu development represents Japan's bid to diversify chip manufacturing beyond Kanto and Kansai concentrations. Dedicated transport arrangements for high-security precision equipment flows will concentrate around new fab clusters.
Hokkaido
Agricultural and seafood export flows through Otaru and Hakodate ports demand temperature-controlled logistics infrastructure for North Asian markets. JR Freight rail networks serve bulk chemical movements between regional production hubs. Cold chain expansion for fresh produce exports drives GDP-certified infrastructure investment.
Japan Freight Forwarding Market Competitive Landscape
Global majors compete with regional champions across service breadth and vertical specialization, creating a tiered structure where scale-driven integrators face niche specialists. Ocean freight scale operators battle parcel-delivery infrastructure owners for multi-modal contract dominance. Three archetypes define positioning: integrated express networks, ocean-forwarding specialists, and vertical-focused cold chain operators. Capacity expansion through hydrogen corridor trials and strategic partnerships for semiconductor logistics represent dominant competitive moves.
Within the integrated network tier, Nippon Express exemplifies nationwide depot coverage for temperature-controlled pharmaceutical flows, while SG Holdings anchors last-mile dominance through parcel-delivery infrastructure. Mitsui O.S.K. Lines occupies the ocean-forwarding specialist position competing on transpacific lane scale. These three represent distinct strategic archetypes rather than direct substitutes, with each leveraging core infrastructure to defend forwarding contract positions against cross-tier encroachment.
| Leading Market Players |
|---|
| SG Holdings |
| Mitsui O.S.K. Lines |
| Nippon Express |
| Kuehne + Nagel |
| Yusen Logistics |
| Yamato Holdings |
| Kintetsu World Express |
| JAS Forwarding |
| NYK Line |
| Others |
Pricing and Supply Chain Analysis
IFO 380 bunker fuel indices cascade through ocean freight contract tiers, compressing margins for road-dedicated operators while METI's decarbonization mandates force premium pricing on certified multi-modal providers. Diesel price volatility in the Kanto corridor feeds directly into spot trucking rates, creating three-tier pricing stratification across certified cold chain, standard container, and economy bulk segments.
Pricing Analysis
Input-cost pass-through from fuel and labor categories dominates contract renegotiation cycles, with ocean freight carriers indexing bunker adjustments monthly and truck brokers surcharging diesel fluctuations weekly. Price differentiation separates GDP-certified pharmaceutical lanes from standard automotive parts movements, with temperature-validated services commanding sustained premiums. Cost compression in domestic road freight is intensifying because METI's driver hour restrictions cap fleet utilization below regional benchmarks. Retailers and spot-market shippers exhibit highest price sensitivity, while automotive tier-one suppliers under METI resilience mandates absorb premium rates for redundant routing guarantees.
Supply Chain Analysis
Logistics cost concentration in the Kanto industrial corridor—spanning Yokohama port terminals, Tokyo distribution centers, and Chiba manufacturing clusters—creates natural chokepoints that amplify rate volatility during peak seasonal volumes. Supply concentration draws from China for electronics components, South Korea for semiconductor equipment, and Southeast Asia for automotive parts. Raw material dependencies include carbon fiber composites for lightweight pallets, refrigerants for cold chain infrastructure, and specialized container chassis for automotive just-in-time flows. Single-source vulnerability persists in customs brokerage talent, where declining examination enrollment constrains documentation throughput. Distribution runs through Nippon Express depot networks for pharmaceutical flows, SG Holdings parcel infrastructure for last-mile execution, and Mitsui O.S.K. Lines ocean terminals for transpacific volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Japan freight forwarding rests on hydrogen corridor subsidies reducing long-haul fuel costs and pharmaceutical cold chain certification enabling premium-tier rate capture. METI's supply chain resilience mandates create captive demand for redundant routing services that resist commoditization pressure.
For Market Incumbents: Deepen intermodal partnerships to distribute METI compliance burdens across ocean-air-road networks, securing dedicated lane contracts along Tokyo-Osaka hydrogen corridors. Acquire GDP-certified cold chain infrastructure in Kansai and Kanto to defend against emerging vertical specialists targeting pharmaceutical biologics exports. SG Holdings and Nippon Express must lock in exclusive depot access before new entrants capture semiconductor logistics clusters in Kyushu. For New Entrants and Emerging Players: Enter via Kyushu semiconductor fab corridors, where Kumamoto and Fukuoka construction creates uncontracted demand for photolithography equipment forwarding. Target underpenetrated hydrogen fuel cell truck trials with dedicated lane contracts between Kanto and Chubu industrial zones. Position as GDP-certified specialists for pharmaceutical exports, bypassing incumbent generalists through PMDA temperature-validation expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented road brokerage operators face diesel margin compression without hedging mechanisms permitted under Japan's commercial transport licensing. Long-term viability favors multi-modal providers with captive pharmaceutical certification and hydrogen corridor access. Target acquisition archetypes include regional cold chain specialists with PMDA-validated infrastructure and customs brokers with examination-qualified talent pipelines. Watch METI amendments to the Act on Rationalization of Energy Use as the inflection signal for fleet-renewal investment timelines and intermodal M&A acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Corridor Partnership | METI subsidies for zero-emission Tokyo-Osaka lanes create first-mover contract advantages. |
| GDP Certification Investment | PMDA-validated cold chain infrastructure captures biologics export premiums from Takeda and Kyowa Kirin. |
| Customs Broker Talent Acquisition | Japan Customs examination-qualified brokers resolve documentation bottlenecks during peak automotive volumes. |
| Carbon Fiber Pallet Standardization | JIS certification for composite loading equipment enables premium pricing on high-value electronics lanes. |
| Kyushu Semiconductor Logistics Cluster | Kumamoto and Fukuoka fab construction demands dedicated photolithography equipment forwarding corridors. |
Research Methodology
Bottom-up automotive and pharmaceutical shipper modeling reconciled against top-down ocean carrier capacity tracking forms the analytical core of this study. Primary interviews with freight forwarding operations directors, pharmaceutical supply chain managers, automotive tier-one procurement leads, and METI policy officers combined with secondary validation from Japan Ministry of Land, Infrastructure, Transport and Tourism port throughput statistics, Nippon Kaiji Kyokai vessel registry data, Japan Customs trade declarations, and PMDA GDP certification databases. Triangulation across stakeholder inputs and documentary sources ensures segment-level accuracy.
Historical trendline analysis of container volumes, modal share shifts, and contract rate movements established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type splits across ocean, air, road, and rail freight; customer archetypes spanning manufacturers, importers, exporters, and retailers; transport mode configurations from multi-modal to dedicated transport; and industry verticals including automotive, pharmaceuticals, electronics, and consumer goods. CAGRs derived from regression analysis of macroeconomic drivers, regulatory implementation timelines, and infrastructure investment cycles, with specific weighting for METI supply chain resilience mandate compliance costs and hydrogen corridor subsidy uptake rates.
The model holds under stable METI regulatory implementation and continued automotive production concentration in Aichi and Kanto; deviation in port capacity expansion timelines, customs broker examination pass rates, or hydrogen infrastructure deployment would shift volume and value trajectories. Forecasts reflect documented assumptions about modal substitution elasticity and certification cost pass-through. Stakeholders should weight assumptions against their own operating context and contract renewal cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Global Connected Logistics Market