
 South America Freight and Logistics Market | 2026-2036
South America Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Freight and Logistics Market Analytics
Agricultural commodity flows is shifting toward temperature-controlled containerization across Mercosur trade lanes. CMA CGM Group leverages its Buenos Aires–Montevideo feeder network to sustain transshipment dominance. JSL S.A. anchors Brazilian road freight through its specialized fleet serving the Central-West soybean belt. DP World competes for port terminal concessions along the Paraná–Paraguay waterway corridor.
South America freight and logistics encompasses the multimodal movement of goods across road, rail, air, and maritime networks, typically involving containerized or bulk cargo with transit times ranging from 48 hours for regional trucking to 14–21 days for deep-sea routes, primarily serving commodity export, manufacturing supply chain, and retail distribution functions. Road freight absorbs the dominant share of tonnage given the continent's sparse rail infrastructure, while sea freight captures the highest value per shipment through Brazilian and Chilean port gateways. GPS Tracking and Freight Management Software segments are expanding fastest as carriers digitize fleet dispatch and customs documentation. IoT Solutions remains nascent but holds concentrated margin pools in pharmaceutical and perishable cold-chain monitoring.
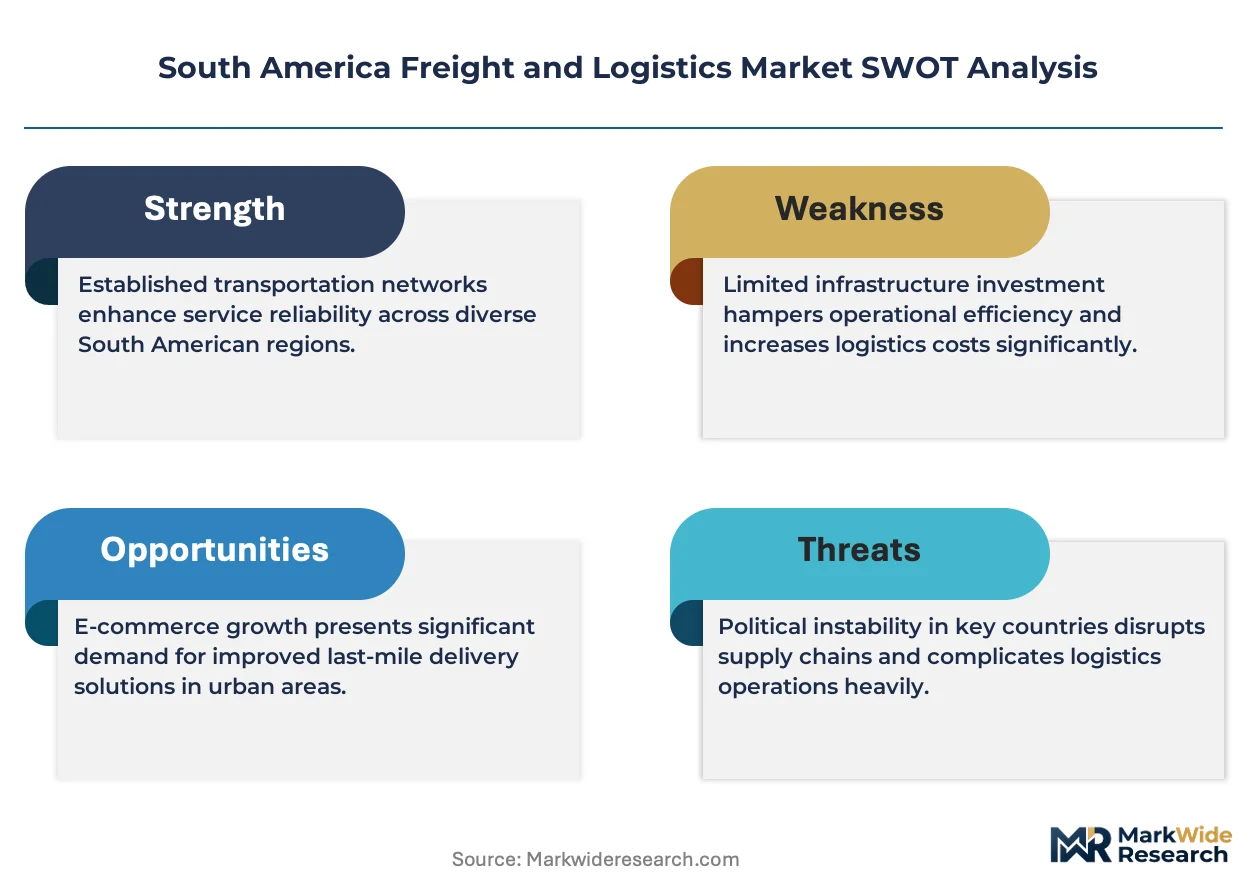
Brazil's ANTT regulates minimum freight rates and driver rest mandates, reshaping cost structures for domestic trucking operators. Argentina's CNRT enforces axle-load limits and emissions standards that filter fleet modernization requirements. Chile's MTT port authority frameworks govern concession terms for Pacific container terminals. Stakeholders must weigh infrastructure investment timing against regulatory uncertainty surrounding Mercosur customs harmonization and emerging carbon-border protocols.
Market Dynamics
Brazil's ANTT freight rate floor regulations are compressing carrier margins while forcing rapid fleet modernization across the São Paulo–Santos corridor. Soybean belt exporters now demand temperature-controlled containerization, reshaping equipment deployment patterns.
Growth Catalysts
- Agribusiness cold-chain expansion:Brazilian and Argentine beef and soy exporters are mandating refrigerated container standards for Mercosur shipments. This pulls investment into reefer fleet capacity.
- Paraná–Paraguay waterway dredging:Improved draft depth at Corumbá and Asunción terminals enables barge consolidation of Mato Grosso grain flows. Intermodal economics strengthen against pure trucking.
- GPS-based freight management platforms:Real-time fleet dispatch systems reduce empty backhaul rates on Brazilian federal highways. Digitization cuts documentation delays at land borders.
Market Restraints
- Diesel price volatility:Brazilian road freight operators face fuel cost swings unhedged by ANTT's fixed minimum rate structures. Margin compression hits independent truckers hardest.
- Rail infrastructure gaps:Sparse coverage beyond the Carajás iron ore line forces dependence on BR-163 highway trucking for Central-West agricultural exports. Bottlenecks persist at Rondonópolis.
- Mercosur customs non-harmonization:Divergent documentation requirements between Brazilian Receita Federal and Argentine AFIP create border processing friction. Transshipment delays accumulate at Paso de los Libres.
Strategic Opportunities
- Uruguay's free-port status:Montevideo's tax-advantaged logistics zone attracts transshipment volume from landlocked Paraguay and Bolivia. Feeder network density can expand.
- Pharmaceutical cold-chain monitoring:IoT sensor deployment for temperature-sensitive biologics remains underpenetrated in Andean distribution corridors. ANVISA traceability mandates create compliance-driven demand.
- Green hydrogen corridor development:Chile's Antofagasta–Mejillones mining logistics cluster positions for ammonia-fueled vessel bunkering. Regulatory tailwinds from MTT decarbonization frameworks accelerate pilot projects.
Industry Challenges
- Qualified driver shortages:Brazil's CNRT mandatory rest period enforcement reduces effective fleet utilization hours. Recruitment lags in remote Mato Grosso loading zones.
- Port concession renegotiation complexity:Santos terminal operators face MTIC tariff disputes while attempting berth expansion capex. Investment timelines misalign with regulatory review cycles.
- Legacy TMS integration:Mid-size Brazilian carriers struggle to connect dispatch software with ANTT's electronic freight document systems. Data standardization gaps persist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Freight and Logistics Market |
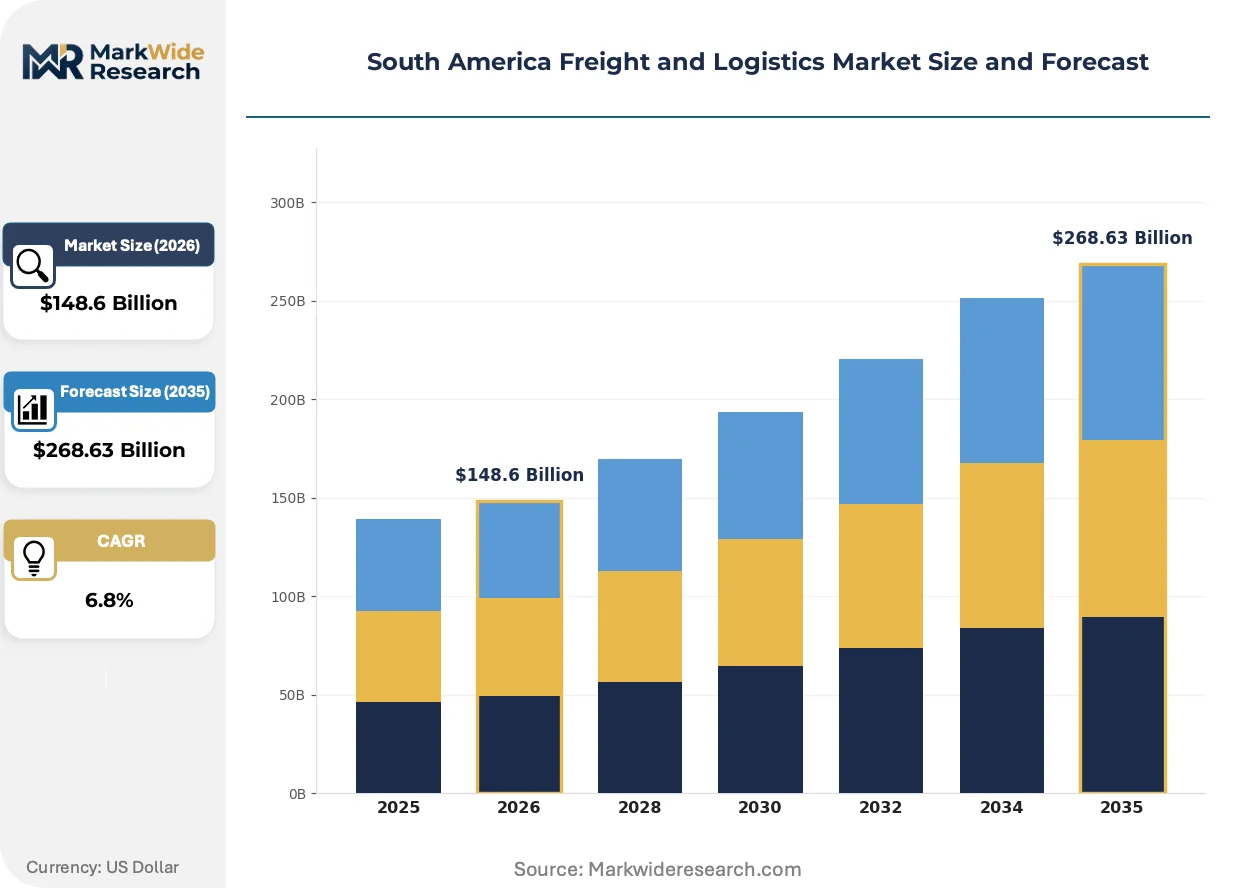
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight Technology: GPS Tracking, Warehouse Management, Freight Management Software, IoT Solutions Industry Vertical: Manufacturing, Retail, Oil & Gas, Agriculture Delivery Model: Direct Delivery, Last Mile Delivery, Cross-Docking, 3PL Services |
| Companies Covered | Kuehne+Nagel, CEVA Logistics, CMA CGM Group, JSL S.A., GEODIS, DHL Group, DP World, TASA Logística, DSV A/S, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Freight and Logistics Market Evolving Landscape
Digital freight platforms are compressing broker layers while regulatory pressure on emissions intensifies equipment turnover cycles. Cold-chain integrity standards now dictate modal choice for high-value agricultural exports.
Telematics-enabled predictive maintenance is unifying fleet uptime management across Brazilian long-haul operators. Large agribusiness shippers now require real-time cargo condition visibility as a contract precondition. This capability compression is squeezing out smaller carriers lacking sensor infrastructure investment capacity.
Chile's MTT green port certification framework mandates shore power connectivity and electric yard tractor deployment at Valparaíso and San Antonio terminals. Container lines face berth allocation penalties for non-compliant vessel calls. Pacific coastal routes serving Santiago distribution centers absorb the strictest enforcement timelines.
Consolidation among Argentine cereal exporters is shifting procurement toward integrated logistics contracts bundling trucking, barge, and port handling. Traditional fragmented spot-market brokerage loses share in Rosario–Bahía Blanca soybean flows. This concentration is most visible in Santa Fe province where major trading houses now operate captive fleet subsidiaries.
South America Freight and Logistics Market Segmentation
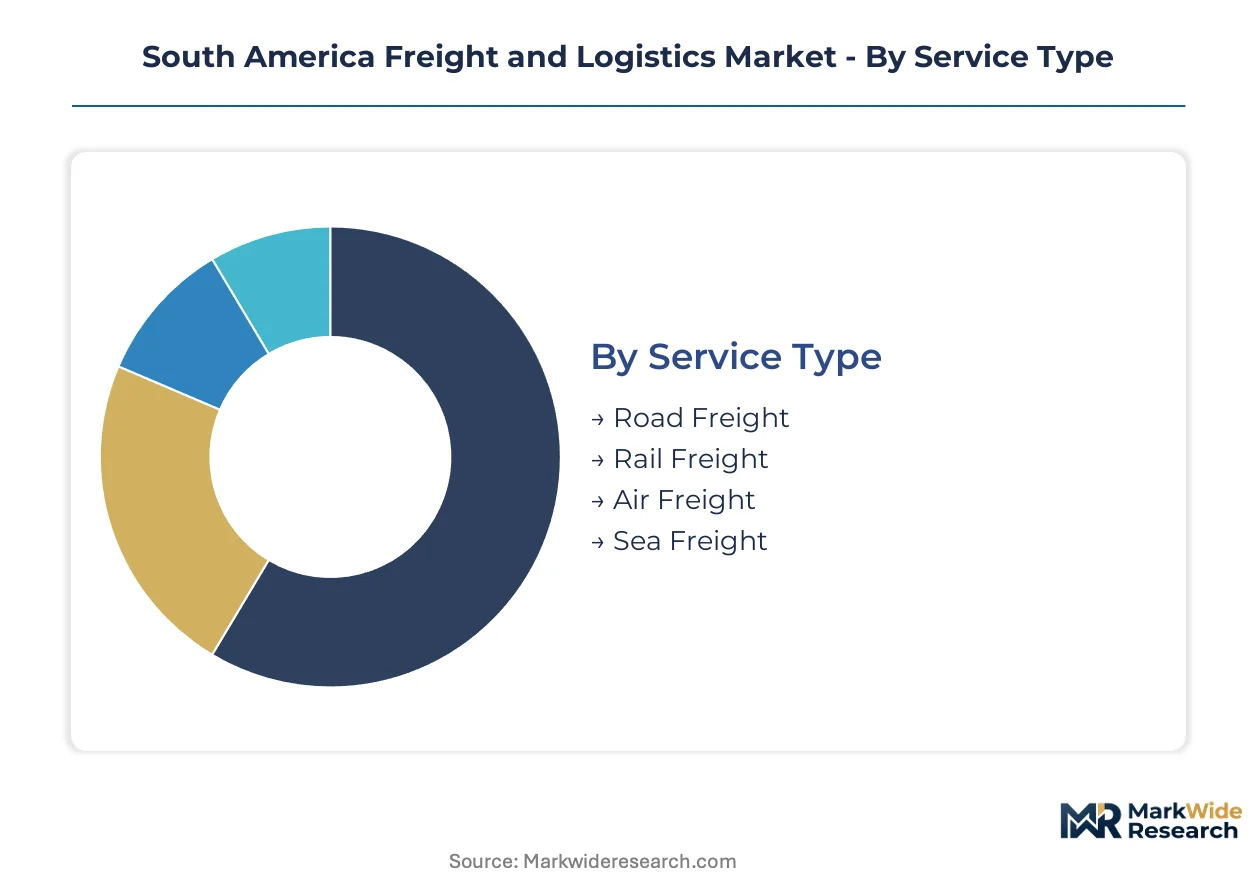
Modal choice in South American freight hinges on infrastructure availability and cargo value density. Cold-chain requirements and digitization pressures are reshaping how shippers configure service bundles across the continent's sparse rail network and congested port corridors.
Service Type:
Standardized bulk movements dominate low-value commodity flows, while temperature-controlled and time-definite services command premium positioning for agribusiness and manufacturing supply chains.
- Road Freight:BR-163 and São Paulo–Santos corridor trucking handles the majority of Central-West soybean and beef exports. ANTT minimum rate regulations compress independent operator margins while consolidating volume around fleet-scale carriers with GPS dispatch capabilities.
- Sea Freight:Brazilian and Chilean deep-water terminals capture the highest value per shipment through containerized agricultural and manufactured goods. Santos and Paranaguá congestion drives shippers toward Buenos Aires–Montevideo feeder alternatives for Mercosur transshipment.
- Rail Freight:Concentrated on the Carajás iron ore line and limited agricultural spurs in southern Brazil. Infrastructure gaps beyond these corridors force modal substitution onto federal highways.
- Air Freight:Serves pharmaceutical cold-chain and high-value electronics through São Paulo–Guarulhos and Santiago hubs. Perishables demand ANVISA-compliant temperature monitoring for ANVISA-regulated biologics distribution.
Most installed capacity flows through Road Freight. Expansion is steepest in Sea Freight as port terminal concessions attract consolidation investment.
Technology:
Adoption depth correlates with fleet scale and shipper compliance requirements, creating a bifurcated landscape between integrated enterprise systems and fragmented point solutions.
- Freight Management Software:Real-time dispatch and electronic documentation platforms reduce empty backhaul rates on Brazilian federal highways. Large agribusiness shippers now mandate API connectivity as a contract precondition for carrier procurement.
- GPS Tracking:Telematics-enabled fleet visibility unifies uptime management across long-haul operators serving the Mato Grosso soybean belt. Predictive maintenance algorithms cut unplanned downtime for refrigerated fleets.
- Warehouse Management:Inventory optimization systems concentrate in São Paulo distribution centers serving retail and manufacturing clusters. Integration with ANTT electronic freight documents remains uneven among mid-size 3PL operators.
- IoT Solutions:Temperature and humidity sensors for pharmaceutical and perishable monitoring hold concentrated margin pools in Andean distribution corridors. ANVISA traceability mandates are pulling adoption beyond early pharmaceutical adopters.
Freight Management Software absorbs the largest deployment spend. IoT Solutions is climbing the fastest as cold-chain compliance hardens across beef and soy export corridors.
Industry Vertical:
Volume concentration in commodity exports contrasts with value concentration in manufacturing supply chains, driving divergent service requirements across the same infrastructure base.
- Agriculture:Soybean, beef, and poultry exporters in Brazil and Argentina are mandating refrigerated container standards for Mercosur shipments. Temperature-controlled equipment deployment patterns now follow harvest calendars across the Central-West and Pampas regions.
- Manufacturing:Automotive and electronics supply chains require just-in-time sequencing through the São Paulo industrial corridor. Component imports from Asia-Pacific route through Santos and Paranaguá with strict dwell-time penalties.
- Retail:E-commerce fulfillment is compressing delivery windows in Santiago, São Paulo, and Buenos Aires metropolitan zones. Last-mile density challenges multiply in informal urban settlements with limited address infrastructure.
- Oil & Gas:Exploration equipment and offshore platform supplies move through specialized heavy-lift corridors serving Brazil's pre-salt fields. Cabotage regulations favor domestic-flag vessel deployment for coastal supply runs.
Agriculture channels the heaviest tonnage. Manufacturing is gaining share fastest as nearshoring redirects Asia-Pacific supply chain volume toward Brazilian industrial clusters.
Delivery Model:
Asset ownership structures range from captive fleet operations among major trading houses to outsourced arrangements with multi-client 3PL platforms.
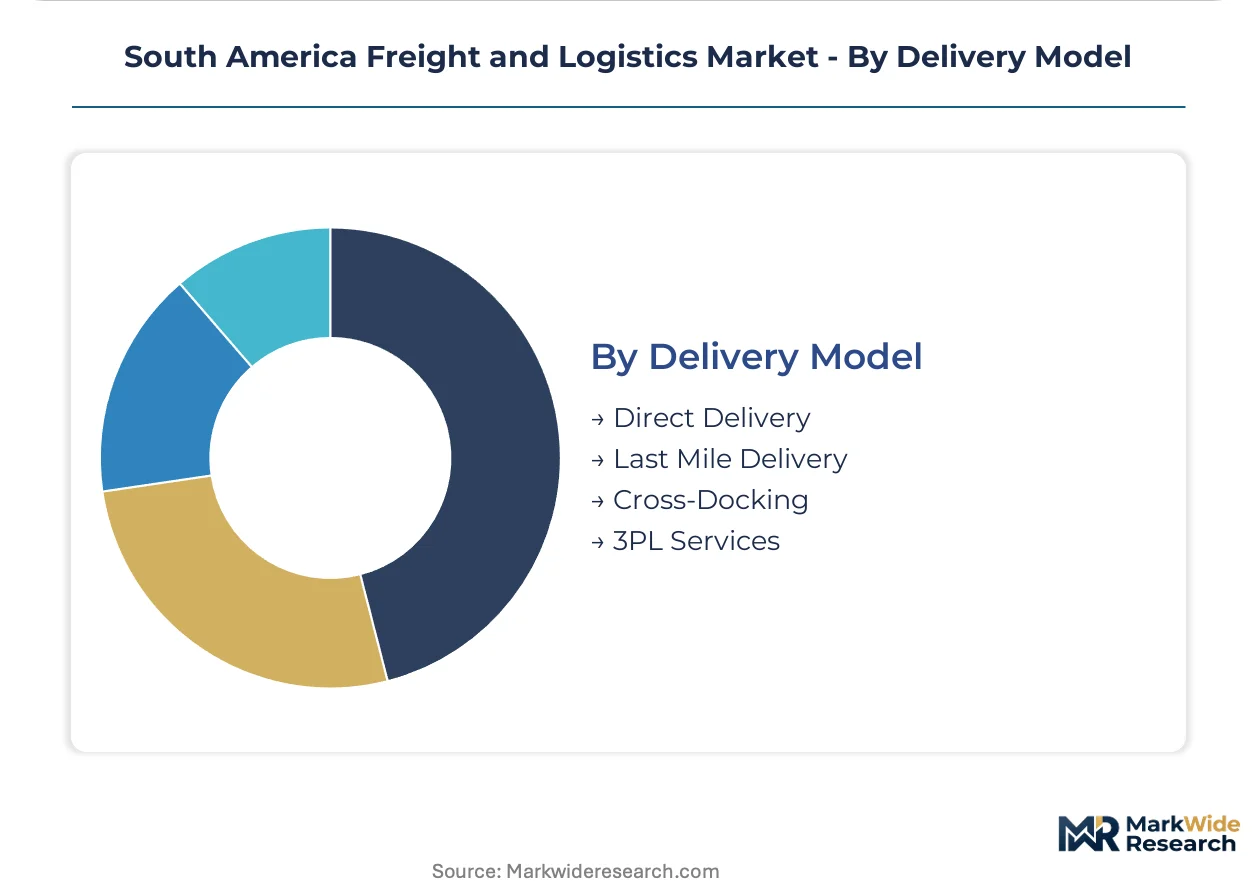
- 3PL Services:Integrated logistics contracts bundling trucking, barge, and port handling are displacing fragmented spot-market brokerage in Rosario–Bahía Blanca soybean flows. Major trading houses now operate captive fleet subsidiaries in Santa Fe province.
- Last Mile Delivery:Urban congestion and security constraints in São Paulo and Santiago are driving electric vehicle pilot programs and micro-fulfillment node placement. Delivery density remains challenging in informal settlement peripheries.
- Cross-Docking:Consolidation terminals at Rondonópolis and Campo Grande reduce handling costs for Central-West agricultural exports. Facility investment lags behind volume growth on the BR-163 corridor.
- Direct Delivery:Dedicated fleet arrangements serve high-value manufacturing supply chains with strict sequencing requirements. Asset utilization suffers from backhaul imbalance on specialized equipment.
3PL Services captures the broadest shipper adoption. Last Mile Delivery is expanding most quickly as e-commerce penetration accelerates urban logistics infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo–Santos corridor anchors South American freight movement, handling the densest concentration of containerized agricultural exports and manufacturing imports across the continent.
Brazil
Soybean and beef exporters in Mato Grosso and Goiás are mandating refrigerated container standards for Mercosur shipments. ANTT minimum freight rate regulations compress independent trucker margins while consolidating volume around fleet-scale carriers. Santos port congestion and BR-163 highway bottlenecks at Rondonópolis persist despite federal infrastructure investment programs.
Argentina
Cereal exporters in Santa Fe and Buenos Aires provinces are shifting procurement toward integrated logistics contracts bundling trucking, barge, and port handling. CNRT axle-load limits and emissions standards filter fleet modernization requirements across the Pampas grain belt. Rosario–Bahía Blanca soybean flows concentrate around trading houses operating captive fleet subsidiaries.
Chile
Mining logistics clusters in Antofagasta and Mejillones position for ammonia-fueled vessel bunkering pilot projects. MTT green port certification mandates shore power connectivity and electric yard tractor deployment at Valparaíso and San Antonio terminals. Santiago distribution centers absorb strictest enforcement timelines for Pacific coastal routes serving retail and manufacturing supply chains.
Uruguay
Montevideo's free-port status attracts transshipment volume from landlocked Paraguay and Bolivia through tax-advantaged logistics zones. Feeder network density expands along the Buenos Aires–Montevideo maritime corridor. Port terminal operators compete for barge consolidation of Mato Grosso grain flows seeking Atlantic outlet alternatives.
Colombia
Manufacturing supply chains in Bogotá and Medellín require just-in-time sequencing for automotive and electronics components. The national transport regulator enforces rest period mandates and emissions standards that reshape fleet economics on the Andean highway corridors. Pacific port development at Buenaventura competes with Caribbean alternatives for Asia-Pacific import routing.
South America Freight and Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as carriers invest in reefer fleet deployment and port terminal concessions. The market structure bifurcates between integrated global logistics platforms and specialized regional operators with dense local network coverage. Three archetypes prevail: asset-heavy ocean carriers with feeder network control, technology-enabled road freight consolidators, and port terminal concession holders with waterway corridor positioning. M&A activity and strategic partnerships concentrate around cold-chain capability acquisition and last-mile density building in metropolitan São Paulo and Santiago.
Among global integrated logistics providers, Kuehne+Nagel and DHL Group exemplify the asset-light platform model with technology-enabled customs brokerage and multimodal orchestration. CMA CGM Group anchors the ocean carrier archetype through its Buenos Aires–Montevideo feeder network dominance and transshipment hub control. These three represent contrasting strategic positions: neutral freight forwarding, captive vessel capacity, and hybrid port-to-door integration.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| CEVA Logistics |
| CMA CGM Group |
| JSL S.A. |
| GEODIS |
| DHL Group |
| DP World |
| TASA Logística |
| DSV A/S |
| Others |
Value Network & Pricing Analysis
Diesel fuel costs cascade through Brazilian road freight pricing tiers, compressing independent trucker margins while fleet-scale carriers with GPS dispatch capabilities capture volume consolidation. ANTT minimum rate floors transmit fuel volatility into shipper contract renegotiations across the São Paulo–Santos corridor.
Pricing Analysis
Distributor margins on refrigerated equipment separate premium cold-chain services from standard dry-cargo trucking across Mercosur lanes. Price differentiation rests on ANVISA certification tiers for pharmaceutical shipments and volume scale commitments from Mato Grosso soybean exporters. Pricing pressure stems from diesel cost swings unhedged by fixed minimum rate structures. Independent owner-operators exhibit highest price sensitivity; integrated trading houses with captive fleets demonstrate lowest.
Supply Chain Analysis
Regional distribution centers at Rondonópolis and Campo Grande anchor hub-and-spoke patterns for Central-West agricultural exports. Manufacturing inputs concentrate in China, Germany, and Mexico for Brazilian automotive assembly. Reefer container chassis and telematics hardware draw from East Asian production. Single-source vulnerability runs through the Paraná–Paraguay waterway chokepoint at Corumbá. Distribution runs through Santos and Paranaguá port terminals with Buenos Aires–Montevideo feeder alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American freight and logistics functions as a stable compounder, with agribusiness export volumes providing consistent tonnage baselines regardless of manufacturing cycle volatility.
For Market Incumbents: Anticipate margin compression from ANTT rate floor enforcement by accelerating fleet-scale GPS platform deployment and securing long-term terminal concessions at Santos. Vertical integration into captive barge operations on the Paraná–Paraguay waterway offsets highway diesel exposure. For New Entrants and Emerging Players: Mid-size pharmaceutical distributors in Andean corridors represent underserved buyer archetypes lacking IoT cold-chain infrastructure. White-space targets include ANVISA-compliant sensor deployment for biologics and last-mile electric vehicle pilots in Santiago informal settlements. Go-to-market angle: compliance-as-a-service bundling hardware with regulatory documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent trucking fleets face ANTT compliance costs exceeding capital access. Long-term viability favors asset-light technology platforms and waterway corridor positioning over pure highway exposure. Acquisition target archetype: regional 3PLs with established feeder network relationships. Signal to watch: port terminal renegotiation timelines at Santos indicating infrastructure investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Reefer Fleet Expansion | Captures cold-chain premium from Brazilian beef and soy exporters mandating temperature-controlled standards. |
| Waterway Corridor Investment | Paraná–Paraguay dredging enables barge consolidation of Mato Grosso grain flows against BR-163 trucking. |
| GPS Platform Integration | Real-time dispatch systems reduce empty backhaul rates on federal highways and satisfy shipper API mandates. |
| Port Terminal Concession | Santos berth expansion secures capacity for manufacturing imports amid persistent congestion bottlenecks. |
| Green Certification Program | Chile MTT shore power compliance at Valparaíso attracts vessel calls facing berth allocation penalties. |
Research Methodology
Multiple input streams — carrier dispatch records, port authority throughput data, and agribusiness shipper procurement contracts — were reconciled across primary interviews with fleet operations managers, terminal concession directors, and trading house logistics heads. Secondary validation drew from ANTT regulatory filings, Santos Port Authority traffic statistics, and Mercosur customs documentation databases. Bottom-up equipment deployment counts and top-down trade flow estimates were triangulated.
Historical volume trajectories were cross-referenced against panel input from carrier executives and port operators across the projection horizon. Segmentation dimensions modeled include service type, technology adoption tier, industry vertical, and delivery model structure. CAGRs were derived from equipment capacity expansion schedules and trade lane growth assumptions. Forecast inputs incorporated ANTT rate regulation compliance costs and Paraná–Paraguay waterway draft improvement timelines.
Inputs from Brazilian regulatory agencies and Argentine grain export associations were available through the study window; gaps in real-time carrier financial disclosures introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding diesel price corridors and customs harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Latin America Logistics Market