
 Europe Third Party Logistics Market | 2026-2036
Europe Third Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Third Party Logistics Market Analysis
E-commerce fulfillment is pivoting toward specialized last-mile networks across Europe. DHL Supply Chain & Global Forwarding leverages its pan-European warehouse footprint to anchor pharmaceutical and consumer electronics flows. Kuehne + Nagel sustains competitive density through its digital freight platform integration. DB Schenker differentiates via rail-forwarding dominance on east-west corridors.
Third party logistics encompasses outsourced supply chain management where providers coordinate transportation, warehousing, inventory control, and freight forwarding under service-level agreements typically spanning 3-5 year contracts. Road freight retains the largest share by delivery mode, though rail intermodal solutions are gaining share on carbon-accounting grounds. Warehousing services command premium margins in temperature-controlled and bonded customs facilities. Value-added services, including kitting, labeling, and reverse logistics, represent the fastest-expanding revenue pool as brands outsource non-core fulfillment tasks.
The EU Green Deal and F-Gas Regulation are tightening emission standards for refrigerated transport fleets, while REACH compliance adds chemical-handling protocols to hazardous goods logistics. ECHA classification rules now extend to lithium battery shipments, forcing providers to retool dangerous goods certifications. Stakeholders must monitor how CSRD disclosure requirements reshape shipper selection criteria for logistics partners.
Market Dynamics
The EU Green Deal's emission reduction mandates are compressing fleet replacement cycles and forcing capital reallocation toward electrified refrigerated transport across European logistics corridors.
Growth Catalysts
- Pharmaceutical outsourcing:Cold chain complexity is pushing vaccine and biologics manufacturers toward specialized 3PL partners with EMA-certified temperature validation protocols.
- Rail intermodal incentives:Germany's KBA and France's ecological transition ministry are channeling freight volume onto east-west rail corridors through carbon accounting subsidies.
- E-commerce fulfillment specialization:Same-day delivery promises from Rhine-Ruhr urban clusters are spawning dedicated last-mile micro-fulfillment networks.
Market Restraints
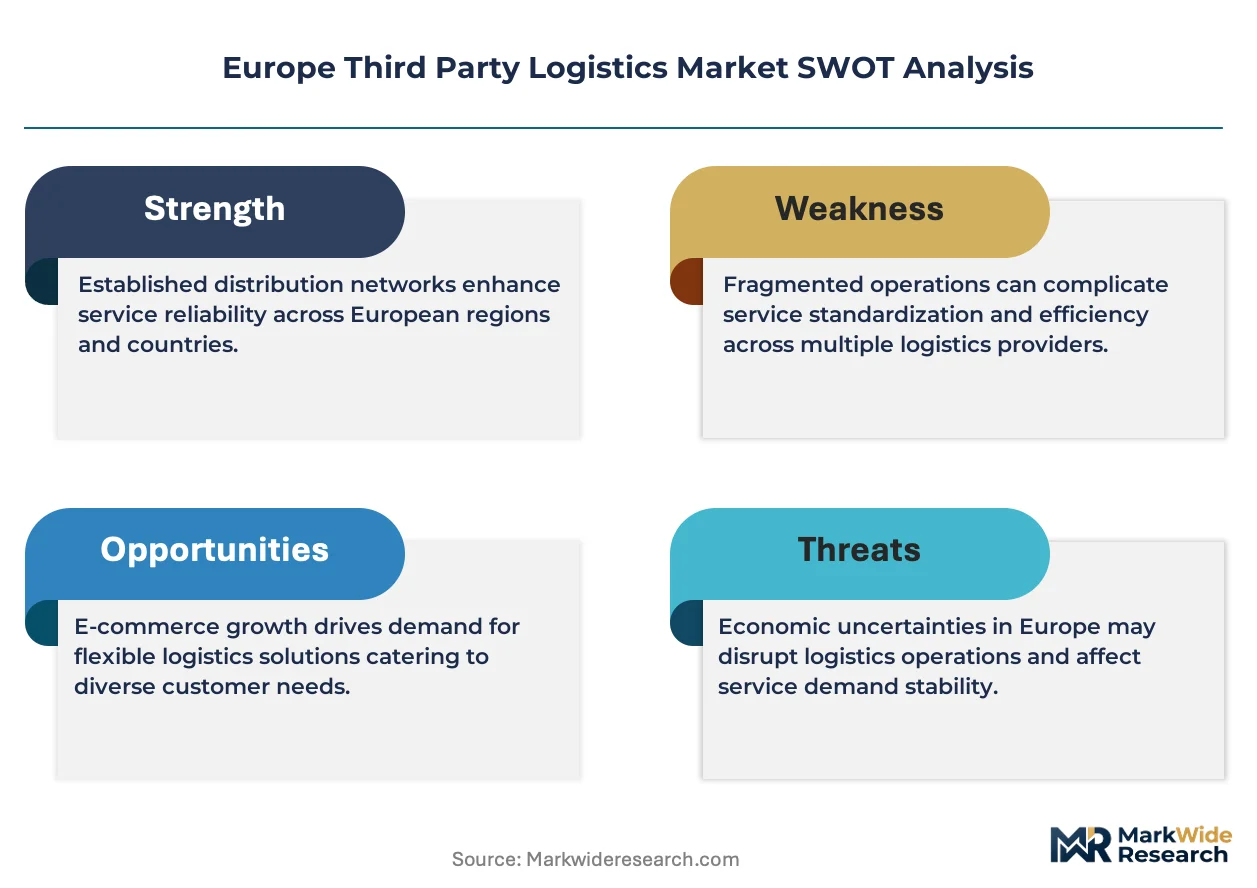
- Refrigerated fleet electrification costs:Battery-electric cold chain vehicles command 40-60% capital premiums over diesel equivalents, compressing SME carrier margins.
- REACH chemical-handling compliance:ECHA classification expansions for lithium battery shipments are extending dangerous goods certification timelines by 8-14 weeks.
- Driver availability constraints:Eastern European labor pools that historically supplied long-haul capacity are tightening due to wage convergence and demographic shifts.
Strategic Opportunities
- Poland-Czech corridor expansion:Underpenetrated Central European manufacturing zones offer first-mover positioning for bonded warehousing and customs facilitation services.
- CSRD-aligned disclosure services:The EU's Corporate Sustainability Reporting Directive is creating premium advisory revenue streams for 3PLs that can audit and document Scope 3 emissions.
- Reverse logistics unbundling:Electronics and apparel brands are separating returns processing from forward fulfillment, opening specialized facility contracts.
Industry Challenges
- Telematics integration complexity:Legacy warehouse management systems at established European carriers resist API connectivity with real-time freight visibility platforms.
- Temperature validation talent scarcity:Qualified cold chain engineers with EMA Good Distribution Practice certification command 25-35% wage premiums in Benelux markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Third Party Logistics Market |
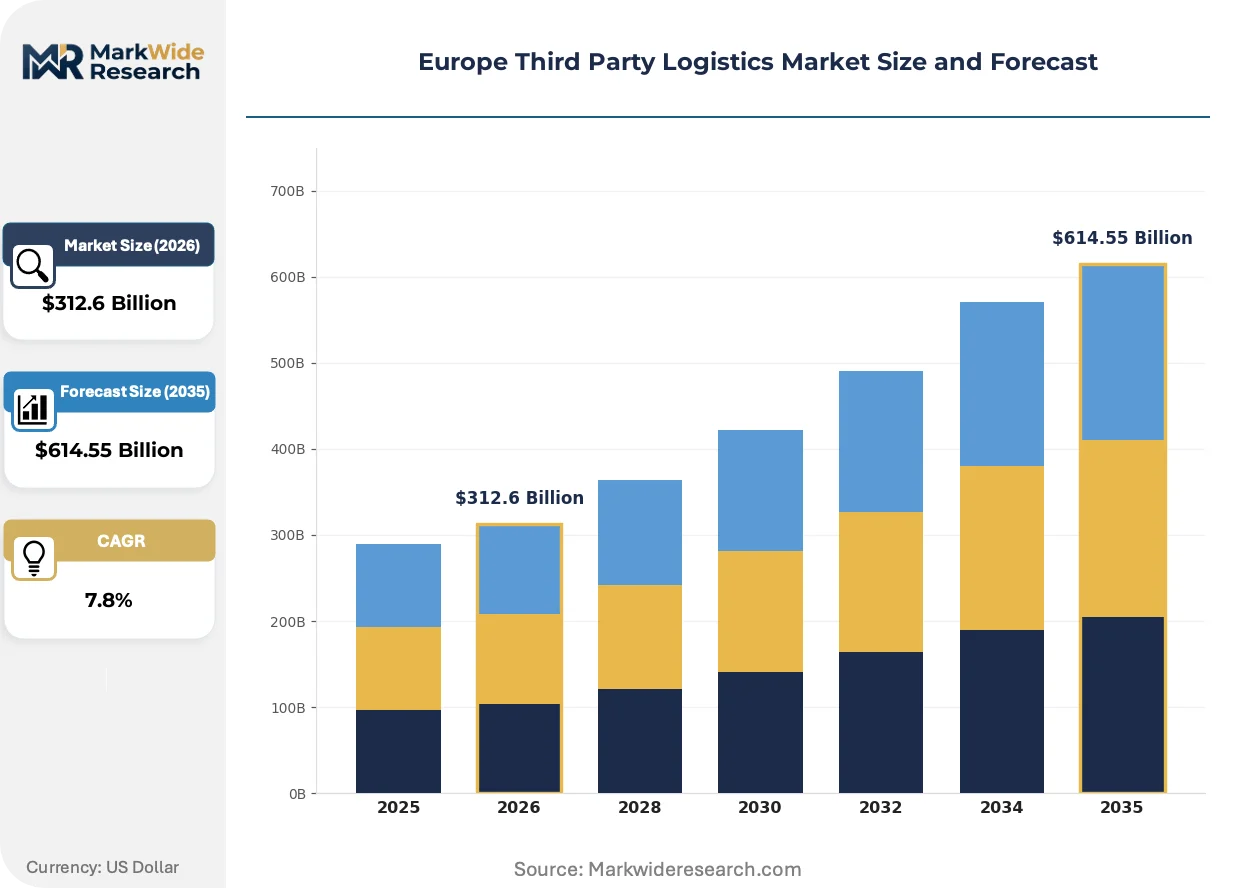
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $614.55 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Value-Added Services End User: Retail, E-commerce, Manufacturing, Automotive Delivery Mode: Road, Rail, Air, Sea Capacity: Small Scale, Medium Scale, Large Scale, Bulk |
| Companies Covered | DB Schenker, Maersk Logistics, DHL Supply Chain & Global Forwarding, Rhenus Logistics, GEODIS, Kuehne + Nagel, CEVA Logistics, DACHSER, DSV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Third Party Logistics Market Emerging Trajectories
Digital freight platforms and electrified cold chain hardware are converging to reshape how European shppers select and contract logistics partners. Sustainability disclosure requirements are becoming competitive differentiators rather than compliance checkboxes.
Autonomous yard management systems are modularizing warehouse throughput by decoupling trailer positioning from human forklift operators. Pharmaceutical distributors in the Netherlands and Belgium are piloting these systems to compress dwell times at temperature-controlled cross-docks. The technology is modularizing facility design assumptions that previously anchored multi-year lease commitments.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing refrigerated transport operators to retool fleet specifications before 2030. EMA-validated cold chain protocols now require alternative cooling technology documentation for cross-border pharmaceutical shipments. German and French carriers are accelerating CO2 refrigeration adoption to maintain biologics handling credentials.
Shippers are unbundling freight procurement from integrated 3PL contracts, creating spot-market platforms for lane-specific capacity. Consumer electronics brands in the Rhine-Ruhr corridor are fragmenting volume across multiple regional carriers rather than consolidating with pan-European incumbents. This pattern is most pronounced in high-velocity electronics where inventory carrying costs exceed freight rate optimization priorities.
Europe Third Party Logistics Market Segmentation
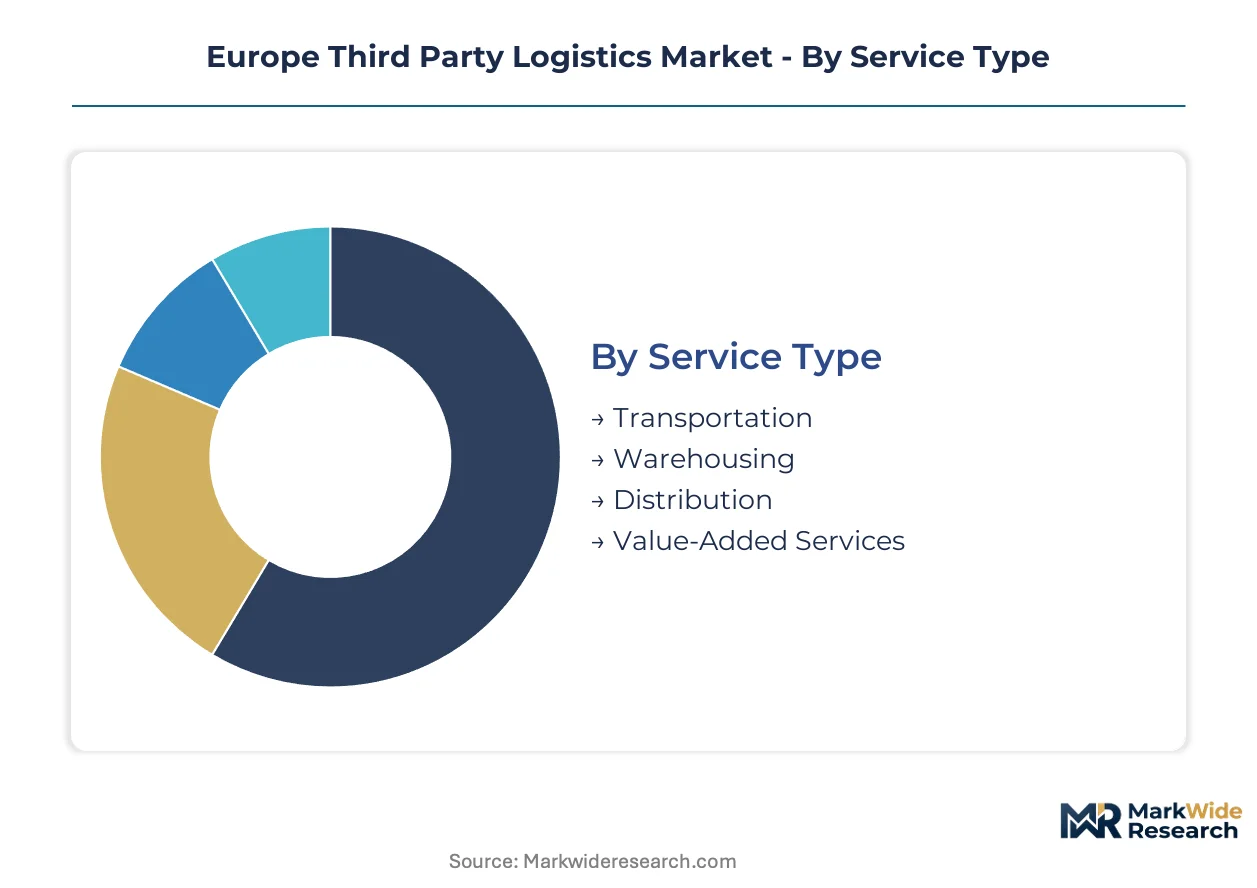
European 3PL procurement patterns diverge sharply by service complexity and regulatory exposure. Buyers segment providers based on cold chain certification depth, carbon disclosure readiness, and cross-border customs integration rather than rate cards alone.
Service Type:
Shippers differentiate providers by asset ownership depth and value-added service breadth.
- Transportation:Full-truckload and less-than-truckload carriage dominates contract value, with Rhine-Ruhr corridor flows commanding premium rates for pharmaceutical and electronics cargo. German KBA emission standards and France's ecological transition subsidies are compressing diesel fleet viability while elevating intermodal rail-road combinations.
- Warehousing:Temperature-controlled and bonded customs facilities extract margin premiums through EMA-validated cold chain protocols and EU customs union compliance infrastructure. Demand concentrates in Netherlands-Belgium pharmaceutical clusters where ECHA chemical-handling rules intersect with REACH lithium battery classifications.
- Distribution:Consolidated last-mile networks serving e-commerce same-day promises in urban Rhine-Ruhr and Paris-Île-de-France clusters.
- Value-Added Services:Kitting, labeling, and reverse logistics processing for apparel and electronics returns.
Volume sits with Transportation; growth tilts toward Value-Added Services.
End User:
Vertical specialization requirements reshape provider selection criteria across buyer categories.
- Retail:Seasonal volume spikes and promotional calendar synchronization demand flexible capacity contracting with penalty clauses for peak-season shortfalls.
- E-commerce:Same-day and next-day delivery promises in dense urban corridors require micro-fulfillment node proximity. This segment climbs the fastest as Rhine-Ruhr and Benelux urban clusters fragment volume across regional specialists rather than pan-European incumbents.
- Manufacturing:Just-in-sequence delivery to assembly plants with vendor-managed inventory integration.
- Automotive:Sequenced parts delivery synchronized to production line takt times.
Manufacturing anchors current contract value; e-commerce reshapes growth trajectories.
Delivery Mode:
Carbon accounting rules and infrastructure density determine modal selection hierarchies.
- Road:Retains dominant share through door-to-door flexibility and established carrier networks across EU member states. Diesel fleet replacement pressures from EU Green Deal mandates are forcing capital reallocation toward electrified alternatives.
- Rail:East-west corridor density through Germany-Poland-Czech routes benefits from carbon subsidy structures. This mode gains share fastest as France and Germany channel freight volume onto intermodal combinations through ecological transition ministry incentives.
- Air:Pharmaceutical and high-value electronics express networks with temperature-controlled container requirements.
- Sea:Deep-sea container feeds into Rotterdam and Hamburg for continental distribution.
Road freight holds volume dominance; rail intermodal captures incremental share expansion.
Capacity:
Scale tier determines pricing leverage and contract structure flexibility.
- Small Scale:Parcel and express networks serving urban last-mile density with dynamic route optimization.
- Medium Scale:Regional pallet networks and shared-user warehousing for mid-market shippers without dedicated facility requirements.
- Large Scale:Dedicated contract logistics with multi-year commitments and customized WMS integration.
- Bulk:Project cargo and industrial freight requiring specialized handling equipment and permit coordination across EU member state jurisdictions.
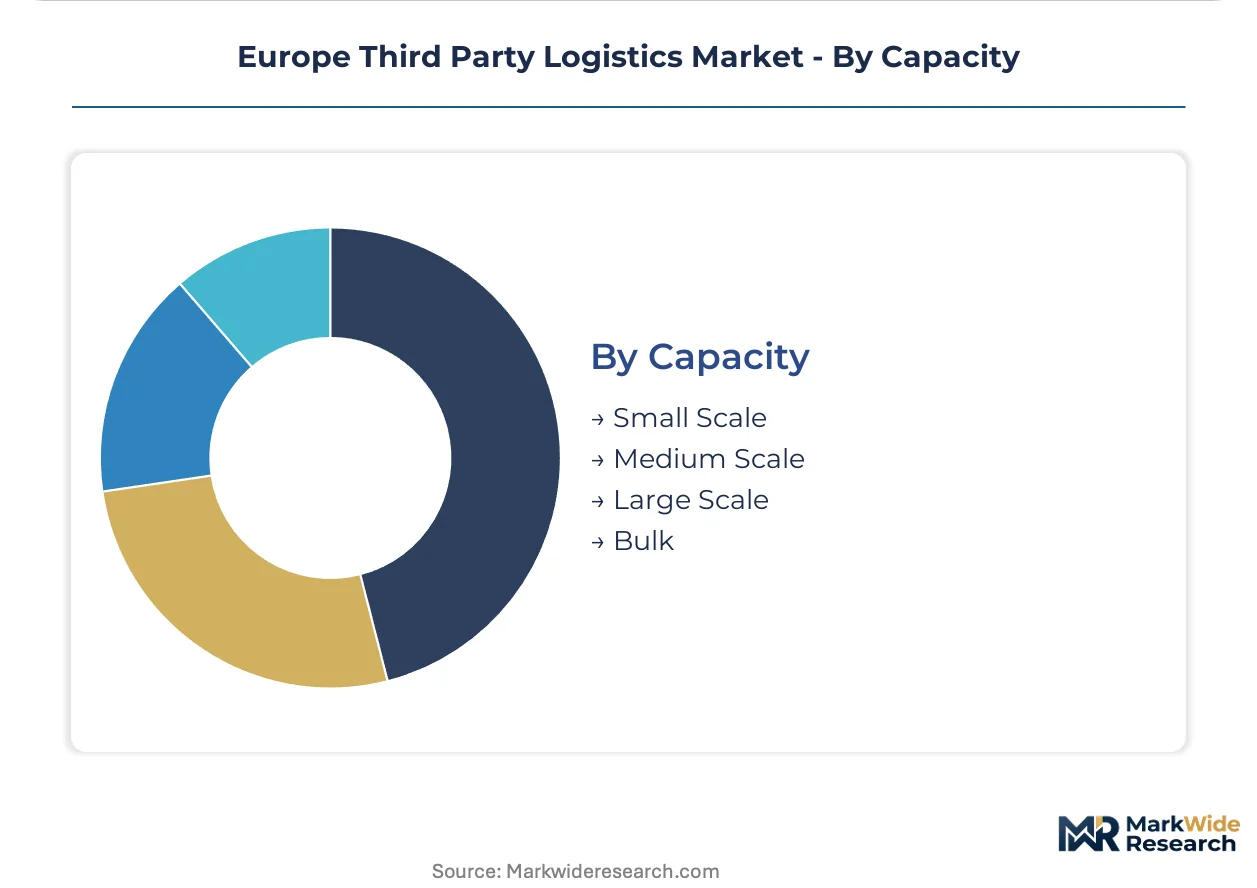
Large Scale contracts concentrate revenue; Small Scale networks expand fastest through e-commerce fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract contract logistics investment through corporate tax exemptions extending through 2026. These zones concentrate automotive and electronics assembly operations demanding bonded warehousing infrastructure. The EU Green Deal's emission mandates are accelerating fleet electrification across Central European corridors.
Germany
The Rhine-Ruhr logistics corridor processes pharmaceutical and consumer electronics flows through Duisburg and Cologne distribution nodes. KBA emission standards compress diesel fleet replacement cycles while channeling freight onto rail intermodal combinations. Bavaria's automotive assembly plants in Munich and Ingolstadt generate just-in-sequence delivery demand for specialized 3PL contracts.
Netherlands
Rotterdam's port-centric logistics cluster handles deep-sea pharmaceutical and chemical imports requiring EMA-validated cold chain protocols. ECHA chemical-handling rules intersect with REACH lithium battery classifications at Venlo and Eindhoven distribution parks. The Randstad urban corridor spawns dedicated last-mile micro-fulfillment networks serving Benelux e-commerce density.
France
Paris-Île-de-France urban logistics demand concentrates same-day delivery capacity around Clichy and Gennevilliers distribution nodes. The ecological transition ministry channels freight volume onto east-west rail corridors through carbon accounting subsidies. Lyon and Grenoble pharmaceutical manufacturing clusters outsource cold chain fulfillment to EMA-certified regional providers.
Poland
Manufacturing investment in Wrocław and Poznań generates bonded warehousing demand for automotive and electronics assembly supply chains. EU structural funds finance intermodal terminal development along the Germany-Poland-Czech rail corridor. Demographic shifts in Eastern European labor pools tighten long-haul driver availability for cross-border freight operations.
Belgium
Antwerp's pharmaceutical distribution cluster requires temperature-controlled facilities with EU customs union compliance infrastructure. Brussels-based regulatory proximity attracts EMA Good Distribution Practice certification services for cross-border biologics shipments. Liège's cargo airport anchors express pharmaceutical networks with alternative cooling technology documentation.
Europe Third Party Logistics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pan-European integrators commanding pharmaceutical and automotive contracts while regional carriers capture e-commerce fragmentation. The vendor base concentrates around four strategic archetypes: rail-forwarding dominants, digital freight platforms, cold chain specialists, and last-mile micro-fulfillment operators. Competitive moves center on fleet electrification partnerships and CSRD-aligned emissions auditing capabilities.
Among Germany-based logistics integrators, DB Schenker and DACHSER occupy positions within rail-forwarding and European pallet network archetypes respectively. DHL Supply Chain & Global Forwarding represents the pan-European warehouse footprint model anchoring pharmaceutical flows. Kuehne + Nagel sits within the digital freight platform tier connecting shippers to capacity across fragmented carrier markets.
| Leading Market Players |
|---|
| DB Schenker |
| Maersk Logistics |
| DHL Supply Chain & Global Forwarding |
| Rhenus Logistics |
| GEODIS |
| Kuehne + Nagel |
| CEVA Logistics |
| DACHSER |
| DSV |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical and e-commerce shippers in the Rhine-Ruhr corridor anchor contract value through multi-year service-level agreements with penalty structures for peak-season shortfalls. These buyers concentrate procurement power among EMA-certified cold chain specialists and rail-forwarding integrators, compressing rate competition to carbon disclosure readiness and temperature validation protocols.
Pricing Analysis
Expedited lead-time commitments command 15-25% rate premiums over standard lane contracts in pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMA certification depth, EU customs union integration, and real-time visibility API connectivity. Cost compression in SME carrier tiers is intensifying because battery-electric refrigerated fleet premiums drain operating margins. Price-sensitive mid-market shippers without dedicated facility requirements gravitate toward shared-user warehousing, while least-sensitive biologics manufacturers prioritize EMA-validated cold chain credentials over rate optimization.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs and pharmaceutical distributors require qualified backup carriers on Germany-Poland-Czech rail corridors. Manufacturing inputs draw from Netherlands-Belgium pharmaceutical clusters, German automotive assembly plants, and Polish electronics Special Economic Zones. Lithium battery cells, hydrofluorocarbon refrigerant alternatives, and intermodal rail capacity constitute critical component dependencies. Single-source vulnerability concentrates in EMA-certified cold chain engineer talent pools across Benelux markets. Distribution runs through Rotterdam and Hamburg deep-sea feeds into continental road-rail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over electrified refrigerated fleet capacity and EMA-certified cold chain engineering talent represents the decisive upstream lever separating consolidators from margin-compressed carriers.
For Market Incumbents: Acquire battery-electric refrigerated vehicle fleets and CO2 refrigeration technology documentation capabilities. Consolidate EMA Good Distribution Practice certification services in Benelux markets to defend against digital freight platform disintermediation. Backward integration into autonomous yard management systems at Netherlands-Belgium cross-docks protects throughput advantages from human forklift operator scarcity. For New Entrants and Emerging Players: Digital freight platforms with real-time carbon accounting APIs offer the most penetrable wedge. Target Poland-Czech corridor bonded warehousing for automotive and electronics assembly supply chains. White-space exists in CSRD-aligned Scope 3 emissions auditing services for mid-market shippers lacking in-house disclosure capabilities. Go-to-market through ecological transition ministry subsidy qualification accelerates rail intermodal volume capture. For Investors and Strategic Acquirers: The window for entry favors cold chain specialists with EMA-validated protocols and electrified fleet transition roadmaps. Long-term viability hinges on regulatory compliance infrastructure rather than pure asset scale. Watch for inflection when EU Green Deal emission mandates accelerate diesel fleet obsolescence beyond replacement cycle capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Secures KBA-compliant refrigerated capacity for pharmaceutical corridors ahead of diesel phaseout deadlines. |
| EMA Certification Acquisition | Transfers validated cold chain protocols and Good Distribution Practice credentials to expand biologics handling. |
| Rail Intermodal Joint Venture | Channels Germany-Poland-Czech freight volume through carbon subsidy structures and ecological ministry incentives. |
| CSRD Auditing Service Launch | Captures premium advisory revenue from shippers facing mandatory Scope 3 emissions disclosure requirements. |
| Reverse Logistics Facility Buildout | Positions for electronics and apparel brand contracts unbundling returns processing from forward fulfillment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet operations directors, pharmaceutical supply chain managers, EMA regulatory affairs specialists, and rail intermodal planners combined with bottom-up carrier capacity assessments and top-down EU trade flow validation. Secondary sources encompassed KBA emission standard filings, ECHA chemical classification updates, EU Green Deal implementation progress reports, and Netherlands customs bonded facility registries.
Data-stream reconciliation across transportation mode splits, service type revenue allocation, and end-user vertical demand patterns informed the analytical framework. Segmentation dimensions modeled included service complexity tier, delivery mode carbon intensity, cold chain certification depth, and geographic corridor density. CAGRs were computed from annual contract value trajectories and fleet capacity expansion pipelines. Forecast inputs incorporated EU structural fund allocations for intermodal terminal development and F-Gas Regulation refrigerant phasedown timelines.
Several conditions sit outside the modeled scope, including abrupt EU member state withdrawal from customs union protocols, lithium battery shipment classification reversals by ECHA, and technological breakthroughs in autonomous long-haul trucking. Forecasts reflect assumptions around subsidy continuity for rail intermodal incentives and EMA certification pathway stability. Deviation in EU Green Deal emission mandate acceleration or battery-electric vehicle total cost of ownership convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
Turkey Cold Chain Logistics Market