
 Turkey Cold Chain Logistics Market | 2026-2036
Turkey Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Cold Chain Logistics Market Analytics
Turkey's updated food safety traceability mandates under the Ministry of Agriculture and Forestry is pivoting the cost-of-entry calculus for cold chain operators. DHL Supply Chain Turkey leverages its integrated warehousing and last-mile refrigerated fleet to dominate pharmaceutical distribution corridors. Ekol Logistics anchors its competitive position through extensive cross-border cold storage capacity linking European and Middle Eastern markets. Kuehne + Nagel differentiates via specialized temperature-controlled solutions for biopharmaceutical clients requiring GDP-compliant handling.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining ranges from deep-frozen minus 25 degrees Celsius to controlled ambient 15-25 degrees Celsius through refrigerated vehicles, insulated containers, and climate-managed warehouses—designed to preserve product integrity of perishable goods, pharmaceuticals, and temperature-sensitive chemicals throughout distribution. Transportation and storage segments command the largest share of operational investment, reflecting the capital intensity of refrigerated fleet assets and multi-temperature warehouse construction. The pharmaceuticals product type category generates premium margin pools due to stringent GDP certification requirements and validated cold chain documentation, while IoT-enabled monitoring technology is displacing conventional manual temperature logging across Turkish distribution networks.
Turkish Ministry of Agriculture and Forestry regulations enforce HACCP-based cold chain compliance for food products, while the Turkish Medicines and Medical Devices Agency (TITCK) mandates GDP standards for pharmaceutical distribution, collectively elevating technical requirements for market participation. BIS-equivalent Turkish Standards Institution certifications for refrigerated transport equipment further shape procurement criteria for logistics buyers. Stakeholders must monitor evolving TITCK guidance on cell and gene therapy distribution requirements, as these advanced therapeutics will demand ultra-low temperature infrastructure investments that reshape competitive positioning in Turkey's cold chain landscape.
Market Dynamics
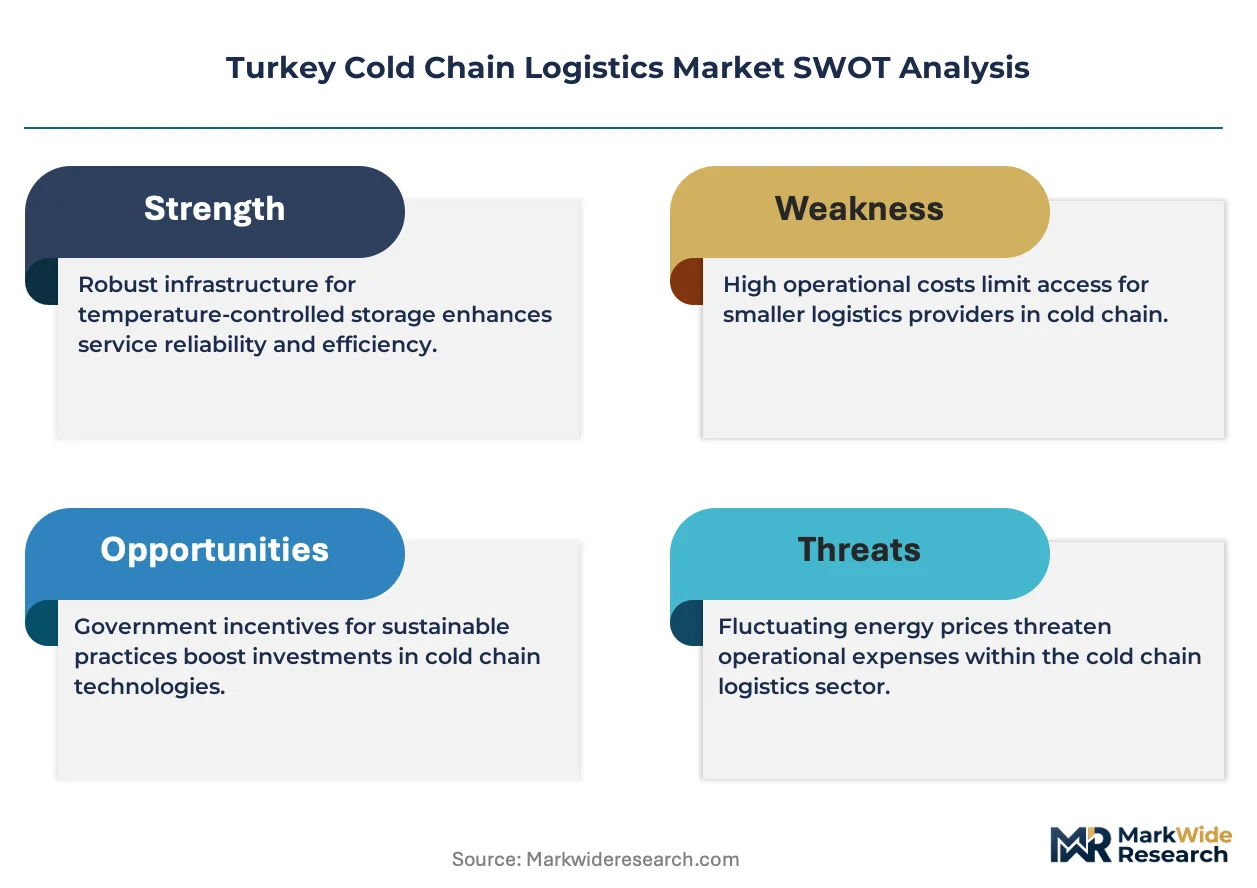
Turkish cold chain operators face a structural squeeze between TITCK's GDP compliance mandates for pharmaceuticals and the Ministry of Agriculture and Forestry's HACCP-based food safety traceability rules, forcing simultaneous capital deployment across dual certification regimes.
Growth Catalysts
- Vaccine and biologics distribution:Turkey's expanding immunization programs and domestic pharmaceutical manufacturing are pulling refrigerated capacity into Ankara and Istanbul corridors. Cold storage buildouts now prioritize validated temperature ranges for mRNA products.
- IoT-enabled temperature monitoring:Real-time sensor networks are replacing manual logging across Turkish warehouse networks. Operators deploying these systems gain audit-ready documentation that satisfies both TITCK and EU export requirements.
- Marmara logistics concentration:The Port of Mersin's container throughput and Istanbul's highway-rail interchanges create natural aggregation points for national cold chain infrastructure. Regional clustering reduces empty backhaul miles for refrigerated fleets.
Market Restraints
- Refrigerated fleet asset intensity:Multi-temperature vehicles with independent cooling zones command 40-60% capital premiums over standard trucks. Turkish operators face compressed ROIC timelines given equipment replacement cycles.
- Cross-border customs friction:EU-Turkey customs union gaps and Middle Eastern border documentation requirements create dwell-time risks for temperature-sensitive cargo. Perishables face spoilage thresholds at Bulgarian and Iranian entry points.
- Electricity grid instability:Warehouse operators in eastern Anatolia report voltage fluctuations that compromise compressor reliability. Backup generator dependence adds opex layers that erode margin pools in lower-density markets.
Strategic Opportunities
- Cell and gene therapy infrastructure:TITCK guidance on advanced therapeutics distribution will mandate ultra-low temperature infrastructure. First-mover operators securing minus 150 degrees Celsius cryogenic capacity will capture premium biopharma contracts.
- Aegean export corridor expansion:Izmir's port modernization and direct ferry links to Greek islands create alternative routing for EU-bound Turkish produce. Refrigerated container flows through this channel bypass Istanbul congestion.
- Blockchain-IoT convergence:Immutable temperature records tied to sensor streams are emerging as a competitive differentiator for Turkish operators serving multinational food brands. Integration costs are falling as platform providers localize offerings.
Industry Challenges
- GDP auditor scarcity:TITCK-qualified validation specialists are concentrated in Istanbul, creating certification bottlenecks for Anatolian warehouse projects. Training pipelines have not scaled with facility construction timelines.
- Multi-temperature warehouse complexity:Simultaneous maintenance of frozen, chilled, and controlled ambient zones within single facilities demands sophisticated building management systems. Turkish engineering capacity for these integrations remains thin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Cold Chain Logistics Market |
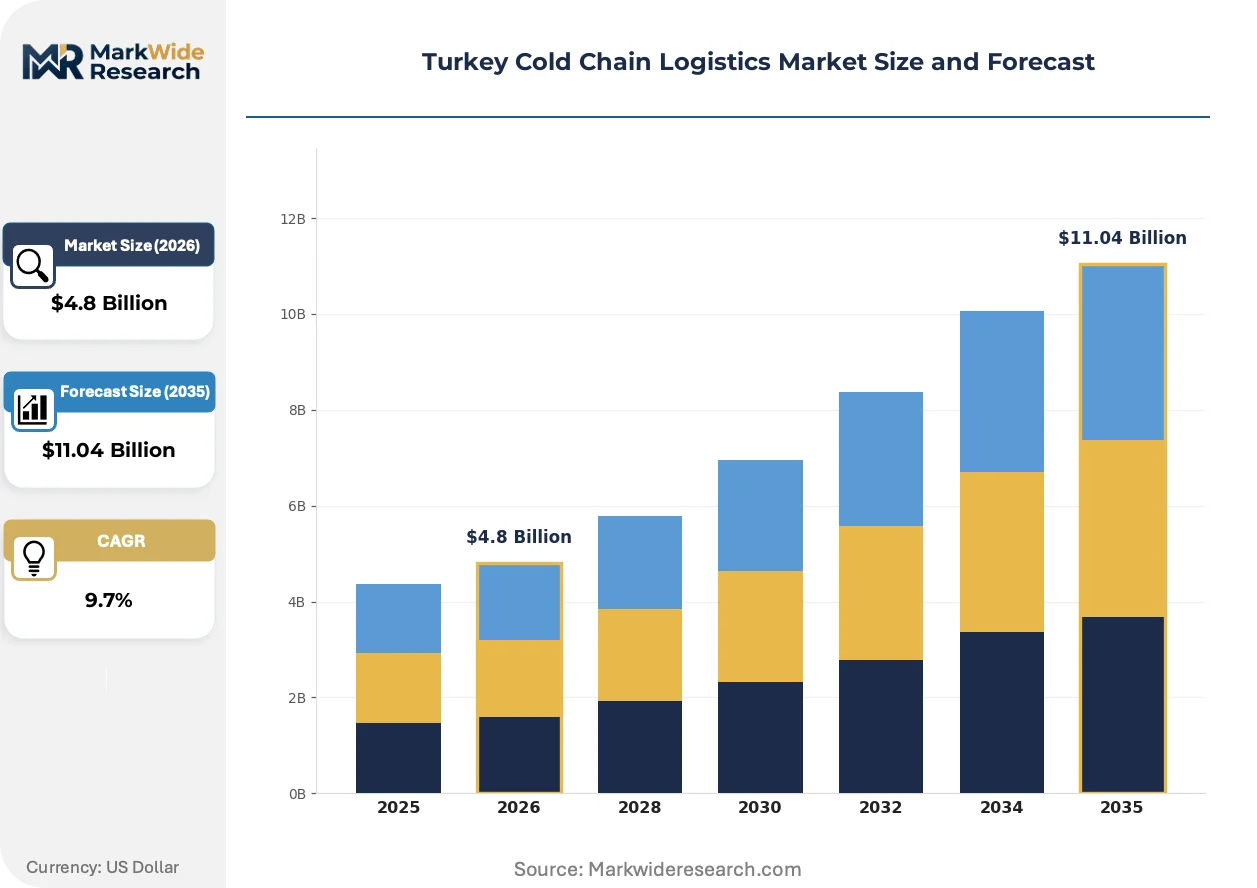
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Transportation, Storage, Packaging, Monitoring Product Type: Pharmaceuticals, Perishables, Chemicals, Electronics End User: Retailers, Distributors, Manufacturers, Hospitals Technology: IoT, RFID, GPS, Automation |
| Companies Covered | DHL Supply Chain Turkey, Kuehne + Nagel, Havi Logistics, CEVA Logistics, DB Schenker, Yusen Logistics, Polar Express Cold Chain Logistics, Agility Logistics Turkey, Ekol Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Cold Chain Logistics Market Evolving Landscape
Digital infrastructure and regulatory precision are converging to reshape Turkish cold chain operations. Three developments dominate the current transformation trajectory.
Refrigerated container racking with automated retrieval systems is modularizing warehouse design across Turkish pharmaceutical distribution centers. Ekol Logistics and DHL Supply Chain Turkey are deploying these configurations in Istanbul hubs to achieve SKU-level temperature segregation. The technology compresses facility footprint requirements while enabling GDP-compliant batch tracking.
TITCK's evolving guidance on good distribution practice for biologics is tightening documentation standards for temperature excursions. Turkish pharmaceutical distributors must now maintain continuous data logger records with 15-minute granularity for international shipments. Cold chain operators serving EU export markets are retrofitting legacy warehouses with redundant sensor networks to preempt audit failures.
Consolidation of buying power among Turkish supermarket chains is compressing third-party logistics contract durations. Retail procurement teams now demand outcome-based pricing tied to delivered quality metrics rather than per-pallet storage rates. This shift is most visible in Marmara region produce distribution, where CarrefourSA and Migros are unbundling transportation from warehousing in vendor selection.
Turkey Cold Chain Logistics Market Segmentation
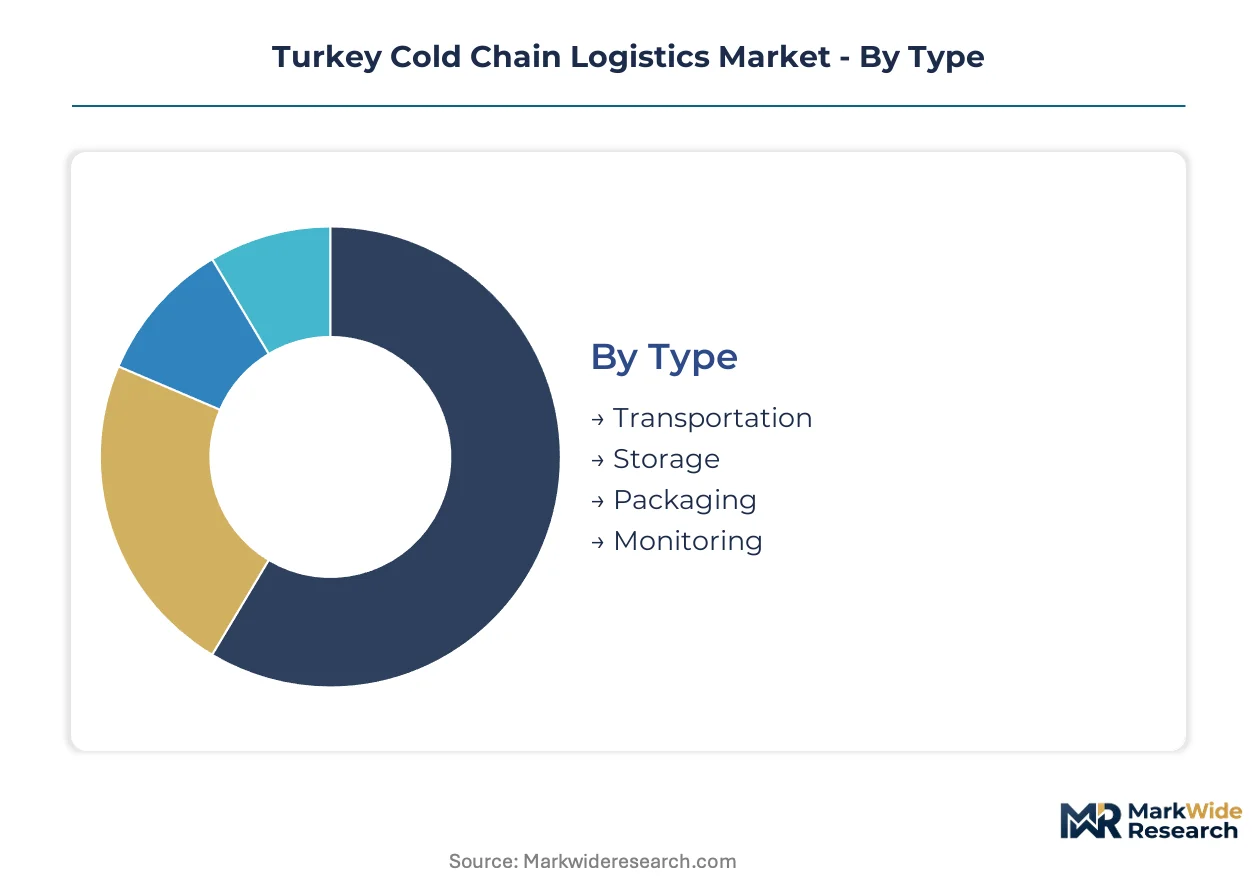
Turkey's cold chain logistics market fragments across operational layers where certification requirements and capital intensity create divergent competitive barriers. Each segment demands distinct technical capabilities and regulatory compliance postures that reshape operator economics.
Type:
TITCK GDP certification and Ministry of Agriculture HACCP mandates apply unevenly across operational types, with pharmaceutical-facing segments bearing heavier audit burdens than food-distribution equivalents.
- Transportation:Multi-temperature refrigerated vehicles with independent cooling zones maintain validated ranges from minus 25 to plus 25 degrees Celsius. Fleet operators in Istanbul and Ankara corridors face compressed replacement cycles amid TITCK's tightening documentation requirements for biologics distribution.
- Storage:Climate-managed warehouses with simultaneous frozen, chilled, and controlled ambient zones require sophisticated building management systems. Marmara region facilities command premium rates due to proximity to the Port of Mersin and Istanbul's highway-rail interchanges.
- Packaging:Insulated containers and phase-change materials provide passive temperature control for last-mile delivery. Turkish pharmaceutical exporters deploy validated cold boxes to satisfy EU GDP requirements at Bulgarian border crossings.
- Monitoring:Real-time sensor networks with 15-minute data granularity are displacing manual temperature logging. IoT-enabled systems generate audit-ready documentation for TITCK inspections and international shipment validation.
Leading the category by volume: Transportation. Growing fastest: Monitoring.
Product Type:
Margin structures vary sharply across product categories, with pharmaceutical handling commanding premium pricing due to GDP compliance costs that food distributors avoid.
- Pharmaceuticals:Vaccines, biologics, and cell therapies demand validated cold chains with continuous temperature documentation. mRNA product distribution in Ankara and Istanbul is pulling investment toward ultra-low temperature infrastructure.
- Perishables:Fresh produce, dairy, and meat products require HACCP-compliant handling under Ministry of Agriculture traceability mandates. Aegean export corridors through Izmir are expanding refrigerated container capacity for EU-bound shipments.
- Chemicals:Temperature-sensitive industrial compounds need controlled ambient storage between 15 and 25 degrees Celsius. Turkish chemical distributors face lower regulatory burdens than pharmaceutical or food handlers.
- Electronics:Semiconductors and precision components require humidity-controlled environments alongside temperature management. Electronics cold chain remains the smallest product category in Turkey's market structure.
Highest margin capture: Pharmaceuticals. Steepest expansion trajectory: Perishables driven by supermarket consolidation.
End User:
Procurement sophistication divides end users, with multinational pharmaceutical manufacturers imposing stricter vendor qualification than domestic food retailers.
- Retailers:Turkish supermarket chains including CarrefourSA and Migros are unbundling transportation from warehousing contracts. Outcome-based pricing tied to delivered quality metrics is replacing per-pallet storage rates in Marmara region produce distribution.
- Distributors:Third-party logistics providers serve as intermediaries between manufacturers and downstream customers. Pharmaceutical distributors in Istanbul and Ankara are expanding refrigerated capacity to capture vaccine and biologics volume.
- Manufacturers:Domestic pharmaceutical and food producers are building captive cold chain infrastructure. Turkish vaccine manufacturers require GDP-compliant distribution networks for both domestic immunization programs and export markets.
- Hospitals:Healthcare facilities demand just-in-time delivery of temperature-sensitive therapeutics and diagnostics. Ankara's hospital clusters are driving localized cold storage buildouts for biologics administration.
Contract value concentration: Distributors. Procurement innovation leader: Retailers.
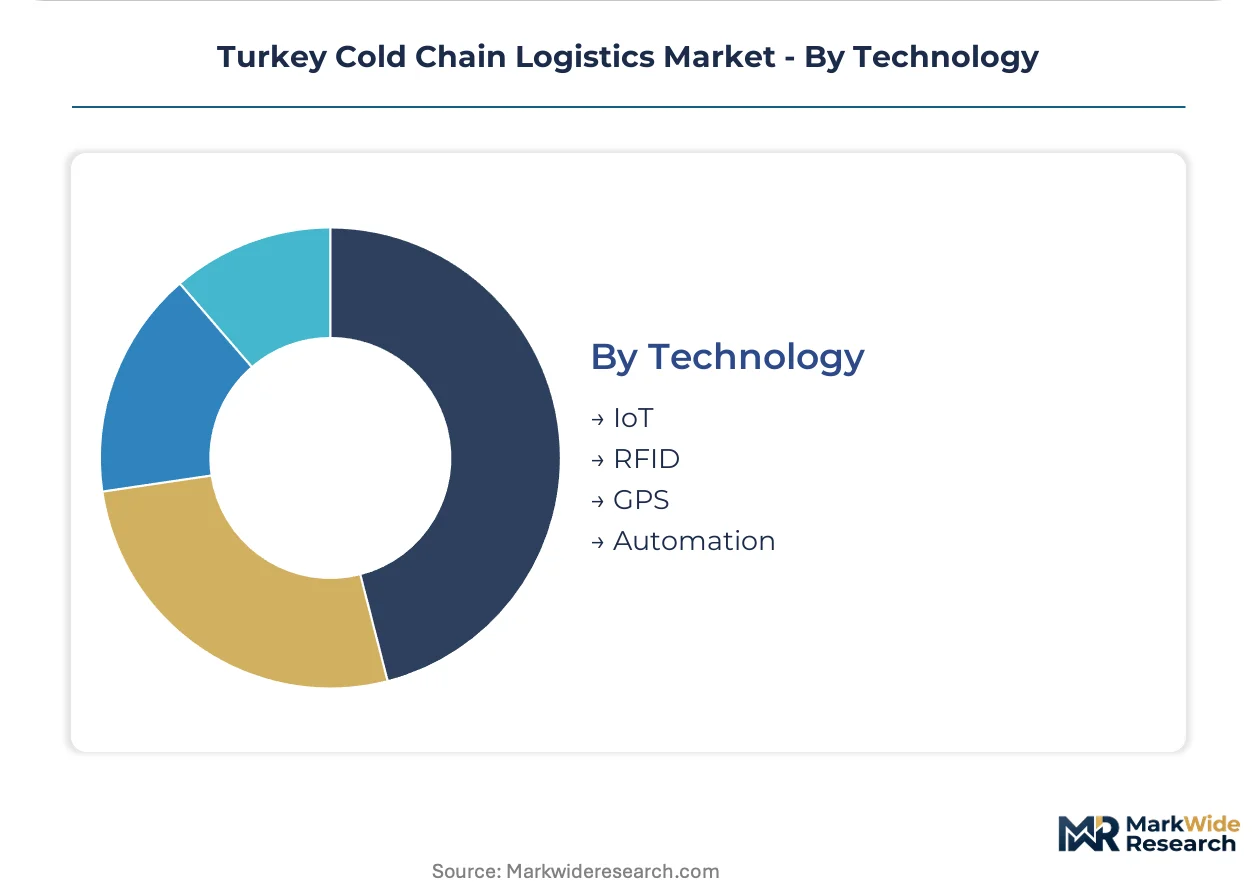
Technology:
Technology deployment correlates with customer export orientation, with EU-facing operators investing more heavily in traceability systems than domestically focused competitors.
- IoT:Sensor networks enabling real-time temperature, humidity, and location tracking are becoming standard in pharmaceutical warehouses. Turkish operators deploying redundant IoT systems gain competitive advantage in TITCK audits and EU export qualification.
- RFID:Radio-frequency identification enables SKU-level batch tracking through distribution networks. RFID integration with automated warehouse systems supports GDP-compliant pharmaceutical handling in Istanbul hubs.
- GPS:Fleet telematics provide route optimization and dwell-time alerts for refrigerated transport. Cross-border operators use GPS tracking to preempt customs delays at Bulgarian and Iranian entry points.
- Automation:Automated storage and retrieval systems compress facility footprints while enabling precise temperature zone segregation. Ekol Logistics and DHL Supply Chain Turkey are deploying these configurations for pharmaceutical distribution efficiency.
Widest installed base: GPS. Fastest technology climb: IoT displacing manual logging systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's cold chain logistics demand concentrates in the Marmara region, where Istanbul's pharmaceutical corridors and Ankara's biologics clusters pull refrigerated capacity toward the country's northwestern industrial spine.
Marmara Region
Istanbul's vaccine distribution networks and the Port of Mersin's container throughput anchor national cold chain infrastructure. TITCK's GDP compliance mandates for pharmaceutical exports force warehouse operators in Gebze and Tuzla to deploy redundant sensor networks. The Istanbul-Ankara highway corridor hosts the densest concentration of multi-temperature facilities serving both domestic and EU-bound shipments.
Aegean Region
Izmir's port modernization and direct ferry links to Greek islands are expanding refrigerated container flows for Turkish produce exporters. The Ministry of Agriculture's HACCP traceability rules apply stringently to Aegean olive oil and dairy shipments. Cold storage buildouts in Manisa and Aydın prioritize EU export qualification to bypass Istanbul congestion.
Central Anatolia
Ankara's hospital clusters and domestic vaccine manufacturing plants are driving localized GDP-compliant warehouse construction. The Turkish Medicines and Medical Devices Agency maintains its headquarters here, creating regulatory proximity advantages for pharmaceutical distributors. Konya's agricultural processing zones demand chilled capacity for dairy and meat distribution to Istanbul markets.
Mediterranean Region
Antalya's greenhouse agriculture exports and Mersin's port logistics create dual demand streams for refrigerated transport. Food safety traceability mandates from the Ministry of Agriculture and Forestry apply to citrus and vegetable shipments through this corridor. Cold chain operators here face electricity grid instability that compromises compressor reliability in peak summer months.
Black Sea Region
Samsun and Trabzon anchor hazelnuts, tea, and fisheries exports requiring temperature-controlled handling. The region's mountainous terrain complicates last-mile refrigerated delivery to coastal processing facilities. Operators here serve lower-margin agricultural segments with less stringent certification requirements than pharmaceutical corridors.
Turkey Cold Chain Logistics Market Competitive Landscape
European logistics majors anchor one tier; Turkish domestic specialists hold regional density advantages through localized fleet networks and customs brokerage relationships. The market presents a tiered structure where global forwarders compete on pharmaceutical certification depth against national operators optimizing for cross-border agility. Three archetypes dominate: integrated supply chain managers with GDP-validated warehousing, regional cold storage specialists with multi-temperature facilities, and port-centric operators leveraging Mersin's container throughput. Competitive moves concentrate on automated warehouse deployments and strategic partnerships with supermarket chains seeking outcome-based logistics contracts.
Among European-anchored integrated providers, DHL Supply Chain Turkey and Kuehne + Nagel occupy positions exemplifying pharmaceutical-grade certification depth and biopharmaceutical handling specialization. Ekol Logistics represents the domestic specialist archetype, with its cross-border cold storage capacity linking European and Middle Eastern markets. These three companies illustrate the competitive tension between global compliance standards and regional operational density that defines Turkish cold chain positioning.
| Leading Market Players |
|---|
| DHL Supply Chain Turkey |
| Kuehne + Nagel |
| Havi Logistics |
| CEVA Logistics |
| DB Schenker |
| Yusen Logistics |
| Polar Express Cold Chain Logistics |
| Agility Logistics Turkey |
| Ekol Logistics |
| Others |
Value Network & Pricing Analysis
GDP-certified validation specialists concentrated in Istanbul create labor-cost differentials that widen pricing-tier spreads between Marmara-region pharmaceutical corridors and Anatolian food-distribution networks. Turkish cold chain operators absorb premium wage structures for TITCK-qualified auditors while eastern warehouse projects face compressed margins from certification bottlenecks.
Pricing Analysis
Volume concentrates in food-distribution contracts while margin pools accrue to pharmaceutical handling. Three-tier pricing structure across GDP-validated premium, HACCP-compliant standard, and non-certified economy levels separates Turkish operators by audit readiness. Pricing pressure stems from supermarket chains unbundling transportation from warehousing and demanding outcome-based contracts tied to delivered quality metrics. Domestic food retailers exhibit highest price sensitivity, while multinational biopharmaceutical manufacturers accept premium rates for validated cold chain documentation.
Supply Chain Analysis
Turkish Standards Institution certifications for refrigerated transport equipment function as de facto local-content rules, reshaping sourcing toward domestically certified compressor and insulation suppliers. Equipment manufacturing draws from Germany, Italy, and China for core refrigeration components, while sensor networks and IoT platforms rest on South Korean and Taiwanese semiconductor inputs. Single-source vulnerability runs through EU-bound pharmaceutical exports facing customs union documentation gaps at Bulgarian border crossings. Distribution feeds from Istanbul-Ankara corridor aggregation points through cross-border forwarding networks into European and Middle Eastern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkish cold chain logistics is becoming a vertical-integration race as operators pursue captive control over GDP-certified warehousing to escape auditor scarcity bottlenecks and capture biopharmaceutical margin pools.
For Market Incumbents: Deploy redundant IoT sensor networks across legacy warehouse portfolios to preempt TITCK audit failures and defend contract renewals against European logistics majors. Consolidate validation specialist training pipelines through partnerships with Ankara-based technical institutes to reduce certification delays for eastern Anatolia expansion projects. Backward integration into refrigerated fleet maintenance capabilities will compress opex layers eroded by electricity grid instability. For New Entrants and Emerging Players: TITCK's evolving guidance on cell and gene therapy distribution opens a window for ultra-low temperature infrastructure plays in Ankara hospital corridors. Target Aegean region produce exporters seeking EU qualification through Izmir port modernization, bypassing Istanbul congestion. White-space exists in blockchain-IoT convergence platforms for multinational food brands demanding immutable temperature records. Go-to-market through outcome-based pricing pilots with mid-sized supermarket chains unbundling logistics contracts. For Investors and Strategic Acquirers: Re-rating potential sits with domestic specialists possessing cross-border cold storage capacity linking European and Middle Eastern markets, given accelerating biopharmaceutical export volumes from Turkish vaccine manufacturers. Long-term viability frames around operators securing minus 150 degrees Celsius cryogenic infrastructure ahead of TITCK mandates. Acquisition targets should display GDP-validated warehousing plus established customs brokerage relationships at Mersin and Izmir ports. Watch TITCK publication timelines for advanced therapeutics distribution guidance as the inflection signal for infrastructure investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Low Temperature Infrastructure Buildout | Positions operators to capture TITCK-mandated cell and gene therapy contracts ahead of regulatory deadlines. |
| IoT-Blockchain Platform Integration | Generates immutable temperature records that satisfy multinational food brand traceability requirements. |
| GDP Certification Training Pipeline Investment | Resolves Istanbul-concentrated auditor scarcity constraining Anatolian warehouse project timelines. |
| Aegean Export Corridor Capacity Expansion | Captures Izmir port modernization flows for EU-bound Turkish produce bypassing Istanbul congestion. |
| Multi-Temperature Fleet Renewal Program | Replaces aging refrigerated vehicles facing compressed ROIC timelines under TITCK documentation tightening. |
Research Methodology
Document review covered TITCK regulatory filings, Turkish Ministry of Agriculture traceability mandates, and EU GDP guidance documents, complemented by interviews with cold chain operations directors, pharmaceutical distribution managers, and supermarket procurement leads. Secondary validation drew from customs trade databases, refrigerated transport equipment certification records, and hospital procurement disclosures. Bottom-up facility capacity counts triangulated against top-down market size estimates across the analysis window.
Segmentation outputs reflect operational type, product category, end-user procurement sophistication, and technology deployment intensity modeled throughout the forecast period. CAGRs derived from trend extrapolation of refrigerated warehouse construction permits, pharmaceutical export volumes, and IoT sensor installation rates. Forecast inputs incorporated TITCK audit frequency data and supermarket chain consolidation patterns.
The model assumes a particular technology adoption path for IoT-enabled temperature monitoring; alternative pathways for manual logging persistence or blockchain-IoT convergence acceleration would alter the outlook. Forecasts reflect assumptions around TITCK guidance publication timing, EU-Turkey customs union stability, and electricity grid reliability in eastern Anatolia. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
United States Air Freight Market