
 Chile Cold Chain Logistics Market | 2026-2036
Chile Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Cold Chain Logistics Market Outlook
HACCP certification is rotating toward a baseline market-access requirement for Chilean cold chain operators seeking European and North American export lanes. Emergent Cold LatAm leverages its LatAm network scale to anchor regional cross-border refrigerated corridors. Transportes Nazar competes through specialized seafood logistics along the Los Lagos coastline. Friofort SA sustains domestic dairy distribution dominance via controlled-atmosphere fleet assets.
Cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods within specified thermal bands, typically minus 25°C to plus 15°C, utilizing insulated vehicles, refrigerated containers, and monitored warehousing to preserve product integrity. The primary purpose centers on extending shelf life and ensuring safety across food, pharmaceutical, and chemical supply chains. Refrigerated transport leads solution-type revenue given Chile's elongated geography and export-dependent agricultural economy. IoT Solutions within temperature monitoring represents the fastest-expanding technology segment as real-time telemetry reduces spoilage claims and satisfies buyer audit requirements. Cold storage occupies mature margin pools in Valparaíso and Biobío port zones where land scarcity limits new facility development.
Chile's Sanitary Code enforcement by the Ministry of Health, coupled with SUBPESCA seafood traceability mandates and EU F-Gas Regulation alignment via the National Customs Service, shapes equipment replacement cycles and refrigerant transition timelines. These frameworks compel fleet operators to phase out high-GWP coolants and install continuous data-logging systems prior to export clearance. Stakeholders must weigh capital allocation between automated warehousing upgrades and last-mile refrigerated capacity as e-commerce grocery penetration reshapes service-level expectations.
Market Dynamics
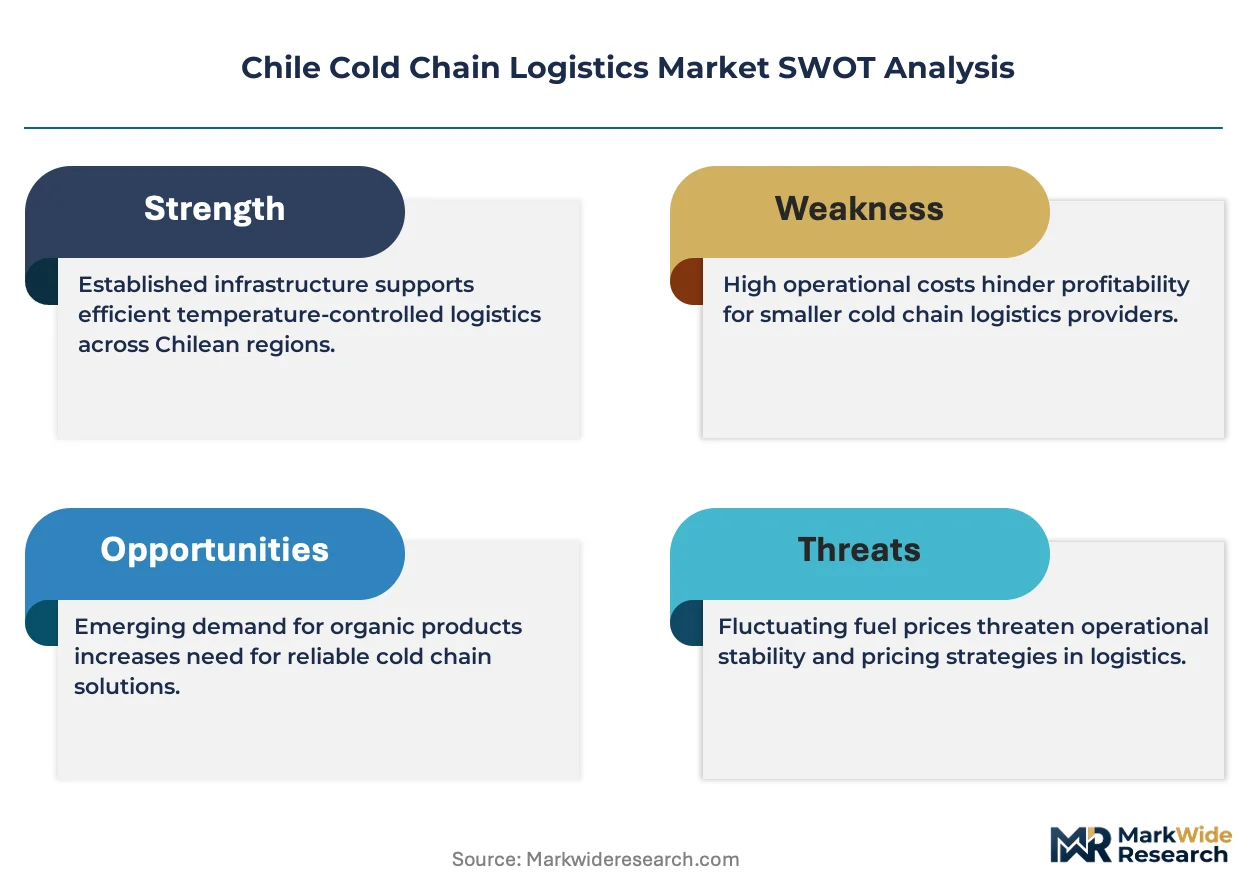
EU F-Gas Regulation alignment is forcing Chilean cold chain operators to retire high-GWP refrigerants ahead of equipment end-of-life, compressing replacement cycles and reshaping capital deployment priorities across port-based storage and long-haul fleet assets.
Growth Catalysts
- Sanitary Code traceability mandates:Chile's Ministry of Health now requires HACCP-aligned digital logs across seafood and dairy handling facilities, pulling investment into temperature-monitoring infrastructure.
- Fresh produce export corridors:Exporters in O'Higgins and Maule regions are scaling controlled-atmosphere capacity to satisfy EU phytosanitary entry requirements for stone fruit and table grapes.
- IoT telemetry adoption:Real-time cold chain visibility tools are reducing spoilage claims and satisfying buyer audit requirements from European retail consolidation.
Market Restraints
- Land scarcity in port zones:Valparaíso and Biobío face constrained greenfield development for automated cold storage, elevating facility costs and extending project timelines.
- Refrigerant transition costs:The shift from R-404A and R-22 to lower-GWP alternatives demands simultaneous equipment replacement and technician retraining.
- Energy price volatility:Chile's grid-dependent cold storage operators face margin compression from fluctuating electricity tariffs in the central interconnected system.
Strategic Opportunities
- E-commerce grocery penetration:Last-mile refrigerated capacity remains underdeveloped in Santiago's outer metropolitan ring, creating white space for urban micro-fulfillment hubs.
- Los Lagos seafood specialization:The southern coastline's salmon and shellfish processing clusters lack integrated cold chain density, opening corridor development for temperature-controlled multimodal links.
- SUBPESCA traceability incentives:Early compliance with seafood origin documentation requirements unlocks preferential export clearance and premium market access.
Industry Challenges
- Refrigeration technician shortage:The domestic labor pool lacks certified personnel for next-generation coolant systems and automated warehouse management platforms.
- Legacy fleet integration:Smaller transport operators struggle to retrofit existing vehicles with continuous data-logging hardware required for export lane qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Cold Chain Logistics Market |
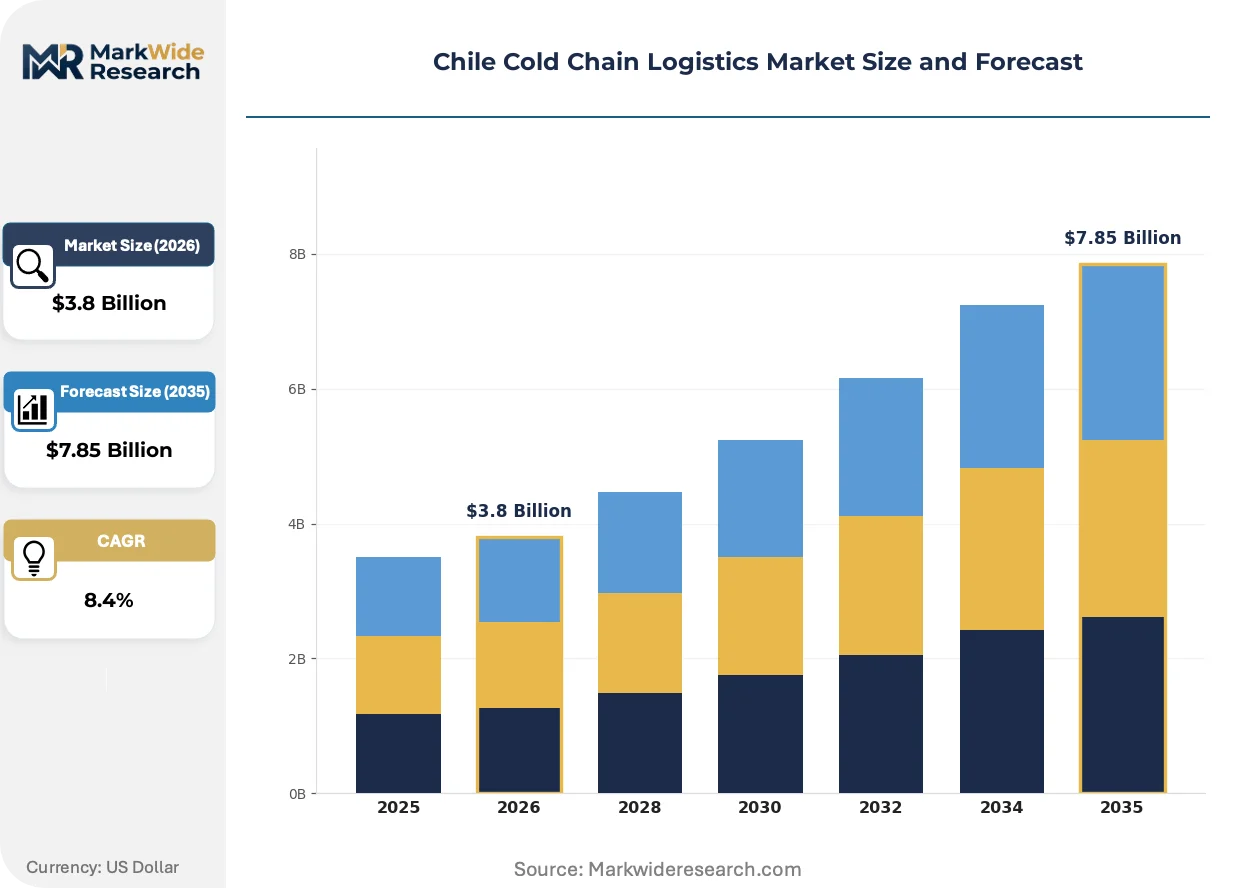
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Seafood Solution Type: Refrigerated Transport, Cold Storage, Temperature Monitoring, Packing Solutions End User: Retailers, Distributors, Food Manufacturers, Restaurants Technology: IoT Solutions, Refrigeration Systems, Automated Warehousing, Blockchain |
| Companies Covered | Empresas Taylor, Frigorificos Puerto Montt, Transportes Nazar, Emergent Cold LatAm, Ceva Logistics, Tudefrigo SA, Friofort SA, IceStar Chile, Megafrio Chile SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Cold Chain Logistics Market Strategic Shifts
Telematics-enabled predictive maintenance is compressing equipment downtime and reshaping service contracts across Chile's elongated logistics corridors. Three developments are reconfiguring competitive positioning.
Phase-change materials in insulated shipping containers are supplanting diesel-powered mechanical refrigeration for medium-haul produce movements. Berry exporters to North America are adopting these passive systems for trans-Pacific ocean freight legs. The technology is compressing fuel cost exposure and simplifying customs inspection protocols at destination ports.
Chile's National Customs Service is accelerating alignment with EU F-Gas Regulation timelines, requiring import documentation for refrigerant-containing equipment to specify GWP ratings and disposal certification. Cold storage developers in the Biobío region are prioritizing ammonia-CO2 cascade systems in new builds. Seafood processors face the steepest compliance curve given existing fleet age profiles.
Consolidated retail buyers are unbundling temperature-controlled transport from storage contracts, forcing logistics providers to bid lane-by-lane rather than on integrated warehouse-plus-delivery bundles. Santiago-based supermarket chains are driving this fragmentation. Dairy distributors in the Central Valley are experiencing the sharpest margin compression from this procurement shift.
Chile Cold Chain Logistics Market Segmentation
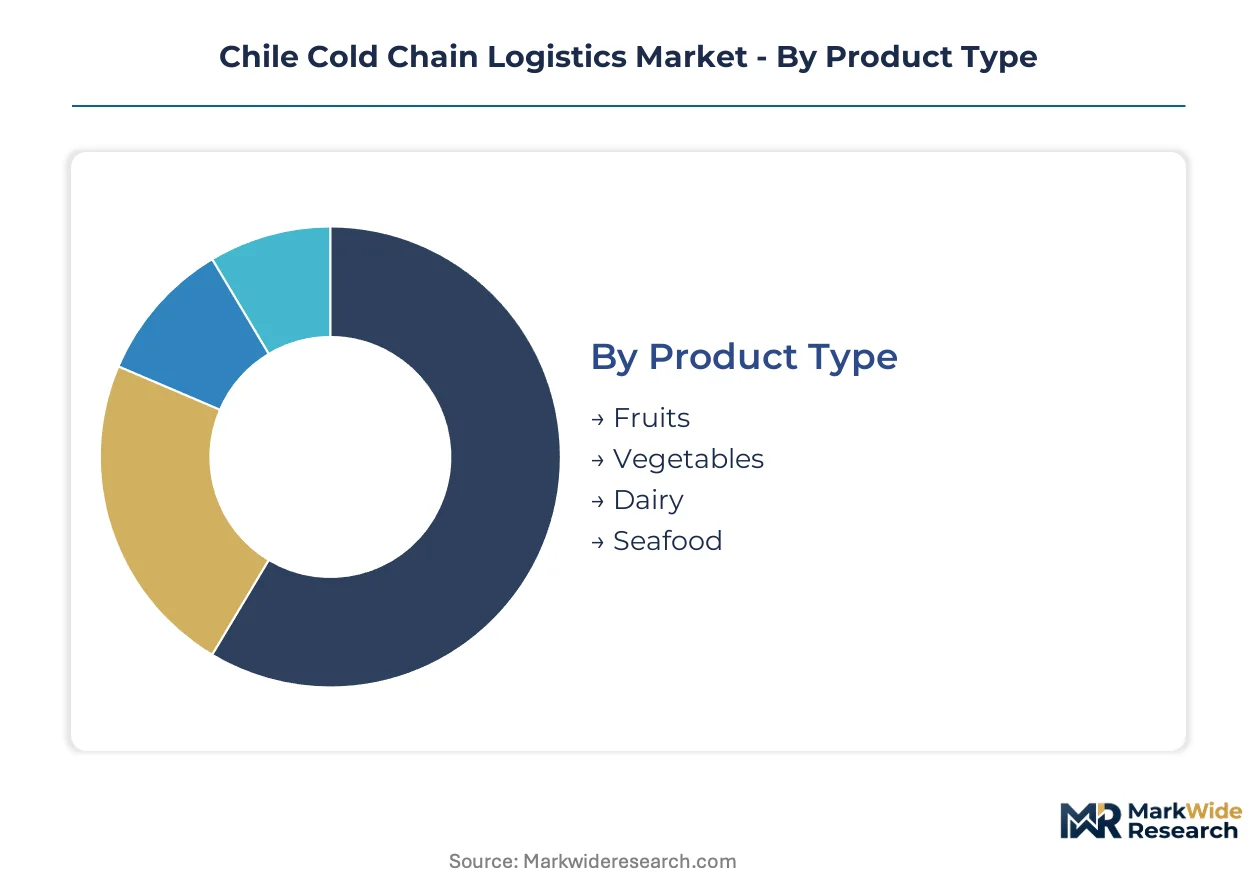
Chile's cold chain logistics segmentation reflects the country's dual identity as a domestic consumption market and a global agricultural exporter. Product flows split between Santiago metropolitan distribution and port-bound export corridors, with each segment demanding distinct temperature protocols and compliance frameworks.
Product Type:
Domestic consumption concentrates on dairy and fresh vegetables, while fruits and seafood dominate export-led demand through Valparaíso and San Antonio ports.
- Fruits:Controlled-atmosphere protocols for stone fruit and table grapes bound for EU and North American markets. O'Higgins and Maule region exporters are expanding pre-cooling capacity to meet phytosanitary entry requirements.
- Seafood:Salmon and shellfish from Los Lagos processing clusters require continuous chain-of-custody documentation under SUBPESCA traceability mandates. Temperature excursions trigger automatic export clearance rejection.
- Vegetables:Leafy greens and brassicas move through shorter domestic circuits with less stringent documentation.
- Dairy:Fluid milk and cheese distribution centers on Central Valley production zones serving Santiago retailers.
Fruits holds the largest share; momentum sits with seafood as traceability compliance deepens value-added processing.
Solution Type:
Cost tier differentiation separates capital-intensive infrastructure from asset-light service models, with integrated operators capturing margin across multiple solution layers.
- Refrigerated Transport:Long-haul fleet assets connecting Central Valley production to port terminals. Chile's elongated geography favors dedicated refrigerated trucking over rail alternatives.
- Cold Storage:Automated high-bay facilities in Biobío and Valparaíso face land scarcity constraints. Existing operators command premium rates for bonded warehouse capacity.
- Temperature Monitoring:Real-time telemetry systems are climbing the fastest as HACCP-aligned digital logs become mandatory for seafood and dairy handling.
- Packing Solutions:Phase-change material containers for trans-Pacific produce movements reduce fuel cost exposure.
Refrigerated transport anchors revenue; cold storage claims the steepest margin expansion trajectory.
End User:
Customer type segmentation reveals procurement fragmentation, with consolidated retail buyers unbundling transport from storage contracts.
- Retailers:Santiago supermarket chains are driving lane-by-lane bidding rather than integrated warehouse-plus-delivery bundles.
- Distributors:Dairy and produce wholesalers in the Central Valley experience sharpest margin compression from disaggregated procurement.
- Food Manufacturers:Processed meat and ready-meal producers require synchronized inbound ingredient and outbound finished goods temperature control.
- Restaurants:Foodservice operators represent emerging last-mile demand as e-commerce grocery penetration reshapes urban logistics.
Retailers command the largest volume; restaurants are gaining share fastest through delivery platform expansion.
Technology:
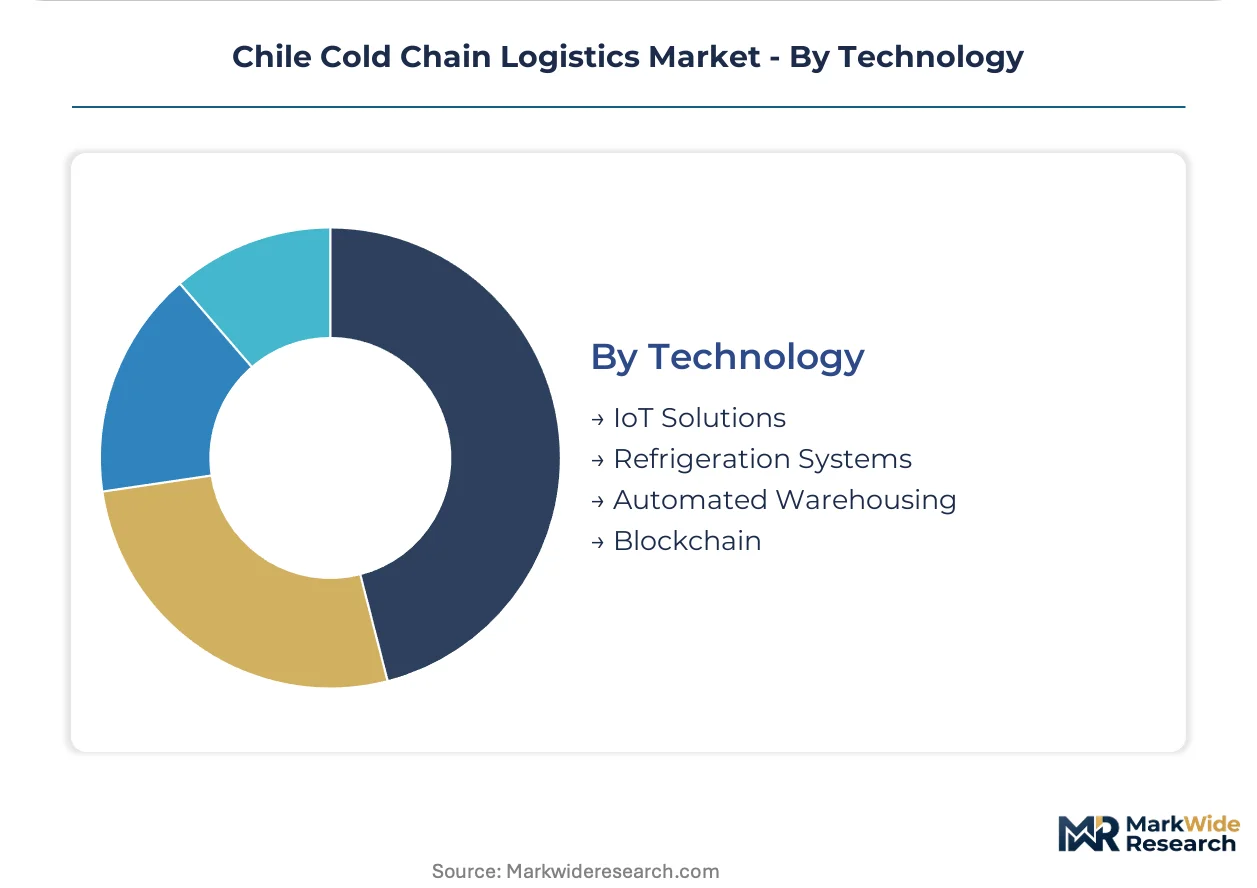
Technology maturity separates proven refrigeration hardware from emerging digital layers, with adoption curves varying by export lane requirements.
- IoT Solutions:Sensor networks and cloud-based visibility platforms reduce spoilage claims and satisfy European retail audit requirements.
- Refrigeration Systems:Ammonia-CO2 cascade systems are displacing high-GWP alternatives in new Biobío facilities as EU F-Gas alignment accelerates.
- Automated Warehousing:Robotics and warehouse management systems face technician shortage constraints in domestic labor markets.
- Blockchain:Distributed ledger pilots for seafood origin documentation remain pre-commercial despite SUBPESCA incentive structures.
Refrigeration systems dominate installed base; IoT solutions are expanding most quickly through retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail consolidation in Santiago drives procurement centralization, while export corridors radiate toward Valparaíso and San Antonio ports. Cold storage investment clusters along these axes, with regulatory enforcement tightening traceability requirements across all zones.
Greater Santiago Metropolitan Region
Santiago anchors domestic consumption demand through supermarket chain distribution networks. The Ministry of Health enforces updated Sanitary Code provisions mandating HACCP-aligned digital logs across dairy handling facilities. Last-mile refrigerated capacity remains underdeveloped in the outer metropolitan ring, opening white space for urban micro-fulfillment hubs.
Valparaíso Region
Port-bound fruit exports generate concentrated cold storage demand for EU and North American phytosanitary compliance. EU F-Gas Regulation alignment via the National Customs Service shapes equipment replacement cycles for bonded warehouse operators. Land scarcity in the port zone elevates facility costs and extends project timelines for automated high-bay developments.
O'Higgins Region
Stone fruit and table grape exporters are scaling controlled-atmosphere pre-cooling capacity to satisfy EU entry requirements. SUBPESCA traceability mandates intersect with regional produce handling through cross-docking facilities serving multi-modal export corridors. Rancagua and surrounding production zones concentrate temperature-controlled packing infrastructure investment.
Maule Region
Fresh produce exporters are expanding temperature-controlled capacity to meet EU phytosanitary entry requirements for premium fruit categories. Chile's Sanitary Code enforcement pulls investment into temperature-monitoring infrastructure across handling facilities. Talca and Curicó anchor regional logistics clusters connecting Central Valley production to port terminals.
Los Lagos Region
Salmon and shellfish processing clusters generate specialized cold chain demand under continuous chain-of-custody documentation requirements. SUBPESCA seafood traceability mandates trigger automatic export clearance rejection for temperature excursions. Puerto Montt and surrounding coastline lack integrated cold chain density, opening corridor development for temperature-controlled multimodal links.
Chile Cold Chain Logistics Market Competitive Environment
Player mix skews toward diversified logistics conglomerates with refrigerated capabilities alongside pure-play cold chain specialists. The competitive structure segments into three archetypes: multinational network operators leveraging LatAm scale, regional seafood-focused transporters, and domestic dairy distribution incumbents. Capacity expansion and fleet modernization dominate competitive moves, with refrigerant transition timelines compressing equipment replacement cycles.
Within the multinational network tier, Emergent Cold LatAm anchors regional cross-border refrigerated corridors through its LatAm network scale. Among domestic specialists, Transportes Nazar occupies a position exemplifying seafood logistics concentration along the Los Lagos coastline, while Friofort SA represents the controlled-atmosphere fleet archetype sustaining domestic dairy distribution dominance. These three companies illustrate the competitive segmentation between export corridor specialists and metropolitan consumption zone operators.
| Leading Market Players |
|---|
| Empresas Taylor |
| Frigorificos Puerto Montt |
| Transportes Nazar |
| Emergent Cold LatAm |
| Ceva Logistics |
| Tudefrigo SA |
| Friofort SA |
| IceStar Chile |
| Megafrio Chile SA |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of inventory coverage across Santiago's cold storage network compresses pricing power for bonded warehouse operators while amplifying cost pass-through leverage for fleet-dependent transport providers. This lead-time differential between static storage and mobile refrigerated assets shapes how EU F-Gas compliance costs distribute across Chile's elongated logistics corridors.
Pricing Analysis
Cost-plus contracts indexed to Chile's central interconnected system electricity tariffs dominate cold storage agreements, while refrigerated transport pricing stratifies across premium, standard, and economy tiers based on HACCP certification level and real-time telemetry inclusion. Price differentiation rests on SUBPESCA traceability documentation completeness and automated temperature-logging hardware integration. Pricing pressure stems from supermarket chains unbundling warehouse-plus-delivery bundles into lane-by-lane bidding. Dairy distributors in the Central Valley exhibit highest price sensitivity due to thin margins on fluid milk volumes, whereas salmon exporters accept premium tiers for uninterrupted chain-of-custody documentation.
Supply Chain Analysis
Inventory concentration in Valparaíso and Biobío port zones extends project timelines for automated high-bay developments while elevating facility rates for existing bonded capacity. Equipment manufacturing draws from China, Germany, and the United States for refrigeration compressors and ammonia-CO2 cascade system components. Single-source vulnerability sits with specialized phase-change material suppliers for trans-Pacific produce containers. Distribution runs through multimodal cold hubs connecting Santiago's metropolitan corridor to San Antonio port terminals, with last-mile refrigerated capacity underdeveloped in outer metropolitan rings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's cold chain logistics market operates as a substitution defense against passive shipping container technologies that threaten mechanical refrigeration's cost position on medium-haul produce movements. Incumbents must navigate this displacement risk while consolidating fragmented regional capabilities.
For Market Incumbents: Secure HACCP-aligned traceability infrastructure ahead of Ministry of Health enforcement waves to lock in export lane qualification. Acquire controlled-atmosphere fleet assets in O'Higgins and Maule production zones before land scarcity elevates facility costs further. Backward integration into ammonia-CO2 cascade system maintenance capabilities counters technician shortage risks while capturing refrigerant transition service revenue.
For New Entrants and Emerging Players: SUBPESCA certification fast-tracks unlock preferential export clearance for seafood origin documentation compliance, opening Los Lagos corridor development where integrated cold chain density remains lowest. Target urban micro-fulfillment hub construction in Santiago's outer metropolitan ring where e-commerce grocery penetration outpaces last-mile refrigerated capacity deployment. Lead with IoT telemetry subscription models that reduce spoilage claims for berry exporters seeking North American market access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified logistics conglomerates with underutilized refrigerated capabilities alongside core dry freight operations. Five-to-ten-year viability hinges on EU F-Gas alignment completion and automated warehousing penetration rates. Monitor National Customs Service import documentation rulemaking for refrigerant-containing equipment as the inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Fast-Track | SUBPESCA traceability compliance unlocks premium seafood export clearance before competitors complete documentation systems. |
| Ammonia-CO2 Cascade System Deployment | Biobío cold storage developers capture EU F-Gas alignment advantages through lower-GWP refrigerant infrastructure. |
| IoT Telemetry Platform Integration | Real-time cold chain visibility reduces spoilage claims for stone fruit exporters facing European retail audit requirements. |
| Urban Micro-Fulfillment Hub Construction | Santiago outer metropolitan ring capacity addresses e-commerce grocery penetration gaps before supermarket chains consolidate procurement. |
| Phase-Change Material Container Adoption | Trans-Pacific produce movements achieve fuel cost compression while simplifying customs inspection protocols at destination ports. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings from listed logistics operators, and Ministry of Health regulatory filings. Cold chain logistics executives, refrigerated fleet procurement managers, and seafood processing plant operators provided operational data on temperature-monitoring infrastructure deployment. SUBPESCA documentation requirements and EU F-Gas Regulation alignment timelines were validated through National Customs Service procedural updates. Bottom-up capacity assessments across Valparaíso and Biobío port zones triangulate against top-down trade flow analysis.
Segmentation dimensions modeled include product type, solution type, end user category, and technology layer across the projection horizon. Refrigerated transport revenue shares and cold storage margin trajectories derive from facility cost structures and fleet replacement cycle timing. CAGRs reflect equipment replacement acceleration under refrigerant transition mandates and IoT telemetry adoption curves through retrofit demand. SUBPESCA traceability compliance rates and Santiago e-commerce grocery penetration patterns anchor scenario-weighted outputs.
The analysis sits within stated boundaries; outcomes outside EU F-Gas alignment timelines or electricity tariff stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding HACCP enforcement intensity and land availability constraints in port zones. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Ukraine Freight and Logistics Market