
 United States Contract Logistics Market | 2026-2036
United States Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Contract Logistics Market Analytics
Aluminum racking and composite flooring is broadening warehouse construction economics across temperature-controlled facilities. GXO Logistics leverages automated sortation systems to sustain margin in e-commerce fulfillment. DHL Supply Chain anchors pharmaceutical distribution networks with validated cold-chain infrastructure. Ryder Supply Chain Solutions specializes in dedicated fleet operations for automotive parts movement.
Contract logistics encompasses the outsourcing of supply chain execution—including transportation management, warehousing operations, inventory optimization, and value-added services such as kitting, labeling, and reverse logistics—to third-party providers operating under multi-year service agreements. Warehousing services command the largest revenue pool due to fixed-asset intensity and long lease structures, while value-added services generate the fastest expansion as shippers seek consolidated packaging and quality-assurance labor. Electronics and pharmaceutical verticals concentrate margin pools because of compliance documentation requirements and temperature-validated handling protocols.
FDA serialization mandates and EPA refrigerant-phaseout rules under the AIM Act reshape cold-chain infrastructure investment requirements for pharmaceutical and food-grade distribution networks. DOT hours-of-service regulations and OSHA warehouse safety standards constrain labor deployment models and automation ROI calculations. Stakeholders must weigh captive fleet ownership against outsourced capacity as diesel-electric transition timelines and driver availability thresholds shift operational risk profiles.
Market Dynamics
Pharmaceutical serialization mandates and lithium-ion battery storage protocols are forcing warehouse operators to rebuild temperature-controlled infrastructure across Texas and California fulfillment corridors.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace requirements for pharmaceutical distribution are expanding demand for validated cold-chain facilities with serialized inventory management systems.
- Automotive electrification:Battery supply chains require hazmat-certified warehousing near assembly plants, pulling contract logistics providers into dedicated cell storage and sequencing operations.
- Omnichannel retail consolidation:Merchants are collapsing separate e-commerce and store replenishment networks into unified fulfillment nodes to reduce last-mile duplication.
Market Restraints
- Refrigerant cost volatility:EPA AIM Act phaseout of hydrofluorocarbons is raising retrofit costs for existing cold-storage infrastructure before replacement systems achieve scale economies.
- Driver pool concentration:DOT hours-of-service enforcement tightens further in long-haul corridors, constraining dedicated fleet availability for just-in-time automotive parts movement.
- Automation capex thresholds:Warehouse robotics integration requires minimum facility sizes that exclude smaller urban infill locations from efficiency gains.
Strategic Opportunities
- IRA clean energy incentives:Tax credits for electric vehicle supply chain localization are drawing battery logistics providers to establish Southeast distribution hubs.
- Reverse logistics specialization:E-commerce return volumes are outpacing merchant processing capacity, creating white space for providers with automated inspection and refurbishment lines.
- AI-driven demand sensing:Machine learning forecast engines are converging with robotic putaway systems to compress safety stock requirements in pharmaceutical distribution.
Industry Challenges
- Warehouse automation technician scarcity:Maintenance of automated sortation and mobile robotics systems requires electro-mechanical skills that outpace vocational training pipeline output.
- Legacy WMS integration friction:Pharmaceutical distributors running validated ERP environments face extended validation timelines when connecting to cloud-native warehouse execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Contract Logistics Market |
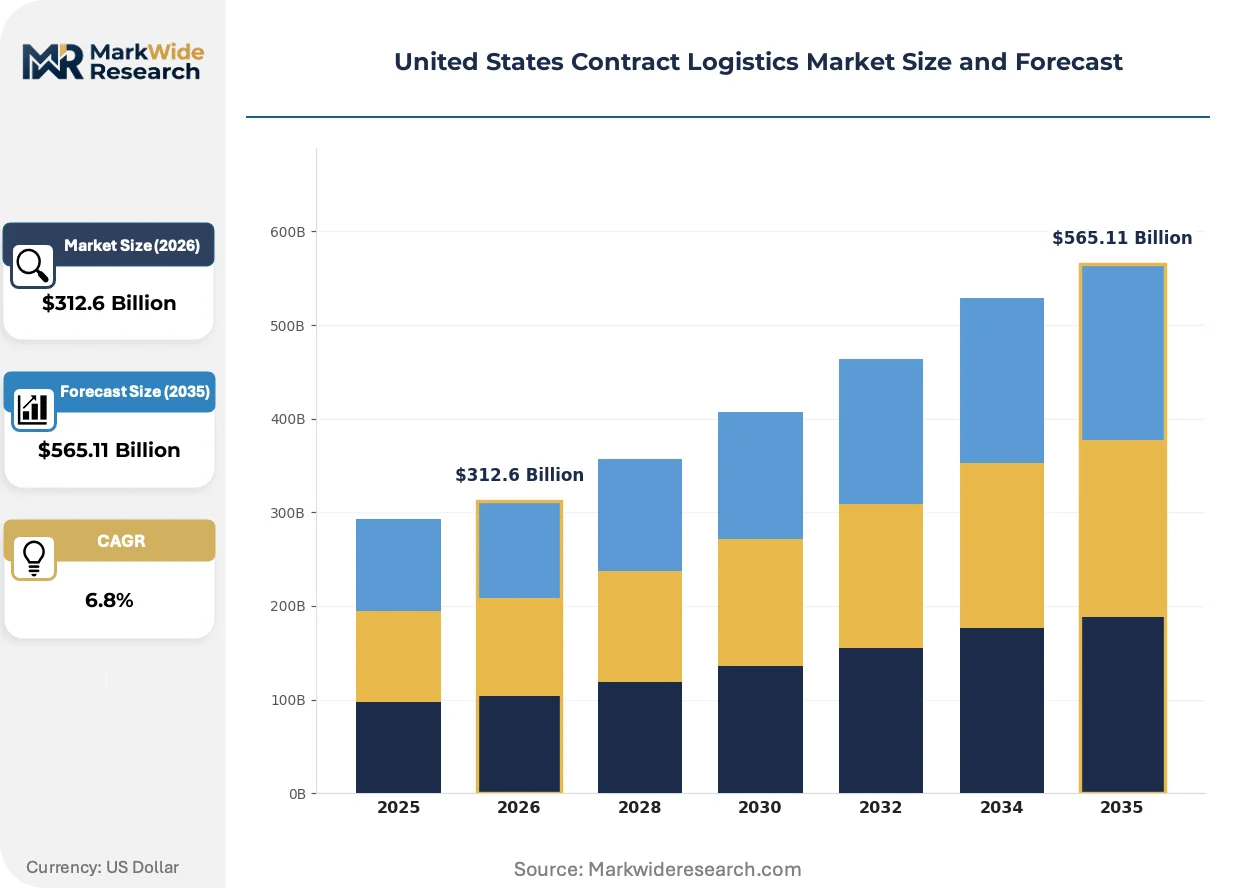
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Value-Added Services Industry Vertical: Retail, Automotive, Pharmaceuticals, Electronics Distribution Channel: Direct, E-Commerce, Wholesale, Third-Party End User: Manufacturers, Distributors, Online Retailers, SMBs |
| Companies Covered | GXO Logistics, UPS Supply Chain Solutions, DHL Supply Chain, Ryder Supply Chain Solutions, XPO Logistics, C.H. Robinson, J.B. Hunt Transport Services, Kuehne+Nagel, Penske Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Contract Logistics Market Evolving Landscape
Automation architectures are compressing labor dependency in high-throughput fulfillment while regulatory compliance layers add system complexity. Material handling equipment and software control layers are merging into unified platforms.
Autonomous mobile robots with fleet management software are unifying goods-to-person workflows across variable SKU profiles. Pharmaceutical distributors with validated environments are piloting these systems in secondary pick modules to reduce picker travel without triggering full revalidation. The technology is unifying previously siloed automation investments into interoperable warehouse control architectures.
EPA refrigerant regulations under the AIM Act are accelerating cold-storage infrastructure replacement timelines. Operators must phase out R-404A and R-507A systems before 2028, compressing capital deployment into a narrow window. Food-grade and pharmaceutical facilities in California and Texas are prioritizing CO2 transcritical systems to preempt compliance deadlines.
Merchant procurement of fulfillment services is fragmenting across specialized providers rather than consolidating with integrated 3PLs. Direct-to-consumer brands are unbundling warehousing from transportation management to optimize each leg independently. This pattern concentrates in apparel and electronics verticals where seasonal volatility rewards operational flexibility over contract scale.
United States Contract Logistics Market Segmentation
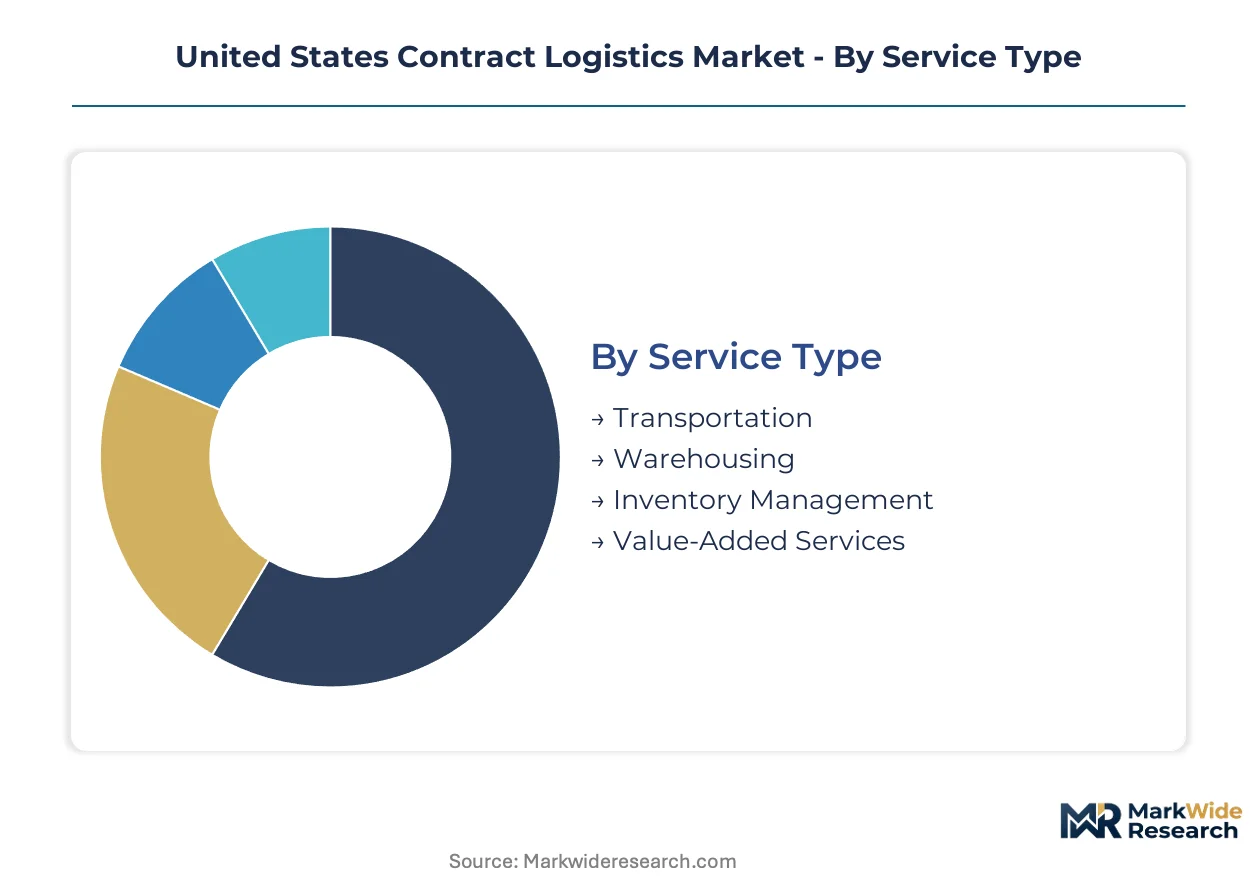
Contract logistics segmentation reveals where capital concentrates and where margin pools shift. Service mix, vertical exposure, channel configuration, and customer scale each dictate infrastructure requirements and contract economics differently across the United States.
Service Type:
Warehouse fixed assets and transportation variable costs split investment risk unevenly across service categories.
- Transportation:Fleet assets and driver labor dominate cost structures. Dedicated contract carriage absorbs demand from automotive assembly plants in Michigan and Tennessee where just-in-time delivery windows compress to hours.
- Warehousing:Cold-chain facilities command lease premiums due to refrigeration equipment density. California and Texas distribution corridors concentrate temperature-controlled square footage serving pharmaceutical serialization mandates.
- Inventory Management:Serialized tracking systems support FDA Drug Supply Chain Security Act compliance. Real-time visibility platforms integrate with client ERP environments.
- Value-Added Services:Kitting, labeling, and quality inspection labor scales flexibly with e-commerce promotional cycles.
Warehousing absorbs the bulk of installed capacity; value-added services are expanding most quickly.
Industry Vertical:
Compliance burden and handling complexity stratify profitability across end-use sectors.
- Retail:Omnichannel fulfillment networks collapse separate e-commerce and store replenishment streams. Seasonal volatility demands labor models that surge without fixed cost entrenchment.
- Automotive:Electrification pulls contract logistics into battery cell storage and sequencing operations near assembly plants. Hazmat certification requirements filter provider eligibility.
- Pharmaceuticals:Validated cold-chain infrastructure with serialized inventory management supports FDA track-and-trace mandates. Temperature excursion liability concentrates provider selection on proven compliance records.
- Electronics:High-velocity SKU profiles favor automated sortation investments. Reverse logistics volumes from e-commerce returns strain manual processing capacity.
Retail commands the largest contract volume; pharmaceuticals delivers the steepest margin expansion.
Distribution Channel:
Channel selection determines last-mile cost allocation and inventory positioning strategy.
- Direct:Manufacturer-controlled fulfillment bypasses wholesale intermediaries. Direct-to-consumer brands in apparel and electronics unbundle warehousing from transportation to optimize each leg independently.
- E-Commerce:Two-day and next-day delivery promises compress distribution node placement to within 100 miles of population centers. Urban infill facilities sacrifice automation scale for proximity.
- Wholesale:Pallet-in, pallet-out operations sustain throughput economics in exurban locations. Full-truckload consolidation reduces per-unit handling costs.
- Third-Party:Marketplace sellers rely on outsourced fulfillment to avoid fixed asset commitment. Amazon FBA and independent 3PL networks compete for merchant account control.
E-commerce claims the fastest share gain; wholesale retains the highest throughput efficiency.
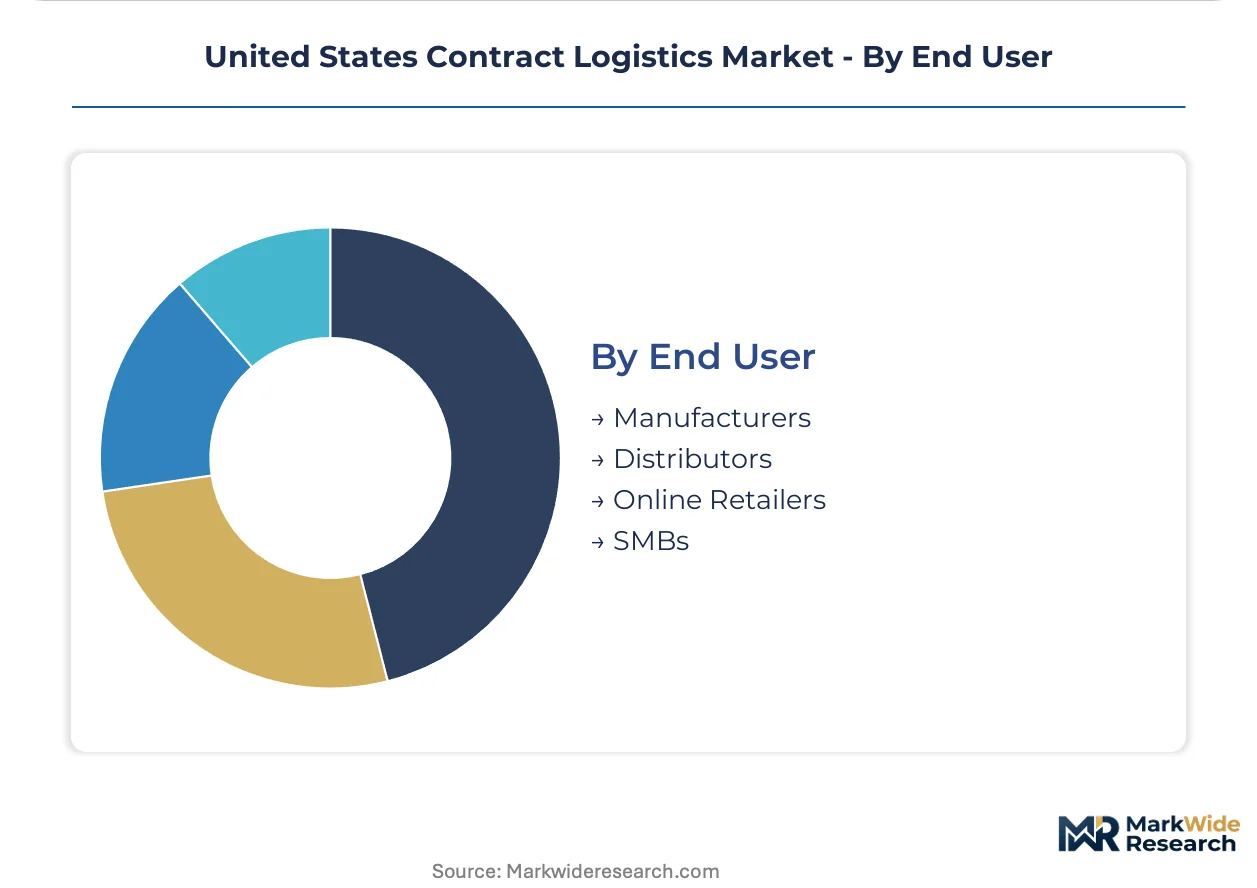
End User:
Customer scale dictates contract structure flexibility and technology integration depth.
- Manufacturers:Inbound supply chain management and finished goods distribution require synchronized production schedules. Tier 1 automotive suppliers demand sequenced parts delivery to assembly lines.
- Distributors:Multi-vendor inventory consolidation and cross-dock operations compress dwell time. Pharmaceutical distributors operate validated environments with extended ERP validation timelines.
- Online Retailers:Promotional demand spikes and return processing volumes favor flexible labor arrangements. Automated inspection lines address capacity constraints in high-volume return corridors.
- SMBs:Shared warehousing and consolidated transportation purchasing access scale economies without dedicated facility commitment. Fragmented demand concentrates in coastal metropolitan markets.
Manufacturers anchor long-term contract value; online retailers drive technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for contract logistics concentrates in coastal and border-adjacent corridors where pharmaceutical serialization mandates and automotive electrification converge. The analysis examines five sub-regional clusters driving infrastructure deployment.
California
Pharmaceutical cold-chain facilities cluster around Los Angeles and San Diego to serve FDA track-and-trace compliance for Pacific Rim import distribution. EPA AIM Act refrigerant phaseout rules accelerate CO2 transcritical system retrofits in temperature-controlled warehouses. The Inland Empire logistics corridor absorbs e-commerce fulfillment expansion as merchants compress last-mile nodes within 100 miles of population centers.
Texas
Cross-border automotive sequencing operations concentrate along the I-35 corridor connecting Laredo to Dallas-Fort Worth for just-in-time parts delivery to assembly plants. DOT hours-of-service enforcement tightens capacity for dedicated fleet operations serving maquiladora supply chains. Houston anchors pharmaceutical distribution networks with validated cold-chain infrastructure supporting Gulf Coast import volumes.
Midwest Manufacturing Belt
Michigan and Ohio assembly plants pull contract logistics providers into battery cell storage and hazmat-certified warehousing for electrification supply chains. OSHA warehouse safety standards constrain automation ROI calculations in legacy facilities. Detroit and Toledo logistics nodes specialize in sequenced parts delivery with compressed delivery windows.
Southeast Growth Corridor
IRA clean energy incentives draw battery logistics providers to Georgia and Tennessee distribution hubs serving regional automotive assembly. The region's right-to-work labor environment supports flexible staffing models for seasonal e-commerce surges. Charleston and Savannah port expansions reposition containerized pharmaceutical imports for inland cold-chain distribution.
Northeast Metro Concentration
New York and New Jersey pharmaceutical distributors operate validated ERP environments with extended validation timelines for cloud-native warehouse execution platforms. Urban infill facilities sacrifice automation scale for proximity to dense consumer populations. Boston's biotech cluster generates specialized cold-chain demand for clinical trial materials distribution.
United States Contract Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated 3PLs holding concentrated positions in pharmaceutical and automotive verticals while regional operators capture fragmented e-commerce fulfillment demand. The market structures around three tiers: global network operators with validated infrastructure, mid-scale specialists in dedicated verticals, and asset-light technology platforms. Consolidation pressure intensifies as automation capex thresholds exclude smaller players from efficiency gains. M&A activity targets cold-chain capabilities and last-mile density; strategic partnerships connect legacy WMS environments to cloud-native execution layers.
Among integrated network operators, UPS Supply Chain Solutions and DHL Supply Chain exemplify the validated infrastructure tier with pharmaceutical serialization compliance capabilities. GXO Logistics occupies a position at the automation-forward end, representing providers that leverage robotic sortation to sustain margin in high-throughput e-commerce fulfillment. Ryder Supply Chain Solutions anchors the dedicated fleet specialization archetype for automotive parts movement. These three patterns—compliance-heavy pharmaceutical networks, automation-driven e-commerce operators, and fleet-centric automotive specialists—capture the dominant competitive positioning vectors in the market.
| Leading Market Players |
|---|
| GXO Logistics |
| UPS Supply Chain Solutions |
| DHL Supply Chain |
| Ryder Supply Chain Solutions |
| XPO Logistics |
| C.H. Robinson |
| J.B. Hunt Transport Services |
| Kuehne+Nagel |
| Penske Logistics |
| Others |
Value Network & Pricing Analysis
EPA AIM Act refrigerant-phaseout mandates gate access to premium-tier cold-chain contracts and qualified temperature-controlled warehousing supply. Buyers seeking FDA-validated pharmaceutical distribution capabilities face supply scarcity that elevates pricing power for providers with compliant CO2 transcritical infrastructure.
Pricing Analysis
Volume-heavy e-commerce fulfillment compresses margins while pharmaceutical cold-chain services sustain premium returns. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated facilities from general warehousing and shared multi-tenant space. Price differentiation hinges on serialization compliance certification and geographic proximity to coastal population centers. Cost compression in standard-tier warehousing intensifies as automation capex thresholds exclude smaller operators from efficiency gains. SMB merchants exhibit highest price sensitivity; pharmaceutical distributors prioritize compliance reliability over rate negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand through dedicated fleet operations along the I-35 corridor and Midwest assembly plant networks. Material handling equipment and warehouse control systems draw from China, Germany, and domestic automation vendors. Lithium-ion battery cells, aluminum racking systems, and refrigeration compressors anchor capital deployment decisions. Single-source vulnerability concentrates in specialized cold-chain equipment where EPA compliance timelines compress supplier capacity. Distribution runs through third-party logistics networks that fragment across specialized providers rather than consolidated national operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where automation capex thresholds and regulatory compliance burdens force sub-scale operators toward exit or acquisition. The narrowing window for EPA refrigerant retrofits accelerates this pressure.
For Market Incumbents: Acquire cold-chain-certified facilities in California and Texas distribution corridors to secure scarce qualified supply. Integrate cloud-native warehouse execution platforms with legacy pharmaceutical ERP environments to defend against technology-forward entrants. Battery logistics capabilities near Southeast automotive assembly clusters offer defensive positioning against electrification-driven demand shifts. For New Entrants and Emerging Players: Capture reverse logistics white space where automated inspection and refurbishment capacity lags e-commerce return volumes. Target SMB merchant segments in coastal metropolitan markets where shared warehousing demand fragments across underserved niches. Lead with AI-driven demand sensing tools that compress pharmaceutical safety stock requirements as a differentiated entry wedge. For Investors and Strategic Acquirers: FDA serialization enforcement acceleration is the leading indicator that pharmaceutical cold-chain assets will command scarcity premiums. Five-to-ten year viability favors operators with validated infrastructure and proven temperature excursion liability records. Monitor EPA refrigerant retrofit completion rates as the signal for which facilities will retain contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Acquisition | EPA AIM Act deadlines concentrate qualified supply in California and Texas corridors. |
| Automated Sortation Deployment | GXO Logistics validates robotic putaway economics in high-velocity e-commerce fulfillment. |
| Reverse Logistics Specialization | Automated inspection lines address capacity constraints in apparel and electronics returns processing. |
| Battery Supply Chain Localization | IRA clean energy incentives draw providers to Georgia and Tennessee distribution hubs. |
| Cloud-Native WMS Integration | Pharmaceutical distributors reduce validation friction when connecting legacy ERP environments. |
Research Methodology
Document review covered SEC 10-K filings, DOT enforcement records, and EPA regulatory dockets, complemented by interviews with contract logistics executives, pharmaceutical distribution operations directors, and automotive procurement managers. Secondary validation drew from customs trade data, warehouse construction permits, and cold-chain certification databases. Bottom-up facility capacity estimates triangulated against top-down market size reconstructions.
Model outputs projected service-type and vertical-segment trajectories across the analysis window. Segmentation dimensions included service category, industry vertical, distribution channel, and customer scale tier. CAGRs derived from facility investment pipelines, lease commencement data, and contract award velocity. Forecast inputs incorporated EPA refrigerant-phaseout compliance timelines and FDA serialization mandate implementation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to automation technology adoption curves and driver availability thresholds. Projections reflect assumptions about regulatory enforcement consistency and capital market access for infrastructure deployment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
United Kingdom Freight and Logistics Market