
 Central and Eastern Europe Freight and Logistics Market | 2026-2036
Central and Eastern Europe Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Central and Eastern Europe Freight and Logistics Market Insights
ISO 9001 certification is bifurcating the Central and Eastern Europe freight and logistics landscape into qualified operators and excluded regional carriers. Gebrüder Weiss leverages its integrated warehousing network across Austria and Hungary to sustain cross-border pharmaceutical distribution. DSV A/S anchors its regional hub strategy through controlled capacity at Budapest Ferenc Liszt International Airport. Raben Group differentiates via specialized food-grade logistics occupying temperature-controlled corridors between Poland and the Baltics.
Central and Eastern Europe freight and logistics encompasses the planning, execution, and management of goods movement across road, rail, air, and sea modalities, typically involving cargo consolidation, customs documentation, and last-mile distribution within a 3,000-kilometer east-west corridor stretching from the Baltic to the Black Sea. The sector functions as the industrial circulatory system for European manufacturing supply chains, with particular density in automotive component sequencing and e-commerce fulfillment. Transportation services dominate value capture due to fuel cost pass-through mechanisms and driver scarcity premiums, while warehousing segments exhibit structural margin compression from speculative development oversupply in Romania and Bulgaria. Freight forwarding retains resilient profitability through customs complexity arbitrage, especially along EU-non-EU border corridors where Serbia and Moldova transit volumes generate documentation-intensive revenue.
EU Green Deal emissions regulations enforced by the European Commission, CE marking requirements for logistics equipment under ECHA frameworks, and Poland's CEA-monitored rail electrification standards collectively elevate compliance costs for diesel-dependent road operators. These regulatory layers accelerate fleet renewal cycles and privilege rail-intermodal investments on Budapest-Belgrade and Warsaw-Berlin corridors. Stakeholders must monitor whether EU carbon border adjustments extend scope to embedded transport emissions, as this would reconfigure modal choice algorithms for steel and automotive exports originating from Czech and Slovak industrial zones.
Market Dynamics
The EU Green Deal's emissions trading requirements for heavy-duty transport are forcing fleet renewal cycles and privileging rail-intermodal investments across Poland, the Czech Republic, and Hungary. Automotive manufacturers in Silesia and Moravia are expanding just-in-time supply chain contracts, tightening capacity allocation for qualified logistics operators.
Growth Catalysts
- EU Green Deal emissions regulations:The European Commission's carbon pricing mechanisms for heavy-duty vehicles accelerate electrified fleet procurement and rail-intermodal corridor development between Warsaw and Berlin.
- Automotive just-in-time sequencing:Component manufacturers across Silesia and Moravia are consolidating logistics contracts with ISO 9001-certified operators capable of sub-two-hour delivery windows.
- Poland's CEA-monitored rail electrification:Central Energy Agency standards for catenary infrastructure expand electrified freight capacity along the Baltic-Black Sea corridor.
Market Restraints
- Diesel fuel cost pass-through volatility:Road operators face margin compression from fuel price fluctuations that contract structures cannot fully hedge.
- Driver scarcity premiums:Demographic contraction in qualified heavy-goods vehicle operators across Hungary and Slovakia elevates labor costs beyond automated alternatives.
- Speculative warehouse oversupply:Romania and Bulgaria exhibit structural margin compression from development pipelines that outpace demand absorption.
Strategic Opportunities
- Pharmaceutical cold chain corridors:Temperature-controlled distribution networks between Austria and the Baltics remain underdeveloped relative to Western European density.
- EU carbon border adjustment extension:Embedded transport emissions regulation would reconfigure modal choice algorithms for steel and automotive exports from Czech and Slovak industrial zones.
- Serbia and Moldova transit documentation:EU-non-EU border complexity generates arbitrage potential for customs-specialized freight forwarders.
Industry Challenges
- CE marking compliance timelines:Logistics equipment certification under ECHA frameworks delays fleet deployment and elevates working capital requirements.
- Rail-road intermodal integration:Legacy terminal infrastructure in Poland and Hungary creates friction for seamless cargo transfer between modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central and Eastern Europe Freight and Logistics Market |
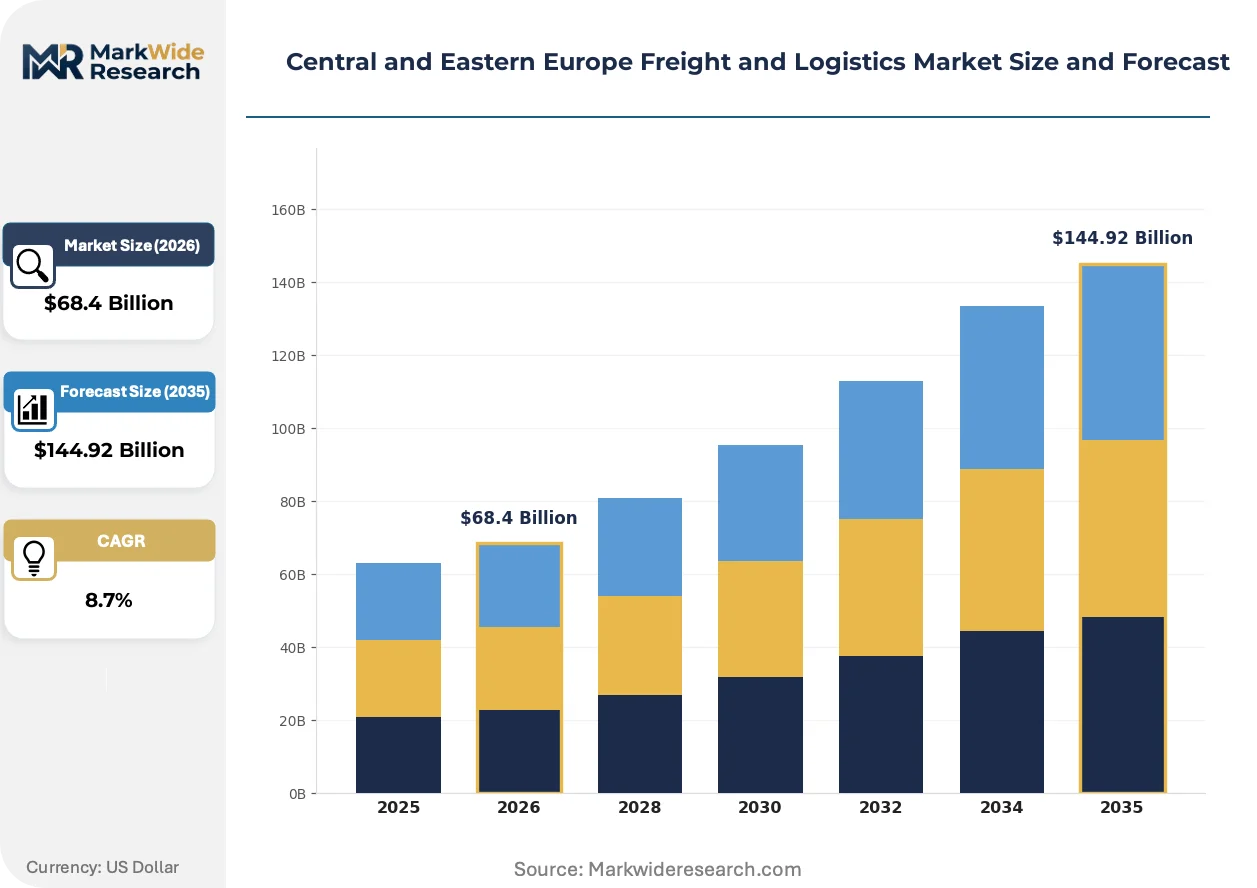
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Industry Vertical: Manufacturing, Retail, E-commerce, Automotive Delivery Mode: Road, Rail, Air, Sea Client Type: SMEs, Large Enterprises, Public Sector, NGOs |
| Companies Covered | DB Schenker, Rohlig SUUS, DHL Group, Gebrüder Weiss, Hellmann Worldwide Logistics, DSV A/S, Raben Group, Waberer’s, Kuehne+Nagel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central and Eastern Europe Freight and Logistics Market Trends and Innovations
Digital freight platforms and electrification technologies are fragmenting traditional carrier-shipper relationships across the Baltic-Black Sea corridor. Established operators must now compete with algorithmic load-matching services and asset-light intermediaries.
Telematics-enabled dynamic routing is fragmenting static lane contracts that previously dominated automotive and retail distribution. Tier-one manufacturers in the Czech Republic now pilot real-time re-routing based on congestion and emissions pricing. This capability compresses margins for carriers without comparable data infrastructure.
EU Green Deal emissions trading requirements enforced by the European Commission are mandating carbon accounting integration into transport management systems. Heavy-duty operators must now document Scope 1 emissions per kilometer for regulatory compliance. Polish and Hungarian fleet managers are responding with telematics retrofits and alternative fuel trials.
Buyer consolidation among e-commerce fulfillment platforms is compressing contract renewal cycles from annual to quarterly terms. Large retail aggregators in Poland now demand volume-flexible pricing with performance penalties. This shift is most visible in Warsaw and Krakow metropolitan distribution networks.
Central and Eastern Europe Freight and Logistics Market Segmentation
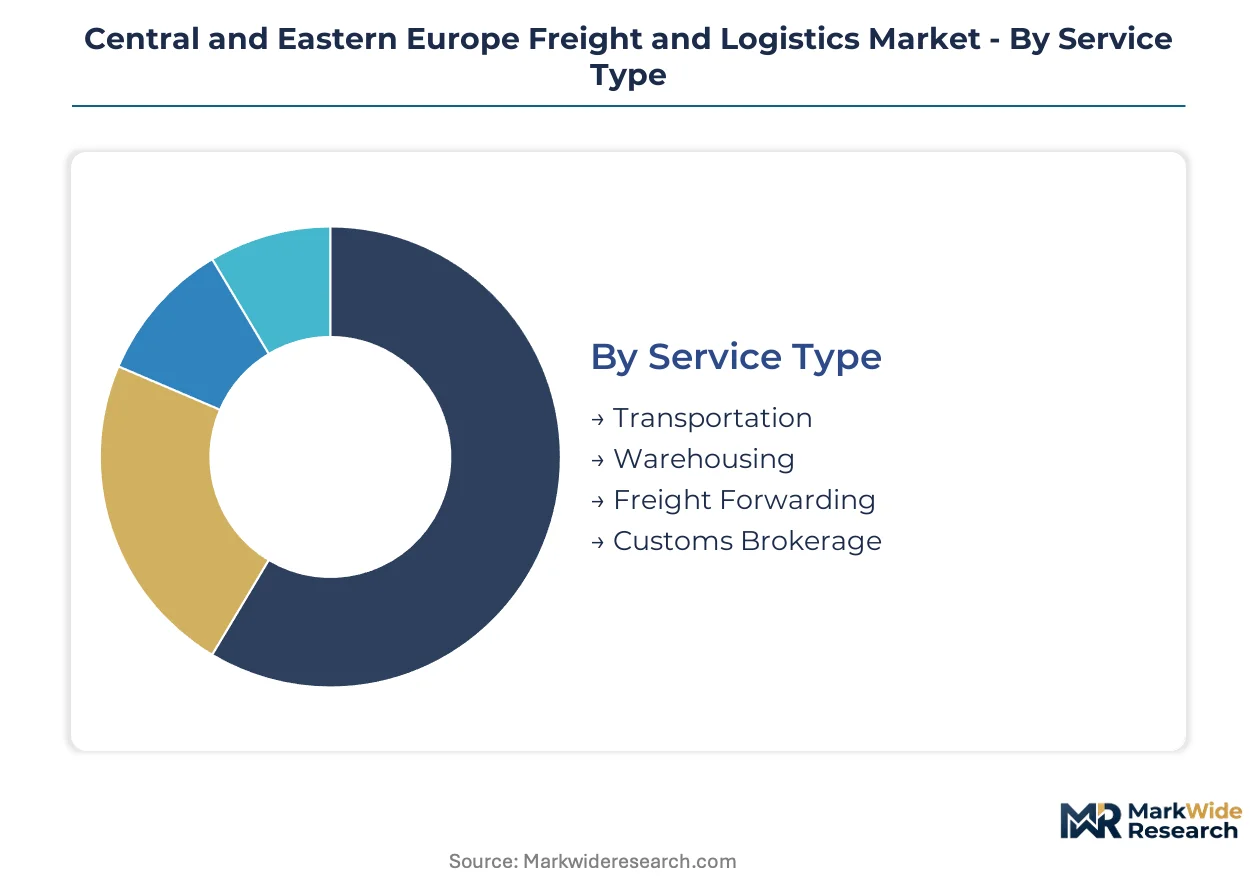
Modal choice and certification requirements fragment the Central and Eastern Europe freight and logistics market into distinct operational tiers. Service differentiation across transportation, warehousing, and customs brokerage determines which operators capture automotive sequencing contracts versus commodity flows.
Service Type:
EU Green Deal emissions regulations enforced by the European Commission differentiate service profitability through carbon accounting mandates and fleet renewal timelines.
- Transportation:Road and rail carriers dominate value capture through fuel cost pass-through mechanisms and driver scarcity premiums. Polish and Hungarian fleet operators face accelerated electrification requirements under CEA-monitored standards, compressing margins for diesel-dependent carriers.
- Warehousing:Temperature-controlled facilities and automated fulfillment centers concentrate demand in Poland's Silesian corridor, where vacancy rates remain the tightest regionally. Speculative development oversupply in Romania and Bulgaria exerts structural margin pressure on speculative assets.
- Freight Forwarding:Customs documentation arbitrage generates resilient profitability along EU-non-EU border corridors, particularly Serbia and Moldova transit volumes.
- Customs Brokerage:CE marking compliance under ECHA frameworks elevates working capital requirements and delays equipment deployment for integrated service providers.
Transportation handles the majority of throughput; Freight Forwarding is expanding most quickly on regulatory complexity.
Industry Vertical:
Customer procurement patterns stratify around delivery precision requirements and contract renewal cycles.
- Automotive:Just-in-time sequencing contracts from Silesia and Moravia manufacturers demand sub-two-hour delivery windows and ISO 9001 certification, tightening capacity allocation for qualified operators.
- E-commerce:Buyer consolidation among Polish fulfillment platforms compresses contract terms from annual to quarterly, with volume-flexible pricing and performance penalties now standard in Warsaw and Krakow metropolitan networks.
- Manufacturing:Steel and component exports from Czech and Slovak industrial zones face potential carbon border adjustment scope extension to embedded transport emissions.
- Retail:Telematics-enabled dynamic routing fragments static lane contracts, with tier-one Czech manufacturers piloting real-time re-routing based on congestion and emissions pricing.
Automotive commands premium pricing; E-commerce is gaining share fastest on platform consolidation.
Delivery Mode:
Infrastructure electrification and terminal modernization reshape modal competitiveness across the Baltic-Black Sea corridor.
- Road:Diesel fuel cost volatility and driver demographic contraction across Hungary and Slovakia elevate labor costs beyond automated alternatives.
- Rail:Poland's CEA-monitored catenary standards expand electrified freight capacity, privileging intermodal investments on Warsaw-Berlin and Budapest-Belgrade corridors.
- Air:Controlled capacity at Budapest Ferenc Liszt International Airport anchors regional hub strategies for time-sensitive pharmaceutical distribution.
- Sea:Baltic and Black Sea port connectivity supports bulk commodity flows with lower carbon intensity per ton-kilometer.
Road maintains volume dominance; Rail is climbing the fastest on Green Deal corridor investment.
Client Type:
Scale determines access to integrated service tiers and contract structure flexibility.
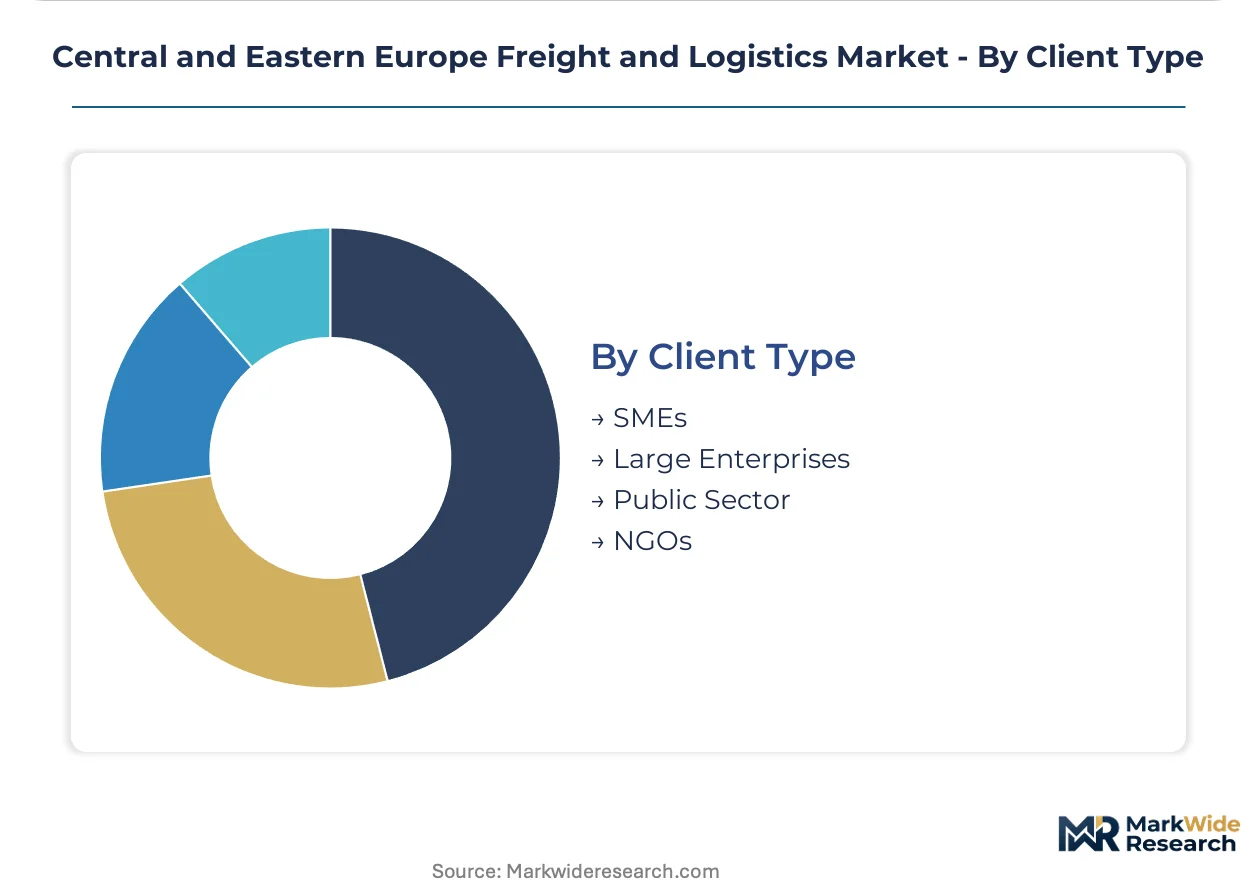
- Large Enterprises:Automotive and retail aggregators consolidate logistics contracts with qualified operators capable of cross-border pharmaceutical distribution and temperature-controlled corridor management.
- SMEs:Digital freight platforms fragment traditional carrier relationships through algorithmic load-matching services and asset-light intermediaries.
- Public Sector:Defense and infrastructure procurement follows distinct compliance timelines separate from commercial logistics frameworks.
- NGOs:Humanitarian supply chains prioritize corridor reliability over cost optimization in Moldova and Ukraine transit zones.
Large Enterprises drive contract consolidation; SMEs are the fastest mover on platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions trading requirements are accelerating fleet renewal investments across Poland, the Czech Republic, Hungary, Slovakia, and Austria. Rail electrification standards monitored by national energy agencies are expanding intermodal corridor capacity between Warsaw and Berlin. Automotive manufacturers in Silesia and Moravia are consolidating just-in-time contracts with qualified operators.
Poland
Automotive component sequencing from Silesian manufacturers drives demand for sub-two-hour delivery windows. The Central Energy Agency monitors catenary infrastructure standards that expand electrified freight capacity along Baltic-Black Sea corridors. Warehouse vacancy rates in the Silesian logistics corridor remain the tightest regionally as e-commerce fulfillment platforms consolidate.
Czech Republic
Tier-one manufacturers in Moravia pilot telematics-enabled dynamic routing based on congestion and emissions pricing. CE marking requirements under ECHA frameworks delay logistics equipment deployment and elevate working capital needs. The Ostrava industrial zone anchors steel and automotive export flows facing potential carbon border adjustment scope extension.
Hungary
Controlled capacity at Budapest Ferenc Liszt International Airport anchors regional hub strategies for time-sensitive pharmaceutical distribution. Demographic contraction in qualified heavy-goods vehicle operators elevates labor costs beyond automated alternatives. The Budapest-Belgrade rail corridor attracts intermodal investment under CEA-monitored electrification standards.
Slovakia
Steel and component exports from industrial zones near Bratislava face regulatory pressure from embedded transport emissions accounting. Driver scarcity premiums across the Hungarian-Slovak border region compress margins for diesel-dependent road operators. The Zilina automotive cluster tightens capacity allocation for ISO 9001-certified logistics providers.
Austria
Integrated warehousing networks support cross-border pharmaceutical distribution between Vienna and Baltic markets. EU Green Deal carbon pricing mechanisms accelerate electrified fleet procurement for alpine transit routes. The Vienna-Bratislava metropolitan distribution network concentrates temperature-controlled corridor investments.
Central and Eastern Europe Freight and Logistics Market Competitive Landscape
Player mix skews toward diversified European logistics conglomerates with integrated warehousing and forwarding capabilities. Market structure exhibits tiered consolidation where ISO 9001 certification bifurcates qualified operators from excluded regional carriers. Three strategic archetypes dominate: integrated multimodal networks, specialized temperature-controlled operators, and digital freight platforms. Competitive moves concentrate on rail-intermodal capacity expansion and cross-border pharmaceutical corridor development.
Among diversified European logistics groups, Gebrüder Weiss, DSV A/S, and Raben Group occupy distinct positioning vectors. Gebrüder Weiss exemplifies the integrated warehousing archetype with cross-border pharmaceutical distribution capabilities. DSV A/S represents hub-and-spoke air freight specialization anchored at controlled capacity airports. Raben Group sits within the temperature-controlled corridor segment serving food-grade logistics between Poland and Baltic markets. These three operators illustrate how certification compliance and modal integration separate premium-tier positioning from commodity forwarding services.
| Leading Market Players |
|---|
| DB Schenker |
| Rohlig SUUS |
| DHL Group |
| Gebrüder Weiss |
| Hellmann Worldwide Logistics |
| DSV A/S |
| Raben Group |
| Waberer's |
| Kuehne+Nagel |
| Others |
Pricing and Supply Chain Analysis
Electrified fleet scale economies in Poland and Hungary compress unit costs for rail-intermodal operators while elevating price floors for diesel-dependent road carriers stranded below minimum viable scale. Capacity utilization spreads across the Silesian logistics corridor tighten warehouse pricing power, whereas speculative oversupply in Romania and Bulgaria forces asset discounts that ripple through regional rate benchmarks.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-qualified operators and excluded regional carriers across automotive sequencing contracts. Three-tier pricing structure separates premium certified operators from standard compliance-tier providers and economy-grade spot market haulers. Pricing pressure intensifies in the economy tier as digital freight platforms fragment static lane contracts with algorithmic undercutting. E-commerce fulfillment platforms exhibit highest price sensitivity through quarterly contract renegotiations, while pharmaceutical distributors accept premium rates for temperature-controlled corridor reliability.
Supply Chain Analysis
Port congestion at Baltic terminals and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for equipment and alternative fuel technologies. Supply concentration centers on Poland, the Czech Republic, and Hungary for qualified logistics capacity, with Slovakia and Austria as secondary corridor nodes. Raw material dependencies span diesel fuel hedging instruments, electrified rolling stock components, and cold-chain refrigeration units. Single-source vulnerability concentrates in qualified heavy-goods vehicle operators across Hungary and Slovakia. Distribution runs through hub-and-spoke networks anchored at Budapest Ferenc Liszt International Airport and Poland's Silesian logistics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon pricing mechanisms for heavy-duty transport constitute a regulatory inflection that disrupts incumbent fleet economics while opening intermodal investment corridors. This technological-regulatory convergence accelerates winner-take-most dynamics across the Baltic-Black Sea logistics network.
For Market Incumbents: Fortify rail-intermodal capacity positions along Warsaw-Berlin and Budapest-Belgrade corridors before electrification standards harden competitive moats. Deepen backward integration into temperature-controlled warehousing networks to defend margin positions against digital freight platform encroachment. Prioritize ISO 9001 certification maintenance as automotive manufacturers consolidate contracts around qualified operators capable of sub-two-hour delivery windows.
For New Entrants and Emerging Players: Lead with pharmaceutical cold chain corridor specialization between Austria and Baltic markets, where incumbent density remains lowest relative to Western European benchmarks. Target SME segments through asset-light digital freight platforms that fragment traditional carrier relationships via algorithmic load-matching. Deploy customs documentation arbitrage capabilities along Serbia and Moldova transit routes as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated multimodal networks with electrified fleet exposure over pure-play road operators facing diesel asset stranding. Long-term viability concentrates in operators controlling Budapest hub capacity and Silesian warehouse scarcity. Watch EU carbon border adjustment scope extension to embedded transport emissions as the decisive inflection signal for steel and automotive export corridor reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Intermodal Capacity Expansion | CEA-monitored electrification standards privilege early movers on Warsaw-Berlin corridor investments. |
| Temperature-Controlled Corridor Development | Pharmaceutical distribution networks between Austria and Baltics remain underdeveloped relative to demand density. |
| Digital Freight Platform Integration | Algorithmic load-matching fragments static lane contracts and compresses margins for data-poor carriers. |
| Customs Documentation Specialization | EU-non-EU border complexity along Serbia and Moldova transit generates arbitrage potential for specialized forwarders. |
| Electrified Fleet Procurement | EU Green Deal emissions trading mandates accelerate asset renewal cycles and strand diesel-dependent operators. |
Research Methodology
The analysis maps transportation, warehousing, freight forwarding, and customs brokerage sub-sectors, each validated through fleet operations managers, automotive procurement directors, pharmaceutical supply chain leads, and customs brokerage specialists. Primary interview findings triangulate against secondary sources including EU Green Deal regulatory filings, ECHA framework documentation, Central Energy Agency infrastructure reports, and customs trade flow databases. Bottom-up service segment sizing reconciles with top-down regional GDP and industrial production indices.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span service type, industry vertical, delivery mode, and client scale tier. CAGRs derive from logistic cost intensity ratios applied to industrial output forecasts, with sensitivity testing around fuel price volatility and driver demographic contraction assumptions.
Underlying assumptions cover EU emissions trading enforcement timelines, rail electrification completion rates, and warehouse absorption velocities, with deviation risk concentrated in carbon border adjustment scope decisions and alternative fuel technology cost curves. Practitioners should keep alternative scenarios live as regulatory implementation schedules and automotive production shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Latin America Cold Chain Logistics Market