
 Solar Watch Market | 2026-2036
Solar Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Watch Market Insights
Titanium is shifting from premium niche to mainstream chassis material as watchmakers reduce reliance on nickel-heavy stainless steel. Citizen Watch Co. Ltd. leverages its proprietary Eco-Drive photovoltaic cell architecture to dominate light-powered analog segments. Seiko Holdings Corporation anchors its solar lineup through in-house semiconductor fabrication, ensuring supply security for calibers. Casio Computer Co. Ltd. competes at the entry-to-mid tier with G-Shock solar variants that emphasize shock resistance alongside photovoltaic charging.
A solar watch converts ambient light into electrical energy through amorphous silicon or dye-sensitized photovoltaic cells integrated beneath the dial, storing charge in lithium-ion or titanium lithium rechargeable cells to power quartz or connected movements for months in darkness. Analog solar watches occupy the largest volume tier, sustained by heritage design preferences and lower price points, while hybrid and smart segments capture expanding margin pools through GPS and heart rate monitor integration. Stainless steel retains material dominance in formal and professional segments, though ceramic and recycled ocean plastics gain traction in feature-driven outdoor lines.
REACH and RoHS frameworks in Europe restrict cadmium and lead content in photovoltaic cells and battery assemblies, compelling reformulation of charge-storage components. The EU Green Deal's extended producer responsibility rules mandate take-back programs for electronic timepieces, altering distribution economics. Japan's METI enforces strict energy-efficiency labeling that rewards longer power-reserve specifications. Stakeholders must monitor how battery chemistry regulations and right-to-repair legislation reshape component sourcing and after-service architecture.
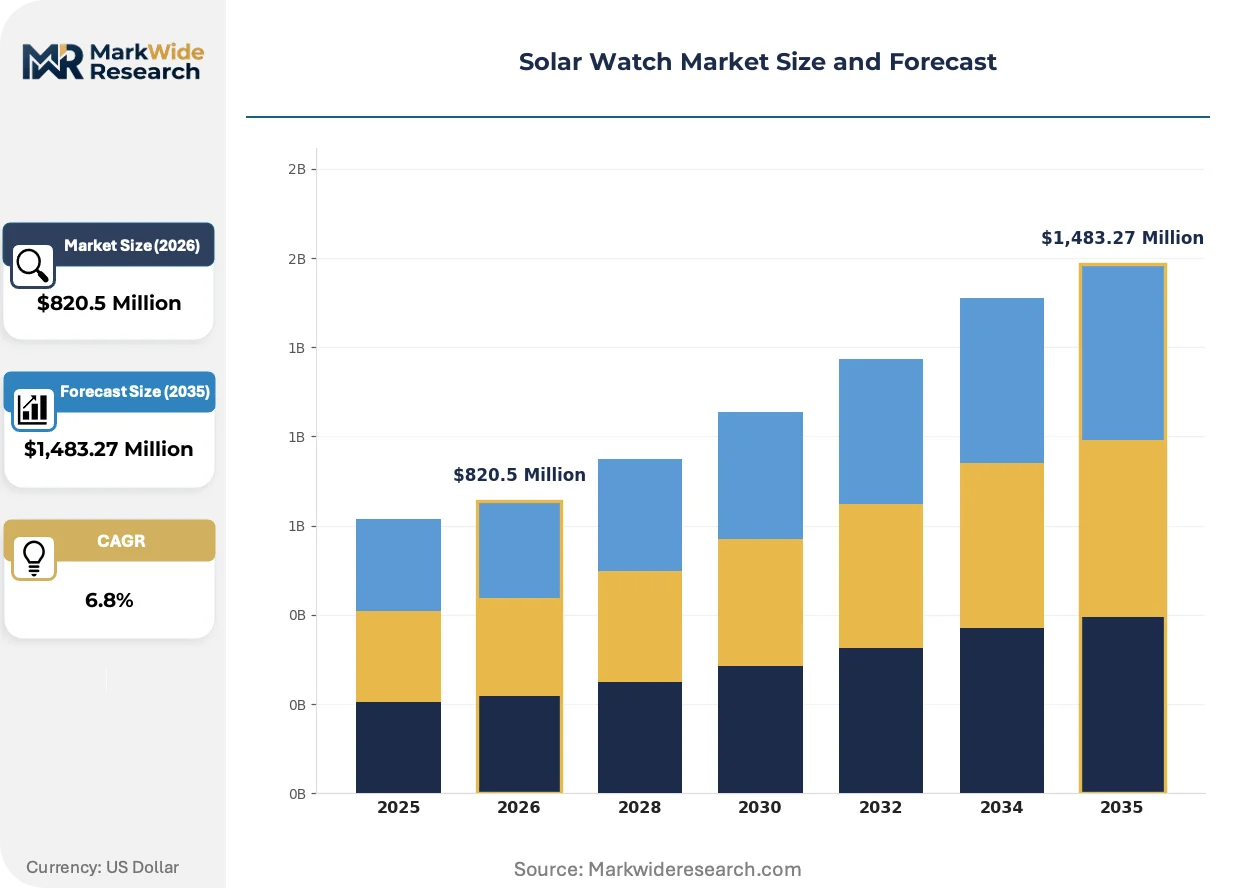
Market Dynamics
Photovoltaic cell miniaturization and the EU Green Deal's circular economy mandates are forcing manufacturers to redesign charge-storage architectures while outdoor recreation demand pulls solar timepieces into mainstream positioning.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Take-back program mandates are accelerating closed-loop material recovery and recyclability investments across European distribution networks.
- Amorphous Silicon Cell Efficiency Gains:Improved low-light energy conversion is extending operational viability in Nordic latitudes and indoor environments previously unsuitable for photovoltaic charging.
- Outdoor Recreation Equipment Integration:Mountaineering and ultralight backpacking communities are adopting solar watches as standard expedition gear, eliminating battery weight and replacement logistics.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Rechargeable cell production clusters in East Asian manufacturing hubs, creating single-source vulnerability for titanium lithium variants.
- REACH Cadmium Restrictions:ECHA reformulation requirements for photovoltaic assemblies are compressing approved supplier lists and extending qualification timelines.
- Mechanical Watch Resurgence:Swiss automatic movements are recapturing collector attention in formal segments, constraining solar adoption in dress-watch categories.
Strategic Opportunities
- India BIS Energy Labeling Expansion:Proposed efficiency grading for electronic timepieces would create first-mover advantage for brands with proven power-reserve specifications.
- Dye-Sensitized Cell Architecture:Organic photovoltaic integration with flexible substrates enables curved dial designs and wearable convergence applications.
- Direct-to-Consumer Repair Platforms:Right-to-repair legislation in multiple jurisdictions is legitimizing modular component sales and independent servicing channels.
Industry Challenges
- Semiconductor Fabrication Talent Scarcity:In-house photovoltaic cell production requires specialized thin-film deposition expertise concentrated in legacy electronics manufacturing regions.
- RoHS Lead-Free Solder Transition:Battery terminal and circuit board assembly requalification is extending new product introduction cycles and raising failure-rate risk during ramp-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Watch Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Smart End User: Men, Women, Children, Unisex Material: Stainless Steel, Plastic, Leather, Ceramic Feature: Water Resistant, GPS, Heart Rate Monitor, Bluetooth |
| Companies Covered | Citizen Watch Co. Ltd., Seiko Holdings Corporation, Casio Computer Co. Ltd., Tissot SA, Garmin Ltd., Fossil Group Inc., TAG Heuer SA, Junghans, Timex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Watch Market Trends and Innovations
Material science breakthroughs and regulatory chemistry restrictions are simultaneously enabling new form factors and compelling component redesign across the solar watch value chain.
Dye-sensitized photovoltaic cells are electrifying flexible substrate applications by converting ambient light through organic semiconductors rather than rigid silicon wafers. Smart apparel manufacturers and medical wearable developers are piloting curved solar surfaces for integration with biometric monitoring bands. This architecture is compressing the boundary between traditional horology and textile-integrated electronics.
REACH Annex XVII cadmium limitations are forcing reformulation of charge-storage electrodes and photovoltaic junction layers in assemblies bound for European markets. Manufacturers are qualifying titanium lithium and solid-state alternatives to maintain market access. Analog dress-watch lines face the steepest compliance cost escalation due to thinner component tolerances.
Expedition outfitters and guided adventure operators are consolidating procurement through specialized outdoor equipment distributors rather than general jewelry channels. This shift is elevating technical specifications and durability testing standards above aesthetic considerations in commercial purchasing decisions. Japanese alpine guiding cooperatives and Patagonian trekking operators are driving this specification-first buying pattern most visibly.
Solar Watch Market Segmentation
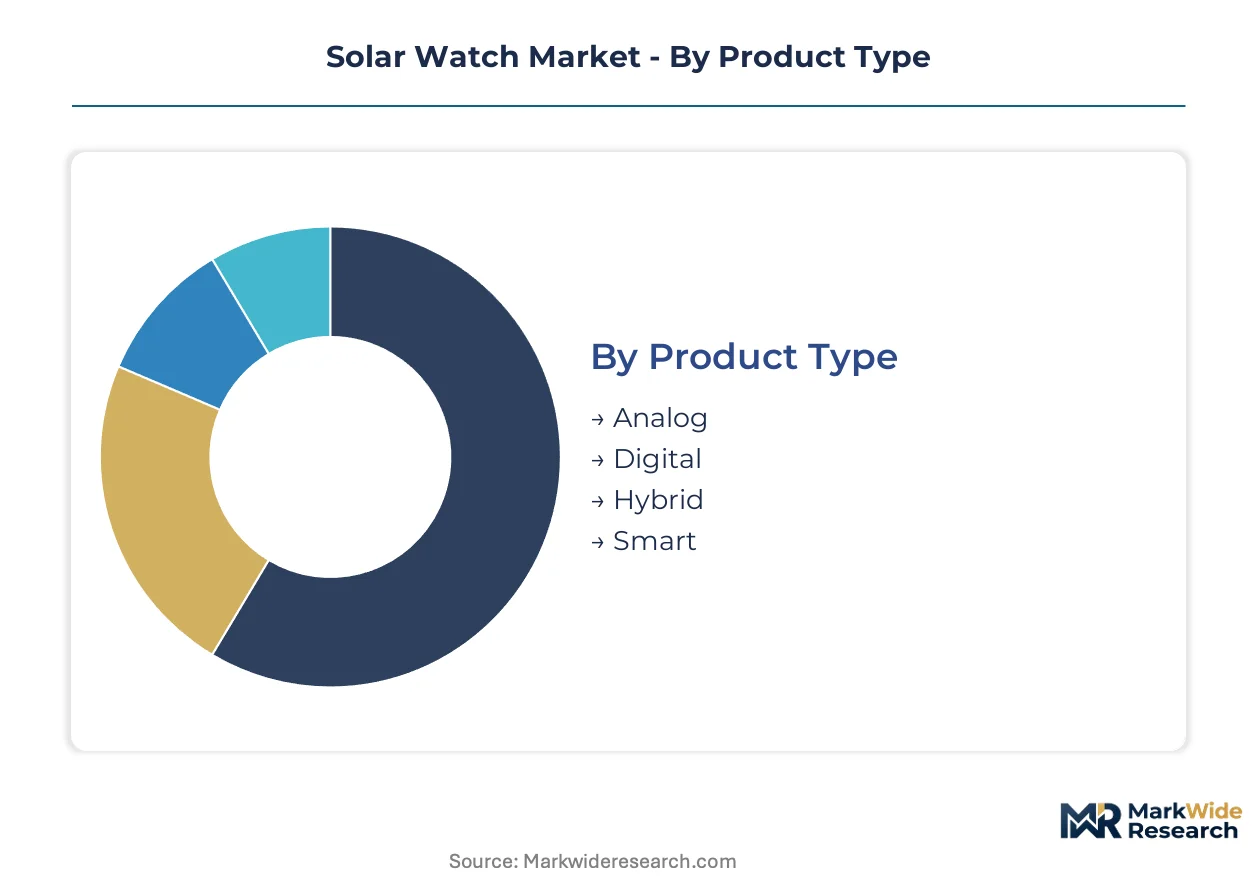
Solar watch segmentation reveals how photovoltaic integration intersects with divergent buyer priorities: heritage aesthetics versus expedition functionality, formal material expectations versus weight-driven outdoor performance. Manufacturers must configure cell architectures, case engineering, and movement calibrations to match distinct use-case economics rather than pursuing universal designs.
Product Type:
Movement complexity and power-draw profiles separate buyers across this dimension, with heritage collectors prioritizing analog simplicity while outdoor professionals demand sensor-rich hybrid configurations.
- Analog:Photovoltaic cells beneath traditional dial apertures power quartz movements with six-month dark reserves. Heritage enthusiasts in Japan sustain this segment through multi-decade brand loyalty to light-powered mechanical aesthetics.
- Smart:Continuous GPS and biometric monitoring drain cells rapidly, requiring larger surface areas and lithium-titanium storage architectures. Mountaineering outfitters in the Alps specification-test these units for expedition reliability.
- Digital:LCD or OLED displays with basic calendar functions occupy entry price tiers through simplified module integration.
- Hybrid:Mechanical hands overlay digital subdisplays, balancing traditional legibility with connected notification functions.
Analog leads volumes today; smart configurations are gaining share fastest.
End User:
Case diameter preferences and strap ergonomics create substantially different engineering requirements across demographic specifications.
- Men:Larger case volumes accommodate bigger photovoltaic apertures and extended battery reserves. Professional segments in Germany prioritize titanium cases for reduced wrist fatigue during industrial shifts.
- Women:Miniaturized cells and curved case architectures address smaller wrist circumferences without sacrificing charge capacity. Japanese domestic market preferences drive ceramic bezel integration for formal occasions.
- Unisex:Modular strap systems and 38-42mm case ranges target shared household purchasing and gift markets.
- Children:Impact-resistant polycarbonate housings with educational time-teaching displays dominate this niche.
Men's specifications anchor current production volumes; women's segments show the steepest expansion trajectory.
Material:
Weight-to-strength ratios and nickel allergy compliance differentiate procurement decisions across case and bracelet compositions.
- Stainless Steel:316L and 904L grades retain dominance in formal segments through scratch resistance and polishability. Swiss finishing houses supply brushed and mirror surfaces for dress-watch lines.
- Titanium:Grade 2 and Grade 5 alloys reduce mass by 40% versus steel while eliminating nickel content. Ultralight backpackers in the Pacific Northwest specify titanium for multi-week treks.
- Plastic:Glass-reinforced polymers enable G-Shock-tier shock absorption at entry price points.
- Leather:Traditional strap material with limited solar relevance; primarily aesthetic for dress-watch configurations.
- Ceramic:Scratch-proof zirconium dioxide cases command premium positioning through sintered manufacturing complexity.
Stainless steel maintains volume leadership; titanium alloys are climbing the fastest among outdoor-oriented buyers.
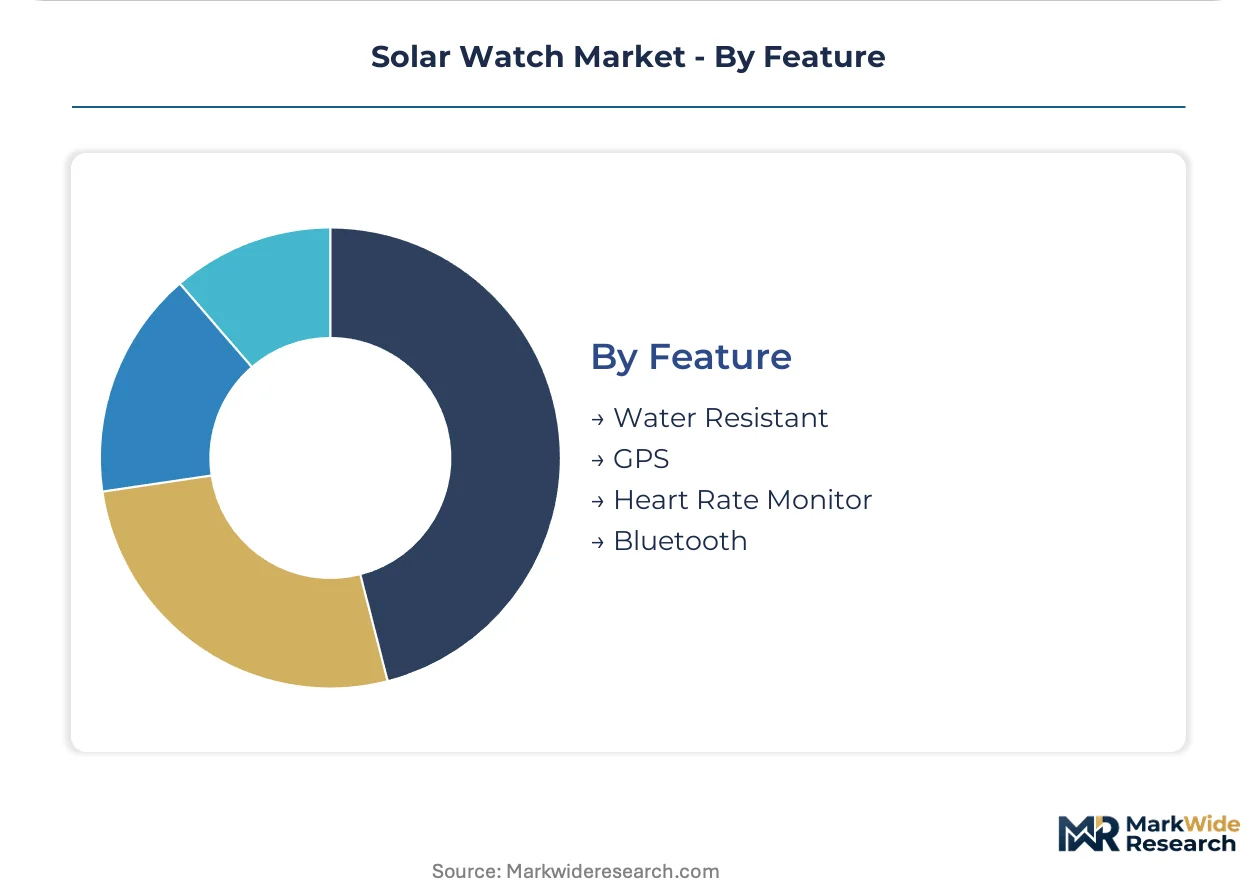
Feature:
Sensor integration depth determines power consumption curves and photovoltaic surface area requirements.
- Water Resistant:100-200 meter depth ratings with screw-down crowns protect cell assemblies during marine exposure. Dive operators in Australia specification-test units for saturation diving compatibility.
- GPS:Multi-constellation positioning drains reserves rapidly, demanding expanded cell surface or supplemental charging. Antarctic expedition coordinators require redundant location logging.
- Heart Rate Monitor:Optical plethysmography sensors add continuous biometric tracking with moderate power draw. Fitness coaches in California integrate these into client monitoring protocols.
- Bluetooth:Low-energy tethering to smartphones enables notification relay with minimal photovoltaic burden.
Water resistance leads feature penetration; GPS integration is expanding most quickly among professional outdoor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo-Yokohama's precision manufacturing corridor concentrates photovoltaic cell fabrication and quartz movement assembly for solar timepieces. Japanese domestic demand for Eco-Drive and Solar caliber watches sustains production volumes that dwarf other national markets. Export flows from this cluster supply North American outdoor retailers and European jewelry distributors with light-powered analog and hybrid configurations.
Japan
Heritage brand loyalty drives replacement cycles among domestic consumers who purchased first-generation solar watches in the 1990s. METI energy-efficiency labeling rewards six-month power reserves, pushing manufacturers toward titanium lithium cell architectures. The Nagoya-Tokaido industrial belt hosts thin-film deposition facilities that supply proprietary photovoltaic junction layers to domestic watchmakers.
United States
Pacific Northwest ultralight backpacking communities specification-test titanium-cased solar watches for multi-week treks without battery replacement. EPA e-waste guidelines in California and Washington pressure distributors to establish take-back programs for rechargeable cell recovery. Boulder, Colorado and Seattle, Washington host expedition outfitters that drive procurement standards for GPS-integrated solar timepieces.
Germany
Industrial shift workers in Baden-Württemberg and Bavaria prioritize titanium cases for reduced wrist fatigue during twelve-hour manufacturing rotations. ECHA REACH Annex XVII cadmium restrictions compel reformulation of charge-storage electrodes for European market access. The Black Forest watchmaking cluster around Pforzheim adapts traditional finishing techniques to solar-compatible case architectures.
Switzerland
Swiss finishing houses in La Chaux-de-Fonds supply brushed and mirror surfaces for dress-watch lines that compete against solar alternatives through mechanical heritage positioning. Swissmedic medical device frameworks create regulatory precedent for biometric sensor integration that solar smartwatch manufacturers reference. Geneva-based luxury distributors resist solar adoption in formal segments where automatic movements dominate collector attention.
India
Proposed BIS energy labeling for electronic timepieces would create first-mover advantage for brands with proven power-reserve specifications entering this price-sensitive market. DGFT import regulations on lithium cells shape local assembly economics for rechargeable storage modules. Mumbai and Delhi-NCR jewelry retailers are expanding solar watch inventory to capture gift-market demand from outdoor recreation enthusiasts.
Solar Watch Market Competitive Landscape
Proprietary photovoltaic cell architecture dominates the current landscape as manufacturers differentiate through in-house semiconductor fabrication rather than module sourcing. The market structures around three tiers: heritage Japanese houses with decades of light-powered expertise, Swiss luxury brands defending mechanical positioning, and electronics specialists integrating solar charging into connected wearables. Strategic archetypes include vertically integrated cell producers, movement specialists licensing calibers to third-party brands, and outdoor equipment manufacturers specification-testing units for expedition reliability. Capacity expansion in titanium lithium cell production and technology licensing agreements for dye-sensitized architectures represent the dominant competitive vectors.
Among heritage Japanese manufacturers, Citizen Watch Co. Ltd., Seiko Holdings Corporation, and Casio Computer Co. Ltd. occupy positions defined by proprietary energy conversion technologies and domestic supply chain control. Citizen exemplifies the vertically integrated archetype through captive photovoltaic cell production. Seiko represents semiconductor fabrication depth ensuring supply security for movement calibers. Casio anchors the durability-focused tier where shock-resistant solar variants compete at entry-to-mid price points. These three entities collectively shape technical standards that European and North American distributors reference in procurement specifications.
| Leading Market Players |
|---|
| Citizen Watch Co. Ltd. |
| Seiko Holdings Corporation |
| Casio Computer Co. Ltd. |
| Tissot SA |
| Garmin Ltd. |
| Fossil Group Inc. |
| TAG Heuer SA |
| Junghans |
| Timex Group |
| Others |
Pricing and Supply Chain Analysis
Expedition outfitters in the Pacific Northwest and Japanese domestic collectors anchor contrasting pricing models across the solar watch market. Procurement consolidation among alpine guiding cooperatives compresses margins on titanium-cased GPS-integrated units, while heritage buyers in Tokyo sustain premium positioning for analog dress-watch configurations with six-month power reserves.
Pricing Analysis
Amorphous silicon cell costs and titanium lithium battery chemistry pass through to landed pricing with 3-6 month lags, compressing margin buffers for mid-tier hybrid configurations. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-finished dress watches from G-Shock-tier durability models and entry-level digital variants. Cost compression in titanium Grade 5 cases is intensifying because REACH cadmium restrictions are extending supplier qualification timelines. Price sensitivity concentrates among ultralight backpackers prioritizing weight-to-cost ratios, while Japanese domestic buyers exhibit lowest elasticity due to multi-decade brand loyalty.
Supply Chain Analysis
REACH Annex XVII and RoHS lead-free solder certifications gate supplier access for European-bound assemblies, compressing approved vendor lists for photovoltaic junction layers. Manufacturing concentrates in Japan, China, and South Korea, with thin-film deposition expertise clustering in the Nagoya-Tokaido corridor and Shenzhen semiconductor hubs. Raw material dependencies include amorphous silicon wafers, titanium sponge for rechargeable cells, and zirconium dioxide for ceramic cases. Single-source vulnerability concentrates in East Asian lithium-titanium cell production. Distribution runs through specialized outdoor equipment distributors in North America and jewelry retail networks in Japan and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar watch market functions as a geographic-arbitrage play where EU Green Deal extended producer responsibility rules raise compliance costs for European distribution, while India's proposed BIS energy labeling creates first-mover windows for brands with proven power-reserve specifications at lower landed cost.
For Market Incumbents: Hedge against mechanical watch resurgence in formal segments by deepening captive supply of photovoltaic cells and titanium lithium architectures. Accelerate qualification of dye-sensitized cell suppliers to maintain European market access under REACH cadmium restrictions. Prioritize direct-to-consumer repair platforms in jurisdictions with active right-to-repair legislation to capture aftermarket service revenue. For New Entrants and Emerging Players: The $200-$400 price-point gap between premium Swiss dress watches and economy-tier digital solar units offers white-space capture potential. Target women's segments in Japan and India where ceramic bezel integration and miniaturized cell architectures remain underpenetrated. Enter through expedition outfitter procurement channels in Colorado and Washington state, specification-testing units for GPS reliability under alpine conditions. For Investors and Strategic Acquirers: Outdoor equipment manufacturers are the most active acquirer in this space, seeking vertical integration into photovoltaic timepiece technology for brand portfolio expansion. Long-term viability hinges on titanium lithium cell supply security and dye-sensitized architecture licensing positions. Watch for inflection signals in Indian BIS labeling implementation timelines and EU Green Deal take-back program enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Dye-Sensitized Cell Licensing | Enables curved dial designs for wearable convergence with flexible organic photovoltaic substrates. |
| Titanium Lithium Capacity Expansion | Reduces single-source vulnerability in East Asian rechargeable cell manufacturing clusters. |
| Direct-to-Consumer Repair Platform Launch | Captures modular component sales revenue under EU and US right-to-repair legislative frameworks. |
| Expedition Outfitter Distribution Partnership | Elevates technical specifications above aesthetic considerations in commercial procurement decisions. |
| India BIS Energy Labeling Pre-Qualification | Creates first-mover positioning in price-sensitive gift-market demand from outdoor recreation buyers. |
Research Methodology
Multiple input streams — thin-film deposition specialists, expedition outfitter procurement managers, jewelry retail category buyers, and regulatory affairs leads at heritage manufacturers — were reconciled through structured primary interviews and secondary validation. Primary engagement targeted photovoltaic cell engineers, alpine guiding cooperative equipment officers, and METI energy-efficiency program administrators. Secondary sources included ECHA REACH restriction updates, METI labeling specifications, EPA e-waste guidelines, and customs trade data for titanium and amorphous silicon wafer flows. Bottom-up unit economics and top-down market sizing were triangulated against production capacity disclosures from Japanese movement manufacturers.
Historical shipment patterns were cross-referenced against panel input from distribution channel partners to construct the analytical framework across the analysis window. Segmentation dimensions modeled include movement type, case material grade, end-user demographic, and feature integration depth alongside expedition versus formal use-case positioning. CAGRs were derived from fitted growth curves applied to base-year consumption data, incorporating photovoltaic cell efficiency improvement trajectories and outdoor recreation equipment spending elasticity assumptions.
Caveats apply where REACH cadmium restriction enforcement intensity, lithium cell supply disruptions, or mechanical watch resurgence velocity could materially shift the outlook. Forecasts reflect assumptions about regulatory chemistry reformulation timelines and right-to-repair legislative adoption rates. A model refresh is warranted upon material change in EU Green Deal extended producer responsibility implementation or Indian BIS labeling finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Solar Traffic Light Market