
 Composite Materials in Renewable Energy Market | 2026-2036
Composite Materials in Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Materials in Renewable Energy Market Analysis
The capability gap between capital-heavy integrated fiber producers and specialized prepreg converters is collapsing as resin infusion automation drives down minimum efficient scale. Toray Industries sustains upstream dominance through captive carbon fiber supply chains spanning precursor to finished fabric. Gurit Holding AG differentiates via advanced core material formulations tailored to longer blade architectures. TPI Composites navigates customer concentration risks by operating dedicated blade manufacturing facilities adjacent to Vestas and GE assembly plants across multiple continents.
Composite materials in renewable energy encompass fiber-reinforced polymers engineered with glass, carbon, or aramid reinforcements embedded in thermoset or thermoplastic matrices, manufactured through processes achieving specific strength-to-weight ratios exceeding 200 MPa/(g/cm³) to withstand cyclic aerodynamic loading across twenty-year service lives. Wind turbine blades represent the dominant product type, with blade lengths surpassing 100 meters driving demand for hybrid carbon-glass layup schedules to manage tip deflection and root moment loads. Prepreg technology commands premium positioning in offshore wind segments where void content below 1% and fiber volume fractions above 60% justify higher material costs against field failure risks. Resin infusion gains share in onshore applications where cost-sensitive utility providers prioritize throughput over ultimate performance margins.
The EU Green Deal and REACH frameworks mandate recyclability disclosures and restrict hazardous substance content in composite manufacturing, compelling reformulation of epoxy systems toward cleavable amine hardeners. Germany's KBA and Denmark's national energy agency enforce blade certification standards under IEC 61400-23 that dictate full-scale structural testing protocols, effectively filtering market access for non-compliant suppliers. Stakeholders must monitor thermoplastic composite welding breakthroughs and blade end-of-life processing infrastructure buildout as these developments will reshape supplier qualification criteria and asset residual value calculations.
Market Dynamics
Resin infusion automation is collapsing minimum efficient scale thresholds and eroding the historical capability gap between integrated fiber producers and specialized prepreg converters, forcing mid-tier suppliers to consolidate or exit.
Growth Catalysts
- EU Green Deal mandates:Binding recyclability targets under REACH and F-Gas Regulation compel blade manufacturers to substitute thermoset epoxies with recyclable thermoplastic matrices, opening material qualification windows for compliant suppliers.
- Offshore wind blade scaling:Tip deflection requirements for 100+ meter architectures drive hybrid carbon-glass layup schedules that triple fiber volume fraction specifications versus onshore equivalents.
- Port of Esbjerg cluster proximity:Siemens Gamesa and Vestas co-location with specialized core material formulators compresses logistics costs and enables just-in-time infusion scheduling for North Sea deployment.
Market Restraints
- Acrylonitrile precursor cost volatility:Carbon fiber production depends on petroleum-derived feedstocks exposed to refinery capacity constraints and energy price spikes, compressing margin buffers for non-integrated converters.
- Toray Industries supply concentration:Captive precursor-to-fabric supply chains dominate aerospace-qualified fiber grades, limiting spot market availability for wind energy specifications during demand surges.
- Cleavable amine hardener technical immaturity:Recyclable epoxy formulations under EU Green Deal compliance timelines exhibit reduced glass transition temperatures versus conventional systems, restricting load-bearing applications.
Strategic Opportunities
- Thermoplastic composite welding:Automated fiber placement with in-situ consolidation eliminates autoclave bottlenecks and enables blade segment joining without adhesive bonds, reducing field assembly labor hours.
- Blade end-of-life processing infrastructure:Pyrolysis and solvolysis facility buildout in Denmark and Germany creates residual value recovery mechanisms that improve project finance terms for offshore wind developers.
- IEC 61400-23 certification data monetization:Full-scale structural test results from KBA and Denmark's national energy agency protocols constitute proprietary datasets for predictive maintenance algorithm training.
Industry Challenges
- Resin transfer molding technician scarcity:Vacuum infusion process control requires specialized expertise in leak detection and flow front monitoring that outpaces vocational training program output in blade manufacturing regions.
- Multi-continental facility qualification timelines:TPI Composites and dedicated blade manufacturers must replicate IEC-compliant testing protocols across Vestas and GE assembly plant adjacencies, extending customer onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Materials in Renewable Energy Market |
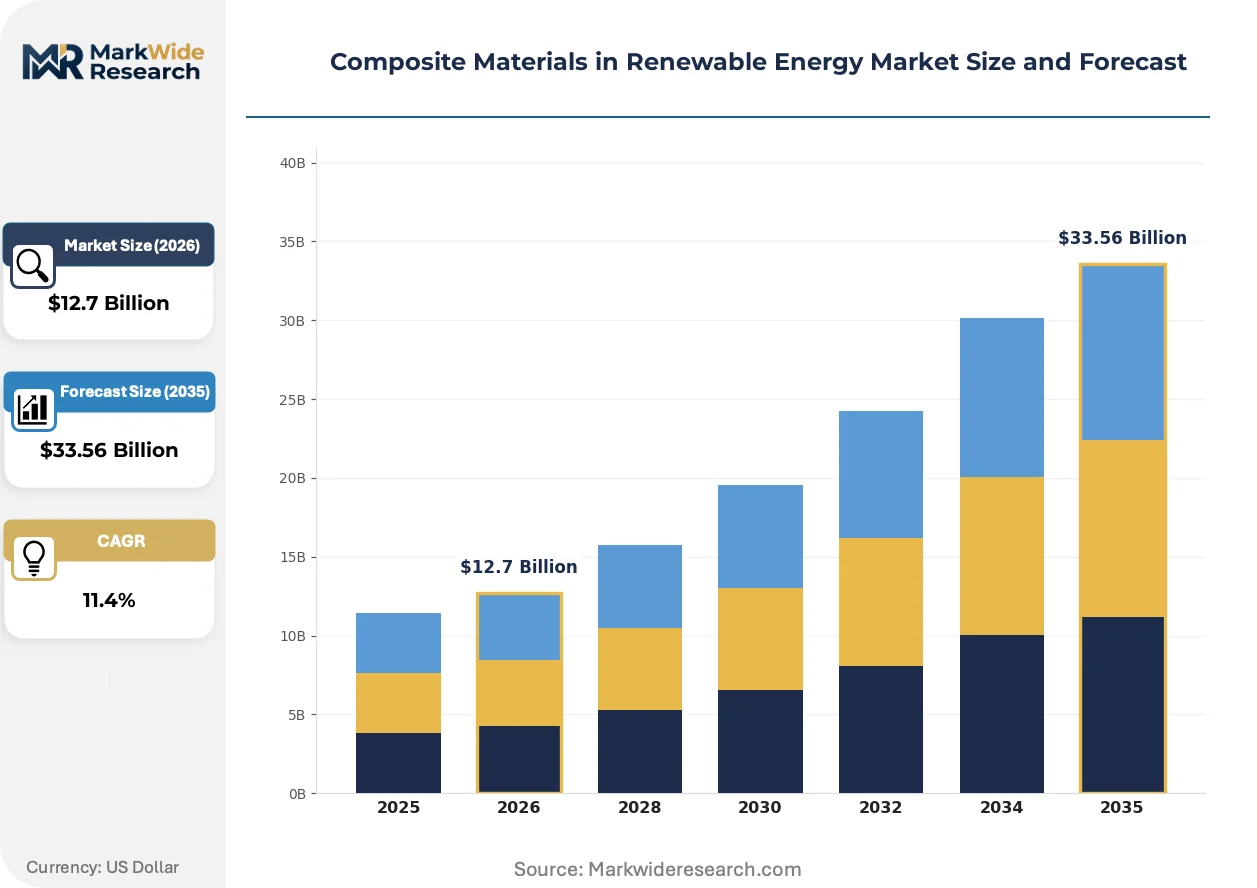
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wind Turbine Blades, Solar Panels, Energy Storage System, Composite Pipes Technology: Filament Winding, Resin Infusion, Vacuum Bagging, Prepregs End User: Manufacturers, Utility Providers, Renewable Installers, Research Institutions Application: Wind Energy, Solar Power, Energy Efficiency, Structural Components |
| Companies Covered | SGL Carbon, Gurit Holding AG, Hexcel Corporation, Vestas, TPI Composites, Inc., Toray Industries, Inc., Teijin Limited, Mitsubishi Chemical Group Corporation, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Materials in Renewable Energy Market Emerging Trajectories
Thermoplastic matrix adoption is fragmenting established supply relationships as blade manufacturers bypass traditional epoxy formulators to secure direct thermoplastic resin supply agreements with polymer compounders.
Automated fiber placement with in-situ consolidation is fragmenting the autoclave-dominated manufacturing landscape for carbon fiber spar caps. Offshore wind blade producers in Denmark and Germany are piloting this technology for 120-meter root segments. The process eliminates cure cycle bottlenecks and enables localized repair protocols that reduce blade replacement logistics costs.
The EU F-Gas Regulation and national implementations are banning hydrofluorocarbon blowing agents in structural core materials by 2030. Manufacturers in Germany must reformulate PET and PVC foam cores with CO2-based or hydrocarbon alternatives that meet KBA durability standards. This regulatory compression is accelerating qualification partnerships between core material suppliers and blade OEMs ahead of compliance deadlines.
Utility-scale wind developers are unbundling blade supply contracts from turbine OEM agreements to secure direct pricing leverage with independent blade manufacturers. Procurement teams at European offshore consortia now issue separate RFPs for blade fabrication versus nacelle assembly, fragmenting historical sole-source relationships. This channel restructuring is most advanced in German and Danish markets where developer concentration enables collective bargaining power.
Composite Materials in Renewable Energy Market Segmentation
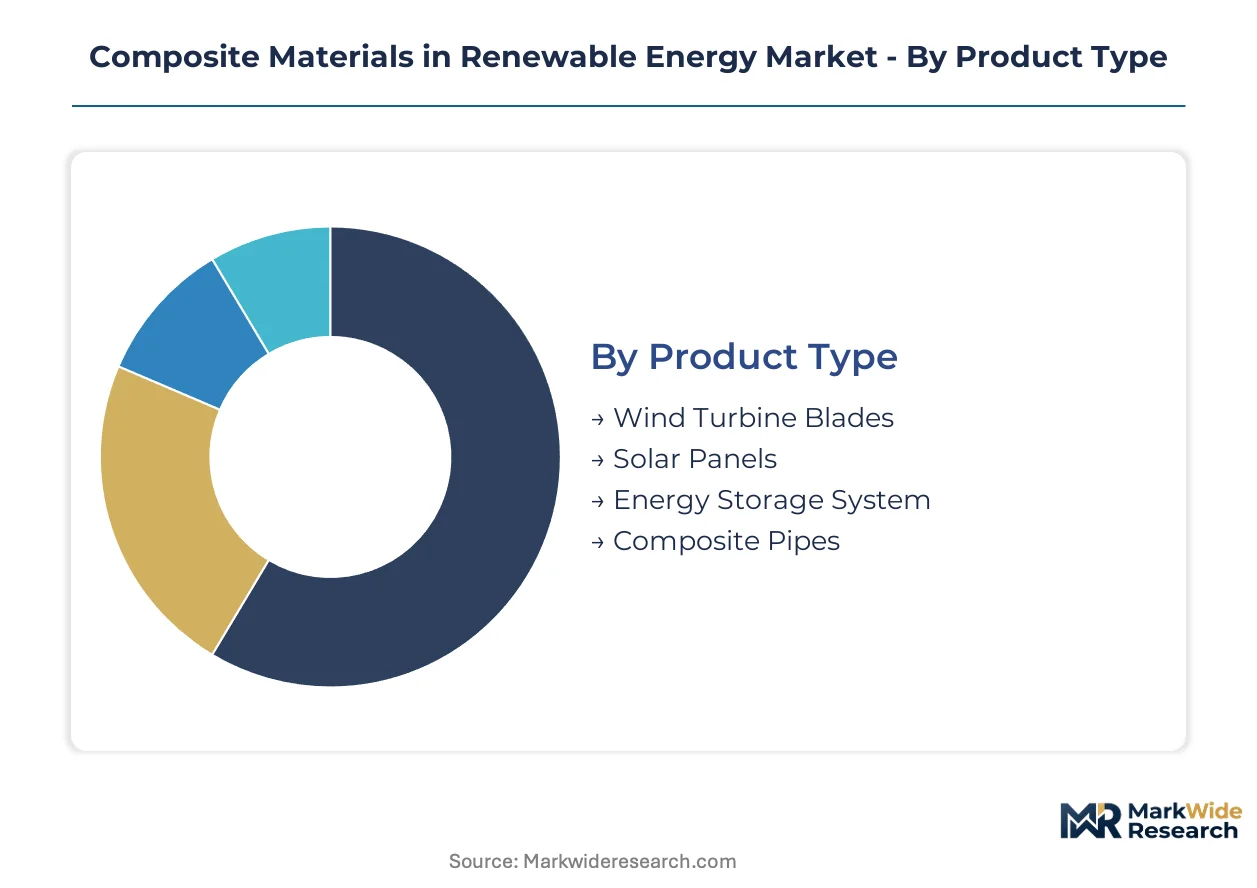
Segmentation in composite materials for renewable energy reveals how regulatory pressure, blade scaling requirements, and manufacturing process economics allocate value across distinct technical specifications and customer relationships.
Product Type:
EU Green Deal recyclability mandates and F-Gas Regulation compliance timelines differentiate product categories by their substitution vulnerability and end-of-life processing infrastructure readiness.
- Wind Turbine Blades:Hybrid carbon-glass fiber laminates with thermoplastic or cleavable epoxy matrices dominate this segment. Siemens Gamesa and Vestas procurement specifications for 100+ meter offshore architectures drive fiber volume fraction requirements above 60% and void content below 1%. KBA certification protocols under IEC 61400-23 filter supplier access, concentrating demand among prepreg-qualified manufacturers with full-scale structural testing capabilities.
- Solar Panels:Glass fiber reinforced polymer frames and mounting structures compete with aluminum extrusions on weight and corrosion resistance. Germany's utility-scale solar developers specify composite alternatives for floating PV installations where saltwater exposure accelerates metal degradation, though thermoset epoxy content complicates EU-mandated recyclability disclosures.
- Energy Storage System:Compression-molded SMC enclosures for battery modules and hydrogen pressure vessels.
- Composite Pipes:Filament-wound GRE/GRP piping for geothermal and district heating networks.
Established volume favors Wind Turbine Blades; emerging adoption favors Solar Panels.
Technology:
Cost tier separation between premium performance specifications and throughput-optimized processes determines technology selection across onshore versus offshore deployment contexts.
- Prepregs:Factory-impregnated carbon fiber fabrics with controlled resin content deliver fiber volume fractions exceeding 60% and void content below 1% for offshore wind spar caps. Toray Industries' captive precursor-to-fabric supply chains dominate aerospace-qualified grades, limiting spot availability for wind energy specifications during demand surges from Port of Esbjerg cluster expansions.
- Resin Infusion:Vacuum-assisted resin transfer molding achieves cost-sensitive throughput for onshore blades. Automation of flow front monitoring and leak detection collapses minimum efficient scale thresholds, eroding historical capability gaps between integrated fiber producers and specialized converters.
- Filament Winding:Automated fiber placement for pressure vessels and pipe structures with consistent wall thickness control.
- Vacuum Bagging:Hand layup consolidation for prototype and repair applications with lower capital requirements.
Prepregs command premium positioning offshore; Resin Infusion gains share onshore where cost sensitivity dominates.
End User:
Customer type concentration shapes procurement leverage, with utility providers unbundling blade contracts from turbine OEM agreements to secure direct pricing access.
- Utility Providers:European offshore wind consortia in Germany and Denmark now issue separate RFPs for blade fabrication versus nacelle assembly, fragmenting historical sole-source relationships. Procurement teams exploit developer concentration for collective bargaining power, demanding recyclability disclosures and end-of-life processing guarantees under EU Green Deal compliance timelines.
- Manufacturers:TPI Composites and dedicated blade fabricators operate facilities adjacent to Vestas and GE assembly plants across multiple continents, navigating customer concentration risks through geographic diversification. IEC 61400-23 qualification replication extends customer onboarding cycles but locks in multi-year supply commitments.
- Renewable Installers:Regional contractors specifying composite mounting hardware and repair materials.
- Research Institutions:National energy agencies and KBA protocol developers advancing thermoplastic welding and cleavable amine formulations.
Utility Providers drive contract unbundling; Manufacturers absorb qualification complexity for facility adjacency returns.
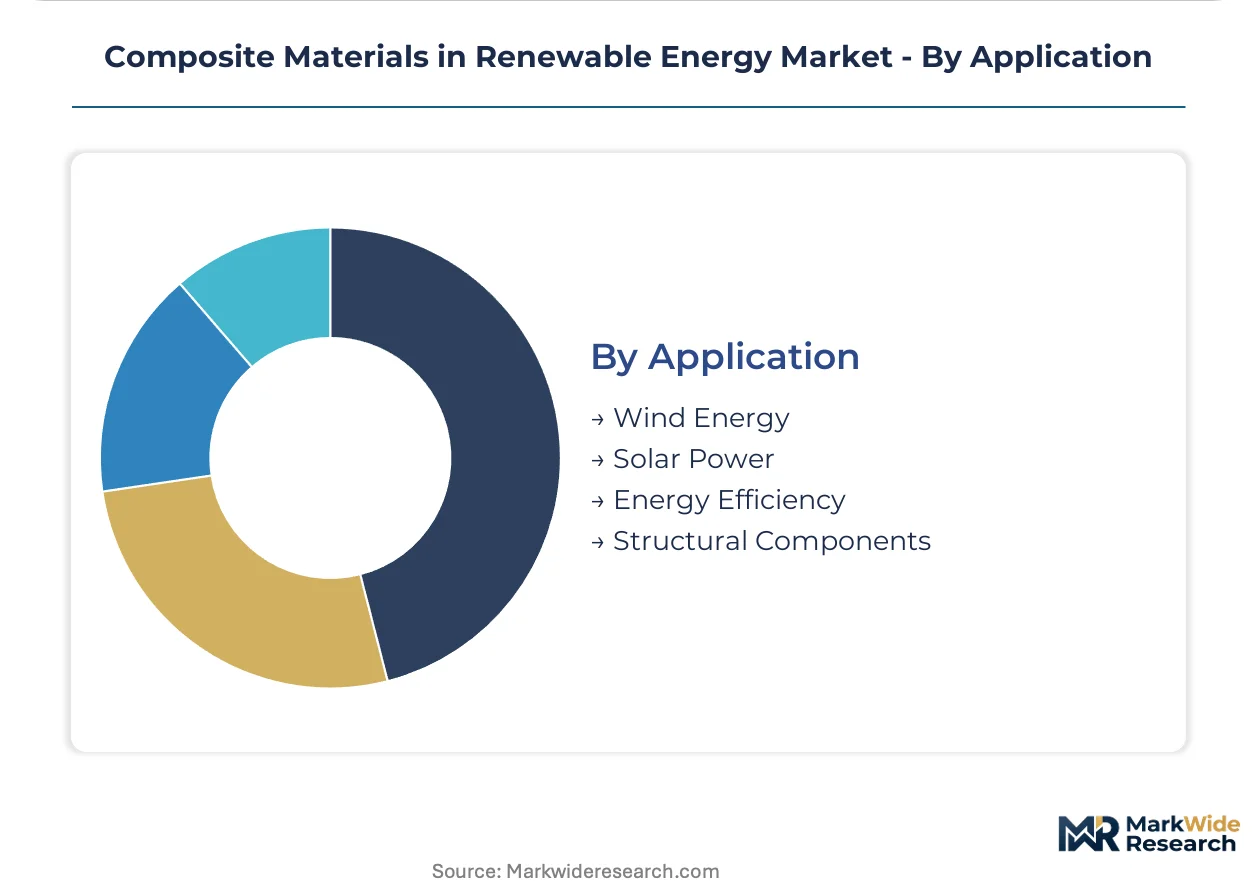
Application:
Application maturity correlates with blade length scaling and the infrastructure density of end-of-life processing facilities.
- Wind Energy:Dominant application segment where 120-meter root segments pilot automated fiber placement with in-situ consolidation. Denmark and Germany lead pyrolysis and solvolysis facility buildout, creating residual value recovery mechanisms that improve project finance terms for offshore developers.
- Solar Power:Composite frames and mounting structures gain traction in floating PV and agrivoltaic installations where corrosion resistance and reduced foundation loads offset material cost premiums.
- Energy Efficiency:Insulation panels and thermal storage vessels utilizing glass fiber reinforced composites.
- Structural Components:Secondary applications including nacelle housings and tower internals.
Wind Energy anchors installed base economics; Solar Power applications are expanding most quickly in specialized deployment contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Denmark and Germany exhibit low price elasticity for offshore blade specifications, while Chinese and Indian procurement teams drive hard volume discounts for onshore resin infusion contracts. This demand-elasticity contrast shapes regional supplier strategies and certification investments.
Germany
KBA certification protocols under IEC 61400-23 mandate full-scale structural testing that filters non-compliant suppliers from the market. The EU Green Deal and REACH frameworks compel reformulation toward cleavable amine hardeners and recyclable thermoplastic matrices. Manufacturing concentrates in Lower Saxony and the Port of Esbjerg-adjacent cluster, where Siemens Gamesa and Vestas operate blade production facilities with just-in-time infusion scheduling.
Denmark
Offshore wind developers specify fiber volume fractions above 60% and void content below 1% for 100+ meter architectures, creating premium positioning for prepreg-qualified manufacturers. Denmark's national energy agency enforces blade certification standards that extend supplier onboarding cycles. Pyrolysis and solvolysis facility buildout in Esbjerg and Copenhagen creates residual value recovery mechanisms that improve project finance terms.
United States
Utility-scale wind developers unbundle blade supply contracts from turbine OEM agreements to secure direct pricing leverage with independent manufacturers. The IRA provides production tax credits that compress effective material costs for domestic blade fabrication. TPI Composites operates dedicated manufacturing facilities adjacent to Vestas and GE assembly plants in Colorado and Iowa, navigating customer concentration through geographic diversification.
China
State-owned wind developers drive aggressive cost-down targets for onshore resin infusion applications, prioritizing throughput over ultimate performance margins. MIIT industrial standards and dual carbon goals accelerate domestic carbon fiber capacity expansion to reduce import dependence. Manufacturing clusters in Jiangsu and Guangdong provinces concentrate blade production for both domestic installation and export markets.
India
Wind energy capacity auctions under CEA guidelines impose stringent localization requirements that favor domestic composite fabricators over imported prepreg solutions. BIS standards for wind turbine components create compliance barriers for non-integrated suppliers lacking in-house testing facilities. Manufacturing activity concentrates in Gujarat and Tamil Nadu, where blade OEMs establish facilities to serve western and southern wind resource zones.
Composite Materials in Renewable Energy Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with upstream fiber producers controlling precursor supply and downstream fabricators competing on blade-adjacent manufacturing scale. The market structure concentrates around carbon fiber supply chains, prepreg qualification capabilities, and resin infusion automation. Two strategic archetypes dominate: integrated fiber-to-fabric producers with captive precursor operations, and specialized blade manufacturers with multi-continental facility networks. Competitive moves center on backward integration into precursor production and geographic expansion through dedicated facilities adjacent to turbine OEM assembly plants.
Within the integrated fiber tier, Toray Industries and Teijin Limited represent upstream dominance through captive carbon fiber supply chains spanning precursor to finished fabric. Among specialized blade fabricators, TPI Composites exemplifies the facility-adjacency model, while Gurit Holding AG occupies a position in advanced core material formulations. SGL Carbon anchors the European carbon fiber segment. These companies illustrate how supplier qualification protocols and resin infusion automation are collapsing historical capability gaps between tiers.
| Leading Market Players |
|---|
| SGL Carbon |
| Gurit Holding AG |
| Hexcel Corporation |
| Vestas |
| TPI Composites, Inc. |
| Toray Industries, Inc. |
| Teijin Limited |
| Mitsubishi Chemical Group Corporation |
| Owens Corning |
| Others |
Supply Flow & Price Mechanics
IEC 61400-23 certification protocols gate both supplier qualification and price differentiation simultaneously, creating tiered access where KBA-compliant manufacturers command premiums over non-certified converters while resin infusion automation compresses margins for mid-tier entrants lacking full-scale structural testing capabilities.
Pricing Analysis
After-sales service contracts and blade end-of-life processing guarantees now drive lifetime value capture. Three-tier pricing structure across premium prepreg, standard resin infusion, and economy-grade thermoplastic formulations separates offshore wind specifications from onshore utility procurement. Price differentiation rests on fiber volume fraction certification and void content testing under Denmark's national energy agency protocols. Cost compression in onshore resin infusion tiers is intensifying because Chinese state-owned developers drive aggressive throughput targets. Utility providers in Germany and Denmark exhibit lowest price sensitivity for offshore blade specifications, while Indian auction participants under CEA guidelines show highest elasticity.
Supply Chain Analysis
Inventory buffers for acrylonitrile precursor and carbon fiber tow have tightened to eight-week cycles as Toray Industries' captive supply chains limit spot market availability during Port of Esbjerg cluster expansions. Manufacturing concentrates in Germany, Denmark, and China, with Jiangsu province hosting expanding domestic carbon fiber capacity under MIIT industrial standards. Raw material dependencies draw from petroleum-derived acrylonitrile, glass fiber rovings from Owens Corning, and specialized PET foam cores subject to F-Gas Regulation reformulation deadlines. Single-source vulnerability around aerospace-qualified carbon fiber grades threatens wind energy spot procurement during demand surges. Distribution runs through dedicated blade manufacturing facilities adjacent to Vestas and GE assembly plants across multiple continents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic matrix substitution under EU Green Deal mandates constitutes a high-growth disruption, with cleavable amine hardener technical maturation and automated fiber placement welding poised to reshape supplier economics across the next decade.
For Market Incumbents: Compound certification investments under IEC 61400-23 protocols to lock out mid-tier resin infusion converters threatening margin compression. Prioritize backward integration into precursor production to offset acrylonitrile cost volatility eroding margin buffers. Capture residual value recovery through pyrolysis facility partnerships in Denmark and Germany before independent blade manufacturers consolidate end-of-life processing relationships. For New Entrants and Emerging Players: KBA fast-track certification for thermoplastic composite welding equipment offers entry into 120-meter root segment fabrication where automated fiber placement eliminates autoclave bottlenecks. Target Indian utility-scale auctions under CEA localization requirements where domestic fabricators lack IEC-compliant testing infrastructure. Lead with resin infusion automation packages that collapse minimum efficient scale thresholds for regional blade manufacturers in Gujarat and Tamil Nadu. For Investors and Strategic Acquirers: F-Gas Regulation 2030 compliance deadlines reshape the acquisition landscape toward core material formulators with CO2-based blowing agent formulations already qualified by Siemens Gamesa and Vestas. Long-term viability centers on suppliers with demonstrated thermoplastic matrix welding capabilities and blade end-of-life processing infrastructure ownership. Watch for thermoplastic composite in-situ consolidation breakthroughs at Denmark's national energy agency test facilities as the signal indicating qualification window shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries' captive acrylonitrile-to-fabric supply chains demonstrate margin defense against petroleum feedstock volatility. |
| Thermoplastic Matrix Qualification Partnership | Direct resin supply agreements with polymer compounders bypass traditional epoxy formulators fragmenting established supplier relationships. |
| End-of-Life Processing Infrastructure Buildout | Pyrolysis facility investments in Esbjerg and Copenhagen create residual value recovery mechanisms improving offshore project finance terms. |
| Multi-Continental Facility Replication | TPI Composites' dedicated manufacturing adjacencies to Vestas and GE assembly plants lock in multi-year supply commitments through IEC qualification. |
| Automated Fiber Placement Deployment | In-situ consolidation technology eliminates autoclave bottlenecks for 120-meter root segments piloted by Danish and German offshore blade producers. |
Methodological Framework
A spread of perspectives from blade manufacturing plant managers, utility procurement officers at European offshore consortia, carbon fiber R&D directors, resin formulator technical leads, and EPC contractors converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from IEC 61400-23 certification databases, KBA structural test records, EU F-Gas Regulation implementation tracking, customs trade data for carbon fiber imports, and SEC filings from publicly traded blade manufacturers. Bottom-up blade production volume estimates and top-down composite materials consumption projections were triangulated to anchor forecast ranges.
Segmentation dimensions modeled span fiber reinforcement type, matrix chemistry, manufacturing process technology, blade length architecture, and regional regulatory cluster across the analysis window. CAGRs were derived from regression analysis against historical capacity expansion announcements and projected offshore wind auction pipelines. Forecast inputs incorporated thermoplastic matrix substitution curves under EU Green Deal compliance timelines and resin infusion automation adoption rates affecting minimum efficient scale thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and carbon fiber precursor supply continuity; material deviation in cleavable amine hardener technical performance or acrylonitrile refinery capacity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Solar Watch Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Marine Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Europe Solar Tracker Market