
 South Korea Motor Insurance Market | 2026-2036
South Korea Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Motor Insurance Market Analytics
Fleet buyer consolidation among logistics and delivery platforms is realigning premium volume toward commercial customer segments. Samsung Fire & Marine Insurance leverages its agency network to sustain dominance in comprehensive coverage. Hyundai Marine & Fire Insurance anchors its position through direct channel integration with automotive OEMs. DB Insurance competes on digital claims processing speed for ride-sharing operators.
South Korea motor insurance constitutes risk-transfer contracts indemnifying policyholders against vehicle damage, bodily injury, and third-party liability, priced via actuarial models incorporating telematics data, repair cost indices, and regional accident frequency rates. The primary purpose centers on financial protection for asset owners and liability shielding for drivers operating in dense urban traffic environments. Comprehensive policies command the largest premium pool, while ride-sharing segments within customer type exhibit the fastest expansion trajectory. Distribution channel dynamics reveal online platforms capturing share from traditional agent networks as younger demographics prefer self-service quotation and binding.
The Financial Services Commission and Financial Supervisory Service jointly govern insurer solvency, product filing approvals, and consumer protection standards, with the Korea Insurance Development Institute setting reference loss ratios and ratemaking guidelines. MFDS automotive safety mandates indirectly shape claim severity by accelerating advanced driver assistance system penetration in new vehicles. Stakeholders must monitor how autonomous vehicle liability frameworks evolve and whether usage-based insurance data standards fragment across competing telematics platforms.
Market Dynamics
Telematics-enabled usage-based insurance is compressing traditional risk-pooling models as the Financial Services Commission mandates capital adequacy buffers that favor granular data collection over historical loss ratios.
Growth Catalysts
- ADAS penetration:MFDS automotive safety mandates accelerate advanced driver assistance system installation in new vehicles, reducing claim frequency and expanding insurable asset pools.
- Fleet digitization:Logistics platforms consolidate procurement of commercial coverage, redirecting premium volume toward comprehensive policies with integrated telematics monitoring.
- Direct channel expansion:Online quotation and binding platforms capture share from traditional agency networks as Seoul metropolitan corridor demographics skew younger and mobile-first.
Market Restraints
- Repair cost inflation:Semiconductor shortages and specialized EV component scarcity inflate collision claim severity, compressing loss ratios for comprehensive underwriters.
- Capital adequacy pressure:Financial Services Commission solvency requirements force smaller insurers to raise reserves or exit, concentrating risk-bearing capacity among top-tier carriers.
- Telematics platform fragmentation:Competing data standards between automotive OEM systems and third-party device providers create integration friction for unified risk scoring.
Strategic Opportunities
- Autonomous liability frameworks:Evolving fault allocation between vehicle manufacturers and operators creates product white space for cyber-physical coverage hybrids.
- Ride-sharing specialization:Platform economy drivers in Gyeonggi and Busan corridors remain underpenetrated by tailored per-mile policies with dynamic premium adjustment.
- Korea Insurance Development Institute data pooling:Centralized loss ratio benchmarking enables smaller carriers to compete on pricing precision without captive telematics infrastructure.
Industry Challenges
- Actuarial talent scarcity:Demand for data scientists capable of integrating telematics streams with traditional risk models outstrips supply from domestic university pipelines.
- Legacy system integration:Incumbent policy administration platforms require costly re-architecture to support real-time premium adjustment and API-driven partner connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Motor Insurance Market |
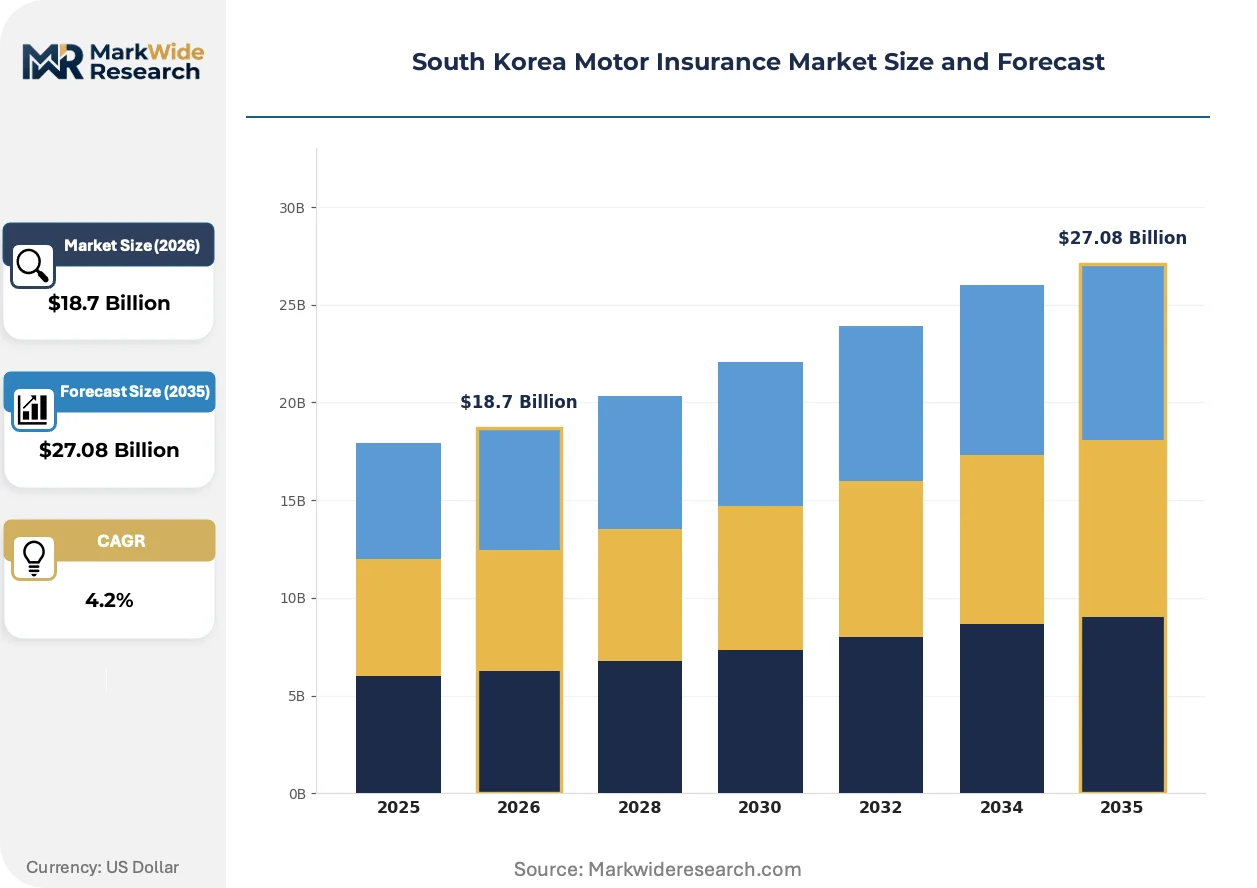
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party Liability, Collision, Personal Injury Protection Customer Type: Individual, Commercial, Fleet, Ride-sharing Coverage Level: Basic, Standard, Enhanced, Premium Distribution Channel: Online, Agents, Brokers, Direct Sales |
| Companies Covered | Korean Reinsurance Company, Lotte Non Life Insurance, Samsung Fire & Marine Insurance, Hanwha General Insurance, DB Insurance, Hyundai Marine & Fire Insurance, Meritz Fire & Marine Insurance, AXA General Insurance, KB Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Motor Insurance Market Evolving Landscape
Digital distribution architectures and embedded insurance partnerships are dismantling the traditional agent-mediated quotation process, while regulatory pressure on capital efficiency accelerates investment in predictive analytics infrastructure.
Telematics data collection through OEM-integrated black boxes and smartphone-based applications is electrifying risk assessment precision for commercial fleets. Large logistics operators in the Seoul-Incheon corridor now demand second-by-second vehicle telemetry to negotiate dynamic premium adjustments. This capability compression is forcing traditional underwriters to abandon annual fixed-rate contracts in favor of usage-calibrated alternatives.
Financial Services Commission solvency regulation revisions now require stress-testing against correlated catastrophe scenarios and cyber-physical system failures. Insurers must model autonomous vehicle liability cascades and connected infrastructure attack vectors in reserve calculations. Commercial comprehensive lines face the steepest compliance burden as fleet-scale exposures concentrate systemic risk.
Younger policyholders in Daegu and Daejeon metropolitan zones increasingly bypass agent networks entirely, completing quotation-to-binding journeys through insurer mobile applications. Self-service channels now capture the majority of new comprehensive policy originations outside the 50-plus demographic. This channel rotation pressures traditional agency networks to pivot toward complex commercial advisory services or face disintermediation.
South Korea Motor Insurance Market Segmentation
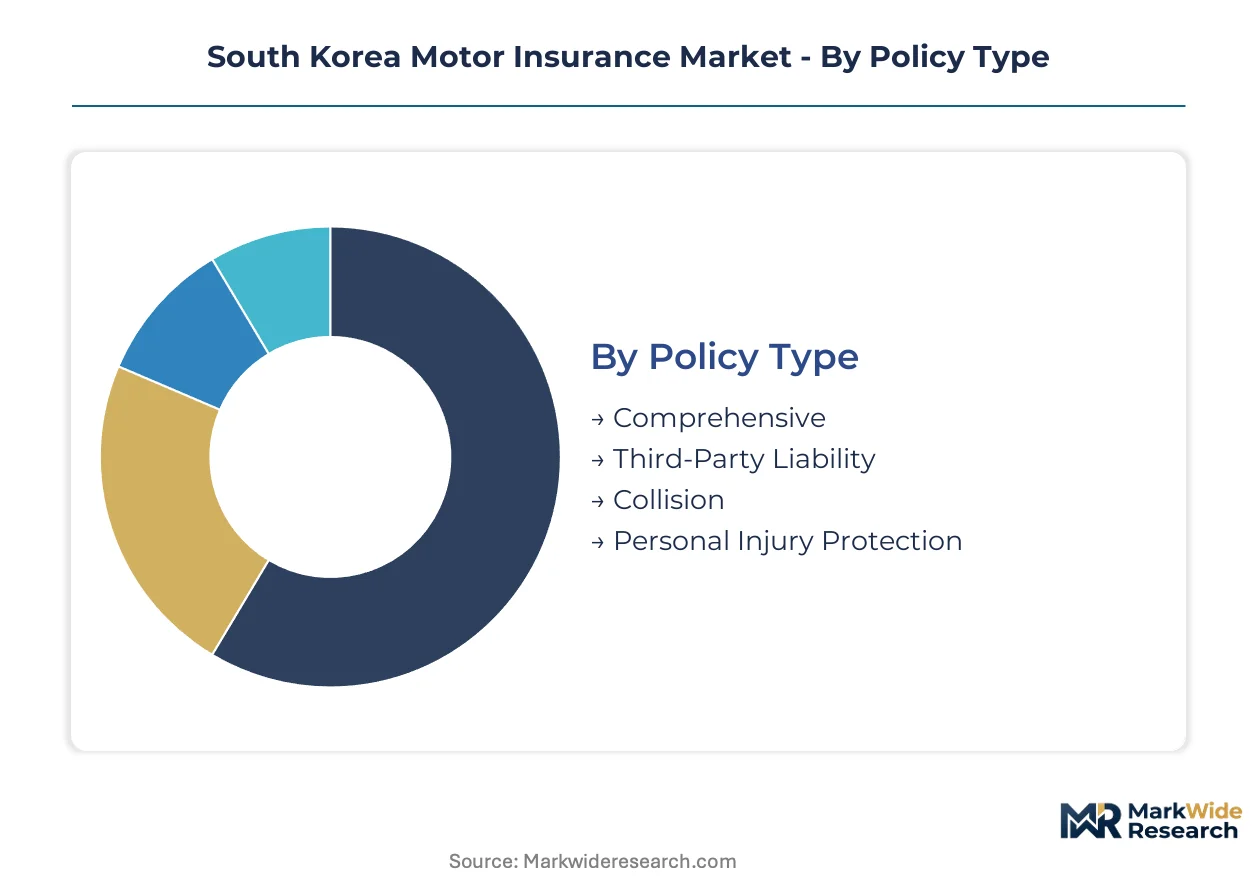
Motor insurance segmentation in South Korea reflects divergent risk profiles between dense urban corridors and commercial logistics corridors. Policy structures, customer categories, and distribution architectures each command distinct pricing models and capital allocation strategies.
Policy Type:
Standalone comprehensive policies operate independently of manufacturer warranties, while embedded liability coverages integrate with OEM service contracts and fleet management platforms.
- Comprehensive:Bundled coverage indemnifying against theft, fire, natural disasters, and collision damage alongside third-party liability. Seoul metropolitan corridor households and premium vehicle owners concentrate demand here as asset values and repair costs escalate in dense traffic environments.
- Third-Party Liability:Mandatory minimum coverage satisfying Financial Services Commission legal requirements for bodily injury and property damage to others. Regulatory compliance drives universal penetration, though coverage limits vary by vehicle class and commercial registration status.
- Collision:Damage-only protection for policyholder vehicles regardless of fault determination. Fleet operators in Busan and Gwangju logistics hubs favor this stripped structure to self-insure liability exposure while transferring physical damage risk.
- Personal Injury Protection:Medical expense and income replacement coverage for occupants irrespective of accident fault allocation. Ride-sharing platforms in Gyeonggi province increasingly mandate this addition for driver-partner contractual compliance.
Volume placements concentrate in Comprehensive; the faster expansion belongs to Personal Injury Protection.
Customer Type:
Cost tier stratification separates mass retail policyholders from commercial entities with captive risk management functions and telematics infrastructure.
- Individual:Private vehicle owners purchasing single-car policies through agency networks or direct channels. Daegu and Daejeon metropolitan zones exhibit the strongest self-service channel migration as mobile-first demographics bypass traditional intermediaries.
- Commercial:Small and medium enterprises operating vehicle fleets under five units, typically procuring through broker-mediated placement. These buyers balance price sensitivity against coverage breadth, often accepting higher deductibles to compress premium outlays.
- Fleet:Large logistics and delivery platforms with centralized procurement functions and integrated telematics monitoring. Seoul-Incheon corridor operators now demand second-by-second telemetry integration to negotiate dynamic premium adjustments based on real-time risk exposure.
- Ride-sharing:Platform economy drivers operating under Transportation Network Company permits, requiring specialized per-mile or per-trip coverage structures. This segment remains underpenetrated by tailored products with dynamic premium adjustment capabilities.
Revenue concentration sits with Fleet buyers; Individual policy origination is climbing the fastest.
Coverage Level:
Margin architecture differentiates basic regulatory compliance offerings from premium tiers with concierge services and guaranteed replacement vehicle provisions.
- Basic:Minimum statutory coverage satisfying Financial Services Commission compulsory insurance mandates. Price-sensitive individual buyers in secondary cities dominate this tier, with limited add-on flexibility and restricted claim service channels.
- Standard:Mid-market positioning combining mandatory liability with modest own-damage protection and standard deductible structures. This tier captures the majority of middle-income household vehicle registrations outside the Seoul metropolitan corridor.
- Enhanced:Elevated liability limits, reduced deductibles, and supplementary benefits including roadside assistance and rental reimbursement. Commercial fleets with moderate risk appetites and individual owners of higher-value domestic vehicles cluster here.
- Premium:Maximum liability ceilings, zero-deductible options, OEM-certified repair guarantees, and dedicated claim concierge services. Luxury vehicle concentrations in Gangnam and Seongnam districts sustain this tier's profitability despite lower policy counts.
Policy count concentrates in Standard; Premium tier revenue per contract is expanding most quickly.
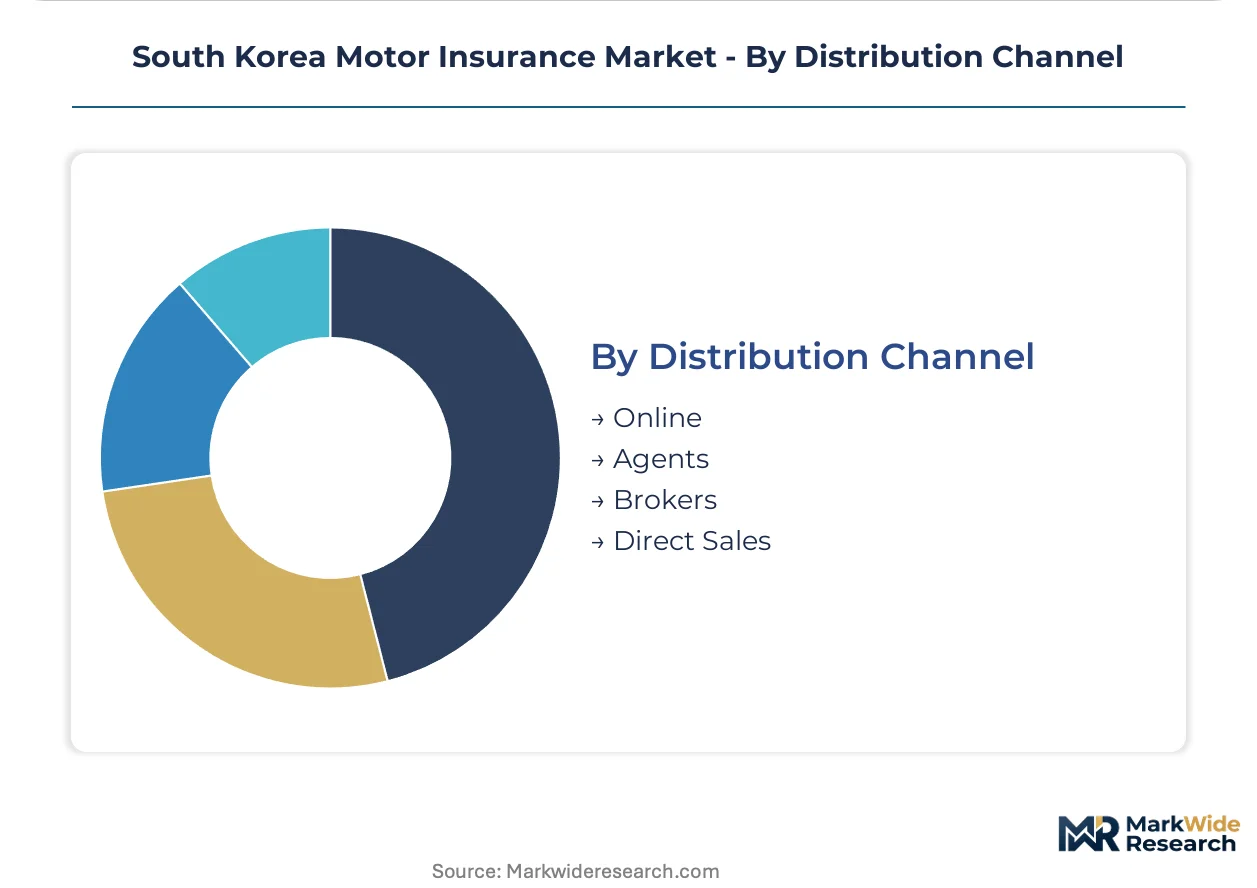
Distribution Channel:
Channel maturity separates legacy agency networks with embedded customer relationships from digital-native platforms capturing younger demographics.
- Online:Self-service quotation and binding through insurer websites and mobile applications. Daegu metropolitan zone demographics under 35 exhibit complete channel preference for this architecture, bypassing human intermediaries entirely.
- Agents:Exclusive and independent representatives providing advisory services and claims advocacy. Samsung Fire & Marine Insurance maintains dominance through this channel for comprehensive coverage placement in established household segments.
- Brokers:Independent intermediaries accessing multiple carrier panels for commercial and complex risk placement. Fleet buyers and commercial entities rely on broker negotiation leverage to secure coverage terms and premium adjustments unavailable through direct channels.
- Direct Sales:Insurer-employed channels integrated with automotive OEMs and financial institutions. Hyundai Marine & Fire Insurance anchors market position through captive arrangements with affiliated vehicle manufacturers and dealer networks.
Transaction volume concentrates in Agents; Online channel share is gaining the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Seoul Capital Area where vehicle density and premium per policy both outpace national benchmarks. The Financial Services Commission capital adequacy rules reshape carrier distribution across metropolitan corridors. Regional variation reflects divergent fleet digitization rates and telematics infrastructure maturity.
Seoul Capital Area
Luxury vehicle concentrations in Gangnam and Seongnam districts sustain premium-tier profitability despite lower policy counts. The Financial Services Commission mandates stricter solvency buffers for carriers underwriting dense urban exposures. Fleet operators in the Seoul-Incheon corridor demand second-by-second telemetry integration for dynamic premium negotiations.
Busan-Ulsan
Logistics platforms consolidate commercial coverage procurement across the southeastern maritime industrial belt. MFDS automotive safety mandates accelerate ADAS penetration in heavy commercial vehicles registered here. Port-centric fleet operators favor collision-only structures to self-insure liability while transferring physical damage risk.
Daegu-Gyeongbuk
Younger demographics under 35 exhibit complete channel preference for self-service mobile applications. The Korea Insurance Development Institute loss ratio benchmarking enables regional carriers to compete without captive telematics infrastructure. Metropolitan zone households bypass traditional agency networks entirely for comprehensive policy origination.
Daejeon-Sejong
Government administrative concentration generates stable commercial fleet demand from public sector contractors. Financial Supervisory Service consumer protection standards enforce uniform disclosure requirements across direct and agent-mediated channels. Administrative city demographics skew toward digital-native professionals preferring online quotation-to-binding journeys.
Gwangju-Honam
Ride-sharing platform economy drivers remain underpenetrated by tailored per-mile policies with dynamic adjustment capabilities. Regional repair cost inflation from semiconductor shortages compresses comprehensive underwriter margins. Honam corridor logistics operators lag Seoul counterparts in telematics-enabled usage-based insurance adoption.
South Korea Motor Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded insurance partnerships and telematics platform integration. The market structure concentrates risk-bearing capacity among top-tier carriers as capital adequacy pressure forces smaller insurers to raise reserves or exit. Three archetypes dominate: legacy agency-network carriers, direct-channel integrators, and digital-native specialists competing on claims processing velocity. Consolidation through selective M&A and strategic technology licensing agreements reshapes tier boundaries.
Within the legacy carrier tier, Samsung Fire & Marine Insurance and Hyundai Marine & Fire Insurance exemplify divergent channel strategies. Samsung Fire & Marine Insurance anchors comprehensive coverage placement through embedded agency relationships. Hyundai Marine & Fire Insurance occupies a position linking automotive OEM distribution networks with captive dealer arrangements. DB Insurance represents the digital-native vector, competing on real-time claims processing infrastructure for platform economy segments.
| Leading Market Players |
|---|
| Korean Reinsurance Company |
| Lotte Non Life Insurance |
| Samsung Fire & Marine Insurance |
| Hanwha General Insurance |
| DB Insurance |
| Hyundai Marine & Fire Insurance |
| Meritz Fire & Marine Insurance |
| AXA General Insurance |
| KB Insurance |
| Others |
Value Network & Pricing Analysis
Telematics-enabled risk scoring infrastructure simultaneously compresses actuarial modeling costs and concentrates data procurement power among carriers with captive OEM partnerships. Financial Services Commission capital adequacy buffers reward granular telemetry integration, forcing smaller insurers toward Korea Insurance Development Institute pooled benchmarks or exit.
Pricing Analysis
Volume concentrates in third-party liability minimums while margins accrue to premium-tier comprehensive policies with zero-deductible structures. Price differentiation rests on telematics data granularity and repair network certification tier—OEM-certified garages command 15-25% premium uplifts over independent shops. Cost compression in collision coverage intensifies because semiconductor shortages inflate EV component replacement costs. Individual buyers in Daegu and Daejeon corridors exhibit highest price sensitivity; fleet operators in Seoul-Incheon corridor show lowest sensitivity due to captive risk management functions.
Supply Chain Analysis
Domestic-content mandates from the Ministry of Trade, Industry and Energy reshape telematics device sourcing toward Korea-certified black box manufacturers. Component supply concentrates in South Korea, Taiwan, and Japan for semiconductor modules and sensor arrays. Raw material dependencies include lithium-ion battery cells, advanced driver assistance system chipsets, and collision repair aluminum alloys. Single-source vulnerability runs through Taiwan semiconductor foundries serving automotive OEM telematics stacks. Distribution runs through insurer-integrated agency networks for comprehensive policies and direct OEM-dealer channels for embedded coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea motor insurance market sits in a technology-transition phase where smartphone-based telematics displaces dedicated black box installations as the dominant risk data collection mode.
For Market Incumbents: Anchor market position through exclusive telematics data partnerships with Hyundai Motor Group and Kia Corporation, securing first-mover access to next-generation vehicle sensor streams. Consolidate agency network control in Seoul metropolitan corridor comprehensive coverage while accelerating legacy policy administration platform cloud migration to support real-time premium adjustment capabilities. For New Entrants and Emerging Players: Ride-sharing platform partnerships offer the most penetrable entry vector, as Transportation Network Company driver coverage remains underdeveloped in Gyeonggi and Busan corridors. Target per-mile policy origination through API integration with Coupang and Baemin delivery platforms, leveraging Korea Insurance Development Institute loss ratio benchmarks to bypass captive telematics infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic technology licensing to tier-two carriers seeking telematics capabilities without R&D investment. Long-term viability favors carriers with demonstrated autonomous vehicle liability modeling competence and regulatory pre-approval for cyber-physical coverage products. Monitor Financial Services Commission solvency rule revisions as the primary inflection signal for forced consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time risk scoring from Hyundai and Kia vehicle data streams compresses loss ratios for early adopters. |
| OEM Embedded Insurance Partnership | Coverage binding at point-of-sale through dealer networks captures younger demographics before agency channel contact. |
| Autonomous Liability Product Filing | Financial Services Commission pre-approval for cyber-physical coverage creates regulatory moat against late entrants. |
| Claims Processing Velocity Investment | DB Insurance's real-time settlement infrastructure sets benchmark for ride-sharing operator retention. |
| Korea Insurance Development Institute Data Pooling | Centralized loss ratio access enables tier-two carriers to compete on pricing without captive infrastructure. |
Research Methodology
Document review covered Financial Services Commission solvency filings, Korea Insurance Development Institute ratemaking guidelines, and MFDS automotive safety mandates, complemented by interviews with chief underwriting officers, telematics platform engineers, fleet procurement directors, and agency network managers. Secondary validation drew from insurer annual reports, vehicle registration databases, and repair cost indices published by the Korea Insurance Development Institute. Bottom-up policy origination modeling triangulated against top-down premium pool estimates from regulatory disclosures.
Historical premium growth patterns cross-referenced against panel input from underwriting executives informed the analytical framework across the analysis window. Segmentation dimensions modeled include policy type, customer category, coverage tier, and distribution channel, with additional granularity for telematics adoption status. CAGRs derived from regression analysis of premium pool expansion against vehicle fleet growth and average insured value trends. Industry-specific forecast inputs incorporated ADAS penetration curves from MFDS safety mandate timelines and ride-sharing platform driver registration data.
Several conditions sit outside the modeled scope, including autonomous vehicle liability framework revisions, catastrophic cyber-physical infrastructure failures, and Financial Services Commission capital adequacy rule changes beyond current consultation drafts. Forecasts reflect assumptions regarding telematics data standard convergence and repair cost inflation stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Philippines Motor Insurance Market