
 United Kingdom Motor Insurance Market | 2026-2036
United Kingdom Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Motor Insurance Market Analytics
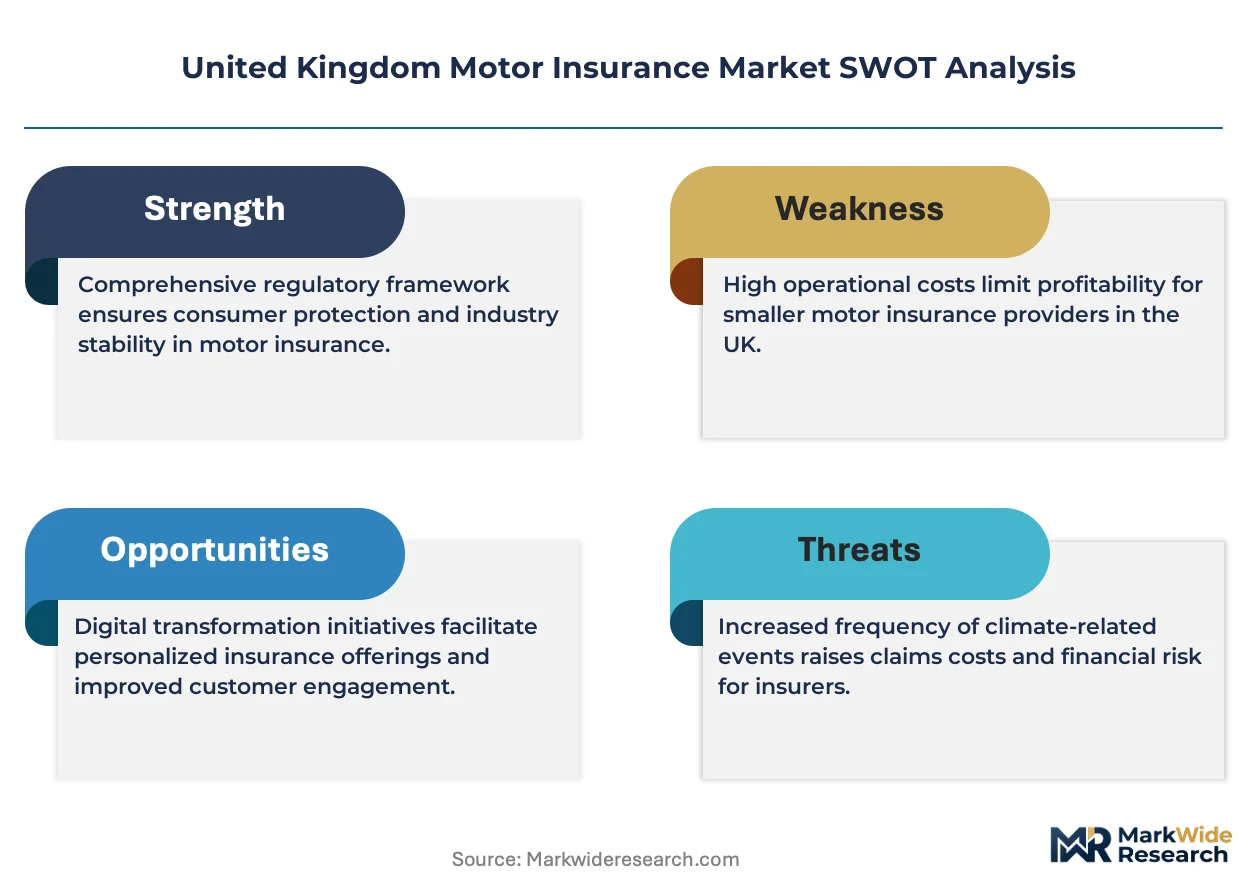
Greater London is narrowing its concentration of high-value motor insurance underwriting capacity relative to provincial UK markets. Admiral Group leverages direct-to-consumer digital distribution to sustain pricing agility across postcode-tiered risk pools. Aviva anchors its competitive position through integrated telematics data feeds from its in-house IoT infrastructure. NFU Mutual specializes in rural and agricultural vehicle segments where it dominates niche liability coverage outside standard metropolitan risk profiles.
United Kingdom motor insurance constitutes a contractual risk-transfer mechanism underwritten by regulated carriers, priced through actuarial models incorporating vehicle telemetry, driver behavior scoring, and geographic claims frequency data. Its primary commercial purpose is to indemnify policyholders against collision liability, theft, and third-party bodily injury while satisfying the Road Traffic Act's compulsory coverage mandate. Comprehensive coverage captures the dominant share of gross written premium as policyholders bundle own-damage protection with statutory third-party requirements. Monthly premium payment modes are displacing annual lump-sum structures among younger driver segments where cash-flow sensitivity shapes purchasing behavior. Pay-as-you-go telemetry-linked policies represent the fastest-growing premium payment mode as connected vehicle penetration deepens.
The Financial Conduct Authority's Consumer Duty framework and the Prudential Regulation Authority's solvency standards jointly constrain product design and capital allocation across UK motor carriers. The Association of British Insurers coordinates industry-wide responses to fraud detection protocols and claims settlement practices that the FCA audits for fair customer outcomes. Stakeholders must monitor how the UK government's automated vehicle legislation reshapes liability attribution between manufacturers, software providers, and traditional policyholders as conditional autonomy reaches commercial deployment.
Market Dynamics
The Financial Conduct Authority's Consumer Duty framework is compressing product design cycles while forcing carriers to reprice legacy policies around fair value benchmarks. This regulatory pressure intersects with connected vehicle data streams that enable real-time risk recalibration.
Growth Catalysts
- Telematics-enabled pricing models:Connected vehicle penetration allows granular driver behavior scoring that aligns premiums with actual risk exposure rather than proxy variables.
- The Road Traffic Act's compulsory coverage mandate:Statutory requirements ensure universal addressable market depth regardless of economic cyclicality.
- Fleet electrification:Commercial vehicle operators in Greater London and the South East corridor are expanding insured vehicle counts as zero-emission mandates tighten.
Market Restraints
- Prudential Regulation Authority solvency requirements:Capital reserve ratios constrain product experimentation and niche market entry by smaller carriers.
- Whiplash claims inflation:Soft tissue injury settlements drive loss ratio volatility that standard rate increases cannot fully offset.
- Repair cost escalation:Advanced driver assistance system sensors and electric vehicle battery packs inflate average claim severity beyond historical actuarial baselines.
Strategic Opportunities
- Pay-as-you-go distribution channels:Usage-linked policies capture younger driver segments abandoned by traditional annual premium structures.
- Rural agricultural vehicle specialization:Niche liability coverage outside metropolitan risk profiles commands pricing power through underwriting expertise scarcity.
- Automated vehicle legislation preparation:Product liability frameworks for conditional autonomy create first-mover advantage in manufacturer-policyholder boundary definition.
Industry Challenges
- Legacy core system modernization:Mainframe-dependent carriers face integration friction with real-time telemetry data feeds required for competitive pricing.
- Actuarial talent scarcity:Shortages in predictive modeling specialists delay telematics product deployment against faster-moving digital-native competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Motor Insurance Market |
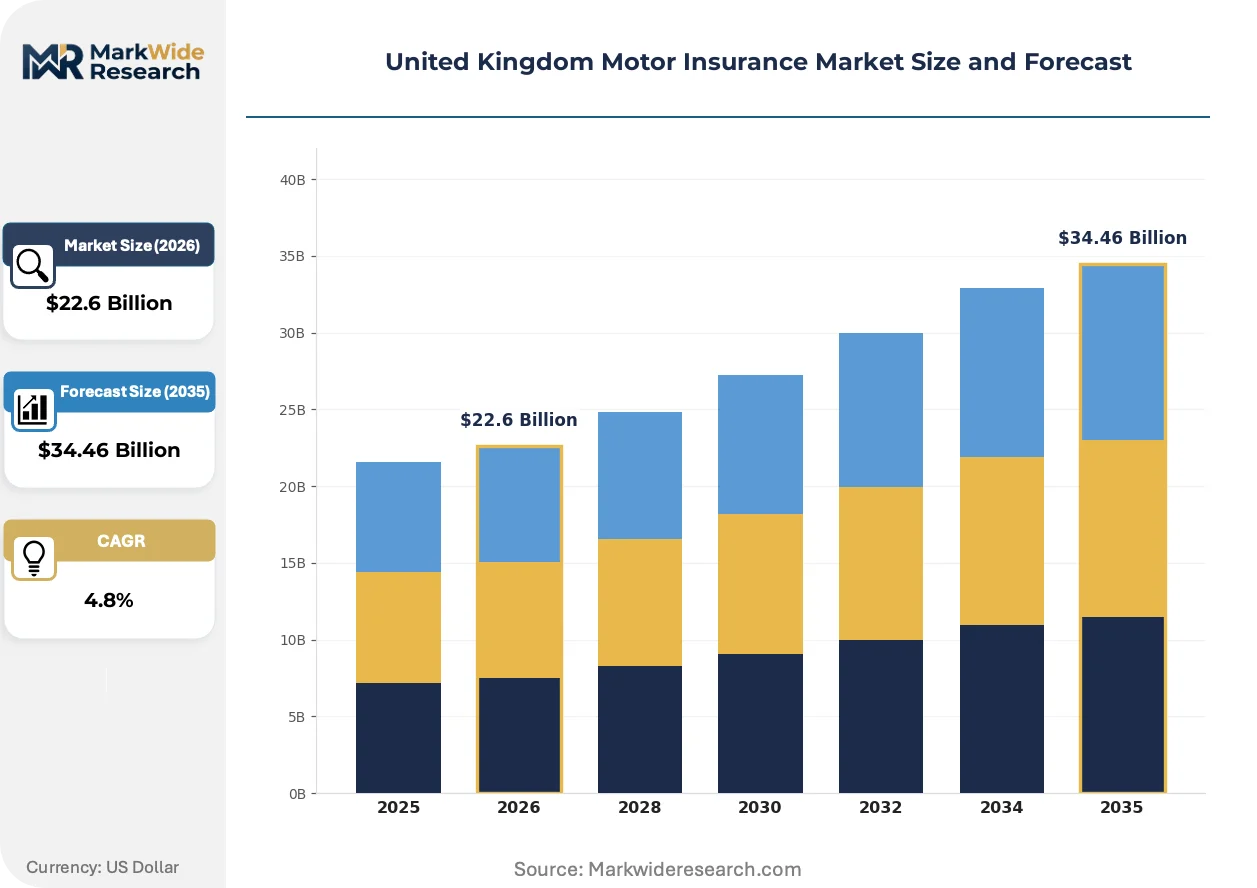
| Market Size in 2026 | $22.6 Billion |
| Market Size in 2035 | $34.46 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Comprehensive, Third Party, Third Party Fire & Theft, Short-Term Customer Segment: Private Individuals, Fleet Operators, Businesses, Young Drivers Premium Payment Mode: Monthly, Annually, Single Payment, Pay-As-You-Go Coverage Extent: Basic Coverage, Additional Coverage, Full Coverage, Custom Packages |
| Companies Covered | LV=, Ageas, Admiral Group, NFU Mutual, AXA, U K Insurance, Hastings, esure, Aviva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Motor Insurance Market Evolving Landscape
Connected vehicle architectures and regulatory transparency mandates are converging to compress traditional intermediation layers. Carriers must now embed compliance and data capabilities directly into policy lifecycle management.
Embedded telematics hardware is rendering obsolete the reliance on self-reported annual mileage and static demographic proxies for risk segmentation. Younger driver cohorts in Greater London are adopting smartphone-integrated monitoring apps at accelerating rates. This behavioral data capture is rendering obsolete the information asymmetry that once justified broad risk pooling across heterogeneous driver profiles.
The Financial Conduct Authority's Consumer Duty rules mandate demonstrable fair value in product design and claims outcomes. Underwriters must now document how premium levels correspond to expected claims costs and service quality. Motor carriers are responding by restructuring commission arrangements and enhancing policy documentation clarity, particularly for price comparison website-sourced customers.
Monthly premium payment modes are displacing annual lump-sum structures among cash-flow-sensitive younger segments. Digital-native distributors capture this demand through automated bank mandate setups that reduce friction. The South East corridor exhibits the highest concentration of this behavioral shift, correlating with higher vehicle density and premium price points.
United Kingdom Motor Insurance Market Segmentation
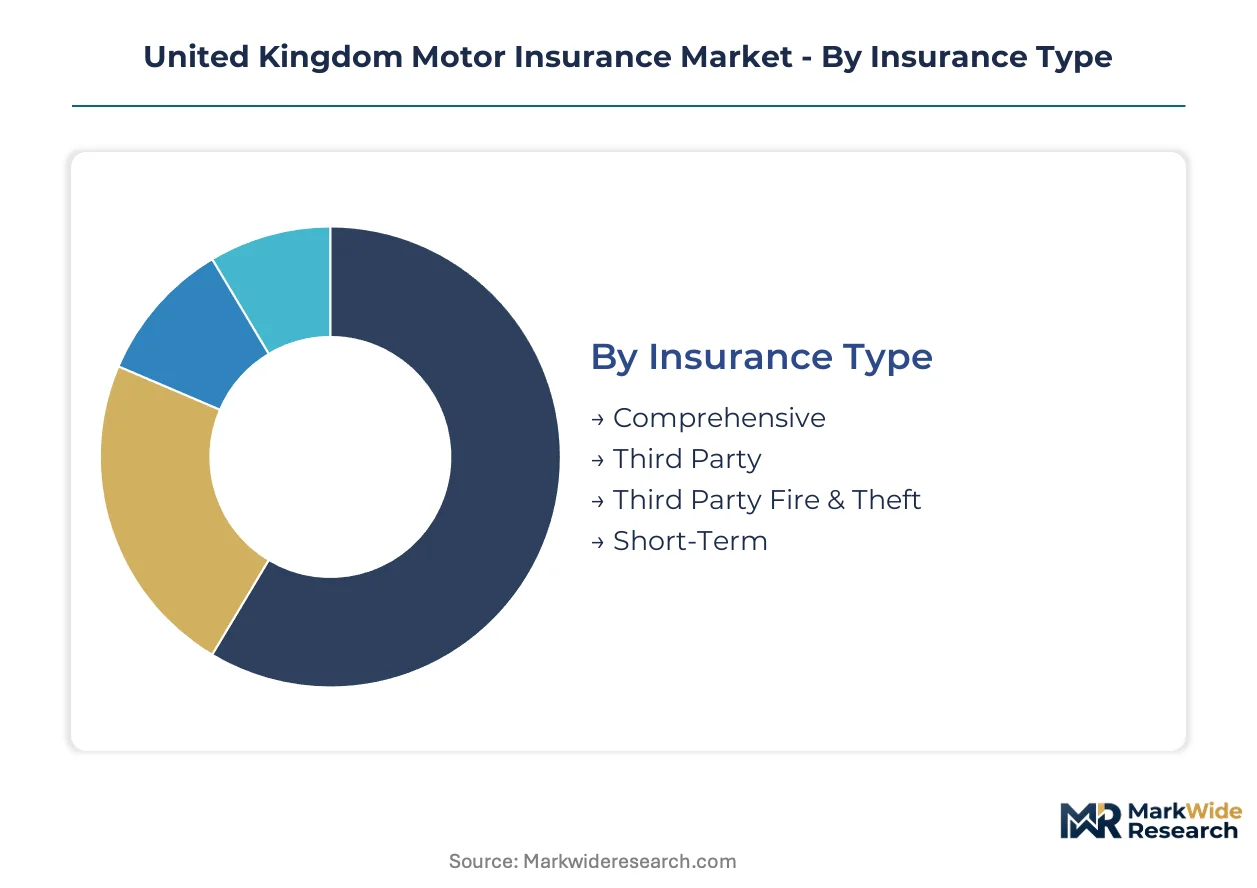
Motor insurance segmentation in the United Kingdom reflects divergent risk appetites across driver demographics and vehicle ownership structures. Granular categorization enables carriers to price policies against specific liability exposures rather than pooled averages. The Financial Conduct Authority's Consumer Duty rules now mandate that segmentation logic demonstrates fair value to each policyholder cohort.
Insurance Type:
Mature coverage forms dominate premium volumes while emerging variants capture behavioral shifts in vehicle usage patterns.
- Comprehensive:Bundles own-damage protection with statutory third-party liability under a single contract structure. Greater London and the South East corridor concentrate demand here as higher vehicle density elevates collision frequency and theft exposure. The Road Traffic Act's compulsory coverage mandate ensures baseline uptake, though comprehensive policies attract preference where asset values justify broader protection.
- Third Party:Satisfies minimum legal liability requirements without own-damage coverage. Young driver segments in provincial UK markets select this tier where premium affordability constrains purchasing decisions. Telematics-enabled pricing models are gradually displacing this segment as behavior-linked premiums narrow the cost gap with comprehensive alternatives.
- Third Party Fire & Theft:Extends statutory coverage to include vehicle loss through fire damage or criminal appropriation. Rural vehicle owners outside metropolitan risk pools favor this midpoint option where comprehensive pricing overreaches relative to asset depreciation schedules.
- Short-Term:Temporary coverage structures serve intermittent vehicle usage patterns including rental periods, vehicle sales transitions, and seasonal fleet scaling. Digital-native distributors capture this demand through automated policy issuance platforms.
Comprehensive handles the majority of throughput; Short-Term is the fastest mover on share.
Customer Segment:
Risk concentration varies sharply between individual policyholders and commercial vehicle operators with divergent claims frequency profiles.
- Private Individuals:Personal vehicle owners constitute the foundational addressable market under the Road Traffic Act's compulsory coverage mandate. Greater London exhibits the highest policy density per capita as urban vehicle ownership rates intersect with elevated premium pricing. Monthly premium payment modes are displacing annual lump-sum structures among cash-flow-sensitive younger segments in this cohort.
- Fleet Operators:Commercial vehicle aggregators manage pooled risk across multiple assets under master policy structures. Zero-emission mandates in Greater London and the South East corridor are expanding insured vehicle counts as operators electrify delivery and service van fleets. Telematics integration enables real-time driver behavior monitoring that supports experience-rated pricing adjustments.
- Businesses:Corporate entities insure director vehicles, commercial cars, and grey fleet arrangements where personal vehicles serve business purposes. Liability attribution complexity in mixed-use scenarios drives demand for specialized policy endorsements.
- Young Drivers:Provisional license holders and recent test passers face steep actuarial pricing due to statistically elevated collision frequency. Pay-as-you-go telemetry-linked policies represent the fastest-growing premium payment mode as smartphone-integrated monitoring apps reduce information asymmetry.
Private Individuals accounts for the largest premium pool; Young Drivers is expanding most quickly as telematics penetration deepens.
Premium Payment Mode:
Payment structure preferences segment along generational and cash-flow sensitivity lines rather than risk exposure differences.
- Monthly:Recurring bank mandate arrangements spread annual premium obligations across twelve installments. Younger driver segments in the South East corridor adopt this mode at accelerating rates where disposable income timing constraints shape purchasing behavior. Digital-native distributors reduce friction through automated setup workflows.
- Annually:Single upfront payment captures modest discounts from carriers avoiding administrative costs and default risk. Established policyholders with accumulated no-claims discounts favor this structure where premium levels justify lump-sum allocation.
- Single Payment:Identical to annual structures in functional terms, though sometimes distinguished for short-term policy contexts where coverage duration falls below twelve months.
- Pay-As-You-Go:Usage-linked premiums calibrate charges against actual mileage and driving behavior captured through embedded or smartphone-integrated telematics. Connected vehicle penetration enables this mode's steepest expansion trajectory among price comparison website customers seeking transparent cost-to-usage alignment.
Monthly handles the majority of new policy issuance; Pay-As-You-Go is climbing the fastest on adoption metrics.
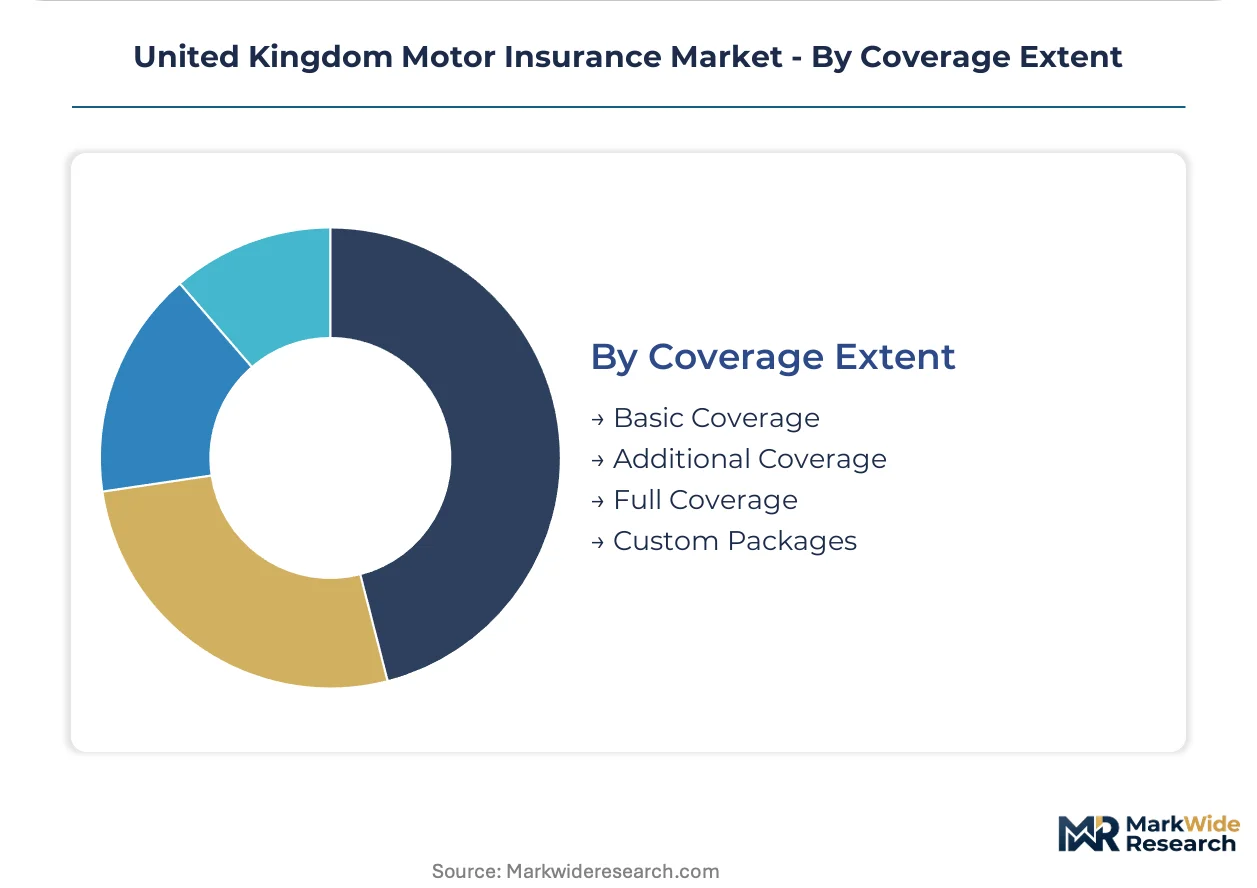
Coverage Extent:
Protection depth tiers align with asset value thresholds and policyholder risk tolerance rather than regulatory minimums.
- Basic Coverage:Satisfies statutory third-party liability requirements without supplemental protection. Cost-sensitive segments in provincial UK markets select this tier where vehicle replacement values fall below comprehensive premium justification thresholds.
- Additional Coverage:Modular endorsements extend base protection to include windscreen damage, personal accident benefits, or legal expense reimbursement. Fleet operators frequently bundle these additions to standardize protection across pooled vehicle assets.
- Full Coverage:Comprehensive protection encompassing own-damage, theft, fire, and third-party liability within unified policy structures. Higher-value vehicle owners in Greater London concentrate here as repair cost escalation for advanced driver assistance system sensors elevates exposure severity.
- Custom Packages:Bespoke policy constructions tailored to unusual vehicle categories, modified automobiles, or specialized commercial usage patterns. Agricultural vehicle segments outside standard metropolitan risk profiles command this tier where NFU Mutual and similar specialists dominate niche liability coverage.
Full Coverage dominates premium volume; Custom Packages is gaining share fastest as vehicle electrification diversifies risk profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Financial Conduct Authority anchors the United Kingdom's motor insurance landscape through its Consumer Duty framework, which mandates fair value documentation across all policy tiers. Greater London and the South East corridor concentrate the highest premium density, while provincial markets exhibit divergent risk profiles and pricing structures.
Greater London
Zero-emission mandates for commercial fleets and elevated vehicle density drive underwriting capacity concentration here. The Ultra Low Emission Zone expansion tightens compliance requirements for diesel and petrol vehicles. Fleet operators in Canary Wharf and the City electrify delivery van assets, expanding insured vehicle counts under master policy structures.
South East Corridor
Commuter belt expansion and high-value vehicle ownership elevate comprehensive coverage penetration. Thames Valley technology clusters generate above-average disposable income that supports premium policy selection. Connected vehicle adoption accelerates fastest here among younger driver cohorts using smartphone-integrated telematics.
Midlands
Automotive manufacturing heritage sustains commercial motor insurance demand across logistics and parts distribution networks. Birmingham's freight hub status generates fleet operator concentration requiring specialized liability endorsements. Telematics-enabled pricing models gain traction among younger drivers in Coventry and Leicester urban centers.
North England
Post-industrial urban centers exhibit higher claims frequency that compresses carrier margins and elevates base premiums. Manchester and Liverpool postcodes face actuarial pricing adjustments reflecting theft and collision exposure. Cost-sensitive segments here favor third-party coverage tiers where telematics products narrow the gap with comprehensive alternatives.
Scotland
Rural vehicle ownership patterns and agricultural commercial usage sustain demand for custom liability packages. Edinburgh and Glasgow concentrate private motor policy density while Highland regions command specialist underwriting expertise. NFU Mutual and comparable rural specialists dominate niche coverage outside metropolitan risk pools here.
United Kingdom Motor Insurance Market Competitive Landscape
Direct-to-consumer digital distributors and integrated multi-line incumbents split the market between pricing agility and capital depth. The carrier base concentrates around five to eight dominant underwriters with meaningful scale, while smaller mutuals and niche specialists occupy protected rural segments. Two strategic archetypes predominate: technology-enabled direct writers leveraging real-time data feeds, and established composite insurers with captive telematics infrastructure. Competitive moves center on embedded telematics partnerships and pay-as-you-go product launches that capture younger driver segments.
Within the direct-to-consumer tier, Admiral Group exemplifies pricing agility through postcode-tiered risk pools and automated distribution workflows. Aviva anchors the integrated incumbent position through in-house IoT infrastructure that feeds granular behavior data into actuarial models. NFU Mutual occupies the rural specialist archetype, commanding pricing power in agricultural vehicle segments where underwriting expertise scarcity protects margins.
| Leading Market Players |
|---|
| LV= |
| Ageas |
| Admiral Group |
| NFU Mutual |
| AXA |
| U K Insurance |
| Hastings |
| esure |
| Aviva |
| Others |
Value Network & Pricing Analysis
Greater London's underwriting capacity concentration generates pricing power asymmetries that cascade through UK motor insurance markets. Carriers domiciled in the capital leverage proximity to Fleet Street reinsurance markets and the Financial Conduct Authority's regulatory orbit to recalibrate premium structures faster than provincial competitors.
Pricing Analysis
Geographic price spreads between Greater London and North England postcodes exceed threefold multiples for equivalent comprehensive coverage tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by telematics integration depth and no-claims discount accumulation. Pricing pressure stems from repair cost escalation for electric vehicle battery packs and ADAS sensor arrays. Young driver segments exhibit highest price sensitivity, while fleet operators demonstrate lowest elasticity due to statutory coverage mandates.
Supply Chain Analysis
Claims fulfillment capacity concentrates among national repair networks anchored in Birmingham, Manchester, and Glasgow hubs. Raw material dependencies span automotive glass from Pilkington's St Helens facility, OEM parts from German and Japanese component suppliers, and lithium-ion cells from South Korean manufacturers. Single-source vulnerability characterizes electric vehicle specialist repair certification, where manufacturer-controlled training gates limit third-party capacity. Distribution runs through price comparison website aggregators that capture seventy percent of new policy origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward digitally-empowered younger segments as price comparison website aggregation fragments carrier pricing opacity. This fragmentation compresses incumbent margin structures while rewarding agile direct-to-consumer distributors.
For Market Incumbents: Entrench telematics data moats through proprietary IoT infrastructure investments that newcomer carriers cannot replicate without capital-intensive buildouts. Consolidate claims fulfillment relationships with certified electric vehicle repair networks before manufacturer-controlled training gates harden. The Prudential Regulation Authority's solvency requirements threaten smaller carriers with capital starvation, creating acquisition opportunities for well-capitalized composites. For New Entrants and Emerging Players: Establish a beachhead in pay-as-you-go telemetry-linked policies where behavioral data asymmetry still permits underwriting margin recovery. Rural agricultural vehicle segments outside metropolitan risk profiles offer white-space penetration with limited incumbent digital investment. Partner with smartphone-integrated monitoring app developers to bypass embedded hardware cost barriers that constrain legacy carriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because carrier fragmentation below the top eight underwriters generates persistent inefficiency against regulatory compliance scale requirements. Target mutual insurers with captive rural membership bases and unexploited telematics infrastructure. Watch automated vehicle legislation progression as the signal indicating when manufacturer-policyholder liability boundary disputes will trigger product redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Investment | Proprietary IoT data feeds enable real-time risk recalibration against Admiral Group's direct-to-consumer pricing agility. |
| Electric Vehicle Repair Certification | Manufacturer-controlled training gates limit third-party claims fulfillment capacity as zero-emission mandates tighten across Greater London. |
| Pay-As-You-Go Product Launch | Usage-linked policies capture younger driver segments abandoned by traditional annual premium structures in the South East corridor. |
| Rural Specialist Acquisition | NFU Mutual's agricultural vehicle dominance demonstrates pricing power through underwriting expertise scarcity outside metropolitan pools. |
| Consumer Duty Compliance Automation | Fair value documentation mandates from the Financial Conduct Authority favor carriers with embedded policy lifecycle management systems. |
Research Methodology
Cross-validation between Association of British Insurers statistical returns and Prudential Regulation Authority solvency disclosures anchors the qualitative findings. Primary interviews with motor carrier underwriting directors, telematics platform engineers, price comparison website product managers, and Financial Conduct Authority policy supervisors combined with secondary validation from regulatory filings, vehicle registration databases, and claims cost indices. Bottom-up policy volume triangulation against top-down premium pool estimates ensures segmentation integrity.
Calibration against historical loss ratio trajectories and telematics penetration curves shaped the projection framework across the analysis window. Segmentation dimensions modeled include insurance type tier, customer segment archetype, premium payment mode preference, and geographic risk pool clustering. CAGRs derived from actuarial frequency-severity assumptions incorporating connected vehicle adoption curves and repair cost inflation indices. Electric vehicle fleet conversion timelines and automated vehicle liability framework development served as industry-specific forecast inputs.
Stress conditions across whiplash claims inflation, electric vehicle repair cost escalation, and automated vehicle liability attribution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption curves. Quarterly review of telematics penetration rates, Consumer Duty enforcement patterns, and zero-emission mandate compliance timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Philippines Motor Insurance Market