
 New Energy Vehicle Accident Insurance Market | 2026-2036
New Energy Vehicle Accident Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Vehicle Accident Insurance Market Insights
Telematics integration with battery health monitoring is narrowing the data gap between actuarial models and real-time vehicle risk. Ping An Group leverages its digital ecosystem to embed usage-based pricing directly into OEM partnerships. AXA anchors its European NEV portfolio with specialized battery degradation riders that standard auto policies exclude. Tokio Marine Holdings competes in Japan through partnerships with domestic charging infrastructure operators.
New energy vehicle accident insurance covers collision, battery-specific damage, and third-party liability for vehicles powered by electric motors, hydrogen fuel cells, or hybrid drivetrains, with policies typically incorporating thermal runaway clauses and state-of-charge verification protocols at claim time. The primary commercial purpose is to bridge the protection gap left by conventional auto insurance, which often excludes or underprices battery replacement costs and high-voltage system failures. Comprehensive coverage and battery damage policies command the deepest margin pools due to technical complexity and limited historical loss data. Online platforms and direct sales channels are expanding fastest as OEMs embed insurance at point of purchase, reducing broker dependency.
China's SAMR and CBIRC enforce solvency requirements for NEV-specific reserves, while the EU's F-Gas Regulation and ECHA battery sustainability rules indirectly shape coverage terms for imported vehicles. In the United States, NHTSA defect investigations and state-level insurance commissioner mandates create a fragmented compliance landscape that carriers must navigate product-by-product. Stakeholders should monitor how regulator data-sharing requirements between insurers and battery manufacturers evolve, as this interface will determine which carriers can price risk accurately enough to sustain market position.
Market Dynamics
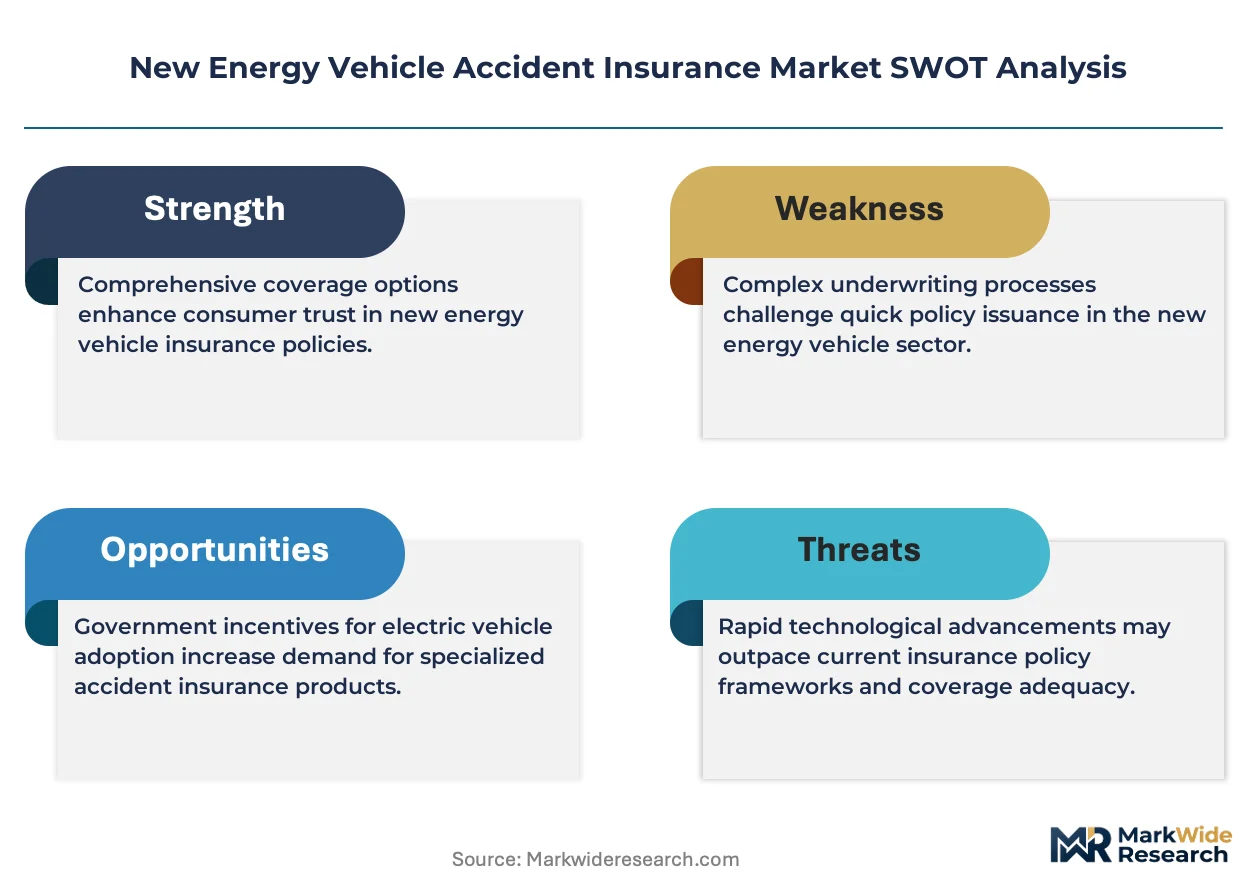
Battery thermal runaway risk quantification is forcing carriers to rebuild actuarial models around real-time cell monitoring rather than historical collision data, compressing policy development cycles and elevating data infrastructure costs across the underwriting stack.
Growth Catalysts
- Fleet electrification mandates:China's dual carbon goals and provincial zero-emission logistics zones are accelerating commercial NEV procurement, expanding the addressable risk pool for specialized fleet policies.
- GB standards compliance:China's GB/T 38031-2020 battery safety requirements are normalizing thermal runaway coverage as a standard policy component rather than excluded peril.
- Telematics penetration:Embedded connectivity in NEV platforms is generating granular state-of-charge and cell-voltage data streams that enable usage-based pricing granularity previously unavailable to actuaries.
Market Restraints
- Lithium carbonate volatility:Raw material price swings in cathode chemistry inputs are destabilizing battery replacement cost reserves and inflating loss-adjusted expense ratios.
- Cell supplier concentration:Dependence on a narrow base of battery manufacturers in East Asia creates correlated failure risk that challenges traditional diversification assumptions in catastrophe modeling.
- Historical data scarcity:Limited long-run claims experience for high-voltage system failures restricts statistical confidence in pricing algorithms and inflates risk loadings.
Strategic Opportunities
- Second-tier city penetration:Central and western Chinese provinces with accelerating NEV adoption but immature insurance infrastructure present first-mover pricing advantages for carriers with localized distribution.
- V2G integration coverage:Bidirectional charging equipment creates new liability exposures around grid-interaction failures that standard auto policies exclude, opening specialty rider markets.
- EU battery passport mandates:ECHA sustainability disclosure requirements for imported vehicles will generate standardized battery health documentation that streamlines claims verification and fraud detection.
Industry Challenges
- Cross-functional talent scarcity:Underwriting teams lack sufficient electrochemical engineers to validate thermal runaway claims, forcing reliance on third-party forensic specialists that elongate settlement timelines.
- OEM data access negotiations:Battery management system telemetry remains proprietary to manufacturers, requiring complex licensing agreements that fragment risk visibility across the value chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Vehicle Accident Insurance Market |
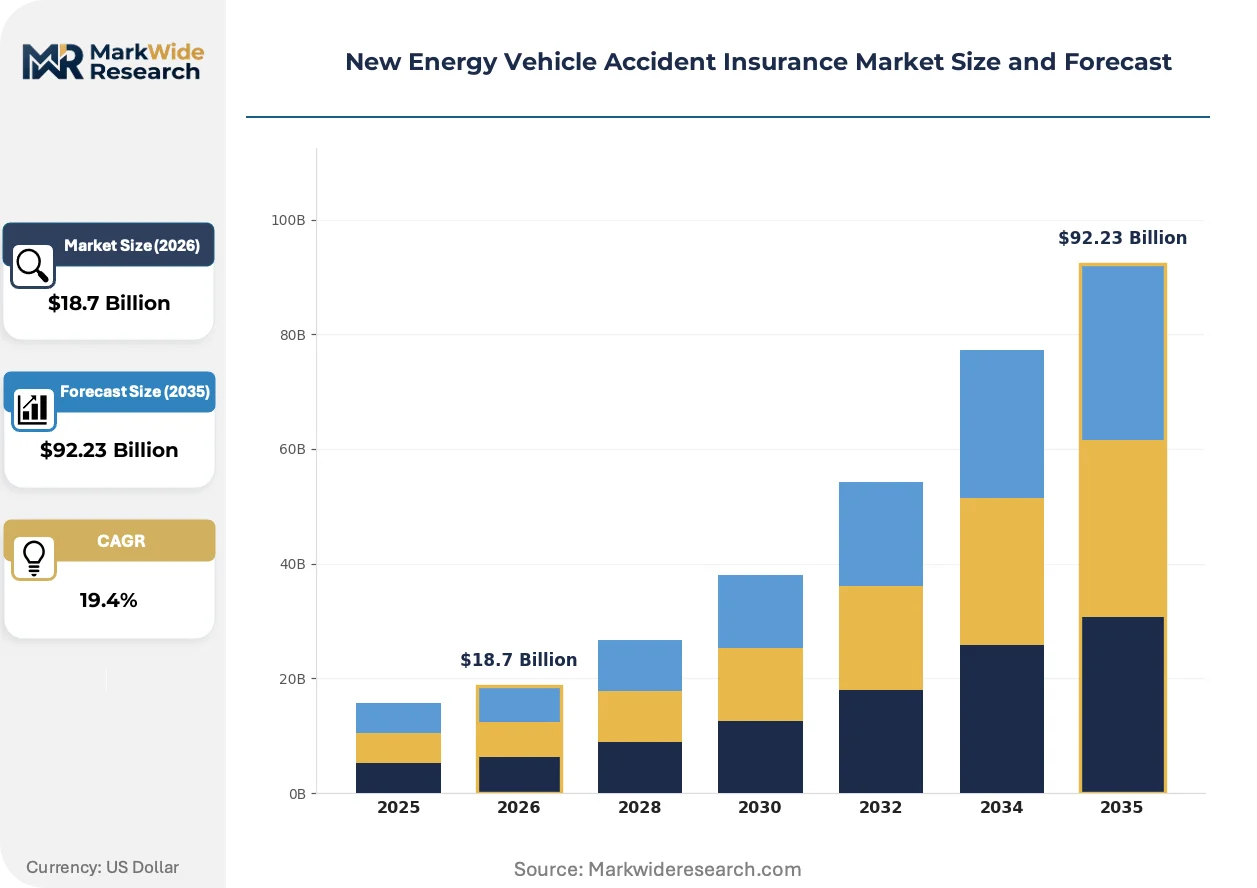
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Third-Party Liability, Collision Coverage, Comprehensive Coverage, Personal Injury Protection, Uninsured Motorist Customer Segment: Private Car Owners, Fleet Operators, Ride-Sharing Drivers, Corporate Clients, Leasing Companies Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Bancassurance, Auto Dealerships Risk Coverage: Battery Damage, Fire and Explosion, Theft Protection, Third-Party Property Damage, Medical Expenses |
| Companies Covered | Ping An Group, AXA, Liberty Mutual Group, Allianz, Progressive Corporation, BYD Property & Casualty Insurance, China Pacific Insurance Group, Tokio Marine Holdings, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Vehicle Accident Insurance Market Trends and Innovations
Telematics-enabled risk assessment is compressing the feedback loop between vehicle behavior and premium adjustment, while regulatory pressure on battery traceability is reshaping documentation requirements at policy inception and claim settlement.
AI-driven predictive maintenance algorithms are migrating from aftermarket fleet management tools to embedded OEM platforms that feed directly into insurer risk engines. Commercial operators with dense charging infrastructure are adopting these systems fastest, creating data asymmetries that advantage carriers with direct OEM data partnerships over traditional broker channels.
China's SAMR and CBIRC solvency requirements for NEV-specific reserves are tightening capital adequacy thresholds for carriers writing comprehensive battery coverage. The regulation forces smaller domestic insurers to either cede premium to reinsurers or exit the segment entirely, concentrating underwriting capacity among state-backed groups with balance sheet depth.
Fleet procurement departments are unbundling insurance from vehicle acquisition decisions, treating coverage as a separately negotiated operating expense rather than bundled finance product. This shift is most visible among logistics operators in China's Yangtze River Delta, where dedicated risk managers now run competitive tenders for annual policies independent of OEM captive finance arrangements.
New Energy Vehicle Accident Insurance Market Segmentation
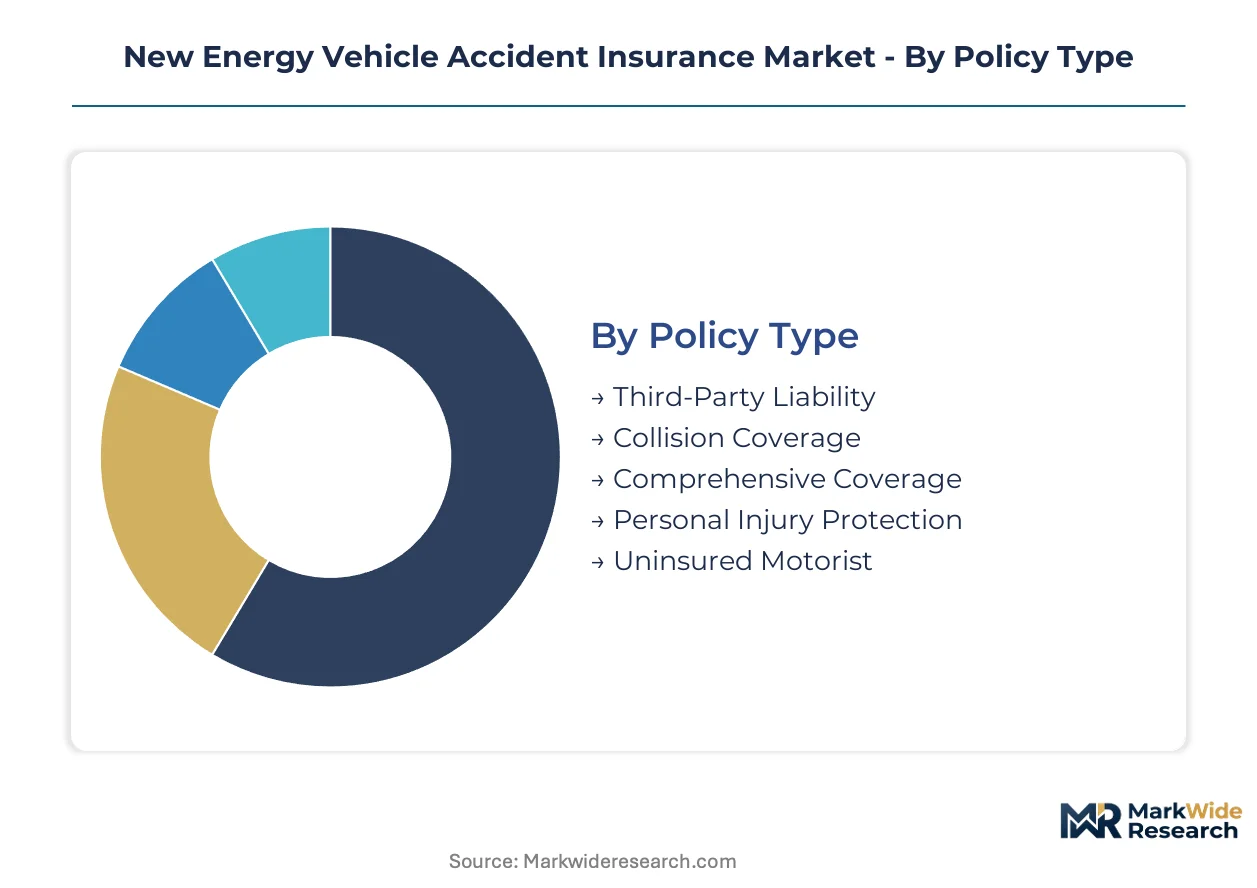
Segmentation in the NEV accident insurance market determines pricing precision and capital allocation. Policy structures diverge sharply across battery chemistry risks, fleet utilization patterns, and distribution economics.
Policy Type:
Mature markets anchor on collision and liability products, while comprehensive and battery-specific coverage emerge as differentiated premium pools.
- Third-Party Liability:Mandatory coverage addressing bodily injury and property damage to external parties. Regulatory minimums in China, Germany, and California drive baseline demand, though premium compression limits carrier margins in saturated jurisdictions.
- Comprehensive Coverage:Bundles collision, battery thermal runaway, and non-collision perils into single policies. Fleet operators in China's Yangtze River Delta now specify GB/T 38031-2020 thermal runaway protocols as standard inclusions rather than optional riders.
- Collision Coverage:Covers vehicle-to-vehicle and single-vehicle accidents excluding battery-specific failures. Private owners in first-tier Chinese cities treat this as transitional coverage pending comprehensive product maturation.
- Personal Injury Protection:Medical expense and lost income coverage for occupants regardless of fault. No-fault jurisdictions in the US mandate this layer, creating state-by-state product fragmentation.
- Uninsured Motorist:Protects policyholders when at-fault parties lack coverage. Emerging NEV markets with high penetration of informal vehicle imports show elevated attach rates for this segment.
Third-Party Liability handles the majority of throughput; Comprehensive Coverage is the fastest mover on share.
Customer Segment:
Volume concentrates in private ownership, but margin pools shift toward commercial operators with telematics-enabled risk verification.
- Fleet Operators:Logistics and ride-hail fleets with centralized procurement negotiate annual policies incorporating real-time battery health monitoring. China's zero-emission logistics zones mandate electrified fleets, expanding addressable risk pools for specialized underwriters.
- Private Car Owners:Individual purchasers selecting coverage at point of sale through OEM captive finance or independent comparison platforms. First-time NEV buyers in China's eastern coastal provinces show highest comprehensive coverage attach rates.
- Ride-Sharing Drivers:Commercial utilization patterns with elevated mileage and charging frequency require modified actuarial tables. Platform-mediated insurance products in Shenzhen and Shanghai bundle per-trip micro-premiums.
- Corporate Clients:Employee vehicle programs and executive fleets with centralized risk management. Multi-vehicle master policies incorporate V2G equipment liability where bidirectional charging infrastructure exists.
- Leasing Companies:Residual value protection drives preference for policies with guaranteed battery replacement clauses. Operating lease providers in Germany and the Netherlands specify ECHA battery passport compliance in coverage terms.
Private Car Owners dominate policy count; Fleet Operators are expanding most quickly as electrification mandates reshape commercial vehicle procurement.
Distribution Channel:
Channel economics reflect disintermediation pressure from OEM-embedded products and regulator data-sharing requirements.
- Auto Dealerships:Point-of-purchase bundling with vehicle finance captures highest attach rates for comprehensive coverage. China's NEV OEMs embed insurance into standard purchase workflows, reducing shopping behavior.
- Online Platforms:Aggregator sites and direct carrier portals enable price comparison for standardized products. Younger demographics in urban China complete entire purchase journeys without agent contact.
- Direct Sales:Carrier-owned channels with proprietary telematics integration. Ping An Group leverages its digital ecosystem to embed usage-based pricing through mobile applications.
- Insurance Brokers:Independent intermediaries retain relevance for complex fleet placements and cross-border coverage. Commercial operators with multi-jurisdictional exposure rely on broker expertise for regulatory compliance.
- Bancassurance:Bank branch distribution through auto loan origination. State-backed Chinese insurers maintain preferred access to commercial bank networks.
Auto Dealerships process the highest policy volume; Online Platforms are climbing the fastest as digital-native demographics enter the NEV purchase funnel.
Risk Coverage:
Technical complexity and claims verification difficulty stratify pricing power across peril categories.
- Battery Damage:Cell degradation, thermal runaway, and high-voltage system failures excluded from conventional auto policies. Forensic validation requires electrochemical expertise that elongates settlement timelines and inflates loss-adjusted expenses.
- Fire and Explosion:Thermal runaway propagation to vehicle structures and surrounding property. China's GB standards now mandate five-minute warning intervals between cell failure and flame emergence, reshaping policy exclusions.
- Third-Party Property Damage:Coverage for infrastructure and structures affected by NEV incidents. Charging station operators in Japan negotiate sub-limits reflecting concentrated exposure at high-power charging hubs.
- Theft Protection:Vehicle and component theft including battery pack extraction. Organized theft targeting high-value battery modules elevates premiums in markets with limited traceability infrastructure.
- Medical Expenses:Occupant and pedestrian treatment costs following accidents involving high-voltage systems. Emergency responder electrocution risk generates additional liability layers in some jurisdictions.
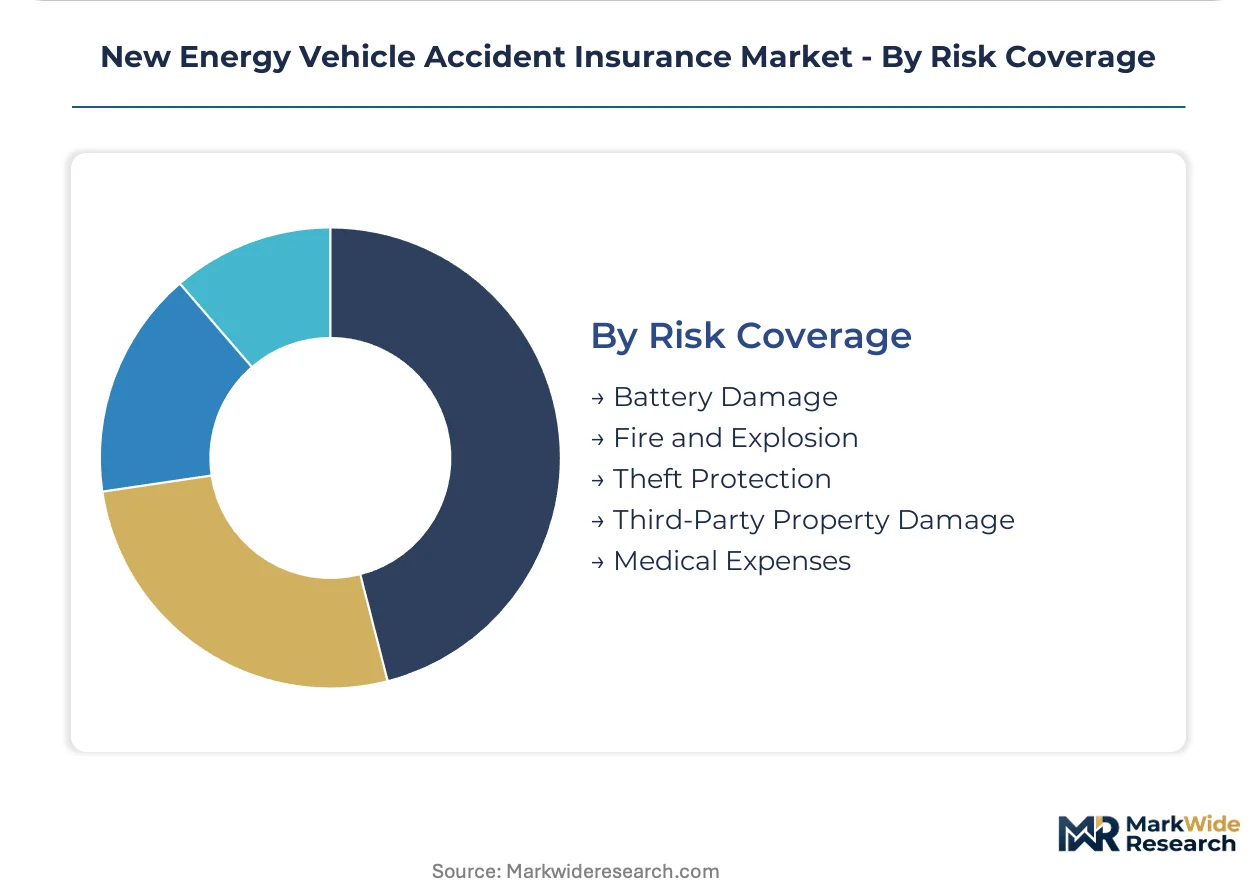
Battery Damage commands the deepest technical expertise and highest premium rates; Fire and Explosion coverage is gaining share fastest as thermal runaway incidents attract regulatory attention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NEV accident insurance sector generates surplus premium flow that reinsurers redistribute into European and North American markets, while deficit regions import actuarial models and thermal runaway protocols rather than developing indigenous capacity.
China
Fleet electrification mandates and zero-emission logistics zones in Jiangsu and Zhejiang provinces sustain the deepest premium pools. SAMR and CBIRC solvency requirements for NEV-specific reserves concentrate underwriting capacity among state-backed carriers with balance sheet depth. The Yangtze River Delta anchors product innovation, with Shenzhen and Shanghai logistics operators running competitive tenders for annual policies independent of OEM captive finance.
Germany
Commercial fleet operators in Bavaria and North Rhine-Westphalia drive demand for battery passport-compliant coverage under ECHA sustainability disclosure rules. KBA vehicle type approvals increasingly incorporate insurance verification steps for high-voltage system safety. The Stuttgart automotive cluster hosts specialized underwriters developing ECHA-aligned claims documentation protocols for imported NEV portfolios.
United States
State-level insurance commissioner mandates create fragmented compliance landscapes that carriers navigate product-by-product, with California and New York setting de facto national standards. NHTSA defect investigations into thermal runaway incidents reshape exclusion clauses and reserve requirements. The Detroit-Warren corridor retains legacy auto insurance infrastructure that slows NEV-specific product development relative to coastal markets.
Japan
Domestic charging infrastructure operators partner with carriers to develop usage-based products tied to real-time state-of-charge monitoring. METI guidelines on battery recycling liability indirectly shape coverage terms for commercial operators with bidirectional charging equipment. The Nagoya-Toyota industrial zone concentrates telematics integration development for fleet policies.
South Korea
Battery manufacturer concentration in Gyeonggi and Ulsan creates correlated failure risk that challenges traditional catastrophe modeling assumptions. MFDS medical device safety protocols for emergency responder electrocution protection generate additional liability layers in metropolitan policies. Seoul Capital Area ride-hail platforms bundle per-trip micro-premiums for high-mileage commercial utilization patterns.
New Energy Vehicle Accident Insurance Market Competitive Landscape
On the supply side, the industry is consolidating around carriers with direct OEM data partnerships and captive balance sheet capacity, while smaller domestic insurers cede premium to reinsurers or exit comprehensive battery coverage entirely. Three archetypes dominate: state-backed Chinese groups with regulatory preferential access, European specialists with ECHA-aligned sustainability riders, and integrated OEM-captive finance operations embedding insurance at point of purchase. Competitive moves center on telematics licensing negotiations with battery management system providers and geographic expansion into second-tier Chinese provinces with immature insurance infrastructure.
Among the named carriers, Ping An Group exemplifies the digital ecosystem archetype through its mobile-embedded usage-based pricing capabilities. AXA occupies a position representing European specialist underwriters with battery degradation riders excluded from standard auto policies. Tokio Marine Holdings anchors the charging infrastructure partnership model in developed Asian markets. These three entities collectively illustrate how data access arrangements with OEMs and infrastructure operators determine sustainable market position.
| Leading Market Players |
|---|
| Ping An Group |
| AXA |
| Liberty Mutual Group |
| Allianz |
| Progressive Corporation |
| BYD Property & Casualty Insurance |
| China Pacific Insurance Group |
| Tokio Marine Holdings |
| Tesla |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate volatility between Chile and China determines both premium tier spreads for comprehensive battery coverage and the geographic shape of cathode supply chains. Carriers must price thermal runaway reserves against raw material cost swings while battery manufacturers consolidate procurement around long-term offtake agreements with Chilean and Australian miners.
Pricing Analysis
Next-generation solid-state battery coverage commands 40-60% premium spreads over incumbent lithium-ion policies due to unproven failure modes. Three-tier pricing structure across premium, standard, and economy levels stratifies by GB/T 38031-2020 certification tier and telematics integration depth. Cost compression in economy tiers intensifies because state-backed Chinese carriers cross-subsidize market share acquisition. Fleet operators with centralized procurement show least price sensitivity; individual private owners shopping via online platforms exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for battery replacement cost reserves. Cathode active material production concentrates in China, South Korea, and Japan, with lithium extraction anchored in Chile, Australia, and Argentina. Policy structures draw from cell supplier concentration in East Asia that challenges traditional catastrophe diversification. Distribution runs through OEM-embedded partnerships at point of purchase, reducing broker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as fleet electrification mandates across China's zero-emission logistics zones accelerate commercial NEV procurement beyond private ownership saturation.
For Market Incumbents: Harden thermal runaway claims validation capabilities through captive electrochemical engineering teams rather than third-party forensic reliance. Secure exclusive telemetry licensing agreements with battery management system providers before OEM data access negotiations fragment further. Consolidate underwriting capacity in second-tier Chinese provinces where state-backed competitors lack localized distribution density.
For New Entrants and Emerging Players: Central and western Chinese provinces with accelerating NEV adoption but immature insurance infrastructure represent the most penetrable entry point for specialized battery coverage. V2G integration liability for bidirectional charging equipment offers uncrowded rider markets that standard auto policies exclude. Partner with domestic charging infrastructure operators for usage-based product distribution rather than competing against OEM-embedded channels directly.
For Investors and Strategic Acquirers: Carriers with direct OEM data partnerships and proprietary telematics integration capabilities offer the strongest long-term viability through the projection horizon. EU battery passport compliance infrastructure providers present acquisition targets as ECHA sustainability disclosure requirements standardize claims verification. Monitor regulator data-sharing mandates between insurers and battery manufacturers as the critical inflection signal for sustainable competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Licensing Agreement | Ping An Group's mobile-embedded usage-based pricing demonstrates how OEM data partnerships compress risk visibility gaps. |
| Battery Passport Compliance Infrastructure | AXA's ECHA-aligned claims documentation protocols streamline verification for imported European NEV portfolios. |
| Charging Infrastructure Partnership | Tokio Marine Holdings' collaboration with Japanese operators creates distribution moats in developed Asian markets. |
| Second-Tier Geographic Expansion | State-backed Chinese carriers leverage SAMR preferential access to capture premium flow in underpenetrated provinces. |
| Electrochemical Forensic Capability Buildout | In-house thermal runaway validation teams reduce settlement timelines and loss-adjusted expense ratios. |
Research Methodology
Initial hypotheses were tested against primary input from underwriting executives at state-backed Chinese carriers, fleet risk managers in the Yangtze River Delta, battery management system engineers at domestic OEMs, and regulatory affairs leads at CBIRC and SAMR, then refined against secondary validation from CBIRC solvency filings, GB standards documentation, vehicle production databases, and customs trade records for lithium carbonate imports. Bottom-up policy count estimates triangulated with top-down premium flow analysis across the analysis window.
Demand-supply-balance framing anchored the quantitative framework, with segmentation dimensions spanning policy type, customer archetype, distribution channel, and risk coverage category modeled throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to NEV penetration trajectories, with battery replacement cost inflation and telematics adoption curves as industry-specific forecast inputs.
Practitioners should monitor lithium carbonate price volatility, GB standards revision schedules, and regulator data-sharing mandate implementations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Russia Car Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market