
 US Motor Insurance Market | 2026-2036
US Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Motor Insurance Market Analytics
Texas is reshaping competitive dynamics in US motor insurance through its expanding urban corridors and energy-sector fleet growth. Progressive leverages telematics infrastructure to price risk at the individual trip level. State Farm anchors its position through captive agency networks that control distribution in suburban and rural counties. GEICO competes on direct-to-consumer digital acquisition, sustaining low expense ratios relative to traditional channel models.
US motor insurance constitutes a contractual risk-transfer mechanism where insurers pool premiums from policyholders to indemnify against collision, liability, and comprehensive losses tied to vehicle operation. Pricing relies on actuarial modeling of frequency and severity, with modern platforms incorporating real-time driving telemetry, credit-based insurance scores, and geographic catastrophe exposure. Liability coverage dominates premium volume due to state-mandated minimum requirements, while comprehensive coverage captures growing share as vehicle replacement costs rise and climate-related peril severity intensifies. The rideshare customer segment expands fastest, though commercial fleet policies retain the deepest margin pools due to multi-vehicle pricing power and loss-control engineering services.
NHTSA crash-test protocols and state department of insurance rate filings shape product design and pricing transparency across the US. The SEC oversees insurer investment portfolios, constraining capital deployment into risk assets that backstop claim reserves. State Farm and Progressive must navigate this dual regulatory architecture while monitoring autonomous vehicle liability allocation, usage-based insurance regulatory approvals, and climate-stress testing requirements that will determine capital adequacy and product availability.
Market Dynamics
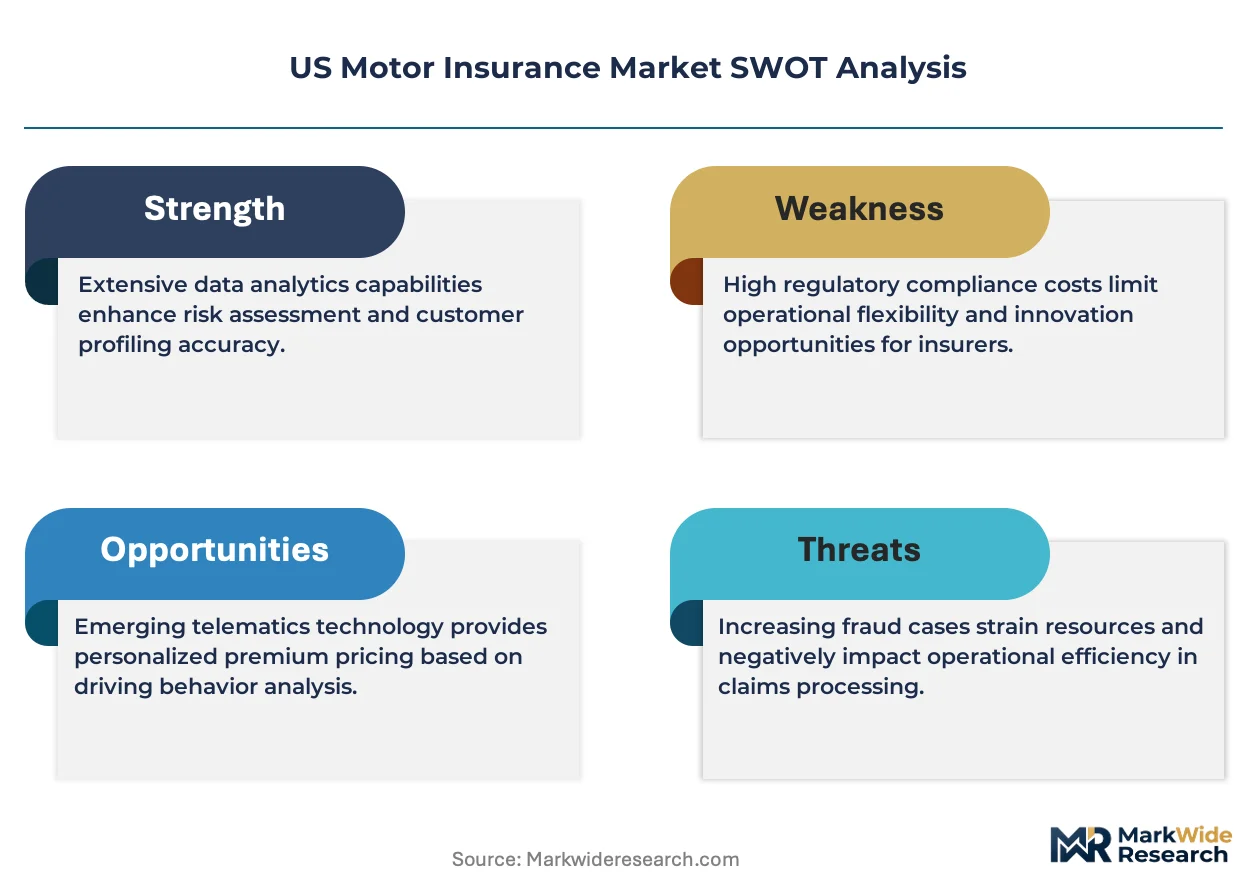
Telematics-enabled usage-based pricing is compressing traditional risk-pooling models as real-time driving data supplants retrospective actuarial tables in rate-setting workflows.
Growth Catalysts
- NHTSA Advanced Driver-Assistance System Mandates:Federal safety requirements for automatic emergency braking and lane-keeping assistance are expanding insurable vehicle populations and creating new coverage categories for semi-autonomous systems.
- Commercial Fleet Electrification:Corporate sustainability commitments are accelerating battery-electric vehicle adoption among delivery and logistics operators, generating demand for specialized coverage addressing thermal runaway risks and charging infrastructure liability.
- Climate-Peril Intensification:Hailstorm and flood severity in the Gulf Coast and Great Plains regions is driving comprehensive coverage attachment rates among previously minimum-coverage policyholders.
Market Restraints
- Vehicle Repair Cost Inflation:Semiconductor shortages and aluminum body panel complexity have elevated average collision severity, compressing combined ratios for physical damage coverage lines.
- Reinsurance Capacity Contraction:Catastrophe bond spreads and collateral requirements from Bermuda and London markets are raising cost-of-capital for primary carriers writing wind and flood exposure.
- Data Privacy Fragmentation:The California Consumer Privacy Act and pending state biometric laws are creating compliance friction for telematics data collection and cross-state pricing model deployment.
Strategic Opportunities
- Embedded Insurance Distribution:Point-of-sale coverage integration with automotive OEM financing platforms and dealership management systems is capturing first-policy relationships before traditional agent contact.
- Autonomous Vehicle Liability Reallocation:Product liability migration from driver negligence to manufacturer defect claims is opening specialty lines for technology E&O and cyber-physical system failures.
- Rideshare Gap Coverage Standardization:Period 1 and Period 2 liability arbitrage between personal auto and TNC commercial policies presents white-space products for hybrid usage profiles.
Industry Challenges
- Telematics Data Science Talent Scarcity:Actuarial departments face recruitment gaps for machine learning engineers capable of deploying real-time scoring algorithms at scale.
- Legacy Policy Administration System Migration:Core system modernization for usage-based billing and dynamic rating requires capital deployment competing with dividend obligations and surplus growth targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Motor Insurance Market |
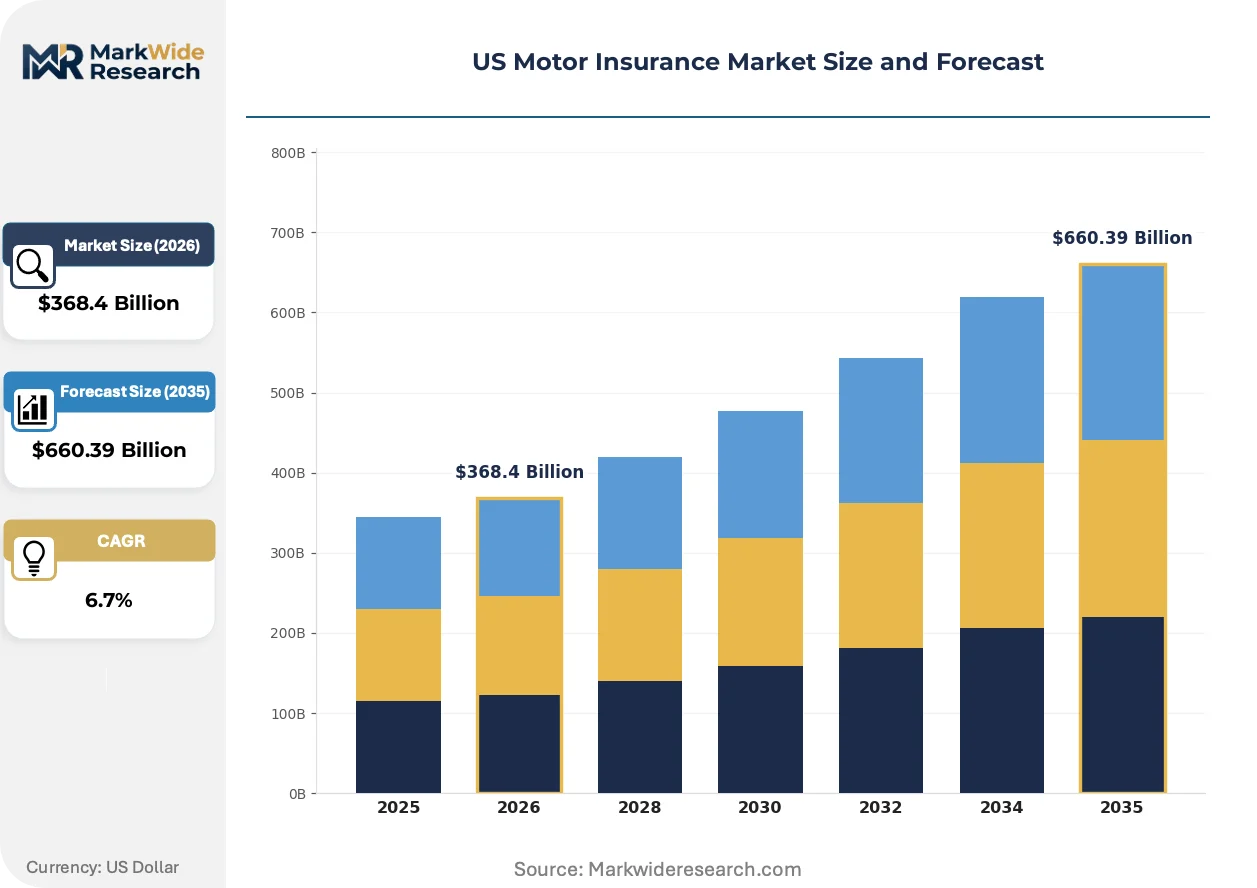
| Market Size in 2026 | $368.4 Billion |
| Market Size in 2035 | $660.39 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
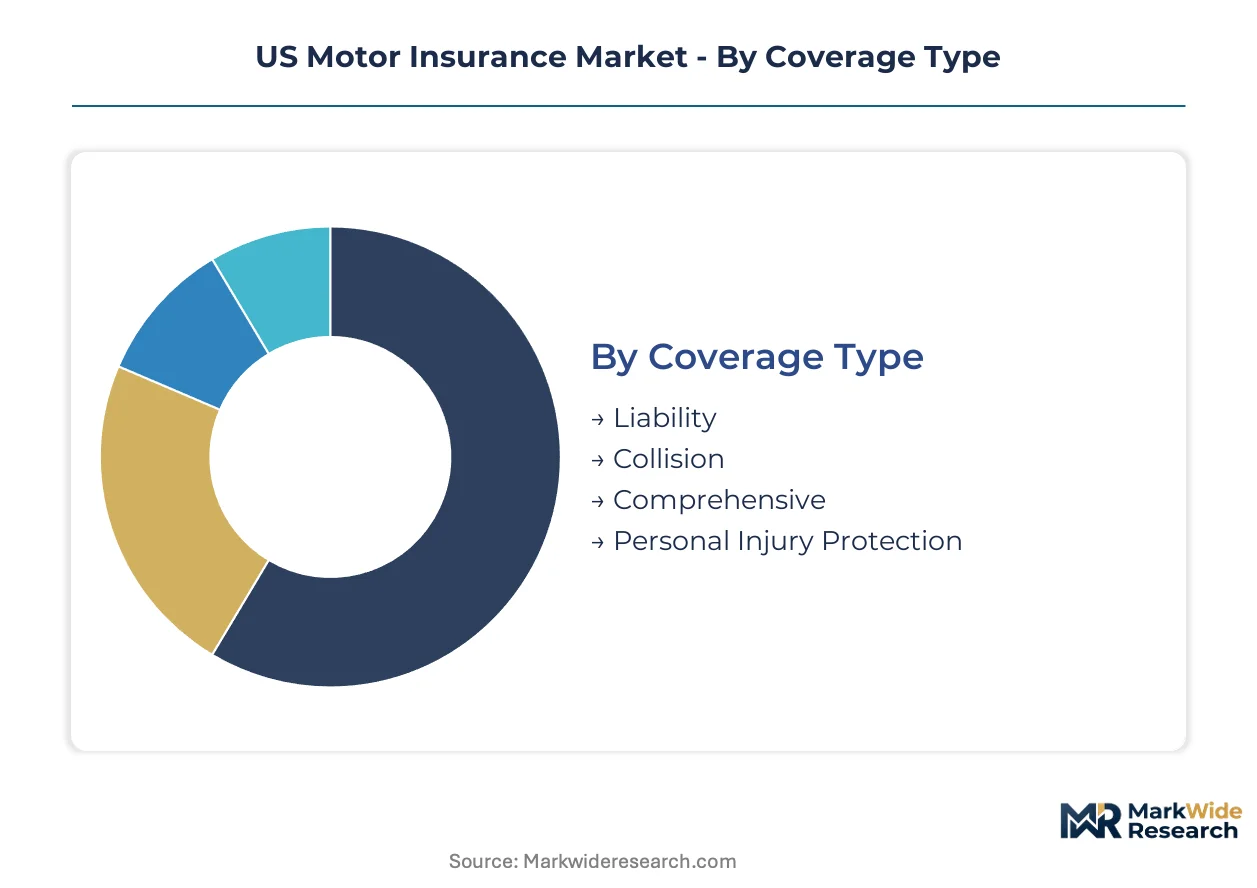
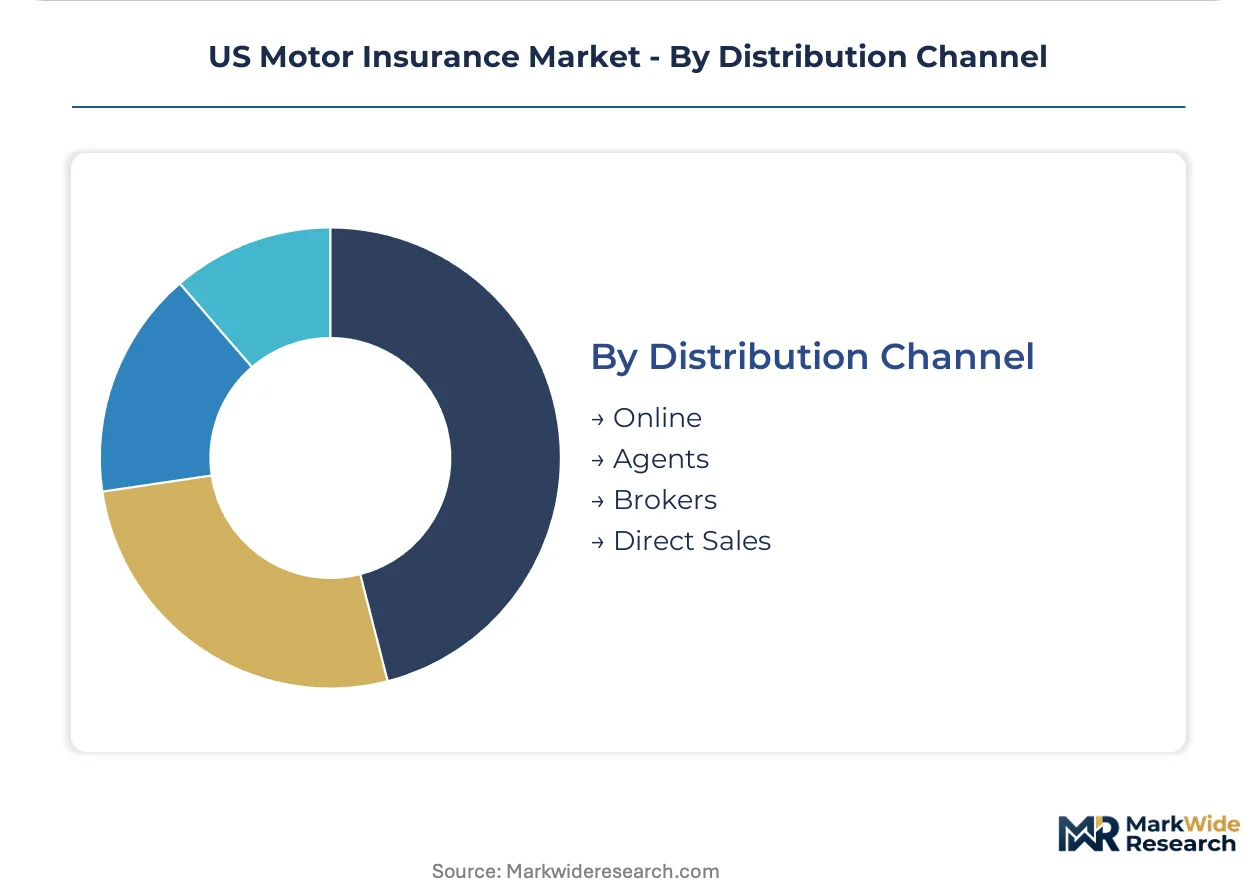
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Personal Injury Protection Policy Type: Standard, Non-Owner, Short-Term, High-Risk Customer Segment: Individual, Fleet, Commercial, Rideshare Distribution Channel: Online, Agents, Brokers, Direct Sales |
| Companies Covered | State Farm, Progressive, GEICO, Allstate, USAA, Liberty Mutual, Farmers Insurance, Nationwide, American Family Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Motor Insurance Market Evolving Landscape
Connected vehicle architectures and parametric loss settlement mechanisms are converging to compress claims cycles from weeks to hours. Real-time data streams now enable pre-crash event reconstruction and automated reserve allocation.
Telematics-based risk scoring is migrating from annual policy renewal adjustments to continuous price optimization at the trip level. Commercial fleet managers and high-mileage individual policyholders are adopting smartphone-integrated and OEM-embedded monitoring devices fastest. This granular visibility is compressing adverse selection pools and enabling immediate risk transfer pricing rather than retrospective experience rating.
The SEC's climate disclosure rules and NAIC's Own Risk and Solvency Assessment modernization are forcing reserves stress-testing against correlated catastrophe scenarios. Insurers must model multi-peril annual aggregate losses incorporating secondary uncertainty from supply chain disruption and litigation financing trends. Florida and California carriers are responding by ceding peak wind and wildfire exposure through increasingly complex catastrophe bond structures.
Policyholder service expectations are compressing claims settlement cycles from adjuster-mediated processes to automated image recognition and direct-to-consumer payment rails. Collision repair networks and total-loss valuation vendors are being disintermediated by AI-enabled damage assessment and instant settlement algorithms. Texas and Arizona markets exhibit the fastest adoption of self-service claims applications among younger policyholder cohorts.
US Motor Insurance Market Segmentation
Segmentation in US motor insurance determines pricing precision, capital allocation, and regulatory compliance across divergent risk pools. Underwriters deploy distinct models for personal auto versus commercial fleet exposures, while distribution economics vary sharply between captive agent networks and direct-to-consumer digital platforms.
Coverage Type:
Mature liability lines anchor premium volume while emerging comprehensive products respond to climate-peril intensification and repair cost inflation.
- Liability:State-mandated bodily injury and property damage coverage constitutes the foundational policy layer. Texas, California, and Florida generate the deepest premium pools due to high vehicle density and elevated litigation frequency in urban corridors.
- Comprehensive:Non-collision peril coverage addresses theft, vandalism, hail, and flood losses. Gulf Coast and Great Plains policyholders are attaching this coverage fastest as hailstorm severity and flood exposure reshape risk perception among previously minimum-coverage holders.
- Collision:Physical damage coverage for at-fault accidents faces severity pressure from semiconductor-laden repair costs and aluminum body complexity.
- Personal Injury Protection:No-fault medical and lost-wage coverage operates in mandatory states including Florida and New York, with utilization rates tied to state tort thresholds.
Liability retains volume leadership; comprehensive holds the steepest expansion curve.
Policy Type:
Cost-tier stratification separates mass-market standard products from specialized non-owner and high-risk alternatives with divergent underwriting economics.
- Standard:Six-month and annual term policies for conventional vehicle owners dominate policy-in-force counts. State Farm and Progressive compete most intensely for these renewals through telematics-enabled pricing and captive agency retention programs.
- High-Risk:Assigned-risk and non-standard auto plans serve drivers with violation histories or coverage lapses. State residual market mechanisms in California, Florida, and Texas absorb these exposures through insurer-of-last-resort pools with explicit surcharge schedules.
- Non-Owner:Named-operator liability coverage addresses urban dwellers without vehicle ownership who maintain driving privileges.
- Short-Term:Temporary coverage products span rental car gaps and vehicle purchase intervals, distributed through dealership management systems and travel platforms.
Standard policies anchor carrier profitability; high-risk segments command the widest pricing spreads.
Customer Segment:
Application-based segmentation distinguishes personal mobility from commercial vehicle deployment with fundamentally different loss-control engineering and pricing granularity.
- Individual:Personal auto policies cover household vehicles with driver-rated pricing. Telematics adoption concentrates among high-mileage commuters in Texas and Arizona seeking usage-based discounts.
- Commercial:Multi-vehicle fleet policies bundle liability, physical damage, and cargo coverage for logistics and delivery operators. Fleet managers in California and Texas are attaching specialized electric vehicle coverage as battery-electric adoption accelerates in last-mile delivery.
- Fleet:Corporate and government vehicle pools require loss-control engineering services and guaranteed repair network access.
- Rideshare:Hybrid usage policies address Period 1, 2, and 3 liability arbitrage between personal auto and TNC commercial coverage. California and Texas regulators have standardized gap-filling products fastest.
Individual policies generate premium volume; rideshare and commercial fleets are climbing the fastest.
Distribution Channel:
Channel economics separate high-touch advisory models from low-cost digital acquisition with divergent expense ratios and customer lifetime value profiles.
- Agents:Captive and independent producers control policy placement in suburban and rural counties where personal relationships drive retention. State Farm's captive agency network dominates this channel.
- Online:Direct-to-consumer digital platforms enable real-time quoting and policy issuance. GEICO and Progressive sustain sub-20% expense ratios through this channel versus 25-30% for agency-dependent carriers.
- Brokers:Commercial and high-net-worth intermediaries access surplus lines and specialty markets for complex risk placements.
- Direct Sales:Call center and mail-based acquisition persists among older demographics with lower digital engagement.
Agent channels retain renewal loyalty; online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California, Texas, and Florida consume motor insurance through distinct risk profiles shaped by litigation density, hailstorm exposure, and fleet electrification timelines that diverge sharply from Midwestern and Northeastern states.
California
Silicon Valley autonomous vehicle pilots and Los Angeles rideshare density drive specialty coverage demand. The California Department of Insurance enforces Proposition 103 rate filing requirements that mandate prior approval for premium adjustments. San Francisco Bay Area carriers are deploying telematics-at-scale for usage-based pricing among tech-sector commuters.
Texas
Houston-Galveston hurricane exposure and Permian Basin energy fleet expansion elevate commercial premium volumes. The Texas Department of Insurance maintains a competitive rating system allowing rate flexibility within statutory corridors. Dallas-Fort Worth metropolitan carriers are integrating embedded insurance partnerships with dealership management systems.
Florida
Miami-Dade litigation frequency and Gulf Coast flood peril intensification compress personal auto combined ratios. The Florida Office of Insurance Regulation imposes Citizens Property Insurance residual market assessments on admitted carriers. Tampa-St. Petersburg insurers are ceding peak wind exposure through catastrophe bond structures to Bermuda markets.
New York
No-fault personal injury protection utilization and upstate severe winter weather patterns distinguish coverage economics. The New York State Department of Financial Services enforces strict prior approval for rate and form filings. New York City metropolitan brokers dominate high-net-worth excess liability placements for luxury vehicle portfolios.
Illinois
Chicago logistics corridor commercial fleet density and Midwest hailstorm corridors shape comprehensive coverage attachment. The Illinois Department of Insurance operates a use-and-file system permitting faster rate implementation than prior-approval states. Peoria and Rockford manufacturing clusters sustain captive fleet insurance programs for automotive supplier operations.
US Motor Insurance Market Competitive Landscape
Capability concentration sits with telematics-enabled pricing specialists; scale advantage sits with captive agency distribution networks. The market structures around three tiers: national direct-to-consumer platforms, exclusive agent-dependent carriers, and mutual holding company architectures. Dominant competitive moves include embedded insurance partnerships with automotive OEMs and legacy policy administration system modernization for real-time rating.
Within the direct-to-consumer tier, GEICO and Progressive exemplify low-expense-ratio acquisition models. State Farm anchors the captive agency vector through suburban and rural distribution control. These three carriers collectively represent the competitive archetypes—digital-native pricing agility, exclusive producer network lock-in, and mutual policyholder ownership structures—that define strategic positioning across state-level rate filing battles.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| GEICO |
| Allstate |
| USAA |
| Liberty Mutual |
| Farmers Insurance |
| Nationwide |
| American Family Insurance |
| Others |
Value Network & Pricing Analysis
Reinsurance capital concentration in Bermuda and London markets directly determines where underwriting margin pools accumulate in US motor insurance, as collateral requirements and catastrophe bond spreads cascade into primary carrier pricing power across Gulf Coast and Florida wind-exposed portfolios.
Pricing Analysis
Contract-based long-term offtake agreements between primary carriers and reinsurance markets dominate capital sourcing, though spot-market capacity purchases spike post-catastrophe. Price differentiation rests on loss-control engineering depth and telematics data granularity, with standard personal auto tiers compressing fastest. Pricing pressure stems from vehicle repair cost inflation driven by semiconductor-laden component complexity. Commercial fleet buyers exhibit lowest price sensitivity due to bundled loss-control services, while minimum-coverage individual policyholders in Texas and Florida face acute premium elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Bermuda reinsurers and London market syndicates are tightening collateral terms for US primary carriers writing peak catastrophe exposure. Geographic supply concentration centers on Bermuda, London, and Zurich for risk capital; domestic actuarial talent and telematics infrastructure concentrate in California, Texas, and Illinois. Raw material dependencies span catastrophe modeling software, IoT sensor hardware, and cloud computing infrastructure. Single-source vulnerability in proprietary telematics platforms poses structural risk. Distribution runs through captive agency networks and direct-to-consumer digital platforms with divergent acquisition economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering talent capable of deploying real-time driving-scoring algorithms at scale is scarce across actuarial departments, constraining usage-based insurance expansion for carriers competing on telematics-enabled pricing precision.
For Market Incumbents: Pre-empt disintermediation by embedded insurance partnerships through exclusive data-sharing agreements with automotive OEM financing platforms. Fortify position by accelerating legacy policy administration system migration to cloud-native architectures capable of dynamic rating. Channel control through captive agency networks remains defensible against direct-to-consumer digital entrants in suburban and rural counties. For New Entrants and Emerging Players: Rural counties in Texas and Florida exhibit underpenetration by telematics-enabled pricing specialists, presenting white-space entry points before State Farm and Progressive complete agency network digitization. Target commercial fleet electrification coverage gaps in last-mile delivery operations. Pursue point-of-sale integration with dealership management systems as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed insurtech platforms possessing telematics infrastructure but lacking captive distribution scale. Long-term viability favors carriers with dual capability in real-time data science and exclusive agency network control. Monitor NHTSA autonomous vehicle liability rulemaking as inflection signal for product liability migration from driver negligence to manufacturer defect claims.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Deployment | Enables trip-level pricing granularity that compresses adverse selection pools for Progressive and GEICO. |
| Embedded Insurance Partnership | Captures first-policy relationships through OEM financing platforms before traditional agent contact in Texas. |
| Legacy System Modernization | Accelerates dynamic rating capabilities for usage-based billing competing with dividend obligations at State Farm. |
| Reinsurance Capacity Diversification | Reduces Bermuda market dependency for Florida wind exposure through catastrophe bond structures. |
| Autonomous Vehicle Liability Product Development | Opens specialty lines for technology E&O as NHTSA mandates expand semi-autonomous vehicle populations. |
Research Methodology
A standing panel of chief underwriting officers, telematics product managers, state insurance department rate filing examiners, and reinsurance broker placement specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA crash-test protocol filings, state department of insurance rate filing databases, SEC insurer investment portfolio disclosures, and NAIC Own Risk and Solvency Assessment reports. Bottom-up policy-level data triangulated against top-down premium volume estimates from regulatory financial statements.
Scenario-bracketing around autonomous vehicle adoption timelines, climate-peril severity trajectories, and telematics regulatory approval pathways anchored the analytical framework across the projection horizon. Segmentation dimensions modeled coverage type, policy tier, customer segment, and distribution channel with state-level regulatory cluster overlays. CAGRs derived from actuarial loss-cost trend analysis combined with premium volume elasticity estimates. Forecast inputs incorporated vehicle repair cost inflation indices and reinsurance market capacity availability indicators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized insurtech platforms or autonomous vehicle OEMs entering insurance vertically would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Marine Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Germany Motor Insurance Market