
 Russia Car Insurance Market | 2026-2036
Russia Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Car Insurance Market Insights
Telematics-linked leasing and pay-as-you-drive financing is reconfiguring entry barriers for new competitors in the Russia car insurance sector. Sogaz leverages its state-affiliated corporate relationships to dominate fleet and commercial lines. Ingosstrakh sustains broad retail distribution through an extensive branch network spanning federal subjects. Alfa Strakhovanie differentiates via digital-first policy issuance, capturing younger individual policyholders in major urban centers.
Russia car insurance constitutes a contractual risk-transfer mechanism where underwriters assume financial liability for vehicle damage, theft, or third-party bodily injury in exchange for premium payments, with policies priced through actuarial models incorporating vehicle age, driver history, and geographic risk zones. The primary purpose is to pool and redistribute accident-related losses across policyholder cohorts while satisfying Russia's compulsory motor third-party liability (OSAGO) legal mandate. Comprehensive coverage leads policy type segmentation by premium value, though basic liability dominates by policy count due to OSAGO enforcement. Fleet owner demand within customer type segmentation is expanding fastest as corporate logistics operators professionalize risk management. Full coverage scope commands superior margins but faces price sensitivity among individual buyers in secondary cities.
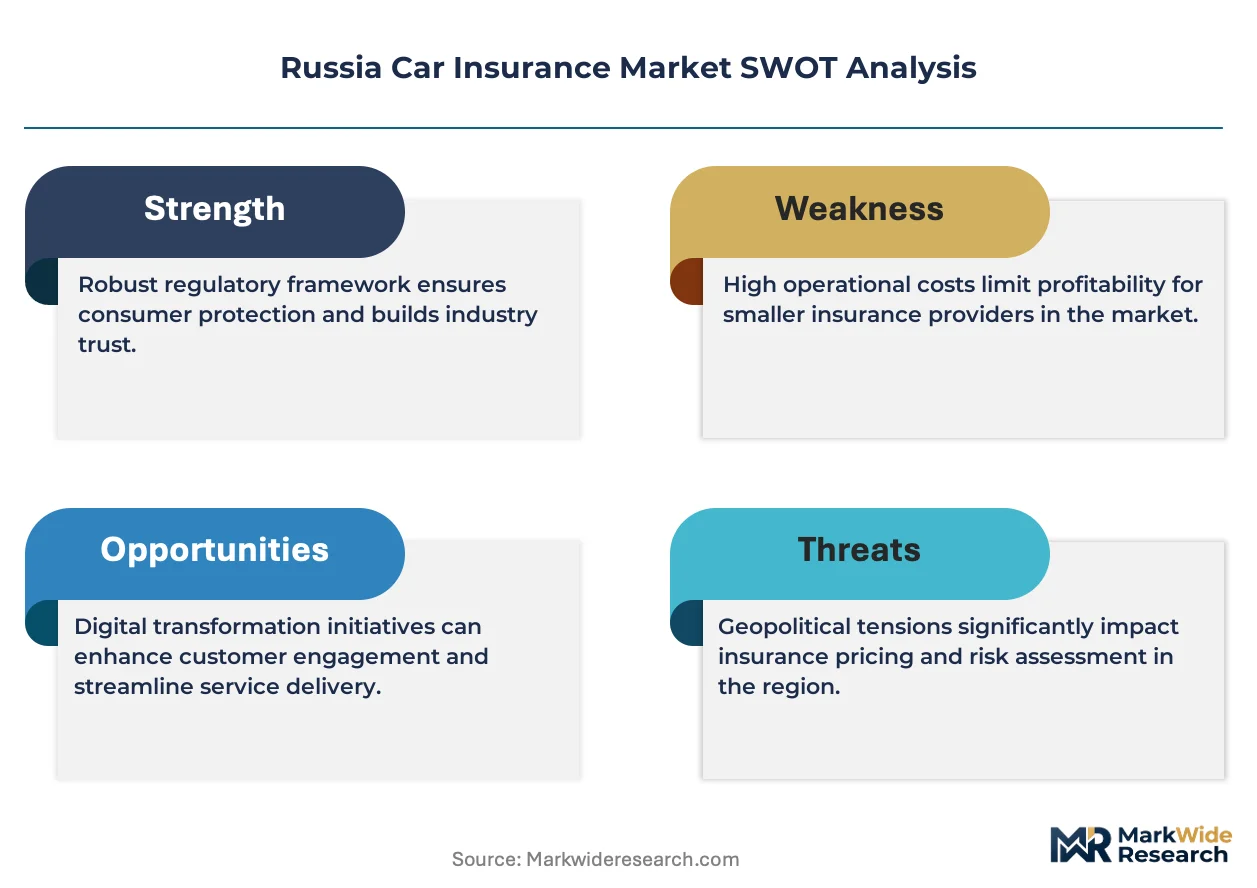
Russia's Central Bank supervises insurer solvency and capital reserves under federal insurance law, while OSAGO tariff regulation sets mandatory pricing corridors that constrain underwriting flexibility. The Central Bank's periodic intervention in loss-ratio calculations directly shapes product profitability and market access conditions for domestic and foreign-licensed carriers. Stakeholders must monitor pending regulatory revisions to OSAGO calculation methodologies and telematics data privacy frameworks to anticipate margin compression or competitive displacement.
Market Dynamics
Russia's Central Bank capital adequacy tightening is forcing insurer consolidation while telematics-linked pricing models restructure competitive entry requirements across the sector.
Growth Catalysts
- OSAGO tariff corridor expansion:The Central Bank's periodic recalibration of mandatory pricing bands creates underwriting flexibility for carriers willing to invest in actuarial sophistication.
- Logistics fleet professionalization:Corporate transport operators are expanding insured vehicle pools under compulsory coverage mandates, driving volume in commercial motor lines.
- Telematics integration:Real-time driving data capture enables dynamic risk scoring and pay-as-you-drive product structures that attract younger policyholders.
Market Restraints
- Capital reserve requirements:The Central Bank's tightened solvency ratios strain smaller underwriters, pushing marginal carriers toward exit or acquisition.
- Loss-ratio volatility:Periodic regulatory intervention in claims calculation methodologies compresses product profitability unpredictably.
- Geographic risk concentration:Premium generation clusters disproportionately in Moscow and the Central Federal District, leaving peripheral regions with thinner risk pools.
Strategic Opportunities
- Digital-first distribution:Mobile policy issuance and claims processing platforms capture underserved urban individual buyers seeking frictionless purchasing.
- Fleet owner segment expansion:Corporate logistics operators professionalizing risk management represent the fastest-growing customer cohort for comprehensive coverage products.
- Telematics data monetization:Aggregated driving behavior analytics create secondary revenue streams through partnerships with automotive OEMs and leasing providers.
Industry Challenges
- Actuarial talent scarcity:Sophisticated pricing model development requires specialized data science capabilities that compete with fintech and banking sectors for skilled labor.
- Legacy system integration:Incumbent carriers face friction connecting telematics platforms to decades-old policy administration infrastructure.
- Regulatory compliance velocity:Pending revisions to OSAGO calculation methodologies and data privacy frameworks demand continuous operational adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Car Insurance Market |
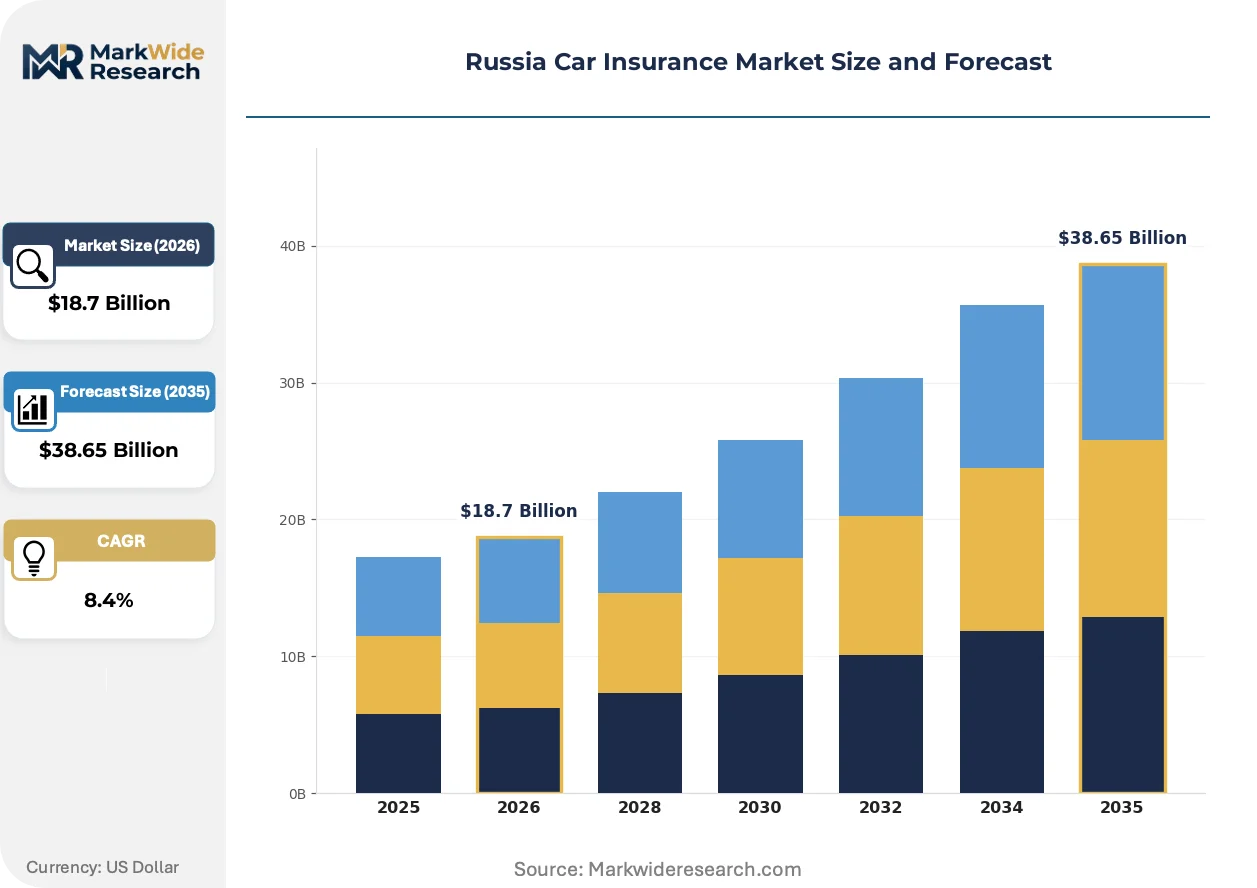
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Basic Liability, Comprehensive, Collision, Third-Party Customer Type: Individual, Fleet Owner, Commercial, Chauffeur Coverage Scope: Full Coverage, Limited Coverage, Additional Riders, Multi-Car Discount Claim Process: Online Submission, Phone Support, Direct Settlement, In-Person Adjustment |
| Companies Covered | Sogaz, Ingosstrakh, Alfa Strakhovanie, Reso-Garantia, Rosgosstrakh, Sberbank Insurance, VTB Insurance, Tinkoff Insurance, Renaissance Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Car Insurance Market Trends and Innovations
Telematics infrastructure deployment is restructuring how risk is priced and distributed, with regulatory pressure and buyer behavior shifts compounding the transformation of carrier business models.
Connected vehicle data platforms are virtualizing traditional underwriting workflows. Fleet operators and individual policyholders alike transmit real-time telemetry on braking patterns, mileage, and geolocation. This data stream enables granular risk segmentation that compresses cross-subsidization between safe and hazardous drivers. The technology is virtualizing the entire policy lifecycle from quotation through claims settlement.
The Central Bank's evolving OSAGO framework is reshaping product economics. Tariff corridor adjustments and loss-ratio calculation interventions directly constrain carrier pricing autonomy. Commercial motor lines face the steepest compliance burden as regulators scrutinize reserve adequacy against claims volatility. Carriers respond by diversifying into voluntary comprehensive products with greater margin flexibility.
Buyer preference is migrating toward usage-based coverage structures. Younger drivers in major urban centers reject annual fixed premiums in favor of mileage-linked or behavior-scored alternatives. Digital-native distributors capture this shift through mobile-first policy issuance that bypasses traditional branch networks. Moscow and Saint Petersburg exhibit the most pronounced channel migration, with secondary cities following at slower adoption curves.
Russia Car Insurance Market Segmentation
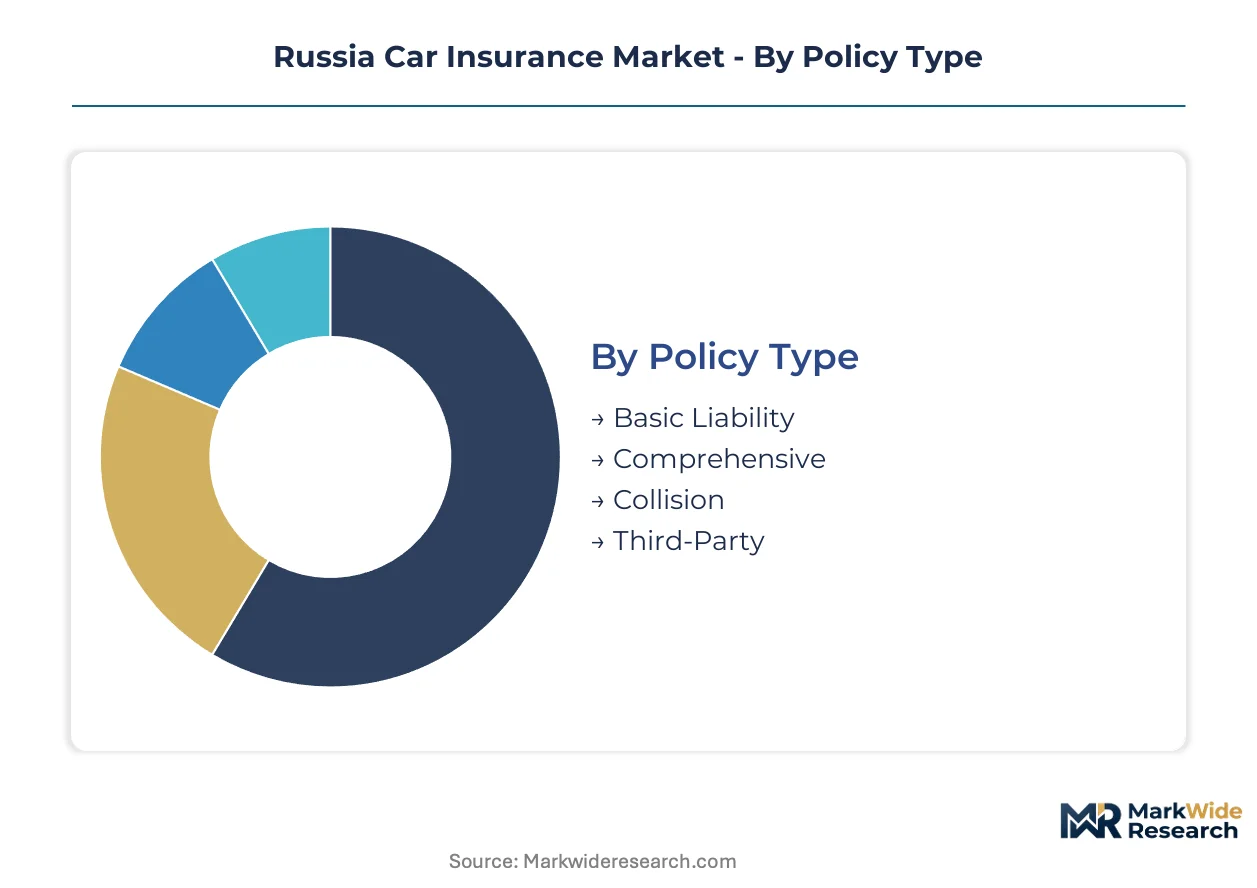
Segmentation in the Russia car insurance market reveals how regulatory mandates and buyer sophistication split demand across risk-transfer products. Carriers calibrate capital allocation and distribution strategy around these divisions.
Policy Type:
Cost tier differentiation separates mandatory minimum coverage from premium voluntary products, with pricing power concentrated in upper tiers.
- Basic Liability:OSAGO-mandated minimum coverage satisfies legal driving requirements with standardized tariff corridors set by the Central Bank. Moscow and Saint Petersburg generate disproportionate policy count despite thinner margins per contract.
- Comprehensive:Voluntary coverage bundles own-vehicle damage, theft, and third-party liability into single policies with superior underwriting margins. Fleet operators in the Central Federal District drive volume as logistics firms professionalize risk management.
- Collision:Narrow-scope coverage limits payouts to at-fault accidents involving the insured vehicle. Individual policyholders in secondary cities select this tier to reduce premium outlays.
- Third-Party:Standalone liability coverage extends beyond OSAGO minimums for drivers seeking elevated protection limits. Urban professionals with high-value assets favor this segment.
Basic Liability holds installed capacity. Comprehensive is rotating up the share rankings.
Customer Type:
Application-based segmentation aligns product design with risk management maturity and purchasing sophistication.
- Individual:Retail policyholders purchase through branch networks or digital channels with price sensitivity varying by geography. Younger buyers in major urban centers migrate toward mobile-first issuance platforms.
- Fleet Owner:Corporate logistics operators manage pooled vehicle risk under compulsory coverage mandates with expanding insured unit counts. This cohort is expanding most quickly as commercial transport fleets scale.
- Commercial:Business entities insure vehicles used for revenue-generating activities beyond pure logistics. Regional distributors and construction firms populate this segment.
- Chauffeur:Professional driver coverage addresses specialized liability profiles for employed and contracted operators. Premium car services in Moscow concentrate demand here.
Fleet Owner captures the steepest expansion trajectory. Individual maintains volume dominance.
Coverage Scope:
Volume segmentation reflects how policyholders bundle or strip coverage components based on asset value and risk tolerance.
- Full Coverage:Maximum protection tier combining compulsory liability, own-damage, theft, and natural peril coverage. High-net-worth individuals in Moscow and the surrounding region anchor demand.
- Limited Coverage:Stripped-back policies covering only specified perils with explicit exclusions. Cost-conscious buyers in peripheral federal subjects select this tier.
- Additional Riders:Modular extensions for roadside assistance, replacement vehicles, or legal protection. Fleet operators attach these to comprehensive base policies.
- Multi-Car Discount:Volume pricing mechanisms for households or small businesses insuring multiple vehicles under single contracts. Suburban families around Saint Petersburg favor this structure.
Full Coverage commands margin leadership. Limited Coverage is gaining share fastest among price-sensitive segments.
Claim Process:
Distribution channel segmentation tracks how policyholders initiate and resolve claims, with digital migration reshaping cost structures.
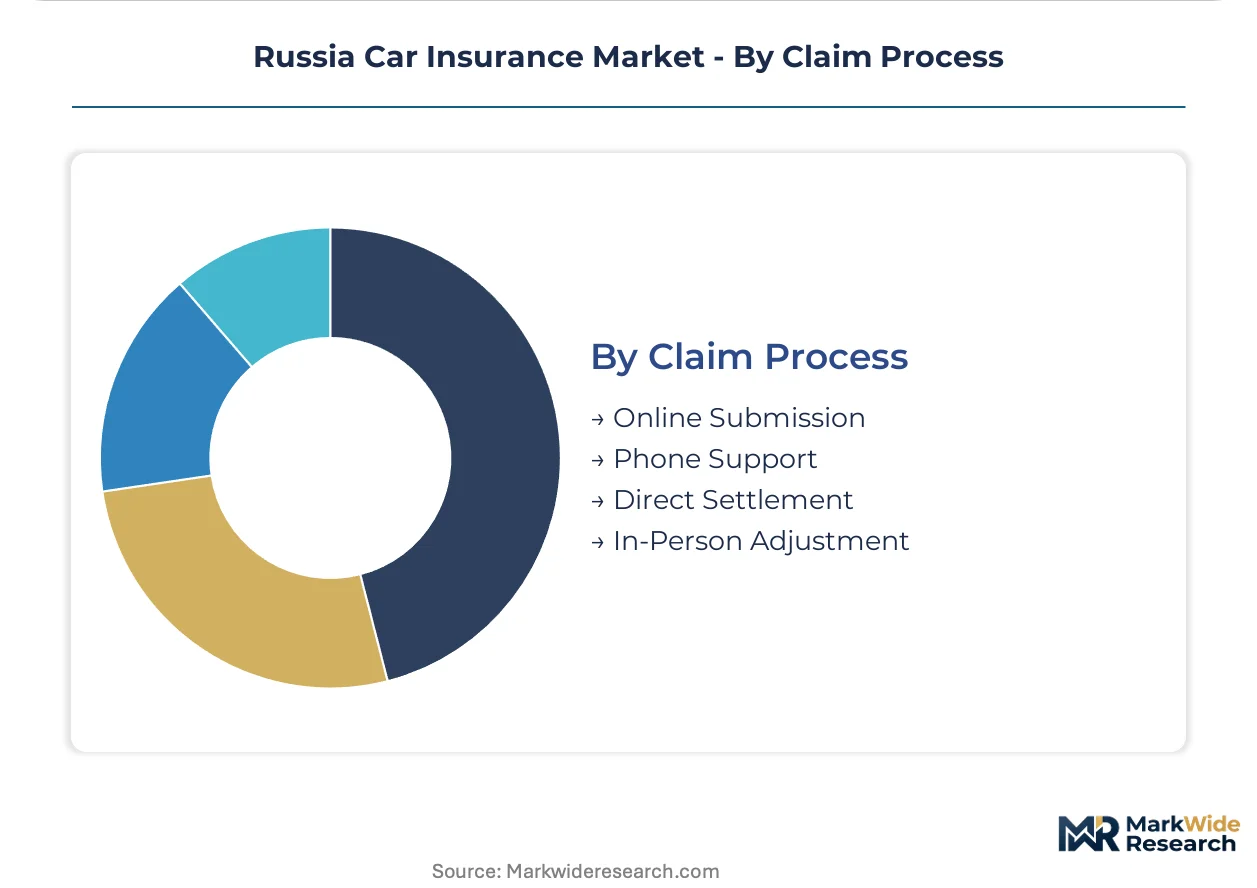
- Online Submission:Self-service portals and mobile applications enable documentation upload and status tracking without human intervention. Alfa Strakhovanie and digital-native competitors prioritize this channel.
- Phone Support:Call center-based claims initiation persists among older policyholders and complex liability disputes. Legacy carriers maintain infrastructure here.
- Direct Settlement:Pre-negotiated repair network relationships enable cashless claims resolution at authorized service centers. Sogaz leverages state-affiliated relationships to dominate this channel.
- In-Person Adjustment:Physical inspection requirements for high-value or contested claims demand adjuster site visits. Rural and remote regions rely heavily on this process.
Online Submission holds technology investment priority. Direct Settlement is climbing the channel rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mandatory OSAGO coverage expansion and Central Bank capital requirements are redistributing underwriting capacity toward federal districts with superior risk-pooling depth and commercial fleet density.
Central Federal District
Moscow concentrates premium generation through high vehicle density and elevated pricing power. The Central Bank's OSAGO tariff corridors enable sophisticated carriers to deploy dynamic pricing models. Fleet operators in the Moscow Oblast are expanding insured commercial vehicle pools under compulsory coverage mandates.
Northwestern Federal District
Saint Petersburg anchors demand for digital-first policy issuance among younger individual policyholders. Regional branches of federal underwriters maintain extensive physical distribution networks. Logistics corridors through Leningrad Oblast drive fleet owner segment expansion.
Volga Federal District
Nizhny Novgorod and Kazan exhibit rising comprehensive coverage penetration among professional service workers. The Central Bank's solvency requirements are pressuring smaller regional underwriters toward consolidation. Commercial transport operators in Tatarstan are professionalizing risk management practices.
Siberian Federal District
Novosibirsk generates concentrated demand despite thinner risk pools and lower premium pricing power. Harsh climatic conditions elevate claims frequency for own-damage coverage. Regional distributors are attaching modular riders to base policies for construction and mining fleet operators.
Southern Federal District
Rostov-on-Don and Krasnodar Krai display accelerating telematics adoption among individual buyers seeking usage-based alternatives. Agricultural and port logistics fleets drive commercial line growth. Digital-native distributors are capturing channel migration through mobile-first platforms.
Russia Car Insurance Market Competitive Landscape
On the supply side, the industry is consolidating around tiered competitive positions where capital adequacy requirements filter marginal participants from sustainable operators. State-affiliated and banking-affiliated carriers command structural advantages in commercial lines and digital distribution respectively. Strategic archetypes include diversified financial conglomerates, specialized national underwriters, and technology-driven direct writers. Consolidation through acquisition and telematics platform investment constitute the dominant competitive moves reshaping market access.
Within the state-affiliated tier, Sogaz leverages its corporate relationships to anchor fleet and commercial segment positions. Ingosstrakh occupies a position exemplifying broad retail distribution through extensive branch infrastructure. Alfa Strakhovanie represents the digital-first archetype capturing urban individual policyholders through mobile issuance platforms. These three carriers illustrate how capital depth, physical presence, and technology investment respectively configure competitive positioning under tightening regulatory constraints.
| Leading Market Players |
|---|
| Sogaz |
| Ingosstrakh |
| Alfa Strakhovanie |
| Reso-Garantia |
| Rosgosstrakh |
| Sberbank Insurance |
| VTB Insurance |
| Tinkoff Insurance |
| Renaissance Insurance |
| Others |
Pricing and Supply Chain Analysis
The M11 Neva highway freight corridor's cost volatility compresses margins for insurers serving fleet operators across the Central Federal District, concentrating pricing power among carriers with captive repair networks and dynamic OSAGO tariff modeling capabilities.
Pricing Analysis
Actuarial sophistication creates the primary spread between premium tiers in the Russia car insurance sector. Three-tier pricing structure across premium, standard, and economy levels dominates, with certification-grade risk scoring and telematics integration driving differentiation. Cost compression in the economy tier is intensifying because Central Bank loss-ratio interventions constrain underwriting flexibility. Individual policyholders in secondary cities exhibit highest price sensitivity, while fleet operators prioritize claims service quality over premium minimization.
Supply Chain Analysis
Technology transfer restrictions on connected vehicle platforms limit telematics hardware flows into the Russian market, forcing insurers toward domestically sourced data capture solutions. Supply concentrates in China for sensor hardware, South Korea for telematics platform software, and domestic Russian assembly for final device integration. Raw material dependencies span semiconductor chips, GPS modules, and cellular communication components. Single-source vulnerability in telematics chipset supply creates procurement risk. Distribution runs through authorized dealer networks and direct OEM partnerships for fleet installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fleet operators as logistics consolidation concentrates purchasing volume, fragmenting price-setting autonomy among individual retail underwriters.
For Market Incumbents: Pre-empt telematics-native entrants by acquiring regional repair network capacity in the Volga and Siberian Federal Districts. Central Bank capital adequacy tightening threatens smaller carriers with forced exit, creating acquisition targets with established OSAGO license infrastructure. Backward integration into claims fulfillment assets defends margin position against digital distributors. For New Entrants and Emerging Players: Establish a beachhead in the Southern Federal District telematics-adoption corridor, where Krasnodar Krai and Rostov-on-Don display accelerating usage-based policy demand. White-space exists in mobile-first claims processing for individual buyers aged 25-35. Partner with automotive OEMs for embedded insurance at point-of-sale as the primary go-to-market angle. For Investors and Strategic Acquirers: Digital-native mid-tier underwriters with proprietary telematics platforms and established Central Federal District presence represent the most viable acquisition archetype. Long-term viability hinges on regulatory technology adaptation velocity rather than scale alone. Watch Central Bank OSAGO calculation methodology revisions as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables dynamic risk scoring that compresses cross-subsidization between safe and hazardous driver cohorts. |
| Repair Network Acquisition | Captures claims fulfillment margin and accelerates direct settlement channel dominance against branch-dependent competitors. |
| Embedded Insurance Partnership | Locks distribution access at vehicle purchase point, bypassing price-comparison aggregator displacement. |
| Actuarial Talent Recruitment | Secures data science capabilities competing with banking and fintech sectors for specialized labor pools. |
| Regulatory Technology Investment | Automates compliance with Central Bank solvency reporting and OSAGO tariff corridor adjustments. |
Research Methodology
The analysis maps compulsory motor liability, comprehensive coverage, collision policies, and third-party extensions, each validated through underwriter product managers, Central Bank regulatory affairs specialists, fleet operator risk directors, and automotive OEM partnership leads. Primary interviews with these stakeholders combined with secondary validation against Bank of Russia statistical bulletins, OSAGO tariff corridor regulatory filings, federal subject vehicle registration databases, and insurer solvency disclosure reports. Bottom-up policy count and premium volume estimates triangulated against top-down Central Bank sector aggregates.
Assumptions held Central Bank capital adequacy thresholds and OSAGO mandatory coverage mandates fixed across the projection horizon, while telematics adoption curves and loss-ratio calculation methodologies varied. Segmentation dimensions modeled include policy type tier, customer application, coverage scope breadth, and claims channel preference. CAGRs derived from historical premium growth patterns adjusted for regulatory intervention frequency and fleet expansion trajectories. Forecast inputs incorporate vehicle sales projections and logistics sector employment trends.
Sensitivities concentrate around Central Bank OSAGO tariff recalibrations and telematics data privacy framework revisions. Forecasts reflect these documented assumptions with explicit boundary conditions. Material shifts in compulsory coverage enforcement intensity or foreign technology import restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market