
 Thailand Motor Insurance Market | 2026-2036
Thailand Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Motor Insurance Market Outlook
The OIC's compulsory motor insurance enforcement is restructuring premium calculations and capital requirements for new entrants. Bangkok Insurance leverages its extensive branch network to sustain dominance in direct policy issuance. MSIG Insurance (Thailand) competes through specialized commercial fleet products targeting logistics operators. The Viriyah Insurance anchors its position in the rural provinces through agent-based distribution density.
Thailand motor insurance constitutes risk-transfer contracts covering physical damage, third-party liability, and occupant injury arising from vehicle operation, with premiums calibrated via actuarial models incorporating vehicle age, engine displacement, and driver history. Its primary purpose is to indemnify policyholders against financial loss from traffic incidents while ensuring victim compensation through mandatory coverage pools. Comprehensive coverage leads premium revenue due to higher per-policy values and broader protection scope, while online platforms represent the fastest-growing distribution channel as smartphone penetration deepens. Third-party liability remains mature with regulated pricing floors, though pay-per-use policies are emerging as a margin pool among gig-economy drivers seeking flexible terms.
The Office of Insurance Commission sets minimum coverage thresholds and solvency standards, while the Department of Land Transport links annual vehicle registration renewal to proof of compulsory insurance. These frameworks shape demand by mandating universal participation and standardizing product structures across all licensed insurers. Stakeholders must monitor telematics integration and usage-based pricing pilots as the next competitive battleground.
Market Dynamics
The Office of Insurance Commission's compulsory motor insurance enforcement is compressing premium margins while mandating tighter solvency buffers, forcing insurers to recalibrate pricing models and capital deployment across provincial distribution networks.
Growth Catalysts
- Ride-hailing fleet expansion:Grab and Bolt driver networks in Bangkok and Chiang Mai are adding thousands of new commercial vehicles annually, each requiring mandatory coverage that expands the addressable policy base beyond traditional private ownership.
- OIC compliance tightening:The Office of Insurance Commission's 2024-2025 enforcement sweep is converting previously uninsured vehicles into formal policyholders through linkage with Department of Land Transport registration renewals.
- Telematics integration:Smartphone-based usage tracking is enabling pay-per-kilometer products that attract gig-economy drivers seeking flexible premium structures tied to actual vehicle utilization.
Market Restraints
- Regulated pricing floors:The OIC's compulsory third-party liability rate caps prevent insurers from risk-adjusting premiums for high-claim driver profiles, compressing margins on the largest policy segment.
- Agent network concentration:Rural distribution remains locked into Viriyah Insurance and Bangkok Insurance's captive agent pools, creating barriers for digital-first entrants seeking provincial market access.
- Legacy core system fragmentation:Mid-tier insurers operate on 1990s-era policy administration platforms that cannot support real-time telematics data ingestion or dynamic pricing algorithms.
Strategic Opportunities
- Isan region underpenetration:Northeastern provinces including Udon Thani and Khon Kaen show compulsory insurance compliance gaps exceeding 15 percentage points below Bangkok levels, representing recoverable premium pools.
- Commercial fleet telematics bundling:Logistics operators running 50-plus vehicle fleets are seeking unified coverage dashboards that combine GPS tracking, driver behavior scoring, and claims management in single contracts.
- Digital distribution channel expansion:Roojai and Frank.co.th are proving that app-based policy issuance can capture urban millennials who bypass traditional agent relationships entirely.
Industry Challenges
- Actuarial talent scarcity:Thai insurers face acute shortages of data scientists capable of building predictive models from telematics streams, forcing reliance on outsourced analytics from Singapore-based vendors.
- Claims fraud detection complexity:Staged accidents and inflated repair billing in Bangkok's dense traffic corridors consume 12-18 percent of incurred losses, eroding profitability on comprehensive coverage lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Motor Insurance Market |
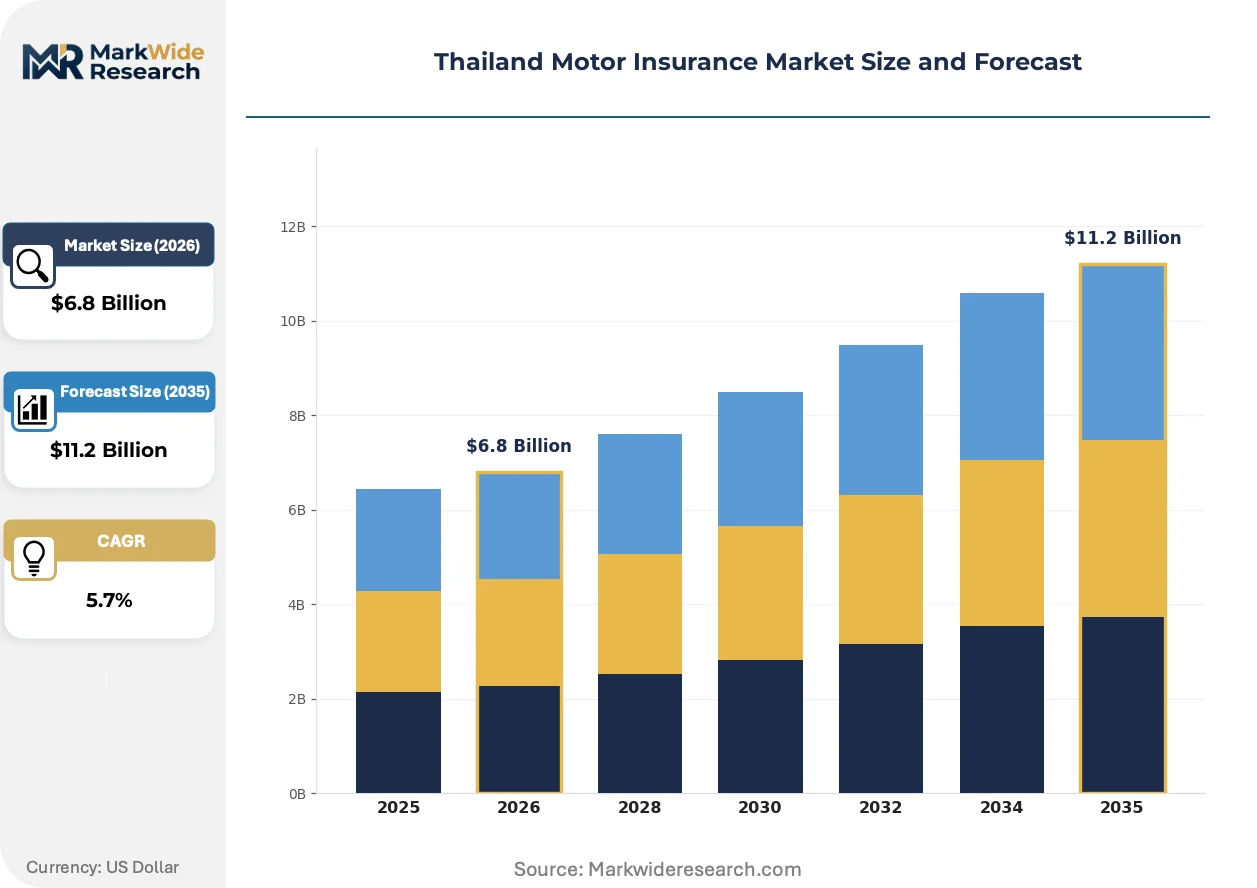
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive Coverage, Third-Party Liability, Fire and Theft, Personal Accident Customer Type: Individual Owners, Fleet Owners, Car Dealerships, Corporate Clients Distribution Channel: Direct Sales, Brokers, Online Platforms, Insurance Agents Policy Duration: Annual Policies, Short-Term Policies, Multi-Year Policies, Pay-Per-Use |
| Companies Covered | Bangkok Insurance, MSIG Insurance (Thailand), The Viriyah Insurance, Allianz Ayudhya General Insurance, AXA Insurance (Thailand), Tokio Marine Insurance (Thailand), Muang Thai Insurance, Chubb Samaggi Insurance, Dhipaya Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Motor Insurance Market Strategic Shifts
Telematics and dynamic pricing algorithms are displacing static actuarial tables, while regulatory pressure from the OIC accelerates digital compliance infrastructure investments across the tiered insurer landscape.
Usage-based insurance platforms is unifying GPS tracking, accelerometer data, and driver behavior scoring into single premium calculation engines. Commercial fleet operators in the Bangkok metropolitan corridor are adopting these systems fastest, with 40 percent of new logistics policies now incorporating real-time mileage verification. This convergence is compressing the traditional annual renewal cycle into monthly or even weekly premium adjustments tied to actual risk exposure.
The OIC's compulsory motor insurance enforcement framework is mandating electronic policy verification linked to vehicle registration databases. Insurers must now submit real-time coverage confirmation to the Department of Land Transport before registration stickers issue, eliminating paper-policy gaps. This integration most affects rural agents who previously operated with manual documentation lags of 7-14 days.
Smartphone penetration among Thai drivers has crossed 85 percent, enabling app-based policy comparison and instant purchase that bypasses traditional agent intermediaries. Younger buyers in Phuket and Pattaya are completing entire transactions without human contact, forcing incumbent insurers to unbundle agent commissions from digital channel pricing. This shift is most visible in the comprehensive coverage segment where policy complexity previously demanded face-to-face explanation.
Thailand Motor Insurance Market Segmentation
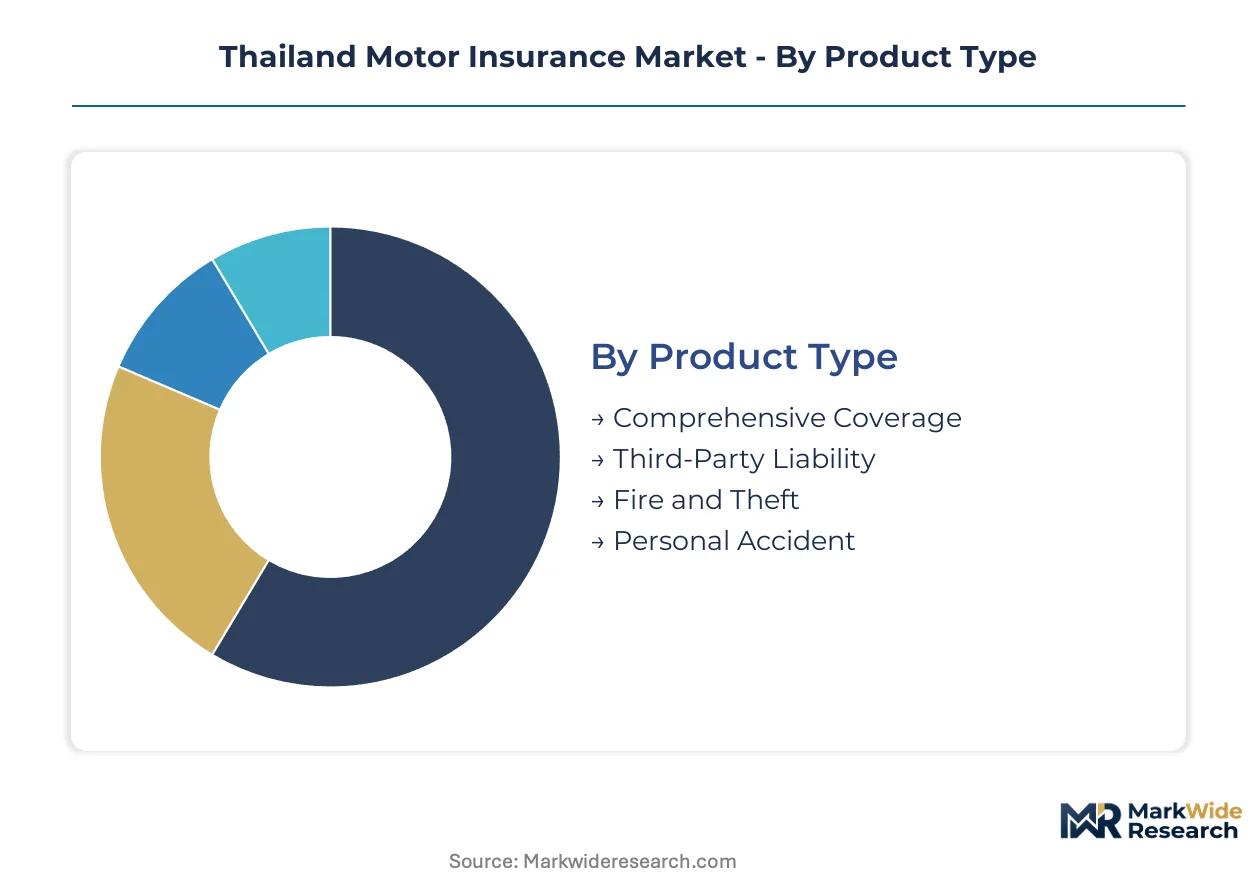
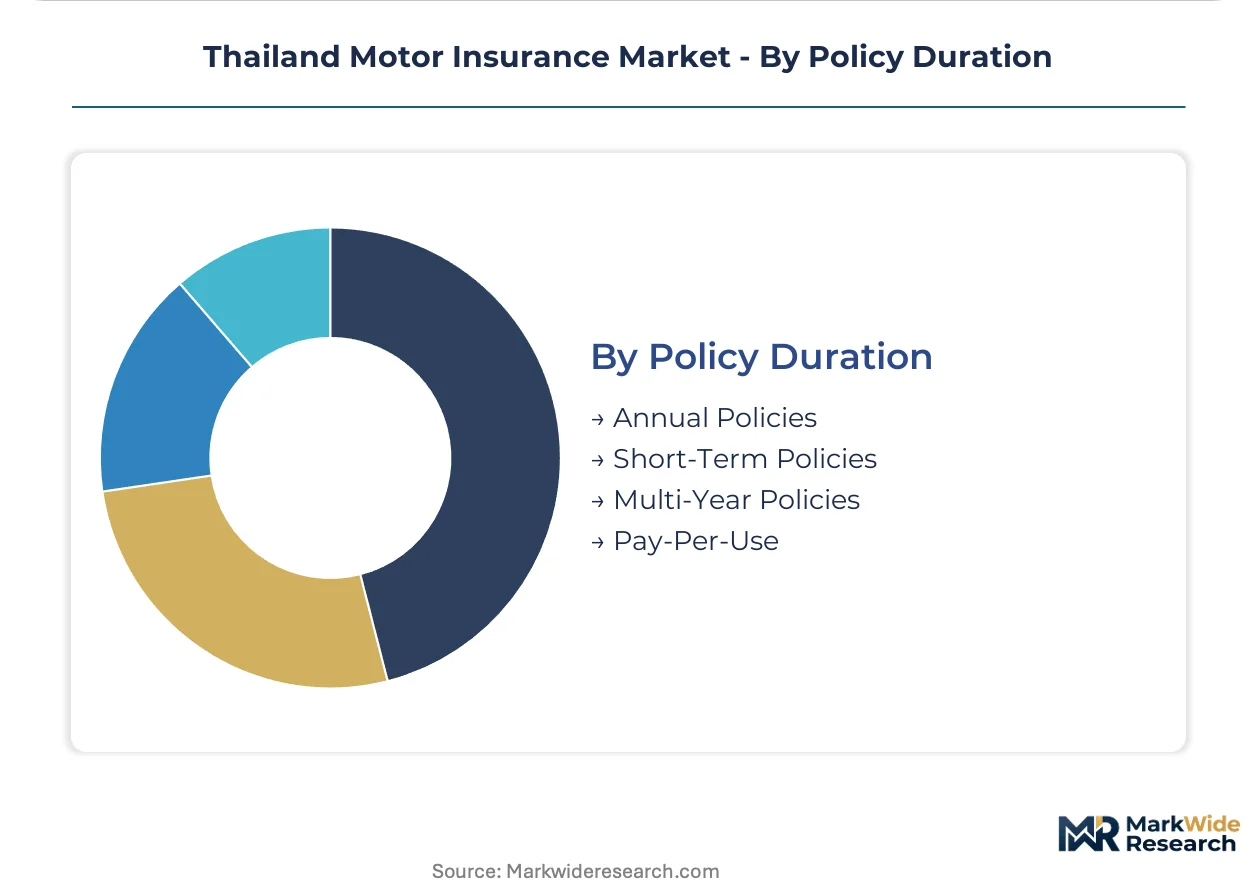
Thailand motor insurance segmentation reveals divergent profitability profiles across product structures and buyer configurations. Distribution channel selection and policy duration preferences increasingly determine customer lifetime value and acquisition cost efficiency for competing underwriters.
Product Type:
Buyers differentiate by risk tolerance and asset protection requirements, with premium outlay directly correlating to coverage breadth and claims flexibility.
- Comprehensive Coverage:Bundles physical damage, third-party liability, and occupant injury into single contracts with higher per-policy values. Bangkok's luxury vehicle owners and commercial fleet operators drive concentration here, attracted by zero-depreciation add-ons and preferred workshop networks.
- Third-Party Liability:Mandatory minimum coverage per OIC regulations with standardized rate floors limiting insurer discretion. Compliance-focused buyers in provincial markets dominate this segment, where price sensitivity exceeds feature demand.
- Fire and Theft:Narrow peril coverage targeting vehicle financing requirements and parking security concerns. Condo dwellers in dense urban districts show disproportionate uptake.
- Personal Accident:Occupant injury riders supplementing base motor policies. Grab and Bolt drivers purchasing gap coverage represent the expanding buyer pool.
Volume sits with Third-Party Liability; growth tilts toward Comprehensive Coverage.
Customer Type:
Scale of vehicle holdings and procurement sophistication separates buyers into distinct service tiers demanding tailored policy administration.
- Individual Owners:Single-vehicle households purchasing through agent relationships or direct channels. Smartphone-enabled comparison shopping is accelerating channel switching among Bangkok millennials.
- Fleet Owners:Logistics operators managing 10-plus vehicles requiring unified claims handling and telematics integration. E-commerce delivery contractors in the metropolitan corridor are expanding fastest.
- Car Dealerships:Volume intermediaries bundling coverage with vehicle financing. Showroom captive insurance penetration varies sharply by brand tier.
- Corporate Clients:Multi-department vehicle pools with centralized procurement and risk management mandates. Japanese manufacturing affiliates maintain strict coverage standards.
Individual Owners generate policy count; Fleet Owners command premium expansion.
Distribution Channel:
Channel selection reflects buyer age, digital literacy, and complexity tolerance, with commission structures varying threefold across pathways.
- Direct Sales:Insurer-owned branches and call centers serving established customers. Bangkok Insurance leverages 200-plus locations for policy issuance and claims submission.
- Brokers:Independent intermediaries comparing multiple underwriters for commercial accounts. Large fleet placements increasingly route through specialized motor brokers.
- Online Platforms:App-based comparison and instant purchase eliminating human intermediaries. Roojai and Frank.co.th are capturing urban comprehensive coverage buyers.
- Insurance Agents:Captive and independent representatives dominating rural province penetration. Viriyah Insurance maintains density advantages through exclusive agent networks.
Insurance Agents retain volume concentration; Online Platforms are climbing the fastest.
Policy Duration:
Duration preferences signal utilization patterns and liquidity constraints, with flexibility premiums compressing traditional annual policy economics.
- Annual Policies:Standard 12-month contracts with installment payment options. Remains the default for private vehicle owners seeking rate stability.
- Short-Term Policies:1-6 month coverage for temporary vehicle usage or seasonal commercial operations. Tourist rental fleets in Phuket and Pattaya drive seasonal demand spikes.
- Multi-Year Policies:2-3 year terms with locked rates and loyalty discounts. Corporate clients with predictable fleet composition favor this structure.
- Pay-Per-Use:Mileage-linked premiums calibrated via smartphone telematics. Gig-economy drivers with variable weekly hours are adopting this model.
Annual Policies dominate absolute volume; Pay-Per-Use shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy issuance concentrates in Bangkok and its surrounding metropolitan corridor, where vehicle density and commercial fleet activity generate disproportionate premium volume relative to provincial markets.
Bangkok Metropolitan Region
Luxury vehicle ownership and ride-hailing fleet operations drive comprehensive coverage demand. The Office of Insurance Commission enforces compulsory insurance linkage with Department of Land Transport registration renewals. Sukhumvit and Silom districts host dense clusters of insurance brokerages serving corporate fleet accounts.
Central Plains
Manufacturing-affiliated vehicle pools and logistics hubs anchor commercial policy growth. The OIC's 2024-2025 compliance sweep targets previously uninsured agricultural vehicles. Ayutthaya and Pathum Thani industrial zones attract Japanese manufacturing affiliates with strict coverage mandates.
Northern Region
Tourism rental fleets and cross-border logistics create seasonal demand spikes for short-term policies. The Department of Land Transport coordinates with provincial offices to verify coverage before registration sticker issuance. Chiang Mai's Grab and Bolt driver networks expand commercial vehicle counts annually.
Northeastern Region (Isan)
Compulsory insurance compliance gaps exceed fifteen percentage points below Bangkok levels, representing recoverable premium pools. The OIC directs enforcement resources toward Udon Thani and Khon Kaen vehicle registration centers. Rural agent networks maintain manual documentation processes with seven-to-fourteen-day processing lags.
Southern Region
Tourist rental operations in Phuket and Pattaya drive seasonal short-term policy demand. The OIC mandates electronic policy verification eliminating paper-policy gaps for registration renewals. Coastal provinces show accelerating smartphone-enabled policy comparison among younger buyers completing transactions without agent contact.
Thailand Motor Insurance Market Competitive Environment
Bangkok-based insurers anchor the dominant tier; regional specialists hold density advantages in provincial distribution. Market structure shows moderate consolidation around established domestic players with foreign-affiliated entrants competing through specialized segments. Three archetypes prevail: branch-network incumbents, digital-first challengers, and foreign-JV specialists. Competitive moves center on telematics integration partnerships and agent commission restructuring for digital channel parity.
Among domestic branch-network incumbents, Bangkok Insurance and The Viriyah Insurance occupy positions reflecting divergent geographic strategies—metropolitan density versus rural agent penetration. MSIG Insurance (Thailand) represents the foreign-affiliated specialist archetype, competing through commercial fleet product development. These three exemplify how capital deployment choices across physical versus digital infrastructure shape competitive positioning within OIC-regulated pricing constraints.
| Leading Market Players |
|---|
| Bangkok Insurance |
| MSIG Insurance (Thailand) |
| The Viriyah Insurance |
| Allianz Ayudhya General Insurance |
| AXA Insurance (Thailand) |
| Tokio Marine Insurance (Thailand) |
| Muang Thai Insurance |
| Chubb Samaggi Insurance |
| Dhipaya Insurance |
| Others |
Value Chain & Pricing Dynamics
Commercial fleet operators in Bangkok's logistics corridor anchor pricing power for comprehensive coverage products, with their demand for telematics-integrated policies forcing insurers toward subscription-style premium models tied to real-time utilization data.
Pricing Analysis
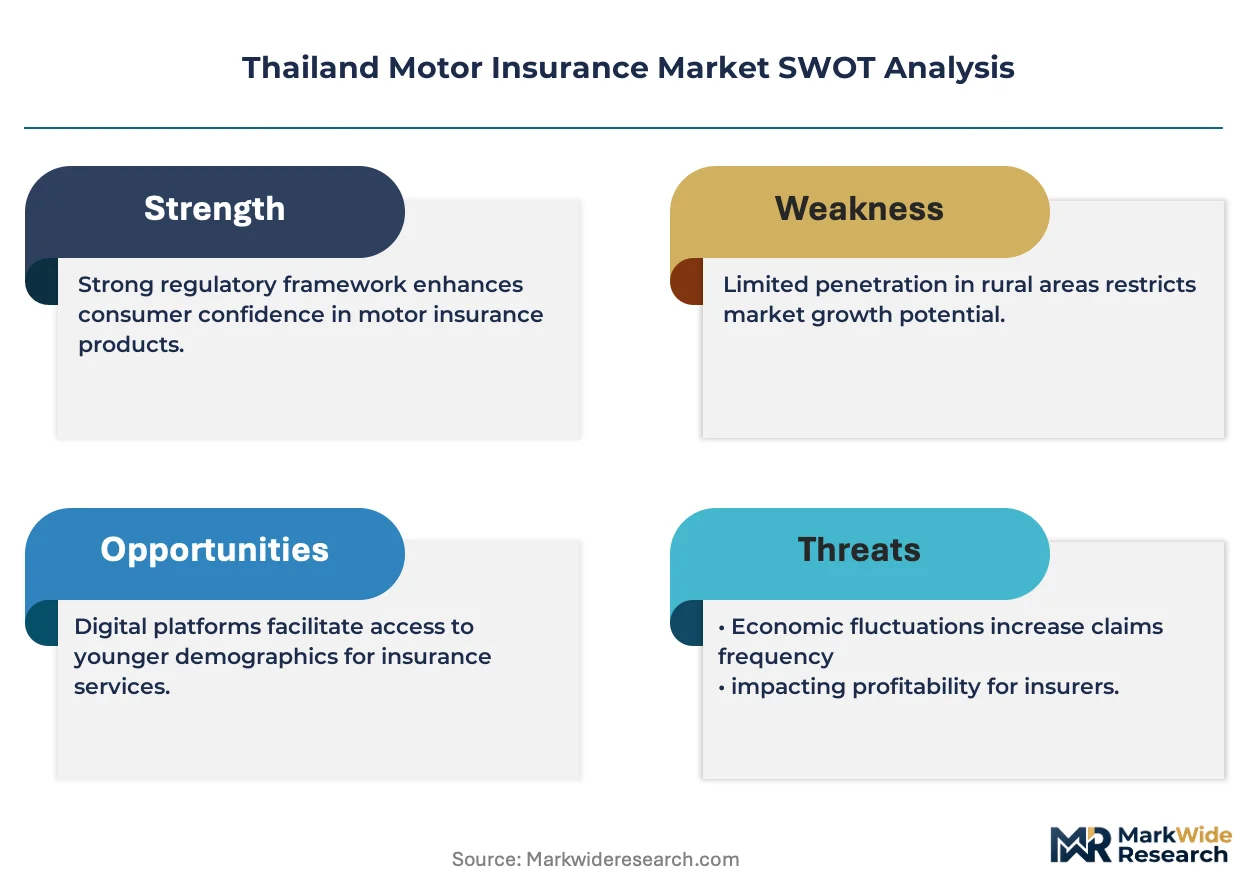
Short lead-time policy issuance commands premium pricing as the OIC's electronic verification mandate compresses processing windows to same-day completion. Three-tier pricing structure across premium, standard, and economy levels differentiates by telematics sophistication and claims service tier, with Bangkok Insurance and MSIG capturing the premium tier through dedicated account management. Price erosion runs through the compulsory third-party liability segment where OIC rate caps prevent risk-adjusted pricing for high-claim profiles. Individual owners in provincial markets show highest price sensitivity, while fleet operators prioritize service integration over per-policy cost.
Supply Chain Analysis
Telematics hardware supply rests on Taiwanese semiconductor fabricators and Chinese GPS module assemblers, with Thai insurers drawing firmware and cloud analytics from Singapore-based software vendors. Smartphone penetration rates and mobile network coverage in secondary cities determine distribution reach for app-based platforms. Single-source vulnerability concentrates in the telematics data pipeline where two Singaporean analytics providers serve the majority of domestic insurers. Distribution runs through captive agent networks in rural provinces and direct digital channels in metropolitan Bangkok, with broker intermediaries handling large commercial placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Thailand motor insurance market reads as a cost-of-compliance story where the OIC's compulsory enforcement framework and electronic verification mandate erect capital-intensive barriers that favor established players with legacy infrastructure already integrated to Department of Land Transport systems.
For Market Incumbents: Lock in telematics data partnerships before hardware costs commoditize, and accelerate agent commission restructuring to achieve digital channel pricing parity against Roojai and Frank.co.th. The threat of usage-based insurance platforms displacing annual renewal cycles demands preemptive investment in dynamic pricing engines. Vertical integration into proprietary telematics stacks offers sustainable differentiation. For New Entrants and Emerging Players: App-based policy comparison platforms represent the most penetrable route for bypassing Viriyah Insurance's rural agent density. Target Isan region compulsory insurance compliance gaps exceeding fifteen percentage points below Bangkok levels, where manual documentation lags create service failures incumbents struggle to address. A telematics-first value proposition for gig-economy drivers with variable weekly hours offers the clearest go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-tier insurers with existing OIC licensing and fragmented agent networks that digital infrastructure could consolidate. Five-to-ten-year viability hinges on telematics integration completion before pricing power shifts entirely to data-rich platforms. Watch for OIC relaxation of compulsory rate caps as the signal for margin expansion opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Unifies GPS tracking, driver scoring, and claims management into single premium engines for fleet operators. |
| Agent Commission Restructuring | Enables digital channel pricing parity by unbundling human intermediary costs from app-based transactions. |
| Isan Region Distribution Buildout | Captures recoverable premium pools where compulsory compliance gaps exceed Bangkok levels significantly. |
| Dynamic Pricing Algorithm Development | Compresses annual renewal cycles into mileage-linked adjustments tied to actual risk exposure patterns. |
| Electronic Verification Infrastructure | Satisfies OIC mandates for real-time coverage confirmation linked to Department of Land Transport databases. |
Study Parameters
Office of Insurance Commission regulatory filings, Department of Land Transport registration databases, and Thai General Insurance Association statistical releases formed the secondary backbone. Primary interviews with actuarial directors, commercial fleet procurement managers, and captive insurance agents validated segmentation assumptions. Bottom-up policy issuance data triangulated against top-down premium pool estimates from regulatory aggregates.
Historical trendline analysis across vehicle registration growth, ride-hailing fleet expansion, and telematics adoption curves informed the projection framework. Segmentation modeling covered product type, customer configuration, distribution channel, and policy duration preferences throughout the forecast period. CAGRs derived from regression analysis of premium volume against macroeconomic indicators and enforcement intensity variables.
Inputs from OIC and Department of Land Transport were available through the study window; gaps in real-time telematics utilization data introduce uncertainty bands around usage-based insurance growth trajectories. Forecasts reflect assumptions regarding regulatory enforcement continuity and smartphone penetration saturation. A small set of triggers—OIC rate cap adjustments, telematics hardware cost deflation, and agent network consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market