
 Brazil Car Insurance Market | 2026-2036
Brazil Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Car Insurance Market Insights
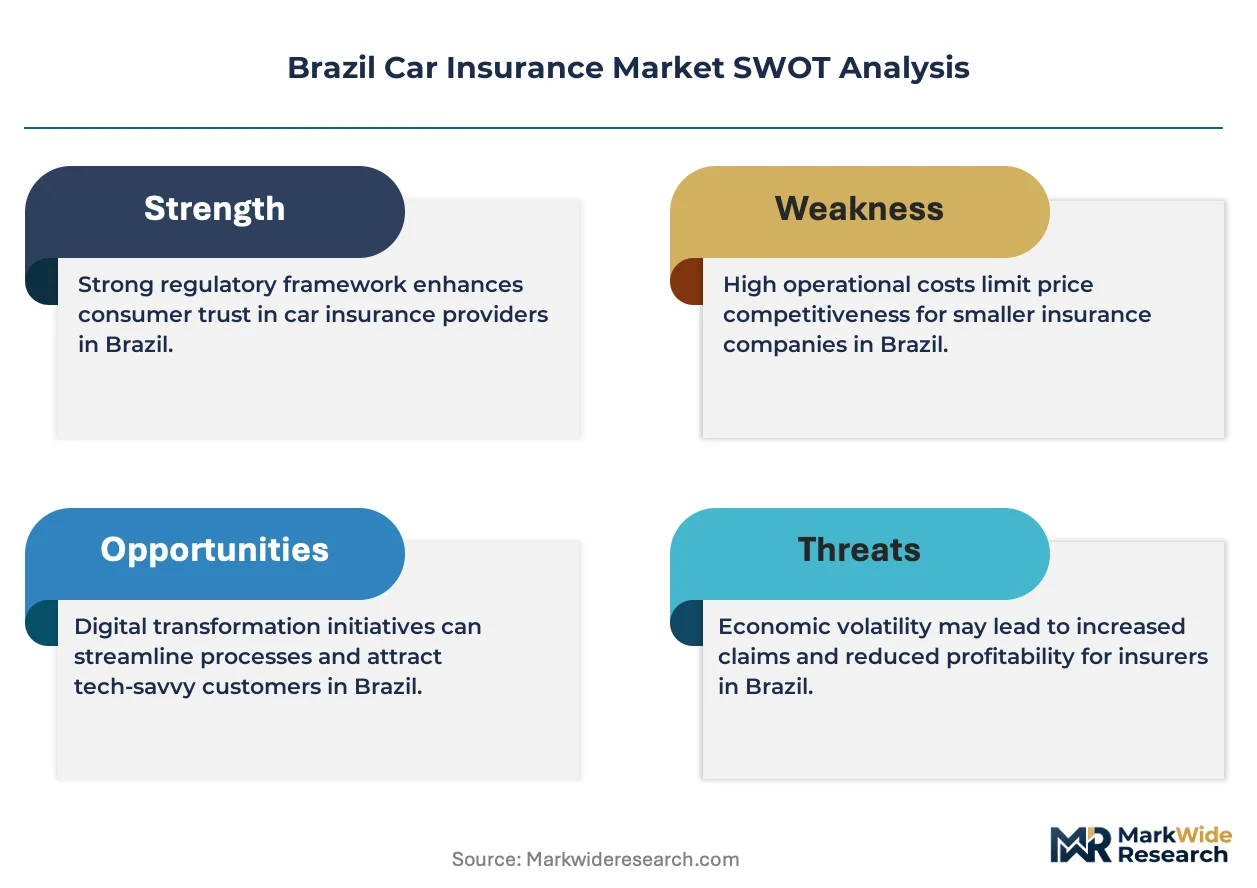
Telematics hardware is pivoting from optional add-ons to standard policy infrastructure across Brazilian portfolios. Porto Seguro leverages proprietary IoT platforms to refine risk-adjusted pricing granularity. Bradesco Seguros anchors its distribution through captive banking channels spanning thousands of physical branches. Tokio Marine competes on commercial fleet specialization, where loss-ratio engineering demands sustained actuarial investment.
Brazil car insurance constitutes a contractual risk-transfer mechanism indemnifying policyholders against vehicle damage, theft, third-party liability, and bodily injury, with premium calculations grounded in actuarial models incorporating driver history, geographic exposure, and vehicle technical specifications such as repair cost indices and anti-theft device ratings. The product's primary commercial purpose is to absorb financial volatility from automotive asset operation while satisfying compulsory third-party liability mandates. Liability coverage dominates policy volumes given federal compulsory requirements, while comprehensive segments command superior margins through elective protection against theft and collision. Pay-as-you-go structures are gaining traction among gig-economy drivers, though annual policies still occupy the core revenue base.
SUSEP, Brazil's private insurance superintendent, imposes capital reserve requirements and tariff flexibility boundaries that directly constrain pricing autonomy and product design scope. ANS and CONTRAN intersect with car insurance through occupational accident linkages and vehicle safety standard compliance, respectively. Stakeholders must monitor how SUSEP's open insurance initiative and evolving data-privacy interpretations reshape competitive access to driver-behavior datasets.
Market Dynamics
SUSEP's open insurance initiative is decentralizing data access across Brazilian underwriting pools, eroding the information asymmetry that historically protected incumbent pricing power. This regulatory pivot is compressing risk-assessment timelines while elevating capital adequacy burdens.
Growth Catalysts
- Telematics infrastructure:IoT-enabled vehicle monitoring is penetrating commercial fleets along São Paulo-Rio de Janeiro logistics corridors. Loss-ratio engineering now incorporates real-time driver-behavior telemetry.
- SUSEP solvency modernization:Tighter capital reserve requirements are filtering out undercapitalized regional underwriters. Market consolidation is concentrating premium volumes among scale-compliant carriers.
- Mandatory liability expansion:Federal compulsory coverage mandates are extending to motorcycle and light-commercial categories. Policy volumes are absorbing previously uninsured vehicle classes.
Market Restraints
- Reinsurance capacity concentration:Catastrophe exposure in Brazil's flood-prone coastal zones is tightening retrocession availability. Primary carriers face capacity rationing for comprehensive physical damage lines.
- Claims inflation in parts:Import-dependent vehicle repair networks are absorbing currency volatility. Loss-cost indices for collision coverage are outpacing premium adjustment frequencies.
- Data privacy friction:LGPD interpretations are constraining telematics data sharing between insurers and third-party analytics providers. Behavioral pricing models face consent-collection overhead.
Strategic Opportunities
- Northeast corridor penetration:Recife and Salvador metropolitan zones exhibit vehicle density growth without proportional coverage adoption. Digital-first distribution can capture underpenetrated middle-market segments.
- Pay-per-kilometer products:Usage-based structures align premium exposure with actual vehicle utilization. Gig-economy drivers and occasional-use households represent addressable white space.
- Embedded insurance integration:Auto finance and vehicle leasing platforms are opening captive distribution channels. Point-of-sale policy origination reduces customer acquisition friction.
Industry Challenges
- Actuarial talent scarcity:Brazilian universities produce insufficient quantitative risk specialists. Carriers compete for data-science competencies against fintech and banking sectors.
- Legacy system integration:Core policy administration platforms require costly modernization to support real-time telematics ingestion. Migration timelines extend 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Car Insurance Market |
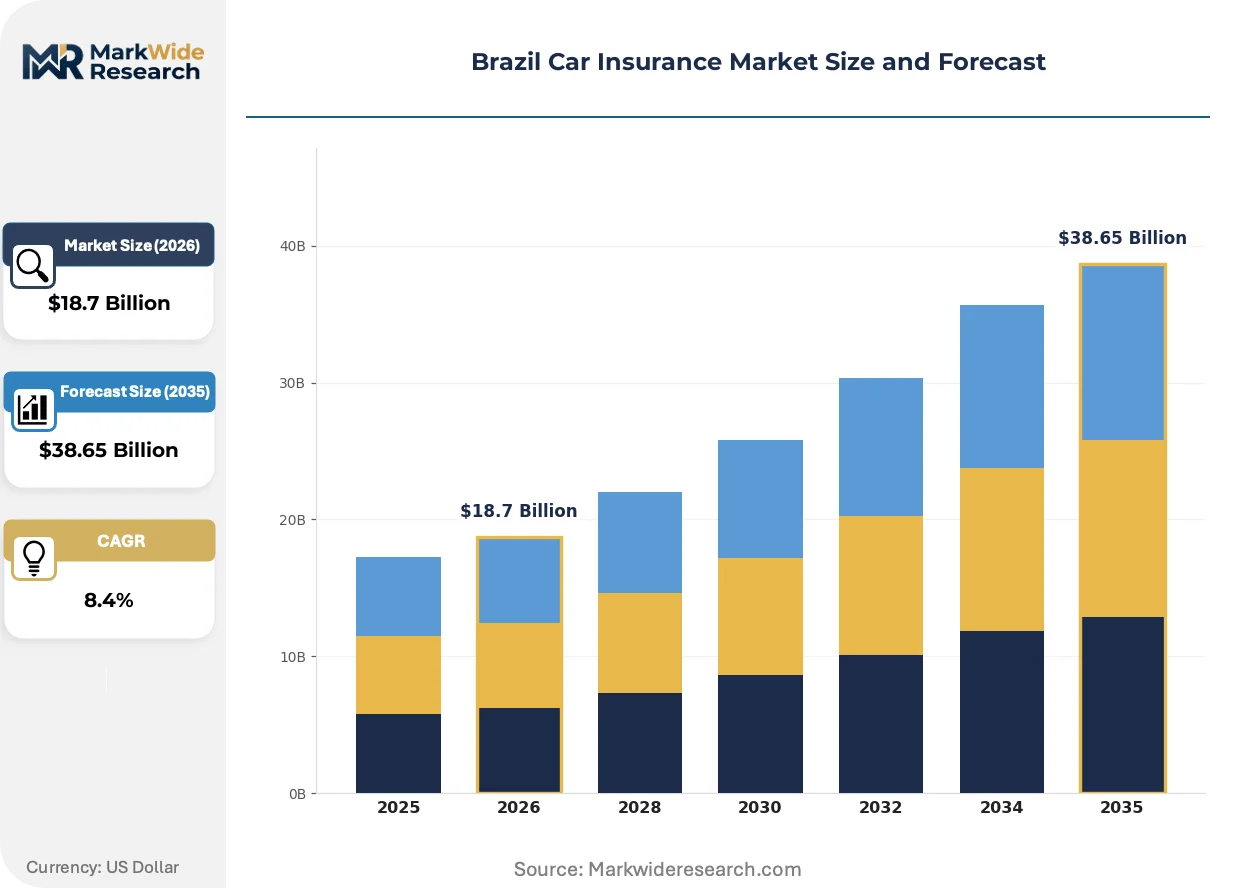
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Personal Injury Protection Customer Type: Individual Drivers, Fleet Owners, Corporate Clients, Car Rentals Policy Length: Short-Term, Annual, Multi-Year, Pay-As-You-Go Sales Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | Porto Seguro, Bradesco Seguros, Tokio Marine, Zurich Insurance Company, Mapfre, Allianz Global Corporate & Specialty, HDI, Santander Auto, Nubank Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Car Insurance Market Trends and Innovations
Telematics hardware is migrating from peripheral add-on to policy infrastructure core, compressing risk-assessment cycles while exposing incumbent carriers to data-platform competition from insurtech entrants.
Blockchain-enabled smart contracts are decentralizing claims settlement authority. Commercial fleet operators in Minas Gerais industrial zones are piloting parametric triggers for theft and total-loss events. This architecture is compressing indemnity payment cycles from weeks to hours while reducing loss-adjustment expenses.
SUSEP's open insurance regulatory framework is mandating standardized data portability across underwriting systems. Mid-tier carriers must rebuild policy administration architectures to comply with interoperability requirements. São Paulo-based commercial lines specialists are absorbing compliance costs faster than regional peers, widening technology investment gaps.
Subscription-based coverage models are displacing annual policy tenures among urban gig-economy drivers. Digital-native distribution platforms in Belo Horizonte and Curitiba are unbundling traditional agent commissions. This behavioral pivot is most visible in motorcycle delivery segments where vehicle utilization patterns demand flexible coverage windows.
Brazil Car Insurance Market Segmentation
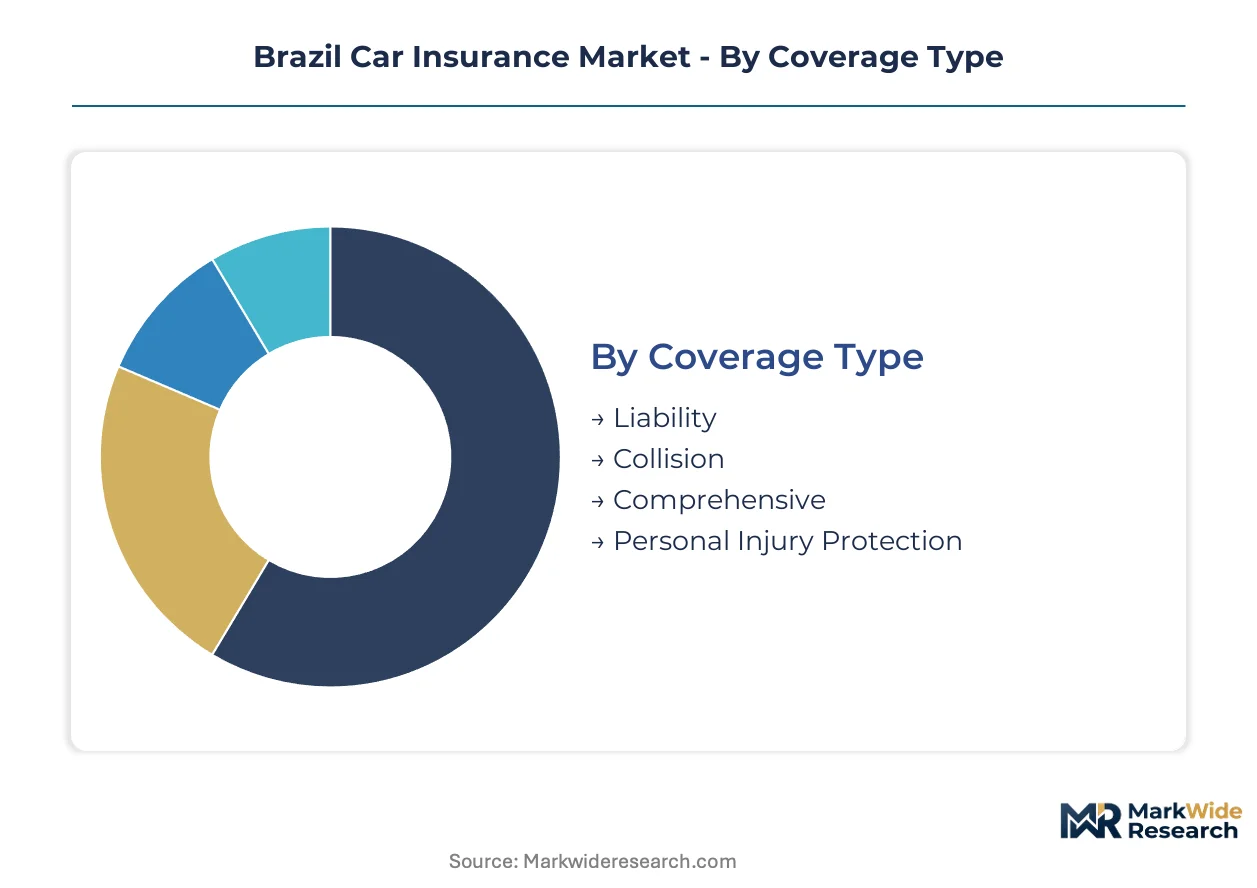
Segmentation in Brazil's car insurance market determines pricing granularity, distribution architecture, and capital reserve allocation. Underwriters align product design with risk profiles across coverage types, customer categories, policy tenures, and sales channels to optimize loss ratios and customer lifetime value.
Coverage Type:
Cost tier drives buyer selection, with compulsory mandates anchoring baseline adoption and elective protections commanding premium differentials.
- Liability:Federal compulsory coverage indemnifies third-party bodily injury and property damage. São Paulo's metropolitan corridor generates disproportionate policy volumes given vehicle density and enforcement concentration. SUSEP's tariff flexibility boundaries constrain pricing autonomy despite elevated claim frequency in dense urban zones.
- Comprehensive:Elective protection spans theft, fire, and natural catastrophe exposure. Demand concentrates in coastal flood-prone regions where reinsurance capacity rationing elevates premium loading factors. Anti-theft device ratings directly influence underwriting acceptability and deductible structures.
- Collision:Physical damage coverage for at-fault accidents carries import-dependent repair cost volatility. Currency fluctuations in parts procurement compress loss-cost adequacy timelines.
- Personal Injury Protection:Medical expense and disability coverage for occupants operates under ANS occupational accident linkages. Corporate fleet purchasers bundle this coverage with liability to satisfy CONTRAN compliance requirements.
Volume sits with Liability; growth tilts toward Comprehensive as vehicle financing penetration deepens collateral protection requirements.
Customer Type:
Application context shapes risk engineering, with commercial utilization patterns demanding telematics integration and individual policies favoring simplified underwriting.
- Fleet Owners:Commercial logistics operators along São Paulo-Rio de Janeiro corridors deploy IoT-enabled monitoring for loss-ratio engineering. Real-time driver-behavior telemetry informs risk-adjusted pricing granularity and claims prevention protocols.
- Individual Drivers:Personal vehicle coverage dominates policy count but exhibits higher lapse rates and price elasticity. Digital-native distribution platforms in Belo Horizonte and Curitiba capture this segment through unbundled commission structures.
- Corporate Clients:Multi-vehicle employers negotiate master policies with fleet safety program discounts. CONTRAN vehicle safety standard compliance intersects with coverage acceptability.
- Car Rentals:Short-term fleet utilization demands flexible coverage windows and rapid claims settlement. Blockchain-enabled smart contracts pilot in Minas Gerais industrial zones compress indemnity cycles.
Policy count concentrates with Individual Drivers; margin expansion tilts toward Fleet Owners as telematics infrastructure penetrates commercial corridors.
Policy Length:
Customer utilization frequency determines tenure preference, with gig-economy drivers rejecting annual commitments and traditional owners favoring price stability.
- Annual:Standard twelve-month tenure anchors core revenue base through premium upfront collection. SUSEP's open insurance initiative enables mid-term portability, elevating retention investment.
- Pay-As-You-Go:Usage-based structures align exposure with actual kilometer consumption. Motorcycle delivery segments in urban centers exhibit steepest expansion trajectory given irregular utilization patterns.
- Short-Term:Temporary coverage windows serve seasonal vehicle operation and cross-border transit. Digital platforms reduce origination friction for sub-annual tenures.
- Multi-Year:Extended commitments lock pricing against inflation but expose underwriters to loss-cost adequacy risk. SUSEP solvency modernization tightens reserve requirements for long-duration liabilities.
Premium volume concentrates with Annual; product innovation tilts toward Pay-As-You-Go as embedded insurance integration penetrates auto finance platforms.
Sales Channel:
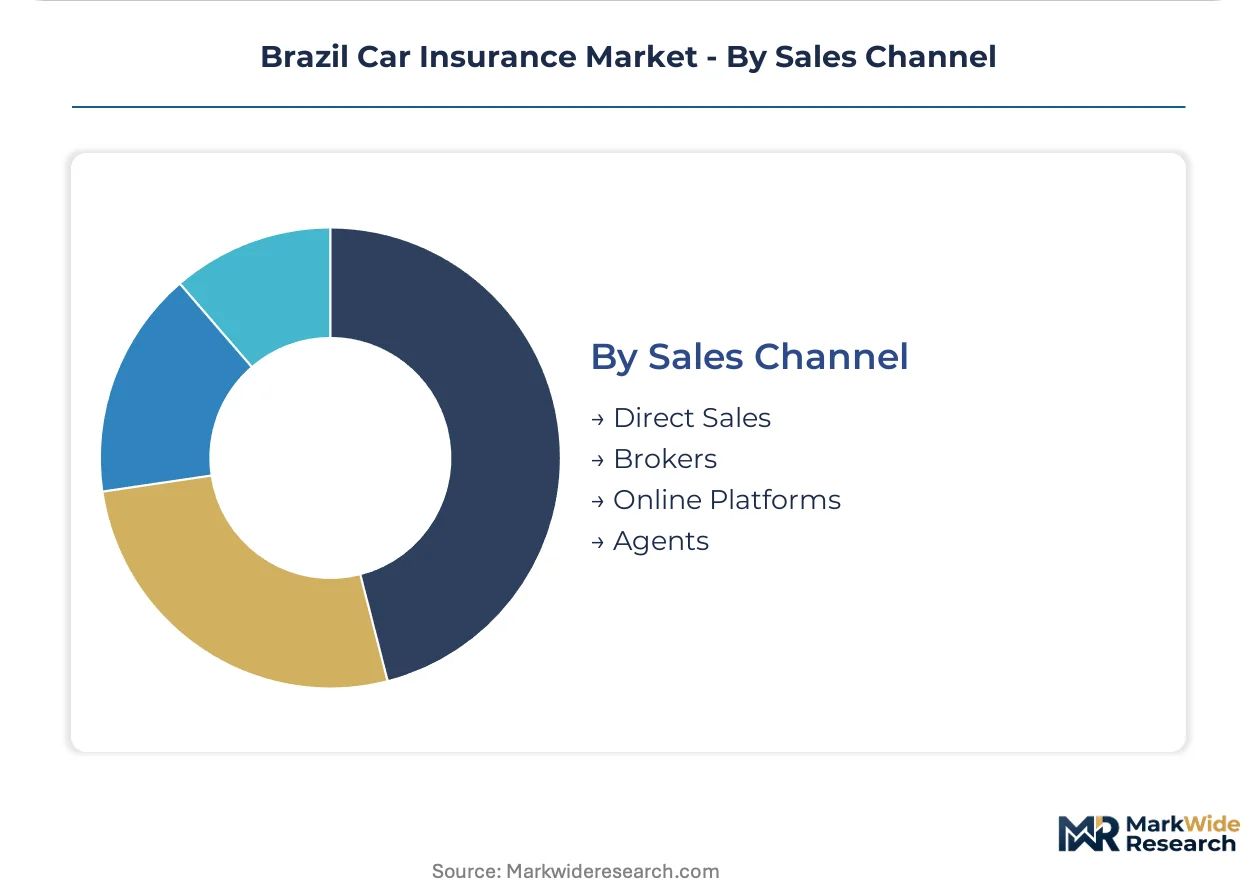
Distribution economics and customer acquisition cost differentiate channel performance, with digital platforms compressing friction and agent networks retaining complex commercial placement.
- Brokers:Independent intermediaries dominate commercial fleet placement and corporate risk structuring. Commission structures reflect policy complexity and renewal retention performance.
- Online Platforms:Digital-native distribution captures price-sensitive individual segments through algorithmic quoting and instant policy issuance. LGPD consent-collection overhead constrains behavioral data deployment.
- Agents:Captive and independent representatives maintain presence in underpenetrated Northeast corridor markets. Recife and Salvador metropolitan zones exhibit channel mix favoring personal consultation.
- Direct Sales:Insurer-controlled origination reduces distribution cost but requires brand investment and technology infrastructure. Porto Seguro's proprietary IoT platforms enable direct telematics policy binding.
Transaction volume concentrates with Brokers; channel expansion tilts toward Online Platforms as SUSEP's open insurance framework standardizes data portability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Manaus Free Trade Zone attracts electronics assembly for telematics hardware, concentrating device manufacturing in Amazonas state before distribution to underwriting centers nationwide.
São Paulo
SUSEP headquarters proximity shapes regulatory interpretation velocity for carriers headquartered in the metropolitan corridor. CONTRAN enforcement intensity peaks in this zone given vehicle density metrics. São Paulo-Rio de Janeiro logistics corridors host the densest commercial fleet telematics deployments.
Minas Gerais
Industrial mining fleets generate specialized commercial coverage demand with elevated third-party liability exposure. ANVISA occupational accident linkages intersect with CONTRAN vehicle safety mandates for heavy equipment operators. Belo Horizonte digital-native distribution platforms pilot subscription-based motorcycle coverage.
Rio Grande do Sul
Porto Alegre automotive manufacturing clusters create captive insurance demand through supplier network vehicle fleets. SUSEP solvency modernization filters undercapitalized regional underwriters faster here than in northern states. Flood-prone coastal zones tighten reinsurance capacity availability for comprehensive physical damage lines.
Bahia
Salvador metropolitan expansion outpaces proportional coverage adoption, creating white space for digital-first distribution. LGPD consent-collection overhead constrains telematics data deployment in emerging broker networks. Recife and Salvador corridors exhibit vehicle density growth without matching premium volume expansion.
Paraná
Curitiba logistics hubs anchor cross-border commercial fleet operations demanding flexible coverage tenures. SUSEP open insurance data portability requirements accelerate technology investment gaps between capital-compliant carriers and regional peers. Agricultural vehicle seasonal utilization patterns favor pay-per-kilometer product experimentation.
Brazil Car Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with banking-captive distribution channels commanding individual policy volumes while commercial fleet specialists concentrate margin extraction. Market structure tilts toward consolidation as SUSEP solvency modernization filters undercapitalized regional underwriters. Three archetypes dominate: banking-integrated carriers leveraging branch infrastructure, telematics-native specialists engineering loss-ratio granularity, and international commercial lines underwriters with reinsurance capacity access. Competitive moves concentrate on embedded insurance integration with auto finance platforms and proprietary IoT platform development.
Among banking-integrated carriers, Bradesco Seguros and Santander Auto exemplify the captive distribution archetype through thousands of physical branch touchpoints. Porto Seguro anchors the telematics-native tier with proprietary IoT platforms enabling direct policy binding and real-time risk-adjusted pricing. Tokio Marine represents international commercial specialization, where sustained actuarial investment supports fleet loss-ratio engineering.
| Leading Market Players |
|---|
| Porto Seguro |
| Bradesco Seguros |
| Tokio Marine |
| Zurich Insurance Company |
| Mapfre |
| Allianz Global Corporate & Specialty |
| HDI |
| Santander Auto |
| Nubank Auto |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent concentration in São Paulo's metropolitan corridor feeds labor-cost differentials into pricing-tier spreads, with carriers headquartered near SUSEP headquarters absorbing compliance overhead faster than regional peers.
Pricing Analysis
Volume concentrates with compulsory liability coverage anchoring policy counts, while margin extraction tilts toward comprehensive segments where reinsurance loading factors and anti-theft device ratings create premium differentiation. Three-tier pricing structure across premium, standard, and economy levels separates fleet telematics-enabled policies from traditional annual coverage and basic mandatory liability. Cost compression in collision coverage is intensifying because import-dependent repair networks absorb currency volatility in parts procurement. Individual drivers exhibit highest price elasticity, while commercial fleet purchasers demonstrate lowest sensitivity given CONTRAN compliance requirements and bundled safety program discounts.
Supply Chain Analysis
Direct-to-OEM channels handle captive insurance demand through auto finance platforms, while broker networks retain complex commercial fleet placement requiring loss-ratio engineering consultation. Telematics hardware manufacturing concentrates in Amazonas state's Manaus Free Trade Zone, with device assembly drawing from semiconductor inputs originating in Taiwan, South Korea, and China. Reinsurance capacity for comprehensive physical damage lines rests on retrocession availability from international markets, exposing primary carriers to single-source vulnerability when catastrophe events tighten capacity. Distribution runs through banking-captive branches, independent broker networks, and digital-native platforms in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's car insurance sector sits in a technology-transition phase where telematics infrastructure is displacing legacy annual-policy underwriting, with SUSEP's open insurance initiative accelerating data-platform competition.
For Market Incumbents: Anchor proprietary IoT platform development to defend pricing granularity against insurtech entrants leveraging SUSEP-mandated data portability. Prioritize backward integration into telematics hardware sourcing from Manaus Free Trade Zone assembly to reduce device procurement exposure. Accelerate legacy policy administration modernization to support real-time telemetry ingestion before compliance deadlines filter undercapitalized peers.
For New Entrants and Emerging Players: Enter via digital-first distribution targeting Salvador and Recife metropolitan zones where vehicle density growth outpaces proportional coverage adoption. Capture motorcycle delivery segments through pay-per-kilometer subscription models addressing gig-economy utilization patterns. Partner with embedded insurance platforms at point-of-sale auto finance origination to reduce customer acquisition friction against established banking-captive channels.
For Investors and Strategic Acquirers: Re-rating potential sits with telematics-native specialists given SUSEP solvency modernization filtering regional underwriters and concentrating premium volumes among scale-compliant carriers. Long-term viability favors carriers with demonstrated loss-ratio engineering in commercial fleet segments and proprietary data platform architecture. Monitor SUSEP's evolving open insurance data-privacy interpretations as inflection indicator for competitive access to driver-behavior datasets.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary IoT Platform Development | Porto Seguro's direct policy binding capability demonstrates pricing granularity defense against insurtech competition. |
| Embedded Insurance Integration | Point-of-sale origination through auto finance platforms reduces acquisition friction versus traditional broker channels. |
| Pay-Per-Kilometer Product Launch | Usage-based structures align premium exposure with actual vehicle utilization for gig-economy driver segments. |
| Backward Integration into Telematics Hardware | Manaus Free Trade Zone assembly proximity reduces device procurement cost volatility and supply chain risk. |
| Northeast Corridor Digital Distribution Expansion | Salvador and Recife metropolitan zones exhibit underpenetrated middle-market segments addressable through algorithmic quoting. |
Research Methodology
Document review covered SUSEP regulatory filings, ANVISA occupational accident linkage documentation, and CONTRAN vehicle safety mandate updates, complemented by interviews with underwriting executives at national carriers, actuarial directors, SUSEP compliance officers, commercial fleet risk managers, and digital distribution platform operators. Secondary validation drew from insurance superintendent statistical bulletins, reinsurance market capacity reports, telematics hardware trade data, and automotive sector production databases. Bottom-up policy volume modeling and top-down premium aggregation were cross-referenced for triangulation.
Historical loss-ratio trends were cross-referenced against panel input from underwriting specialists to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include coverage type, customer category, policy tenure structure, and sales channel architecture, with additional granularity for telematics-enabled versus traditional underwriting. CAGRs were derived through regression analysis of premium volume trajectories, incorporating SUSEP solvency modernization timelines and fleet telematics penetration curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under catastrophic flood events tightening reinsurance availability or LGPD interpretations constraining behavioral data deployment. Forecasts reflect assumptions regarding SUSEP regulatory implementation velocity, telematics hardware cost curves, and currency stability in parts procurement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Personal Auto Insurance Market