
 Bangladesh Motor Insurance Market | 2026-2036
Bangladesh Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Motor Insurance Market Outlook
Fleet operator consolidation across Bangladesh's logistics and ride-sharing sectors is decoupling premium growth from individual owner expansion. Green Delta Insurance Company Limited leverages its digital distribution platform to capture fleet accounts in Dhaka and Chittagong. Sadharan Bima Corporation anchors the compulsory third-party segment through its statutory monopoly on basic motor coverage. Eastern Insurance Company Limited differentiates via specialized commercial vehicle products for heavy freight operators.
Bangladesh motor insurance constitutes risk-transfer contracts covering physical damage, third-party liability, and theft loss for motorized road vehicles, with policies typically specifying insured declared value, depreciation schedules, and no-claim bonus parameters. These instruments indemnify owners and operators against collision, fire, and legal liability arising from vehicle use across national highways and urban road networks. Comprehensive coverage leads policy type segmentation due to broader protection scope, while pay-as-you-go models within coverage duration segments attract digitally active ride-sharing drivers seeking variable cost structures. Fleet operators within customer type segmentation generate disproportionate premium volumes through negotiated group policies and telematics-linked risk assessments.
The Bangladesh Road Transport Authority enforces compulsory motor third-party insurance under the Motor Vehicles Ordinance, while the Insurance Development and Regulatory Authority supervises solvency ratios and policy form approvals across non-life underwriters. Bangladesh Bank's prudential guidelines for insurers constrain capital allocation and reinsurance arrangements, shaping product availability and pricing floors. Stakeholders must monitor regulatory digitization mandates and telematics data governance frameworks as these will determine underwriting model viability and distribution channel economics.
Market Dynamics
Fleet consolidation across Dhaka and Chittagong is restructuring premium distribution, as group policies negotiated by logistics operators and ride-sharing platforms displace individual owner coverage. The Bangladesh Road Transport Authority's enforcement tightening on compulsory third-party liability accelerates this shift toward centralized underwriting relationships.
Growth Catalysts
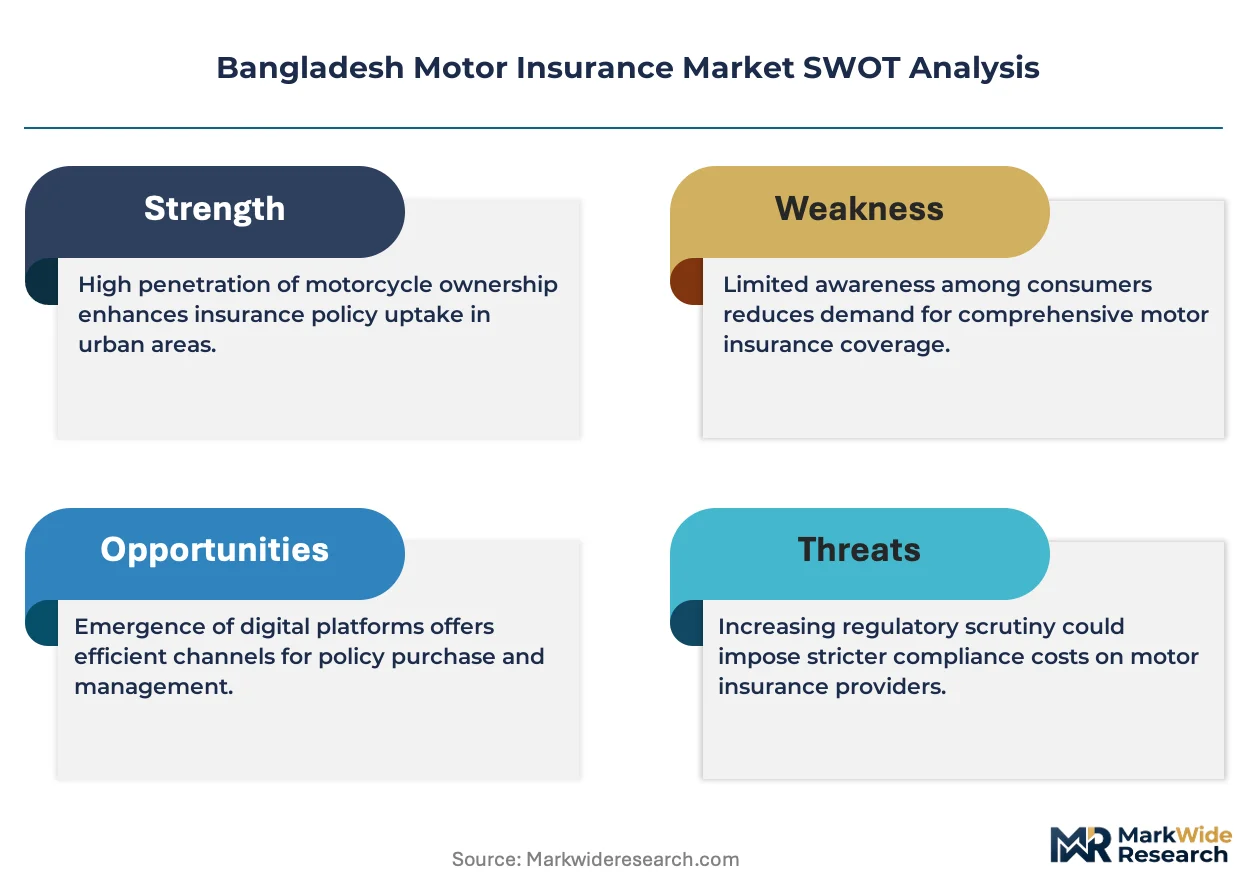
- Mandatory Third-Party Liability:The Motor Vehicles Ordinance enforcement by the Bangladesh Road Transport Authority compels commercial vehicle registration compliance, expanding the addressable policy base.
- Telematics Integration:GPS-linked risk assessment tools enable usage-based pricing models that attract digitally active ride-sharing drivers seeking variable premium structures.
- Dhaka-Chittagong Industrial Corridor:Freight volume concentration along this route generates disproportionate demand for commercial vehicle coverage among heavy logistics operators.
Market Restraints
- Reinsurance Dependency:Bangladesh Bank's prudential capital constraints force domestic underwriters to cede significant premium portions to international reinsurers, compressing retained margins.
- Claims Settlement Infrastructure:Sparse garage networks and assessor availability outside major urban centers delay physical damage claim resolution, elevating operational costs.
- Depreciation Schedule Rigidity:Fixed insured declared value calculations fail to capture real-time vehicle valuation swings, creating coverage gaps during inflationary periods.
Strategic Opportunities
- Micro-Insurance Penetration:Rural two-wheeler and three-wheeler segments remain underserved, offering scalable premium volume through mobile distribution channels.
- Green Vehicle Incentives:Government electric vehicle adoption frameworks may create preferential premium tiers for battery-powered commercial fleets.
- API-Enabled Embedded Distribution:Partnerships with ride-hailing and logistics platforms allow policy issuance at point-of-transaction, capturing drivers during onboarding workflows.
Industry Challenges
- Actuarial Talent Scarcity:Limited domestic expertise in telematics data modeling constrains refined risk-pricing development for usage-based products.
- Legacy System Integration:Core policy administration platforms at established underwriters resist seamless API connectivity with external distribution partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Motor Insurance Market |
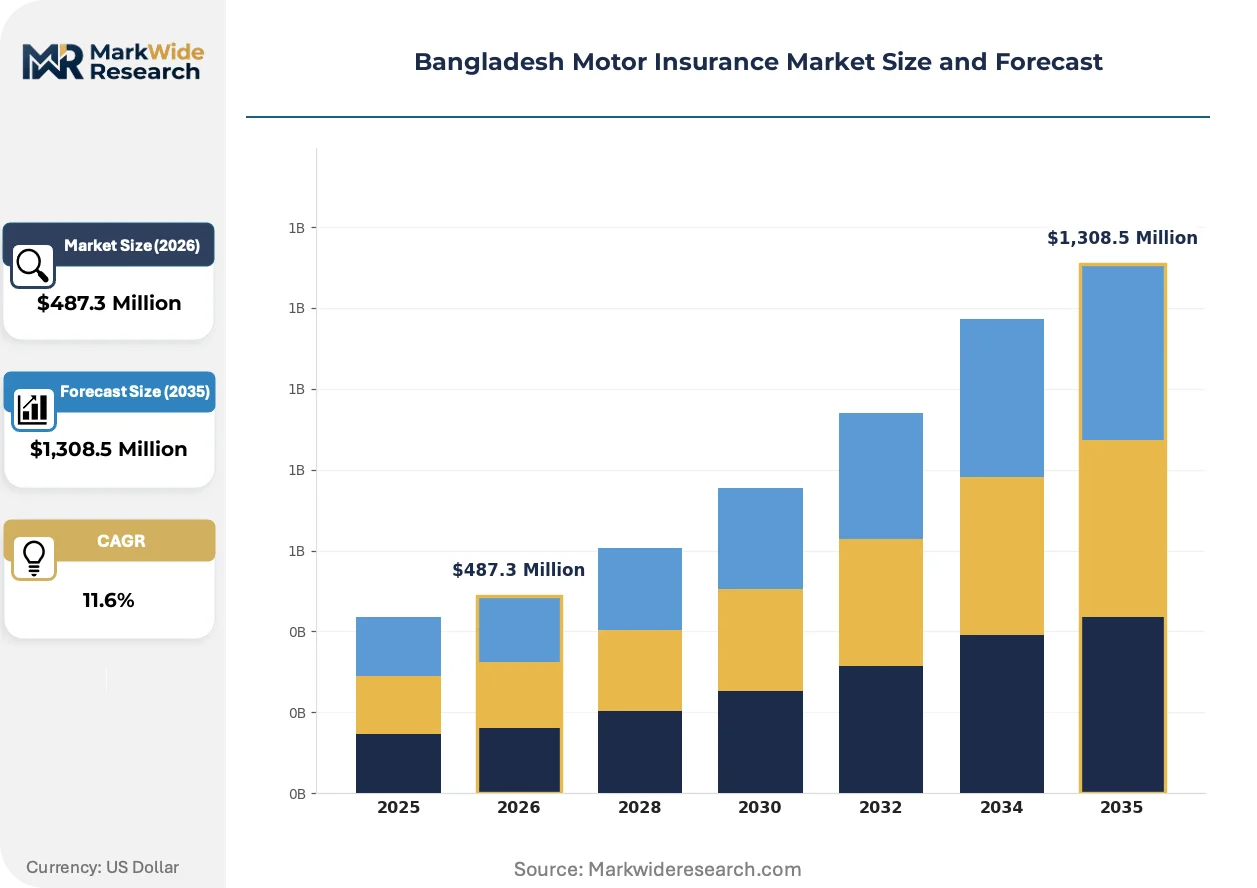
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party, Fire and Theft, Own Damage Customer Type: Individual Owners, Fleet Operators, Commercial Vehicles, Ride-sharing Services Coverage Duration: Annual, Short-term, Multi-year, Pay-as-you-go Distribution Channel: Brokerage Firms, Direct Sales, Online Portals, Agents |
| Companies Covered | Eastern Insurance Company Limited, Rupali Insurance Company Limited, Phoenix Insurance Company Limited, Sadharan Bima Corporation, Green Delta Insurance Company Limited, Peoples Insurance Company Limited, Asia Insurance Limited, Eastland Insurance Company Limited, Reliance Insurance Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Motor Insurance Market Strategic Shifts
Digital distribution infrastructure is compressing policy issuance timelines from days to minutes, while data-driven underwriting models replace experience-rated pricing. These shifts are reconfiguring channel economics and carrier competitive positioning.
Telematics-enabled usage-based insurance is overtaking traditional annual premium models among commercial fleet operators. GPS and accelerometer data streams allow real-time risk scoring that adjusts premiums to actual driving behavior. Dhaka-based logistics companies with dense vehicle deployments adopt these instruments fastest, as their scale justifies hardware installation costs and data analytics overhead.
The Insurance Development and Regulatory Authority's digitization mandates are accelerating policy form standardization and electronic record-keeping requirements. This regulatory pressure forces smaller underwriters to modernize core systems or exit direct distribution. The compulsory third-party segment faces the steepest compliance burden, as Sadharan Bima Corporation's statutory role requires parallel legacy and digital platform maintenance.
Fleet procurement of insurance is consolidating through employer-sponsored group schemes rather than individual driver purchases. Ride-sharing platforms and logistics operators now bundle coverage into driver contracts, displacing traditional agency channel relationships. This concentration is most visible in Chittagong port logistics, where container haulage contractors negotiate master policies covering hundreds of vehicles under single risk assessments.
Bangladesh Motor Insurance Market Segmentation
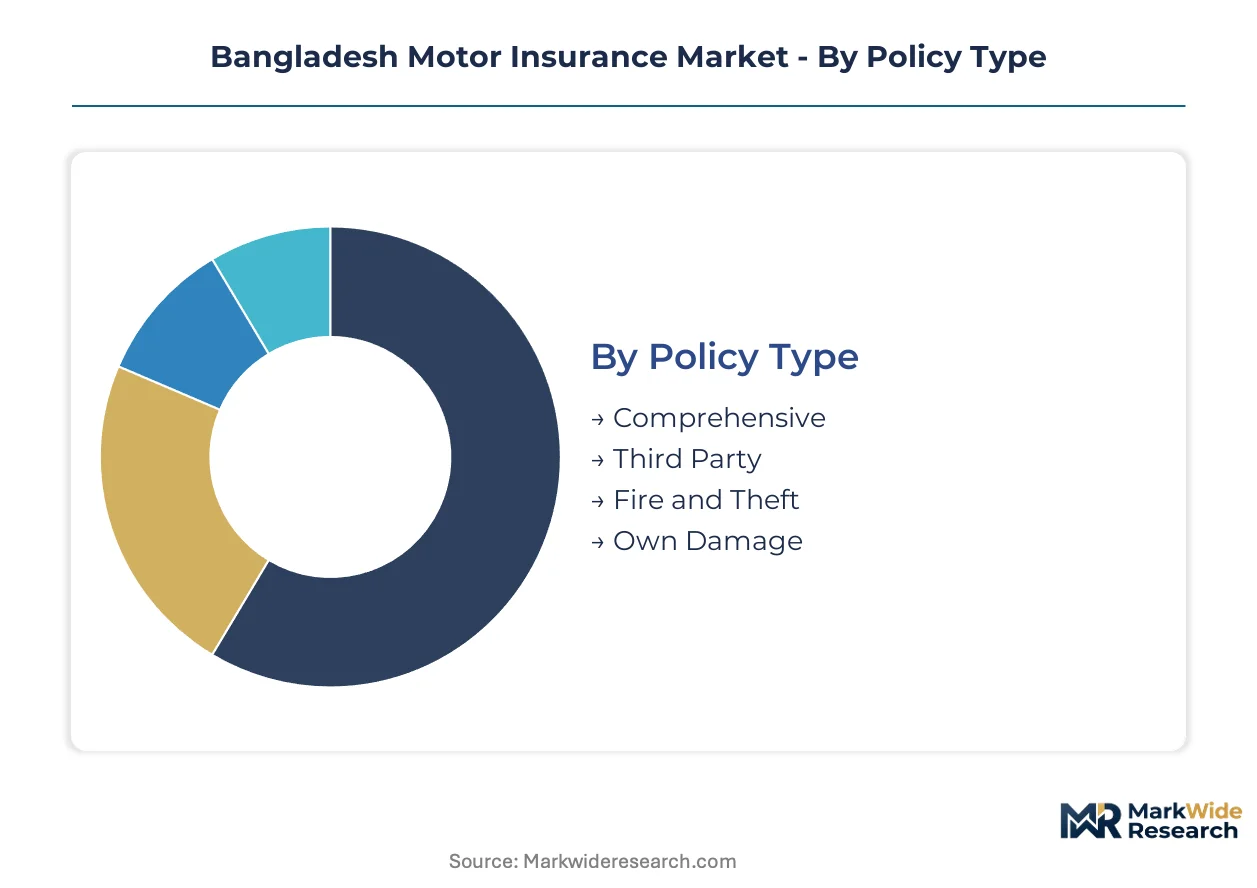
Fleet operators and ride-sharing platforms in Dhaka and Chittagong are consolidating procurement decisions, reshaping how coverage types and distribution channels compete. Understanding these segment boundaries clarifies where underwriting investments concentrate and where digital distribution yields leverage.
Policy Type:
Buyers weigh protection breadth against premium outlay, with commercial operators prioritizing liability limits and individual owners responding to no-claim bonus structures.
- Comprehensive:Bundles physical damage, third-party liability, and theft protection under single declarations. Fleet operators along the Dhaka-Chittagong corridor negotiate these policies at scale, leveraging telematics data to secure experience-rated discounts from underwriters.
- Third Party:Statutorily mandated minimum coverage satisfying Motor Vehicles Ordinance requirements. Sadharan Bima Corporation dominates this segment through its compulsory monopoly, though enforcement tightening by the Bangladesh Road Transport Authority expands compliance-driven purchases among unregistered commercial vehicles.
- Fire and Theft:Limited peril coverage excluding collision liability. Garment sector logistics operators in Ashulia and Narayanganj favor this tier for older fleet assets where comprehensive premiums exceed vehicle residual value.
- Own Damage:Collision and accidental damage protection excluding third-party claims. Individual sedan owners in Gulshan and Banani commercial districts select this midpoint between statutory minimum and full comprehensive coverage.
Volume sits with Third Party due to regulatory compulsion; growth tilts toward Comprehensive as fleet consolidation accelerates.
Customer Type:
Risk concentration and purchasing power determine carrier sales force deployment and pricing model sophistication.
- Individual Owners:Fragmented demand across private cars, motorcycles, and personal-use microbuses. Dhaka's middle-class vehicle owners drive this segment through agency channel relationships and no-claim bonus accumulation.
- Fleet Operators:Centralized procurement of group policies covering dozens to hundreds of vehicles. Chittagong port logistics contractors and Dhaka-based e-commerce delivery networks generate disproportionate premium volumes through master policy structures.
- Commercial Vehicles:Heavy freight operators, construction equipment fleets, and intercity bus companies. The Bangladesh Road Transport Authority's fitness certificate renewal requirements tie coverage validity to operating permits.
- Ride-sharing Services:Platform-mediated driver pools requiring standardized coverage for passenger liability. Pathao and Uber Bangladesh bundle insurance into driver onboarding, displacing individual policy purchases.
Premium concentration favors Fleet Operators; expansion is steepest in Ride-sharing Services as platform economics mature.
Coverage Duration:
Cash flow predictability versus flexibility shapes buyer preferences across vehicle utilization patterns.
- Annual:Standard policy term with depreciation-adjusted renewal pricing. Established underwriters at Green Delta and Eastern Insurance anchor retention strategies around this duration tier.
- Short-term:Three-to-six month coverage for seasonal agricultural transport and construction project vehicles. Rangpur and Rajshahi districts generate demand during harvest and infrastructure construction windows.
- Multi-year:Locked premium structures hedging against tariff inflation. Corporate fleet managers in export-oriented garment logistics favor this duration for budget certainty.
- Pay-as-you-go:Telematics-linked variable pricing based on mileage and driving behavior. Digitally active ride-sharing drivers in Dhaka's Gulshan and Uttara zones adopt this model fastest.
Annual coverage dominates transaction count; pay-as-you-go gains share fastest as GPS infrastructure penetrates commercial fleets.
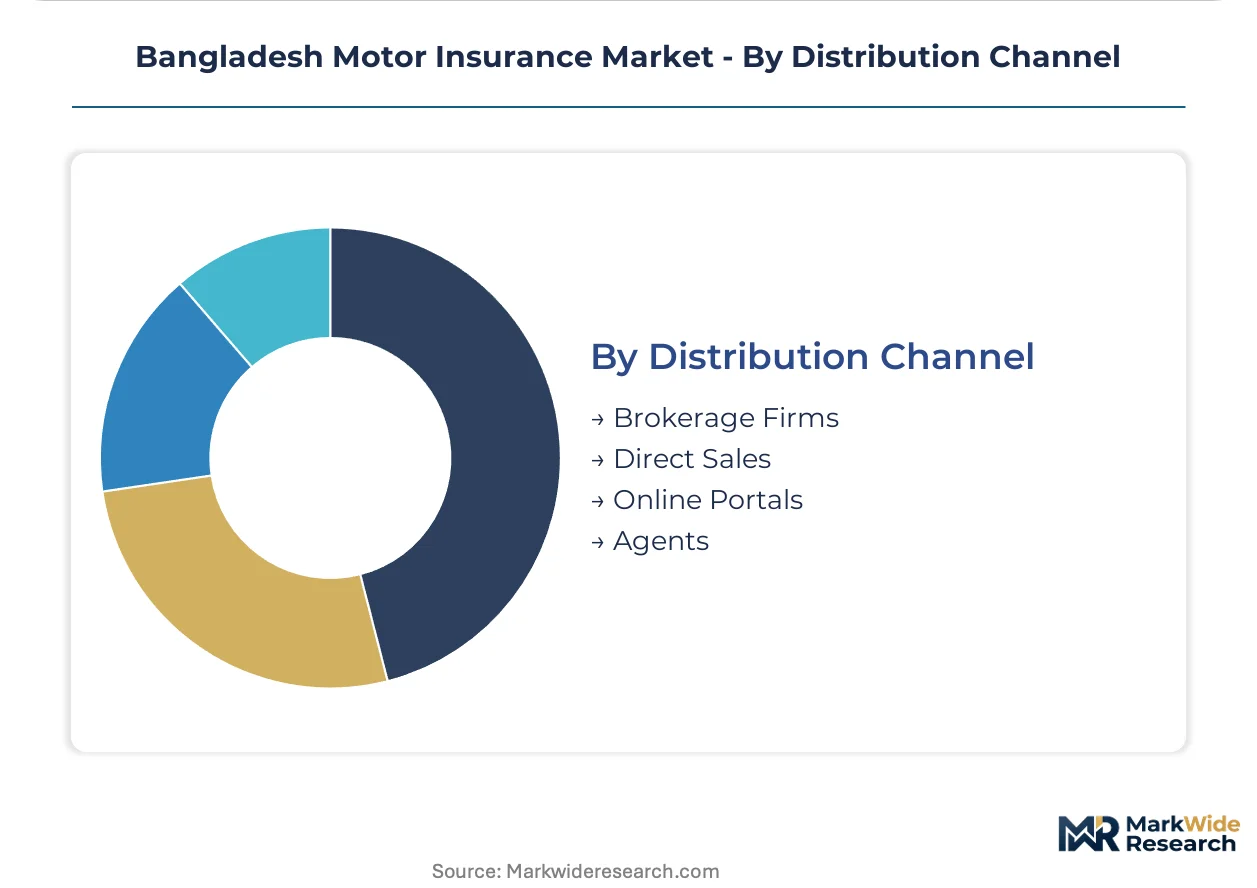
Distribution Channel:
Channel economics and customer acquisition cost dictate underwriter resource allocation across urban and rural geographies.
- Brokerage Firms:Intermediary networks placing coverage for corporate accounts and high-value commercial risks. Dhaka's Motijheel commercial district hosts concentrated broker activity serving listed companies.
- Direct Sales:Carrier-employed representatives targeting large fleet accounts without commission splits. Sadharan Bima Corporation maintains extensive direct sales infrastructure for compulsory third-party enforcement.
- Online Portals:Digital policy issuance and renewal platforms. Green Delta Insurance Company's distribution platform captures digitally literate urban buyers seeking instant quotation and document delivery.
- Agents:Commission-based individual producers serving neighborhood-level vehicle owners. Small towns across Sylhet and Khulna divisions rely on agent relationships for claims assistance and premium collection.
Transaction volume flows through Agents; Online Portals climb fastest as smartphone penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka's financial district anchors premium generation, while Chittagong's port corridor concentrates commercial vehicle risk pools. The Bangladesh Road Transport Authority's enforcement networks extend regulatory reach across divisional boundaries.
Dhaka Division
Ride-sharing platforms and e-commerce logistics fleets generate concentrated policy demand across Gulshan, Uttara, and Motijheel commercial zones. The Insurance Development and Regulatory Authority's solvency oversight applies uniformly across underwriters headquartered in the capital. Green Delta Insurance Company Limited's digital platform captures urban fleet accounts through instant quotation infrastructure.
Chittagong Division
Container haulage contractors and port logistics operators negotiate master policies covering heavy freight vehicle deployments. The Bangladesh Road Transport Authority's fitness certificate requirements tie operating permits to valid third-party coverage. Patenga and Anwara industrial zones host dense commercial vehicle registrations serving the Chittagong Port Authority's cargo throughput.
Rajshahi Division
Seasonal agricultural transport and construction project vehicles drive short-term coverage demand during harvest and infrastructure windows. Agent networks in Bogra and Naogaon districts collect premiums and process claims for rural motorcycle and microbus owners. The Bangladesh Road Transport Authority's regional enforcement checkpoints accelerate compliance-driven policy purchases.
Sylhet Division
Remittance-funded private vehicle acquisitions expand comprehensive coverage uptake among middle-class households in Sylhet city and surrounding towns. Commission-based agent relationships dominate distribution, with neighborhood producers handling renewal collections and documentation. The Bangladesh Bank's prudential guidelines constrain capital allocation for regional underwriters serving this geography.
Khulna Division
Industrial freight operators serving Mongla Port and Khulna shipyard clusters generate commercial vehicle insurance demand. The Bangladesh Road Transport Authority's intercity bus route licensing ties coverage validity to passenger transport permits. Jessore and Kushtia districts exhibit growing two-wheeler and three-wheeler micro-insurance penetration through mobile distribution pilots.
Bangladesh Motor Insurance Market Competitive Environment
Established underwriters occupy the standard tier; emerging digital entrants pursue API-enabled distribution partnerships. The market structures around statutory monopoly provision, private comprehensive coverage, and specialized commercial vehicle underwriting. Three archetypes dominate: state-mandated compulsory insurers, digitally integrated private carriers, and legacy generalists with branch networks. Competitive moves concentrate on telematics integration and fleet account consolidation through master policy structures.
Within the statutory tier, Sadharan Bima Corporation anchors compulsory third-party provision through its monopoly mandate. Among private underwriters, Green Delta Insurance Company Limited exemplifies digital-first distribution architecture, while Eastern Insurance Company Limited occupies specialized commercial vehicle positioning. These three entities represent the dominant competitive archetypes shaping premium flow and channel economics across Bangladesh's motor insurance infrastructure.
| Leading Market Players |
|---|
| Eastern Insurance Company Limited |
| Rupali Insurance Company Limited |
| Phoenix Insurance Company Limited |
| Sadharan Bima Corporation |
| Green Delta Insurance Company Limited |
| Peoples Insurance Company Limited |
| Asia Insurance Limited |
| Eastland Insurance Company Limited |
| Reliance Insurance Limited |
| Others |
Value Chain & Pricing Dynamics
Reinsurance capacity from London and Singapore markets feeds directly into Bangladeshi underwriter pricing tiers, with ceded premium ratios compressing retained margins for domestic carriers while statutory third-party floors prevent race-to-bottom dynamics. This cost cascade stratifies final premiums across fleet-negotiated master policies, individual comprehensive coverage, and compulsory minimum liability products.
Pricing Analysis
Warranty and claims-handling service bundling separates premium motor products from economy tiers, with Green Delta and Eastern Insurance packaging dedicated garage networks and accelerated assessor dispatch into comprehensive fleet contracts. Pricing stratifies across premium, standard, and economy tiers based on telematics integration depth and third-party liability limits. Cost compression in the individual owner segment intensifies because Sadharan Bima Corporation's statutory monopoly on basic coverage sets a rigid price ceiling. Ride-sharing drivers exhibit highest price sensitivity, while Chittagong port logistics contractors demonstrate lowest sensitivity due to operating permit compliance requirements.
Supply Chain Analysis
Reinsurance capacity rests on London, Singapore, and Munich specialty markets, with domestic Bangladeshi underwriters drawing treaty capacity from these hubs to satisfy Bangladesh Bank solvency requirements. Actuarial talent, telematics hardware, and garage network infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in international reinsurer appetite for Bangladesh commercial vehicle risk, which fluctuates with regional catastrophe loss experience. Distribution runs through brokerage firms in Dhaka's Motijheel district for corporate accounts, agent networks in secondary cities for individual owners, and API-embedded platforms for ride-hailing platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent scarcity props pricing power for carriers with in-house modeling capabilities, as supply-constrained risk-pricing expertise limits new product development across the market.
For Market Incumbents: Anchor market position through exclusive telematics data partnerships with ride-sharing platforms, locking out competitors from usage-based pricing infrastructure. Deepen backward integration into garage network ownership to compress claims settlement timelines and differentiate service tiers. The threat of API-enabled insurtech entrants demands preemptive platform integration investments before distribution channel economics shift irreversibly. For New Entrants and Emerging Players: The gap between premium fleet pricing and economy individual coverage creates entry space for digitally native micro-insurance products targeting rural two-wheeler owners in Rajshahi and Khulna divisions. Target mobile-first distribution through bKash and Nagad wallet integrations, capturing premium collection and policy issuance within existing financial behavior patterns. The most penetrable segment sits with seasonal agricultural vehicle owners currently underserved by annual policy structures. For Investors and Strategic Acquirers: Bangladesh Road Transport Authority digitization mandates accelerating compliance timelines is the leading indicator that carrier technology infrastructure quality will separate acquisition targets from stranded assets. Long-term viability hinges on underwriting platform modernization completion before regulatory deadlines harden. Target acquisition archetypes include mid-tier generalists with established agent networks but legacy core systems requiring replacement capital. Watch for telematics data governance framework publication as the signal for regulatory technology barriers to formalize.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables usage-based pricing for Dhaka ride-sharing fleets, displacing annual premium models. |
| Garage Network Acquisition | Captive repair infrastructure compresses claims settlement cycles for Eastern Insurance commercial accounts. |
| API-Enabled Embedded Distribution | Partnership with Pathao and Uber Bangladesh captures driver onboarding workflows as policy issuance moments. |
| Micro-Insurance Product Launch | Mobile-distributed coverage penetrates rural Rajshahi two-wheeler segments outside agent network reach. |
| Reinsurance Treaty Diversification | Multi-hub capacity sourcing from Singapore and Munich reduces London market concentration risk. |
Study Parameters
Multi-period observation of commercial vehicle registration trends, telematics adoption rates, and regulatory enforcement intensity anchored the trend analysis, supplemented by interviews with underwriter product development heads, Bangladesh Road Transport Authority enforcement officers, fleet procurement managers at Chittagong port logistics contractors, and Insurance Development and Regulatory Authority supervisory staff. Secondary validation drew from Bangladesh Bank prudential guideline circulars, Insurance Development and Regulatory Authority annual reports, Bangladesh Road Transport Authority fitness certificate issuance databases, and customs vehicle import records. Bottom-up premium volume estimates by segment triangulated against top-down carrier reported data.
Input-output matrix framing connected vehicle stock projections, fleet operator consolidation trajectories, and regulatory digitization mandates to premium flow estimates across the analysis window. Segmentation dimensions modeled included policy type, customer archetype, coverage duration tier, and distribution channel geography. CAGRs derived from fitted growth curves applied to base-year market sizing, with sensitivity testing around reinsurance capacity availability and telematics penetration assumptions. Forecast inputs incorporated Bangladesh Bank capital adequacy requirements and Insurance Development and Regulatory Authority solvency ratio thresholds.
Inputs from regulatory filings and carrier disclosures were available through the study window; gaps in granular telematics usage data and rural agent network transaction records introduce uncertainty bands around pay-as-you-go segment projections. Forecasts reflect documented assumptions regarding enforcement continuity and reinsurer market appetite. Regulatory digitization timeline delays or international reinsurance capacity contraction represent specific revision triggers. A small set of triggers—mandatory telematics data submission requirements, Bangladesh Bank capital rule amendments, and London market catastrophe loss events—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
China Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Two Wheeler Insurance Market