
 Europe Mandatory Motor Third-Party Liability Insurance Market | 2026-2036
Europe Mandatory Motor Third-Party Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mandatory Motor Third-Party Liability Insurance Market Insights
Fleet operators is redrawing demand patterns across the Europe Mandatory Motor Third-Party Liability Insurance Market as commercial vehicle pools expand under stricter liability mandates. Allianz leverages its dominant position in German fleet coverage to sustain pricing power across Central European corridors. AXA anchors its southern European network through specialized bodily injury settlement protocols in France and Spain.
Europe Mandatory Motor Third-Party Liability Insurance constitutes a compulsory financial instrument covering legal liability arising from motor vehicle operation against third-party property damage and bodily injury, with premium calculations tied to actuarial risk pools, vehicle classification systems, and driver history scoring. Its primary commercial purpose is to guarantee victim compensation while enforcing risk-adjusted cost allocation across motor vehicle operators. Coverage type segments reveal bodily injury as the mature, high-volume pool where regulatory minimums drive baseline participation, while property damage segments concentrate margin extraction through deductible layering and premium tiering. Customer type dynamics show fleet operators as the fastest-growing structural category, absorbing multi-vehicle master policies with embedded telematics monitoring that reduces claims frequency.
EMA coordination with national regulators and the EU Motor Insurance Directive establish baseline coverage floors across member states, while CE marking for telematics hardware and GDPR data governance constrain how insurers collect and apply driver behavior data for premium optimization. National implementations vary, with Germany's KBA enforcing strict vehicle-type classifications and France's ANSM-equivalent insurance oversight mandating standardized claim settlement timelines. Stakeholders must monitor how the EU AI Act intersects with algorithmic underwriting models before deploying automated risk scoring across cross-border policies.
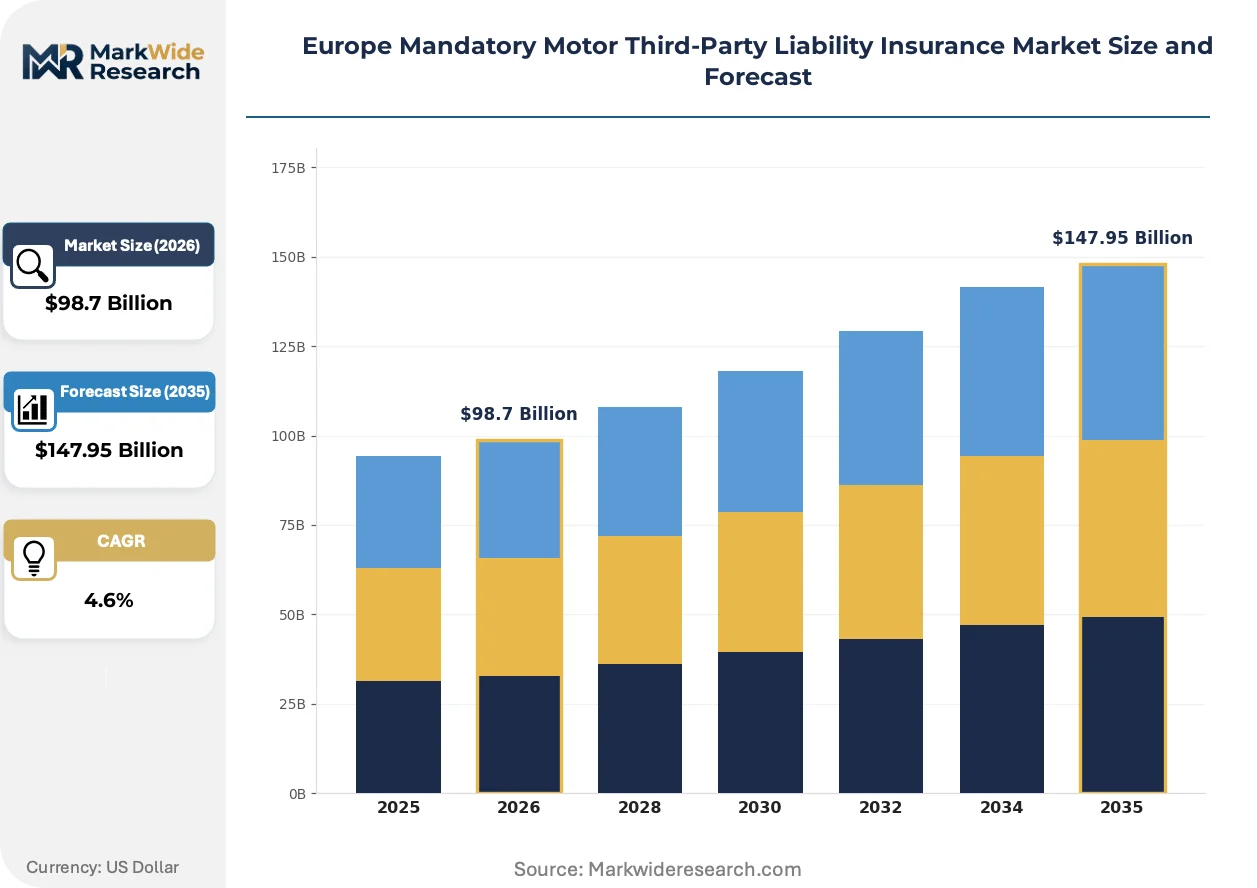
Market Dynamics
Fleet telematics integration is compressing claims frequency across commercial vehicle pools while EU Motor Insurance Directive revisions tighten baseline coverage floors. German KBA enforcement and French standardized settlement timelines are accelerating policy standardization.
Growth Catalysts
- EU Green Deal mandates:Commercial logistics corridors face expanded liability frameworks for electric fleet transitions. Germany's KBA enforces strict vehicle-type classifications that embed insurance verification into registration protocols.
- Telematics hardware adoption:Fleet operators deploy embedded monitoring systems that reduce claims frequency through real-time driver behavior scoring. CE marking requirements ensure hardware standardization across member states.
- Bodily injury regulatory minimums:France's ANSM-equivalent oversight mandates standardized claim settlement timelines that accelerate victim compensation and sustain baseline participation.
Market Restraints
- GDPR data governance friction:Insurers face constrained collection and application of driver behavior data for premium optimization across cross-border policies.
- Algorithmic underwriting uncertainty:The EU AI Act intersects with automated risk scoring models before deployment, creating compliance timeline delays.
- Actuarial risk pool concentration:Premium calculations tied to vehicle classification systems and driver history scoring limit pricing flexibility in mature bodily injury segments.
Strategic Opportunities
- Italian enforcement mechanism expansion:Central and southern European corridors show underpenetrated fleet coverage relative to German and French saturation.
- Telematics-AI convergence:Real-time monitoring systems integrate with algorithmic risk assessment to enable dynamic premium adjustment for commercial vehicle pools.
- Cross-border master policy standardization:Multi-vehicle coverage spanning EU member states benefits from EMA coordination with national regulators on baseline coverage floors.
Industry Challenges
- Actuarial talent scarcity:Specialized underwriting functions for fleet risk assessment face recruitment gaps as telematics complexity increases.
- Legacy system integration:Established insurers confront technical debt when embedding real-time data streams into existing policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mandatory Motor Third-Party Liability Insurance Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Property Damage, Bodily Injury, Personal Injury Protection, Uninsured Motorist Policy Duration: Monthly, Quarterly, Biannual, Annual Customer Type: Individual Drivers, Fleet Operators, Corporate Clients, Government Agencies Claim Settlement Method: Cashless, Reimbursement, Third-Party Involvement, Direct Settlement |
| Companies Covered | Allianz, AXA, Aviva, Admiral Group, MAPFRE, Generali Group, Zurich Insurance Group, Chubb Limited, Ergo Insurance, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mandatory Motor Third-Party Liability Insurance Market Trends and Innovations
Connected vehicle data streams are restructuring how liability is priced and verified across European motor pools. Three developments are compressing traditional underwriting cycles.
On-board diagnostic systems are miniaturizing into plug-and-play hardware formats that fleet operators deploy without vehicle modification. Logistics providers across German commercial corridors adopt these units at accelerated pace to satisfy KBA documentation requirements. The technology is miniaturizing risk assessment infrastructure from garage-based inspection to continuous remote monitoring.
GDPR enforcement by CNIL and fellow national data regulators constrains how insurers apply telematics-derived behavior scoring to premium calculation. French and Spanish carriers face particular scrutiny on automated decision-making transparency. Fleet operators in these markets respond by demanding clearer data governance protocols from hardware vendors and underwriters alike.
Commercial buyers are consolidating procurement of multi-vehicle master policies with embedded monitoring clauses. Traditional broker channels face displacement as direct insurer platforms offer real-time claims reporting and settlement. This concentration is most visible across German and French logistics corridors where fleet scale justifies dedicated underwriting relationships.
Europe Mandatory Motor Third-Party Liability Insurance Market Segmentation
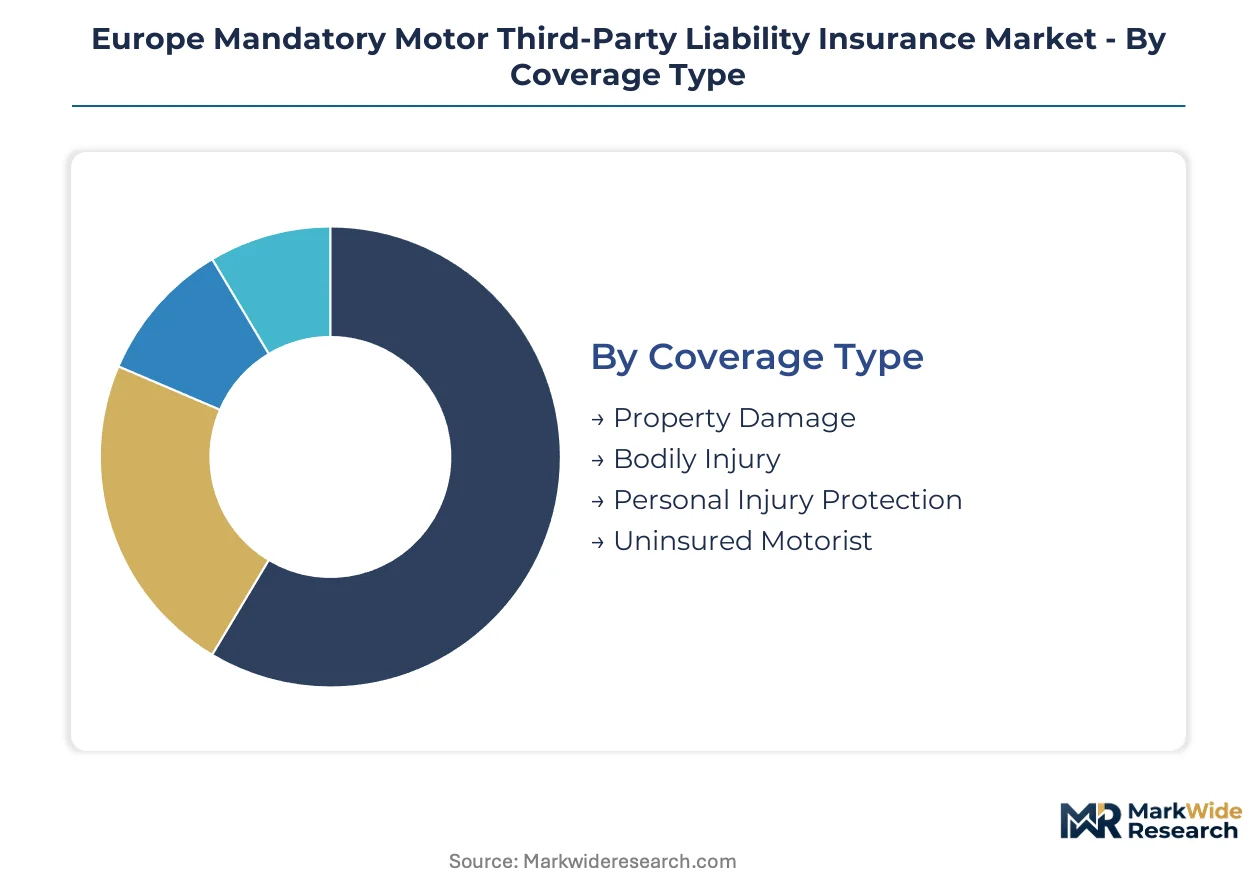
Segmentation in Europe Mandatory Motor Third-Party Liability Insurance Market determines how carriers allocate capital reserves, price risk pools, and configure distribution infrastructure. Distinct coverage types flow through specialized underwriting channels while customer categories demand tailored policy administration systems.
Coverage Type:
Channel mix varies sharply across coverage categories, with bodily injury pooling through established broker networks and property damage migrating toward direct digital platforms.
- Bodily Injury:Mandated minimums establish the baseline coverage floor across all EU member states. German KBA enforcement and French standardized settlement timelines concentrate demand in mature regulatory environments where victim compensation guarantees drive participation.
- Property Damage:Deductible layering and premium tiering enable margin extraction beyond regulatory minimums. Fleet operators across German commercial corridors deploy embedded telematics to compress claims frequency and negotiate master policy terms.
- Personal Injury Protection:Supplements mandatory coverage with accelerated medical expense settlement. Italian and Spanish carriers emphasize this add-on for individual driver segments seeking streamlined claims pathways.
- Uninsured Motorist:Addresses residual liability gaps where opposing parties lack valid coverage. Central European enforcement mechanisms limit addressable market size relative to southern European corridors.
Bodily injury dominates installed base. Property damage is where expansion concentrates.
Policy Duration:
Cost tiering separates premium pricing across duration bands, with longer commitments capturing rate discounts that reflect reduced administrative overhead.
- Annual:Standard commercial vehicle coverage format embedding telematics monitoring clauses. Fleet operators across French logistics networks prefer this structure for consolidated renewal cycles and predictable budgeting.
- Monthly:Flexible commitment structure attracting individual drivers with variable vehicle usage patterns. Digital distribution platforms capture this segment through automated payment processing and minimal underwriting friction.
- Quarterly:Intermediate duration bridging short-term flexibility with moderate rate advantages. Seasonal commercial operators in Italian agricultural and construction sectors favor this alignment.
- Biannual:Limited adoption concentrated in transitional customer segments testing carrier relationships before annual commitment.
Annual policies dominate installed base. Monthly structures are climbing the fastest as digital distribution expands.
Customer Type:
Application intensity varies by operational scale, with multi-vehicle pools demanding integrated risk management infrastructure absent from individual driver relationships.
- Fleet Operators:Multi-vehicle master policies with embedded telematics monitoring represent the most intensive underwriting category. Real-time driver behavior scoring reduces claims frequency across German and French commercial logistics corridors.
- Individual Drivers:Fragmented demand distributed through broker networks and direct digital channels. GDPR constraints on data collection limit premium optimization potential relative to commercial segments.
- Corporate Clients:Non-fleet business vehicle coverage requiring specialized liability frameworks. French and Italian professional service sectors generate concentrated demand for executive vehicle protection.
- Government Agencies:Public fleet procurement subject to standardized tender processes and extended settlement timelines. Municipal vehicle pools across German federal states operate under centralized purchasing agreements.
Individual drivers dominate installed base. Fleet operators represent the steepest expansion trajectory as commercial vehicle pools multiply.
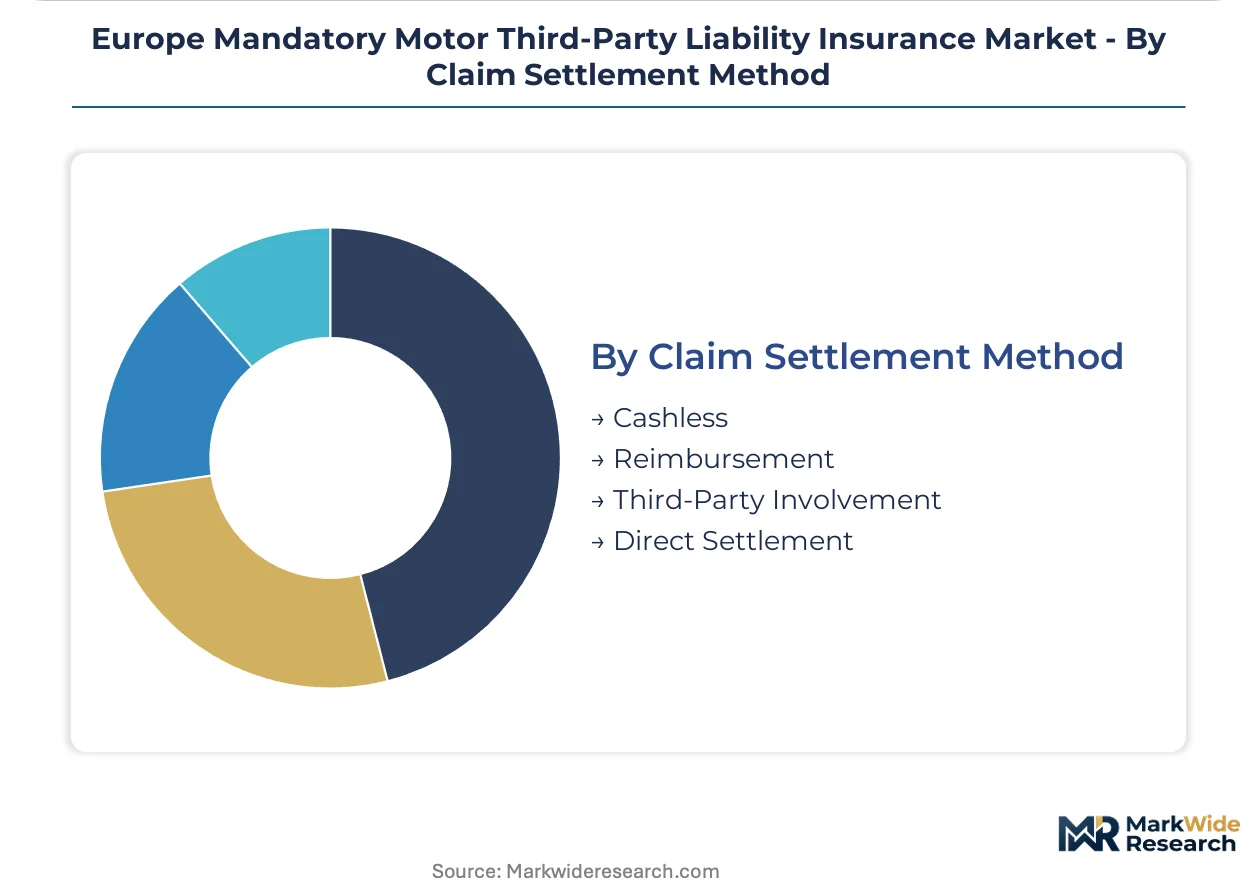
Claim Settlement Method:
Margin structure correlates with settlement complexity, with cashless protocols capturing efficiency premiums and reimbursement methods retaining cost advantages.
- Cashless:Network-based repair authorization eliminating out-of-pocket expenditure for policyholders. German KBA documentation requirements accelerate adoption across commercial vehicle segments.
- Direct Settlement:Carrier-to-carrier negotiation bypassing policyholder involvement in liability disputes. French standardized timelines mandate this pathway for bodily injury claims above threshold values.
- Reimbursement:Post-expense recovery model retaining lower premium positioning. Individual driver segments accept administrative burden for rate reduction.
- Third-Party Involvement:External adjusters and legal representatives extending settlement duration. Complex liability disputes across cross-border incidents require this intervention layer.
Reimbursement dominates installed base. Cashless protocols are gaining share fastest as network infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor freight rail network underwrites Germany's dominance in commercial fleet coverage, while Mediterranean port clusters anchor southern European logistics insurance demand.
Germany
Commercial logistics corridors between Hamburg and Munich drive fleet policy density. KBA enforcement embeds insurance verification into vehicle registration protocols, creating mandatory participation. The Ruhr industrial belt concentrates underwriting expertise for heavy commercial vehicle pools.
France
Paris-Lyon logistics arteries sustain bodily injury settlement volume. ANSM-equivalent oversight mandates standardized claim timelines that compress victim compensation cycles. The Île-de-France metropolitan area anchors direct settlement infrastructure for high-frequency commercial claims.
Italy
Milan-Naples freight corridors show underpenetrated fleet coverage relative to northern European saturation. National enforcement mechanisms are tightening liability verification at regional motor vehicle offices. Lombardy's industrial concentration attracts specialized bodily injury underwriters.
Spain
Barcelona-Valencia port logistics generate concentrated commercial vehicle insurance demand. GDPR enforcement by AEPD constrains telematics data application for premium scoring. The Mediterranean corridor sustains property damage coverage growth through deductible-tiered products.
Netherlands
Rotterdam-Europoort container throughput anchors cross-border fleet master policy demand. EMA coordination with national regulators enables baseline coverage standardization. The Randstad logistics cluster concentrates telematics-enabled underwriting for international haulage operators.
Europe Mandatory Motor Third-Party Liability Insurance Market Competitive Landscape
Concentration sits with diversified European insurers holding dominant positions in their home markets. Three structural tiers operate: integrated financial conglomerates with captive reinsurance capacity, national champions with specialized bodily injury settlement infrastructure, and digital-native distributors targeting monthly policy flexibility. Competitive moves center on telematics platform partnerships and cross-border master policy standardization.
Among Germany-based diversified insurers, Allianz and Ergo Insurance exemplify integrated conglomerates with captive reinsurance structures. AXA represents the French national champion archetype with specialized bodily injury protocols. Admiral Group occupies a position within the digital-native tier targeting flexible policy duration.
| Leading Market Players |
|---|
| Allianz |
| AXA |
| Aviva |
| Admiral Group |
| MAPFRE |
| Generali Group |
| Zurich Insurance Group |
| Chubb Limited |
| Ergo Insurance |
| Others |
Pricing and Supply Chain Analysis
Telematics hardware substitution for traditional garage-based risk assessment is redrawing supply geography toward CE-marked device manufacturers while compressing premium economics through real-time claims frequency reduction. Fleet operators now source embedded monitoring systems from standardized hardware vendors rather than regional inspection networks, collapsing procurement lead times and enabling volume-discount negotiations across multi-vehicle master policies.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement, with annual master policies capturing rate advantages over monthly commitments through reduced administrative overhead. Price differentiation rests on telematics adoption depth and KBA documentation compliance tier, with German commercial corridors commanding premium positioning for embedded monitoring integration. Cost compression in individual driver segments intensifies as digital distribution platforms eliminate broker intermediation. Fleet operators exhibit lowest price sensitivity due to claims frequency reduction value, while individual drivers prioritize rate minimization over service bundling.
Supply Chain Analysis
KBA documentation protocols create a chokepoint where German vehicle registration authorities underwrite insurance verification before plate issuance. Hardware supply concentrates in Germany, France, and the Netherlands, with CE-marked telematics device manufacturing anchored in Dutch technology clusters and German automotive component networks. Raw material dependencies span semiconductor chips for processing units, GPS modules for location tracking, and cellular modems for real-time data transmission. Single-source vulnerability sits with specialized firmware providers serving algorithmic underwriting platforms. Distribution runs through direct insurer procurement teams and fleet management system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive structure where mandatory participation and KBA enforcement create entrenchment against price-based competition. Switching costs for fleet operators escalate through embedded telematics integration and multi-year master policy structures.
For Market Incumbents: Consolidate underwriting expertise in heavy commercial vehicle pools across the Ruhr industrial belt and Rhine-Alpine corridor. Acquire specialized actuarial talent for telematics-integrated risk scoring before GDPR-constrained competitors. Vertical integration into hardware vendor relationships secures data pipeline control against algorithmic underwriting entrants. For New Entrants and Emerging Players: Differentiate on monthly policy flexibility targeting individual drivers with variable vehicle usage patterns in Italian and Spanish markets where enforcement mechanisms lag northern European saturation. Penetrate Lombardy's industrial concentration for bodily injury specialization. Deploy direct digital platforms with automated payment processing to bypass established broker networks. For Investors and Strategic Acquirers: The market sits at a telematics-integration phase that favors carriers with captive data infrastructure and algorithmic underwriting capabilities. Long-term viability over the next decade hinges on EU AI Act compliance positioning and cross-border master policy standardization. Acquisition targets should demonstrate embedded monitoring deployment at scale. Watch GDPR enforcement intensity by CNIL and fellow national regulators as the signal for premium optimization headroom.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded monitoring systems reduce claims frequency across German commercial logistics corridors. |
| Cross-Border Master Policy Standardization | EMA coordination with national regulators enables baseline coverage floors spanning EU member states. |
| Algorithmic Underwriting Investment | EU AI Act intersection demands compliance-ready automated risk scoring for fleet operators. |
| Specialized Bodily Injury Settlement Infrastructure | French ANSM-equivalent oversight mandates standardized timelines compressing victim compensation cycles. |
| Digital Distribution Platform Launch | Direct insurer platforms displace traditional broker channels in monthly policy flexibility segments. |
Research Methodology
Operator-level perspectives from fleet managers, insurance underwriters, telematics hardware vendors, and national motor vehicle registration officials anchored the qualitative base. Primary interviews combined with secondary validation from EU Motor Insurance Directive documentation, KBA enforcement protocols, EMA coordination frameworks, and national insurance supervisory authority filings. Bottom-up premium volume estimates triangulated against top-down regulatory participation mandates across member states.
Sensitivity analysis tested forecast outputs against telematics adoption velocity and GDPR enforcement intensity variations across the projection horizon. Segmentation dimensions modeled include coverage type, policy duration, customer type, and claim settlement method, with regional regulatory cluster as an additional insurance-specific dimension. CAGRs derived from actuarial risk pool growth trajectories and fleet operator expansion patterns. Industry-specific inputs incorporated electric fleet transition timelines under EU Green Deal mandates and algorithmic underwriting deployment readiness.
The analysis sits within stated boundaries; outcomes outside sustained EMA coordination and stable GDPR enforcement frameworks would require recalibration. Forecasts reflect assumptions regarding telematics hardware standardization and cross-border policy portability. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and national enforcement mechanism variations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market