
 Asia-Pacific Car Insurance Market | 2026-2036
Asia-Pacific Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Car Insurance Market Insights
Fleet operator consolidation across Southeast Asia is expanding the addressable base for commercial motor policies. Ping An Insurance leverages its integrated fintech platform to capture this concentrated buyer segment. MS&AD Insurance Group anchors its regional position through specialized commercial vehicle underwriting expertise. Tokio Marine competes via advanced telematics integration that differentiates risk pricing for fleet accounts.
Asia-Pacific car insurance constitutes a contractual risk-transfer mechanism where insurers indemnify policyholders against financial loss from vehicle collisions, theft, or third-party liability, with premiums calibrated through actuarial models incorporating vehicle age, driver history, and geographic risk density. The product serves both individual asset protection and statutory liability compliance across jurisdictions with mandatory coverage laws. Comprehensive coverage dominates premium volumes due to bundled protection against own-damage and third-party claims, while Pay-As-You-Drive policies represent the fastest-expanding segment as usage-based telemetry enables dynamic pricing. Corporate customer pools concentrate margin contribution through multi-vehicle fleet contracts with negotiated loss-ratio terms.
China's SAMR enforces data localization requirements on connected vehicle telemetry used for premium calculation, while India's IRDAI mandates minimum third-party liability coverage through standardized policy wordings. Australia's ASIC and Japan's FSA impose solvency ratio frameworks that shape capital reserves and pricing adequacy across admitted carriers. Stakeholders must monitor divergence between national data sovereignty rules and cross-border reinsurance arrangements as telematics penetration deepens.
Market Dynamics
Telematics mandates from China's SAMR and India's IRDAI are compressing actuarial cycles and forcing carriers to rebuild pricing engines around real-time vehicle data streams rather than static risk tables.
Growth Catalysts
- Commercial fleet motorization:Fleet operators across Indonesia and Vietnam are expanding vehicle counts under single ownership, creating concentrated premium pools that reward specialized underwriting capabilities.
- IRDAI minimum coverage mandates:India's regulator has tightened third-party liability requirements in Maharashtra and Karnataka, mechanically expanding the addressable policy base in these high-motorization states.
- Connected vehicle telemetry:OEM-embedded data collection hardware is generating granular driving behavior datasets that enable dynamic premium adjustment at policy renewal.
Market Restraints
- Data localization compliance costs:China's SAMR requires domestic storage of connected vehicle telemetry, forcing foreign reinsurers to establish separate cloud infrastructure for PRC policy calculations.
- Actuarial talent scarcity:The specialized skill set combining automotive engineering with predictive modeling concentrates in Shanghai, Tokyo, and Bangalore, creating recruitment bottlenecks for regional expansion.
- Legacy core system fragility:Established carriers in Japan and Australia operate on policy administration platforms from the 1990s that resist API integration with telematics data feeds.
Strategic Opportunities
- Vietnam commercial motor underpenetration:Fleet insurance penetration lags personal lines by a factor of three, presenting first-mover advantages for specialized commercial underwriters.
- Pay-As-You-Drive product innovation:Usage-based coverage that prices by kilometer driven and time-of-day usage is displacing annual fixed-premium comprehensive policies among price-sensitive urban buyers.
- Embedded distribution via OEMs:New vehicle point-of-sale insurance attachment creates captive customer acquisition channels that bypass traditional agent networks.
Industry Challenges
- Cross-border reinsurance data friction:Singapore-based reinsurers face operational complexity when pooling risk across policies governed by divergent national data sovereignty regimes.
- Telematics standardization delays:Absence of unified data formats between Japanese, Korean, and Chinese vehicle OEMs forces carriers to maintain multiple ingestion pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Car Insurance Market |
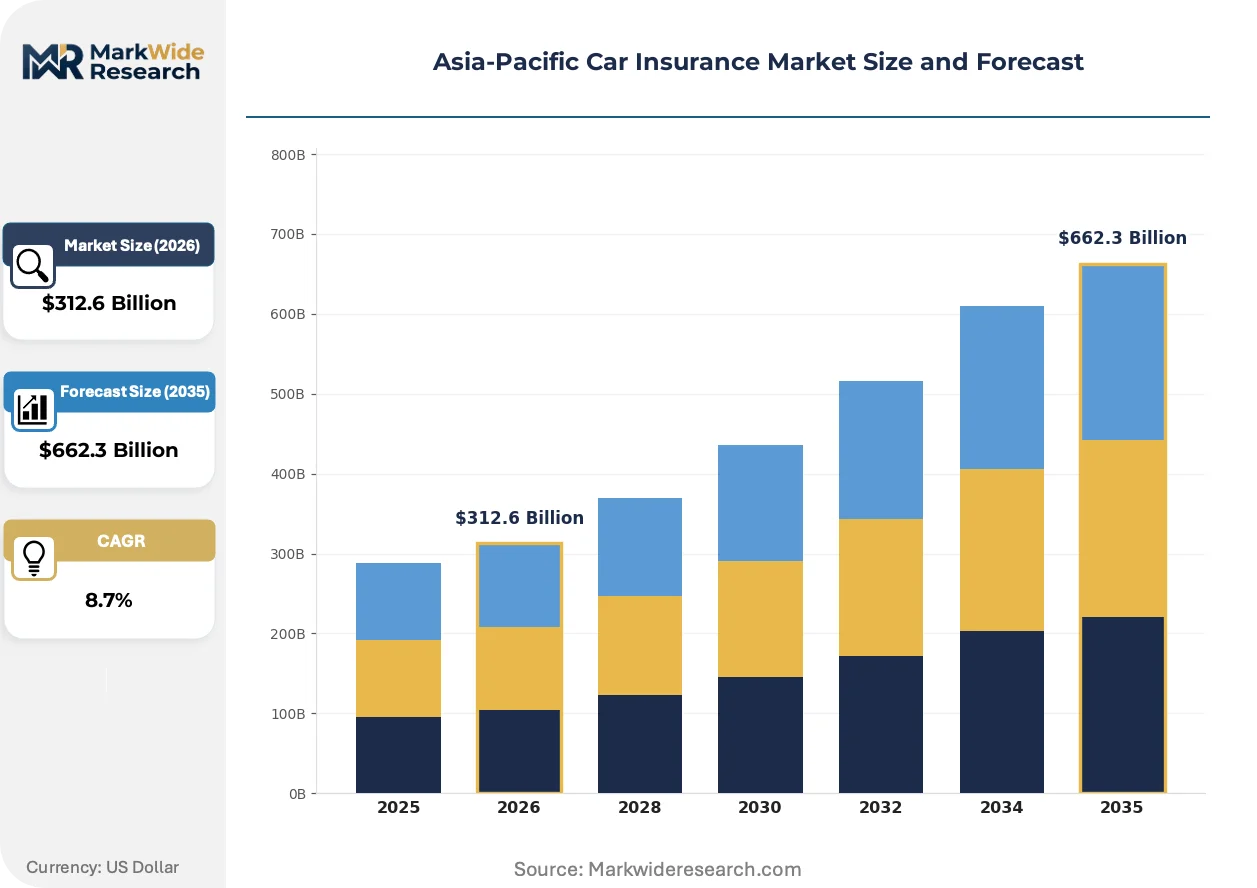
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party, Third Party Fire & Theft, Pay-As-You-Drive Customer Type: Individual, Fleet, Corporate, Government Coverage Scope: Personal Liability, Property Damage, Medical Payments, Uninsured Motorist Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Agents |
| Companies Covered | Ping An Insurance, PICC, Tokio Marine, MS&AD Insurance Group, Sompo Japan Nipponkoa Insurance, Allianz, AXA, AIA Group Limited, IAG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Car Insurance Market Trends and Innovations
Artificial intelligence and connected vehicle infrastructure are compressing the feedback loop between risk exposure measurement and premium adjustment, enabling products that price coverage in near-real-time rather than at annual renewal.
Computer vision damage assessment is converging with mobile claims submission workflows. Policyholders in Australia and South Korea now photograph vehicle damage through insurer-branded applications that apply convolutional neural networks to estimate repair costs within minutes. This technology is compressing claims cycle times from weeks to hours and reducing adjuster field deployment requirements.
India's IRDAI has standardized policy wordings for third-party liability coverage, eliminating carrier-specific contract variations that previously created consumer confusion and regulatory arbitrage. The industrial consequence is a leveling of competitive terrain where differentiation must shift from policy design to service execution and pricing precision. Personal lines carriers in Maharashtra and Karnataka are responding by investing in telematics-enabled dynamic pricing to regain product distinction.
Fleet procurement of insurance is consolidating around multi-year master policies with embedded loss-ratio guarantees rather than annual single-vehicle placements. Large logistics operators across Southeast Asia now negotiate enterprise-wide coverage that bundles risk transfer with safety training and driver monitoring services. This pattern is most visible in Indonesia's Java-based freight corridors where fleet sizes exceed five hundred vehicles.
Asia-Pacific Car Insurance Market Segmentation
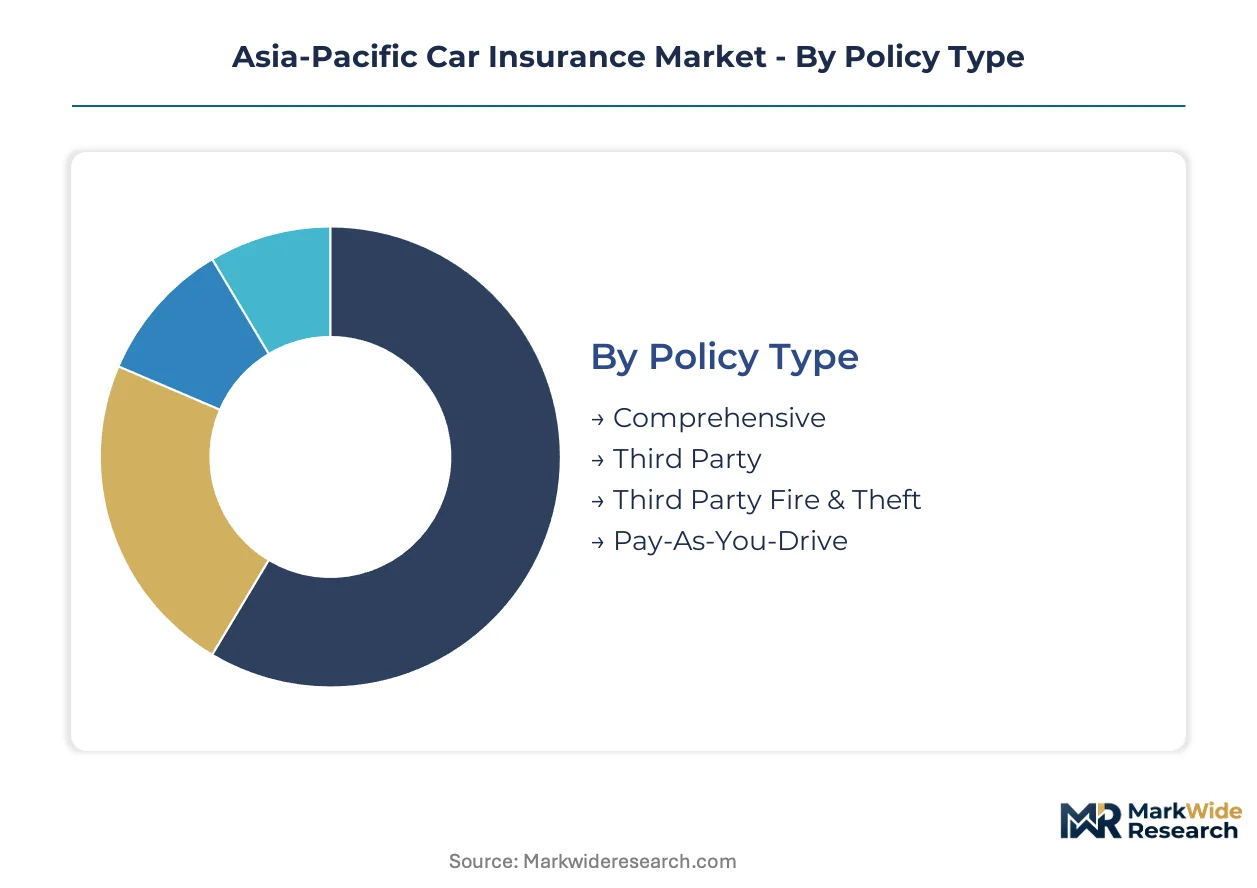
Car insurance segmentation in the Asia-Pacific region reflects divergent risk appetites across buyer types and the accelerating shift toward usage-based pricing models. Telematics penetration and regulatory mandates are compressing traditional category boundaries as carriers rebuild product architectures around real-time data streams.
Policy Type:
Premium tolerance and asset protection needs separate buyers across this category, with fleet operators demanding loss-ratio guarantees while individual policyholders prioritize price sensitivity.
- Comprehensive:Bundles own-damage coverage with third-party liability into single contracts, commanding premium multiples above basic mandates. Demand concentrates in Australia's urban corridors and Japan's prefectural centers where vehicle replacement costs exceed regional medians. IRDAI minimum coverage expansion in Maharashtra mechanically expands this segment's addressable base.
- Pay-As-You-Drive:Prices coverage by kilometer driven and time-of-day usage through OEM-embedded telemetry. Adoption accelerates among price-sensitive urban buyers in South Korea and Singapore where congestion pricing and parking scarcity reduce annual mileage. SAMR data localization requirements force carriers to maintain domestic cloud infrastructure for PRC policy calculations.
- Third Party:Statutory minimum coverage satisfying mandatory liability laws without own-damage protection. Dominates Vietnam and Indonesia's personal lines where premium minimization overrides asset protection priorities.
- Third Party Fire & Theft:Mid-tier coverage adding named perils to basic liability, prevalent in Malaysia and Thailand where vehicle theft rates exceed comprehensive pricing thresholds.
Comprehensive leads volumes today; Pay-As-You-Drive is gaining share fastest.
Customer Type:
Contract scale and negotiation leverage determine pricing mechanics, with enterprise accounts extracting multi-year terms and embedded safety services unavailable to retail buyers.
- Fleet:Multi-vehicle contracts covering fifty-plus units under single master policies with negotiated loss-ratio floors. Indonesia's Java-based freight operators and Vietnam's logistics consolidators anchor regional demand as commercial motorization accelerates. Tokio Marine and MS&AD compete through specialized underwriting expertise and telematics integration.
- Individual:Single-vehicle annual policies representing the volume base across all Asia-Pacific jurisdictions. Concentrated in India's Maharashtra and Karnataka where urban motorization rates climb fastest alongside regulatory minimum coverage expansion.
- Corporate:Non-fleet business vehicles under company registration, common in Australia's SME sector and Japan's regional trading houses.
- Government:Public sector vehicle pools requiring specialized procurement compliance, significant in China's provincial administrations and India's state transport corporations.
Fleet contracts generate the highest margin contribution per policy; Corporate is expanding most quickly as SME commercial motorization rises.
Coverage Scope:
Legal environment and healthcare cost structures shape protection priorities, with litigation risk elevating liability limits in common-law jurisdictions versus no-fault systems.
- Personal Liability:Bodily injury protection against third-party claims, mandatory across all Asia-Pacific jurisdictions with statutory minimums varying by vehicle class. Australia's ASIC solvency frameworks and Japan's FSA capital requirements ensure adequacy.
- Property Damage:Coverage for collision-induced damage to external assets, critical in dense urban corridors where infrastructure replacement costs escalate.
- Medical Payments:First-party healthcare cost reimbursement, dominant in markets with limited public health integration.
- Uninsured Motorist:Protection against liability gaps when at-fault parties lack coverage, prevalent in developing Southeast Asian markets where enforcement of mandatory insurance remains uneven.
Personal Liability anchors premium volumes; Uninsured Motorist is climbing the fastest as enforcement gaps persist.
Distribution Channel:
Customer acquisition cost and data control determine channel economics, with embedded OEM distribution threatening traditional agent networks.
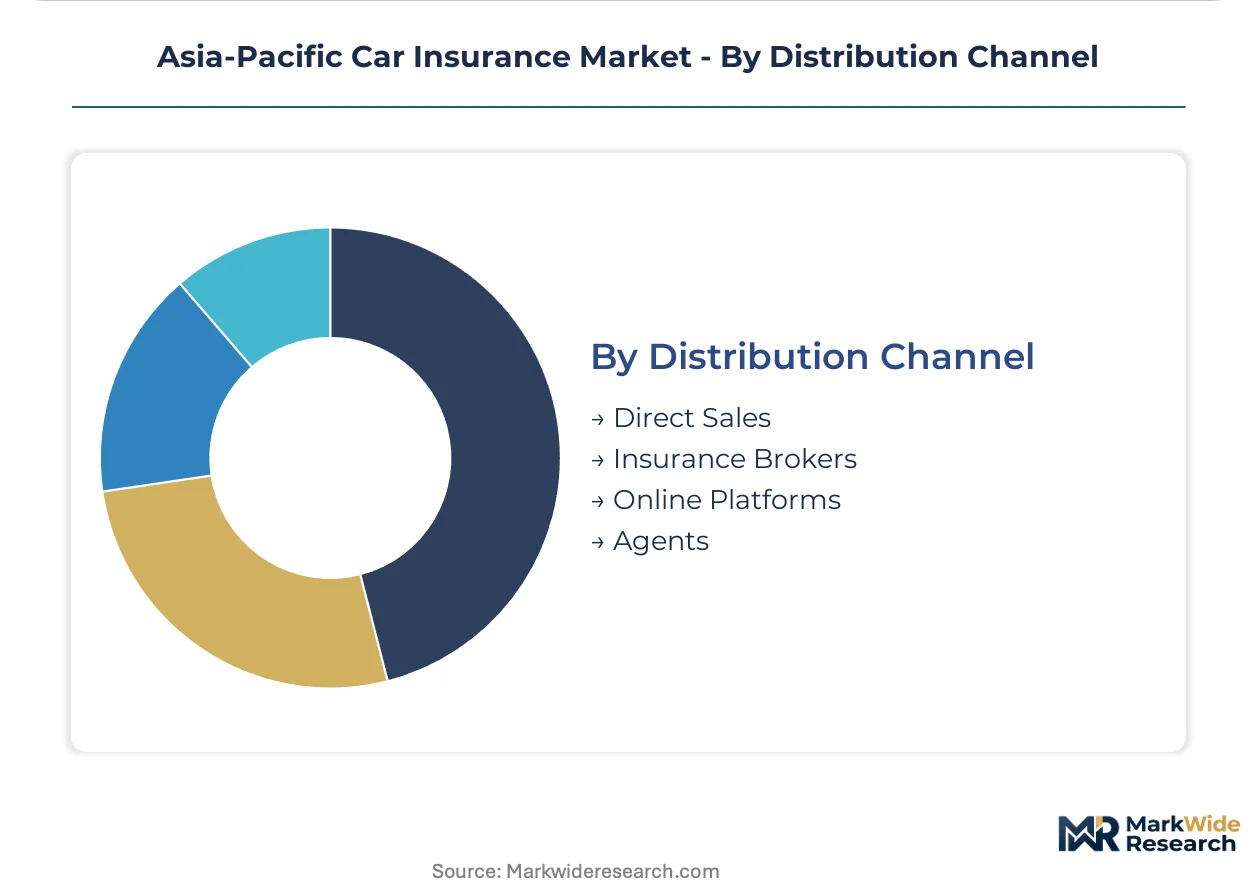
- Online Platforms:Direct digital quotation and policy issuance bypassing intermediaries, capturing price-comparison shoppers in South Korea and Australia. Ping An's integrated fintech platform leverages this channel for fleet customer acquisition.
- Insurance Brokers:Independent intermediaries negotiating terms across multiple carriers, dominant for complex fleet and corporate placements requiring coverage customization.
- Agents:Tied representatives with exclusive carrier relationships, retaining strength in rural India and Indonesia where digital literacy gaps persist.
- Direct Sales:Carrier-owned channels including branch networks and call centers, significant in Japan's agency-light market structure.
Insurance Brokers lead commercial volumes today; Online Platforms are expanding most quickly among personal lines buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's telematics mandates compress actuarial cycles faster than India's regulatory expansion mechanically enlarges policy volumes, creating divergent growth mechanics across the region's two largest markets.
China
SAMR data localization rules force domestic cloud infrastructure for connected vehicle telemetry, reshaping how foreign reinsurers structure PRC policy calculations. NMPA-aligned governance standards now govern OEM-embedded data collection hardware. Premium pricing innovation concentrates in Shanghai's fintech corridor where carriers rebuild engines around real-time vehicle data streams.
India
IRDAI minimum coverage mandates in Maharashtra and Karnataka mechanically expand the addressable policy base as urban motorization rates climb fastest in these states. Standardized third-party liability wordings eliminate carrier-specific contract variations. Mumbai and Bangalore anchor personal lines carrier investments in telematics-enabled dynamic pricing to regain product distinction.
Japan
FSA solvency ratio frameworks shape capital reserves and pricing adequacy across admitted carriers, constraining aggressive premium growth. Legacy core system fragility from 1990s policy administration platforms resists API integration with telematics data feeds. Tokyo's actuarial talent concentration creates recruitment bottlenecks for regional expansion.
Indonesia
Fleet operators across Java-based freight corridors expand vehicle counts under single ownership, creating concentrated premium pools that reward specialized underwriting capabilities. Commercial vehicle ownership rises fastest among logistics consolidators negotiating enterprise-wide coverage. Jakarta anchors multi-year master policies with embedded loss-ratio guarantees for fleet sizes exceeding five hundred vehicles.
Vietnam
Fleet insurance penetration lags personal lines by a factor of three, presenting first-mover advantages for specialized commercial underwriters. Ho Chi Minh City's logistics sector drives commercial motorization as SME freight operators consolidate procurement. The country's national insurance regulator enforces mandatory coverage laws with uneven enforcement gaps that elevate uninsured motorist protection demand.
Asia-Pacific Car Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards telematics integration depth and fleet underwriting expertise. Three strategic archetypes dominate: integrated fintech platforms with captive distribution, specialized commercial vehicle underwriters with loss-ratio guarantees, and telematics-native carriers with dynamic pricing engines. Competitive moves concentrate on M&A to acquire telemetry capabilities and strategic partnerships with OEMs for embedded point-of-sale distribution.
Within the integrated platform tier, Ping An Insurance exemplifies the fintech-carrier hybrid model that captures concentrated fleet buyer segments through direct digital channels. Among specialized commercial underwriters, Tokio Marine and MS&AD Insurance Group occupy positions defined by telematics integration depth and fleet account risk pricing differentiation. These three names anchor the competitive map without exhausting its architecture.
| Leading Market Players |
|---|
| Ping An Insurance |
| PICC |
| Tokio Marine |
| MS&AD Insurance Group |
| Sompo Japan Nipponkoa Insurance |
| Allianz |
| AXA |
| AIA Group Limited |
| IAG |
| Others |
Pricing and Supply Chain Analysis
Telematics infrastructure deployment across China and India is compressing actuarial cost structures while concentrating data processing capabilities in domestic cloud facilities, simultaneously reshaping premium economics and supply chain geography for regional carriers.
Pricing Analysis
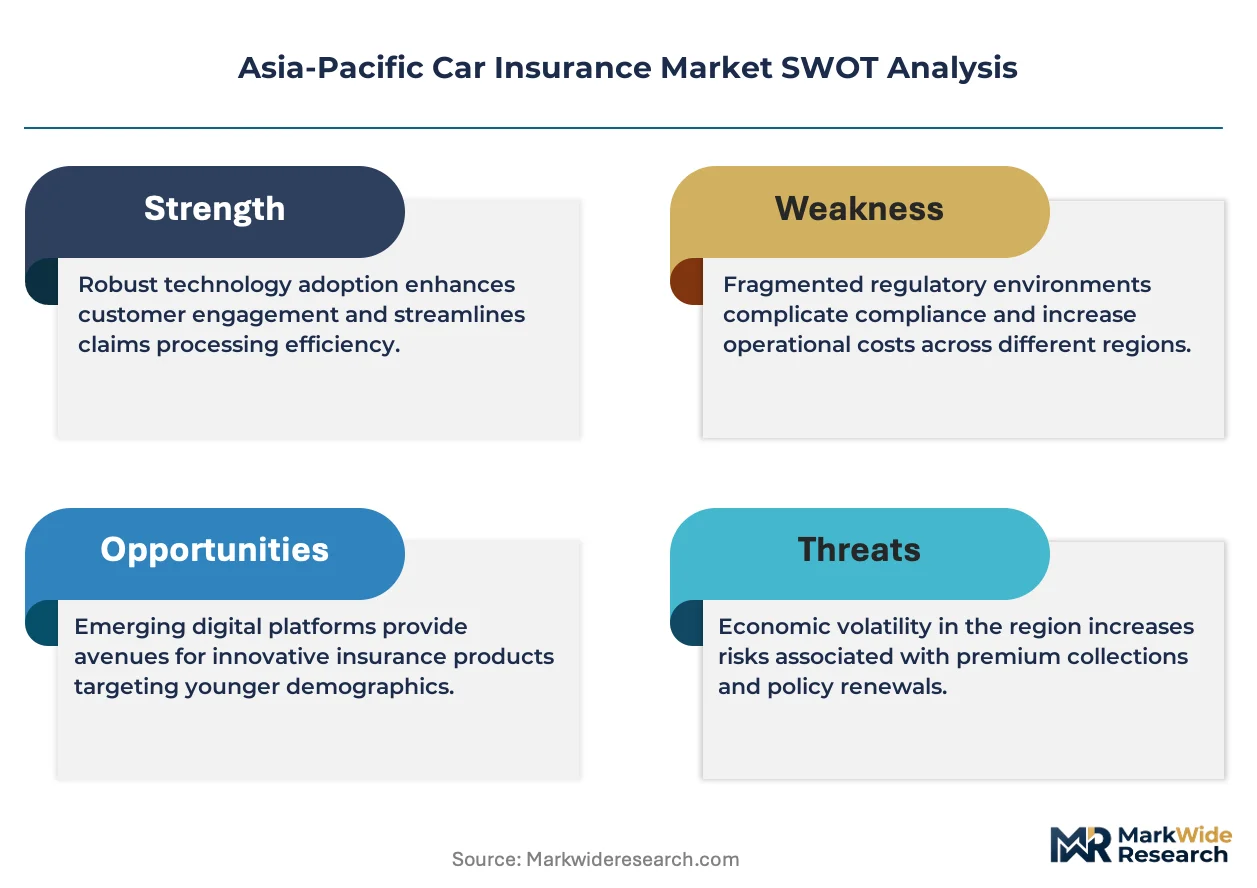
Capacity additions in Vietnam and Indonesia are reshaping price floors for commercial fleet coverage as underwriting competition intensifies. Premium-mid-economy pricing differentiation separates comprehensive policies with embedded telematics from basic third-party mandates. Cost compression in personal lines stems from IRDAI standardization of policy wordings. Individual buyers in Maharashtra exhibit highest price sensitivity; fleet operators with loss-ratio guarantees show lowest.
Supply Chain Analysis
Freight costs from Shanghai and Singapore data centers to regional carrier headquarters are rising as SAMR localization mandates force infrastructure duplication. Raw material inputs for claims processing—cloud compute, actuarial software licenses, and telematics hardware—draw from China, Japan, and South Korea. Single-source vulnerability concentrates in domestic cloud providers meeting PRC data sovereignty rules. Distribution runs through embedded OEM partnerships and broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet buyers now demand premium specifications combining dynamic pricing with loss-ratio guarantees, elevating service quality over pure rate competition across the Asia-Pacific car insurance market.
For Market Incumbents: Deploy telematics integration depth to defend against fintech-platform disintermediation. MS&AD and Tokio Marine should deepen underwriting specialization for Java-based freight corridors. Backward integration into OEM data partnerships secures captive distribution channels against Ping An's digital encroachment. For New Entrants and Emerging Players: Launch via embedded point-of-sale distribution at Vietnam's commercial vehicle dealerships. Fleet insurance underpenetration in Ho Chi Minh City logistics offers the most penetrable white space. Target SME freight consolidators with Pay-As-You-Drive products priced by kilometer and time-of-day usage. For Investors and Strategic Acquirers: Roll-up economics work for telematics-native regional carriers because SAMR and IRDAI mandates are forcing legacy platform replacement. Long-term viability favors specialists with dynamic pricing engines over comprehensive carriers with 1990s core systems. Watch for inflection when China's NMPA expands telemetry standards beyond current passenger vehicle scope.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables real-time premium adjustment for fleet accounts under SAMR data localization rules. |
| Fleet Underwriting Specialization | Captures concentrated premium pools from Indonesia's Java-based freight operators exceeding five hundred vehicles. |
| Embedded OEM Distribution Partnership | Bypasses traditional agent networks through point-of-sale insurance attachment at new vehicle purchase. |
| Dynamic Pricing Engine Development | Regains product distinction lost to IRDAI standardized wordings in Maharashtra and Karnataka. |
| Multi-year Master Policy Structuring | Bundles risk transfer with driver monitoring services for Southeast Asian logistics consolidators. |
Research Methodology
Multiple input streams—carrier underwriting executives, IRDAI regulatory affairs officers, fleet procurement managers, and telematics platform engineers—were reconciled against IRDAI circulars, SAMR data governance filings, vehicle registration databases, and reinsurance treaty disclosures. Bottom-up policy volume estimates from Maharashtra, Karnataka, and Java-based corridors were cross-validated with top-down premium projections across the analysis window.
Data-stream reconciliation anchored the forecast framework across policy type, customer segment, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves incorporating telematics penetration trajectories and fleet motorization rates. Industry-specific inputs included OEM-embedded hardware deployment schedules and IRDAI minimum coverage mandate expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt data sovereignty enforcement or telematics standardization delays between Japanese, Korean, and Chinese OEMs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market