
 Viscosupplementation Market | 2026-2036
Viscosupplementation Market Size, Share, and Industry Trends Forecast 2026-2036
Viscosupplementation Market Analysis
The viscosupplementation market is pivoting on a widening split between premium single-injection formulations and commodity multi-dose hyaluronic acid therapies. Sanofi leverages its biologics manufacturing scale to command pricing power in high-concentration segments. Anika Therapeutics differentiates through specialized orthobiologics R&D, while Seikagaku Corporation anchors supply chains for pharmaceutical-grade sodium hyaluronate raw material.
Viscosupplementation refers to intra-articular injection of hyaluronic acid or related biologics to restore synovial fluid viscosity and cushion weight-bearing joints, typically requiring molecular weights between 500 and 6,000 kDa for optimal rheological performance. Hyaluronic acid products dominate current revenue pools due to established reimbursement codes, while platelet-rich plasma applications represent the fastest-expanding segment as sports medicine centers adopt autologous therapies. Intra-articular delivery mode maintains structural primacy, though injectable formulations with extended-release cross-linked polymers are capturing margin concentration from standard topical alternatives.
The FDA oversees sterility and pyrogen testing for intra-articular devices under device-drug combination rules, while the EMA's MDR framework imposes clinical evidence requirements that slow European market entry for new formulations. ISO 13485 quality management standards govern manufacturing consistency across export-oriented production facilities in Japan and South Korea. Stakeholders must monitor evolving CMS reimbursement thresholds for outpatient joint procedures as these determinations will reshape competitive access for single-injection versus multi-injection therapy protocols.
Market Dynamics
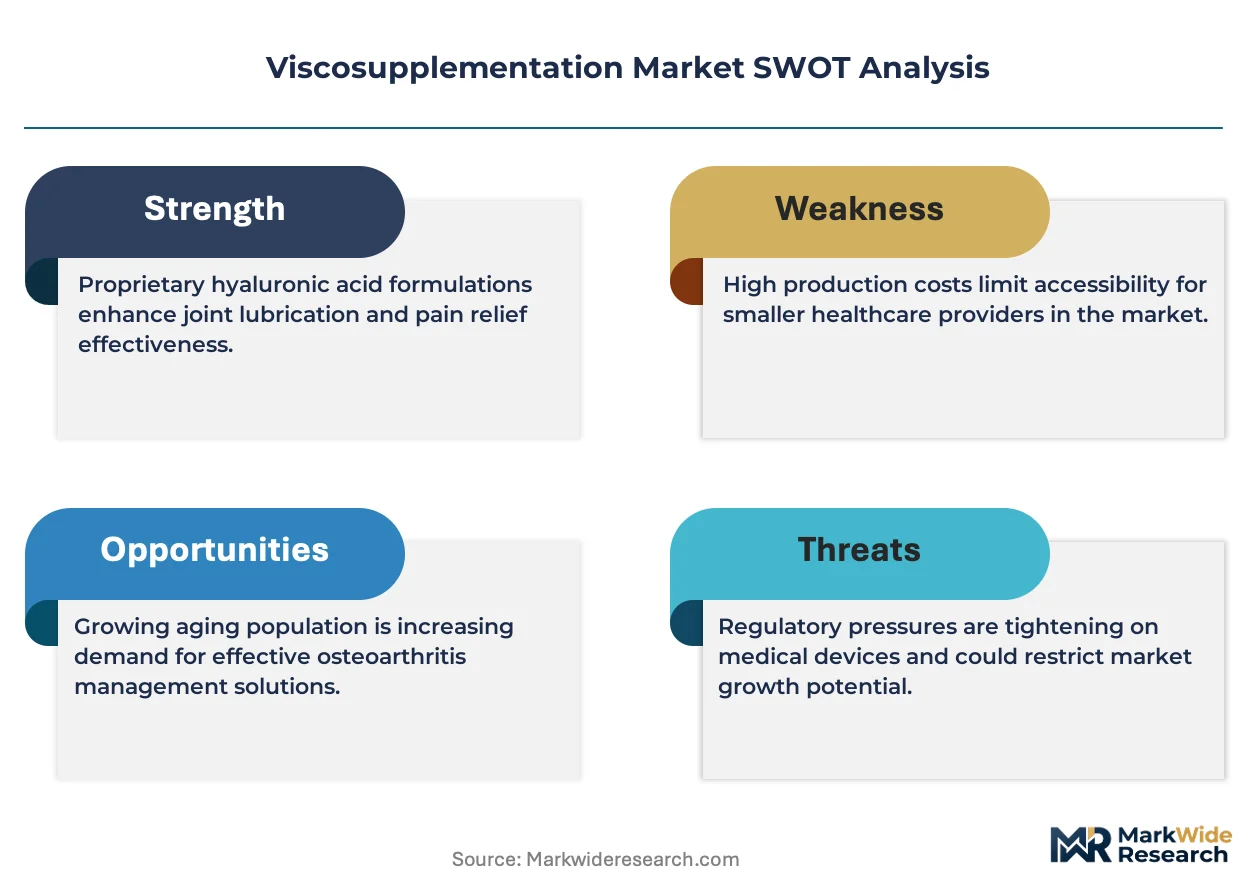
The viscosupplementation market pivots on Medicare reimbursement thresholds that increasingly favor outpatient joint injections over surgical interventions, compressing provider economics and accelerating consolidation around single-injection formulations.
Growth Catalysts
- Aging demographics in developed economies:Rising osteoarthritis prevalence among populations over 65 in the United States and Japan expands the addressable patient pool for intra-articular therapies.
- CMS outpatient reimbursement codes:Medicare's coverage determination for hyaluronic acid injections performed in ambulatory surgical centers reduces patient cost burden and procedure wait times.
- Cross-linked polymer stabilization:Extended-release hyaluronic acid formulations extend therapeutic duration from weeks to months, improving patient compliance and clinical outcomes.
Market Restraints
- Pharmaceutical-grade sodium hyaluronate concentration:Raw material supply concentrates among Japanese and South Korean fermentation facilities, creating single-source vulnerability for Western manufacturers.
- FDA sterility validation requirements:The agency's tightened endotoxin and bioburden testing for intra-articular combination products extends new product approval timelines by 12-18 months.
- Platelet-rich plasma substitution:Autologous biologic therapies from sports medicine centers capture younger osteoarthritis patients seeking regenerative alternatives to synthetic injections.
Strategic Opportunities
- Brazilian regulatory pathway acceleration:ANVISA's streamlined device-drug classification review for hyaluronic acid products enables faster market entry than European MDR compliance.
- Telemedicine-integrated injection protocols:Remote patient monitoring platforms combined with home health nursing services expand access to patients in rural United States counties lacking orthopedic specialists.
- Biomaterial-cytokine convergence:Hyaluronic acid formulations incorporating anti-inflammatory peptides target the subsegment of patients with synovitis-driven pain unresponsive to standard viscosupplementation.
Industry Challenges
- ISO 13485 quality management certification:Small and mid-size manufacturers face 18-24 month implementation timelines to meet updated international standards for medical device quality systems.
- Clinical evidence generation costs:Head-to-head trials against corticosteroid injections require substantial capital deployment with uncertain payer recognition of superiority claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscosupplementation Market |
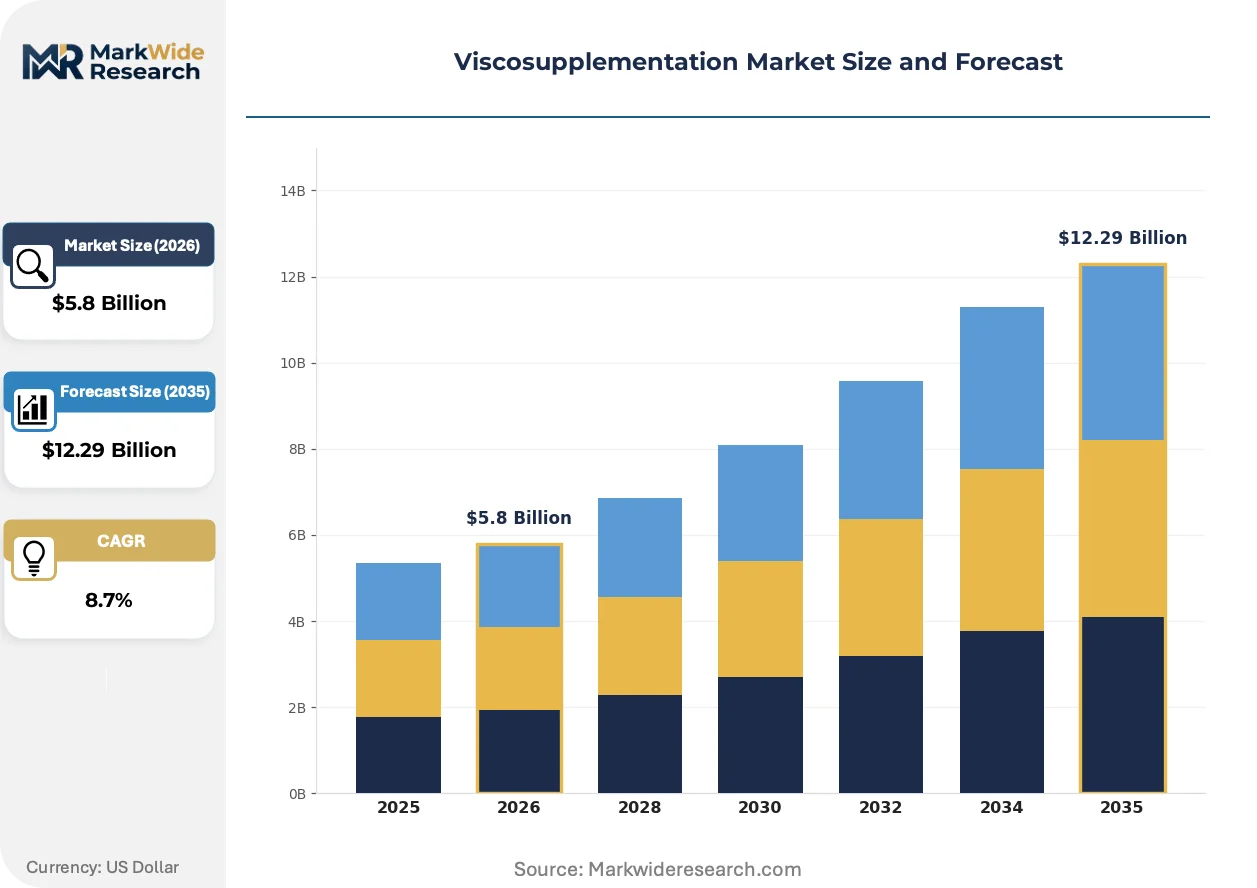
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Corticosteroids, Platelet-Rich Plasma, Others Application: Osteoarthritis, Sports Injuries, Joint Pain Relief, Surgical Applications End User: Hospitals, Clinics, Sports Medicine Centers, Rehabilitation Facilities Delivery Mode: Intra-articular, Injectable, Topical, Others |
| Companies Covered | Sanofi, Zimmer Biomet, Anika Therapeutics, Seikagaku Corporation, Bioventus, Hoffmann-La Roche, Fidia Farmaceutici, Smith & Nephew, Ferring Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscosupplementation Market Emerging Trajectories
Formulation science and reimbursement engineering are converging to reshape competitive advantage in joint pain management, with molecular architecture and delivery economics now inseparable from commercial viability.
Cross-linked high-molecular-weight hyaluronic acid is consolidating market preference among orthopedic clinics seeking to minimize injection frequency and maximize per-procedure revenue. Sports medicine centers in the United States have shifted procurement toward single-injection protocols that align with bundled payment models. This molecular stabilization approach is compressing demand for traditional three-injection regimens and commoditizing standard hyaluronic acid offerings.
Europe's MDR framework imposes clinical evidence requirements that slow new viscosupplementation formulation approvals relative to prior CE-marking pathways. The regulation mandates post-market surveillance and PMCF studies that smaller manufacturers struggle to fund. German and French orthopedic device distributors are responding by consolidating supplier relationships toward established portfolios with existing MDR certifications.
Patient self-referral through direct-to-clinic scheduling platforms is displacing traditional primary-care-gatekeeper models for osteoarthritis diagnosis. United States-based telehealth services now route patients straight to injection-certified clinics, bypassing rheumatology consultations. This channel compression is most visible in Florida and Arizona retirement corridors where Medicare Advantage plans incentivize rapid intervention.
Viscosupplementation Market Segmentation
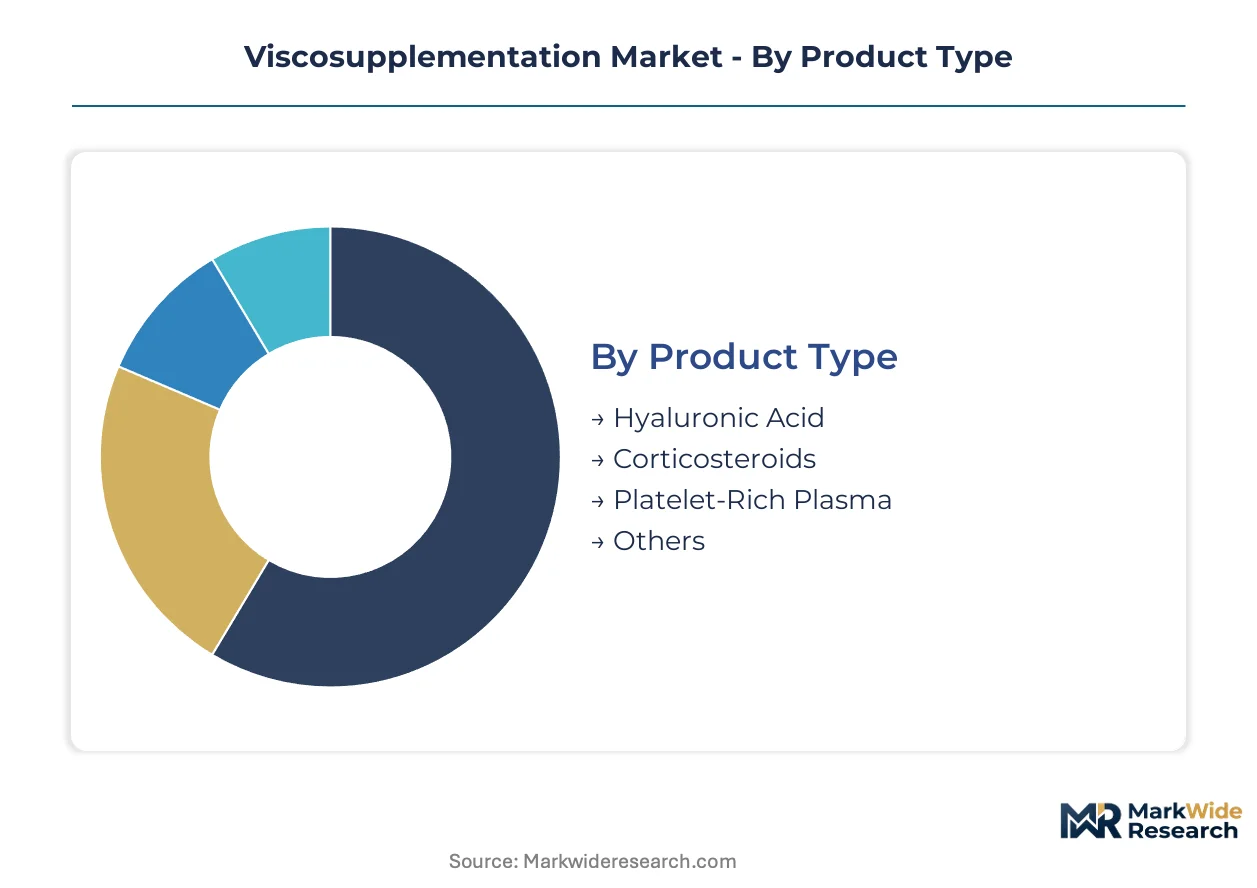
Viscosupplementation procurement varies sharply by clinical setting, molecular formulation, and reimbursement pathway. Segment-specific demand patterns determine which manufacturers capture margin versus volume positions.
Product Type:
Buyers differentiate by therapeutic mechanism, injection frequency tolerance, and autologous versus synthetic preference.
- Hyaluronic Acid:Synthetic formulations spanning 500-6,000 kDa molecular weights dominate current procedure volumes. United States orthopedic clinics favor high-concentration cross-linked variants that align with Medicare's single-injection reimbursement codes.
- Platelet-Rich Plasma:Autologous biologics require centrifuge processing at point-of-care. Sports medicine centers in Florida and Arizona retirement corridors adopt these therapies for younger osteoarthritis patients seeking regenerative alternatives.
- Corticosteroids:Anti-inflammatory compounds provide rapid pain relief but shorter duration than viscosupplementation. Rheumatology practices deploy these for acute flare management.
- Others:Emerging formulations include hyaluronic acid-cytokine conjugates and synthetic polymer alternatives. Japanese manufacturers pilot extended-release biodegradable scaffolds.
Hyaluronic acid leads volumes today; platelet-rich plasma is gaining share fastest.
Application:
Clinical indication determines molecular specification, injection protocol, and payer coverage determination.
- Osteoarthritis:Degenerative joint disease in weight-bearing knees and hips constitutes the primary addressable population. Japanese and United States Medicare systems reimburse intra-articular injections as first-line surgical alternatives.
- Sports Injuries:Acute ligament and meniscal trauma in active populations drives demand for combination therapies. Professional athletic facilities in Germany and Texas prioritize rapid return-to-play protocols.
- Joint Pain Relief:Generalized arthralgia without radiographic degeneration targets a broader patient pool. Primary care gatekeepers in rural United States counties increasingly refer to telemedicine-integrated injection clinics.
- Surgical Applications:Adjunctive use during arthroscopy and post-operative lubrication supports healing. Ambulatory surgical centers bundle these into orthopedic procedure packages.
Osteoarthritis commands the largest patient base; sports injuries show the steepest expansion trajectory among younger demographics.
End User:
Facility type dictates procurement scale, formulary control, and reimbursement capture mechanics.
- Hospitals:Academic medical centers and integrated delivery networks negotiate enterprise contracts spanning multiple therapeutic areas. Their purchasing committees prioritize FDA-compliant suppliers with established MDR certifications for European-sourced devices.
- Clinics:Independent orthopedic and rheumatology practices drive single-injection protocol adoption. These settings maximize per-procedure revenue under Medicare's outpatient payment rates.
- Sports Medicine Centers:Specialized facilities concentrate demand for autologous and regenerative therapies. Their procurement teams source platelet-rich plasma systems and cross-linked hyaluronic acid through direct manufacturer relationships.
- Rehabilitation Facilities:Post-acute care settings employ viscosupplementation as part of multimodal pain management. Physical therapy integration varies by United States state licensing regulations.
Clinics process the highest injection volumes; sports medicine centers are expanding their share of premium formulation procurement.
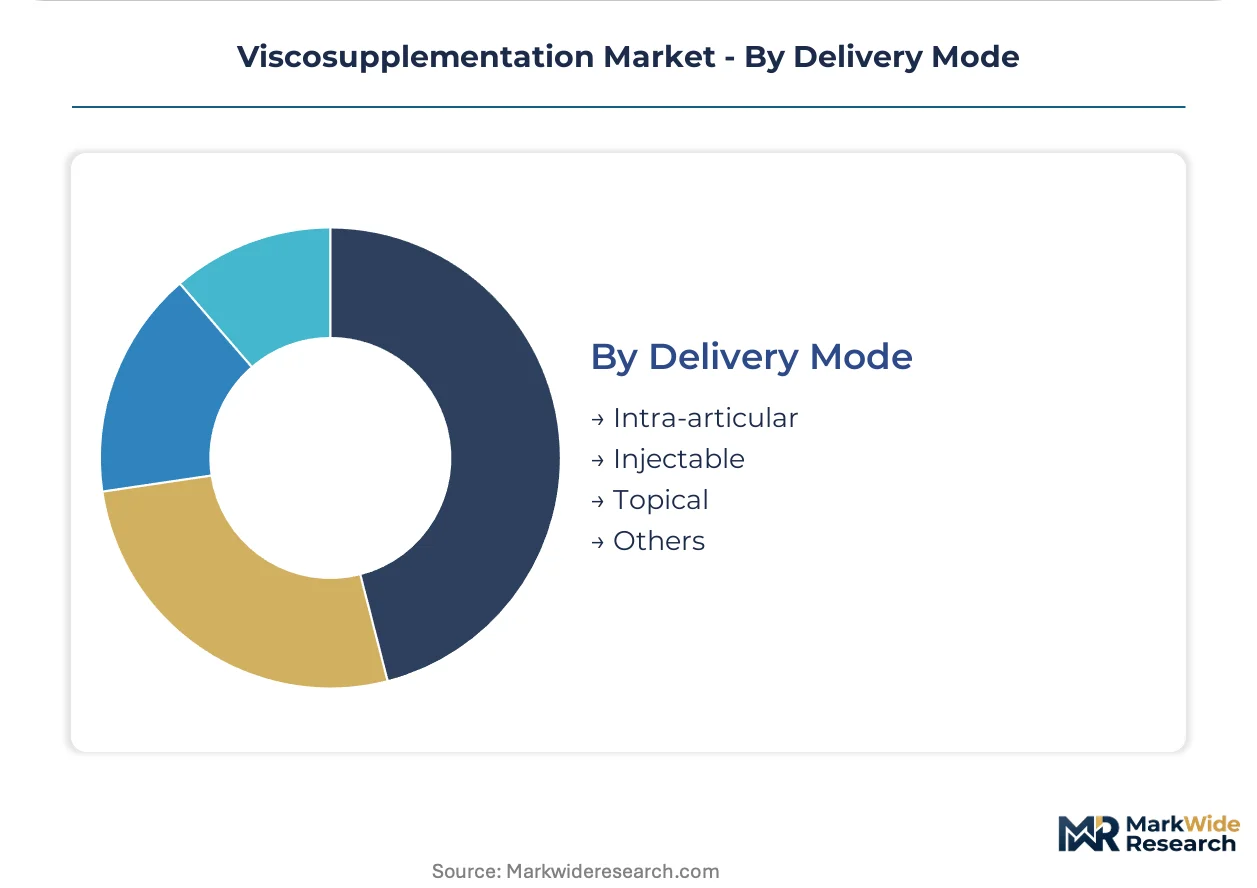
Delivery Mode:
Route of administration determines manufacturing complexity, sterility requirements, and clinical training needs.
- Intra-articular:Direct joint space injection remains the standard for knee and hip osteoarthritis. FDA device-drug combination rules impose stringent endotoxin and bioburden testing that extends approval timelines.
- Injectable:Cross-linked polymer formulations enable extended-release kinetics over months rather than weeks. South Korean and Japanese fermentation facilities supply pharmaceutical-grade sodium hyaluronate for these advanced preparations.
- Topical:Transdermal hyaluronic acid applications target superficial joint pain without invasive procedure requirements. Consumer health divisions market these outside formal reimbursement channels.
- Others:Experimental routes include subcutaneous depot formulations and hydrogel implants. German orthopedic researchers evaluate sustained-release matrices for shoulder applications.
Intra-articular delivery dominates current utilization; injectable extended-release formulations are climbing fastest in United States bundled payment environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement codes favor single-injection protocols, while Japanese raw material suppliers concentrate pharmaceutical-grade sodium hyaluronate production. Germany's MDR compliance timelines diverge sharply from Brazil's accelerated regulatory pathway.
United States
Medicare Advantage plans in Florida and Arizona retirement corridors drive demand for outpatient joint injections. CMS reimbursement thresholds for ambulatory surgical centers compress provider economics toward single-injection formulations. The Mayo Clinic in Rochester anchors clinical validation trials for cross-linked polymer protocols.
Japan
Aging demographics exceeding 29% population over 65 expand the addressable osteoarthritis patient pool. PMDA oversees sterility validation for intra-articular combination products under pharmaceutical regulations. Tokyo and Osaka metropolitan clusters concentrate fermentation facilities producing pharmaceutical-grade sodium hyaluronate raw material.
Germany
EMA's MDR framework mandates post-market surveillance studies that slow new formulation approvals. German orthopedic device distributors consolidate supplier relationships toward established MDR-certified portfolios. The Munich-Stuttgart medical technology corridor hosts sports medicine centers adopting autologous platelet-rich plasma therapies.
Brazil
ANVISA's streamlined device-drug classification review enables faster market entry than European compliance pathways. Private health insurance expansion in São Paulo and Rio de Janeiro broadens access to premium hyaluronic acid formulations. The São Paulo state cluster attracts regional distribution headquarters for intra-articular product manufacturers.
South Korea
MFDS regulates cross-linked polymer formulations under medical device quality management standards. Seoul Capital Area hospitals pioneer telemedicine-integrated injection protocols for rural patient access. The Songdo biocluster hosts manufacturing facilities supplying extended-release hyaluronic acid to export markets.
Viscosupplementation Market Vendor Landscape
Top-tier vendors anchor high-concentration cross-linked segments, while mid-scale specialists concentrate on raw material supply and regional formulation variants. The vendor base stratifies across biologics manufacturing scale, orthobiologics R&D specialization, and pharmaceutical-grade sodium hyaluronate supply chain control. Three archetypes dominate: integrated biopharmaceutical conglomerates, dedicated orthobiologics developers, and fermentation-based raw material suppliers. Competitive moves center on M&A for MDR certification portfolios and backward integration into captive sodium hyaluronate production.
Among the integrated biopharmaceutical tier, Sanofi and Hoffmann-La Roche occupy positions reflecting biologics manufacturing scale and diversified therapeutic portfolios. Anika Therapeutics exemplifies the orthobiologics specialist archetype, while Seikagaku Corporation anchors the raw material supply tier through its position in pharmaceutical-grade sodium hyaluronate fermentation.
| Leading Market Players |
|---|
| Sanofi |
| Zimmer Biomet |
| Anika Therapeutics |
| Seikagaku Corporation |
| Bioventus |
| Hoffmann-La Roche |
| Fidia Farmaceutici |
| Smith & Nephew |
| Ferring Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade sodium hyaluronate fermentation costs cascade through three pricing tiers, with Japanese and South Korean raw material concentration elevating premium cross-linked formulations above commodity multi-injection alternatives. CMS reimbursement compression in United States outpatient settings forces orthopedic clinics toward single-injection protocols that maximize per-procedure yield despite higher unit acquisition costs.
Pricing Analysis
Capacity additions in South Korean bioclusters are reshaping price floors for extended-release hyaluronic acid formulations, pressuring legacy Japanese suppliers to defend market position. Three-tier pricing structure across premium cross-linked, standard linear, and economy non-cross-linked variants segments buyers by injection frequency tolerance and Medicare code alignment. Price differentiation rests on FDA device-drug combination certification tier and molecular weight specification, with hospital systems commanding volume discounts unavailable to independent clinics. Cost compression in standard linear hyaluronic acid intensifies as Brazilian and South Korean manufacturers expand export capacity, eroding margins for undifferentiated multi-injection regimens. Sports medicine centers exhibit lowest price sensitivity, prioritizing therapeutic duration and patient compliance over per-unit acquisition cost.
Supply Chain Analysis
Domestic-content mandates in Brazil and South Korea are reshaping sourcing patterns for intra-articular device assembly, compelling manufacturers to establish regional fermentation partnerships. Geographic supply concentration centers on Japan, South Korea, and China for pharmaceutical-grade sodium hyaluronate raw material, with Tokyo-Osaka and Seoul-Songdo clusters controlling upstream fermentation capacity. Raw material dependencies extend to cross-linking agents, endotoxin-free packaging, and validated sterilization services. Single-source vulnerability concentrates in Japanese sodium hyaluronate suppliers serving Western formulation facilities. Distribution runs through orthopedic device distributors in Germany, direct manufacturer relationships with United States clinic chains, and hospital purchasing committees in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viscosupplementation market functions as a regulatory compounder where FDA sterility guideline tightening and CMS reimbursement code revisions continuously reshape competitive access and demand concentration.
For Market Incumbents: Hedge against platelet-rich plasma substitution by deepening orthobiologics R&D pipelines and securing captive sodium hyaluronate supply through backward integration into Japanese or South Korean fermentation partnerships. Reinforce formulary position with hospital systems by accelerating MDR certification completion ahead of smaller competitors facing 18-24 month implementation timelines. For New Entrants and Emerging Players: Launch via telemedicine-integrated injection protocols targeting rural United States counties lacking orthopedic specialist density, where Medicare Advantage plans incentivize rapid patient routing. Exploit ANVISA's streamlined Brazilian regulatory pathway to establish regional distribution headquarters before European MDR compliance barriers harden further. Target sports medicine centers in Florida and Arizona retirement corridors with autologous therapy positioning that differentiates from synthetic hyaluronic acid commoditization. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification scarcity and clinical evidence generation costs strand mid-scale manufacturers without MDR-compliant portfolios. Long-term viability favors targets with established FDA device-drug combination approvals and existing CMS reimbursement code alignment. Acquisition target archetype: regional formulation specialists with captive raw material supply and telemedicine channel integration. Signal to watch: CMS outpatient payment rate revisions for single-injection versus multi-injection protocols as inflection indicator for demand shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive sodium hyaluronate supply insulates margin from Japanese raw material concentration. |
| MDR Certification Acceleration | Early EMA compliance secures German and French distributor relationships ahead of stranded competitors. |
| Telemedicine Channel Partnership | Remote patient monitoring platforms expand access to rural United States Medicare populations. |
| Cross-Linked Polymer R&D Investment | Extended-release kinetics differentiate premium positioning from commoditized multi-injection alternatives. |
| ANVISA Regulatory Pathway Entry | Brazilian streamlined review enables faster market establishment than European clinical evidence requirements. |
Methodological Framework
Coverage spans the United States, Japan, Germany, Brazil, and South Korea, with primary inputs from each market's reimbursement and regulatory environment. The approach combines structured interviews with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement determinations, and ANVISA registration records. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue segmentation across the analysis window.
Rate-of-change decomposition isolates volume growth from price-mix effects across product type, application, end user, and delivery mode dimensions. The analytical framework models osteoarthritis prevalence demographics, CMS outpatient payment rate trajectories, and sports medicine center expansion patterns throughout the forecast period. CAGRs derive from segmented procedure volume projections calibrated to reimbursement code utilization trends and molecular formulation adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA sterility guideline enforcement intensity and platelet-rich plasma therapy substitution velocity. Forecasts reflect assumptions regarding Medicare reimbursement stability, Japanese raw material supply continuity, and MDR certification timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market