
 Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market | 2026-2036
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market Analysis
Hospital and specialty pharmacy procurement is tilting toward fixed-dose combination products that pair DPP-4 inhibitors with SGLT2 agents or metformin. Merck leverages its manufacturing scale to sustain broad formulary placement across integrated delivery networks. Boehringer Ingelheim anchors its position through in-house production of linagliptin active pharmaceutical ingredient. Eli Lilly and Company competes by extending its diabetes portfolio into overlapping metabolic indications.
Dipeptidyl Peptidase-4 (DPP-4) inhibitors are oral hypoglycemic agents that block the DPP-4 enzyme, thereby prolonging the half-life of incretin hormones GLP-1 and GIP to stimulate glucose-dependent insulin secretion from pancreatic beta cells. These agents typically achieve HbA1c reductions of 0.5–1.0 percentage points with minimal hypoglycemia risk, making them suitable for elderly and renally impaired populations. Sitagliptin dominates product type volume due to first-mover availability and extensive generic entry, while linagliptin commands premium positioning through its non-renal clearance profile. Extended-release formulations within the formulation segment represent the fastest-growing delivery category as patient adherence programs favor reduced dosing frequency.
The FDA's cardiovascular outcomes trial requirements for new antidiabetic therapies have reshaped DPP-4 inhibitor labeling and post-market surveillance obligations, particularly following the SAVOR-TIMI 58 heart failure signal for saxagliptin. EMA's periodic safety update reports and the EU's pharmacovigilance framework sustain scrutiny of pancreatitis and pancreatic cancer signals across the class. Stakeholders must monitor whether GLP-1 receptor agonist expansion into obesity and cardiovascular risk reduction displaces DPP-4 positioning in treatment algorithms or creates sustained combination therapy opportunities.
Market Dynamics
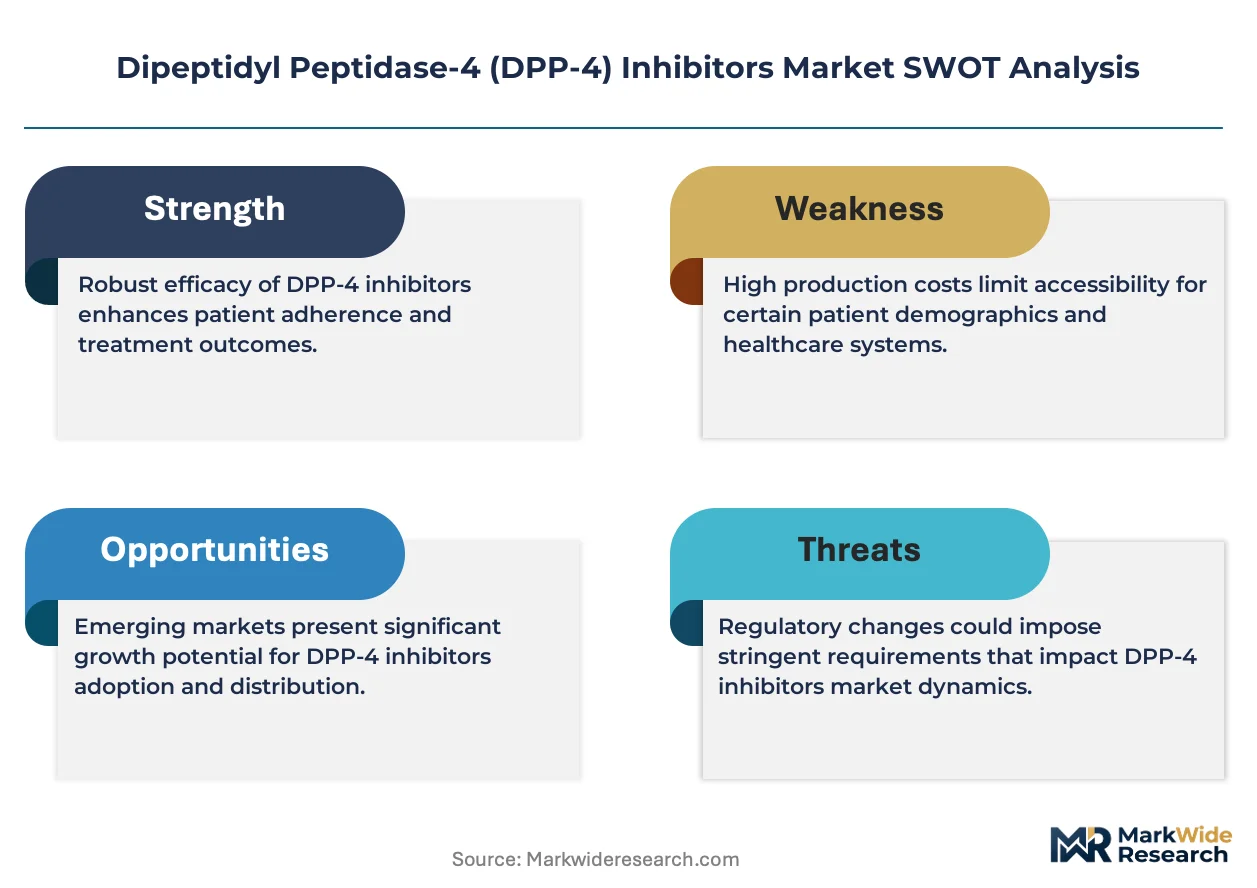
Hospital procurement committees are consolidating oral antidiabetic formularies around cardiovascular safety profiles, forcing manufacturers to reposition DPP-4 inhibitors within combination therapy protocols rather than standalone prescribing.
Growth Catalysts
- Medicare Part D reimbursement expansion:Outpatient oral antidiabetic coverage in the United States incentivizes physician prescribing of DPP-4 agents outside acute care settings.
- Fixed-dose combination innovation:Pairing DPP-4 inhibitors with SGLT2 agents or metformin streamlines adherence protocols for elderly populations with polypharmacy burdens.
- Renal impairment suitability:Linagliptin's non-renal clearance profile captures nephrologist preference in dialysis-dependent diabetes management.
Market Restraints
- Active pharmaceutical ingredient concentration:Boehringer Ingelheim's captive linagliptin production creates supply vulnerability for non-integrated competitors.
- GLP-1 receptor agonist substitution:Semaglutide and tirzepatide expansion into obesity and cardiovascular risk reduction threatens DPP-4 positioning in treatment algorithms.
- FDA cardiovascular outcomes trial mandates:Post-market surveillance obligations for heart failure signals impose sustained compliance costs across the therapeutic class.
Strategic Opportunities
- Extended-release formulation penetration:Once-daily dosing protocols align with Medicare Advantage adherence quality metrics and star rating incentives.
- Integrated delivery network contracting:Risk-based agreements with United States hospital systems lock in multi-year formulary placement against generic sitagliptin erosion.
- EMA pharmacovigilance framework harmonization:Standardized pancreatitis signal monitoring across EU member states reduces regulatory fragmentation for pan-European launches.
Industry Challenges
- Clinical trial endpoint complexity:Demonstrating non-inferiority against GLP-1 cardiovascular outcomes requires larger enrollment and longer duration than historical DPP-4 development programs.
- Patent cliff navigation:Generic sitagliptin saturation in the United States compresses pricing power for originator brands and biosimilar entrants alike.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market |
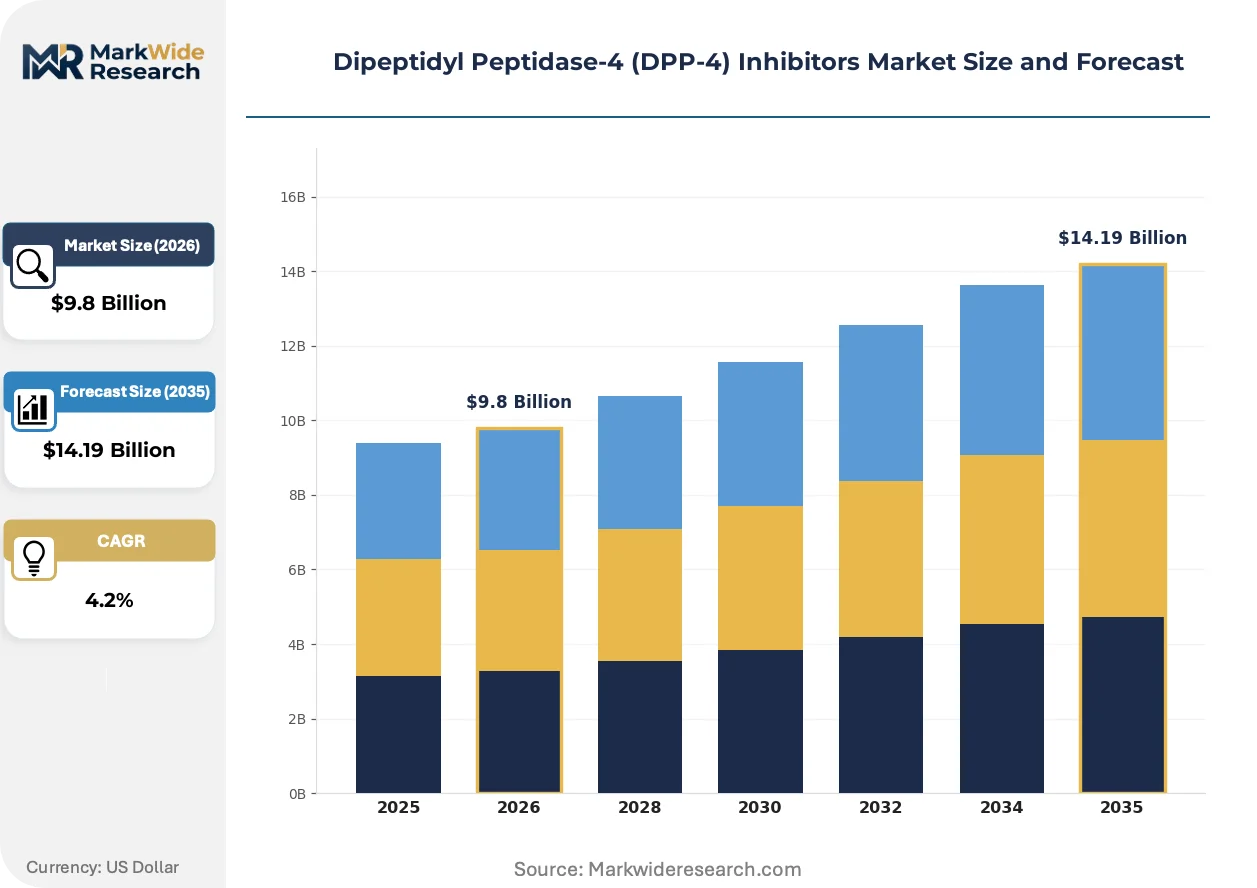
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Therapy Area: Diabetes, Obesity, Metabolic Syndrome, Cardiovascular Disorders End User: Hospitals, Clinics, Pharmacies, Homecare Settings Formulation: Tablets, Injectable, Extended Release, Combination Therapy |
| Companies Covered | Merck, AstraZeneca, Boehringer Ingelheim, Eli Lilly and Company, Takeda Pharmaceutical, Novartis, Pfizer, Bristol-Myers Squibb, Mitsubishi Tanabe Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape how DPP-4 inhibitors reach patients, with delivery mechanisms and safety surveillance both undergoing structural revision.
Extended-release matrix technology is collapsing the adherence gap between DPP-4 inhibitors and long-acting injectable alternatives. Medicare Advantage plans in the United States are prioritizing once-daily oral regimens in their quality bonus calculations. The compression of dosing frequency is enabling DPP-4 retention in step-therapy protocols that previously favored weekly injections.
EMA's periodic safety update report requirements are intensifying post-authorization scrutiny of pancreatitis and pancreatic cancer signals across the DPP-4 class. Manufacturers must now maintain active surveillance infrastructure that rivals pre-approval clinical trial operations. The EU pharmacovigilance framework is redirecting medical affairs resources toward real-world evidence generation rather than promotional activities.
Hospital formularies are unbundling oral antidiabetic procurement from traditional purchasing cooperatives. Integrated delivery networks in the United States are negotiating direct manufacturer contracts that tie formulary placement to cardiovascular outcomes guarantees. This disintermediation is visible most acutely in Medicare-dependent regions where hospital systems bear full risk for thirty-day readmission penalties.
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market Segmentation
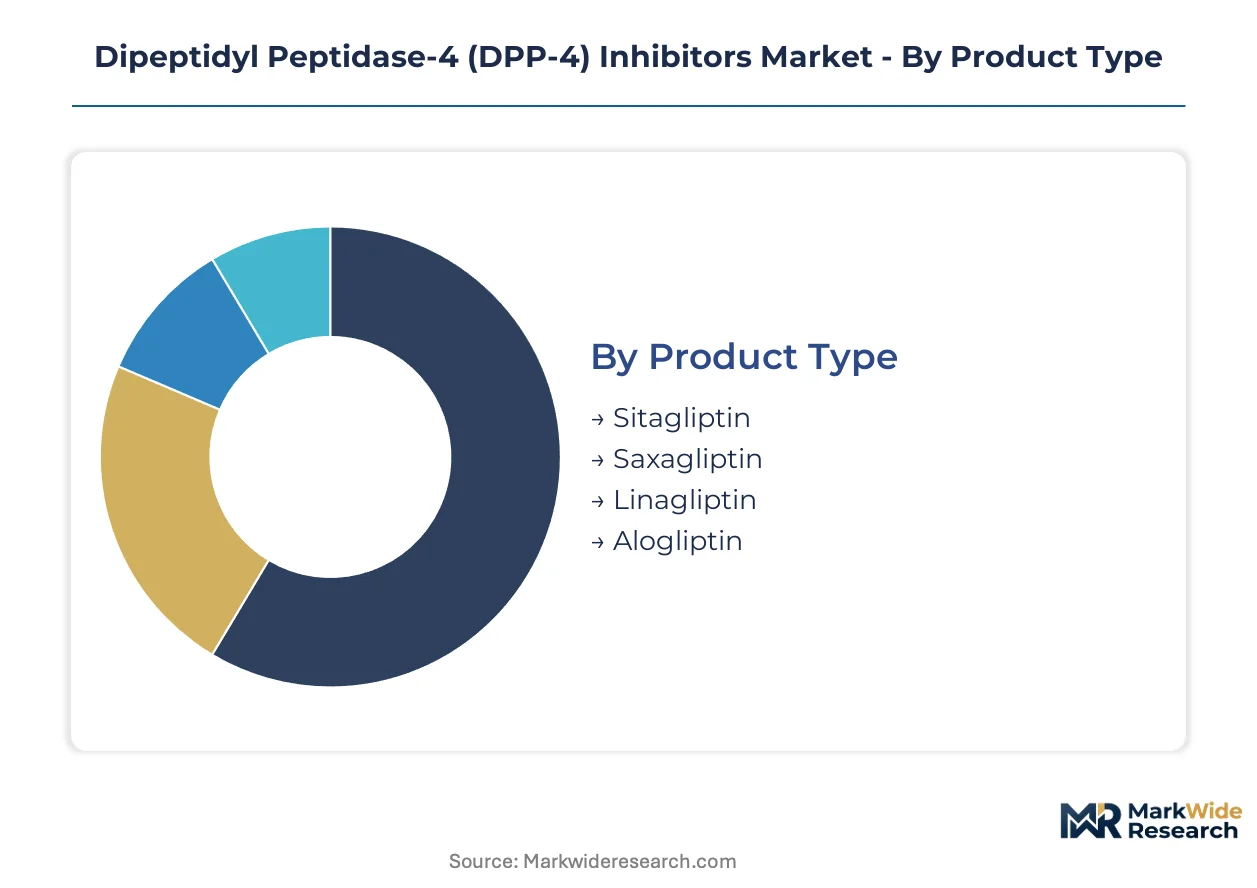
DPP-4 inhibitor commercialization requires precise segment targeting as prescribing patterns diverge between hospital formularies and outpatient settings. Manufacturers must align formulation development with specific therapy area demands and reimbursement pathways.
Product Type:
Use-case spectrum spans first-line oral therapy to niche nephrology applications, with renal clearance profiles dictating prescriber selection across patient populations.
- Sitagliptin:First-mover availability and extensive generic saturation have positioned this agent as the volume foundation of DPP-4 prescribing. Medicare Part D plans in the United States favor sitagliptin for step-therapy protocols due to established prior authorization pathways and cost containment metrics.
- Linagliptin:Non-renal clearance enables dosing without adjustment in dialysis-dependent patients, capturing nephrologist preference where other agents require renal function monitoring. Boehringer Ingelheim's captive API production sustains premium positioning against generic erosion elsewhere in the class.
- Saxagliptin:FDA cardiovascular outcomes labeling requirements following SAVOR-TIMI 58 have restricted this agent to specific risk-stratified populations.
- Alogliptin:Concentrated availability in Japanese and select Asian markets through Takeda's regional distribution infrastructure.
Established volume favors sitagliptin; emerging adoption favors linagliptin.
Therapy Area:
Cost tier stratification separates chronic disease management from emerging metabolic indications, with cardiovascular risk reduction commanding premium reimbursement.
- Diabetes:Core therapeutic indication with HbA1c reduction of 0.5–1.0 percentage points and minimal hypoglycemia risk driving elderly population suitability. Hospital formularies in the United States consolidate procurement around cardiovascular safety profiles for this indication.
- Cardiovascular Disorders:Post-approval outcomes data requirements reshape positioning as clinicians weigh DPP-4 agents against SGLT2 inhibitors and GLP-1 receptor agonists for heart failure risk modification. EMA periodic safety update reports sustain scrutiny of this application.
- Obesity:Limited standalone efficacy restricts DPP-4 use to combination protocols with GLP-1 expansion threatening displacement.
- Metabolic Syndrome:Emerging prescriber interest concentrates in integrated delivery networks with bundled payment accountability.
Reimbursement density clusters in diabetes; pipeline investment shifts toward cardiovascular outcomes differentiation.
End User:
Customer type fragmentation reflects divergent procurement authority between institutional formularies and direct-to-patient dispensing channels.
- Hospitals:Integrated delivery networks negotiate direct manufacturer contracts tying formulary placement to cardiovascular outcomes guarantees. United States hospital systems in Medicare-dependent regions bear full risk for thirty-day readmission penalties, driving protocol standardization.
- Pharmacies:Medicare Advantage star rating incentives prioritize once-daily oral regimens and adherence metrics. Extended-release formulations gain shelf placement through quality bonus calculations.
- Clinics:Outpatient endocrinology practices concentrate combination therapy prescribing where fixed-dose products streamline polypharmacy management.
- Homecare Settings:Limited penetration due to oral administration simplicity reducing need for nursing oversight.
Procurement consolidation favors hospital systems; patient access expansion favors pharmacy channels.
Formulation:
Supply concentration in extended-release technology creates competitive moats as adherence programs prioritize reduced dosing frequency.
- Extended Release:Matrix technology enables once-daily dosing that aligns with Medicare Advantage quality metrics and competes with weekly injectable alternatives. Manufacturers investing in modified-release platforms retain positioning in step-therapy protocols.
- Combination Therapy:Fixed-dose pairing with SGLT2 inhibitors or metformin streamlines adherence for elderly populations with polypharmacy burdens. Hospital procurement committees consolidate formularies around these products.
- Tablets:Immediate-release formulations face generic saturation and pricing compression in the United States market.
- Injectable:Minimal DPP-4 penetration as GLP-1 receptor agonists dominate injectable metabolic therapy.
Technology investment concentrates in extended release; commercial volume concentrates in combination formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution of temperature-sensitive oral antidiabetic agents, while the US Interstate 95 corridor anchors North American formulary procurement networks.
United States
Medicare Part D reimbursement expansion drives outpatient DPP-4 prescribing outside acute care settings. FDA cardiovascular outcomes trial mandates reshape post-market surveillance obligations for heart failure signals. The Philadelphia-Camden pharmaceutical corridor concentrates formulary negotiation activity among integrated delivery networks.
Germany
EMA pharmacovigilance framework harmonization reduces regulatory fragmentation for pan-European launches of extended-release formulations. The country's national pharmaceutical regulator maintains active surveillance infrastructure for pancreatitis signal monitoring across the therapeutic class. The Rhine-Main biotech cluster hosts pharmacovigilance operations serving EU member states.
Japan
PMDA post-approval safety reporting requirements sustain scrutiny of pancreatic cancer signals across DPP-4 inhibitors. METI's healthcare technology assessment protocols influence reimbursement pricing for combination therapies. The Kansai region's pharmaceutical manufacturing base supplies modified-release platforms to Asian markets.
United Kingdom
NICE technology appraisals prioritize cardiovascular outcomes data in oral antidiabetic formulary placement decisions. The Medicines and Healthcare products Regulatory Agency enforces periodic safety update requirements aligned with EMA frameworks. The Greater London hospital procurement consortium negotiates risk-based contracts tying placement to readmission metrics.
India
CDSCO accelerated approval pathways for fixed-dose combination products streamline market entry for DPP-4 pairing with metformin. The country's national pharmaceutical regulator harmonizes safety surveillance with WHO prequalification standards. The Hyderabad-Visakhapatnam API manufacturing belt supplies active pharmaceutical ingredients to regional formulation facilities.
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market Vendor Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive active pharmaceutical ingredient production and established hospital formulary relationships. The competitive terrain separates originator brands defending patent-protected positions from generic manufacturers exploiting sitagliptin saturation. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with in-house API synthesis, specialist diabetes care portfolios with endocrinology-focused medical affairs, and regional generic houses leveraging cost-competitive manufacturing. Dominant competitive moves include strategic partnerships for fixed-dose combination development and geographic expansion through integrated delivery network contracting.
Among vertically integrated conglomerates, Merck and Boehringer Ingelheim occupy positions exemplifying contrasting supply architectures—one leveraging manufacturing scale for broad formulary placement, the other anchoring premium positioning through captive linagliptin production. Eli Lilly and Company sits within the specialist diabetes care tier, representing portfolio diversification strategies that extend into overlapping metabolic indications. These three entities collectively illustrate how API control, formulation innovation, and therapeutic area focus define competitive differentiation in oral antidiabetic markets.
| Leading Market Players |
|---|
| Merck |
| AstraZeneca |
| Boehringer Ingelheim |
| Eli Lilly and Company |
| Takeda Pharmaceutical |
| Novartis |
| Pfizer |
| Bristol-Myers Squibb |
| Mitsubishi Tanabe Pharma |
| Others |
Supply Flow & Price Mechanics
Single-source API dependency for linagliptin production determines both premium tier spreads and supply chain shape across the DPP-4 inhibitor market. Boehringer Ingelheim's captive manufacturing of this active pharmaceutical ingredient compresses pricing flexibility for non-integrated competitors while forcing hospital procurement committees toward risk-mitigation contracting.
Pricing Analysis
Volume-discount tiering separates originator brands from generic sitagliptin saturation and premium linagliptin positioning. Three-tier pricing structure across premium, standard, and economy levels rests on renal clearance profiles, cardiovascular outcomes labeling, and formulary placement depth. Cost compression in the generic tier intensifies because Medicare Part D step-therapy protocols favor lowest-cost alternatives. Integrated delivery networks exhibit lowest price sensitivity; independent pharmacies face highest margin pressure.
Supply Chain Analysis
Extended payment terms from Boehringer Ingelheim and Merck to hospital procurement committees stabilize formulary relationships against generic erosion. Active pharmaceutical ingredient production concentrates in Germany, India, and the United States, with Hyderabad-Visakhapatnam supplying regional formulation facilities. Key inputs include DPP-4 enzyme inhibitors, metformin precursors, and SGLT2 agent intermediates. Single-source vulnerability for linagliptin API creates concentration risk. Distribution runs through integrated delivery network direct contracts and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DPP-4 inhibitor market represents early-cycle expansion as extended-release formulations penetrate Medicare Advantage adherence protocols. Fixed-dose combination innovation with SGLT2 agents sustains portfolio relevance against GLP-1 receptor agonist displacement.
For Market Incumbents: Build captive API manufacturing moats through backward integration into linagliptin precursor synthesis or strategic API supply agreements. Secure multi-year integrated delivery network contracts with cardiovascular outcomes guarantees to lock formulary placement against generic sitagliptin erosion. Prioritize extended-release formulation R&D to retain step-therapy positioning against weekly injectable alternatives.
For New Entrants and Emerging Players: Build out fixed-dose combination development capabilities targeting elderly polypharmacy populations in Medicare-dependent regions. White-space opportunity concentrates in extended-release metformin-DPP-4 pairings for nephrology clinics managing dialysis-dependent diabetes. Go-to-market angle: direct contracting with hospital systems bearing thirty-day readmission penalties.
For Investors and Strategic Acquirers: Specialist diabetes care portfolios with endocrinology-focused medical affairs infrastructure represent priority acquisition targets. Long-term viability hinges on GLP-1 receptor agonist expansion creating sustained combination therapy demand rather than pure displacement. Monitor FDA cardiovascular outcomes trial requirements for new molecular entities as inflection signal for DPP-4 class durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Streamlines adherence protocols for Medicare Advantage polypharmacy populations. |
| Extended-Release Formulation Investment | Aligns with CMS star rating incentives for once-daily oral regimens. |
| Integrated Delivery Network Contracting | Locks multi-year formulary placement against generic erosion through risk-based agreements. |
| Captive API Manufacturing Scale-Up | Reduces supply vulnerability for linagliptin-dependent premium positioning. |
| Cardiovascular Outcomes Data Generation | Satisfies FDA post-market surveillance mandates following SAVOR-TIMI 58 signals. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA periodic safety update reports, ClinicalTrials.gov cardiovascular outcomes databases, and Medicare Part D formulary placement records. Primary interviews captured perspectives from drug development executives, hospital procurement managers, formulary directors, payer access specialists, and nephrology clinicians. Bottom-up prescription volume modeling triangulates against top-down pharmaceutical market sizing across the analysis window.
Forecast inputs incorporate treatment line positioning, dosage form preference, regional regulatory cluster dynamics, and patient population renal function stratification. Analytical framework projects volume and value outputs across the modeling period through segment-level CAGR derivation incorporating cardiovascular outcomes trial completion timelines, generic entry waves, and GLP-1 receptor agonist substitution elasticity. Modeled inputs include hospital formulary consolidation velocity and Medicare Advantage quality bonus calculation weighting.
Practitioners should monitor FDA guidance revisions on heart failure risk assessment, EMA pharmacovigilance framework updates, and GLP-1 receptor agonist cardiovascular indication expansions for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained Medicare reimbursement favoring outpatient oral antidiabetic utilization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Anti-Radiation Drugs Market