
 China Human Papillomavirus Vaccine Market | 2026-2036
China Human Papillomavirus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
China Human Papillomavirus Vaccine Market Insights
China is fragmenting its HPV vaccine manufacturing base across multiple bioclusters. Xiamen Innovax Biotech leverages recombinant protein platforms to anchor supply for municipal immunization programs. Merck dominates the imported nonavalent segment through channel control over tier-one hospital pharmacies. Walvax competes on cost-engineered bivalent formulations for provincial CDC tenders.
Human papillomavirus vaccines are prophylactic biologics containing virus-like particles assembled from recombinant L1 capsid proteins, formulated with aluminum-containing adjuvants to elicit neutralizing antibodies against oncogenic HPV strains. Their primary purpose is preventing cervical, oropharyngeal, and anogenital cancers by interrupting viral transmission before epithelial infection occurs. The nonavalent category leads value generation due to expanded serotype coverage, while therapeutic vaccines represent the fastest-growing segment as developers target existing infections rather than prevention alone. Public health programs command the largest volume channel, though hospitals capture superior margins through private-pay administration.
NMPA oversees lot release testing and post-market pharmacovigilance, while China's National Immunization Program sets inclusion criteria for provincial procurement. GB standards specify cold chain parameters and VLP potency assays that shape manufacturing compliance costs. Stakeholders must monitor NMPA's evolving biologics data requirements and provincial tender pricing benchmarks to calibrate portfolio investments.
Market Dynamics
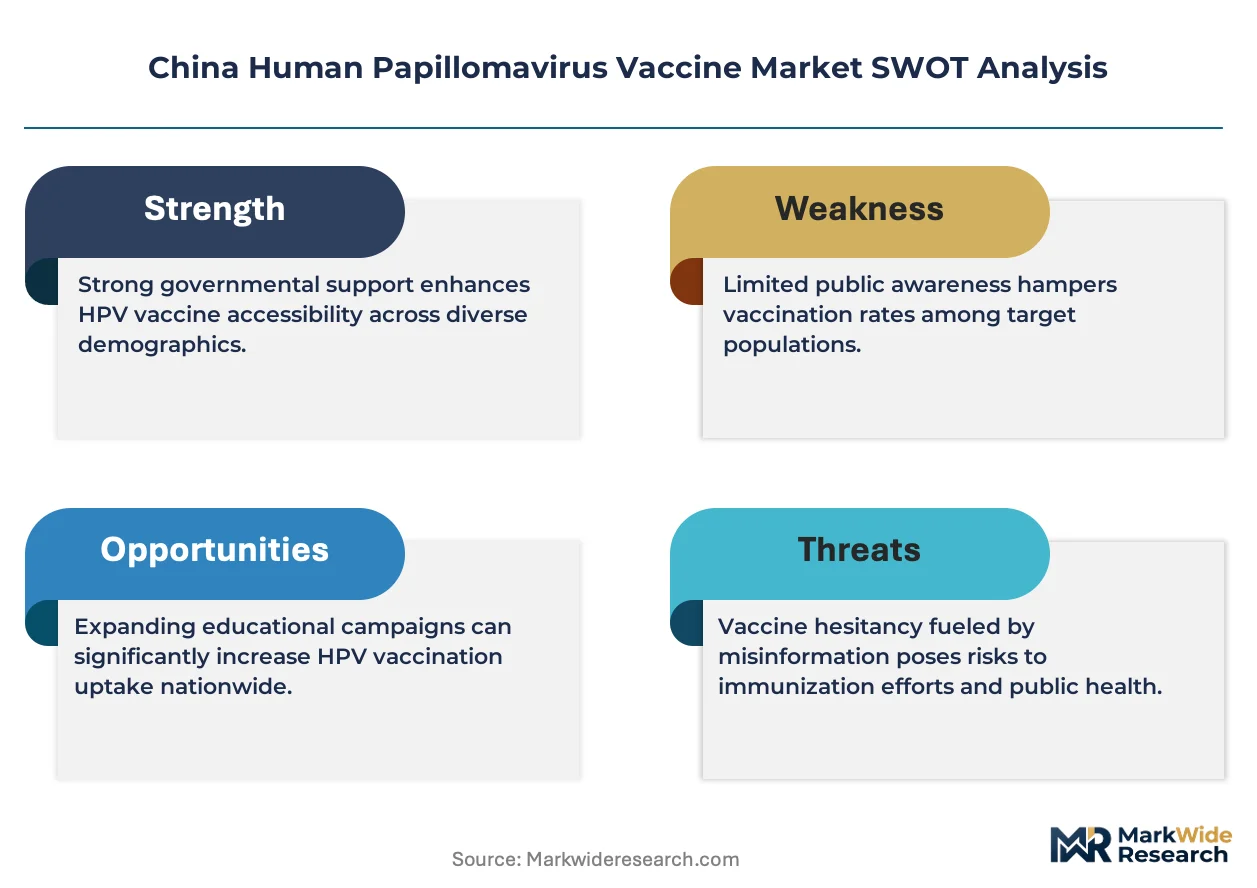
Provincial immunization program expansions are restructuring demand concentration across China's HPV vaccine market, shifting volume from private hospital channels toward municipal CDC procurement frameworks.
Growth Catalysts
- NMPA Accelerated Biologics Pathway:Streamlined review timelines compress domestic product approval cycles, enabling faster market entry for recombinant VLP manufacturers targeting provincial tender schedules.
- Municipal CDC Network Expansion:Tier-two and tier-three cities are integrating HPV vaccination into routine adolescent health services, broadening accessible administration points beyond tier-one hospital pharmacies.
- Recombinant Protein Platform Maturation:Yeast and insect cell expression systems achieve yield parity with imported benchmarks, reducing per-dose production costs for domestic bivalent formulations.
Market Restraints
- Aluminum Adjuvant Supply Concentration:Domestic aluminum hydroxide production clusters in Shandong and Henan provinces, creating input vulnerability for VLP formulation capacity scaling.
- Cold Chain Infrastructure Gaps:GB standard temperature compliance requirements exceed rural distribution network capabilities, limiting provincial immunization program reach in western provinces.
- Serotype Coverage Limitations:Bivalent vaccines face substitution pressure from nonavalent alternatives in urban private-pay segments, compressing margin pools for cost-engineered domestic products.
Strategic Opportunities
- Therapeutic Vaccine White Space:Developers targeting persistent HPV infections with immunotherapy constructs access unaddressed demand among screening-positive cohorts ineligible for prophylactic administration.
- Guangdong-Hong Kong-Macao Greater Bay Area Integration:Cross-border regulatory harmonization pilots enable accelerated clinical data sharing and manufacturing site certification reciprocity.
- Digital Vaccination Credential Systems:Municipal health platforms in Hangzhou and Shenzhen integrate HPV dose tracking with electronic health records, enabling precision recall campaigns and adherence monitoring.
Industry Challenges
- VLP Potency Assay Standardization:Lot release testing variability across provincial CDC laboratories creates batch qualification friction and inventory hold risks for manufacturers.
- Biologics Talent Scarcity:Fermentation process engineering and downstream purification expertise concentrates in Beijing and Shanghai bioclusters, constraining facility expansion in interior provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Human Papillomavirus Vaccine Market |
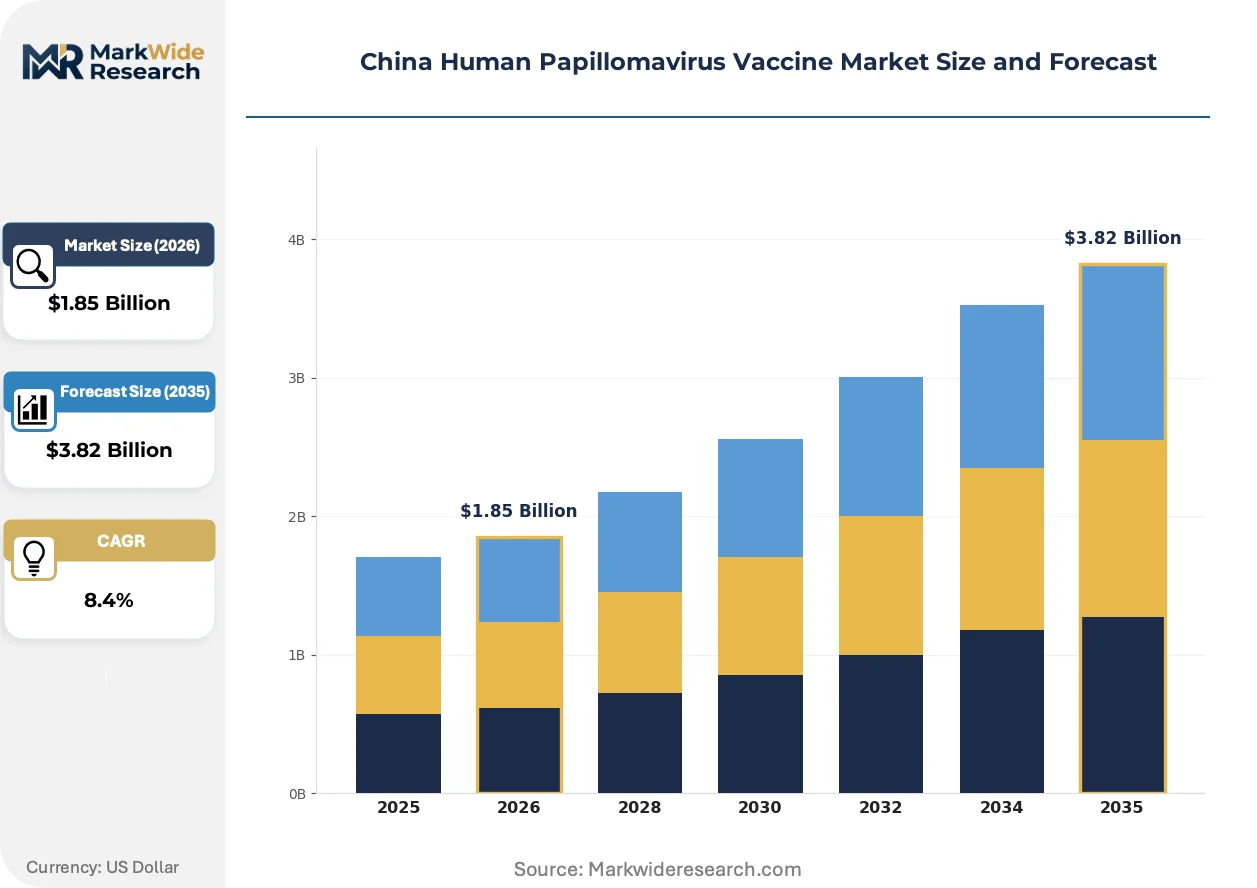
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrivalent Vaccine, Bivalent Vaccine, Nonavalent Vaccine, Therapeutic Vaccine End User: Healthcare Providers, Vaccination Clinics, Hospitals, Pharmacies Administration Route: Intramuscular, Subcutaneous, Intradermal, Oral Distribution Channel: Direct Sales, Wholesale, Online Retail, Public Health Programs |
| Companies Covered | Xiamen Innovax Biotech, Sinovac, Merck, Walvax, CanSino Biologics, Wantai BioPharm, Sinopharm CNBG, BioKangtai, GlaxoSmithKline, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Human Papillomavirus Vaccine Market Trends and Innovations
China's HPV vaccine landscape is experiencing a technology transition from imported dominance toward domestic platform parity, accompanied by regulatory process modernization and channel restructuring toward public procurement frameworks.
mRNA delivery technology is migrating from COVID-19 applications into HPV therapeutic development pipelines, with Suzhou and Chengdu bioclusters hosting clinical-stage programs targeting E6/E7 oncoprotein expression. Domestic developers are adopting lipid nanoparticle formulations previously licensed through pandemic supply agreements, compressing the timeline for therapeutic candidate advancement. This platform shift is enabling precision targeting of established infections rather than prevention alone, expanding addressable patient populations beyond adolescent cohorts.
NMPA's 2023 biologics data integrity guidelines impose enhanced pharmacovigilance reporting requirements on VLP manufacturers, mandating real-world effectiveness tracking through provincial immunization information systems. The regulation accelerates post-market surveillance infrastructure investment across domestic production facilities. Companies with existing digital health integrations in Jiangsu and Zhejiang provinces capture compliance advantages through automated adverse event reporting workflows.
Hospital pharmacy procurement committees in tier-one cities are consolidating HPV vaccine purchasing through centralized municipal tender platforms, displacing individual hospital contracting autonomy. This aggregation concentrates volume allocation decisions within provincial health commission procurement offices, compressing price negotiation leverage for imported nonavalent suppliers. The behavioral shift is most pronounced in Beijing and Shanghai, where municipal CDCs now administer majority shares of both public program and private-pay doses through integrated appointment systems.
China Human Papillomavirus Vaccine Market Segmentation
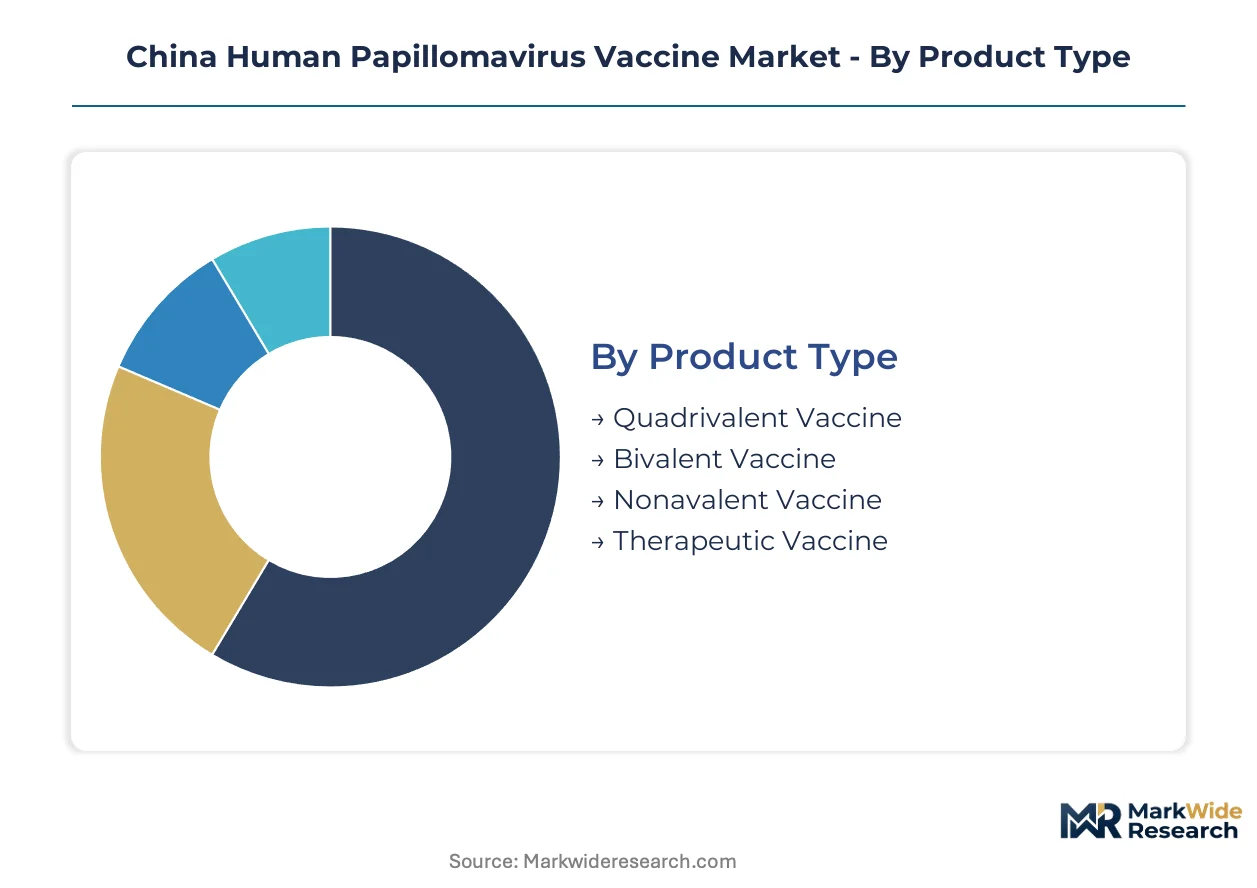
HPV vaccine segmentation in China reflects divergent technical specifications, administration settings, and procurement pathways. Manufacturers calibrate formulation strategies and channel investments against these category boundaries to capture volume in provincial immunization programs versus private-pay hospital segments.
Product Type:
The use-case spectrum spans prophylactic prevention across varying serotype breadths to emerging therapeutic interventions for existing infections.
- Nonavalent Vaccine:Virus-like particle formulations targeting nine oncogenic HPV strains command premium positioning in tier-one hospital pharmacies. Municipal CDCs in Beijing and Shanghai prioritize this category for adolescent catch-up campaigns despite higher per-dose procurement costs.
- Bivalent Vaccine:Recombinant L1 VLP products covering HPV-16 and HPV-18 dominate provincial tender volumes through cost-engineered manufacturing. Domestic producers leverage yeast expression platforms to undercut import pricing in western province immunization programs.
- Quadrivalent Vaccine:Mid-coverage formulations retain niche positioning in transitional markets upgrading from bivalent alternatives.
- Therapeutic Vaccine:E6/E7 oncoprotein-targeting immunotherapy constructs are climbing the fastest, addressing persistent infections in screening-positive cohorts ineligible for prophylactic administration.
Established volume favors bivalent formulations; emerging adoption favors therapeutic candidates.
End User:
Cost tier differentiation separates high-margin private administration from high-volume public procurement channels.
- Hospitals:Tier-one hospital pharmacies capture premium private-pay segments through direct patient billing. NMPA lot release documentation requirements create compliance barriers that reinforce hospital channel concentration for imported nonavalent products.
- Public Health Programs:Provincial CDC frameworks aggregate demand across municipal vaccination centers. GB standard cold chain specifications and VLP potency assay compliance shape manufacturer qualification for this high-volume channel.
- Vaccination Clinics:Specialized administration sites in Hangzhou and Shenzhen integrate digital appointment systems with municipal health platforms.
- Pharmacies:Retail channel penetration remains constrained by biologics storage requirements and prescription administration protocols.
Margin concentration sits with hospitals; volume scaling depends on public health program expansion.
Administration Route:
Application requirements vary by immunogenicity targets, patient compliance factors, and cold chain infrastructure constraints.
- Intramuscular:Deltoid or anterolateral thigh injection remains the standard for aluminum-adjuvanted VLP formulations. Provincial CDCs prefer this route for school-based adolescent programs due to established nursing protocols.
- Subcutaneous:Alternative delivery for specific adjuvant formulations targets populations with muscle mass limitations.
- Intradermal:Dose-sparing potential drives evaluation in cost-sensitive public health applications.
- Oral:Experimental mucosal delivery platforms in preclinical development aim to eliminate cold chain dependencies for rural western province reach.
Clinical validation favors intramuscular delivery; innovation investment targets oral alternatives.
Distribution Channel:
Supply concentration determines access patterns across direct manufacturer relationships, intermediary networks, and digital platforms.
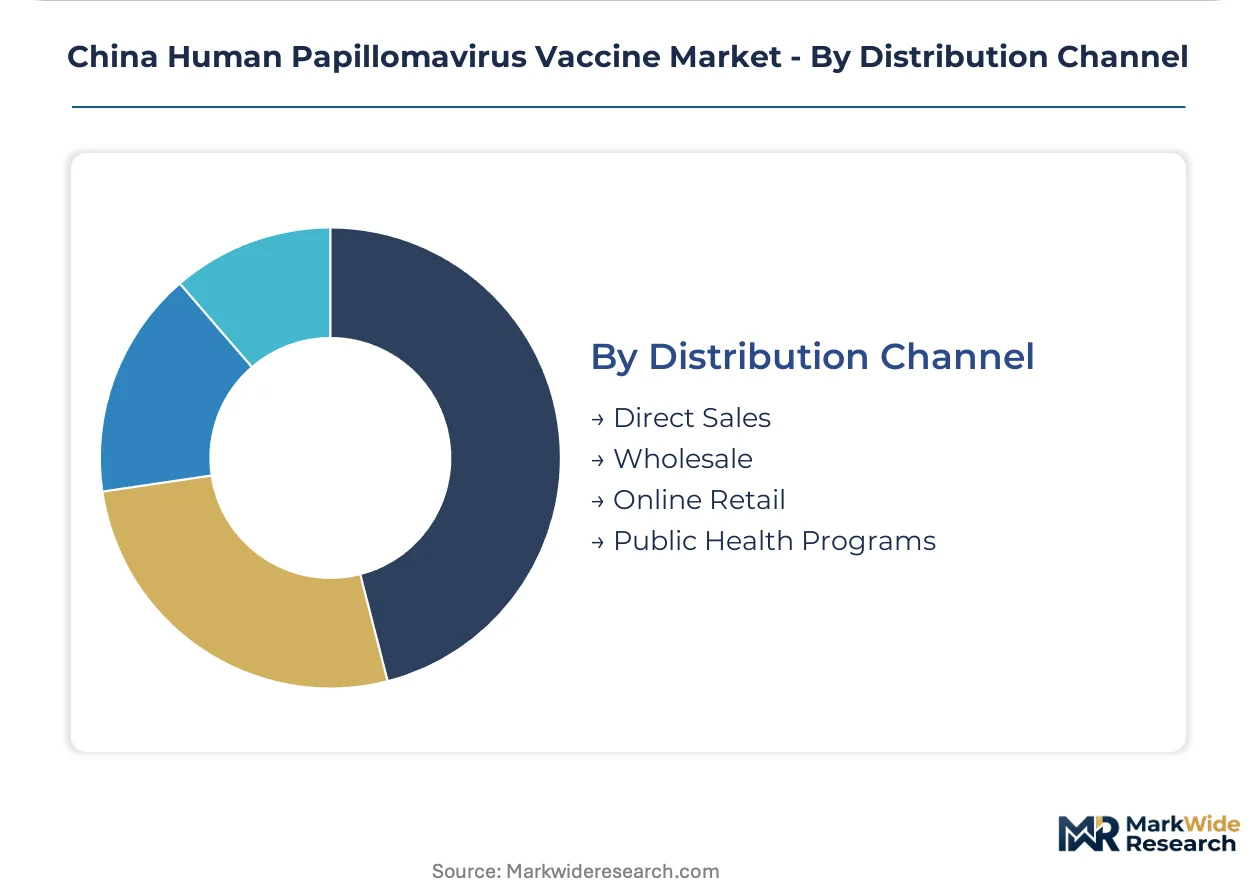
- Direct Sales:Manufacturer-to-CDC contracting dominates provincial immunization program supply. Xiamen Innovax and Walvax maintain dedicated government affairs teams to navigate municipal tender timelines.
- Public Health Programs:Centralized procurement through provincial health commissions aggregates demand across multiple municipalities. NMPA streamlined biologics pathway approvals accelerate supplier qualification for this channel.
- Wholesale:Regional distributors handle temperature-controlled logistics for hospital pharmacy replenishment in tier-two cities.
- Online Retail:Digital platforms facilitate appointment scheduling and dose tracking integration with electronic health records in Hangzhou and Shenzhen pilot programs.
Procurement authority is shifting toward public health program consolidation; direct sales relationships retain importance for manufacturer margin defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along China's eastern seaboard, with recombinant protein production concentrating in bioclusters possessing mature fermentation infrastructure and NMPA-registered quality systems. Provincial immunization program procurement authority has shifted volume allocation toward municipal CDC networks in tier-two and tier-three cities.
Beijing-Tianjin-Hebei
Municipal CDCs in Beijing administer majority shares of both public program and private-pay doses through integrated appointment systems. NMPA's streamlined biologics review pathway accelerates domestic product qualification for this high-volume channel. The region anchors regulatory compliance expertise, with lot release testing infrastructure concentrated in Beijing bioclusters.
Yangtze River Delta
Shanghai municipal health commissions consolidate HPV vaccine purchasing through centralized tender platforms, displacing individual hospital contracting autonomy. GB standard cold chain specifications exceed rural distribution capabilities in western portions of the region. Hangzhou and Shenzhen pilot digital vaccination credential systems integrating dose tracking with electronic health records.
Pearl River Delta
Guangdong province leads provincial immunization program expansion for adolescent catch-up campaigns. Cross-border regulatory harmonization pilots within the Greater Bay Area enable accelerated clinical data sharing and manufacturing site certification reciprocity. Xiamen Innovax leverages regional recombinant protein platforms to anchor supply for municipal programs.
Sichuan-Chongqing
Western province immunization programs face cold chain infrastructure gaps limiting GB standard temperature compliance in rural distribution networks. Domestic producers compete on cost-engineered bivalent formulations for provincial CDC tenders in this price-sensitive market. Chongqing bioclusters host emerging therapeutic vaccine development targeting E6/E7 oncoprotein expression.
Shandong Peninsula
Aluminum hydroxide adjuvant production concentrates in Shandong and adjacent Henan provinces, creating input vulnerability for VLP formulation capacity scaling. Provincial health commissions here aggregate demand across multiple municipalities through centralized procurement frameworks. Fermentation process engineering expertise concentrates in this region, constraining facility expansion timelines for interior provinces.
China Human Papillomavirus Vaccine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adjuvant supply and VLP potency assay services. The China HPV vaccine market exhibits tiered concentration: multinational nonavalent suppliers defend premium positioning in tier-one hospital pharmacies, while domestic recombinant manufacturers capture provincial CDC tender volumes through cost-engineered bivalent alternatives. Three archetypes dominate: import-dependent premium suppliers, domestic platform scale players, and emerging therapeutic specialists. Competitive moves center on NMPA approval timeline acceleration and municipal CDC direct contracting relationships.
Among domestic biologics developers, Xiamen Innovax Biotech and Walvax occupy positions within the cost-engineered formulation tier, representing yeast-expression platform maturation against import benchmarks. Merck exemplifies the import-dependent premium archetype through channel control over tier-one hospital pharmacies. These three anchors illustrate the market's structural divide between municipal public procurement and private-pay hospital administration.
| Leading Market Players |
|---|
| Xiamen Innovax Biotech |
| Sinovac |
| Merck |
| Walvax |
| CanSino Biologics |
| Wantai BioPharm |
| Sinopharm CNBG |
| BioKangtai |
| GlaxoSmithKline |
| Others |
Pricing and Supply Chain Analysis
Shandong Peninsula aluminum hydroxide production clusters anchor VLP formulation input costs, with adjuvant supply concentration translating directly into procurement leverage for domestic manufacturers competing on provincial CDC tenders. NMPA lot release testing requirements and GB standard cold chain specifications layer compliance premiums onto delivered dose economics, compressing margin pools for bivalent formulations while sustaining premium positioning for nonavalent alternatives in tier-one hospital channels.
Pricing Analysis
NMPA's streamlined biologics review pathway dictates the pricing tier structure across China's HPV vaccine market, accelerating domestic product qualification timelines that enable cost-engineered bivalent alternatives to undercut import benchmarks in municipal tender frameworks. Three-tier pricing structure across premium nonavalent, standard quadrivalent, and economy bivalent levels separates hospital pharmacy private-pay segments from public program procurement. Cost compression in the bivalent tier is intensifying because yeast-expression platform maturation achieves yield parity with imported benchmarks. Provincial CDC frameworks exhibit highest price sensitivity; tier-one hospital pharmacies demonstrate lowest sensitivity due to direct patient billing autonomy.
Supply Chain Analysis
Extended payment terms from provincial health commissions to domestic manufacturers strain working capital cycles, with supply-chain finance facilities emerging as critical liquidity bridges during tender fulfillment windows. Manufacturing capacity draws from Shandong, Jiangsu, and Fujian provinces, with fermentation infrastructure clustering in eastern seaboard bioclusters. Aluminum hydroxide adjuvant, recombinant L1 capsid proteins, and lipid nanoparticle formulations constitute critical input dependencies. Single-source vulnerability concentrates in Shandong aluminum hydroxide production, exposing VLP formulation scaling to regional disruption. Distribution runs through direct manufacturer-to-CDC contracting for public programs, with regional wholesalers handling hospital pharmacy replenishment in tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's HPV vaccine market fragments across municipal procurement frameworks and therapeutic development pipelines, with provincial immunization program expansion creating distinct volume and margin niches for differentiated platform strategies.
For Market Incumbents: Entrench municipal CDC direct contracting relationships through dedicated government affairs teams navigating tender timelines in Beijing and Shanghai, while accelerating NMPA approval pathways for next-generation formulations to preempt substitution pressure from emerging therapeutic candidates. Backward integration into aluminum hydroxide adjuvant production mitigates input vulnerability from Shandong supply concentration. Channel control over tier-one hospital pharmacies sustains premium nonavalent positioning against domestic cost-engineered alternatives. For New Entrants and Emerging Players: Pursue therapeutic vaccine white space targeting E6/E7 oncoprotein expression in screening-positive cohorts ineligible for prophylactic administration, with Chengdu and Suzhou bioclusters offering clinical-stage infrastructure for mRNA platform migration. Western province rural markets present the most penetrable geography given cold chain infrastructure gaps limiting incumbent reach. Digital vaccination credential integration with municipal health platforms in Hangzhou and Shenzhen offers a differentiated go-to-market angle for adherence monitoring and recall campaign partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned pharmaceutical parents seeking to monetize non-core biologics assets, with fermentation process engineering capabilities in Beijing and Shanghai bioclusters commanding scarcity premiums. Long-term viability hinges on platform diversification beyond prophylactic VLP formulations toward therapeutic immunotherapy constructs addressing persistent infections. NMPA approval timeline acceleration for domestic therapeutic candidates signals inflection potential for pipeline-stage investments.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Accelerated Approval Pathway | Compressed review timelines enable domestic manufacturers to capture provincial tender schedules before import incumbents adapt. |
| Municipal CDC Direct Contracting | Beijing and Shanghai integrated appointment systems concentrate volume allocation decisions within single procurement offices. |
| Recombinant Platform Scale-Up | Yeast and insect cell expression yield parity reduces per-dose production costs for bivalent formulations in western provinces. |
| Therapeutic Pipeline Diversification | E6/E7 oncoprotein-targeting mRNA constructs expand addressable populations beyond adolescent prophylactic cohorts. |
| Digital Health Integration | Hangzhou and Shenzhen electronic health record linkages enable precision recall campaigns and real-world effectiveness tracking. |
Research Methodology
A standing panel of regulatory affairs leads, municipal CDC procurement officers, hospital pharmacy directors, and bioprocess engineering specialists provided ongoing calibration against NMPA filing timelines and provincial tender schedule shifts. Primary interviews with yeast-expression platform operators and aluminum adjuvant suppliers combined with secondary validation through NMPA biologics approval databases, GB standard compliance filings, and provincial health commission procurement disclosures. Bottom-up dose demand modeling across municipal immunization programs triangulated against top-down market value reconstruction from manufacturer revenue disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning serotype coverage tier, procurement channel type, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical provincial immunization program expansion rates and NMPA approval velocity trends. Forecast inputs incorporated cold chain infrastructure development trajectories in western provinces and mRNA therapeutic candidate clinical advancement timelines.
Macroeconomic conditions sit as an overlay; deviation in provincial fiscal capacity for immunization program expansion or aluminum hydroxide commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding NMPA review pathway efficiency and municipal CDC network integration pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market