
 Anticoagulants Market | 2026-2036
Anticoagulants Market Size, Share, and Industry Trends Forecast 2026-2036
Anticoagulants Market Analysis
Hospital procurement of anticoagulant therapies is reorganizing around outpatient and homecare channels as direct oral anticoagulants displace older vitamin K antagonists. Pfizer Inc. leverages its cardiovascular franchise to sustain hospital formulary access across North American and European markets. Boehringer Ingelheim International GmbH anchors its position through deep specialization in thrombin inhibitor chemistry and physician education programs. Daiichi Sankyo Company, Limited competes aggressively in Asian markets with differentiated factor Xa inhibitor positioning.
Anticoagulants comprise pharmacological agents that interfere with blood coagulation cascades through inhibition of thrombin, factor Xa, or vitamin K-dependent clotting factors, typically administered via oral tablets, subcutaneous injections, or intravenous infusion to prevent thromboembolic events. Their primary commercial purpose centers on reducing stroke risk in atrial fibrillation patients, preventing deep vein thrombosis following surgical procedures, and managing pulmonary embolism in acute care settings. Direct oral anticoagulants command the dominant value share due to predictable pharmacokinetics that eliminate routine INR monitoring requirements. Heparins retain critical surgical and acute care applications where rapid reversibility proves essential. Homecare settings represent the fastest-expanding end user channel as self-administered oral therapies shift treatment away from institutional infusion centers.
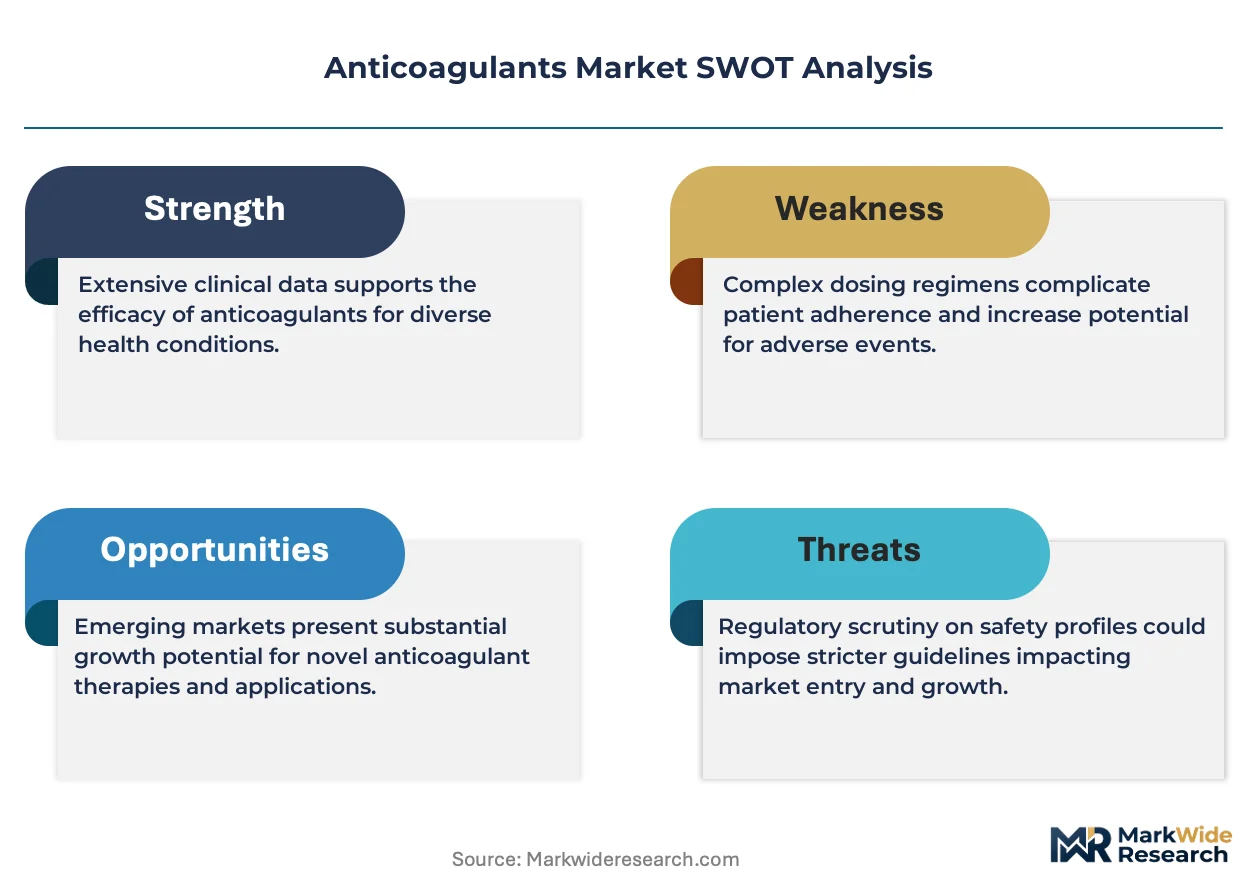
FDA bioequivalence standards and EMA Good Manufacturing Practice inspections govern active pharmaceutical ingredient sourcing, finished dosage form stability, and batch release protocols across manufacturing networks. The FDA's Risk Evaluation and Mitigation Strategy requirements for certain anticoagulant classes impose additional prescriber training and patient counseling obligations that filter market access. Stakeholders must monitor evolving pharmacovigilance signal detection from real-world evidence databases to anticipate label modifications or restricted indication withdrawals before competitor pipelines reshape therapeutic hierarchies.
Market Dynamics
The migration from vitamin K antagonists to direct oral anticoagulants is restructuring hospital procurement around outpatient dispensing and home-based therapy management, compressing traditional infusion-center revenue streams while expanding pharmacy benefit manager influence over formulary placement.
Growth Catalysts
- Aging Demographics in Japan:The country's super-aged population sustains prescription volumes for stroke prevention therapies, with cardiology infrastructure concentrated in Tokyo and Osaka metropolitan clusters driving per-capita utilization rates above OECD averages.
- FDA Risk Evaluation and Mitigation Strategy:Prescriber training mandates for certain anticoagulant classes create competitive moats around established therapies, filtering market access for new entrants and reinforcing incumbent formulary positions.
- Factor Xa Inhibitor Chemistry:Predictable pharmacokinetics eliminate routine INR monitoring requirements, reducing laboratory infrastructure burdens and enabling rural clinic prescribing that was previously restricted to tertiary centers.
Market Restraints
- Heparin Supply Concentration:Porcine intestinal mucosa sourcing depends on concentrated slaughterhouse operations in China, exposing manufacturers to zoonotic disease outbreaks and export restriction volatility.
- EMA Pharmacovigilance Burden:Post-market surveillance obligations for signal detection impose persistent regulatory compliance costs that disproportionately constrain mid-scale generic manufacturers.
- Vitamin K Reversal Agent Limitations:The absence of universal antidotes for direct oral anticoagulants restricts surgical adoption in trauma centers where rapid reversibility remains non-negotiable.
Strategic Opportunities
- Homecare Channel Expansion:Self-administered oral therapies are capturing patient volumes previously managed through institutional infusion centers, creating pharmacy logistics and remote monitoring service opportunities.
- India's Cardiology Infrastructure Buildout:Government hospital modernization programs in Maharashtra and Tamil Nadu are expanding access to anticoagulation clinics in tier-2 cities previously underserved by specialist care.
- Real-World Evidence Integration:Pharmacovigilance signal detection from electronic health record databases enables label expansion submissions and differentiated positioning against competitors reliant on traditional clinical trial data.
Industry Challenges
- Hematology Specialist Shortage:Thrombosis fellowship training programs in Germany and the United States are failing to match retirement rates, constraining patient throughput in anticoagulation clinics and extending appointment wait times.
- Batch Release Protocol Complexity:EMA Good Manufacturing Practice inspections of active pharmaceutical ingredient sourcing networks require multi-site coordination that delays product launches and strains quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticoagulants Market |
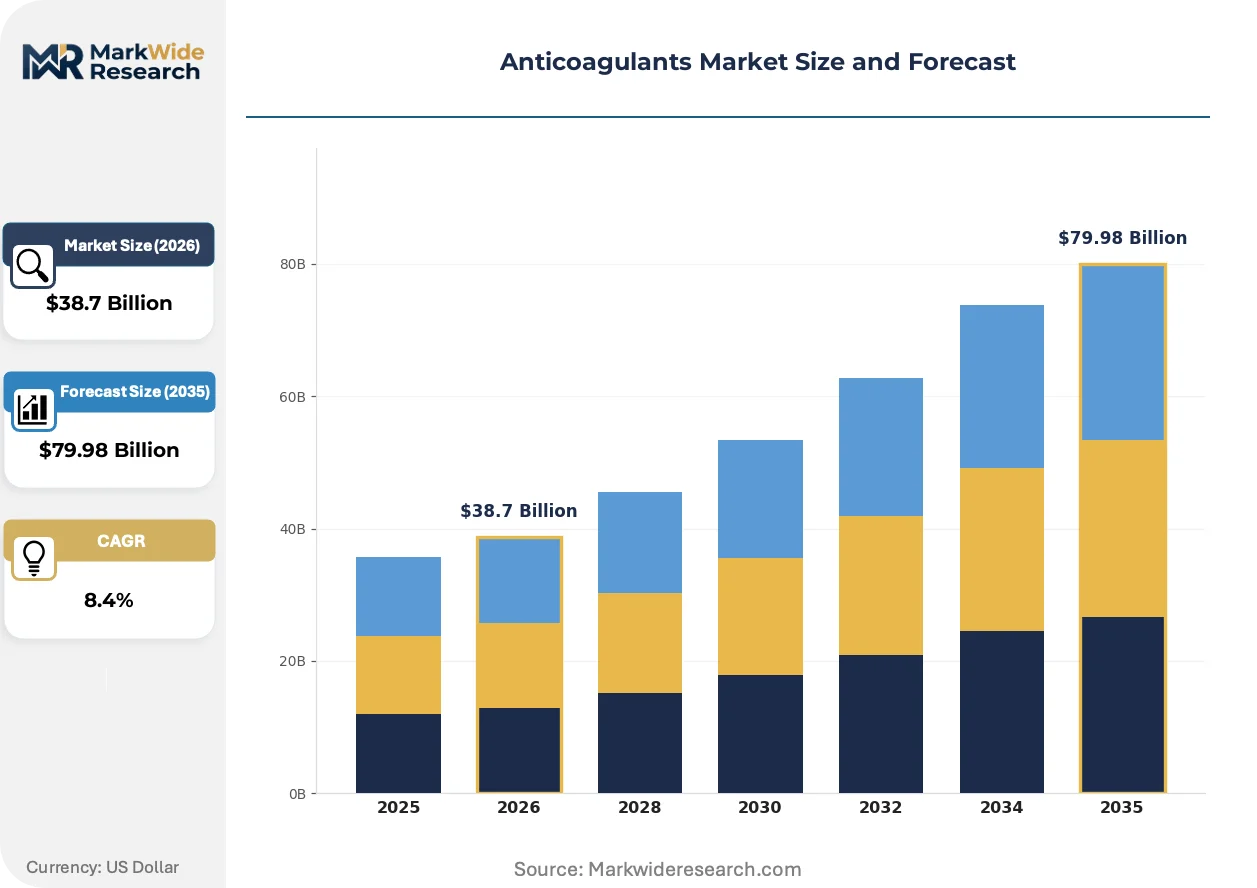
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Oral Anticoagulants, Vitamin K Antagonists, Heparins, Thrombin Inhibitors Application: Cardiovascular Disorders, Surgical Procedures, Atrial Fibrillation, Deep Vein Thrombosis End User: Hospitals, Clinics, Homecare Settings, Long-term Care Facilities Dosage Form: Tablets, Injections, Oral Solutions, Transdermal Patches |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., Bayer AG, Johnson & Johnson, Boehringer Ingelheim International GmbH, Daiichi Sankyo Company, Limited, Sanofi, GSK plc, Aspen Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticoagulants Market Emerging Trajectories
Formulation science and delivery mechanism advances are compressing the competitive advantage window for first-generation direct oral anticoagulants, while regulatory frameworks accelerate post-market surveillance integration into commercial strategy.
Reversal agent development programs are advancing rapidly, with andexanet alfa and ciraparantag representing distinct mechanistic approaches to factor Xa inhibitor neutralization. Emergency medicine departments in the United States are adopting these agents ahead of surgical services, driven by trauma protocol standardization. The technology is displacing frozen plasma and prothrombin complex concentrates as first-line reversal strategies, compressing blood bank revenue per anticoagulation-related admission.
EMA's strengthened pharmacovigilance requirements under the EU's Medical Device Regulation convergence mandate are forcing anticoagulant manufacturers to integrate real-world evidence platforms into post-market obligations. Industrial consequence includes mandatory patient registry participation and signal detection algorithm investments. Direct oral anticoagulant portfolios face heightened scrutiny in France and Germany, where national health technology assessment bodies are conditioning reimbursement on demonstrated real-world safety profiles.
Hospital procurement committees are consolidating anticoagulant purchasing through integrated delivery networks, unbundling historical physician preference item autonomy. Pharmacy and therapeutics committees in the United States are replacing individual drug contracts with class-wide agreements that include outcomes guarantees. This concentration is most visible in the Midwest and Southeast regions, where Catholic health system mergers have created multi-state formularies with limited therapeutic exceptions.
Anticoagulants Market Segmentation
Anticoagulant purchasing flows through distinct channel hierarchies that reshape profitability by segment. Hospital procurement committees, pharmacy benefit managers, and homecare distributors each favor different product configurations and dosage forms, fragmenting go-to-market requirements across the value chain.
Product Type:
Hospital formularies and retail pharmacy channels are splitting procurement authority between self-administered oral therapies and institutionally managed injectables, with reimbursement codes determining which segments flow through outpatient versus inpatient billing.
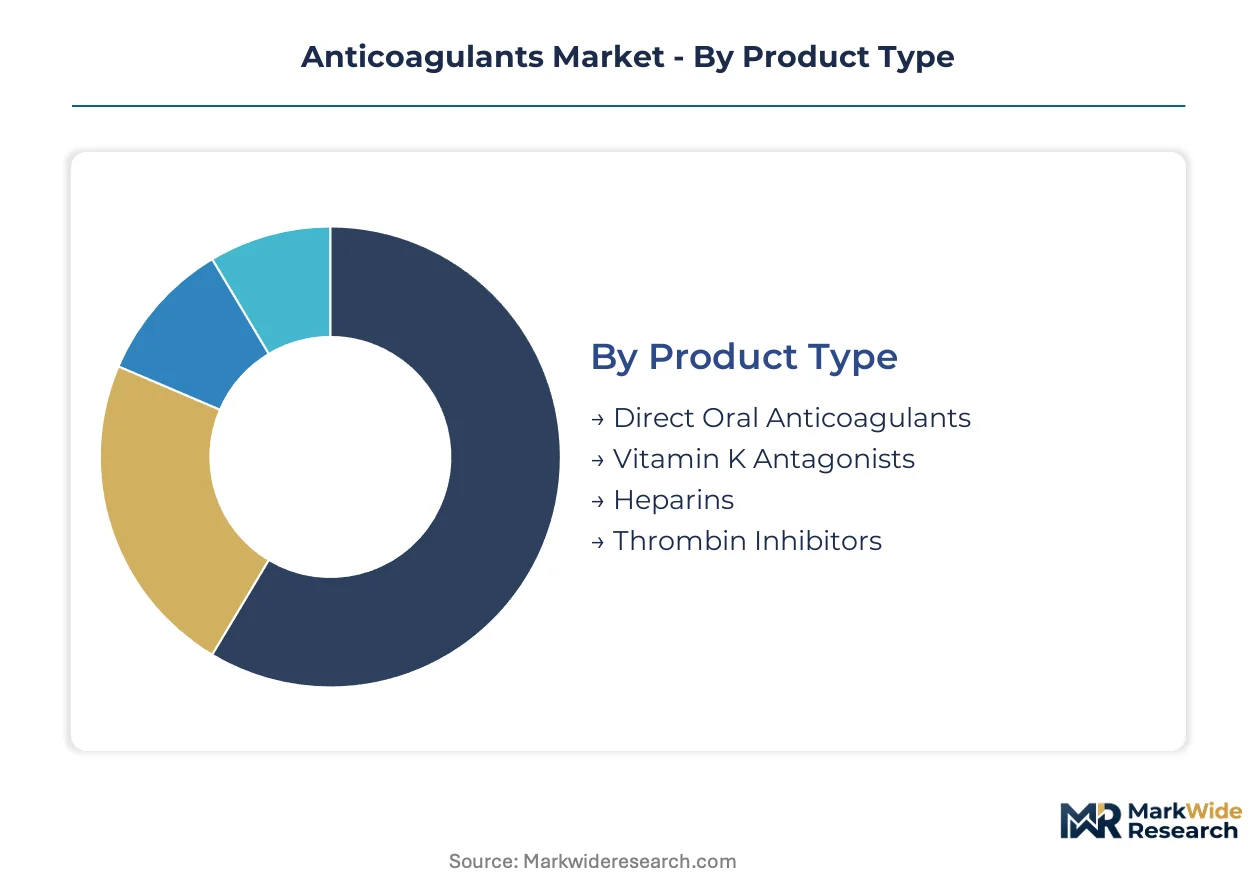
- Direct Oral Anticoagulants:Factor Xa and direct thrombin inhibitors with fixed dosing eliminate INR monitoring requirements. Demand concentrates in United States cardiology practices and German primary care networks where laboratory infrastructure constraints previously limited warfarin prescribing.
- Vitamin K Antagonists:Warfarin and coumarin derivatives require dietary restriction counseling and periodic coagulation testing. Cost-conscious health systems in India and Brazil retain these agents for price-sensitive patient populations despite monitoring burdens.
- Heparins:Unfractionated and low-molecular-weight formulations serve acute surgical and trauma applications where rapid reversibility with protamine sulfate remains essential.
- Thrombin Inhibitors:Parenteral direct thrombin inhibitors occupy narrow niches in heparin-induced thrombocytopenia protocols and cardiac surgery anticoagulation.
Direct Oral Anticoagulants dominate installed base. Heparins are where expansion concentrates in emerging market hospital buildouts.
Application:
Reimbursement intensity varies sharply by clinical indication, with stroke prevention commanding premium pricing relative to post-surgical prophylaxis.
- Cardiovascular Disorders:Broad category encompassing coronary artery disease and peripheral vascular indications where antiplatelet co-therapy complicates bleeding risk management.
- Surgical Procedures:Orthopedic and abdominal surgery protocols mandate mechanical and pharmacological prophylaxis against venous thromboembolism during hospitalization.
- Atrial Fibrillation:Chaotic atrial electrical activity creates stroke risk through left atrial appendage thrombus formation. Japanese geriatric cardiology clinics and United States Medicare Advantage plans drive volume concentration for oral factor Xa inhibitors in this indication.
- Deep Vein Thrombosis:Lower extremity clot formation requires acute anticoagulation followed by extended secondary prevention, with homecare transition creating pharmacy logistics opportunities.
Atrial Fibrillation generates the highest revenue per patient. Surgical Procedures represent the highest-volume, lowest-margin application tier.
End User:
Site-of-care migration is restructuring demand concentration, with institutional volumes flattening as home administration gains regulatory and patient acceptance.
- Hospitals:Tertiary centers and community hospitals manage acute pulmonary embolism and perioperative anticoagulation through pharmacy and therapeutics committee formularies.
- Clinics:Outpatient anticoagulation clinics in Germany and United States urban centers provide INR monitoring for remaining warfarin patients and transition protocols to direct oral agents.
- Homecare Settings:Self-administered subcutaneous injections and oral tablets shift treatment from infusion centers to residential environments. Medicare home health benefit expansions and Japanese long-term care insurance revisions accelerate this channel's expansion trajectory.
- Long-term Care Facilities:Nursing homes manage polypharmacy interactions and fall-risk bleeding complications in frail elderly populations.
Hospitals retain acute case concentration. Homecare Settings are gaining share fastest as oral therapies displace parenteral administration.
Dosage Form:
Manufacturing complexity and cold-chain requirements create divergent margin profiles across formulation types.
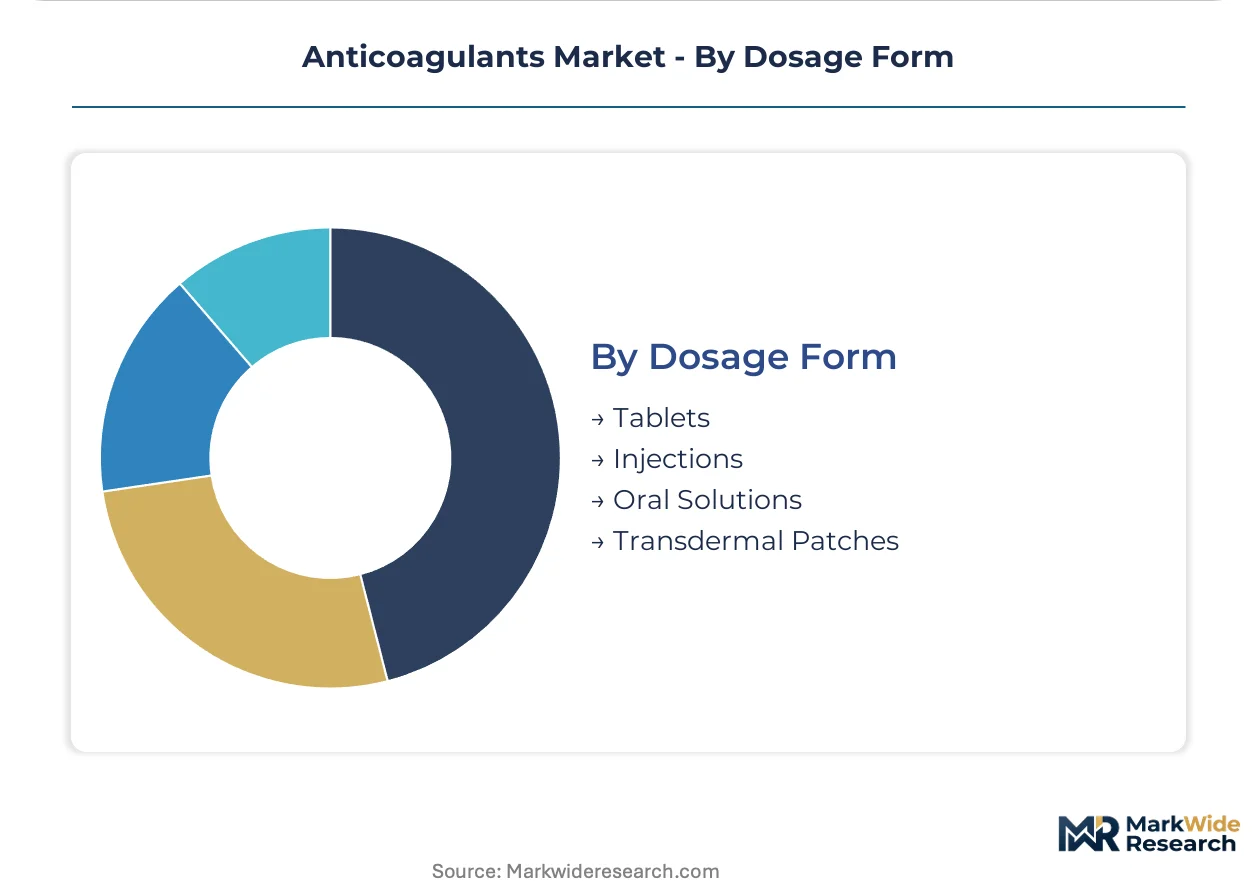
- Tablets:Film-coated immediate and modified-release formulations dominate outpatient prescribing. United States specialty pharmacies and German mail-order distributors handle fulfillment for chronic therapy maintenance.
- Injections:Prefilled syringes and vial presentations serve inpatient and home nursing administration where bioavailability timing is critical.
- Oral Solutions:Liquid formulations address pediatric populations and dysphagia patients unable to swallow solid dosage forms.
- Transdermal Patches:Experimental delivery systems in development seek to bypass hepatic metabolism and improve compliance in elderly populations with complex pill burdens.
Tablets command the value share. Injections retain procedural necessity in surgical and emergency protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution efficiency for temperature-sensitive anticoagulant formulations, while Japan's Kansai International Airport biopharma zone anchors Asia-Pacific logistics for high-value thrombin inhibitors.
United States
Medicare Advantage penetration in Florida and Arizona geriatric populations sustains prescription volumes for oral factor Xa inhibitors. FDA Risk Evaluation and Mitigation Strategy requirements filter market access for new entrants through prescriber certification mandates. The Mayo Clinic Rochester campus and Cleveland Clinic anchor anticoagulation clinic standardization protocols that diffuse to community hospital networks.
Germany
Aging demographics in Bavaria and Baden-Württemberg concentrate stroke prevention therapy demand in primary care networks with embedded cardiology services. EMA pharmacovigilance obligations under the EU Medical Device Regulation convergence mandate impose signal detection infrastructure costs on manufacturers. The Frankfurt-Rhine-Main metropolitan cluster hosts centralized laboratory networks that enable INR monitoring standardization for remaining warfarin patients.
Japan
Super-aged population dynamics in Tokyo and Osaka metropolitan areas drive per-capita utilization rates for atrial fibrillation therapies above OECD benchmarks. PMDA post-market surveillance requirements for direct oral anticoagulants mandate patient registry participation and real-world evidence submission. The Kanto region's long-term care insurance revisions accelerate homecare channel migration for self-administered oral therapies.
India
Government hospital modernization programs in Maharashtra and Tamil Nadu expand access to anticoagulation clinics in tier-2 cities previously underserved by specialist cardiology infrastructure. CDSCO bioequivalence standards for generic direct oral anticoagulants govern active pharmaceutical ingredient sourcing and finished dosage form stability protocols. The Mumbai-Pune pharmaceutical manufacturing corridor concentrates heparin production capacity serving domestic and export markets.
China
Porcine intestinal mucosa sourcing from concentrated slaughterhouse operations in Shandong and Henan provinces exposes heparin supply chains to zoonotic disease outbreak volatility. NMPA Good Manufacturing Practice inspections of active pharmaceutical ingredient networks require multi-site coordination that delays product launches. The Yangtze River Delta biopharma cluster anchors domestic factor Xa inhibitor development programs targeting stroke prevention indications.
Anticoagulants Market Vendor Landscape
Listed leaders compete with private specialists across cardiovascular franchise depth and thrombin inhibitor chemistry specialization. The vendor base consolidates around three tiers: diversified pharmaceutical conglomerates with hospital formulary leverage, mid-scale regional specialists with geographic density advantages, and emerging biosimilar manufacturers with cost-positioning focus. Dominant competitive moves include strategic partnerships for real-world evidence platform integration and backward integration into active pharmaceutical ingredient sourcing to secure porcine heparin supply chains.
Among diversified pharmaceutical conglomerates, Bristol-Myers Squibb Company and Pfizer Inc. exemplify the cardiovascular franchise archetype with established hospital formulary access across North American and European markets. Boehringer Ingelheim International GmbH occupies a specialist position within the direct thrombin inhibitor segment, representing deep chemistry specialization and physician education program investment. These three entities anchor the competitive structure through distinct positioning vectors: formulary breadth, therapeutic specialization, and regional market density respectively.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| Boehringer Ingelheim International GmbH |
| Daiichi Sankyo Company, Limited |
| Sanofi |
| GSK plc |
| Aspen Holdings |
| Others |
Supply Flow & Price Mechanics
FDA Risk Evaluation and Mitigation Strategy certification tiers gate both manufacturer qualification and hospital formulary pricing power simultaneously, separating approved suppliers from conditional entrants and compressing margins for non-compliant generic producers. EMA Good Manufacturing Practice inspections add parallel European qualification layers that sustain price premiums for dual-certified manufacturers while disqualifying single-market players from integrated delivery network contracts.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement through pharmacy and therapeutics committee negotiations, with integrated delivery networks extracting 15-30% concessions for class-wide formulary commitments. Price differentiation rests on bioequivalence certification grade and cold-chain logistics capability, with FDA-approved reference listed drug manufacturers commanding 40-60% premiums over tentative-approval generic entrants. Cost compression in the heparin segment is intensifying because porcine mucosa supply volatility forces spot-market API purchases. Cost-conscious health systems in India and Brazil exhibit highest price sensitivity, while Japanese long-term care insurers demonstrate lowest sensitivity due to bundled reimbursement rates.
Supply Chain Analysis
Inventory lead times for heparin APIs stretch 90-180 days due to porcine intestinal mucosa sourcing cycles, forcing manufacturers to carry 4-6 months of strategic buffer stock. Active pharmaceutical ingredient production concentrates in China, India, and Italy, with Shandong and Henan provinces supplying 60-70% of global heparin crude material. Raw material dependencies center on porcine mucosa, synthetic thrombin inhibitor precursors, and factor Xa inhibitor intermediates. Single-source vulnerability from concentrated Chinese slaughterhouse operations exposes manufacturers to African swine fever outbreak disruption. Distribution runs through pharmaceutical wholesalers to hospital central pharmacies, with specialty pharmacy direct-to-patient channels gaining share for oral anticoagulant maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network mergers in the United States Midwest and Southeast, with Catholic health system consolidations creating multi-state formularies that unbundle historical physician preference autonomy. This consolidation shifts negotiating leverage from manufacturers toward procurement committees demanding outcomes guarantees.
For Market Incumbents: Shield formulary positions through backward integration into porcine heparin supply chains and captive production of factor Xa inhibitor intermediates. Invest in real-world evidence platform infrastructure to satisfy EMA pharmacovigilance signal detection mandates before mid-scale generic competitors achieve compliance. Prioritize certification maintenance for FDA Risk Evaluation and Mitigation Strategy prescriber training programs to sustain competitive moats against emerging biosimilar entrants. For New Entrants and Emerging Players: Anchor in India's tier-2 city hospital modernization programs in Maharashtra and Tamil Nadu, where government infrastructure buildout creates first-mover access to previously underserved anticoagulation clinics. Target the homecare channel transition for self-administered oral therapies, where pharmacy logistics partnerships and remote monitoring service bundling offer differentiation against incumbent hospital-centric portfolios. Pursue CDSCO bioequivalence certification for generic direct oral anticoagulants to unlock price-sensitive public procurement contracts. For Investors and Strategic Acquirers: FDA reversal agent approval pathways reshape the acquisition landscape by elevating manufacturers with andexanet alfa or ciraparantag development programs above commodity anticoagulant producers. Position portfolios for 5-10 year viability around companies integrating real-world evidence capabilities with active pharmaceutical ingredient supply security. Monitor heparin API spot price volatility as an inflection indicator for margin compression across the generic injectables segment.| Strategic Initiative | Industry Significance |
|---|---|
| Reversal Agent Development Program | Andexanet alfa and ciraparantag pipelines differentiate emergency medicine positioning against frozen plasma alternatives. |
| Real-World Evidence Platform Integration | EMA pharmacovigilance convergence mandates require signal detection infrastructure for French and German reimbursement access. |
| Backward Integration into API Sourcing | Porcine heparin supply chain captivity insulates against Shandong province zoonotic disease export restrictions. |
| Homecare Channel Logistics Partnership | Medicare home health benefit expansions and Japanese long-term care insurance revisions accelerate residential administration shift. |
| CDSCO Bioequivalence Certification | Indian government hospital modernization programs in tier-2 cities unlock price-sensitive public procurement volume. |
Methodological Framework
A spread of perspectives from formulary directors at integrated delivery networks, regulatory affairs leads at factor Xa inhibitor manufacturers, hospital procurement managers, and payer access specialists converged on the working assumptions underlying demand projections. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EMA periodic safety update reports, ClinicalTrials.gov protocol registries, and hospital pharmacy procurement databases. Bottom-up patient volume modeling by indication and dosage form triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Segmentation dimensions modeled span product type, application indication, end-user channel, and dosage form across the projection horizon, with additional granularity on regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to base-year installed patient populations, adjusted for therapy switching rates from vitamin K antagonists to direct oral anticoagulants. Forecast inputs incorporated PMDA patient registry participation mandates, Medicare Advantage penetration trajectories in Florida and Arizona geriatric populations, and heparin API supply concentration metrics.
Decision-makers should treat outputs as directional under assumptions of continued integrated delivery network consolidation and stable porcine mucosa supply from Shandong and Henan provinces; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Sporanox Market