
 South Korea Electric Hobs Market | 2026-2036
South Korea Electric Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Electric Hobs Market Insights
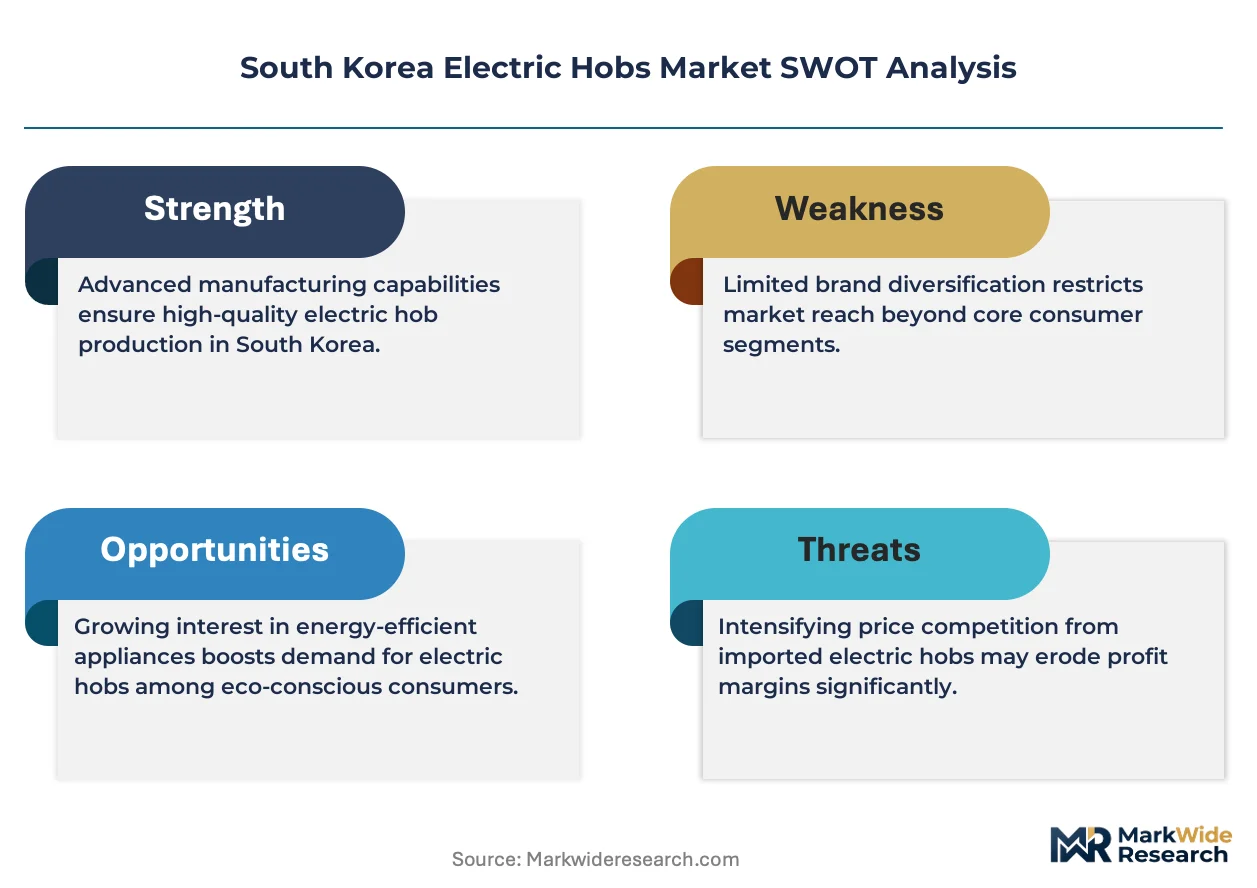
Domestic appliance manufacturing capacity in Gyeonggi Province is decoupling from traditional export-oriented output models. Samsung Electronics leverages in-house semiconductor fabrication to control induction inverter supply chains. LG Electronics anchors its position through captive production of ceramic glass cooktops. Bosch competes on German engineering credentials distributed through specialist kitchen retail channels in Seoul.
South Korea electric hobs are flat-surface cooking appliances employing electromagnetic induction, resistive heating elements, or halogen lamps to transfer thermal energy to cookware, typically operating at power ratings between 1.4 kW and 3.7 kW per cooking zone for residential and commercial food preparation. Induction hobs lead the product type category on energy efficiency metrics and penetration into new-build residential complexes, while ceramic hobs retain volume share in replacement cycles across existing housing stock. Smart technology features including Wi-Fi connectivity and voice assistant integration represent the fastest-growing feature segment as Korean consumers prioritize connected kitchen ecosystems.
MFDS electrical appliance safety certification and MEPS minimum energy performance standards govern product entry and efficiency labeling requirements for electric hobs distributed in South Korea. KC marking obligations administered by KTL and KTC testing institutes add compliance layers for electromagnetic compatibility and fire safety verification. Stakeholders must monitor evolving efficiency tier thresholds and smart appliance cybersecurity guidelines as regulatory scope expands beyond physical safety into data governance domains.
Market Dynamics
Induction inverter miniaturization is compressing form factors while MFDS safety recertification cycles are lengthening product development timelines across Gyeonggi Province manufacturing clusters.
Growth Catalysts
- MFDS Tier 1 Efficiency Labeling:Premium apartment developers in Seoul now mandate induction hobs bearing the highest MEPS ratings to qualify for green building certifications, accelerating replacement of resistive ceramic units in new-build residential towers.
- Smart Home Ecosystem Convergence:Voice assistant integration and Wi-Fi module standardization are pulling demand from tech-forward millennial households toward connected kitchen appliances that synchronize with Samsung SmartThings and LG ThinQ platforms.
- Busan Residential Renovation Pipeline:Kitchen remodeling permits in South Korea's second-largest metropolitan area have surged as aging housing stock enters replacement cycles, creating concentrated demand zones for mid-range ceramic-to-induction upgrades.
Market Restraints
- IGBT Semiconductor Supply Concentration:Induction inverter core components rely on concentrated sourcing from East Asian foundries, exposing domestic assemblers to input cost volatility when power semiconductor lead times extend beyond 26 weeks.
- Copper Coil Raw Material Exposure:Electromagnetic induction hobs require substantial copper winding for heating coils, and price fluctuations in London Metal Exchange copper futures directly compress manufacturing margins across the supply base.
- Gas Infrastructure Legacy:Existing LPG and natural gas pipeline networks in older Seoul districts create substitution friction, as conversion costs for electrical panel upgrades deter rapid switching among price-sensitive replacement buyers.
Strategic Opportunities
- Jeju Island Electrification Mandates:South Korea's southernmost province maintains aggressive carbon neutrality targets that explicitly favor all-electric residential appliances, creating a policy-protected demand enclave with above-average premium product absorption rates.
- Modular Commercial Kitchen Systems:Food service operators in Gangnam and Hongdae dining districts are adopting drop-in induction modules for ghost kitchen configurations, opening a B2B channel with shorter sales cycles than residential new-build projects.
- Cybersecurity Certification Pre-Positioning:MFDS draft guidelines for smart appliance data governance create first-mover advantage for manufacturers that architect firmware security architectures ahead of mandatory compliance deadlines.
Industry Challenges
- KC Electromagnetic Compatibility Testing Bottlenecks:KTL and KTC laboratory capacity constraints extend product launch timelines by 8-14 weeks, compressing revenue recognition windows for seasonal product introductions.
- Legacy Housing Electrical Infrastructure:Pre-2000 apartment buildings across Incheon and Daegu lack 220V dedicated circuits, requiring costly electrical contractor coordination that fragments the addressable market for high-power induction units.
- Induction Cookware Compatibility Verification:Consumer confusion regarding ferromagnetic base requirements generates elevated return rates and customer service costs, demanding educational investments that dilute marketing efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Electric Hobs Market |
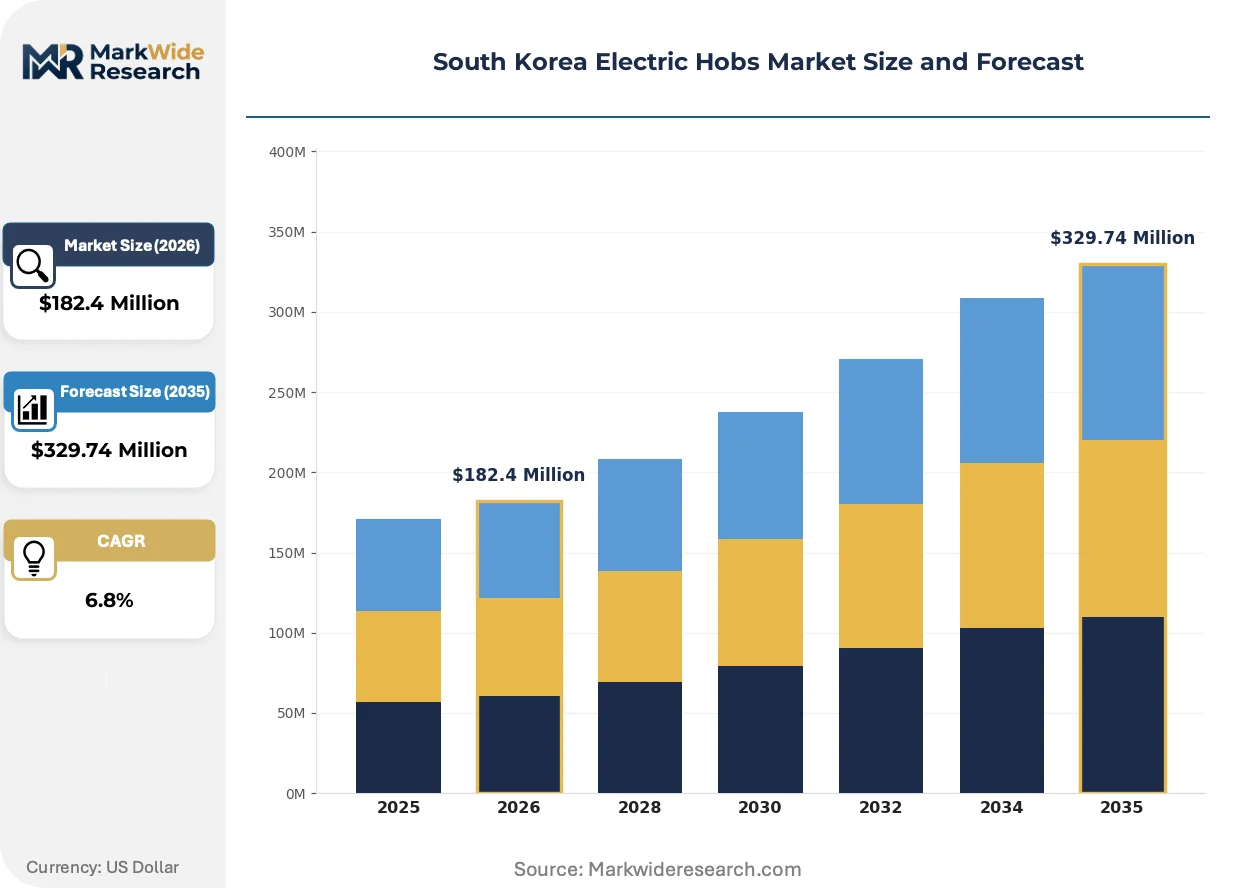
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $329.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Hobs, Ceramic Hobs, Electric Coil Hobs, Halogen Hobs End User: Residential, Commercial, Hospitality, Catering Installation Type: Built-in, Freestanding, Portable, Wall-mounted Feature: Smart Technology, Touch Controls, Child Safety Lock, Timer Function |
| Companies Covered | Miele & Cie. KG, Electrolux AB, Samsung Electronics, Panasonic Corporation, Whirlpool Corporation, LG Electronics, Siemens AG, Haier Group Corporation, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Electric Hobs Market Trends and Innovations
Silicon carbide power semiconductors are penetrating induction inverter designs while regulatory pressure on standby power consumption intensifies technical differentiation requirements across the supply base.
GaN-on-silicon transistors are integrating into next-generation induction inverters to reduce switching losses and enable higher-frequency operation at equivalent thermal output. Premium appliance manufacturers in Gyeonggi Province are adopting these wide-bandgap semiconductors for flagship product lines targeting Seoul luxury apartment developments. The technology is integrating previously discrete power management functions into single-chip solutions that compress PCB footprint by approximately forty percent.
MEPS standby power regulations administered by the Korean Agency for Technology and Standards are tightening maximum allowable wattage during idle states to below one watt for all electric hob categories. Manufacturers must redesign power supply architectures and implement more aggressive sleep-state logic to maintain compliance eligibility. Induction products with always-on Wi-Fi connectivity face disproportionate engineering burden as connectivity modules must now operate within severely constrained power budgets.
Specialist kitchen retail channels in Seoul are consolidating purchasing authority as department store home appliance floors reduce square footage allocated to cooking equipment. Independent kitchen design studios in Apgujeong and Cheongdam are capturing affluent replacement demand through consultative selling models that bundle hobs with cabinetry and ventilation systems. Daegu and Gwangju secondary cities lag this channel evolution by approximately three years, maintaining traditional electronics retail dominance.
South Korea Electric Hobs Market Segmentation
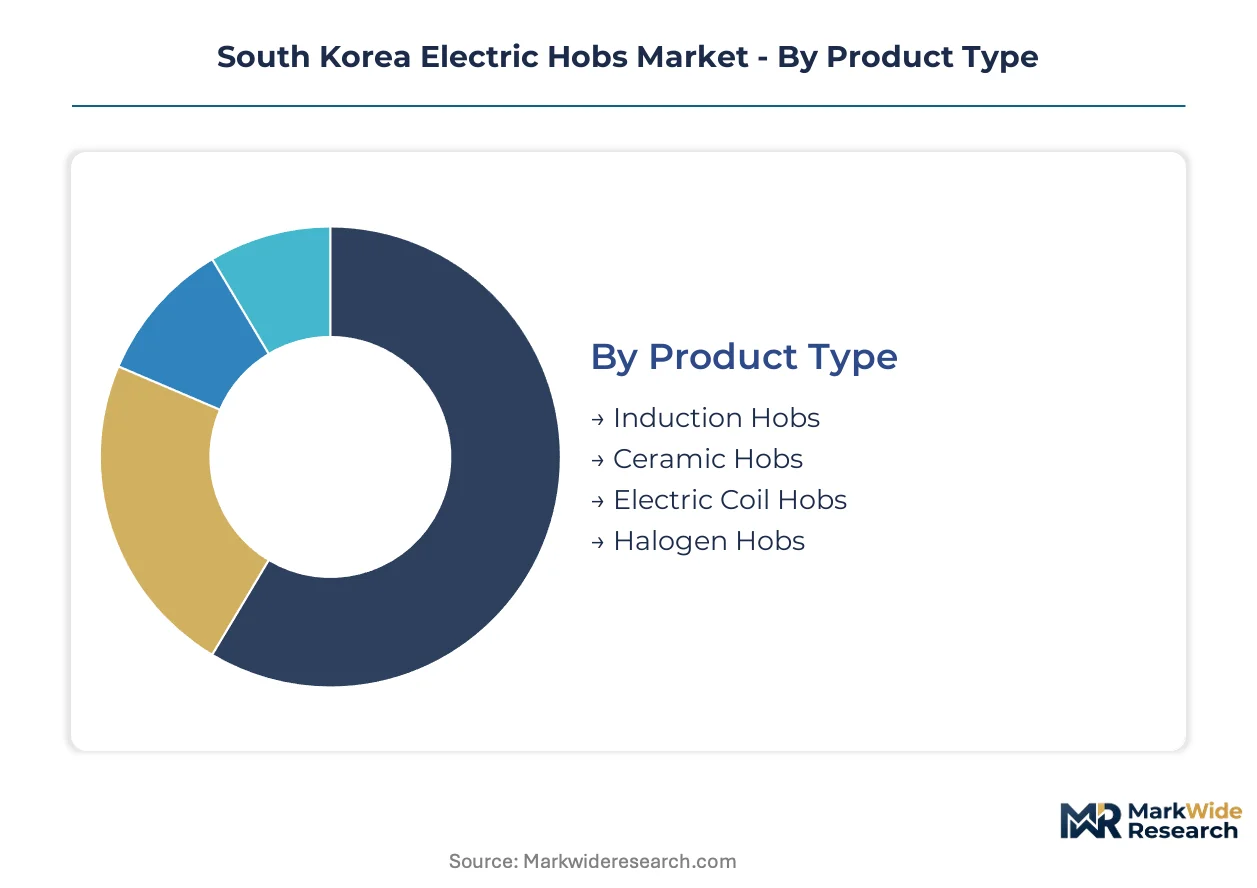
Segmentation in the South Korea electric hobs market reveals how technology specifications, installation constraints, and end-use requirements fragment demand across distinct purchasing contexts. Manufacturers must align product architectures with MFDS certification pathways that vary by heating technology and power rating.
Product Type:
Heating technology defines the core engineering architecture and efficiency profile of electric hobs distributed in South Korea.
- Induction Hobs:Electromagnetic field generation through copper coil windings heats ferromagnetic cookware directly without thermal lag. Seoul luxury apartment developers specify these units for green building certifications, though IGBT semiconductor supply volatility constrains production scaling.
- Ceramic Hobs:Resistive heating elements embedded beneath tempered glass surfaces provide gradual thermal response at lower unit cost. Replacement demand concentrates in Busan and Incheon aging housing stock where electrical infrastructure upgrades remain uneconomical.
- Electric Coil Hobs:Exposed spiral heating elements deliver durable performance in price-sensitive segments.
- Halogen Hobs:Tungsten-halogen lamps generate radiant heat with near-instant response times.
Mature deployment sits with ceramic hobs in existing housing stock. Newer deployment is concentrated in induction systems for premium residential developments.
End User:
Volume concentration and purchasing authority diverge sharply between residential replacement cycles and commercial specification processes.
- Residential:Individual households drive replacement demand through kitchen renovation projects, with purchasing decisions influenced by smart home ecosystem compatibility and MEPS efficiency labeling visibility.
- Commercial:Ghost kitchen operators in Gangnam and Hongdae specify drop-in induction modules for rapid equipment refresh cycles, prioritizing thermal precision and ventilation integration over upfront cost.
- Hospitality:Hotel kitchen procurement follows extended capital expenditure timelines with durability specifications.
- Catering:Event service providers favor portable configurations for operational flexibility.
Volume leadership belongs to residential replacement. Commercial hospitality procurement is climbing fastest as food service automation accelerates.
Installation Type:
Physical integration requirements determine electrical infrastructure compatibility and channel distribution strategy.
- Built-in:Flush countertop integration demands dedicated 220V circuitry and coordinated cabinet installation, limiting addressability to new-build apartments and comprehensive renovations in Gyeonggi Province developments.
- Freestanding:Self-contained units with integrated stands serve rental markets and temporary kitchen configurations where permanent modification is prohibited.
- Portable:Single-zone induction plates with standard plug connections address dormitory and office pantry use cases.
- Wall-mounted:Vertical installation preserves counter space in compact Seoul apartments.
Built-in systems dominate value capture. Portable configurations are expanding most quickly among single-person households.
Feature:
Functional differentiation increasingly centers on connectivity architecture and safety certification depth.
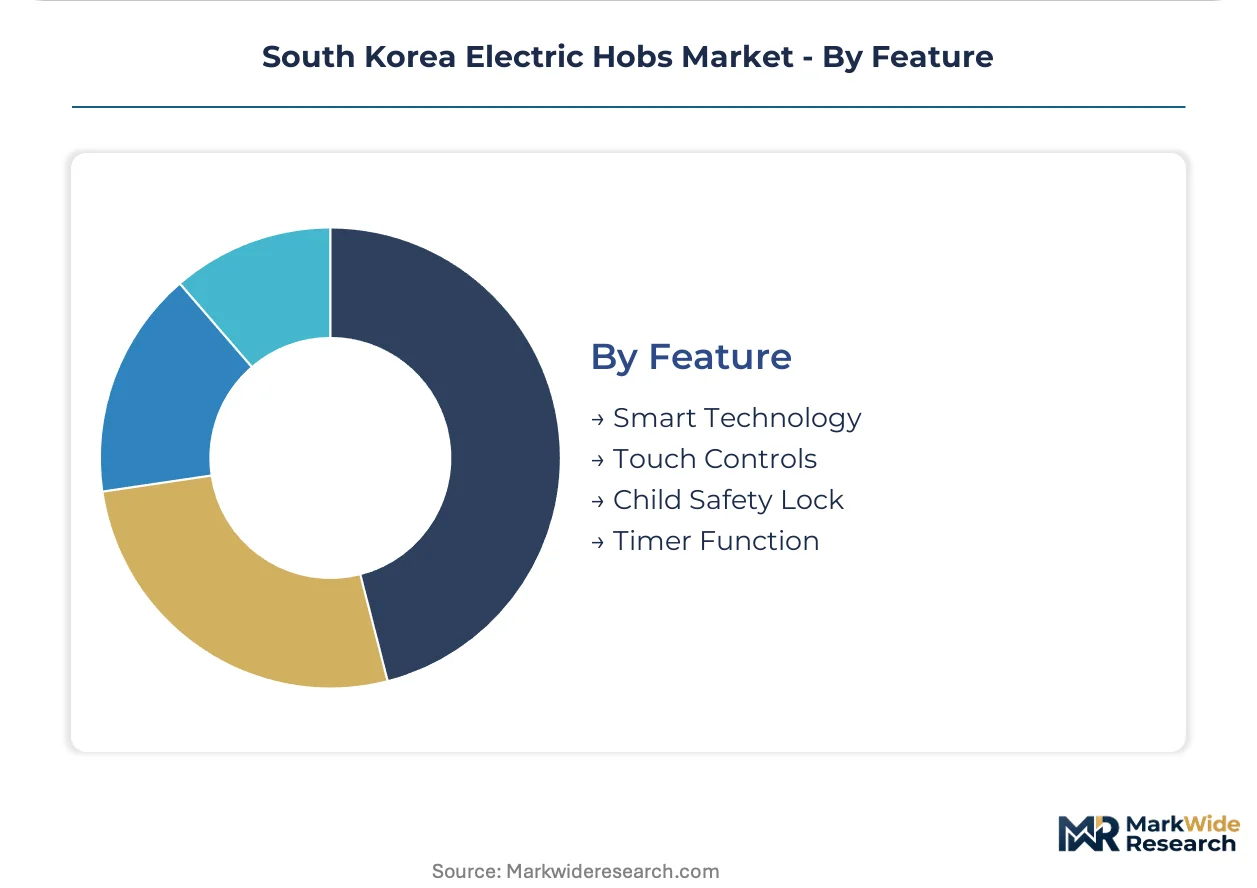
- Smart Technology:Wi-Fi module integration and voice assistant compatibility enable synchronization with Samsung SmartThings and LG ThinQ platforms, though MFDS cybersecurity draft guidelines threaten compliance redesign requirements for always-connected units.
- Touch Controls:Capacitive glass interfaces replace mechanical switches for aesthetic integration and cleaning convenience.
- Child Safety Lock:Activation sequence requirements prevent unintended operation in family households.
- Timer Function:Programmable shutoff reduces energy waste and overcooking risk.
Timer and safety lock features represent baseline expectations. Smart connectivity is gaining share fastest as millennial household formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper coil winding facilities in Busan anchor the southern manufacturing corridor for induction hob components. Seoul's premium residential tower construction drives specification-grade demand for built-in electric cooking systems. Gyeonggi Province assembly plants source tempered glass cooktops from domestic float-glass foundries.
Seoul Capital Area
Luxury apartment developers in Gangnam and Songpa districts specify MEPS Tier 1 induction hobs for green building certifications. MFDS electrical safety recertification cycles compress product launch windows for manufacturers targeting new-build residential towers. Samsung Electronics and LG Electronics maintain headquarters-driven procurement influence over specification channels in Apgujeong kitchen design studios.
Busan-Ulsan
Kitchen remodeling permits in Busan's aging housing stock concentrate demand for ceramic-to-induction upgrade cycles. The region's shipbuilding heritage supports precision copper winding capabilities for induction coil manufacturing. Ulsan industrial parks host secondary glass tempering operations supplying cooktop substrates to Gyeonggi assembly lines.
Daegu-Gyeongbuk
Pre-2000 apartment electrical infrastructure limitations fragment addressability for high-power induction units in Incheon-connected districts. Local electrical contractors coordinate panel upgrades for ceramic hob replacement projects. Daegu maintains traditional electronics retail dominance, lagging Seoul's kitchen design studio channel evolution by approximately three years.
Daejeon-Sejong
KTL and KTC testing institute proximity accelerates KC electromagnetic compatibility certification for manufacturers locating validation operations in the central administrative cluster. Government procurement guidelines for public housing projects reference MEPS efficiency thresholds. Sejong smart city pilot programs test connected kitchen appliance integration with municipal energy management systems.
Gwangju-Honam
Jeju Island electrification mandates create policy-protected demand spillover through Honam regional distribution networks. The province's carbon neutrality targets explicitly favor all-electric residential appliances. Gwangju secondary city retail maintains traditional appliance store formats, preserving volume channels for mid-range ceramic hob replacement cycles.
South Korea Electric Hobs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart connectivity integration and modular commercial configurations. The market structure consolidates around three strategic archetypes: domestic conglomerates with captive component supply, German engineering specialists distributing through premium retail channels, and diversified Asian electronics houses competing on scale. Dominant competitive moves include backward integration into semiconductor fabrication for inverter control and strategic partnerships with kitchen design studios for specification capture.
Within the domestic conglomerate tier, Samsung Electronics and LG Electronics exemplify vertical control strategies through in-house production of critical subsystems. Samsung leverages semiconductor fabrication capabilities for induction inverter supply chain management, while LG anchors positioning through captive ceramic glass cooktop manufacturing. Among German engineering specialists, Miele & Cie. KG and Bosch occupy premium-tier positions distributed through consultative retail channels in Seoul's affluent districts. These company structures represent alternative pathways to market access: domestic scale-driven fabrication versus import-brand engineering credentialing.
| Leading Market Players |
|---|
| Miele & Cie. KG |
| Electrolux AB |
| Samsung Electronics |
| Panasonic Corporation |
| Whirlpool Corporation |
| LG Electronics |
| Siemens AG |
| Haier Group Corporation |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Captive production of ceramic glass cooktops and induction inverters anchors pricing power for domestic conglomerates while compressing margin structures for import-dependent assemblers. Samsung Electronics and LG Electronics leverage in-house semiconductor fabrication and glass tempering operations to buffer against raw material volatility, whereas Bosch and Miele absorb logistics and tariff exposure through premium positioning in Seoul kitchen design studios.
Pricing Analysis
Warranty and installation service bundling separates premium-tier induction systems from unbundled mid-range ceramic replacements in Seoul and Busan. Three-tier pricing structure across premium, standard, and economy levels reflects MEPS certification grade and smart connectivity integration. Cost compression in ceramic hob segments is intensifying because copper coil and IGBT semiconductor input volatility pressures manufacturing margins. Price-sensitive replacement buyers in Daegu and Gwangju prioritize unbundled ceramic units, while Seoul luxury apartment developers show minimal sensitivity to bundled premium induction packages.
Supply Chain Analysis
MFDS electrical safety certification and KC electromagnetic compatibility marking gate entry for all induction inverter and ceramic cooktop suppliers targeting South Korea distribution. Component sourcing draws from South Korea for semiconductor fabrication, China for glass substrate raw materials, and Germany for precision engineering subsystems. Copper winding and tempered glass dependencies expose assemblers to London Metal Exchange price swings and energy-intensive manufacturing bottlenecks. Single-source vulnerability concentrates in IGBT power semiconductor foundries with lead time extensions beyond standard procurement cycles. Distribution runs through Gyeonggi Province assembly clusters to Seoul kitchen design studios and Busan electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS Tier 1 efficiency labeling and impending smart appliance cybersecurity guidelines erect compliance barriers that favor capitalized incumbents over under-resourced entrants. The cost-of-compliance dynamic rewards players with existing KTL and KTC testing relationships and in-house certification expertise.
For Market Incumbents: Acquire copper coil winding and glass tempering facilities to deepen upstream control over critical component supply. Samsung Electronics and LG Electronics should expand captive semiconductor fabrication capacity for induction inverters before IGBT supply constraints worsen. Defensive consolidation through exclusive partnerships with Apgujeong kitchen design studios blocks specification access for German engineering specialists.
For New Entrants and Emerging Players: GaN-on-silicon transistor integration offers a technology-first wedge for premium induction systems targeting Seoul luxury apartment developments. White-space concentration sits with modular commercial drop-in configurations for Gangnam ghost kitchen operators. Secondary city ceramic-to-induction upgrade cycles in Busan present the most penetrable replacement demand. Go-to-market execution through electrical contractor referral networks bypasses entrenched retail channel control.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by domestic conglomerates seeking smart connectivity firmware capabilities and cybersecurity certification readiness. Long-term viability favors manufacturers with pre-positioned compliance architectures for MFDS data governance mandates. Acquisition target archetype: mid-scale assemblers with established KTL testing relationships and Jeju Island distribution access. The signal to watch is draft cybersecurity guideline finalization timing as inflection indicator for regulatory compliance investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Samsung Electronics controls induction inverter supply chains through in-house foundry operations. |
| Cybersecurity Certification Pre-Positioning | Early firmware architecture investment captures first-mover advantage ahead of MFDS mandatory compliance deadlines. |
| Modular Commercial Kitchen System Development | Drop-in induction modules address Gangnam ghost kitchen demand with shorter sales cycles than residential projects. |
| Exclusive Kitchen Design Studio Partnerships | Apgujeong and Cheongdam consultative channels capture affluent replacement demand through bundled specification selling. |
| Jeju Island Distribution Network Expansion | Carbon neutrality mandates create policy-protected demand enclave with above-average premium product absorption rates. |
Research Methodology
Independent corroboration across appliance manufacturing executives, electrical safety certification specialists, and kitchen design studio proprietors underwrites the qualitative findings. Primary fieldwork engaged Gyeonggi Province plant managers, Seoul retail channel heads, and Busan renovation contractors alongside secondary validation through MFDS regulatory filings, MEPS efficiency registry data, and KTL electromagnetic compatibility test records. Bottom-up demand modeling from housing permit flows and renovation cycle timing triangulates against top-down value estimates from manufacturer shipment disclosures and import customs records.
Comparable-period anchoring to historical residential construction peaks and kitchen replacement cycle patterns structures the projection methodology. Segmentation dimensions span heating technology, installation type, end-use application, and smart feature integration across the modeling period. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and efficiency tier mix shifts. Industry-specific forecast inputs include copper futures price assumptions and semiconductor foundry capacity utilization trends.
Several conditions sit outside the modeled scope, including abrupt MFDS regulatory timeline acceleration, IGBT supply chain disruption severity, and gas-to-electric conversion subsidy program introduction. Forecasts reflect documented assumptions regarding housing stock age distribution and electrical infrastructure upgrade economics. A model refresh is warranted upon material change in MEPS efficiency tier threshold revisions or smart appliance cybersecurity guideline finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
US Range Cooker Market