
 Small Kitchen Appliances Market | 2026-2036
Small Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Small Kitchen Appliances Market Intelligence
The traditional replacement cycle driven by household necessity is unwinding as aspirational 'prosumer' and small commercial buyers seek performance-oriented appliances. Bosch Siemens Hausgeräte leverages its engineering reputation to target this premium segment. SharkNinja competes on multi-functionality and aggressive marketing through online channels. Philips Domestic Appliances focuses on health-centric innovations like air fryers to capture a specific consumer wellness trend.
Small kitchen appliances are portable, electrically-powered devices designed for countertop food preparation, typically operating under 2000 watts. They automate or accelerate tasks like blending, heating, and chopping for residential and light commercial users. Within product types, multi-functional devices like combination blender-food processors are seeing strong interest. Smart appliances featuring connectivity and app-based controls command higher price points compared to traditional models.
Product design and market access are shaped by a web of international standards. The EU’s RoHS directive restricts hazardous substances, while CE marking is mandatory for European market entry. In the United States, the EPA's ENERGY STAR program incentivizes the production of energy-efficient models. Manufacturers must now decide how deeply to invest in IoT connectivity versus prioritizing affordability and reliability for mass-market appeal.
Market Dynamics
The market's primary dynamic is the bifurcation of demand between mass-market consumers prioritizing affordability and an emerging 'prosumer' segment seeking professional-grade performance. This split forces manufacturers to manage dual innovation tracks for cost-optimized and feature-rich product lines.
Growth Catalysts
- Regulatory Mandates:The EU's Ecodesign Directive and similar energy efficiency regulations in other regions accelerate replacement cycles, pushing consumers toward newer, more compliant models.
- Urbanization in Emerging Economies:Rapid household formation and kitchen modernization in countries like India and Brazil create foundational demand for a wide range of small appliances.
- Commercial Segment Adoption:Expansion into light commercial applications, such as boutique hotels, cafes, and office pantries, opens a new, performance-oriented customer base for durable appliances.
Market Restraints
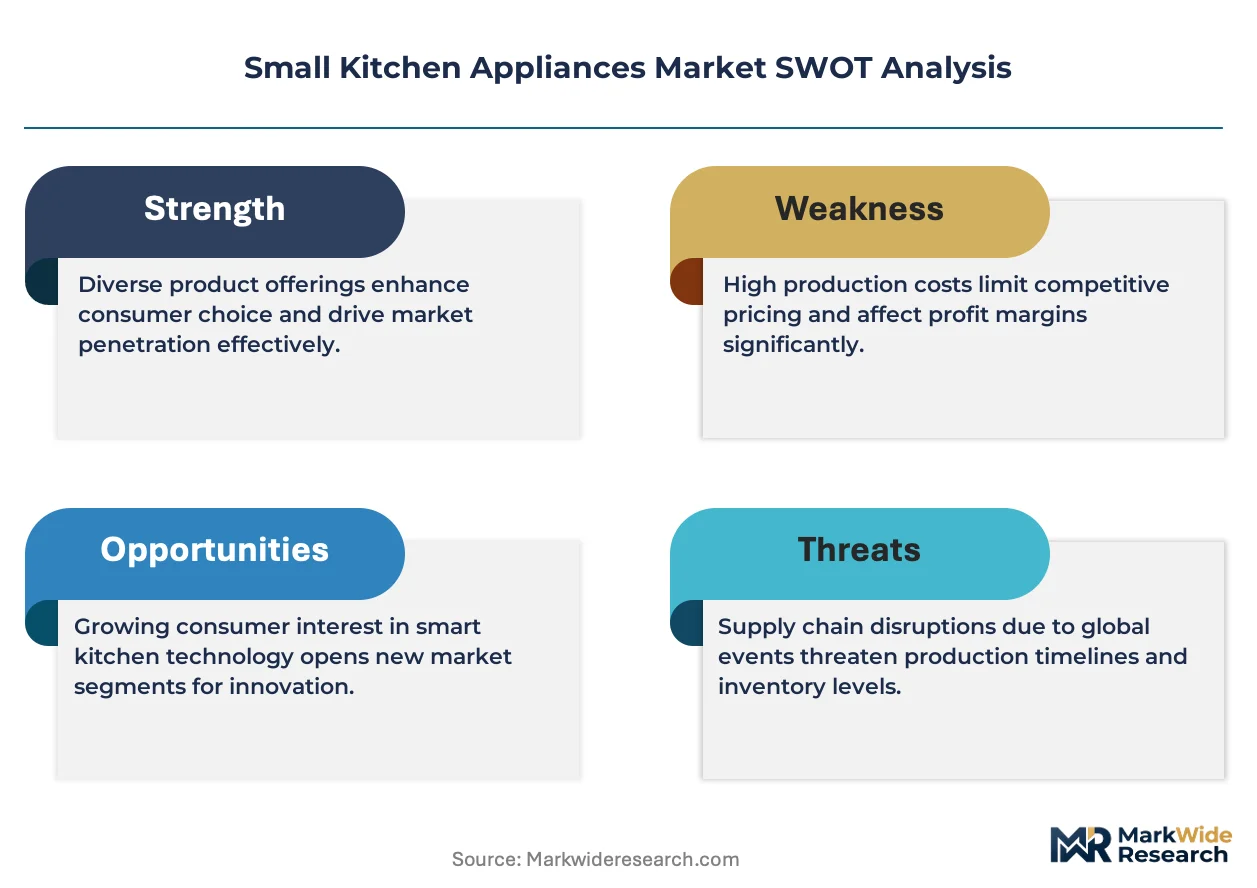
- Input Cost Volatility:Fluctuations in the price of essential materials like stainless steel, copper for motors, and high-grade plastics create margin pressure and sourcing instability for manufacturers.
- Threat of Cannibalization:The rise of multi-functional devices, which combine tasks like blending and food processing, can reduce the total number of individual units sold per household.
- Power and Performance Ceilings:Standard residential electrical circuits and countertop power constraints limit the ultimate performance of appliances, creating a technical barrier for certain high-demand cooking tasks.
Strategic Opportunities
- Smart Home Integration:Developing appliances with IoT connectivity and app-based controls allows for entry into the broader smart home ecosystem, enabling new use cases and premium pricing.
- Health and Wellness Niche:Targeting health-conscious consumers with specialized products like air fryers, vacuum blenders, and sous-vide cookers taps into durable lifestyle trends.
- Direct-to-Consumer Channels:Building robust e-commerce platforms enables manufacturers to control the customer experience, capture richer data, and improve margins by bypassing traditional retail intermediaries.
Industry Challenges
- Compliance Complexity:Manufacturers face significant overhead in navigating a fragmented landscape of international regulations, including the EU's CE marking, RoHS directive, and the US ENERGY STAR program.
- Intellectual Property Protection:The rapid pace of product design and feature innovation is challenged by the difficulty of protecting unique designs and software interfaces from fast-following competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Kitchen Appliances Market |
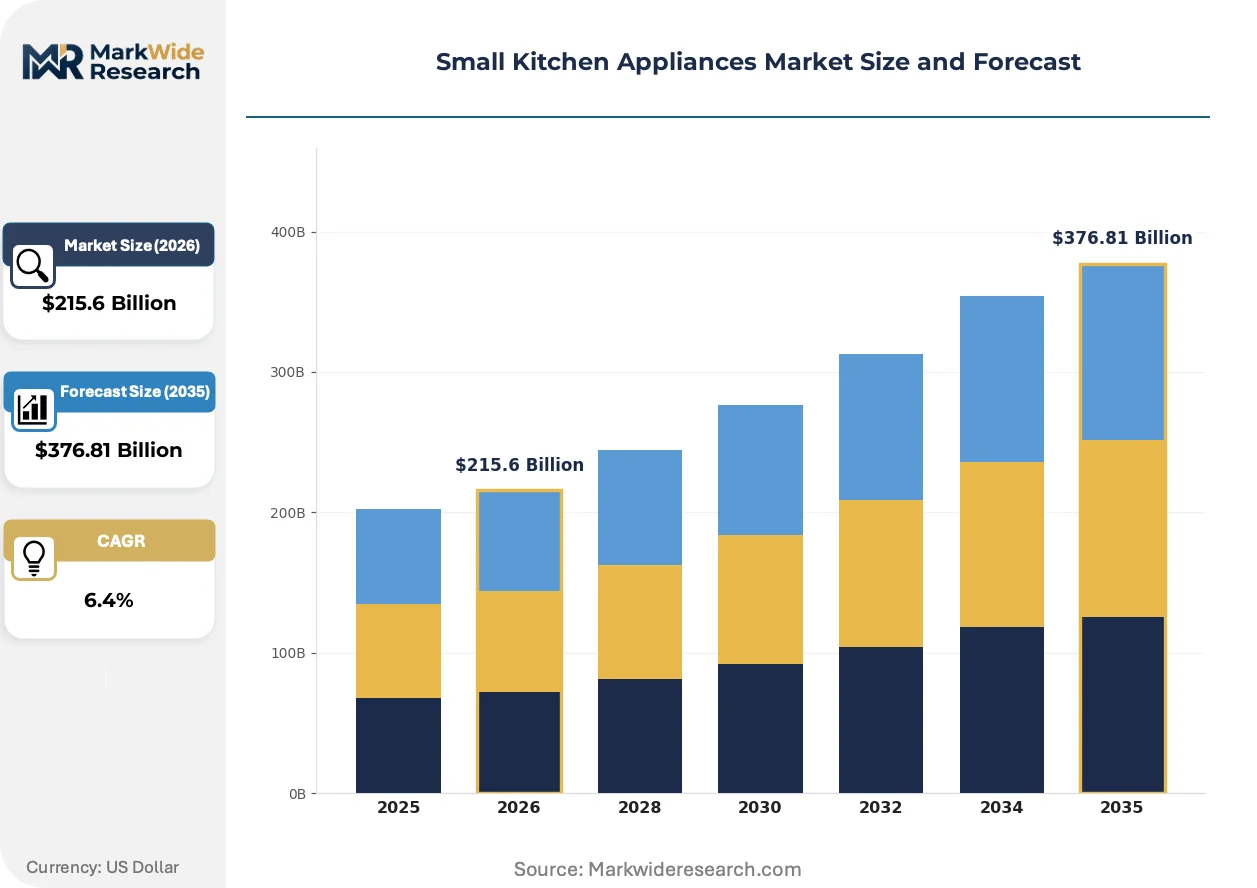
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $376.81 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Toasters, Microwaves, Food Processors Technology: Smart Appliances, Traditional Appliances, Energy-Efficient Models, Multi-functional Devices Customer Type: Households, Commercial Kitchens, Cafés, Hotels Distribution Channel: Online Stores, Retail Shops, Wholesale Distributors, Direct Sales |
| Companies Covered | Electrolux AB, Haier Smart Home, Whirlpool Corporation, Philips Domestic Appliances, Bosch Siemens Hausgeräte, LG Electronics, Midea Group, SharkNinja, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Kitchen Appliances Market Strategic Shifts & Innovations
Product evolution is defined by a push towards multi-functionality and connectivity, transforming standalone gadgets into integrated components of a smart kitchen. This shift aligns with consumer demand for convenience, space efficiency, and lifestyle-oriented features that go beyond basic food preparation.
Multi-functional appliances that integrate blending, chopping, and heating functions into a single chassis represent a major product evolution. Urban households with limited counter space are the primary adopters of these consolidated systems. This trend is decomposing the traditional market for single-purpose appliances, forcing brands to rethink their product portfolio strategy around integrated solutions rather than discrete gadgets.
New regulations governing material use directly influence product engineering and supply chain management. The EU’s RoHS directive, which restricts hazardous substances in electronic equipment, compels manufacturers to redesign components and certify their material sources for European market access. This primarily impacts internal electronics like printed circuit boards and power systems, necessitating investment in compliant component sourcing across the global supply chain.
Consumer purchasing decisions are increasingly influenced by digital media and online communities over traditional marketing. The authority of professional reviewers and social media influencers is disrupting the effectiveness of in-store displays and brand-led advertising. This behavioral shift is most pronounced among younger demographics in North America and Europe, who rely on video reviews and user-generated content for product discovery and validation.
Small Kitchen Appliances Market Segmentation
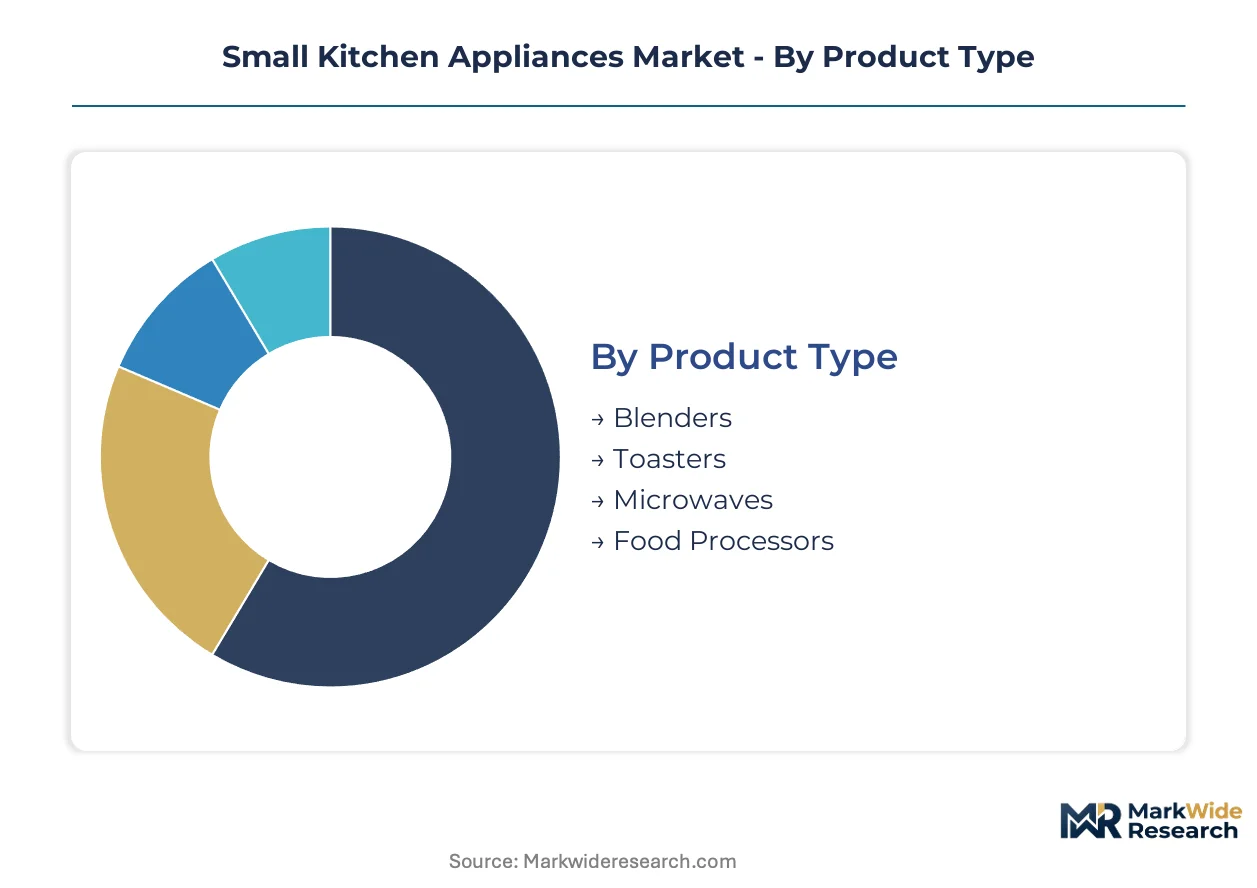
Market segmentation provides a granular view of distinct consumer behaviors and operational requirements shaping the small kitchen appliances industry. Understanding these divisions allows manufacturers to tailor product development and market entry strategies effectively. This analysis identifies key segments influencing market dynamics and growth trajectories.
Product Type:
Regulatory frameworks differentiate small kitchen appliances based on their power consumption and safety standards, influencing product design and market availability across various types.
- Blenders:These devices feature high-speed motors and specialized blades for pureeing, mixing, and crushing ingredients. Demand concentrates within health-conscious urban households in countries like Brazil, driven by the popularity of smoothies and nutritional drinks.
- Toasters:Essential for browning bread and pastries, these appliances serve basic breakfast needs in residential settings.
- Microwaves:Utilizing electromagnetic radiation for rapid heating and cooking, these remain a staple for convenience in households.
- Food Processors:These versatile machines offer multiple functions like chopping, slicing, and shredding with interchangeable attachments. Prosumer buyers and small commercial kitchens in Europe seek these for complex meal preparation, valuing efficiency and consistent results.
Established volume favors Microwaves; emerging adoption favors Food Processors.
Technology:
Customer preferences for convenience and integration define distinct technological pathways for small kitchen appliances.
- Smart Appliances:Equipped with IoT connectivity and app-based controls, these devices offer remote operation and personalized settings. Tech-savvy urban consumers in North America drive adoption, valuing seamless smart home ecosystem integration.
- Traditional Appliances:These models provide core functionalities without advanced connectivity, catering to mass-market appeal and affordability.
- Energy-Efficient Models:Designed to minimize power consumption, these appliances comply with regulations like the EU's Ecodesign Directive.
- Multi-functional Devices:These compact units combine several capabilities, such as blending and food processing, into a single chassis. Urban households with limited counter space in India show strong interest, prioritizing space efficiency and versatility.
Traditional Appliances maintain broad appeal; Smart Appliances are gaining share fastest.
Customer Type:
Small kitchen appliances serve varied operational environments, each requiring specific performance and durability characteristics.
- Households:These consumers prioritize ease of use, aesthetic design, and affordability for daily meal preparation. Rapid household formation in countries like India creates foundational demand for a wide range of appliances.
- Commercial Kitchens:These buyers demand heavy-duty construction, high output, and consistent performance for professional applications. Boutique hotels and cafes increasingly adopt durable appliances for enhanced service offerings.
- Cafés:Specialized appliances for beverage preparation and light food service are crucial for these establishments.
- Hotels:Appliances in this segment support guest room amenities and large-scale breakfast service operations.
Households constitute the foundational demand; Commercial Kitchens exhibit the steepest expansion trajectory.
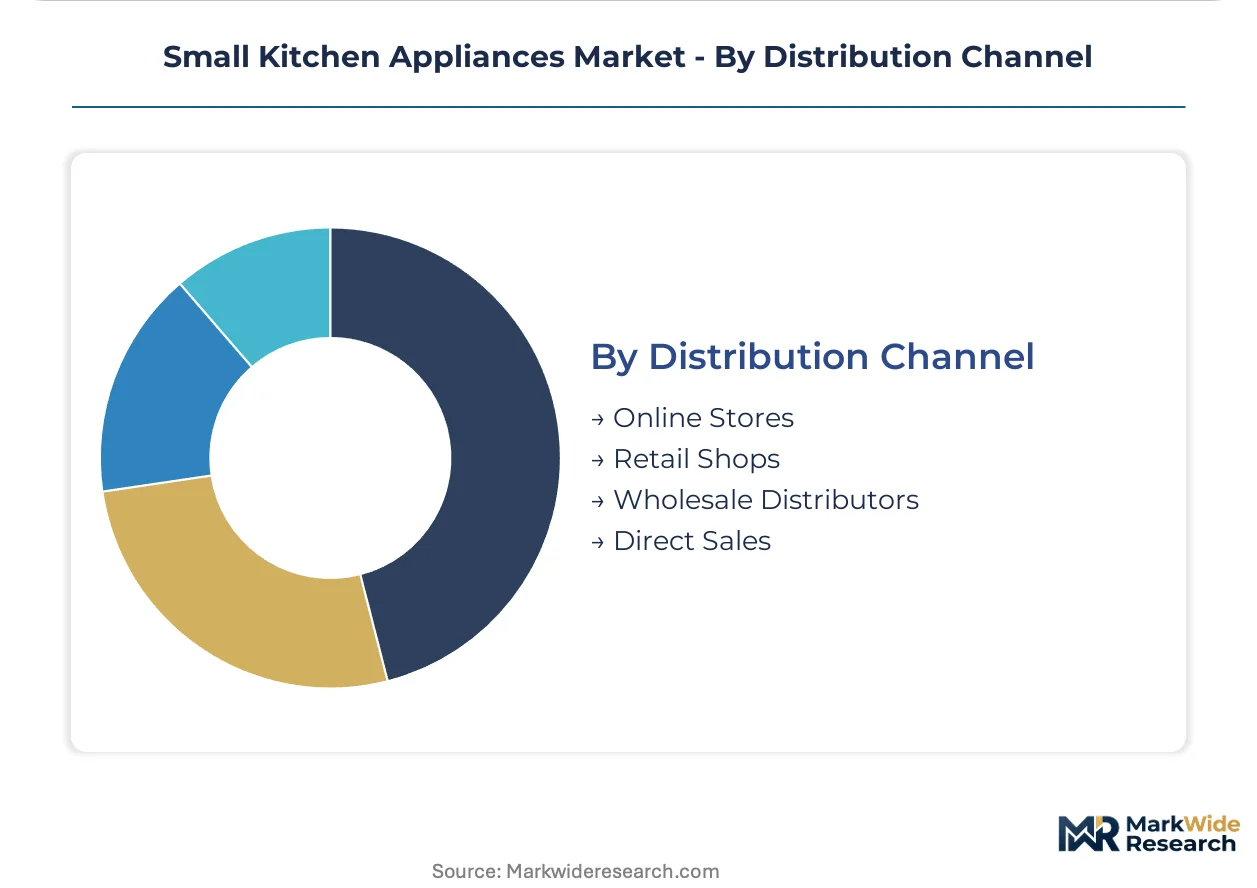
Distribution Channel:
Each distribution channel presents distinct margin profiles and market access strategies for manufacturers.
- Online Stores:Digital platforms offer extensive product catalogs, customer reviews, and competitive pricing. Younger demographics in Europe increasingly rely on these channels for product discovery and validation.
- Retail Shops:Physical storefronts provide immediate product availability and in-person demonstrations, appealing to traditional buyers. Consumers in North America value the ability to inspect products before purchase.
- Wholesale Distributors:These channels facilitate bulk purchasing and supply to commercial clients and smaller retailers.
- Direct Sales:Manufacturers utilize this channel to control the customer experience and capture richer data for specialized products.
Retail Shops maintain a significant footprint; Online Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global shipping lanes and integrated logistics networks underwrite the widespread distribution of small kitchen appliances. Demand patterns reflect diverse consumer preferences and regulatory environments across major economic regions. Urbanization and energy efficiency mandates shape market development in key countries.
United States
United States consumers prioritize smart appliance integration within broader home ecosystems. The EPA's ENERGY STAR program incentivizes energy-efficient models and influences purchasing decisions. Innovation hubs like Silicon Valley drive the development of connected kitchen devices and app-based controls.
Germany
German households and small commercial buyers seek performance-oriented appliances with robust engineering. The EU's Ecodesign Directive mandates energy efficiency, accelerating replacement cycles for compliant models. Engineering centers around Stuttgart concentrate on developing durable, high-quality small kitchen appliances.
India
India's rapid household formation and ongoing kitchen modernization initiatives generate foundational demand for small appliances. BIS standards ensure product quality and safety for mass-market adoption. Urban centers like Mumbai show strong interest in multi-functional devices, prioritizing space efficiency.
Brazil
Brazilian urbanization fuels demand for blenders and health-centric appliances among a growing middle class. INMETRO certification ensures electrical product safety and market access for manufacturers. São Paulo's dynamic consumer market concentrates demand for nutritional drink preparation devices.
China
China's tech-savvy consumers drive adoption of smart appliances with IoT connectivity and app-based controls. GB standards govern product safety and performance, influencing design and manufacturing. Shenzhen's extensive manufacturing ecosystem supports the production of diverse small kitchen appliances for domestic and export markets.
Small Kitchen Appliances Market Key Industry Players
Concentration sits with established global conglomerates leveraging brand recognition and extensive distribution networks. The market exhibits a tiered structure, from premium engineering-focused brands to mass-market multi-functional device providers. Strategic archetypes include innovation leaders, value-focused producers, and specialized niche players. Companies pursue portfolio diversification across small appliance categories and aggressive geographic expansion into emerging economies as dominant competitive moves.
Among globally recognized brands, Bosch Siemens Hausgeräte, a German-based entity, exemplifies the premium segment, leveraging its engineering reputation. This manufacturer targets performance-oriented prosumers and small commercial buyers. SharkNinja, an American-based company, occupies a strong position in the multi-functionality and aggressive online marketing archetype. Philips Domestic Appliances, a Netherlands-based entity, represents the health-centric innovation trend with specialized product offerings like air fryers. These players demonstrate varied approaches to market capture, from engineering excellence to wellness-focused solutions.
| Leading Market Players |
|---|
| Electrolux AB |
| Haier Smart Home |
| Whirlpool Corporation |
| Philips Domestic Appliances |
| Bosch Siemens Hausgeräte |
| LG Electronics |
| Midea Group |
| SharkNinja |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
The substitution of traditional metal components with advanced, lighter-weight polymers reshapes manufacturing footprints and reconfigures raw material procurement strategies. This shift influences pricing economics by altering production costs and supply chain dependencies.
Pricing Analysis
Volume-discount tiering structures define pricing across the small kitchen appliances market. Premium-mid-economy pricing differentiation reflects brand reputation and certified performance levels, particularly for commercial-grade units. Pricing softness runs through the mass-market segment due to intense competition and input cost volatility. Mass-market consumers prioritize affordability, while prosumer and commercial buyers exhibit lower price sensitivity for performance-oriented features.
Supply Chain Analysis
Manufacturers balance just-in-time practices for standard components with strategic stockpiles for specialized electronic modules and motors. Supply concentrates in China, Germany, and Vietnam, which serve as major manufacturing and assembly hubs. The production process relies on stainless steel, copper for motors, and high-grade plastics. Commodity price volatility represents a significant structural risk for component sourcing. Distribution runs through online stores, traditional retail shops, and wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small kitchen appliances market is experiencing a cyclical recovery, driven by renewed household formation rates in emerging economies. This demographic expansion creates foundational demand for essential kitchen infrastructure.
For Market Incumbents: Shield premium market share by investing deeply in IoT connectivity and smart home ecosystem integration. Consolidate market position through strategic acquisitions of specialized tech firms to counter fast-following competitors. Strengthen brand loyalty by leveraging engineering reputation and expanding after-sales service networks. This approach mitigates margin pressure from mass-market offerings.
For New Entrants and Emerging Players: Lead with specialized health and wellness products targeting specific dietary needs, such as advanced vacuum blenders. Penetrate urban households in India and Brazil with compact, multi-functional devices that optimize limited counter space. Utilize direct-to-consumer online channels and influencer marketing to build brand awareness and bypass traditional retail gatekeepers. This strategy captures niche demand effectively.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-functional device specialists demonstrating strong digital channel penetration. The market offers long-term viability over a 5-10 year window, driven by smart home integration trends. Target acquisition profiles include regional manufacturers with robust supply chains or strong intellectual property in app-based controls. Sustained growth in smart appliance penetration rates across North America and Europe signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Manufacturers gain richer customer data and improve margins by bypassing traditional retail intermediaries. |
| IoT Connectivity R&D | Developing app-based controls enables entry into the broader smart home ecosystem for premium pricing. |
| Energy Efficiency Certification Investment | Compliance with EU Ecodesign Directive and EPA ENERGY STAR accelerates replacement cycles. |
| Multi-functional Product Line Diversification | Consolidating functions into single units optimizes counter space for urban households. |
| Emerging Market Localization | Adapting products to local preferences drives foundational demand in India and Brazil. |
Research Approach
Operator-level perspectives from product development leads, procurement managers, and retail channel heads anchored the qualitative base for this analysis. Primary interviews were validated against extensive secondary research, including EU RoHS directives, EPA ENERGY STAR reports, and national statistical office data on household consumption. This approach employed both bottom-up market sizing and top-down validation to ensure data integrity.
Sensitivity analysis informed the projection of market trajectories across the analysis window, accounting for various growth scenarios. The analytical framework modeled dimensions including product type, technology, customer type, distribution channel, and energy efficiency tier. Compound annual growth rates were derived from historical data. Key inputs included household formation rates and urbanization trends in emerging economies.
Forecasts assume regulatory continuity in EU, US, and Indian regimes; material policy shifts would require re-modeling. The analysis reflects assumptions regarding input cost stability and geopolitical trade tensions. Revision becomes warranted when commodity prices or trade policies cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Cotton Candy Maker Market