
 US Range Cooker Market | 2026-2036
US Range Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
US Range Cooker Market Intelligence
The US Environmental Protection Agency's (EPA) ENERGY STAR program is pivoting consumer preference toward more efficient appliances, altering the competitive landscape. In this environment, Viking specializes in the high-end, professional-grade market segment, targeting luxury residential kitchens. Samsung, in contrast, competes by integrating advanced smart technology and connectivity features across a wider range of price points, appealing to tech-savvy households.
A range cooker is a standalone kitchen appliance that integrates a cooktop surface with one or more ovens below. Technical specifications like British Thermal Unit (BTU) output for gas burners or induction element wattage are key performance differentiators. While gas ranges maintain a strong foothold, the induction range product type is gaining share due to efficiency and safety. The market also sees significant investment in smart technology features, with connectivity and automated cooking functions becoming key purchase criteria.
Regulations from the Department of Energy (DOE) set minimum energy conservation standards for residential cooking products. The Federal Trade Commission (FTC) mandates EnergyGuide labels, providing consumers with clear efficiency information. These frameworks ensure a baseline level of performance and influence new product development. Manufacturers now face a strategic choice between prioritizing advanced digital features or focusing on fundamental cooking performance and superior energy efficiency.
Market Dynamics
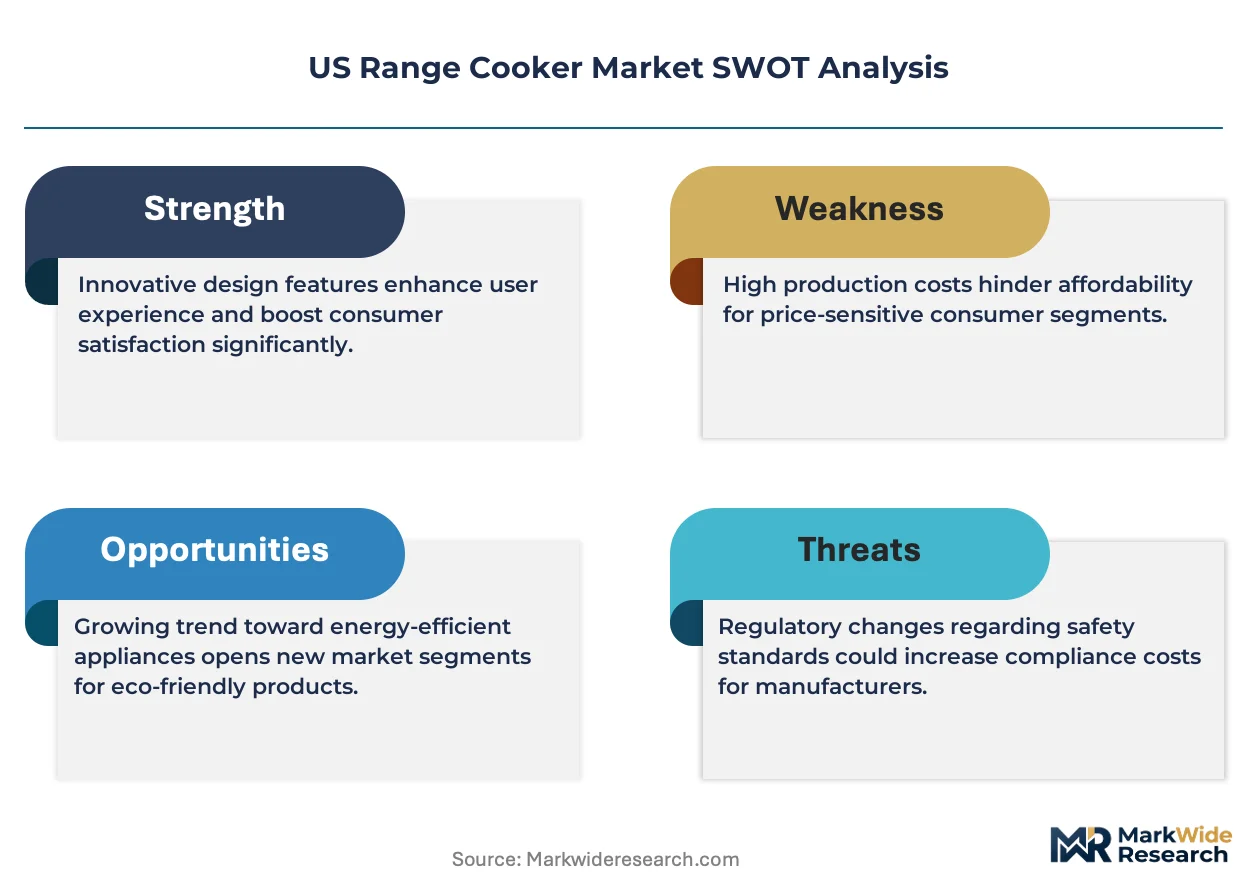
The US range cooker market is defined by a primary tension between regulatory mandates for energy efficiency and escalating consumer demand for professional-grade power and features. This dynamic forces manufacturers to innovate on both performance and sustainability simultaneously.
Growth Catalysts
- Induction Technology Adoption:The shift toward induction cooktops, driven by their superior energy efficiency, rapid heating, and safety profile, is accelerating product replacement cycles in residential kitchens across the United States.
- Premium Residential Renovation:A strong housing market, particularly in high-income states like California, fuels demand for high-end, professional-style range cookers as central features in luxury kitchen remodels.
- ENERGY STAR Program:The EPA's ENERGY STAR certification provides a clear benchmark for energy efficiency, influencing consumer purchasing decisions and incentivizing manufacturers to develop products that exceed baseline federal standards.
Market Restraints
- High Upfront Investment:The significant price premium for professional-grade and feature-rich smart ranges creates a cost barrier, limiting adoption primarily to the high-end residential segment and slowing mass-market penetration.
- Threat of Component-Based Kitchens:Consumers increasingly opt for separate wall ovens and cooktops, which offer greater design flexibility and layout customization, presenting a direct substitution threat to the all-in-one range cooker format.
- Home Infrastructure Limitations:Older homes in many US regions lack the requisite electrical wiring to support high-amperage induction or powerful electric ranges, making installation costly and complex for homeowners.
Strategic Opportunities
- Smart Home Ecosystem Integration:Developing models with advanced IoT connectivity and AI-driven automated cooking functions creates value for tech-forward households and opens new revenue streams through software and service-based features.
- Multi-Family and Build-to-Rent Sector:Targeting large-scale property developers in the growing build-to-rent market with durable, energy-efficient, and stylish appliances offers a significant volume-based sales channel.
- Direct-to-Consumer Customization:Launching direct-to-consumer (DTC) platforms allows for greater product personalization, such as custom colors and hardware finishes, capturing a segment of the market seeking bespoke kitchen aesthetics.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers face the persistent challenge of re-engineering products to meet evolving minimum energy conservation standards set by the Department of Energy (DOE), requiring continuous R&D investment.
- Component Supply Chain Volatility:The reliance on global supply chains for critical electronic components, including semiconductors for smart displays and controls, exposes production schedules to significant disruption and cost instability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Range Cooker Market |
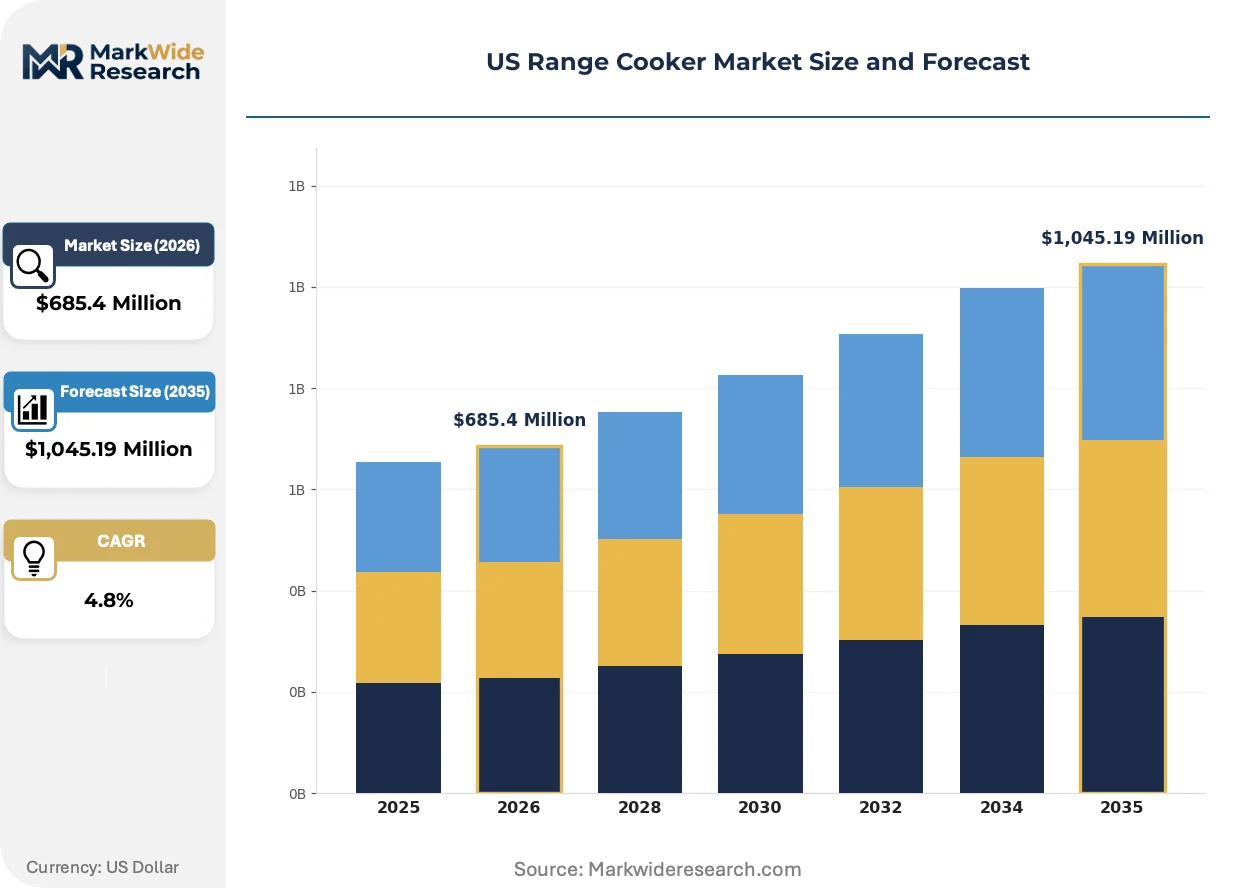
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Range, Electric Range, Dual Fuel Range, Induction Range End User: Residential, Commercial, Hospitality, Catering Size: Compact, Standard, Large, Professional Feature: Smart Technology, Self-Cleaning, Convection Oven, Multi-Function |
| Companies Covered | Café, Bosch, ZLINE Kitchen and Bath, Viking, Samsung, LG, Electrolux, Frigidaire, GE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Range Cooker Market Strategic Shifts & Innovations
Product development in the US range cooker market increasingly balances raw cooking power with sophisticated digital intelligence. This dual focus is pushing manufacturers to compete on both thermodynamic efficiency and user experience, altering the definition of a premium appliance.
Smart connectivity platforms are a defining feature of new product cycles. These systems use Wi-Fi and Bluetooth to link the range cooker to a homeowner's mobile device for remote preheating, monitoring, and diagnostics. Tech-savvy households and the luxury renovation segment are the earliest adopters of this technology. This integration is decentralizing appliance control from the physical interface to a centralized smart home application, enabling more complex, software-driven cooking functions.
The Federal Trade Commission's (FTC) EnergyGuide label mandate directly impacts consumer behavior at the point of sale. This regulation requires a clear, standardized disclosure of an appliance's estimated annual energy consumption and operating cost. The induction range product type benefits most from this transparency, as its efficiency advantages become a tangible selling point against traditional gas and electric coil models.
A notable behavioral shift is the move toward aesthetic personalization over standardized stainless steel designs. Consumers are now demanding a wider palette of finishes, custom hardware options, and modular configurations to match specific kitchen design concepts. This trend disrupts the mass-production model, favoring manufacturers with agile assembly processes capable of supporting build-to-order purchasing. This is most visible in affluent urban markets where kitchen design is a key element of home value.
US Range Cooker Market Segmentation
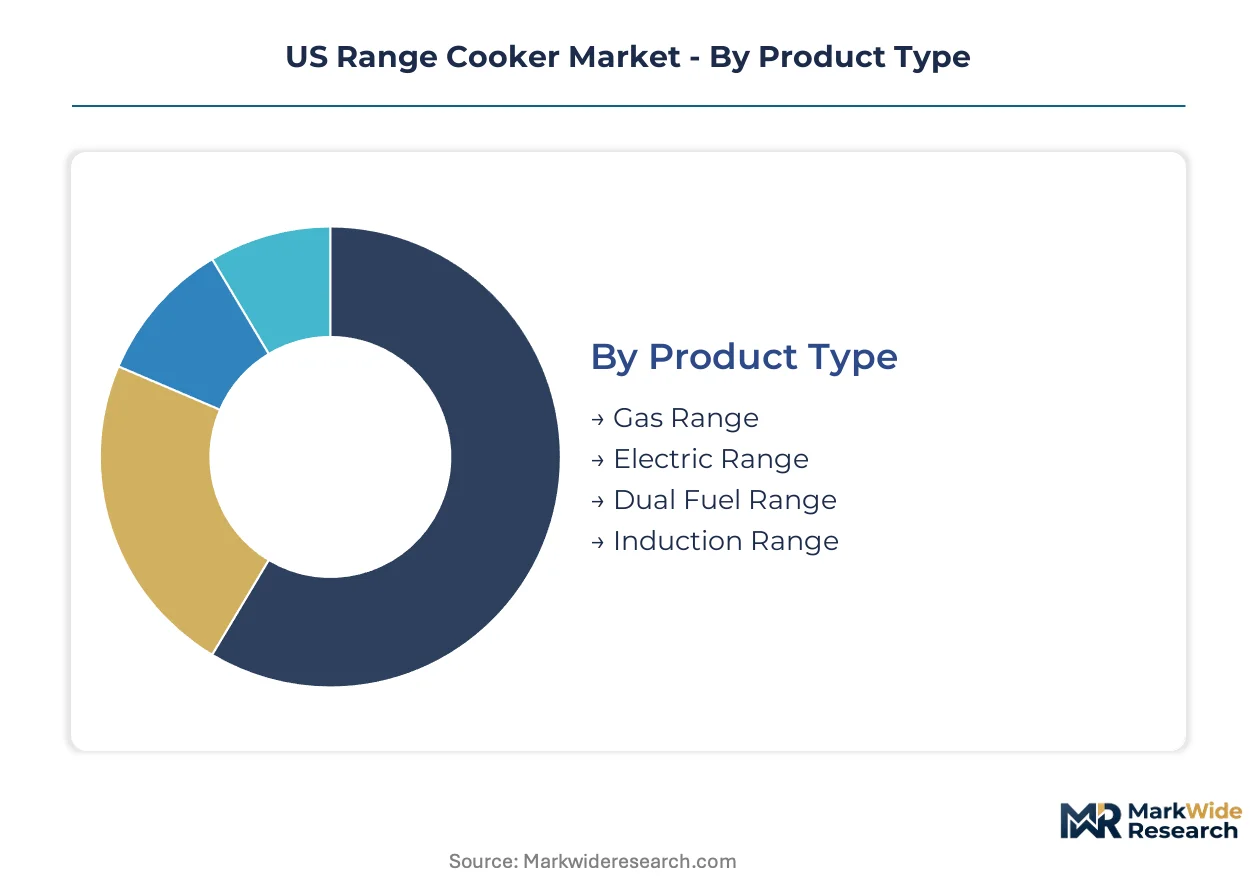
The US range cooker market segmentation reveals distinct consumer preferences and technological adoption patterns. Understanding these categories is critical for manufacturers to align product development with evolving demand and regulatory pressures. This analysis delineates the market by product type, end-user, size, and features, highlighting key areas of growth and competition.
Product Type:
The market's product type segmentation illustrates a dynamic tension between established volume leaders and emerging premium technologies.
- Induction Range:Induction ranges utilize electromagnetic fields to directly heat cookware, offering high energy efficiency and precise temperature control. Demand for these models is concentrating in high-income US states like California, driven by energy efficiency mandates and consumer safety preferences.
- Gas Range:Gas ranges provide instant heat and visible flames, favored by many professional chefs for their responsive cooking performance. Residential demand remains strong in regions with affordable natural gas access and where homeowners prioritize traditional cooking methods.
- Electric Range:Electric ranges use radiant heat from coil or smooth glass-ceramic surfaces, widely available across the US market.
- Dual Fuel Range:Dual fuel ranges combine a gas cooktop with an electric oven, offering versatility for varied cooking tasks in US households.
Mature deployment sits with Electric Range. Newer deployment is concentrated in Induction Range.
End User:
End-user segments define purchasing priorities, ranging from individual household needs to large-scale institutional requirements.
- Residential:Residential users include individual homeowners and families seeking appliances for daily meal preparation within their private kitchens. This segment drives demand for smart features and energy-efficient models, particularly in new home constructions across the US.
- Commercial:Commercial end-users encompass restaurants, cafes, and other food service establishments requiring durable, high-capacity cooking equipment. Demand here prioritizes reliability and high BTU output for continuous, heavy-duty operation.
- Hospitality:The hospitality sector, including hotels and resorts, purchases range cookers for guest suites and on-site dining facilities.
- Catering:Catering businesses require portable or robust range cookers for off-site event preparation and temporary kitchen setups.
The Residential segment exhibits the steepest expansion trajectory. Commercial applications maintain consistent procurement volumes.
Size:
Product size segmentation reflects diverse kitchen layouts and consumer space availability across US homes.
- Standard:Standard size range cookers, typically 30 inches wide, represent the most common appliance dimension in US residential kitchens. This size is prevalent in suburban homes, balancing cooking capacity with typical kitchen footprints.
- Professional:Professional-sized range cookers, often 36 inches or wider, offer expanded cooking surfaces and multiple ovens for serious home chefs. Demand for these units is concentrated in luxury residential renovations, particularly in affluent urban and suburban areas.
- Compact:Compact models are designed for smaller kitchens, apartments, or secondary living spaces, maximizing utility in limited areas.
- Large:Large range cookers provide extensive cooking capacity, often found in larger homes or specialized culinary environments.
Standard sizes form the market's foundational volume. Professional models are gaining share fastest within the premium segment.
Feature:
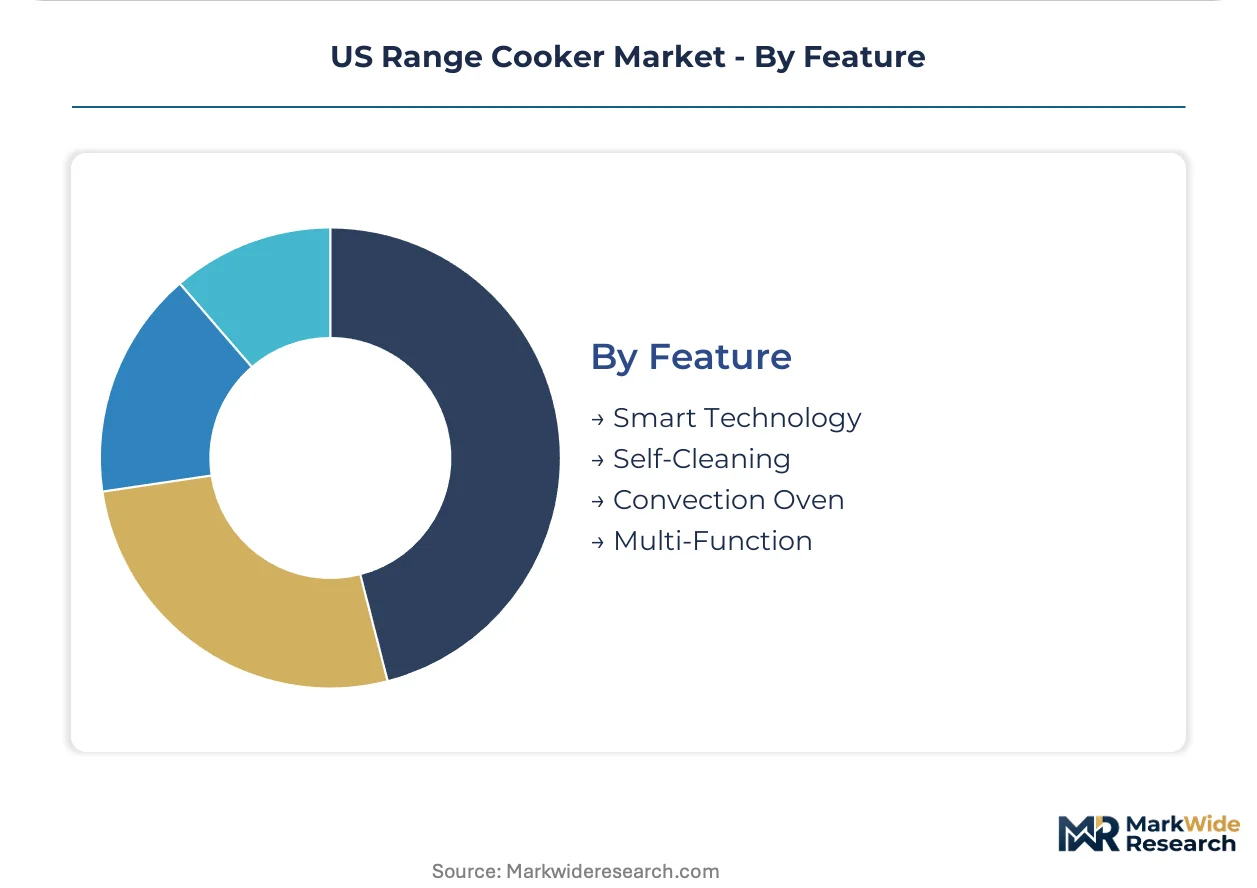
Feature-based segmentation highlights technological advancements and consumer preferences for convenience and enhanced functionality.
- Smart Technology:Smart technology features include Wi-Fi connectivity, remote control via mobile apps, and automated cooking programs. Tech-savvy households in metropolitan areas drive demand for these integrated functionalities.
- Convection Oven:Convection ovens incorporate a fan and exhaust system to circulate hot air, ensuring more even cooking and faster results. This feature is a key differentiator for consumers seeking improved baking and roasting performance.
- Self-Cleaning:Self-cleaning features use high temperatures or steam to simplify oven maintenance, appealing to consumers prioritizing convenience.
- Multi-Function:Multi-function ranges offer various cooking modes beyond standard bake and broil, providing versatility for diverse culinary needs.
Self-Cleaning remains a widely adopted feature. Smart Technology is experiencing the most dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles, California, anchors a significant portion of US range cooker demand, particularly for premium and energy-efficient models. High-income residential renovations across the state drive strong interest in professional-grade appliances. This concentration reflects both lifestyle preferences and stringent local energy efficiency standards.
California
Demand for induction ranges and professional-style units is strong in California, driven by consumer preference for advanced technology. State-level building codes often exceed national minimums, accelerating the adoption of energy-efficient cooking solutions. The San Francisco Bay Area showcases intense competition for smart, connected appliances in luxury residential developments.
Northeast Corridor
Affluent households within the Northeast Corridor prioritize high-performance dual fuel and professional-grade gas ranges for their renovated kitchens. The US Department of Energy (DOE) minimum energy conservation standards influence product offerings throughout this densely populated region. New York City and Boston exhibit sustained demand for compact, feature-rich models in urban apartments.
Texas
Expansive housing growth across Texas fuels consistent demand for standard-sized electric and gas ranges, balancing cost with functionality. The Federal Trade Commission (FTC) EnergyGuide labels inform consumer choices, particularly in the value-driven segments of the market. Houston's booming residential construction sector represents a volume-based sales channel for major appliance manufacturers.
Midwest
Homeowners in the Midwest often seek reliable and durable gas and electric ranges, reflecting a preference for traditional cooking methods and value. The EPA's ENERGY STAR program encourages the purchase of more efficient models, impacting appliance sales in suburban areas. Chicago remains a hub for appliance distribution, influencing product availability across the broader region.
US Range Cooker Market Key Industry Players
The competitive structure tilts toward a balanced mix of established appliance conglomerates and specialized premium manufacturers in the US range cooker market. Several players focus on integrating advanced smart home technology, while others prioritize professional-grade cooking performance. Manufacturers frequently engage in portfolio diversification to cover various price points and pursue strategic partnerships for component supply. This dynamic landscape encourages continuous product innovation across all segments.
Within the premium and professional-grade tier, Viking exemplifies a focus on high-performance appliances designed for luxury residential kitchens. Samsung, a South Korean conglomerate, occupies a position emphasizing smart technology integration and connectivity features across its diverse product lines. Bosch, a German multinational, represents a segment that balances quality engineering with innovative design, appealing to consumers seeking reliable and aesthetically pleasing options.
| Leading Market Players |
|---|
| Café |
| Bosch |
| ZLINE Kitchen and Bath |
| Viking |
| Samsung |
| LG |
| Electrolux |
| Frigidaire |
| GE |
| Others |
Cost & Logistics Intelligence
Induction technology adoption simultaneously reshapes cost economics and supply concentration within the US range cooker market. This shift necessitates new sourcing strategies for specialized components, influencing overall production costs and pricing models.
Pricing Analysis
Performance-driven pricing anchors the premium segment, reflecting advanced cooking capabilities and integrated smart features. Pricing stratifies across premium, standard, and economy tiers, with brand premium and customization level serving as key differentiation drivers. Cost compression in the standard electric and gas range segments intensifies due to broad competition. Luxury residential consumers exhibit lower price sensitivity compared to mass-market households.
Supply Chain Analysis
Single-source vulnerability sits with critical electronic components sourced from East Asian manufacturing hubs. The supply chain draws from specific countries like China, Taiwan, and South Korea for semiconductors and smart display modules. Component supply chain volatility represents a significant structural risk for manufacturers. Distribution runs through a hybrid model, encompassing traditional retail channels, direct-to-consumer platforms, and large-scale builder partnerships for new construction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US range cooker market presents a supply-constrained story, with component supply chain volatility for smart features propping pricing in advanced models.
For Market Incumbents:Acquire specialized software firms to deepen smart home ecosystem integration capabilities. Invest heavily in R&D for advanced induction technology to meet evolving EPA ENERGY STAR standards and counter the threat of component-based kitchens. Expand direct-to-consumer channels to gain greater control over customer experience and customization options. Prioritize certification investment for energy-efficient models to leverage federal incentives and consumer preferences.
For New Entrants and Emerging Players:Begin with targeted solutions for the multi-family and build-to-rent sector, offering durable and energy-efficient compact models. Focus on urban apartments as a penetrable segment, emphasizing space-saving designs and smart connectivity. Leverage a strong digital presence and customization options as a primary go-to-market angle. Innovate on modular designs that simplify installation in homes with existing infrastructure limitations.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized technology providers or niche manufacturers with strong brand equity in the luxury segment. The market exhibits long-term viability, driven by sustained residential renovation cycles and increasing energy efficiency mandates. Target acquisition archetypes include companies with proprietary smart technology platforms or advanced induction manufacturing capabilities. The acceleration of induction range adoption represents a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating range cookers with broader smart home ecosystems enhances user convenience for tech-savvy households. |
| Green Manufacturing Transition | Adopting sustainable production methods aligns with evolving consumer values and regulatory pressures from the EPA. |
| Direct-to-Consumer Launch | Establishing DTC channels allows manufacturers to offer bespoke customization and capture higher margins. |
| Product Line Diversification | Expanding into compact or professional-sized models addresses specific kitchen layouts and end-user demands. |
| R&D Investment | Developing advanced induction technology improves energy efficiency and cooking performance, attracting discerning consumers. |
Research Approach
Independent corroboration across EPA ENERGY STAR data, DOE regulatory documents, and luxury kitchen designers underwrites the qualitative findings. The analysis combines primary interviews with appliance manufacturers' R&D heads, retail channel managers, and residential contractors. Secondary validation draws from housing market analyses and FTC consumer reports, ensuring a robust data foundation for bottom-up and top-down triangulation.
Rate-of-change decomposition forms the analytical framework for projecting market evolution across the analysis window. The model segments market dynamics by product type, end-user, size, feature, and regional adoption patterns. Compound annual growth rates derive from historical trends, projected market drivers, and the evolving energy efficiency policy landscape. Key forecast inputs include residential renovation spending and the pace of smart home technology integration.
Underlying measurement precision varies by segment; professional models and smart technology segments carry tighter precision than others. Forecasts reflect assumptions regarding economic stability and technological progression within the US market. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Toaster Market