
 Australia Kitchen Appliances Market | 2026-2036
Australia Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Kitchen Appliances Market Outlook
The premium kitchen appliance tier is decoupling from commodity segments on the basis of connectivity, energy performance, and design integration rather than price alone. Electrolux anchors its position through European-engineered refrigeration platforms tailored to Australian climate conditions. Breville Group specializes in countertop appliances with barista-grade precision, occupying a defensible niche against full-line competitors. Fisher & Paykel leverages its New Zealand manufacturing heritage to sustain premium dishwasher and cooktop offerings with distinctive drawer-based configurations.
Australia kitchen appliances encompass electrically or gas-powered equipment designed for food storage, preparation, cooking, and cleaning in residential and commercial settings, typically operating at 230-240V/50Hz with energy ratings certified under the Equipment Energy Efficiency program. These products serve households, restaurants, hotels, and institutional catering operations where throughput, hygiene compliance, and operating cost control determine procurement decisions. Refrigerators command the largest product category share due to replacement cycles and secondary-unit purchases in multi-dwelling households. Smart appliances represent the fastest-expanding technology segment as Wi-Fi-enabled ovens and app-controlled refrigeration systems gain traction among tech-forward renovators. The hospitality end user segment concentrates demand for heavy-duty dishwashers and rapid-cook ovens in Sydney's competitive restaurant and hotel construction pipeline.
Energy efficiency standards administered by the Australian government's Equipment Energy Efficiency program and water efficiency labeling governed by WELS directly shape product eligibility for retail placement and consumer rebate programs. The Electrical Equipment Safety System overseen by state-based regulators mandates compliance testing that adds certification cost and time for new market entrants. Stakeholders must monitor impending revisions to MEPS thresholds and the expansion of state-level appliance rebate schemes as these will determine which product portfolios remain commercially viable.
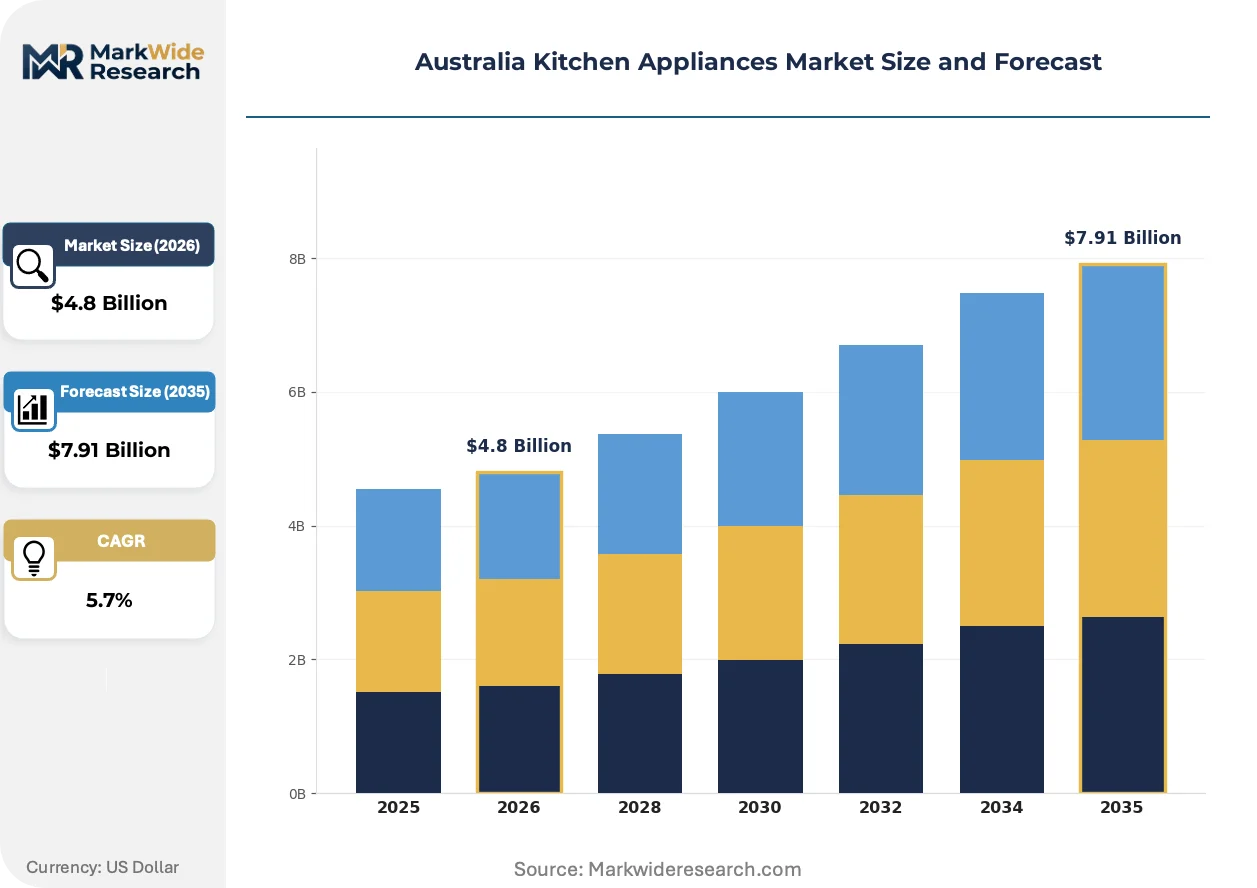
Market Dynamics
Equipment Energy Efficiency program revisions are compressing product development cycles across Australian manufacturers, forcing simultaneous redesign of compressor systems, insulation materials, and control electronics to maintain retail placement eligibility.
Growth Catalysts
- Apartment densification in Sydney and Melbourne:Multi-dwelling construction is generating secondary-unit appliance purchases and compact-format demand that full-line manufacturers are racing to serve.
- MEPS threshold escalations:The Australian government's Equipment Energy Efficiency program is tightening minimum energy performance standards, creating replacement demand as older stock becomes non-compliant.
- Smart kitchen integration:Wi-Fi-enabled refrigeration and app-controlled cooking systems are converging with residential renovation pipelines, expanding the addressable premium tier.
Market Restraints
- Copper and steel input volatility:Raw material cost swings compress margin buffers for mid-tier manufacturers lacking long-term supply contracts.
- Concentrated retail gatekeeping:Major appliance chains in Australia control shelf access, creating distribution bottlenecks for emerging brands.
- Gas connection phase-out timelines:State-level restrictions on new gas infrastructure in Victoria and New South Wales are stranding cooktop development pipelines.
Strategic Opportunities
- Queensland and Western Australia penetration:Secondary metro markets exhibit lower smart-appliance saturation and faster household formation rates than Sydney-Melbourne corridors.
- Commercial hospitality retrofit:Rapid-cook oven and heavy-duty dishwasher demand from Sydney's restaurant construction pipeline outpaces residential replacement cycles.
- WELS rebate expansion:State-level water efficiency incentive programs are creating price-advantaged positioning for compliant dishwasher and tapware portfolios.
Industry Challenges
- Electrical certification timelines:State-based Electrical Equipment Safety System testing creates 4-6 month market entry delays for new product introductions.
- Legacy system integration:Smart appliance connectivity protocols fragment across proprietary platforms, forcing manufacturers to maintain multiple software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Kitchen Appliances Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Microwaves End User: Residential, Commercial, Hospitality, Catering Technology: Smart Appliances, Energy-Efficient, Traditional, Induction Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Wholesalers |
| Companies Covered | LG Electronics, Electrolux, Kleenmaid, Whirlpool Corporation, Haier Group, Bosch, Samsung Electronics, Breville Group, Fisher & Paykel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Kitchen Appliances Market Strategic Shifts
Connected kitchen ecosystems are rewriting competitive boundaries as appliance functionality merges with home automation platforms and energy management systems. The convergence is compressing traditional hardware-only margins while opening recurring revenue streams.
Sensor-driven predictive maintenance is converging with refrigeration compressors, enabling failure detection before component breakdown. High-end residential renovators in Melbourne and Sydney are specifying these systems at accelerating rates. The technology is converging with energy retailer demand-response programs, creating dual-revenue positioning for manufacturers.
Australia's Equipment Energy Efficiency program and WELS labeling scheme are tightening compliance thresholds faster than historical revision cycles. Manufacturers must now certify redesigned platforms annually rather than across multi-year product lifecycles. Refrigeration and dishwasher categories face the steepest redesign obligations, compressing R&D amortization periods.
Builder-specified appliance packages are displacing retail-channel selection in new apartment construction. Project home developers in Sydney's middle-ring suburbs are consolidating procurement through direct manufacturer relationships. This channel rotation is most visible in dishwasher and cooktop categories where standardization reduces installation complexity.
Australia Kitchen Appliances Market Segmentation
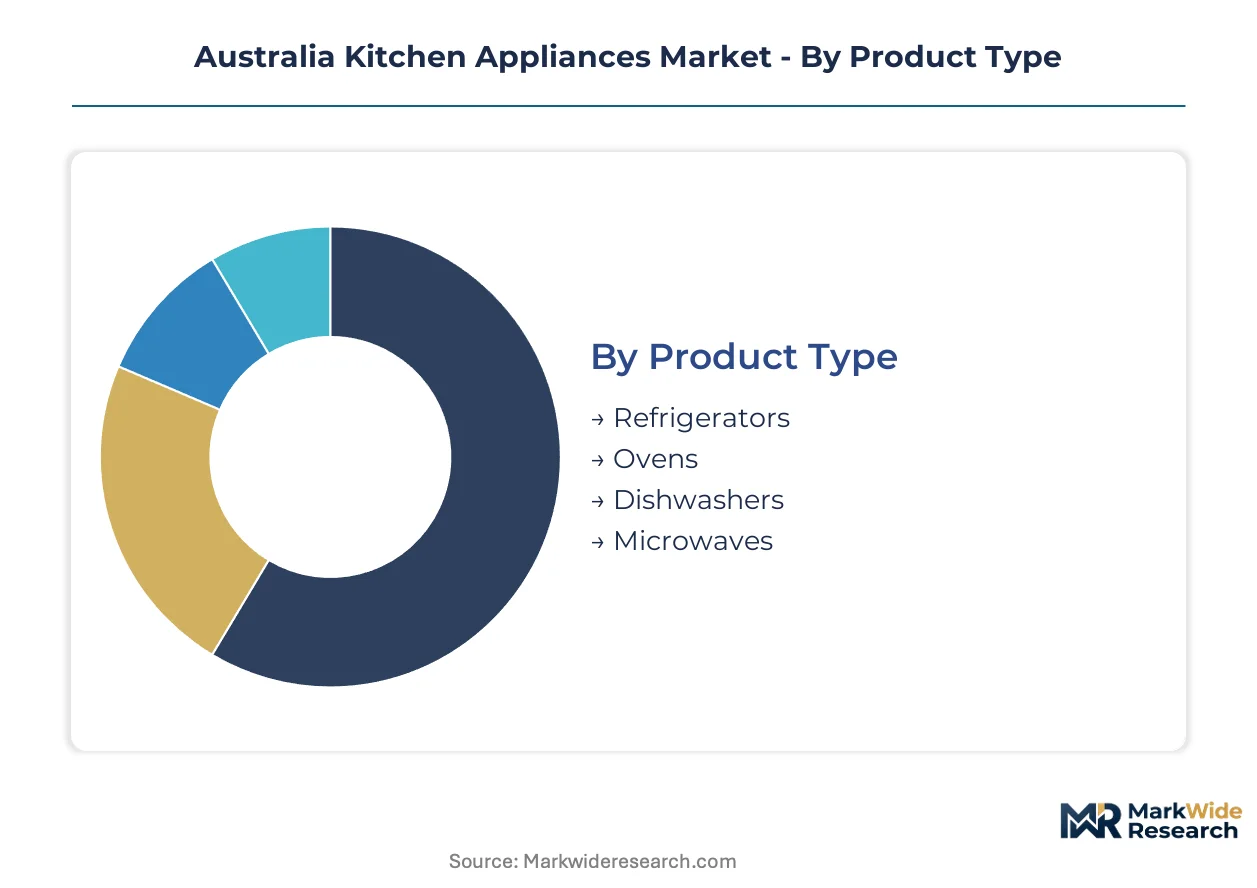
Segmentation in the Australia Kitchen Appliances Market reveals how regulatory pressure and channel evolution are fragmenting demand across incompatible specifications. MEPS thresholds and WELS compliance create non-substitutable product tiers that manufacturers must maintain in parallel.
Product Type:
Refrigeration platforms anchor the largest development investment due to compressor redesign cycles driven by Equipment Energy Efficiency program escalations.
- Refrigerators:Multi-compartment units with inverter-driven compressors and vacuum-insulation panels dominate premium renovation specifications. Demand concentrates in Sydney and Melbourne apartment densification corridors where secondary-unit purchases and compact-format requirements multiply unit velocity per household.
- Ovens:Pyrolytic self-cleaning cavities with steam-assist functionality command specification in high-end residential renovations. Melbourne's inner-ring renovation pipeline favors 90cm built-in configurations with app-controlled temperature profiling.
- Dishwashers:Drawer-based and compact under-bench formats address space constraints in multi-dwelling construction.
- Microwaves:Inverter-based flatbed designs replace turntable mechanisms in countertop refreshes.
Mature deployment sits with Refrigerators. Newer deployment is concentrated in Ovens with connected functionality.
End User:
Procurement authority splits between retail-channel household decision-makers and project-specified builder procurement with incompatible volume and standardization requirements.
- Residential:Individual households selecting through retail chains or online platforms, with replacement cycles averaging 12-15 years for refrigeration and 8-10 years for cooking appliances. Sydney and Melbourne account for disproportionate volume due to renovation intensity and multi-dwelling household formation.
- Hospitality:Restaurants, hotels, and institutional foodservice operations prioritizing throughput, hygiene compliance, and operating cost control. Sydney's competitive restaurant construction pipeline drives rapid-cook oven and heavy-duty dishwasher procurement ahead of residential replacement cycles.
- Commercial:Non-hospitality businesses including corporate cafeterias and aged-care facilities with standardized meal programs.
- Catering:Mobile and event-based foodservice requiring portable equipment with rapid setup and breakdown capabilities.
Volume concentration rests with Residential. Margin expansion is climbing the fastest in Hospitality.
Technology:
Connectivity protocols and energy certification grades are creating incompatible product stacks that fragment manufacturing scale.
- Smart Appliances:Wi-Fi-enabled refrigeration and app-controlled cooking systems with firmware-updatable functionality. Tech-forward renovators in Sydney and Melbourne specify these at accelerating rates, though interoperability fragmentation across proprietary platforms forces manufacturers to maintain multiple software stacks.
- Energy-Efficient:Products certified at 4-star and above under Australia's Equipment Energy Efficiency program, qualifying for state-level rebate programs. MEPS threshold escalations render older stock non-compliant, generating replacement demand.
- Traditional:Non-connected, baseline-efficiency equipment serving price-sensitive replacement demand and rental property specifications.
- Induction:Electromagnetic cooktops with precise temperature control and rapid response, gaining share as Victoria and New South Wales restrict new gas infrastructure connections.
Installed base dominance belongs to Traditional. Specification momentum is shifting most rapidly toward Smart Appliances.
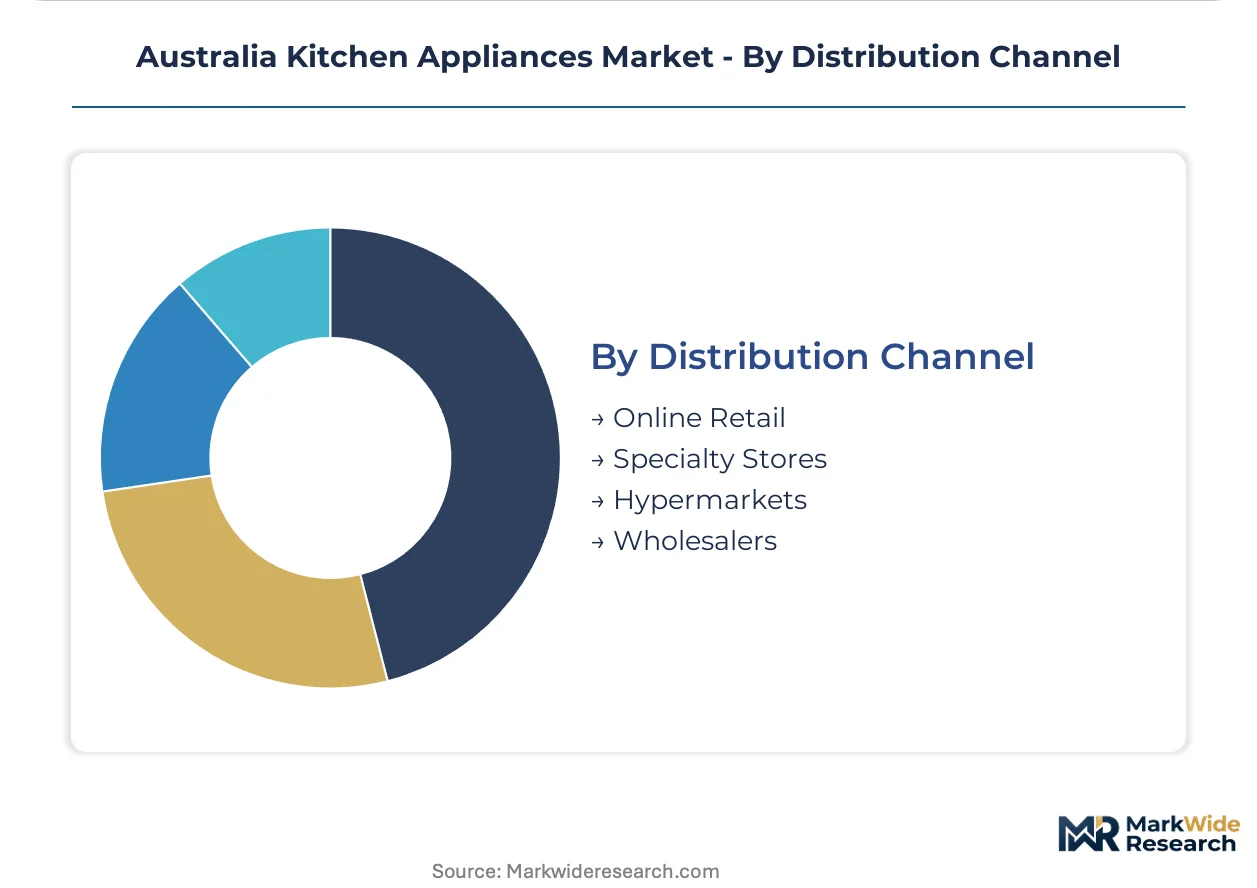
Distribution Channel:
Channel power is rotating toward builder-direct procurement in new construction, compressing retail shelf space for full-line manufacturers.
- Specialty Stores:Kitchen design studios and appliance showrooms with in-house specification consultants. High-consideration purchases in Melbourne and Sydney renovation corridors flow through this channel where design integration services justify premium positioning.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing replacement demand with price transparency and delivery logistics. Countertop appliances and compact formats migrate fastest to this channel.
- Hypermarkets:Big-box retailers with limited-range displays focused on volume SKUs and promotional pricing.
- Wholesalers:Trade-only distributors serving builder-specified projects and commercial hospitality procurement with project pricing and bulk logistics.
Transaction volume leadership sits with Specialty Stores. Channel share is expanding most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australian kitchen appliance demand through apartment densification corridors and renovation intensity unmatched elsewhere. State-level energy efficiency mandates and water rebate programs accelerate replacement cycles in these metros. Secondary state markets present expansion vectors as smart-appliance saturation lags.
New South Wales
Multi-dwelling construction in Sydney's middle-ring suburbs drives builder-specified procurement through direct manufacturer relationships. The state's appliance rebate schemes under Energy Switch and WELS compliance requirements filter retail placement eligibility. Parramatta and Western Sydney corridors concentrate compact-format dishwasher and cooktop demand from project home developers standardizing installations.
Victoria
Melbourne's inner-ring renovation pipeline favors 90cm built-in oven configurations with app-controlled functionality and pyrolytic self-cleaning cavities. The state's gas connection phase-out timeline for new residential construction redirects cooktop demand toward induction platforms. Electrification mandates from the Department of Environment, Energy and Climate Action compress product development cycles for compliant portfolio maintenance.
Queensland
Brisbane and Gold Coast household formation rates exceed Sydney-Melbourne saturation levels for smart-appliance penetration. The state's Building Codes Queensland energy efficiency provisions align with federal MEPS thresholds while allowing faster product registration timelines. Southeast Queensland's project home market consolidates refrigeration and dishwasher procurement through wholesale distributor networks serving volume builders.
Western Australia
Perth's resource-sector household income levels sustain premium-tier specification rates for connected refrigeration and precision cooking equipment. The state's Water Corporation rebate programs for WELS-rated dishwashers create price-advantaged positioning against traditional-efficiency stock. Northern corridor development and infill projects generate secondary-unit appliance purchases with shorter replacement cycles than eastern state averages.
South Australia
Adelaide's renovation market concentrates demand for energy-efficient refrigeration platforms qualifying for state-based Retailer Energy Productivity Scheme incentives. The South Australian government's appliance replacement programs target older stock for MEPS non-compliance retirement. Metropolitan infill and heritage district conversions specify compact-format equipment addressing spatial constraints without performance compromise.
Australia Kitchen Appliances Market Competitive Environment
Premium-margin players sit above commodity-margin players across connectivity integration, energy certification tiers, and design consultancy depth rather than manufacturing scale alone. The vendor base stratifies between full-line manufacturers maintaining refrigeration-to-cooktop portfolios and countertop specialists defending narrow technical advantages. Three archetypes dominate: European-engineered platform licensors, Asia-Pacific scale manufacturers, and domestic niche specialists with regional service density. Competitive moves concentrate on smart-home ecosystem partnerships and state-level rebate program compliance certification rather than price-led share capture.
Within the European-engineered tier, Electrolux and Bosch exemplify climate-adapted platform development and precision manufacturing heritage respectively. Fisher & Paykel anchors the trans-Tasman specialist position through drawer-based configuration differentiation. Breville Group occupies the countertop precision segment with barista-grade technical positioning against full-line competitors. These three represent divergent margin-defense strategies: platform breadth, format innovation, and category depth.
| Leading Market Players |
|---|
| LG Electronics |
| Electrolux |
| Kleenmaid |
| Whirlpool Corporation |
| Haier Group |
| Bosch |
| Samsung Electronics |
| Breville Group |
| Fisher & Paykel |
| Others |
Value Chain & Pricing Dynamics
Copper and steel futures volatility on the London Metal Exchange cascades through Australian appliance manufacturing, compressing margin buffers for mid-tier producers lacking long-term offtake agreements while amplifying pricing power for vertically integrated full-line manufacturers with captive component sourcing.
Pricing Analysis
Throughput-based value pricing anchors commercial hospitality procurement, where rapid-cook oven specifications tie contract value to meals-per-hour output and uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by MEPS certification grade and smart-connectivity bundling. Pricing pressure stems from raw material cost swings and concentrated retail gatekeeping. Residential replacement buyers exhibit highest price sensitivity, while hospitality operators prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Reverse-logistics flows for refrigerator compressor refurbishment and dishwasher component remanufacturing are gaining scale as MEPS non-compliance retirements accelerate replacement cycles. Manufacturing concentration rests on China, South Korea, and Thailand for compressor assemblies, electronic control modules, and precision motors. Supply chains draw from copper winding wire, cold-rolled steel, and refrigerant gas inputs. Single-source vulnerability in semiconductor-based inverter controllers creates procurement risk. Distribution runs through appliance retail chains, builder-direct procurement networks, and wholesale trade distributors serving project specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Australia's Equipment Energy Efficiency program and WELS labeling scheme erect barrier-to-entry moats favoring incumbents with certified product portfolios and regulatory affairs infrastructure.
For Market Incumbents: Deepen vertical control over compressor manufacturing and electronic control module sourcing to offset copper and steel input volatility. Accelerate firmware-updatable smart appliance platforms to defend against emerging Asian scale manufacturers with connectivity-enabled value propositions. Prioritize state-level rebate program pre-certification to lock in retail placement eligibility before MEPS threshold escalations render competing stock non-compliant. For New Entrants and Emerging Players: The mid-market price-point gap between Electrolux-Bosch premium positioning and Haier-Samsung volume tiers offers white-space entry vectors. Target Queensland and Western Australia secondary metro markets with lower smart-appliance saturation and faster household formation rates. Pursue builder-direct procurement relationships with project home developers standardizing appliance packages in Sydney's middle-ring suburbs. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic niche specialists with regional service density and drawer-based format differentiation in Melbourne and Sydney corridors. Long-term viability hinges on compliance certification infrastructure and smart-home ecosystem partnership depth. Monitor Equipment Energy Efficiency program revision announcements and state-level gas connection phase-out timelines as inflection signals for portfolio reallocation toward induction cooktop and connected refrigeration platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Ecosystem Partnership | Integration with Amazon Alexa and Google Home platforms expands addressable premium tier in Sydney-Melbourne renovation corridors. |
| MEPS Pre-Certification Investment | Early compliance with Equipment Energy Efficiency threshold escalations secures retail placement before competitor stock becomes non-compliant. |
| Builder-Direct Procurement Relationship | Direct manufacturer contracts with project home developers displace retail-channel selection in new apartment construction. |
| Compressor Backward Integration | In-house production of inverter-driven compressor systems buffers margin compression from copper and steel input volatility. |
| WELS Rebate Program Alignment | State-level water efficiency incentive qualification creates price-advantaged positioning for compliant dishwasher portfolios. |
Study Parameters
Independent corroboration across appliance manufacturer product managers, retail chain category buyers, and commercial hospitality procurement directors underwrites the qualitative findings in this study. Primary fieldwork engaged regulatory affairs specialists at Australia's Equipment Energy Efficiency program, project home development executives in Sydney and Melbourne, and aftermarket service network operators. Secondary validation drew from Australian Bureau of Statistics construction activity data, state government rebate program disclosures, and customs import records for compressor and electronic component trade flows. Bottom-up unit shipment estimates triangulated against top-down household formation and replacement cycle projections.
Rate-of-change decomposition across product type, end user, technology tier, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by base-year revenue contribution. Forecast inputs incorporated MEPS compliance threshold revision schedules, state-level gas connection phase-out timelines, and smart-appliance penetration curves in renovation versus new construction demand pools.
Inputs from regulatory filings and trade association disclosures were available through the study window; gaps in real-time builder procurement contract terms introduce uncertainty bands around project-channel volume estimates. Forecasts reflect documented assumptions regarding MEPS implementation timing and rebate program continuity. Practitioners should monitor Equipment Energy Efficiency program announcement cycles and state-level electrification mandate progressions for early signals of demand acceleration or portfolio obsolescence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Built-In Coffee Machine Market