
 Global Portable Blenders Market | 2026-2036
Global Portable Blenders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Blenders Market Outlook
Market Context
The gap between consumer-grade and professional-grade motor efficiency is narrowing as brushless DC motor architectures migrate downward from commercial kitchen equipment into handheld formats. BlendJet Inc. leverages direct-to-consumer channel control to sustain premium positioning against mass-market entrants. SharkNinja Operating LLC anchors its portfolio through hybrid designs that bridge countertop and portable use cases. Koninklijke Philips N.V. differentiates via appliance ecosystem integration, allowing its portable units to sync with broader kitchen connectivity platforms.
Technical Definition and Segment Structure
Global portable blenders are compact, battery-operated or USB-powered food processing devices typically housing motors between 50 and 300 watts within vessels ranging from 300 ml to 1 L capacity, designed for single-serve beverage and food preparation outside fixed kitchen installations. Rechargeable blenders now lead volume shipments as lithium-polymer cell costs compress, while USB blenders capture entry-tier demand through universal compatibility with existing consumer power banks and laptop ports. Health-conscious consumers represent the deepest margin pool among end-user segments, exhibiting lower price sensitivity and higher replacement frequency than student or professional cohorts.
Regulatory Environment
FDA food-contact material regulations in the United States, EU REACH restrictions on chemical migration from plastics, and China's GB standards for small appliance electrical safety collectively govern material selection, testing protocols, and market access documentation across the three largest demand centers. BPA-free material specifications have shifted from premium differentiation to baseline compliance requirement in most developed markets, forcing reformulation of legacy polycarbonate housings. Stakeholders must monitor evolving battery transportation regulations from IATA and national aviation authorities, as these rules directly constrain cross-border e-commerce fulfillment models that dominate portable blender distribution.
Market Dynamics
Brushless DC motor architectures are migrating from commercial kitchen equipment into handheld formats, compressing the efficiency gap between consumer-grade and professional-grade portable blenders while redrawing competitive boundaries across price tiers.
Growth Catalysts
- Fitness Enthusiast Demand:Urban commuting cultures in the United States, China, and Germany are creating concentrated cohorts seeking on-the-go nutrition solutions with minimal kitchen dependency.
- REACH Compliance Migration:EU restrictions on chemical migration from plastics have forced BPA-free material specifications from premium differentiation to baseline compliance, raising quality floors across export-oriented manufacturing.
- Lithium-Polymer Cost Compression:Rechargeable battery cell economics are displacing USB-powered entry-tier designs as the dominant volume format, extending single-charge blending cycles without weight penalties.
Market Restraints
- Aviation Transport Friction:IATA battery transportation regulations constrain cross-border e-commerce fulfillment models that dominate portable blender distribution, creating last-mile complexity for direct-to-consumer channels.
- Polycarbonate Reformulation Costs:Legacy housing materials face forced replacement under FDA food-contact material regulations and China's GB standards for small appliance electrical safety, elevating compliance expenditure for established product lines.
- Countertop Substitution Threat:Hybrid designs bridging fixed and portable use cases capture consumers who would otherwise purchase dedicated handheld units, compressing addressable market definition.
Strategic Opportunities
- Appliance Ecosystem Integration:Connectivity platform convergence with broader kitchen device networks creates white space for data-enabled nutrition tracking and automated replenishment services.
- Germany Health-Focused Retail:Underpenetrated pharmacy and wellness channel presence offers expansion potential beyond conventional electronics and housewares distribution.
- India Urban Commuter Segment:Emerging metro rail culture and protein-supplement adoption among office workers present first-mover positioning ahead of mass-market price point achievement.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, REACH, and GB standard compliance testing extends product launch windows and fragments quality assurance resource allocation.
- Brushless Motor IP Licensing:Patent thickets around high-efficiency motor control algorithms create royalty stacking and supplier negotiation complexity for brands without captive motor manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Blenders Market |
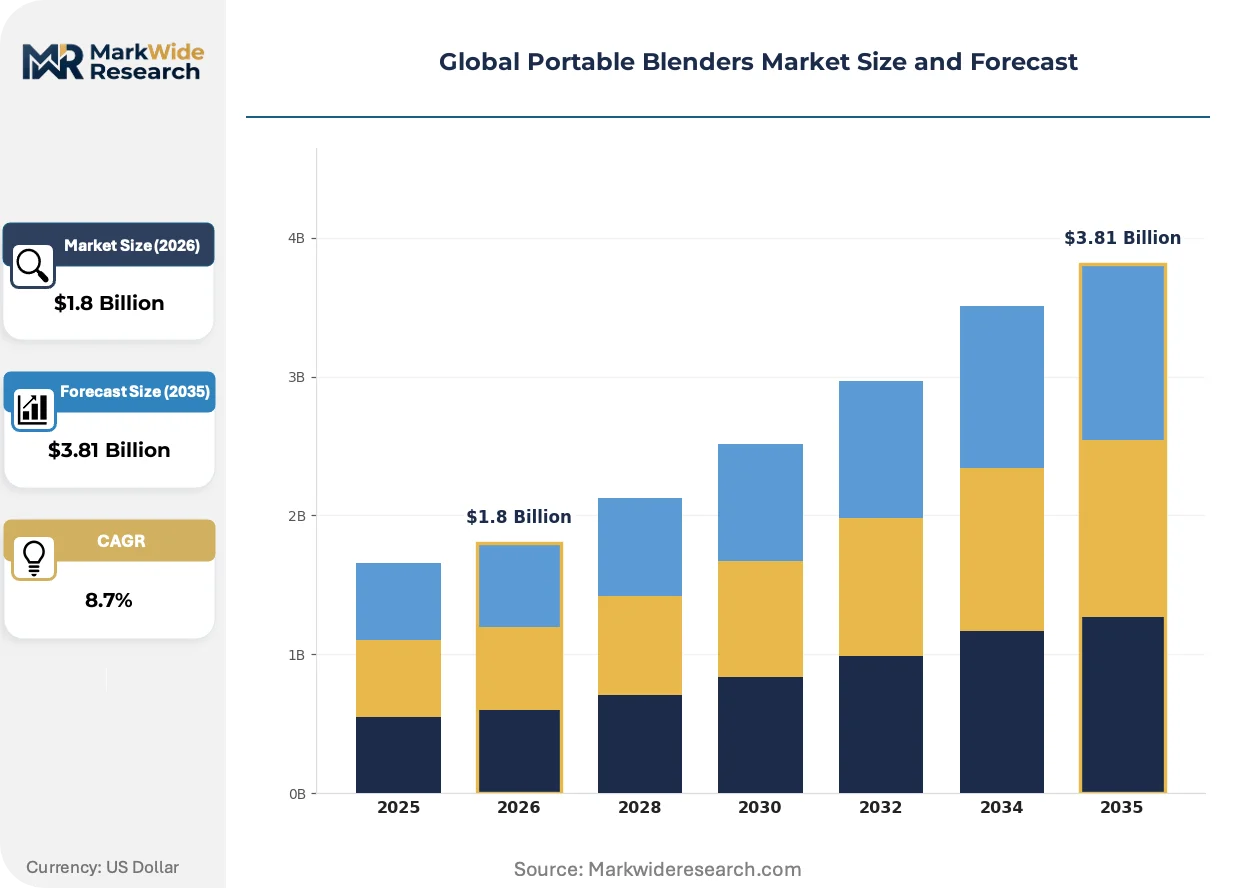
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Blenders, Rechargeable Blenders, USB Blenders, Personal Blenders End User: Fitness Enthusiasts, Students, Professionals, Health-Conscious Consumers Capacity: 300 ml, 500 ml, 750 ml, 1 L Material: Plastic, Stainless Steel, Glass, BPA-Free Material |
| Companies Covered | BlendJet Inc., NutriBullet LLC, SharkNinja Operating LLC, Hamilton Beach Brands Holding Company, Conair Corporation (Cuisinart), Koninklijke Philips N.V., Robert Bosch GmbH, Xiaomi Corporation, Bella Housewares, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Blenders Market Strategic Shifts
Product architecture is converging around dual-use flexibility, regulatory material compliance, and channel-specific fulfillment optimization as the three active reshaping forces in portable blender development.
Magnetic induction charging systems are replacing exposed USB ports in premium portable blender designs, eliminating water ingress failure modes and enabling full submersible cleaning. Health-conscious consumer segments are adopting these sealed-unit formats fastest, accepting price premiums for durability assurance. The technology is hybridizing power delivery standards from electric toothbrush and wearable device ecosystems, compressing development timelines through component reuse.
EU REACH restrictions on chemical migration continue tightening permitted thresholds for plastic food-contact materials, forcing iterative reformulation of polycarbonate and Tritan alternatives. Industrial consequence includes accelerated supplier qualification cycles and elevated raw material testing expenditure. German and French health retailers are responding fastest, demanding third-party migration test documentation as a listing prerequisite.
Subscription-based consumable bundling is displacing standalone hardware transactions in direct-to-consumer channels, locking replacement cycles to personalized nutrition program adherence. Fitness influencers and registered dietitian partnerships are replacing traditional retail discovery for millennial and Gen-Z buyer cohorts. This pattern is most visible in United States urban markets where gym culture and meal-replacement routine adoption overlap most densely.
Global Portable Blenders Market Segmentation
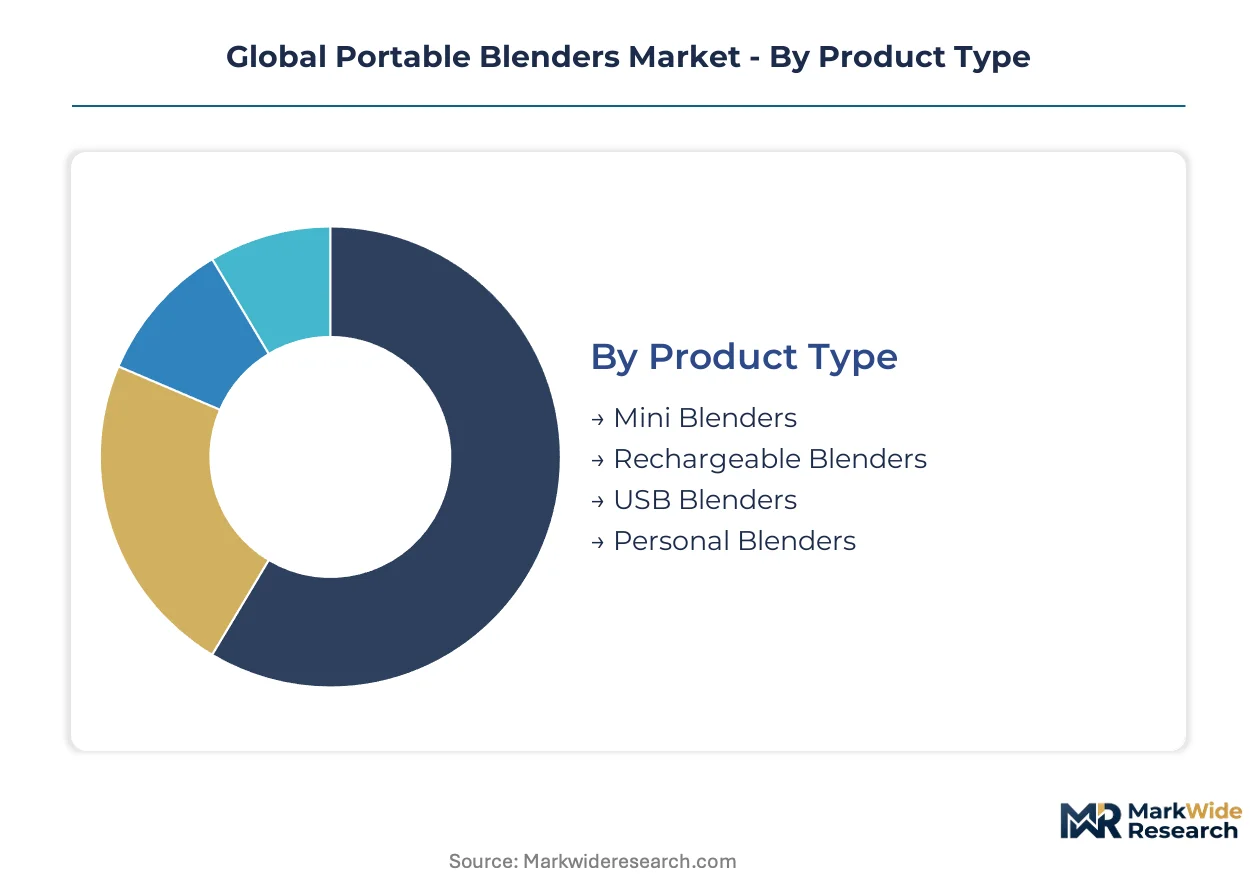
Portable blender segmentation reveals how battery chemistry, material compliance, and user lifestyle intersect to create distinct margin pools. Manufacturers configure product lines across four primary dimensions, each carrying different regulatory burdens and channel economics.
Product Type:
Use-case spectrum spans corded convenience to untethered mobility, with power architecture determining price tier and replacement cadence.
- Rechargeable Blenders:Lithium-polymer cells now dominate volume shipments as energy density improvements extend single-charge cycles without weight penalties. Demand concentrates among fitness enthusiasts in the United States and Germany where gym-to-office commuting patterns reward cordless operation.
- USB Blenders:Universal compatibility with existing power banks and laptop ports anchors entry-tier positioning. Student cohorts in China represent the deepest adoption pool, prioritizing dorm-room convenience over motor performance.
- Mini Blenders:Compact 50-100 watt motors serve single-serve beverage preparation with minimal kitchen footprint. Travel-focused consumers favor these for hotel and Airbnb use cases.
- Personal Blenders:Larger vessel capacities bridge portable and countertop functionality. Health-conscious consumers exhibit highest replacement frequency in this configuration.
Established volume favors rechargeable architectures; emerging adoption favors USB-powered entry designs in price-sensitive developing markets.
End User:
Customer type segmentation maps directly to margin structure, with health motivation correlating to reduced price sensitivity and faster upgrade cycles.
- Health-Conscious Consumers:Registered dietitian endorsements and personalized nutrition tracking drive premium willingness. Replacement frequency runs highest among this cohort as new magnetic induction and sealed-unit formats enter the market.
- Fitness Enthusiasts:Protein supplement integration and post-workout smoothie routines create ritualized usage patterns. United States urban markets show concentrated demand where gym culture and meal-replacement adoption overlap.
- Students:Dormitory restrictions on fixed appliances and limited kitchen access elevate portable relevance. Price sensitivity compresses margins but creates high-volume entry-tier demand.
- Professionals:Office-based consumption and commuter rail usage patterns favor discreet, leak-proof designs. Germany's pharmacy and wellness channels show underpenetrated potential for this segment.
Margin concentration sits with health-motivated buyers; volume expansion depends on professional and student cohorts.
Capacity:
Vessel sizing reflects consumption occasion segmentation from single-serve supplements to shared meal preparation.
- 500 ml:Optimal protein shake and meal-replacement volume aligns with fitness supplement serving sizes. This specification captures the largest addressable use case across all end-user types.
- 300 ml:Espresso-shot and supplement-pre-workout formats suit minimalist commuters. Japan's compact living spaces and bento culture favor this smaller footprint.
- 750 ml:Dual-serve capacity accommodates couples and small households without fixed blender investment. Weekend brunch preparation represents the primary use case.
- 1 L:Family-size and batch-preparation formats blur portable and countertop boundaries. Meal-prep enthusiasts and small-catering applications drive niche demand.
500 ml specifications anchor mainstream production; 300 ml formats gain share fastest in urban density markets.
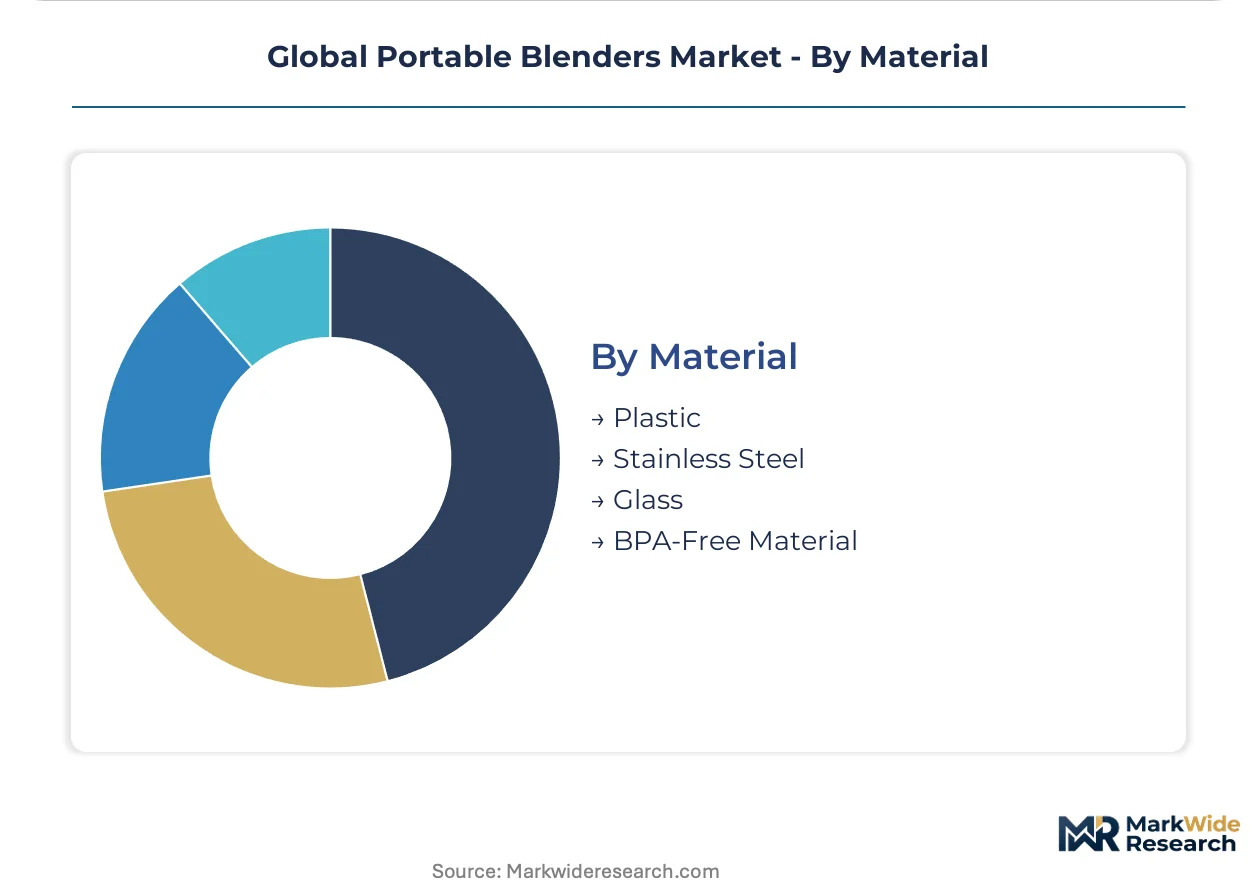
Material:
Regulatory migration across FDA, EU REACH, and China's GB standards has redefined material selection from cost-driven to compliance-mandatory.
- BPA-Free Material:Tritan copolyester and alternative polycarbonate formulations have shifted from premium differentiation to baseline market access requirement. EU REACH tightening on chemical migration thresholds forces iterative supplier qualification.
- Stainless Steel:Thermal retention and durability position these units for outdoor and commercial use cases. Higher unit economics limit penetration to premium tiers.
- Glass:Purity perception and dishwasher compatibility attract health-focused buyers despite weight penalties. Breakage risk constrains true portable applications.
- Plastic:Legacy polycarbonate housings face forced reformulation under FDA food-contact regulations, elevating compliance costs for established product lines.
BPA-free specifications now govern mass-market access; stainless steel and glass retain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and urban commuters concentrate demand in the United States, China, and Germany, where health-focused retail ecosystems and dense transit corridors overlap most completely.
United States
Gym-to-office commuting patterns in New York, Los Angeles, and Chicago drive cordless rechargeable blender adoption among protein-supplement users. FDA food-contact material regulations govern BPA-free housing requirements, forcing polycarbonate reformulation for import compliance. Austin and Miami wellness startup clusters incubate direct-to-consumer brands targeting influencer-driven discovery channels.
Germany
Pharmacy and wellness retail channels in Berlin, Munich, and Hamburg show underpenetrated potential for professional commuter segments. EU REACH restrictions on chemical migration from plastics mandate third-party testing documentation as a listing prerequisite. The Rhine-Ruhr industrial corridor hosts precision motor component suppliers serving brushless DC architecture migration.
China
Student dormitory restrictions and metro rail expansion in Beijing, Shanghai, and Shenzhen elevate USB-powered entry-tier demand. GB standards for small appliance electrical safety govern domestic market access and export certification reciprocity. The Pearl River Delta manufacturing cluster dominates lithium-polymer cell integration and compact motor assembly.
India
Emerging protein-supplement adoption among Mumbai, Bangalore, and Delhi office workers presents first-mover positioning ahead of mass-market price achievement. BIS certification requirements for electronic goods create compliance barriers for unorganized import channels. The National Capital Region logistics hub concentrates cross-border e-commerce fulfillment infrastructure.
Japan
Compact living spaces and bento culture in Tokyo, Osaka, and Yokohama favor 300 ml minimalist formats for single-serve preparation. METI energy efficiency standards influence motor specification requirements for domestic retail placement. The Kanto region appliance distribution network prioritizes sealed-unit durability for frequent commuter rail usage.
Global Portable Blenders Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered price bands, creating a structure where direct-to-consumer brands extract premium margins while mass-market manufacturers defend volume through retail distribution scale. The vendor base organizes around three archetypes: ecosystem-integrated appliance conglomerates, motor-technology specialists, and digitally native vertical brands. Dominant competitive moves include hybrid design development bridging portable and countertop use cases, and magnetic induction charging system adoption eliminating water ingress failure modes.
Within the ecosystem-integrated tier, Koninklijke Philips N.V. and SharkNinja Operating LLC exemplify platform convergence strategies, while BlendJet Inc. occupies a position as the digitally native archetype leveraging channel control for premium positioning. Robert Bosch GmbH anchors the engineering-driven segment with precision motor heritage, and Xiaomi Corporation represents scale-first manufacturing efficiency from Chinese supply chain integration.
| Leading Market Players |
|---|
| BlendJet Inc. |
| NutriBullet LLC |
| SharkNinja Operating LLC |
| Hamilton Beach Brands Holding Company |
| Conair Corporation (Cuisinart) |
| Koninklijke Philips N.V. |
| Robert Bosch GmbH |
| Xiaomi Corporation |
| Bella Housewares |
| Others |
Value Chain & Pricing Dynamics
IATA battery transportation regulations create dual exposure for portable blender manufacturers, compressing margin spreads between premium sealed-unit designs and entry-tier USB formats while forcing supply chain fragmentation across air-freight-compliant and ground-shipment channels.
Pricing Analysis
Cost-plus contracts with lithium-polymer cell indexation dominate rechargeable blender procurement, locking raw material volatility into tiered pricing structures. Price differentiation separates magnetic induction premium formats from exposed-port economy designs, with certification tier serving as the secondary wedge. Cost compression in the USB-powered entry segment is intensifying as Chinese dormitory demand saturates. Students exhibit highest price sensitivity; health-conscious buyers show lowest elasticity, accepting premiums for BPA-free Tritan housings and sealed-unit durability.
Supply Chain Analysis
Upstream feedstock concentration in Chinese lithium-polymer cell manufacturing, Japanese precision motor components, and German brushless DC control systems defines input dependencies. The supply chain draws from Pearl River Delta assembly clusters, Rhine-Ruhr precision engineering corridors, and South Korean battery chemistry specialists. Single-source vulnerability sits with aviation-compliant battery pack certification, where IATA testing bottlenecks constrain cross-border e-commerce throughput. Distribution runs through direct-to-consumer fulfillment centers, pharmacy wellness channels, and mass-market electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable blender market sits in a cyclical recovery phase driven by lithium-ion energy density improvements that refresh replacement cycles and expand cordless use cases.
For Market Incumbents: Insulate margin position by deepening captive supply of brushless DC motor control algorithms, reducing royalty stacking exposure from patent thickets. Accelerate BPA-free material certification investment ahead of EU REACH threshold tightening, converting compliance cost into competitor exclusion. Hybrid design development bridges portable and countertop substitution threats. For New Entrants and Emerging Players: India's urban commuter rail corridors represent the most penetrable entry point, where protein-supplement adoption among office workers precedes mass-market price achievement. Germany's pharmacy and wellness channels offer white-space expansion beyond conventional electronics distribution. Influencer-partnership discovery models bypass incumbent retail shelf control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ecosystem-integrated appliance conglomerates with kitchen connectivity platform assets. Long-term viability rests on data-enabled nutrition tracking and automated consumable replenishment service attachment. Monitor magnetic induction charging patent filings as inflection signal for premium tier technology lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Induction Charging Adoption | Eliminates water ingress failure modes for sealed-unit premium positioning. |
| Appliance Ecosystem Integration | Enables Philips and SharkNinja kitchen platform convergence with nutrition tracking. |
| Direct-to-Consumer Channel Control | BlendJet's influencer-driven discovery bypasses retail margin extraction. |
| BPA-Free Material Reformulation | EU REACH compliance migration converts cost burden into market access barrier. |
| Hybrid Portable-Countertop Design Development | Captures consumers who would otherwise purchase dedicated handheld units. |
Study Parameters
Initial hypotheses were tested against primary input from portable blender brand managers, lithium-polymer cell procurement leads, pharmacy retail category buyers, and fitness influencer partnership coordinators, then refined against secondary validation from FDA food-contact material filings, EU REACH migration test databases, IATA battery transport regulations, and Chinese GB standard certification records. Bottom-up shipment estimates from manufacturing clusters triangulated against top-down retail audit data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value through product type, end-user motivation, vessel capacity tier, and material compliance grade dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic elasticity assumptions. Forecast inputs incorporated lithium-polymer cost compression curves and aviation transport regulatory evolution.
Practitioners should monitor IATA battery rule amendments, EU REACH threshold reductions, and brushless motor patent expiration schedules for early signals of forecast revision. Cross-checking against customs trade data for lithium-polymer cell import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market