
 South America Herbicide Market | 2026-2036
South America Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
South America Herbicide Market Insights
Market Dynamics
The South America herbicide market is consolidating around a widening split between premium formulated products and commodity generic molecules. Syngenta Group leverages its proprietary active ingredient pipeline to sustain pricing power in the premium tier, while UPL Ltd anchors its position through backward integration into generic technical manufacturing. Corteva Agriscience differentiates via seed-trait-herbicide bundling, competing directly with Bayer AG's Roundup Ready system dominance in soybean belts.
Product Landscape
Herbicides are chemical or biological agents designed to control or eliminate unwanted vegetation, typically formulated as emulsifiable concentrates or water-dispersible granules containing active ingredients such as glyphosate, 2,4-D, or atrazine, and applied to protect crop yields by suppressing weed competition for nutrients, water, and sunlight. Post-emergent formulations lead volume sales across the region's extensive soybean and corn rotations, while selective herbicides command margin premiums in specialty fruit and vegetable segments where crop safety thresholds are narrow. Liquid formulations dominate commercial application channels, though dry flowable products are gaining traction among aerial spraying contractors seeking reduced drift profiles and easier tank-mix logistics.
Regulatory Environment
ANVISA in Brazil and SENASA in Argentina enforce residue tolerance standards that directly determine which active ingredients gain market access, while the EU Green Deal's Farm to Fork strategy exerts indirect pressure through export-oriented compliance requirements for South American grain and oilseed shipments. Brazil's national pesticide law revision and escalating state-level buffer zone restrictions in Mato Grosso and Rio Grande do Sul are forcing reformulation investments and label adjustments across the supply chain. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and individual country re-registration timelines to anticipate portfolio exposure and reposition active ingredient mixes accordingly.
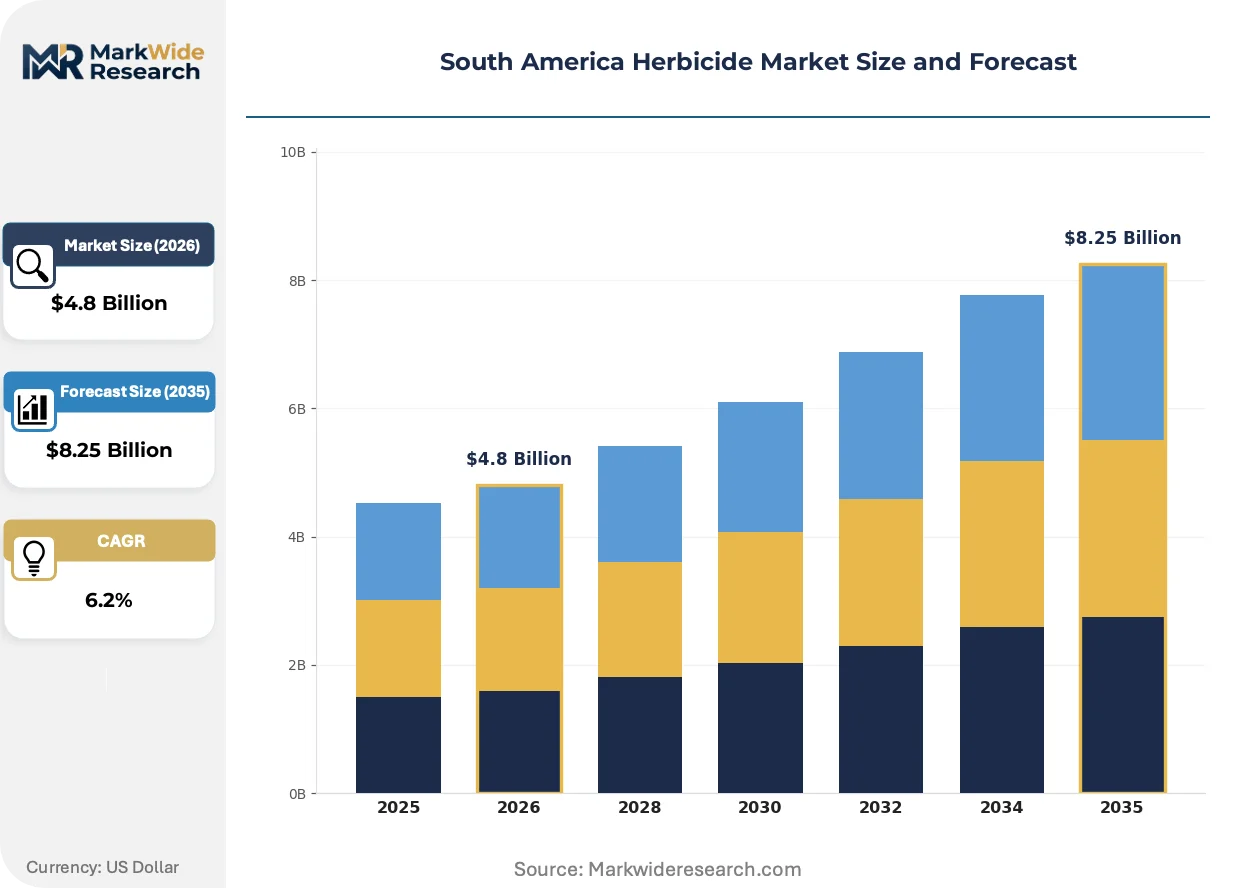
Market Dynamics
ANVISA's glyphosate re-evaluation protocols and escalating state-level buffer zone mandates in Mato Grosso are compressing product registration timelines and forcing wholesale reformulation investments across the Brazilian supply chain. This regulatory pressure is the dominant structural force reshaping competitive positioning.
Growth Catalysts
- No-till farming expansion:Brazil's Cerrado region continues converting millions of hectares to conservation tillage systems that depend on post-emergent herbicide applications for weed management.
- Herbicide-tolerant seed adoption:Soybean and corn rotations incorporating proprietary trait stacks drive bundled chemical procurement across commercial farming operations in Argentina's Pampas.
- Mercosur harmonization efforts:Regional regulatory alignment initiatives are streamlining cross-border product registrations and reducing duplicative compliance costs for active ingredient approvals.
Market Restraints
- Active ingredient supply concentration:Chinese technical-grade manufacturing dominates upstream glyphosate and 2,4-D production, exposing formulators to input cost volatility and geopolitical disruption risk.
- Residue tolerance compression:ANVISA's downward revisions of maximum residue limits for key molecules are disqualifying legacy formulations from premium export channels serving EU buyers.
- Biological substitute emergence:Microbial bioherbicide candidates from Argentine research institutes threaten niche displacement in organic-certified fruit and vegetable segments.
Strategic Opportunities
- Paraguay's underpenetrated commercial sector:Smallholder transition to mechanized farming in the Eastern Region creates first-mover positioning for selective herbicide portfolios.
- Drone-based aerial application:Regulatory clearance for unmanned aerial vehicle spraying in Brazil's Mato Grosso do Sul enables precision variable-rate delivery and reduced buffer zone compliance costs.
- Seed-trait-chemical convergence:Stacking proprietary genetics with tailored chemistries creates captive demand cycles and defensible margin structures in soybean belts.
Industry Challenges
- Formulation chemistry expertise scarcity:Brazil's universities produce insufficient industrial chemists trained in surfactant science and drift-reduction technology.
- Label expansion timeline compression:ANVISA's expedited re-registration reviews demand accelerated toxicology dossier preparation without corresponding budget increases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Herbicide Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-emergent, Post-emergent, Selective, Non-selective Crop Type: Cereal, Oilseed, Fruits, Vegetables Formulation: Liquid, Granular, Dry Flowable, Water-soluble Application Method: Ground, Aerial, Chemigation, Hand-held |
| Companies Covered | Syngenta Group, Corteva Agriscience, BASF SE, Bayer AG, UPL Ltd, FMC Corporation, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co Ltd, American Vanguard Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Herbicide Market Trends and Innovations
Digital agriculture platforms and precision application hardware are converging with novel formulation chemistry to reshape how herbicides are selected, dosed, and validated in the field. This integration is compressing the feedback loop between application and agronomic outcome.
RNA interference-based bioherbicides targeting specific weed genotypes are electrifying research pipelines across Brazilian agricultural universities and private biotechnology laboratories. Large-scale soybean cooperatives in Rio Grande do Sul are piloting these molecules in controlled field trials. The technology is electrifying competitive positioning by threatening to bypass conventional chemical resistance management cycles entirely.
ANVISA's implementation of electronic pesticide prescription systems mandates digital documentation of every herbicide application across commercial farms. This policy forces investments in farm management software and traceability infrastructure. Mato Grosso's large-scale operators face the steepest compliance curve as they retrofit legacy spraying equipment with GPS-logging capabilities.
Cooperative procurement consortia are consolidating input purchasing power across Brazil's southern soybean belt. These buyer aggregations displace traditional distributor relationships with direct manufacturer negotiations and volume-based contracting. The pattern is most visible in Paraná's northern municipalities where farmer cooperatives command multi-year supply agreements.
South America Herbicide Market Segmentation
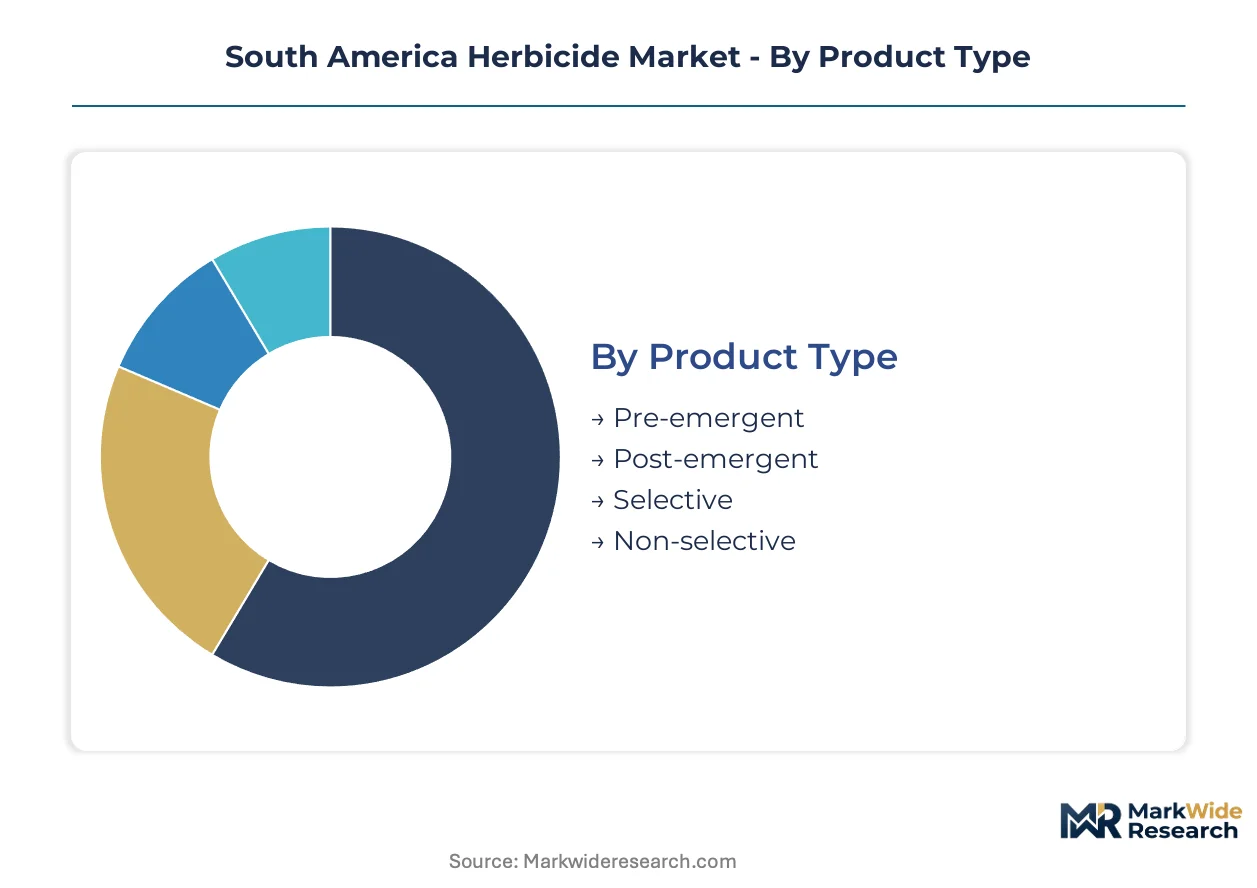
Herbicide procurement patterns across South America diverge sharply between commodity soybean operations and high-value specialty cropping systems. Understanding these segment boundaries clarifies where formulation investments concentrate versus where generic substitution pressures dominate.
Product Type:
The customization-to-standardization spectrum spans from bespoke selective chemistries for narrow crop safety windows to mass-market non-selective molecules engineered for cost efficiency at scale.
- Pre-emergent:Soil-applied formulations containing active ingredients like metolachlor or dinitroanilines create residual weed control barriers before crop emergence. Demand clusters in Brazil's Mato Grosso corn-soybean rotations where early-season weed suppression determines yield outcomes.
- Post-emergent:Foliar-active herbicides including glyphosate and 2,4-D formulations dominate commercial volumes across the Cerrado's no-till systems. ANVISA's residue tolerance compression is disqualifying legacy molecules from EU-bound export channels.
- Selective:Crop-safe chemistries target grassy or broadleaf weeds without harming cultivated plants. Narrow application windows in Argentina's Pampas vegetable belts sustain premium pricing.
- Non-selective:Total vegetation control agents serve pre-plant burndown and industrial right-of-way applications. Commodity pricing pressure intensifies as Chinese technical supply concentrates.
Leading the category by volume: Post-emergent. Expanding most quickly: Selective.
Crop Type:
Margin structures invert across this dimension — broad-acre commodities trade volume for thin returns while intensive horticulture sustains formulation premiums.
- Cereal:Wheat and corn rotations in Rio Grande do Sul depend on triazine and ALS-inhibitor chemistries for grass weed management. Resistance evolution in ryegrass populations is accelerating product rotation requirements.
- Oilseed:Soybean cultivation across Brazil's Cerrado and Argentina's Pampas drives glyphosate-tolerant trait adoption. Herbicide-tolerant seed bundles lock in chemical procurement cycles.
- Fruits:Citrus orchards in São Paulo state and grape vineyards in Mendoza demand specialized selective formulations with narrow phytotoxicity profiles. Residue compliance for export markets dictates product selection.
- Vegetables:High-value tomato and pepper operations in Minas Gerais prioritize crop safety margins over per-hectare chemical cost. Biological substitute emergence threatens niche displacement in organic-certified segments.
Climbing the fastest: Oilseed. Dominating procurement volumes: Cereal.
Formulation:
Physical form determines application infrastructure compatibility and drift liability exposure across South America's diverse farming scales.
- Liquid:Emulsifiable concentrates and suspension concentrates dominate commercial spraying operations. Tank-mix flexibility and rapid field coverage sustain preference among Mato Grosso's large-scale operators.
- Granular:Dry dispersible granules reduce packaging weight and storage footprint for remote farming cooperatives. Handling safety advantages offset slower dissolution kinetics.
- Dry Flowable:Water-dispersible granule formats gain traction among aerial spraying contractors seeking reduced drift profiles. Paraná's northern municipalities show fastest uptake.
- Water-soluble:Powder formulations dissolve completely without emulsification steps. Smallholder adoption concentrates in Paraguay's Eastern Region transition zones.
Volume leadership: Liquid. Steepest expansion trajectory: Dry Flowable.
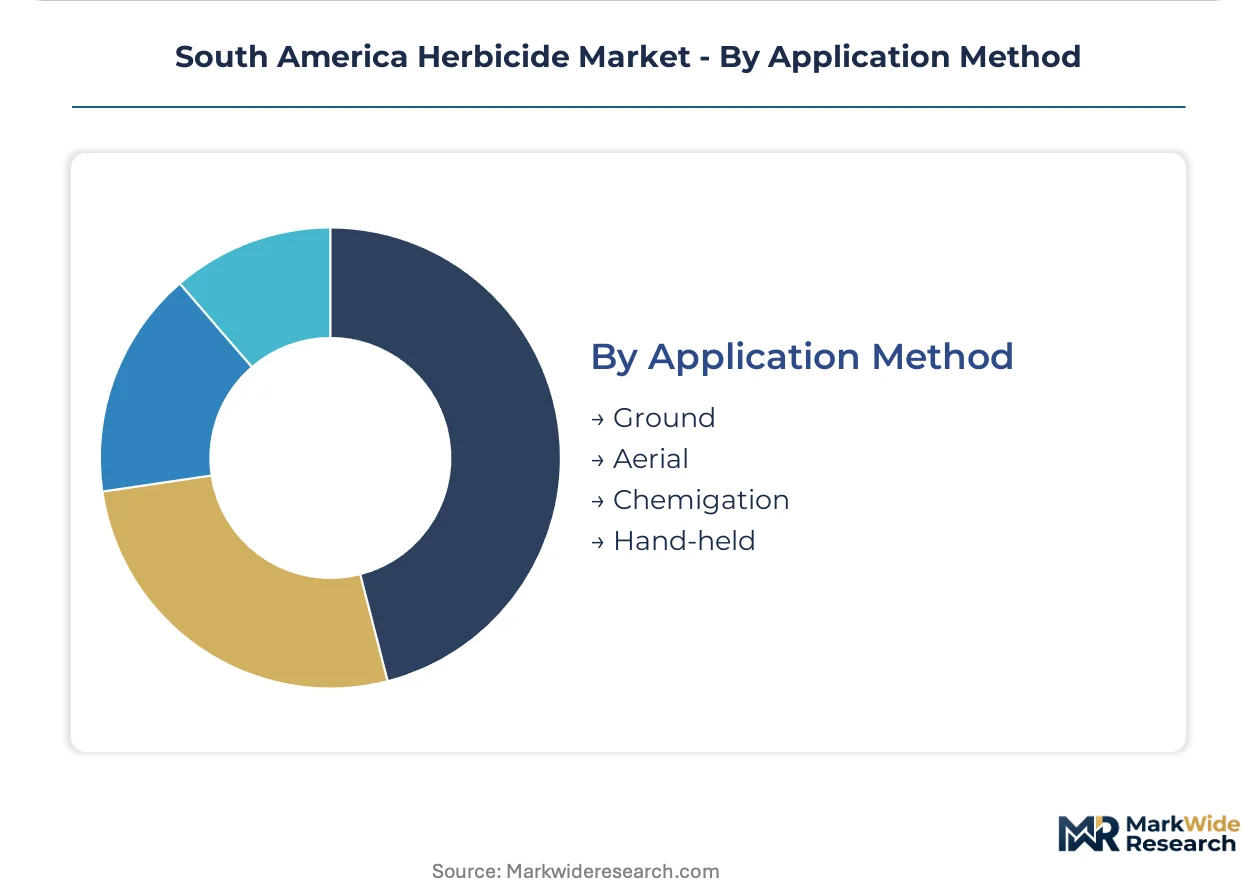
Application Method:
Equipment intensity and labor availability shape method selection from precision agriculture zones to smallholder peripheries.
- Ground:Tractor-mounted boom sprayers remain standard across Brazil's consolidated farms. GPS-guided variable-rate systems retrofitting legacy equipment respond to ANVISA's electronic prescription mandates.
- Aerial:Fixed-wing and rotary aircraft cover vast Cerrado expanses during narrow application windows. Drone-based platforms in Mato Grosso do Sul enable reduced buffer zone compliance.
- Chemigation:Herbicide injection through irrigation systems integrates weed control with water delivery. Center-pivot installations in Argentina's Santa Fe province pilot adoption.
- Hand-held:Backpack sprayers persist in Paraguay's smallholder transition zones and steep vineyard terrain. Labor cost escalation limits expansion.
Commanding volume: Ground. Gaining share fastest: Aerial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's citrus belt and the Ribeirão Preto agro-industrial corridor anchor South American herbicide formulation and distribution infrastructure, with port access to Santos facilitating export-oriented chemical logistics.
Brazil
Mato Grosso's no-till soybean expansion and Paraná's cooperative procurement consortia drive post-emergent herbicide volumes. ANVISA's electronic prescription mandates and glyphosate re-evaluation protocols compress registration timelines. São Paulo state's citrus orchards sustain selective formulation premiums for export-compliant residue management.
Argentina
Pampas grain rotations and herbicide-tolerant seed bundles lock in chemical procurement cycles across Buenos Aires and Córdoba provinces. SENASA enforces residue tolerance standards that determine EU export market access. Mendoza's high-altitude vineyards command narrow-phytotoxicity selective herbicides for premium wine grape protection.
Paraguay
Eastern Region smallholder transition to mechanized farming creates first-mover positioning for selective herbicide portfolios in Caaguazú and Alto Paraná departments. The country's agricultural ministry streamlines import registration for formulated products. Asunción-based distributors are consolidating logistics networks for cross-border supply into Brazil's southern border states.
Chile
Central Valley fruit exports and wine production sustain specialty formulation demand in O'Higgins and Maule regions. The national agricultural service enforces maximum residue limits aligned with EU and US export requirements. Santiago's formulation tolling facilities serve as regional technical manufacturing hubs for Andean markets.
Colombia
Altillanura oil palm and rice expansion in Meta and Casanare departments drives non-selective burndown applications. The national pesticide committee reviews active ingredient registrations under harmonized Andean community protocols. Bogotá-based agronomic service providers are deploying drone-based aerial application platforms for reduced buffer zone compliance.
South America Herbicide Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the proprietary-pipeline versus generic-technical manufacturing divide. The market structure consolidates around three tiers: integrated seed-trait-chemical bundlers, backward-integrated generic technical manufacturers, and regional formulation specialists. Dominant competitive moves include portfolio diversification into biological substitutes and geographic expansion through cooperative procurement direct agreements.
Within the integrated bundler tier, Syngenta Group and Corteva Agriscience exemplify proprietary active ingredient pipelines combined with seed trait platforms. Bayer AG anchors the glyphosate-tolerant system dominance referenced throughout regional soybean belts. UPL Ltd occupies a position representing backward integration into generic technical manufacturing and volume-based commodity supply.
| Leading Market Players |
|---|
| Syngenta Group |
| Corteva Agriscience |
| BASF SE |
| Bayer AG |
| UPL Ltd |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co Ltd |
| American Vanguard Corporation |
| Others |
Pricing and Supply Chain Analysis
Chinese technical-grade glyphosate and 2,4-D manufacturing feed cost volatility through Brazilian formulators into three-tier pricing stratification across premium proprietary, standard branded, and economy generic tiers. ANVISA's residue tolerance compression and state-level buffer zone mandates force reformulation investments that concentrate margin pressure on mid-tier suppliers lacking backward integration into active ingredient production.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for herbicide-tolerant seed bundles in Mato Grosso's no-till soybean operations. Three-tier pricing structure across premium, standard, and economy levels separates Syngenta's proprietary molecule portfolios from UPL's generic technical supply and regional formulators. Cost compression in the economy tier intensifies as Chinese manufacturers concentrate technical-grade output. Smallholder operators in Paraguay's Eastern Region exhibit highest price sensitivity, while export-oriented citrus growers in São Paulo sustain premium tolerance for residue-compliant selective formulations.
Supply Chain Analysis
Freight cost escalation from Chinese ports through Santos and Paranaguá elevates landed costs for technical-grade inputs. Supply concentrates in China for glyphosate and 2,4-D technical, India for intermediate synthesis, and Brazil for terminal formulation. Raw material dependencies include petroleum-derived surfactants, phosphate-based precursors, and packaging resins. Single-source vulnerability in Chinese technical manufacturing exposes formulators to geopolitical disruption. Distribution runs through São Paulo-based distributors, cooperative procurement consortia in Paraná, and direct manufacturer agreements with Mato Grosso large-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America herbicide market is becoming a vertical-integration race where control over technical-grade manufacturing and seed-trait pipelines determines margin capture. Players are pursuing backward integration into Chinese and Indian technical supply as the decisive upstream lever.
For Market Incumbents: Extend proprietary active ingredient pipelines through accelerated toxicology dossier preparation for ANVISA's expedited re-registration reviews. Deepen captive supply of technical-grade inputs to offset Chinese manufacturing concentration risk. Defend against biological substitute emergence from Argentine research institutes by locking in multi-year supply agreements with Rio Grande do Sul cooperatives piloting RNA interference technologies. For New Entrants and Emerging Players: Launch via drone-based aerial application service models in Mato Grosso do Sul where regulatory clearance enables reduced buffer zone compliance costs. Target Paraguay's Eastern Region smallholder transition zones with water-soluble powder formulations suited to mechanizing operations. Penetrate through agronomic advisory bundling that displaces traditional distributor relationships in Caaguazú and Alto Paraná departments. For Investors and Strategic Acquirers: ANVISA's implementation of electronic pesticide prescription systems is the leading indicator that farm management software and traceability infrastructure investments will separate viable targets from stranded assets. Frame long-term viability around consolidation of formulation chemistry expertise scarcity in Brazilian universities. Prioritize acquisition targets with proprietary surfactant science capabilities and drift-reduction technology portfolios. Watch for cooperative procurement consortia in Paraná's northern municipalities commanding multi-year supply agreements as the signal of distributor displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Manufacturing | Captive supply of Chinese and Indian glyphosate technical insulates formulators from input cost volatility. |
| Seed-Trait-Chemical Bundle Expansion | Proprietary genetics stacking with tailored chemistries locks in demand cycles across Cerrado soybean belts. |
| Drone-Based Aerial Application Platform | Regulatory clearance in Mato Grosso do Sul enables precision variable-rate delivery and compliance cost reduction. |
| Electronic Prescription System Compliance | GPS-logging retrofit investments respond to ANVISA mandates and create switching costs for large-scale operators. |
| Biological Substitute Pipeline Development | Microbial bioherbicide candidates from Argentine research institutes threaten niche displacement in organic-certified segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with agronomic service providers, formulation plant managers, cooperative procurement officers, and ANVISA regulatory affairs specialists combined with secondary validation from ANDA industry reports, ANVISA registration databases, and Brazilian customs export records. Bottom-up triangulation across product-level volume estimates and top-down reconciliation against national agricultural census data established market sizing integrity.
Data-stream reconciliation across the projection horizon employed segmented growth modeling. Segmentation dimensions included product type, crop application, formulation technology, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for ANVISA re-registration timeline compression and no-till farming expansion rates. Industry-specific forecast inputs incorporated herbicide-tolerant seed adoption curves and cooperative procurement consolidation patterns.
ANVISA regulatory reversal, Chinese technical supply disruption, and biological substitute efficacy breakthrough are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about Mercosur harmonization progress and residue tolerance compression trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market