
 Indoor Vertical Farm Safe Crop Protection Chemistry Market | 2026-2036
Indoor Vertical Farm Safe Crop Protection Chemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Vertical Farm Safe Crop Protection Chemistry Market Insights
Specialty crop producers is reorganizing procurement priorities around residue-free chemistry, displacing conventional greenhouse operators as the dominant buyer archetype in safe crop protection. Koppert leverages its biological control agent portfolio to dominate European supply channels for vertical farm operators. Bayer sustains R&D intensity in microbial formulation science, while BioWorks anchors North American distribution through grower-direct technical service networks.
Indoor vertical farm safe crop protection chemistry encompasses biological and reduced-risk synthetic formulations engineered for zero-residue performance in controlled-environment agriculture, typically requiring pH stability between 5.5 and 6.5 and compatibility with recirculating hydroponic systems. These chemistries prevent crop loss from fungal pathogens, arthropod pests, and microbial contamination without accumulating in closed-loop irrigation. Biofungicides occupy the deepest margin pools due to recurring application cycles in high-humidity vertical environments, while nanotechnology-enabled formulations represent the fastest-growing technology segment as carriers improve active ingredient precision. Encapsulation technology leads current adoption among large-scale vertical farms seeking labor-efficient application intervals.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act shape product entry timelines, while EU REACH compliance and the impending F-Gas Regulation restrict certain synthetic biocide categories in European vertical farm supply chains. Organic certification standards from USDA and private bodies such as CCOF further filter permissible chemistries, creating dual-track formulation development. Stakeholders must monitor evolving residue thresholds for novel biological actives as regulatory divergence between North American and European frameworks intensifies compliance complexity.
Market Dynamics
Maximum residue limit compression by EPA and EFSA is forcing specialty crop producers to requalify entire chemistry portfolios, accelerating displacement of conventional synthetic fungicides by biological actives engineered for closed-loop hydroponic compatibility.
Growth Catalysts
- EPA Registration Streamlining:The agency's reduced-risk pesticide pathway accelerates biological active approvals, cutting time-to-market for novel biofungicide formulations targeting high-humidity vertical environments.
- Netherlands Cluster Density:Concentrated vertical farm operators around Amsterdam and Rotterdam pilot integrated pest management protocols, creating demonstration effects that pull biological input adoption across European controlled-environment agriculture.
- Hydroponic System Compatibility:pH-stable formulations engineered for recirculating nutrient film technique systems eliminate chemistry-induced root zone disruption, expanding addressable acreage in deep-flow and aeroponic installations.
Market Restraints
- Active Ingredient Supply Concentration:Fermentation capacity for Bacillus-based biofungicides clusters in Denmark and the Netherlands, creating single-source vulnerability for North American formulators.
- F-Gas Regulation Friction:The EU's impending restrictions on certain synthetic biocide categories eliminate fallback chemistry options for European vertical farm operators facing biological formulation failure.
- Encapsulation Input Cost Volatility:Chitosan and alginate carrier material prices fluctuate with marine harvest cycles, compressing margin pools for nanotechnology-enabled formulation developers.
Strategic Opportunities
- USDA Organic Certification Tailwind:Expanding certified organic vertical acreage creates dedicated demand channels for OMRI-listed biopesticides with guaranteed residue-free performance.
- Japan METI Carbon-Neutral Agriculture Mandate:The ministry's 2050 net-zero targets for controlled-environment agriculture incentivize biological chemistry substitution in Tokyo-Osaka vertical farm corridors.
- Direct-to-Grower Digital Distribution:Technical service platforms bypass traditional agrochemical distributor networks, capturing margin from biological input sales to mid-scale vertical farm operators.
Industry Challenges
- Microbial Formulation Stability Expertise Gap:Shortage of fermentation scientists with controlled-environment agriculture specialization delays scale-up of viable shelf-life biological products.
- Dual-Track Certification Complexity:Simultaneous pursuit of EPA registration and EU REACH compliance fragments R&D resources, extending product development timelines for transatlantic market entry.
- Recirculating System Integration Friction:Biological actives require customized dosing protocols incompatible with legacy greenhouse automation, forcing capital expenditure on sensor and control infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Vertical Farm Safe Crop Protection Chemistry Market |
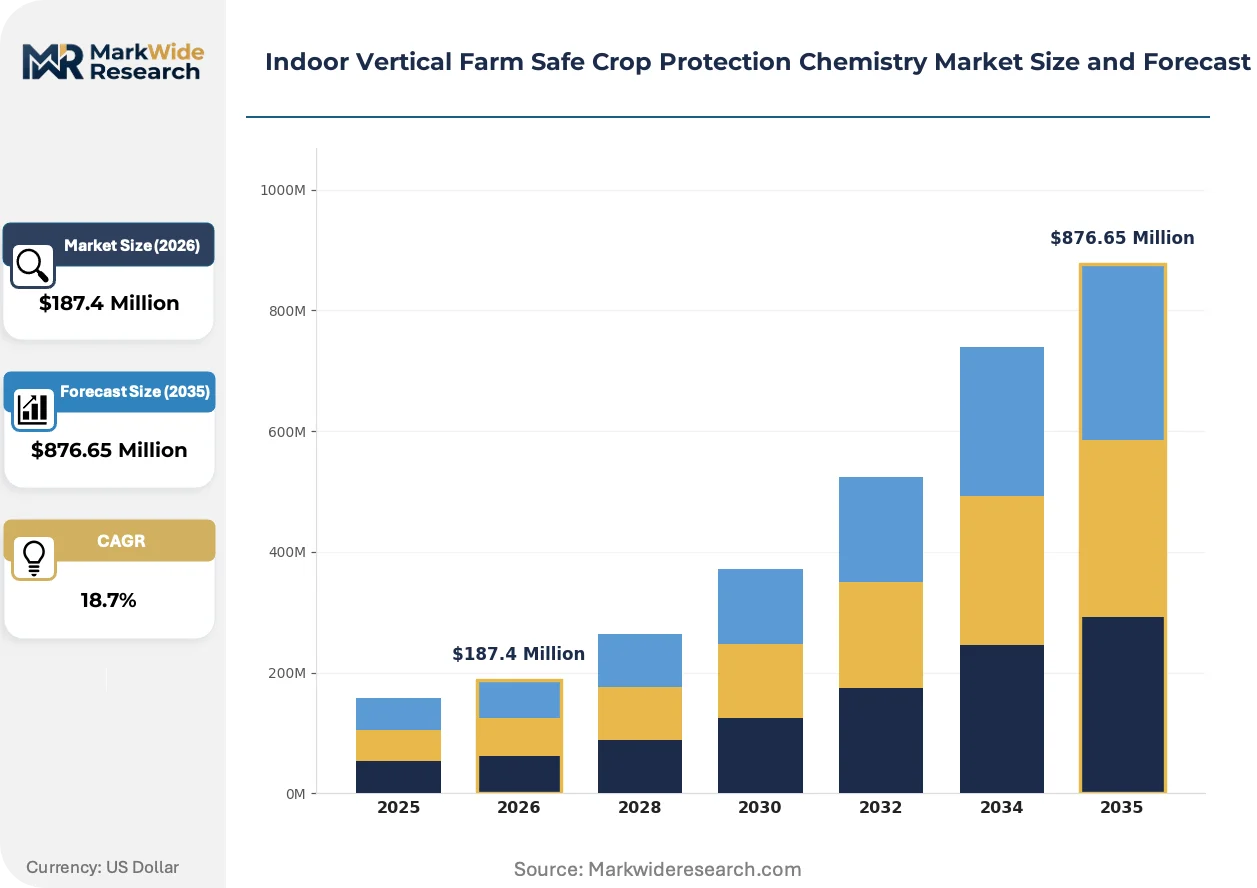
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofungicides, Biopesticides, Insecticides, Herbicides, Rodenticides Application: Leafy Greens, Fruits, Herbs, Microgreens, Edible Flowers Technology: Encapsulation, Controlled Release, Nanotechnology, Biodegradable Formulations, Aqueous Suspensions End User: Vertical Farms, Hydroponic Facilities, Urban Growers, Research Institutions, Specialty Crop Producers |
| Companies Covered | Koppert, BioFirst Group, Andermatt Group, Certis Biologicals, BioWorks, Pro Farm Group, Valent BioSciences, Bayer, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Vertical Farm Safe Crop Protection Chemistry Market Trends and Innovations
Formulation science is converging with automation engineering to reshape application economics in controlled-environment agriculture. Three developments are compressing labor input requirements while tightening residue performance.
Nanotechnology-enabled carrier systems is displacing conventional surfactant-based formulations in large-scale vertical farm operations. These precision-delivery platforms improve active ingredient adhesion to leaf surfaces in high-humidity environments. Operators in the Netherlands and Denmark adopt encapsulated biofungicides to extend spray intervals from weekly to biweekly cycles. The technology is displacing labor-intensive calendar-based application schedules with sensor-triggered intervention protocols.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon propellant options for aerosol biocide delivery in European vertical farm supply chains. Formulators accelerate investment in compressed air and mechanical atomization alternatives. The regulatory compression most affects strawberry and leafy green producers in Belgium and Germany, who are retrofitting application equipment ahead of 2027 prohibition deadlines.
Buyer consolidation among multi-facility vertical farm operators is compressing supplier negotiation cycles and unbundling technical service from product procurement. Large-scale operators in Singapore and the UAE now contract formulation scientists directly, bypassing traditional distributor technical support. This pattern is most visible in controlled-environment tomato and cucumber production, where residue-free chemistry specifications are written into long-term offtake agreements with retail chains.
Indoor Vertical Farm Safe Crop Protection Chemistry Market Segmentation
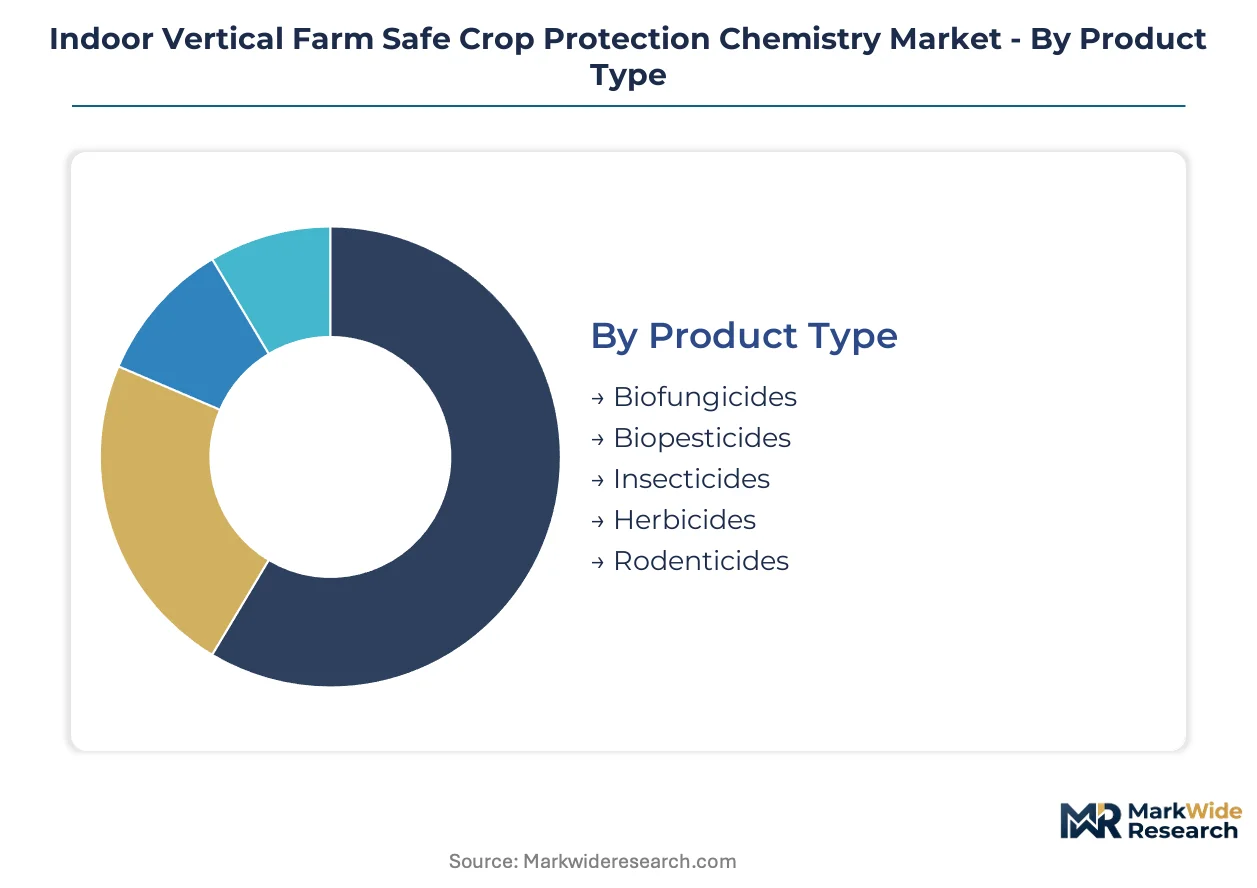
Segmentation in indoor vertical farm crop protection chemistry reveals how formulation requirements diverge across crop types and system architectures. Each dimension—product chemistry, target crop, delivery technology, and operator scale—carries distinct regulatory and performance specifications that reshape supplier R&D priorities.
Product Type:
Dutch and Danish suppliers dominate export channels for fermentation-derived biologicals, while North American formulators serve domestic demand with reduced-risk synthetics.
- Biofungicides:Bacillus subtilis and Trichoderma-based formulations engineered for pH stability between 5.5 and 6.5 in recirculating hydroponic systems. Demand concentrates in Netherlands vertical farm clusters where humidity-induced fungal pressure necessitates recurring application cycles.
- Biopesticides:Microbial and biochemical actives targeting arthropod pests without residue accumulation in closed-loop irrigation. Specialty crop producers in California and Arizona expand procurement as EPA tightens maximum residue limits for controlled-environment agriculture.
- Insecticides:Reduced-risk synthetic and botanical formulations for piercing-sucking pest management in high-density vertical installations.
- Herbicides:Limited deployment confined to substrate-based systems where weed seed contamination occurs; largely displaced by physical weed control in pure hydroponic operations.
- Rodenticides:Restricted-use formulations for perimeter defense in warehouse-converted vertical farms; biological alternatives gain traction in certified organic facilities.
Biofungicides hold the largest share; momentum sits with biopesticides as residue-free specifications tighten across retail offtake agreements.
Application:
Leafy greens and microgreens drive volume due to short crop cycles and continuous production schedules, while fruits and edible flowers command premium positioning through specialized formulation requirements.
- Leafy Greens:Lettuce, spinach, and kale production in nutrient film technique systems requires chemistry compatible with continuous root zone exposure. Singapore and UAE multi-facility operators specify residue-free performance in direct retail contracts.
- Microgreens:Rapid-turnover crops with heightened sensitivity to phytotoxicity demand ultra-low concentration biological formulations. Urban growers in Tokyo-Osaka corridors adopt these chemistries under METI carbon-neutral agriculture mandates.
- Fruits:Strawberry and tomato vertical production requires extended protection windows against fungal and arthropod pressure in high-humidity environments.
- Herbs:Basil, cilantro, and mint cultivation prioritizes flavor-preserving chemistry with zero detectable residue for culinary market specifications.
- Edible Flowers:Niche segment with stringent aesthetic and safety requirements driving adoption of OMRI-listed formulations.
Leafy greens anchor current volume; edible flowers are expanding most quickly as premium retail channels proliferate.
Technology:
Cost tier stratification separates large-scale automated facilities investing in precision delivery from mid-scale operations using conventional aqueous formulations.
- Encapsulation:Chitosan and alginate carrier systems extending spray intervals from weekly to biweekly in Netherlands and Denmark operations. Labor efficiency gains justify input cost premiums for facilities exceeding 10,000 square meters.
- Nanotechnology:Precision-delivery platforms improving active ingredient adhesion in high-humidity vertical environments. Research institutions in Germany and Belgium pilot these systems ahead of commercial scale-up.
- Controlled Release:Polymer-matrix formulations synchronizing active ingredient availability with pest pressure cycles.
- Biodegradable Formulations:Starch and cellulose-based carriers addressing waste stream concerns in certified organic operations.
- Aqueous Suspensions:Conventional liquid formulations retaining dominance among cost-sensitive urban growers with manual application protocols.
Encapsulation leads installed base; nanotechnology carries the steepest expansion trajectory as carrier science matures.
End User:
Customer type determines technical service intensity, with vertical farms and hydroponic facilities requiring system-integrated dosing protocols versus research institutions prioritizing experimental flexibility.
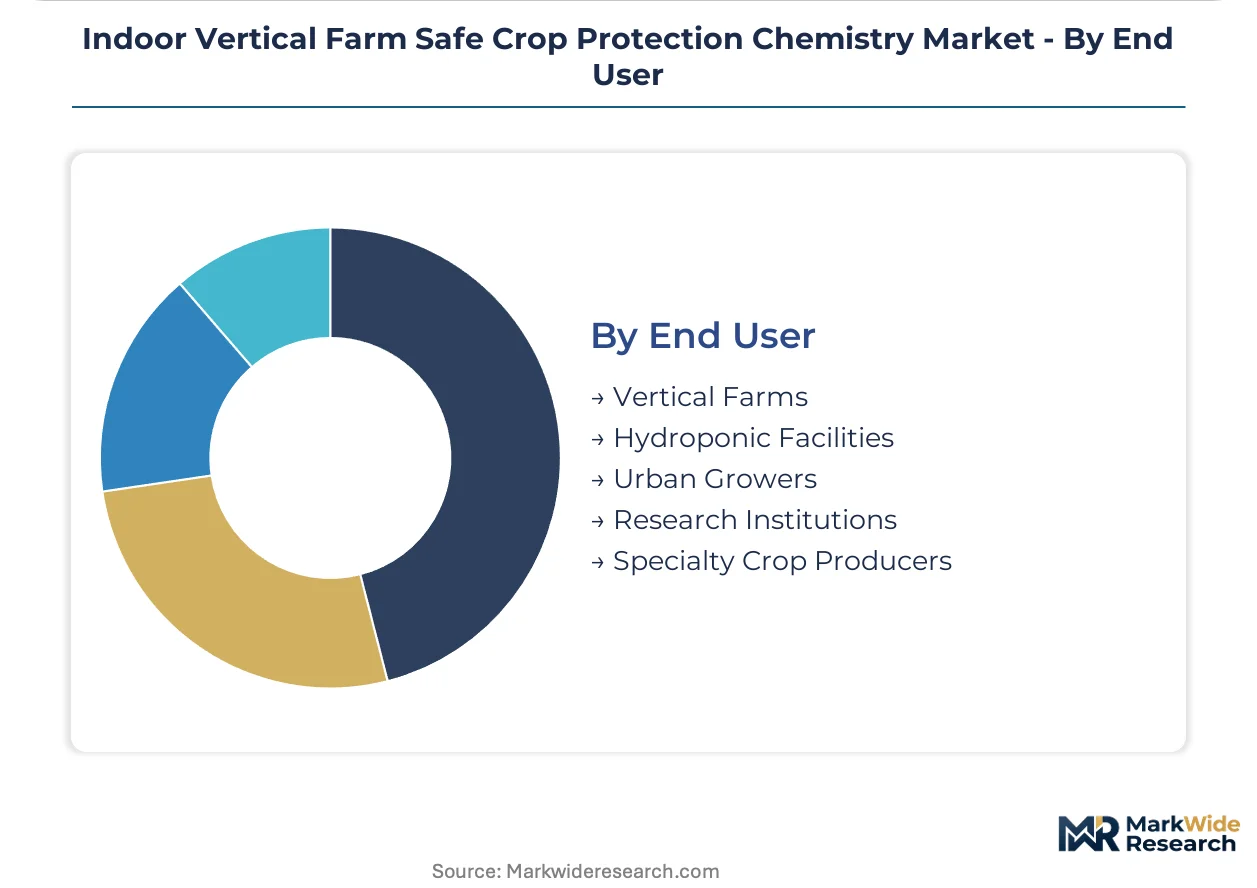
- Vertical Farms:Multi-tier controlled-environment operations with fully automated irrigation demanding pH-stable chemistry compatible with sensor-triggered application systems. Buyer consolidation among Singapore and UAE operators compresses supplier negotiation cycles.
- Hydroponic Facilities:Single-level deep-flow and nutrient film technique installations with semi-automated dosing requiring grower-direct technical support for calibration protocols.
- Urban Growers:Small-scale operations in converted warehouses and shipping containers with manual application methods and price-sensitive procurement.
- Research Institutions:University and government experimental stations testing novel biological actives under controlled conditions.
- Specialty Crop Producers:Diversified operators integrating vertical production into existing greenhouse portfolios with hybrid conventional-biological chemistry strategies.
Vertical farms command the deepest supplier relationships; urban growers are gaining share fastest as entry barriers for small-scale installation decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Netherlands dominance in biological input distribution, while Singapore's Tuas Port expansion anchors Southeast Asian vertical farm chemistry transshipment.
Netherlands
Amsterdam-Rotterdam vertical farm clusters pilot integrated pest management protocols with biological inputs, driving concentrated demand for pH-stable formulations. EFSA maximum residue limit compression accelerates displacement of conventional synthetics by Bacillus-based biofungicides. Wageningen University research corridors partner with commercial operators to validate closed-loop hydroponic compatibility for novel actives.
United States
California and Arizona specialty crop producers expand procurement of residue-free chemistry as EPA tightens maximum residue limits for controlled-environment agriculture. The agency's reduced-risk pesticide pathway accelerates biological active approvals, cutting time-to-market for novel formulations. Indoor farming installations in the Salinas Valley and Phoenix metro areas specify zero-residue performance in direct retail contracts.
Singapore
Multi-facility vertical farm operators compress supplier negotiation cycles and unbundle technical service from product procurement. The city-state's 30-by-30 food security target incentivizes biological chemistry substitution in controlled-environment production. Surbana Jurong engineering clusters retrofit warehouse infrastructure with sensor-triggered application systems for encapsulated formulations.
Germany
Research institutions in Berlin and Munich pilot nanotechnology-enabled carrier systems ahead of commercial scale-up. The impending EU F-Gas Regulation eliminates hydrofluorocarbon propellant options for aerosol biocide delivery, forcing equipment retrofits ahead of 2027 deadlines. Strawberry producers in Lower Saxony adopt compressed air atomization alternatives for high-humidity environments.
Japan
Tokyo-Osaka vertical farm corridors adopt ultra-low concentration biological formulations under METI carbon-neutral agriculture mandates. The ministry's 2050 net-zero targets for controlled-environment agriculture incentivize chemistry substitution in urban production facilities. Kanto region operators specify OMRI-listed inputs for premium retail channel access.
Indoor Vertical Farm Safe Crop Protection Chemistry Market Competitive Landscape
Listed leaders compete with private specialists across formulation science and distribution architecture. The vendor base stratifies between multinational agrochemical conglomerates with microbial R&D platforms and regional biological control agent specialists with grower-direct technical service networks. Three archetypes dominate: fermentation-derived biological suppliers with captive strain libraries, reduced-risk synthetic formulators with EPA registration expertise, and encapsulation technology developers with precision-delivery IP. Competitive moves concentrate on strategic partnerships with automation engineering firms and geographic expansion through distributor acquisition.
Within the biological control agent tier, Koppert and BioWorks exemplify divergent regional anchoring strategies. Koppert leverages its Dutch origin to dominate European supply channels for vertical farm operators, while BioWorks anchors North American distribution through grower-direct technical service networks. Bayer occupies a position bridging synthetic and biological portfolios, sustaining R&D intensity in microbial formulation science. These three represent the competitive spectrum from pure-play biological specialists to integrated agrochemical platforms.
| Leading Market Players |
|---|
| Koppert |
| BioFirst Group |
| Andermatt Group |
| Certis Biologicals |
| BioWorks |
| Pro Farm Group |
| Valent BioSciences |
| Bayer |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with retail chains lock in both supply access and price visibility for large-scale vertical farm operators, insulating preferred suppliers from spot-market volatility while compressing margins for non-contracted formulators competing on technical service differentiation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with OMRI-listed biofungicides commanding top-tier positioning. Price differentiation stems from encapsulation technology adoption and EPA registration status. Cost compression in the economy tier intensifies because fermentation capacity constraints limit Bacillus-based supply expansion. Mid-scale urban growers exhibit highest price sensitivity, while Singapore and UAE multi-facility operators prioritize residue-free performance over unit economics.
Supply Chain Analysis
Rotterdam cold-chain infrastructure underwrites European distribution efficiency for temperature-sensitive biological formulations. Fermentation capacity clusters in Denmark and the Netherlands, while chitosan carrier materials draw from marine harvest cycles in Southeast Asia. Single-source vulnerability for North American formulators creates exposure to transatlantic shipping disruptions. Distribution runs through grower-direct technical service networks in North America and distributor-led channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in controlled-environment agriculture creates runway for residue-free chemistry substitution, with EPA reduced-risk pathway acceleration and METI carbon-neutral mandates combining to pull biological formulation adoption faster than historical greenhouse conversion rates.
For Market Incumbents: Consolidate fermentation capacity in Denmark and the Netherlands through backward integration into strain library development, defending against emerging synthetic biology entrants with CRISPR-enabled microbial engineering capabilities. Capture channel control by embedding formulation scientists directly with Singapore and UAE multi-facility operators, converting technical service relationships into exclusive supply arrangements before buyer consolidation completes. For New Entrants and Emerging Players: EPA reduced-risk registration fast-track offers lowest barrier to commercial validation for novel Bacillus and Trichoderma strains, opening white-space in pH-stable formulations for aeroponic system compatibility. Target Japan's Tokyo-Osaka vertical farm corridors where METI mandates create guaranteed demand pull for carbon-neutral chemistry substitution. Pursue research institution partnerships with Wageningen University or Berlin technical universities to validate hydroponic compatibility ahead of commercial scale-up. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors encapsulation technology developers with precision-delivery IP and established grower-direct relationships. Long-term viability hinges on regulatory divergence between EPA and EFSA frameworks creating durable competitive moats for dual-registered formulators. Watch EPA maximum residue limit compression velocity as the inflection signal indicating biological displacement acceleration versus synthetic retention.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Libraries | Captive Bacillus and Trichoderma access insulates against Danish and Dutch fermentation bottlenecks. |
| Encapsulation Technology Licensing | Chitosan and alginate carrier IP extends spray intervals for Netherlands large-scale operators. |
| Dual-Track Regulatory Investment | Simultaneous EPA and EU REACH registration creates transatlantic market access advantage. |
| Direct-to-Grower Digital Platform | Technical service bypass of distributor networks captures margin from mid-scale vertical farm procurement. |
| Research Institution Partnership | Wageningen University validation accelerates closed-loop hydroponic compatibility certification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with vertical farm operations directors, biological formulation scientists, EPA regulatory affairs specialists, and agricultural distributor procurement managers. Secondary validation drew from EPA registration databases, EFSA maximum residue limit publications, USDA organic certification records, and customs trade data for fermentation equipment imports. Bottom-up acreage estimates for controlled-environment agriculture installations were triangulated against top-down chemical input spend projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product chemistry type, target crop category, delivery technology tier, and operator scale archetype. CAGRs were derived from installed base expansion rates and input intensity per square meter assumptions. Industry-specific forecast inputs incorporated EPA reduced-risk approval velocity and EU F-Gas Regulation phase-down schedules.
The analysis sits within stated boundaries; outcomes outside sustained regulatory compression on maximum residue limits would require recalibration. Forecasts reflect assumptions regarding fermentation capacity expansion and encapsulation input cost stability. Practitioners should keep alternative scenarios live as EPA-EFSA regulatory divergence and marine harvest cycle volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Tembotrione Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Europe Nematicide Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Global Acephate Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
United States Nematicides Market