
 South Korea Cloud Computing Market | 2026-2036
South Korea Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Cloud Computing Market Intelligence
Modular service bundling is decoupling infrastructure procurement from platform commitments across South Korean enterprises. Naver Cloud leverages domestic data center density to anchor government and financial sector contracts. Samsung SDS competes through vertical integration into enterprise IT modernization. Kakao Enterprise specializes in consumer-facing application backends that demand low-latency edge presence.
Cloud computing delivers on-demand computational resources, storage, and application services through networked data centers utilizing virtualization and container orchestration at sub-10 millisecond latency thresholds for real-time workloads. Its primary purpose is to replace capital-intensive on-premises infrastructure with elastic operational expenditure models. Infrastructure as a Service dominates current revenue as enterprises retain control over runtime environments while offloading hardware lifecycle management. Software as a Service exhibits the fastest expansion as domestic SaaS vendors penetrate verticals from legal tech to construction management. Hybrid Cloud configurations capture concentrated margin pools where regulatory complexity demands orchestration between private and public environments.
MFDS guidelines on medical data handling, KISA cloud security certification requirements, and PIPA data localization mandates collectively shape vendor qualification and customer procurement specifications in South Korea. Compliance burden favors domestic operators with pre-certified sovereign infrastructure over foreign hyperscalers without localized tenancy options. Stakeholders must monitor evolving encryption standards and cross-border data flow restrictions that could recalibrate competitive positioning between local and international providers.
Market Dynamics
Sovereign cloud mandates under PIPA are fragmenting procurement patterns across South Korean enterprises, forcing architectural decisions that privilege domestic data residency over cost optimization.
Growth Catalysts
- PIPA Localization Mandates:Data sovereignty requirements steer financial services and healthcare workloads toward certified domestic infrastructure, creating guaranteed demand pools for compliant operators.
- Seoul Metropolitan Density:Hyperscale data center clustering in Gyeonggi and Incheon delivers sub-5 millisecond latency to 50% of national enterprises, anchoring real-time application migration.
- Container Orchestration Maturation:Kubernetes-native platforms enable financial institutions to lift-and-shift legacy monoliths without full re-architecture, accelerating cloud adoption timelines.
Market Restraints
- GPU Supply Concentration:AI training workload expansion faces allocation bottlenecks from Taiwan-based foundry output, inflating reserved instance pricing for machine learning pipelines.
- KISA Certification Friction:Multi-month security evaluation timelines delay foreign hyperscaler service launches, compressing competitive pressure on incumbent pricing.
- Legacy Mainframe Dependency:Core banking systems on IBM zSeries architectures resist cloud-native refactoring, trapping capital in hybrid maintenance contracts.
Strategic Opportunities
- Busan-Ulsan Industrial Belt:Manufacturing automation and port logistics digitization remain underpenetrated by cloud services, offering greenfield deployment opportunities outside Seoul saturation.
- 5G Network Slicing Convergence:Integration of edge computing with carrier-grade slicing enables ultra-reliable low-latency services for autonomous vehicle testing zones.
- Green Data Center Incentives:Renewable energy certificates and carbon intensity disclosure requirements favor operators with hydroelectric or offshore wind power purchase agreements.
Industry Challenges
- Cloud-Native Engineering Scarcity:Financial services and public sector employers compete for Kubernetes-certified DevOps talent, inflating compensation premiums above software industry averages.
- Cross-Domain Integration Complexity:Healthcare providers struggle to reconcile MFDS medical device validation requirements with agile cloud deployment cycles, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Cloud Computing Market |
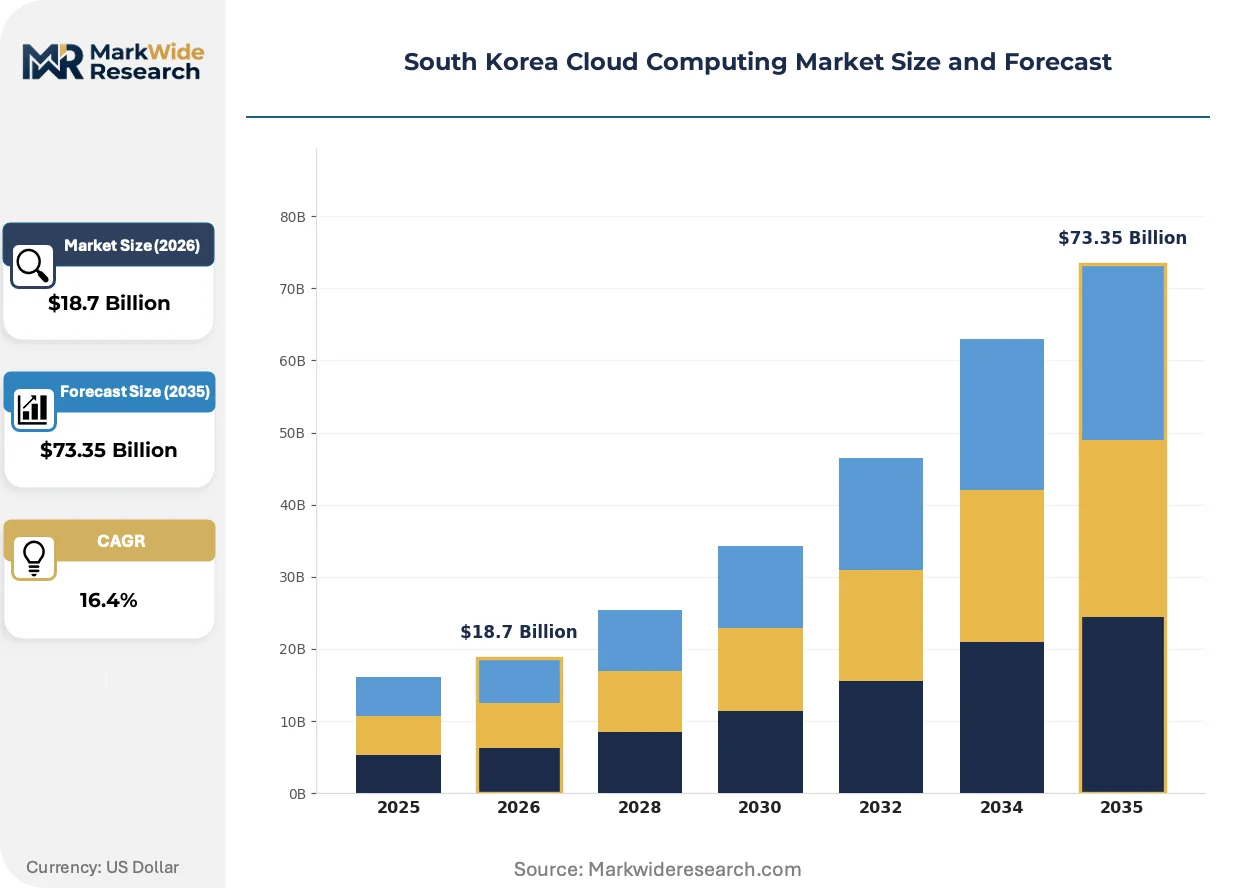
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Backup as a Service End User: Enterprise, Small and Medium Businesses, Government, Education Solution: Cloud Storage, Cloud Security, Disaster Recovery, Cloud Analytics |
| Companies Covered | Naver Cloud, Samsung SDS, Amazon Web Services (AWS), LG CNS, KT Cloud, Microsoft Corporation, Kakao Enterprise, IBM Corporation, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Cloud Computing Market Strategic Shifts & Innovations
Workload portability and sovereign compliance are converging to reshape vendor selection criteria across South Korean enterprises, with architectural decisions increasingly driven by data residency rather than pure technical performance.
Confidential computing hardware is absorbing sensitive workload processing across financial services and government sectors. Banks handling KYC and transaction data are deploying AMD SEV-SNP and Intel TDX-enabled instances at scale. This encryption-in-use capability is absorbing regulatory risk that previously mandated on-premises air-gapped infrastructure.
MFDS guidelines on medical data handling are tightening cloud eligibility for healthcare providers. The 2024 amendments require explicit cloud security certification for any patient data processing outside hospital premises. Hospital IT departments are responding by segmenting workloads, keeping diagnostic imaging on certified private infrastructure while migrating administrative systems to qualified public platforms.
Consumption-based billing models are displacing reserved capacity commitments among mid-market enterprises. SaaS vendors and ISVs are offering pay-per-query data warehouse pricing that eliminates upfront provisioning. This shift is most visible in legal tech and construction management verticals, where seasonal workload volatility makes fixed capacity economically inefficient.
South Korea Cloud Computing Market Segmentation
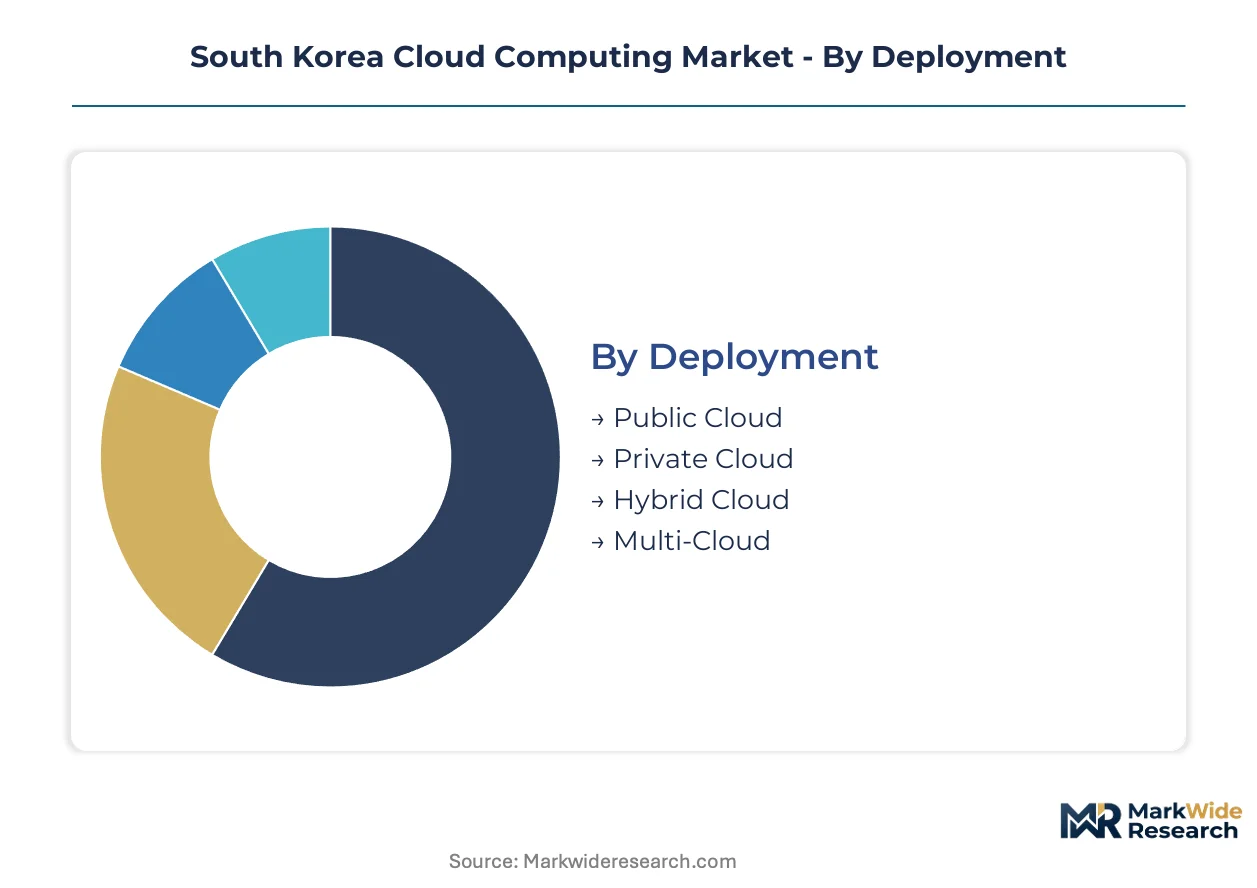
South Korea's cloud market segments reflect the tension between regulatory compliance and technical flexibility. Procurement decisions pivot on data residency requirements, latency sensitivity, and workload portability needs across financial services, manufacturing, and public sector verticals.
Deployment:
Deployment architecture determines data sovereignty posture and operational control boundaries for Korean enterprises navigating PIPA mandates.
- Public Cloud:Third-party infrastructure delivers elastic compute and storage through shared tenancy models. Financial services firms in Seoul's Yeouido district deploy public cloud for non-sensitive workloads while maintaining certified private environments for core banking data.
- Private Cloud:Dedicated infrastructure provides single-tenant isolation with full administrative control over physical and virtual layers. Healthcare providers at Seoul National University Hospital and Samsung Medical Center favor private deployments for patient data repositories subject to MFDS validation requirements.
- Hybrid Cloud:Orchestrated environments span on-premises private infrastructure with burst capacity to public platforms. Manufacturing conglomerates in Gyeonggi Province use hybrid configurations to keep proprietary design data local while leveraging public AI training clusters.
- Multi-Cloud:Distributed workloads across independent provider infrastructures eliminate single-vendor dependency. Government agencies under the Cloud First policy deploy multi-cloud strategies to ensure service continuity during regional outages.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Type:
Service abstraction layers define customer control depth and vendor responsibility boundaries in Korean procurement contracts.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered through virtualized abstraction. IaaS dominates current enterprise spending as Korean firms retain runtime control while offloading hardware lifecycle management to certified domestic operators.
- Platform as a Service:Managed runtime environments with integrated middleware, databases, and development tools. PaaS adoption accelerates among fintech startups in Pangyo Techno Valley seeking rapid application deployment without infrastructure provisioning overhead.
- Software as a Service:Fully managed applications accessed through subscription licensing. SaaS exhibits the steepest expansion trajectory as domestic vendors penetrate verticals from legal tech to construction management with consumption-based pricing.
- Backup as a Service:Automated data protection and recovery orchestration delivered through cloud-native platforms. Korean SMEs in Busan's manufacturing belt adopt BaaS to satisfy cyber insurance requirements without dedicated backup infrastructure investment.
IaaS leads on scale; SaaS leads on momentum.
End User:
Customer scale and procurement sophistication shape pricing structures and service level agreements across the Korean market.
- Enterprise:Large organizations with dedicated IT procurement functions and complex compliance requirements. Enterprise demand concentrates in Seoul's financial district where sovereign cloud mandates drive multi-year infrastructure commitments.
- Small and Medium Businesses:Mid-scale operations with limited technical staff and preference for managed service consumption. SMBs in Daejeon's research corridor favor pay-as-you-grow models that align cloud spending with revenue fluctuations.
- Government:Public sector entities subject to KISA certification and national security screening. Central government agencies under the Digital New Deal initiative mandate domestic cloud tenancy for all citizen data processing.
- Education:Universities and research institutes with high-performance computing and collaborative platform needs. KAIST and POSTECH drive demand for GPU-intensive research computing environments with international peer connectivity.
Enterprise leads on scale; Government leads on momentum.
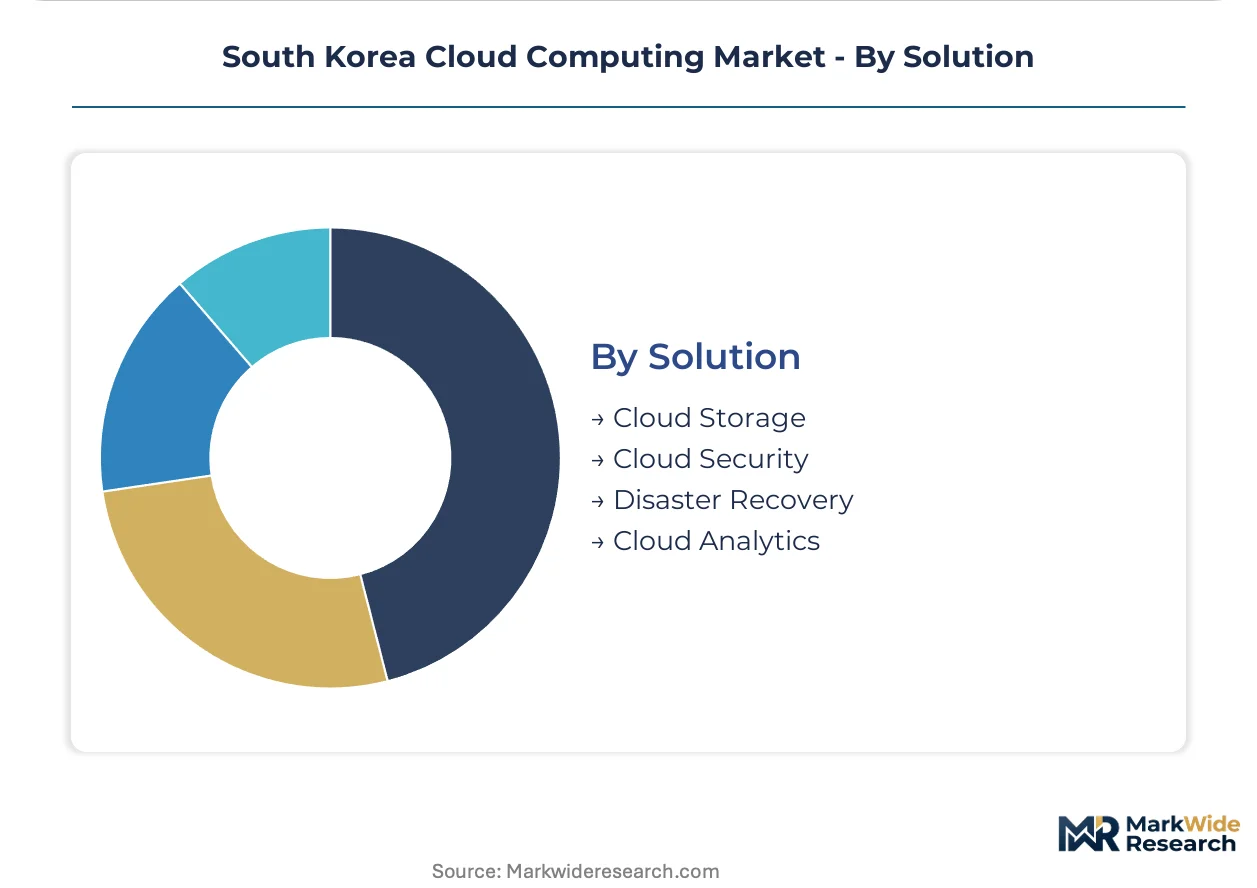
Solution:
Functional capability modules address specific operational risks and analytical requirements across Korean industry verticals.
- Cloud Storage:Scalable object, block, and file storage services with tiered durability guarantees. Object storage demand surges among media streaming platforms serving Korea's mobile-first consumer base.
- Cloud Security:Identity management, encryption, threat detection, and compliance monitoring delivered as integrated services. Banks deploy cloud-native security information and event management to satisfy Financial Supervisory Service audit requirements.
- Disaster Recovery:Automated failover and data replication ensuring business continuity across geographically separated zones. Manufacturers in Ulsan's industrial complex prioritize DR solutions protecting against supply chain disruption.
- Cloud Analytics:Data warehouse, business intelligence, and machine learning platform services. Retail conglomerates deploy cloud analytics to unify online and offline transaction data for real-time demand forecasting.
Cloud Storage leads on scale; Cloud Security leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's cloud computing industry traces its modern lineage to the 2015 Cloud First policy, which centralized government procurement around domestic infrastructure providers and established the regulatory foundation for sovereign data architectures.
Seoul Capital Area
Financial services firms in Yeouido and Teheran-ro drive demand for certified sovereign cloud infrastructure under PIPA mandates. The Financial Supervisory Service enforces strict data localization for core banking systems. Hyperscale data center clusters in Gyeonggi and Incheon deliver sub-5 millisecond latency to half of national enterprises, anchoring real-time application workloads.
Busan-Ulsan
Manufacturing automation and port logistics digitization create greenfield cloud deployment opportunities outside Seoul saturation. The Ministry of Trade, Industry and Energy promotes smart factory initiatives requiring edge computing integration. Hyundai Heavy Industries and Busan Port Authority anchor industrial IoT demand in this southeastern corridor.
Daegu-Gyeongbuk
Textile and machinery manufacturers seek cloud-based supply chain visibility platforms to manage subcontractor networks. The Korea Industrial Complex Corporation sponsors digital transformation subsidies for SME technology adoption. Daegu's manufacturing belt remains underpenetrated by managed cloud services relative to capital region saturation.
Daejeon-Sejong
Public sector research institutions and government agencies concentrate demand for high-performance computing environments. The National Assembly relocation to Sejong City expanded administrative cloud requirements under Digital New Deal procurement rules. KAIST and national laboratories drive GPU-intensive research computing procurement with international peer connectivity needs.
Gwangju-Honam
Renewable energy project developers and agricultural technology startups form emerging cloud demand pockets in Korea's southwestern region. The Ministry of Agriculture, Food and Rural Affairs funds precision farming platforms requiring edge data processing. Gwangju's AI-focused industrial complex attracts cloud providers seeking diversification beyond Seoul-centric competition.
South Korea Cloud Computing Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and sovereign infrastructure ownership. The vendor base stratifies between domestic operators with pre-certified KISA compliance and foreign hyperscalers navigating multi-month security evaluation timelines. Three archetypes dominate: telecommunications carriers with captive data center assets, conglomerate-affiliated IT services divisions with vertical integration advantages, and independent cloud-native platforms specializing in consumer-facing low-latency workloads. Competitive moves center on strategic partnerships with financial institutions seeking compliant infrastructure and capacity expansion in secondary metropolitan zones beyond Seoul saturation.
Among domestic platform operators, Naver Cloud, Samsung SDS, and Kakao Enterprise exemplify divergent strategic positioning within Korea's sovereign cloud ecosystem. Naver Cloud anchors government and financial sector contracts through domestic data center density. Samsung SDS occupies a position reflecting conglomerate-affiliated IT services integration. Kakao Enterprise represents the consumer-facing application backend specialization demanding distributed edge presence.
| Leading Market Players |
|---|
| Naver Cloud |
| Samsung SDS |
| Amazon Web Services (AWS) |
| LG CNS |
| KT Cloud |
| Microsoft Corporation |
| Kakao Enterprise |
| IBM Corporation |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Carbon intensity disclosure requirements under Korea's renewable energy certificate system gate both qualified supply and premium-tier pricing access for cloud operators, as domestic providers with hydroelectric or offshore wind power purchase agreements command pricing premiums over coal-dependent competitors while foreign hyperscalers absorb KISA certification delays.
Pricing Analysis
Reserved capacity commitments with consumption-based billing overlays dominate enterprise procurement, with pricing stratifying across certified sovereign tiers, standard domestic tenancy, and economy-grade shared infrastructure. Price differentiation hinges on KISA certification grade and data center energy source, with green-certified facilities extracting premiums. Cost compression in economy tiers is intensifying because GPU supply concentration from Taiwan-based foundries inflates machine learning pipeline pricing. SMBs in Daejeon's research corridor exhibit highest price sensitivity, while financial services firms in Yeouido accept premium sovereign pricing for PIPA compliance.
Supply Chain Analysis
Freight costs for server hardware and networking equipment from Taiwan, China, and the United States absorb margin at Korean cloud operators, with semiconductor foundry output bottlenecks propagating through delivery timelines. Raw material dependencies center on advanced GPUs from TSMC, memory modules from Samsung and SK Hynix, and optical networking gear from Chinese vendors. Single-source vulnerability in Taiwan-based GPU allocation creates procurement risk for AI training clusters. Distribution runs through direct enterprise sales teams for large contracts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward confidential computing-enabled instances that satisfy MFDS and Financial Supervisory Service encryption-in-use mandates.
For Market Incumbents: Anticipate margin compression from foreign hyperscalers clearing KISA certification backlogs by expanding sovereign data center capacity in Gyeonggi and Incheon before competitive entry. Deepen backward integration into renewable energy procurement to defend pricing power against carbon disclosure requirements. Prioritize Kubernetes-native platform investments to capture container orchestration demand from financial institutions lifting legacy monoliths. For New Entrants and Emerging Players: Enter via the Busan-Ulsan industrial belt, where manufacturing automation and port logistics digitization remain underpenetrated by established Seoul-centric providers. Target smart factory initiatives under the Ministry of Trade, Industry and Energy sponsorship, with edge computing integration as the primary go-to-market angle. Position around 5G network slicing convergence for autonomous vehicle testing zones in this southeastern corridor. For Investors and Strategic Acquirers: Valuations sit cheapest among independent cloud-native platforms lacking captive data center assets but possessing Kubernetes-certified engineering teams. Long-term viability hinges on sovereign infrastructure ownership or exclusive carrier partnerships. Acquisition targets should demonstrate pre-certified KISA compliance and existing government contract relationships. Watch for MFDS guideline amendments on medical data handling as the signal for healthcare cloud eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Expansion | Pre-certified KISA infrastructure in Gyeonggi Province captures financial sector PIPA-mandated workloads. |
| Confidential Computing Platform Launch | AMD SEV-SNP and Intel TDX-enabled instances absorb regulatory risk for banking KYC processing. |
| Renewable Energy Procurement | Offshore wind power purchase agreements satisfy carbon intensity disclosure for premium pricing tiers. |
| Edge Computing Partnership | 5G network slicing integration with KT and SK Telecom enables ultra-reliable low-latency manufacturing services. |
| Vertical SaaS Acquisition | Legal tech and construction management vendors accelerate consumption-based billing model penetration. |
Research Approach
Coverage spans Seoul Capital Area, Busan-Ulsan, Daegu-Gyeongbuk, Daejeon-Sejong, and Gwangju-Honam, with primary inputs from each region combining interviews with cloud platform engineers, IT procurement officers at financial institutions, KISA certification auditors, and data center operations directors. Secondary validation draws from hyperscaler capex disclosures, KISA security certification databases, MFDS medical device guidance documents, and Financial Supervisory Service audit protocols. Bottom-up workload sizing and top-down infrastructure investment tracking triangulate market estimates.
Rate-of-change decomposition across deployment models, service types, and end-user segments drives the analytical framework, with CAGRs derived from elasticity modeling of enterprise IT modernization cycles and public sector Digital New Deal procurement patterns. Segmentation dimensions include sovereign compliance posture, latency sensitivity thresholds, and workload portability requirements throughout the forecast period. GPU supply constraints from Taiwan foundry allocation and PIPA regulatory evolution anchor scenario boundaries.
Inputs from KISA certification timelines and hyperscaler market entry announcements were available through the study window; gaps in real-time enterprise workload migration data introduce uncertainty bands around private-to-public cloud shift assumptions. Forecasts reflect documented elasticity parameters and regulatory enforcement intensity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
France Cloud Computing Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
ASEAN Cloud Computing Market