
 Confidential Computing Market | 2026-2036
Confidential Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Confidential Computing Market Analytics
The EU AI Act is recalibrating the cost-of-entry calculus for cloud providers serving regulated European industries. Microsoft Corporation leverages its Azure confidential computing stack to anchor enterprise workloads requiring verifiable isolation. IBM Corporation specializes in mainframe-integrated trusted execution environments for financial services clients. Google LLC extends its cloud security posture through custom silicon and open-source frameworks for confidential VMs.
Confidential computing refers to technologies that protect data during active processing through hardware-based trusted execution environments, typically employing CPU-enforced memory encryption with keys inaccessible to the host operating system or hypervisor. Its primary commercial purpose is to enable sensitive computations on untrusted infrastructure while maintaining cryptographic guarantees of data integrity and code authenticity. Cloud Security applications lead current deployment value as enterprises migrate regulated workloads, while Secure Multiparty Computation represents the fastest-expanding technology segment for cross-organizational analytics. On-Premises deployment retains the largest installed base among defense and intelligence agencies with stringent data sovereignty requirements.
The EU AI Act, GDPR, and NIST standards collectively shape product certification requirements and procurement criteria for confidential computing infrastructure across transatlantic markets. FDA guidance on cybersecurity for connected medical devices and China's NMPA data localization rules further expand addressable demand in healthcare and life sciences verticals. Stakeholders must monitor evolving sovereign cloud mandates and chip export controls as determinants of regional technology sourcing strategies.
Market Dynamics
Hardware-based trusted execution environments are consolidating control over sensitive cloud workloads as enterprises reject software-only security postures. The EU AI Act's data-in-use mandates are accelerating procurement cycles for verifiable isolation technologies.
Growth Catalysts
- EU AI Act enforcement:The regulation mandates cryptographic protection for AI training data, forcing financial services and healthcare providers to deploy confidential VMs.
- Healthcare data localization:China's NMPA rules and FDA cybersecurity guidance for connected medical devices are expanding demand for on-premises trusted execution environments.
- Financial services migration:Banks are moving core risk analytics to confidential cloud instances to satisfy GDPR Article 32 requirements for processing integrity.
Market Restraints
- Silicon supply concentration:Trusted execution environment capabilities depend on CPU architectures from a narrow set of foundry locations, creating geopolitical exposure.
- Certification cost barriers:Common Criteria EAL4+ evaluation for confidential computing platforms requires multi-year timelines and seven-figure investments.
- Legacy infrastructure incompatibility:Existing virtualization stacks lack attestation primitives, forcing forklift upgrades to hypervisor layers.
Strategic Opportunities
- Secure multiparty computation convergence:The intersection of confidential computing with federated analytics is unlocking cross-institutional fraud detection in German banking consortia.
- Sovereign cloud mandates:France, Germany, and Italy are requiring domestic data processing for public sector workloads, privileging EU-hosted confidential infrastructure.
- Edge deployment expansion:Manufacturing facilities in the United States are adopting confidential computing nodes for industrial IoT data pre-processing.
Industry Challenges
- Attestation protocol fragmentation:Competing remote attestation standards from hardware vendors are complicating multi-cloud deployment architectures.
- Cryptographic talent scarcity:Enterprises lack personnel versed in secure enclave programming models, slowing production deployments.
- Performance overhead trade-offs:Memory encryption introduces latency penalties that conflict with real-time analytics service-level agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confidential Computing Market |
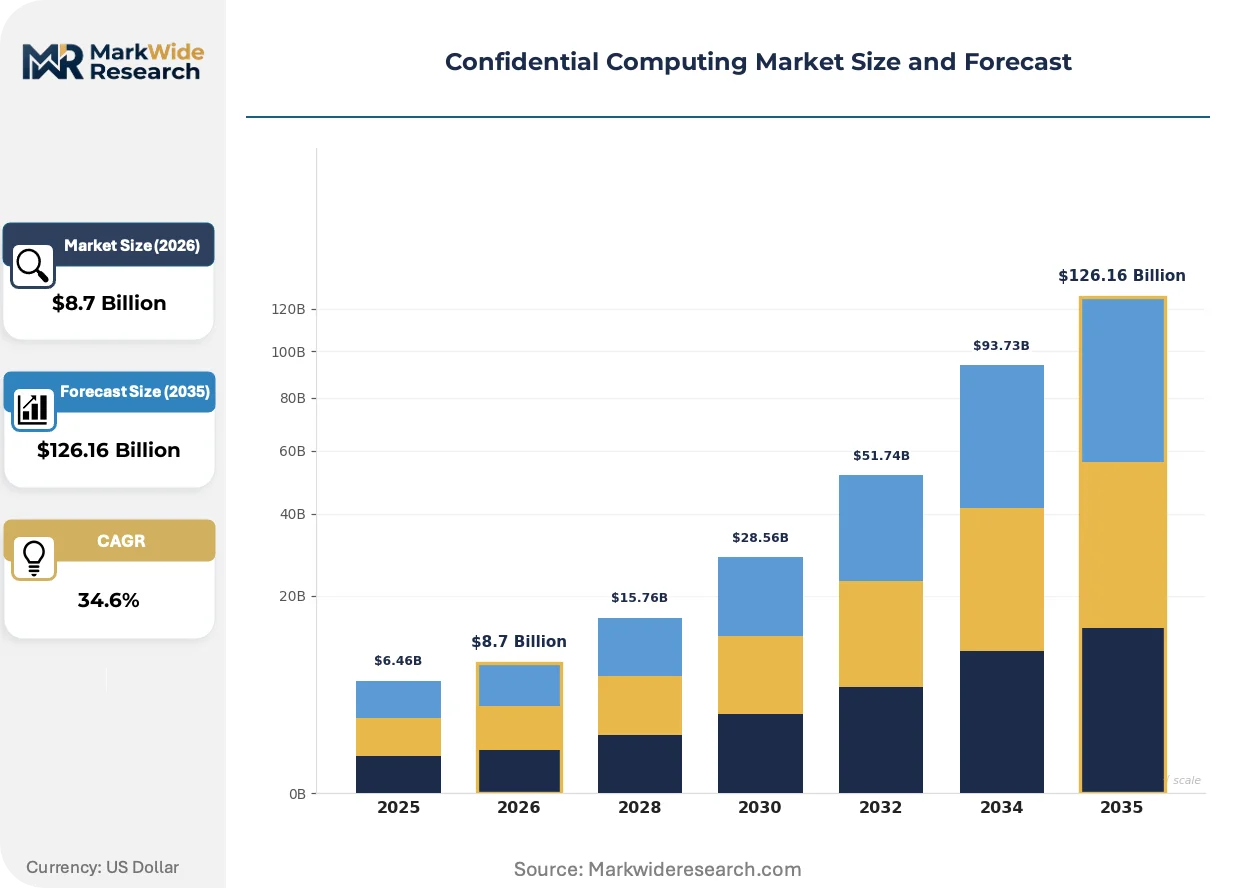
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cloud Security, Data Protection, Secure Enclaves, Endpoint Security Deployment: On-Premises, Hybrid, Multi-Cloud, Private Cloud End User: Financial Services, Government Agencies, Healthcare Providers, Retail Technology: Hardware Security Modules, Trusted Execution Environments, Secure Multiparty Computation, Homomorphic Encryption |
| Companies Covered | Microsoft Corporation, IBM Corporation, Intel Corporation, Google LLC, Advanced Micro Devices, Amazon Web Services, Alibaba Cloud, Arm Limited, Swisscom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confidential Computing Market Evolving Landscape
Confidential computing architectures are bifurcating between cloud-native abstraction layers and sovereign infrastructure stacks. Three forces are compressing technology adoption curves.
Confidential VMs with AMD SEV-SNP and Intel TDX are rewriting the economics of regulated workload hosting. Financial institutions in the United States and Germany are migrating derivatives pricing engines to these environments within eighteen-month windows. The shift is compressing traditional on-premise data center commitments for sensitive analytics.
The EU AI Act's risk classification framework is mandating technical documentation for high-risk AI systems that includes verifiable isolation proofs. Cloud providers serving European healthcare and credit scoring verticals must demonstrate hardware-backed confidentiality. German automotive suppliers are reconfiguring supply chain data sharing to satisfy these attestations.
Enterprise buyers are unbundling security certification from infrastructure procurement, demanding portable confidential computing credentials across cloud boundaries. Financial services procurement teams in New York and Frankfurt now require workload portability between Azure, AWS, and sovereign EU clouds. The pattern is fragmenting single-vendor lock-in strategies that dominated early deployment phases.
Confidential Computing Market Segmentation
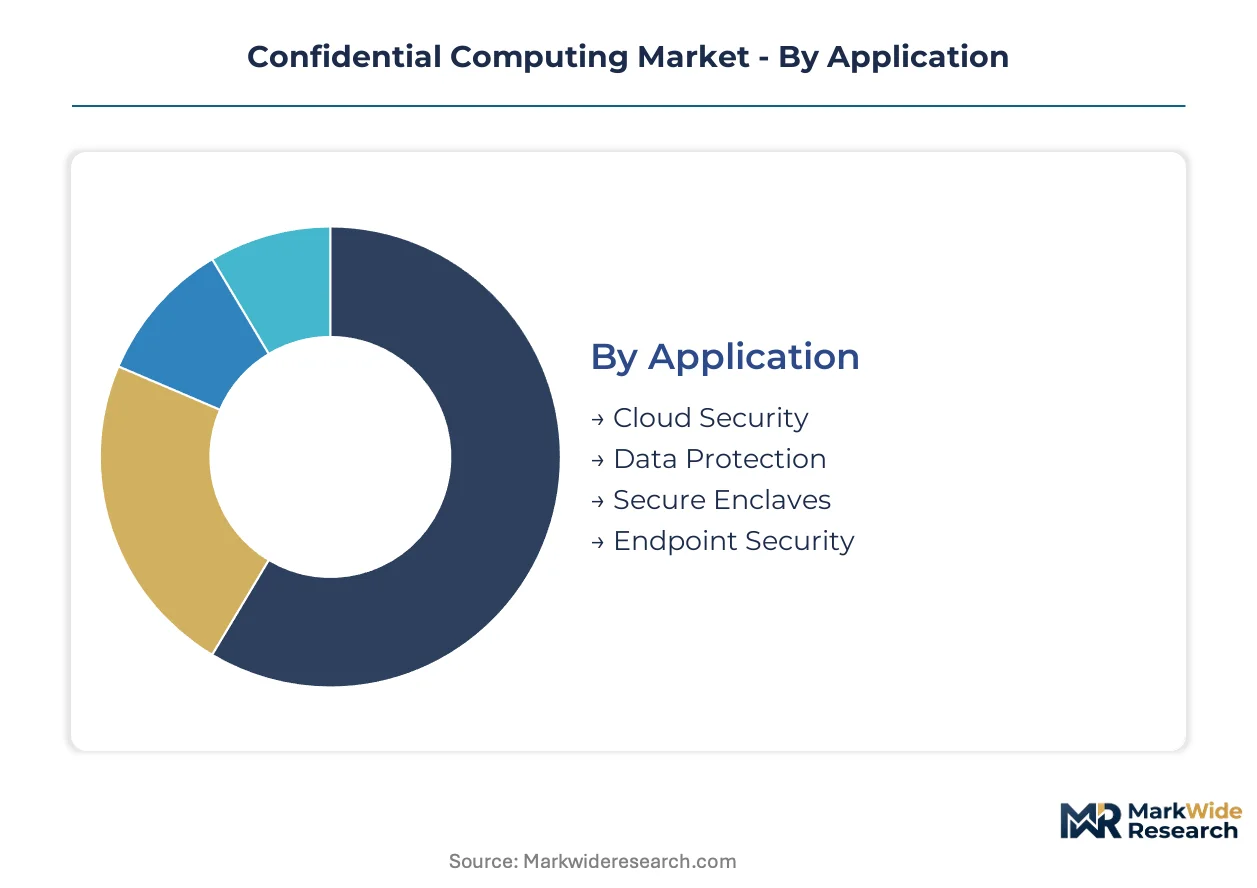
Confidential computing procurement follows distinct technical and regulatory pathways. Buyers prioritize deployment architecture based on data sovereignty mandates and workload sensitivity. Application requirements further segment purchasing decisions between cloud-native isolation and hardware-backed endpoint protection.
Application:
Workload sensitivity determines buyer prioritization across protection layers.
- Cloud Security:Encompasses infrastructure-level isolation for multi-tenant environments through CPU-enforced memory encryption. Financial services firms in the United States and Germany migrate regulated analytics to confidential cloud instances under GDPR Article 32 and EU AI Act mandates.
- Secure Enclaves:Provides process-level isolation with cryptographic attestation for code integrity verification. Healthcare providers deploy these for FDA-compliant connected medical device data processing, particularly where patient records cross organizational boundaries.
- Data Protection:Focuses on encryption-in-use for databases and analytics pipelines. Retailers adopt this for payment card data processing to reduce PCI-DSS compliance scope.
- Endpoint Security:Secures device-level computation through trusted platform modules and secure boot chains. Government agencies specify these for classified workstation deployments.
Cloud Security leads on scale; Secure Enclaves leads on momentum.
Deployment:
Infrastructure control preferences split between sovereignty requirements and operational flexibility.
- On-Premises:Dedicated hardware within facility boundaries with full key custody. Defense and intelligence agencies mandate this architecture for classified workloads under national security directives.
- Hybrid:Combines on-premises enclaves with burst capacity to confidential cloud. German automotive suppliers favor this for supply chain data sharing that must satisfy EU AI Act attestations while retaining engineering IP locally.
- Private Cloud:Single-tenant confidential infrastructure hosted by third-party operators. France and Italy require this for public sector workloads under sovereign cloud mandates.
- Multi-Cloud:Portable confidential workloads across provider boundaries with unified attestation. Financial services procurement teams in New York and Frankfurt now demand this to avoid vendor lock-in.
On-Premises retains the largest committed base; Multi-Cloud is climbing the fastest.
End User:
Sector-specific compliance frameworks dictate technology selection and certification requirements.
- Financial Services:Banks and insurers deploy confidential VMs for derivatives pricing, fraud detection, and cross-border payments. GDPR and EU AI Act enforcement accelerates procurement cycles for verifiable isolation.
- Government Agencies:National security and civilian agencies require Common Criteria EAL4+ certified platforms. China's NMPA data localization rules and US federal zero-trust mandates expand addressable demand.
- Healthcare Providers:Hospitals and research institutions protect patient data during AI training and multi-site analytics. FDA cybersecurity guidance for connected devices and clinical trial data protection drive specifications.
- Retail:Merchants and payment processors secure transaction data and personalization algorithms. PCI-DSS compliance and consumer privacy regulations shape deployment choices.
Financial Services dominates current spending; Healthcare Providers show the steepest expansion trajectory.
Technology:
Hardware-rooted trust anchors differentiate vendor offerings against software-only alternatives.
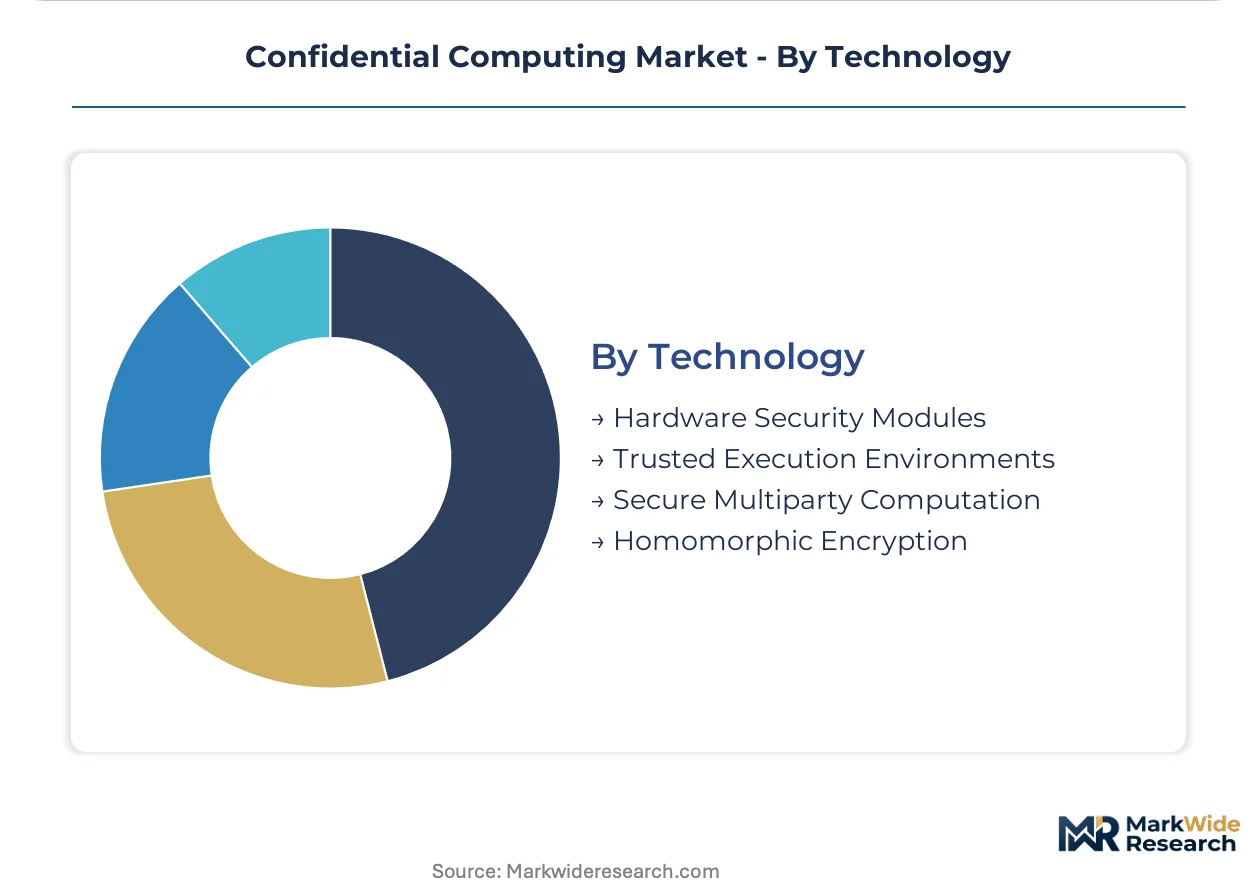
- Trusted Execution Environments:CPU-based secure enclaves with memory encryption and remote attestation. AMD SEV-SNP and Intel TDX implementations are rewriting economics for regulated workload hosting in the United States and Germany.
- Secure Multiparty Computation:Cryptographic protocols enabling joint computation without data exposure. German banking consortia deploy this for cross-institutional fraud detection while preserving data confidentiality.
- Hardware Security Modules:Dedicated appliances for key generation, storage, and cryptographic operations. Financial services maintain these for high-assurance key custody in payment systems.
- Homomorphic Encryption:Enables computation on encrypted data without decryption. Research-intensive verticals pilot this for privacy-preserving machine learning where TEE performance overhead conflicts with real-time requirements.
Trusted Execution Environments commands the installed base; Secure Multiparty Computation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Confidential computing emerged from academic trusted execution research at Princeton and Stanford before commercializing through Intel's SGX launch in 2015. The technology's hardware roots in US semiconductor design and European privacy regulation created divergent regional adoption patterns that persist today.
United States
Financial services firms in New York and Chicago drive demand for confidential VMs processing derivatives pricing and fraud detection workloads. The SEC's cybersecurity disclosure rules and NIST zero-trust architecture mandates accelerate procurement timelines for verifiable isolation technologies. Seattle hosts the dominant cloud infrastructure providers integrating AMD SEV-SNP and Intel TDX into enterprise offerings.
Germany
Automotive suppliers and banking consortia deploy secure multiparty computation for cross-institutional analytics without data exposure. The EU AI Act's high-risk system requirements and GDPR Article 32 enforcement compel hardware-backed confidentiality proofs for AI training pipelines. Frankfurt's financial district anchors sovereign cloud infrastructure development serving regulated European workloads.
China
State-owned enterprises and fintech platforms build domestic trusted execution environments under data localization directives. The NMPA's medical data governance rules and MIIT cloud security standards mandate on-premises confidential processing for sensitive records. Beijing and Shanghai host the primary semiconductor design centers developing indigenous CPU architectures with memory encryption capabilities.
United Kingdom
London-based insurers and investment banks migrate regulated analytics to confidential cloud instances for GDPR compliance. The Financial Conduct Authority's operational resilience requirements and post-Brexit data adequacy negotiations heighten focus on cryptographic data-in-use protection. The Cambridge technology cluster advances secure enclave research for privacy-preserving machine learning applications.
France
Public sector agencies and defense contractors require Common Criteria certified platforms under national security directives. The ANSSI's cloud security qualification program and sovereign cloud mandates privilege domestic confidential infrastructure for sensitive government workloads. Paris hosts the primary systems integrators deploying hybrid confidential computing architectures for EU institutions.
Confidential Computing Market Competitive Landscape
The competitive structure tilts toward hyperscale cloud providers with silicon design capabilities. Market concentration reflects the capital intensity of CPU architecture development and the certification burden for Common Criteria EAL4+ evaluation. Three archetypes dominate: integrated cloud-silicon stacks, mainframe-integrated security specialists, and sovereign infrastructure operators. Partnership strategies and geographic certification expansion constitute the primary competitive vectors as vendors race to satisfy EU AI Act attestation requirements.
Among integrated cloud-silicon providers, Microsoft Corporation and Google LLC exemplify the convergence of custom silicon development with managed confidential VM services. IBM Corporation occupies a distinct position anchoring mainframe-integrated trusted execution environments for financial services clients requiring legacy system interoperability. These three entities collectively represent the tier capable of delivering end-to-end hardware-backed confidentiality with multi-cloud portability credentials demanded by Frankfurt and New York procurement teams.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Intel Corporation |
| Google LLC |
| Advanced Micro Devices |
| Amazon Web Services |
| Alibaba Cloud |
| Arm Limited |
| Swisscom |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud providers with captive silicon design capabilities anchor supply-side pricing discipline, linking infrastructure procurement cycles to CPU foundry economics and certification amortization schedules. Their balance-sheet capacity for multi-year EAL4+ evaluation investments creates tiered access barriers that stratify pricing across sovereign cloud operators and regional managed service providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Common Criteria EAL4+ certified platforms from ISO 27001-aligned offerings and uncertified commodity instances. Price differentiation rests on attestation protocol coverage and geographic data residency guarantees. Pricing pressure stems from German banking consortia demanding portable credentials across Azure, AWS, and sovereign EU clouds. Government agencies exhibit lowest price sensitivity given national security directive mandates, while mid-market retailers face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement specifications as financial services firms in New York and Frankfurt mandate qualification across Intel TDX and AMD SEV-SNP implementations. Silicon supply concentrates in the United States, Taiwan, and South Korea for CPU architectures with memory encryption capabilities. Raw material dependencies span advanced packaging substrates, EUV photoresists, and cryptographic accelerator IP. Single-source vulnerability around leading-edge foundry capacity exposes lead time volatility. Distribution runs through direct hyperscaler channels and sovereign cloud integrators serving ANSSI-qualified workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Frankfurt and Paris run substantially above equivalent infrastructure deployment in US financial hubs, creating margin expansion opportunities for multi-jurisdictional operators.
For Market Incumbents: Acquire attestation protocol portfolios to neutralize fragmentation risks from competing hardware vendor standards. Consolidate certification assets across Common Criteria EAL4+ and emerging EU AI Act attestation frameworks. Defensive positioning requires backward integration into custom silicon development to preserve margin structure against AMD and Intel supply allocation priorities. For New Entrants and Emerging Players: Launch via sovereign cloud partnerships targeting French and Italian public sector mandates where ANSSI qualification creates artificial scarcity. Healthcare secure enclaves for FDA-connected device workloads represent the most penetrable segment given talent scarcity among incumbent systems integrators. Go-to-market execution should anchor on clinical trial data protection use cases with demonstrable GDPR Article 32 compliance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional managed service providers holding dormant EAL4+ certifications without hyperscale balance sheet support. Long-term viability across the analysis window hinges on attestation protocol portability and multi-cloud credential fungibility. Monitor German automotive supplier reconfiguration of supply chain data sharing as the inflection signal for secure multiparty computation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Attestation Protocol Acquisition | Neutralizes fragmentation risk from Intel TDX and AMD SEV-SNP incompatibility in multi-cloud deployments. |
| Sovereign Cloud Partnership | Unlocks ANSSI-qualified infrastructure procurement in France and Italy under national security directives. |
| Healthcare Enclave Specialization | Captures FDA cybersecurity guidance tailwinds for connected medical device data processing workflows. |
| Secure Multiparty Computation Integration | Addresses German banking consortium demand for cross-institutional fraud detection without data exposure. |
| Common Criteria EAL4+ Certification Investment | Satisfies US federal zero-trust mandates and defense agency classified workload requirements. |
Research Methodology
Bottom-up financial services and healthcare provider modeling reconciled against top-down CPU architecture and cloud infrastructure capex tracking forms the analytical core of this study. Primary interviews with confidential computing architects, CISOs at regulated enterprises, sovereign cloud procurement officers, and semiconductor platform engineers combined with secondary validation against SEC hyperscaler filings, NIST zero-trust architecture publications, and EU AI Act technical documentation. Triangulation across these sources anchors segmentation splits by deployment architecture, application layer, and end-user vertical.
Input-output matrices map trusted execution environment adoption rates to GDP-adjusted IT spending across the projection horizon, with cross-elasticities to GDPR enforcement intensity and FDA cybersecurity guidance issuance. Segmentation dimensions modeled include deployment sovereignty tier, attestation protocol coverage, workload sensitivity classification, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to confidential VM migration patterns observed in US and German banking sectors, with sensitivity testing against sovereign cloud mandate acceleration scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under chip export control expansion or Common Criteria evaluation timeline compression. Forecasts reflect documented assumptions regarding EU AI Act enforcement calibration and NIST standard finalization schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Information Rights Management Market
Security Software
Data Loss Prevention Market
Security Software
Global Digital Identity Solutions Market
Security Software
Endpoint Security Solutions Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Source Code Escrow Market
Security Software
Europe User Provisioning Market
Security Software
AD-Blocking Software Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
Banking Encryption Software Market
Security Software
ATM Security Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Certificate Authority Market